
 White Mushroom Market | 2026-2036
White Mushroom Market Size, Share, and Industry Trends Forecast 2026-2036
White Mushroom Market Analytics
Organic-certified grade white mushroom supply is rotating toward premium retail channels as consumers prioritize pesticide-free produce. Monterey Mushrooms, Inc. leverages vertical integration across composting and distribution to control quality consistency from substrate to shelf. Costa Group anchors Australasian production with climate-controlled growing infrastructure that extends harvest windows year-round. Shanghai Finc Bio-Tech dominates domestic Chinese supply through proprietary strain development and scaled indoor farming operations.
White mushrooms comprise the Agaricus bisporus species, a gilled fungus cultivated on composted substrates under controlled humidity and temperature parameters typically spanning 15-18°C for fruiting body development; the species serves as a high-protein, low-calorie ingredient across food manufacturing and foodservice applications. Fresh product type leads volume throughput due to perishability-driven replenishment cycles and direct-to-retail velocity, while dried formats capture margin pools through extended shelf life and export suitability. Online sales channel growth reflects last-mile cold-chain investments that reduce spoilage rates in direct-to-consumer fulfillment.
USDA organic certification and FDA food safety modernization protocols shape cultivation practices and traceability requirements for domestic growers, while EU REACH frameworks govern packaging material compliance for exports into European markets. Stakeholders must monitor evolving substrate sourcing regulations and carbon accounting standards that will reshape competitive compliance costs across major producing regions.
Market Dynamics
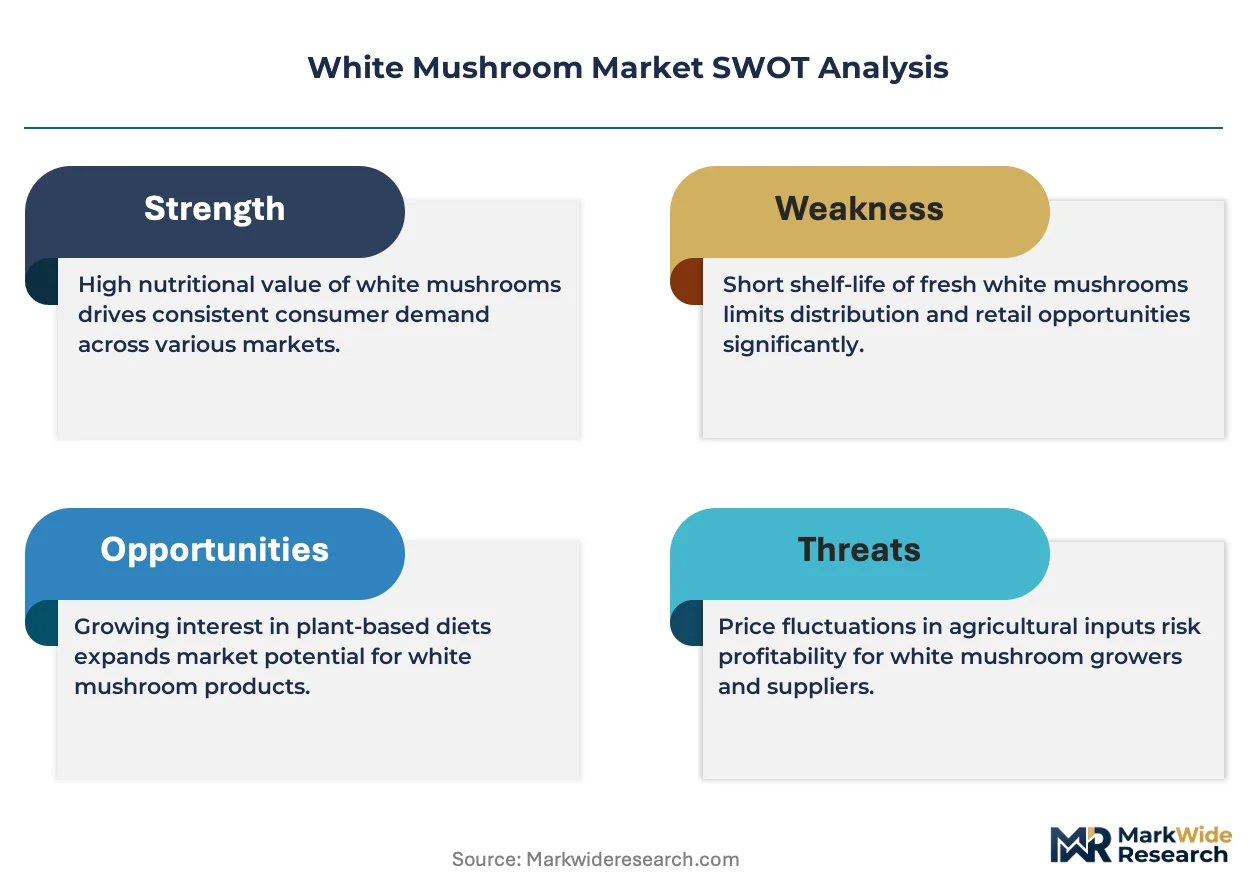
EFSA residue limit tightening for cultivated fungi is compressing margin structures across European supply chains while accelerating substrate quality investments among growers competing for retail access.
Growth Catalysts
- Restaurant chain procurement consolidation:Fresh white mushroom volume commitments from quick-service and casual dining networks in the United States and Canada are standardizing quality specifications and securing offtake for domestic growers.
- China cold-chain maturation:Refrigerated logistics corridor expansion into tier-two and tier-three urban retail zones is extending perishable shelf life and enabling premium fresh distribution beyond coastal megacities.
- USDA organic certification preference:Retail channel gatekeeping through organic-grade requirements is pulling substrate sourcing toward pesticide-free compost inputs and traceable supply documentation.
Market Restraints
- Compost input cost volatility:Wheat straw and poultry manure price swings tied to grain commodity markets directly compress cultivation margins for substrate-dependent operators.
- Spore supply concentration:Proprietary Agaricus bisporus strain development remains controlled by a limited set of biotechnology licensors, creating germplasm access bottlenecks for independent growers.
- Fresh format perishability:Harvest-to-shelf windows under 14 days constrain geographic radius for uncompromised quality delivery, limiting expansion into infrastructure-deficient markets.
Strategic Opportunities
- Direct-to-consumer subscription channels:Last-mile cold-chain investments by specialized fulfillment operators are opening recurring revenue streams bypassing traditional wholesale distribution.
- Plant-based protein formulation partnerships:Food manufacturers seeking mycoprotein texturizers for meat alternatives represent an emerging offtake vertical with differentiated margin profiles.
- EU Green Deal carbon accounting alignment:Indoor farming energy efficiency improvements and renewable power sourcing are positioning controlled-environment growers for preferential retail access under emerging sustainability scoring frameworks.
Industry Challenges
- Mycology technician skill scarcity:Specialized expertise in spawn run management and disease vector identification remains concentrated among aging practitioner cohorts with limited formal training pipeline replacement.
- Climate control capex intensity:Year-round fruiting chamber HVAC and humidity system installation demands substantial upfront capital deployment that strains balance sheet capacity for mid-scale entrants.
- Multi-jurisdiction certification complexity:Simultaneous compliance with FDA food safety modernization, USDA organic, and EU REACH packaging requirements creates documentation overhead and audit fragmentation for export-oriented operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Mushroom Market |
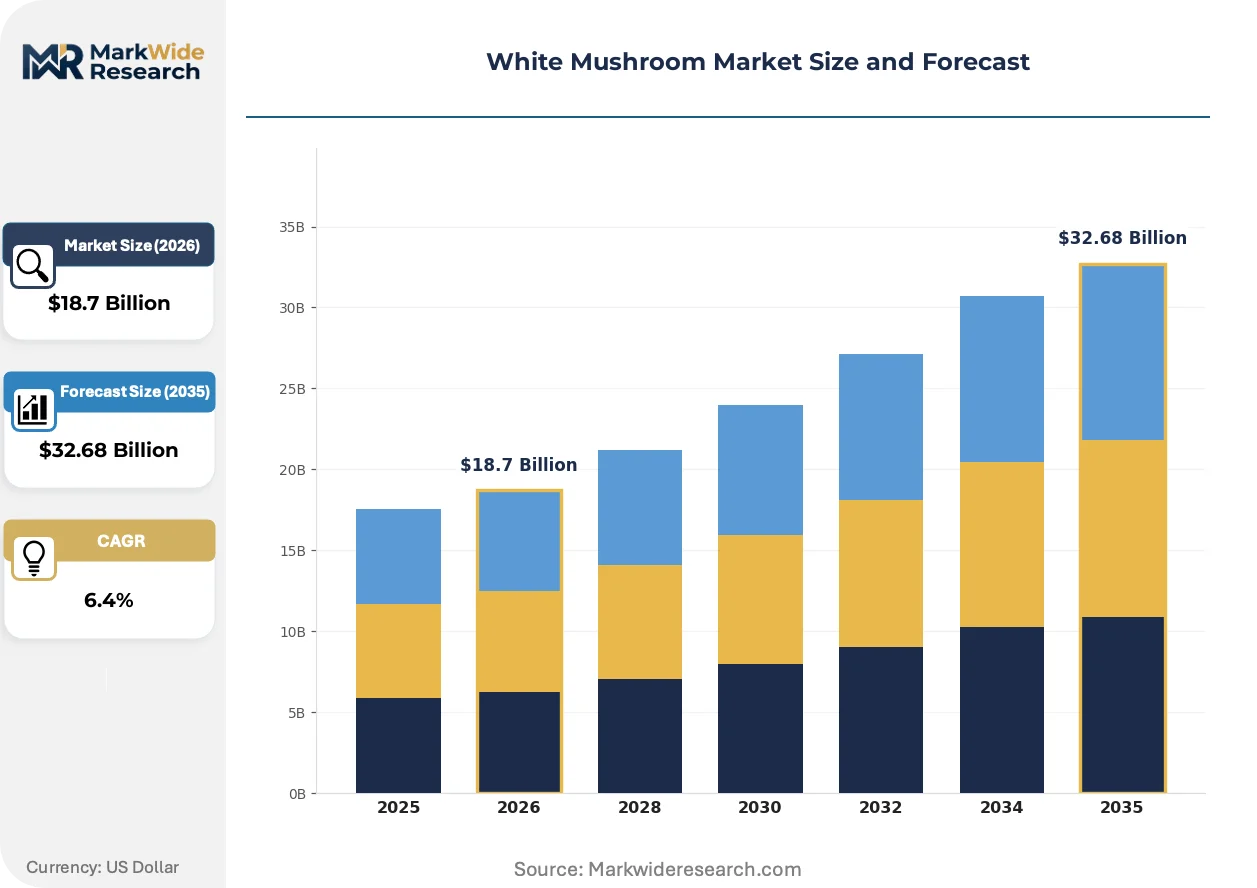
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Dried, Canned, Frozen Sales Channel: Supermarkets, Grocery Stores, Online, Farmers' Markets End User: Households, Restaurants, Food Processors, Hotels Packaging Type: Plastics, Cardboard, Vacuum Sealed, Glass |
| Companies Covered | Bonduelle Group, Costa Group, Monterey Mushrooms, Inc., Phillips Mushroom Farms, Drinkwater Mushrooms, Giorgio Fresh Co., Greenyard, Shanghai Finc Bio-Tech, Fujian Yuxing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Mushroom Market Evolving Landscape
Controlled-environment agriculture technologies are compressing production cycles while regulatory transparency mandates and channel fragmentation are reshaping how white mushrooms reach end consumers.
Sensor-integrated climate management systems are miniaturizing environmental monitoring infrastructure for indoor fruiting operations. Mid-scale growers in the Netherlands and Belgium are deploying compact IoT-enabled humidity and CO2 controllers that previously required facility-scale capital outlay. This technology diffusion is compressing the capital barrier between artisan and commercial production tiers.
EU REACH frameworks are mandating compostable or recyclable packaging material compliance for fresh produce exports into European markets. Mushroom-specific breathable film and molded fiber tray suppliers are reformulating barrier properties to maintain shelf life while eliminating petroleum-based components. Export-oriented packers in Poland and Spain are absorbing transitional material cost premiums to retain retail access.
Consolidated procurement by meal-kit assembly operators is displacing traditional wholesale distributor relationships for premium-grade fresh product. These fulfillment networks specify harvest maturity and bruise-tolerance standards that diverge from conventional foodservice grades. This specification divergence is most visible in the United States, where specialized growing contracts now bypass broadline distribution entirely.
White Mushroom Market Segmentation
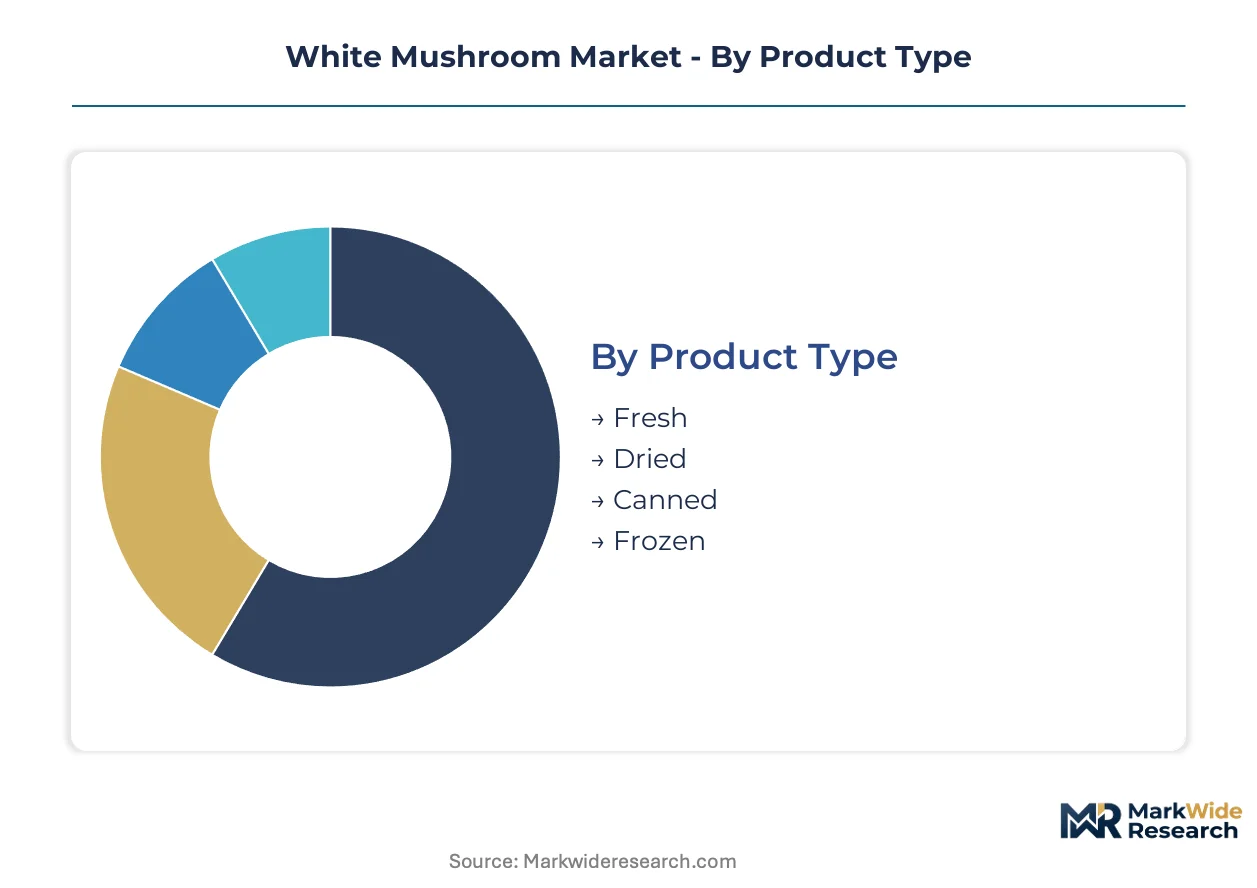
White mushroom commercialization splits across preservation formats, distribution pathways, and buyer specifications that dictate margin capture. Each segmentation axis reveals distinct competitive dynamics around perishability management, cold-chain dependency, and procurement scale.
Product Type:
Margin pools concentrate in formats that extend shelf life while preserving sensory quality, with fresh commanding velocity premiums and dried capturing export arbitrage.
- Fresh:Harvested fruiting bodies with intact cellular structure deliver maximum flavor compounds and textural integrity. Restaurant chains in the United States and Canada specify 48-hour harvest-to-delivery windows, compressing supply radius but securing price premiums through quality consistency.
- Dried:Dehydrated product concentrates umami compounds and eliminates refrigeration requirements. Export corridors into EU markets leverage dried formats to bypass fresh perishability constraints, with REACH-compliant packaging absorbing material cost premiums to retain retail access.
- Canned:Thermally processed product serves institutional procurement with extended ambient storage.
- Frozen:Blast-frozen formats preserve cellular integrity for food manufacturing applications.
The dominant share belongs to Fresh, while Dried is closing the gap fastest through export channel expansion.
Sales Channel:
Channel selection determines cold-chain investment recovery rates and direct consumer relationship depth.
- Supermarkets:Multi-location retail networks consolidate volume procurement and standardize quality grades. Tier-two Chinese urban corridors are extending refrigerated display infrastructure, enabling premium fresh distribution beyond coastal megacities.
- Online:Direct-to-consumer fulfillment bypasses wholesale margin extraction through last-mile cold-chain specialization. Subscription operators in North America specify harvest maturity standards that diverge from conventional foodservice grades.
- Grocery Stores:Independent retail maintains regional sourcing relationships with shorter supply chains.
- Farmers' Markets:Direct producer-consumer contact captures full retail margin but constrains volume scale.
Supermarkets anchor volume throughput, though Online is expanding most quickly through fulfillment infrastructure maturation.
End User:
Buyer type dictates specification stringency and contract structure durability.
- Restaurants:Foodservice operators standardize quality specifications through consolidated procurement. Quick-service and casual dining networks in the United States and Canada secure offtake commitments that stabilize grower revenue visibility.
- Food Processors:Manufacturing buyers integrate mushrooms into plant-based protein formulations and prepared meal applications. Mycoprotein texturizer demand represents an emerging offtake vertical with differentiated margin profiles.
- Households:Retail consumers drive organic-grade preference through pesticide-free produce prioritization.
- Hotels:Hospitality procurement emphasizes presentation-grade specifications for buffet and banquet applications.
Restaurants hold the largest procurement volume, yet Food Processors are gaining share fastest through formulation partnership expansion.
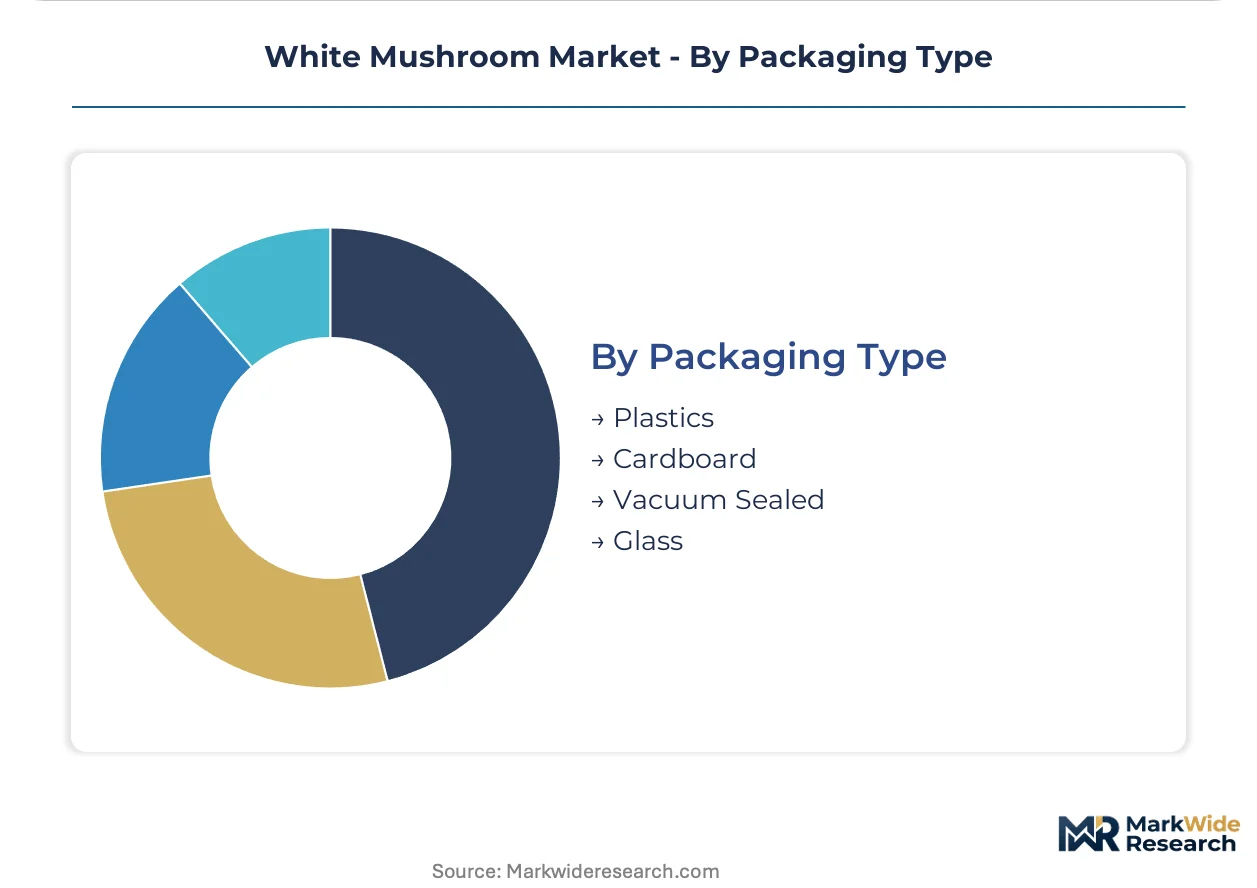
Packaging Type:
Material selection balances shelf-life extension against regulatory compliance cost and sustainability positioning.
- Vacuum Sealed:Oxygen-exclusion packaging extends fresh product viability through modified atmosphere preservation. EU export-oriented packers in Poland and Spain absorb transitional material premiums to meet REACH compostable mandates.
- Cardboard:Molded fiber trays eliminate petroleum-based components while maintaining breathable barrier properties. Retail channel gatekeeping through sustainability scoring frameworks favors renewable material sourcing.
- Plastics:Conventional petroleum-based films face regulatory displacement pressure.
- Glass:Premium positioning for specialty preserved formats carries weight and fragility penalties.
Vacuum Sealed retains the dominant position, while Cardboard is climbing the fastest through EU Green Deal alignment requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China demonstrate the highest price elasticity as cold-chain maturation unlocks premium fresh distribution, while EU procurement exhibits inelastic demand for residue-compliant organic grades. Restaurant chains in North America occupy a middle ground, trading margin for supply security through volume commitments.
United States
Quick-service and casual dining networks consolidate procurement through standardized quality specifications that stabilize grower revenue visibility. FDA food safety modernization protocols mandate traceable supply documentation from substrate sourcing through retail shelf. Pennsylvania's Chester County corridor anchors domestic production with climate-controlled growing infrastructure serving East Coast population centers.
China
Tier-two and tier-three urban retail zones extend refrigerated logistics corridors that enable premium fresh distribution beyond coastal megacities. SAMR oversight of pesticide residue testing tightens compliance thresholds for domestic cultivation operations. Shanghai Finc Bio-Tech dominates Yangtze River Delta supply through proprietary strain development and scaled indoor farming operations.
Netherlands
Mid-scale growers deploy compact IoT-enabled humidity and CO2 controllers that compress capital barriers between artisan and commercial production tiers. EU REACH frameworks mandate compostable packaging material compliance for fresh produce exports. The Westland cluster integrates sensor-integrated climate management systems that previously required facility-scale capital outlay.
Poland
Export-oriented packers absorb transitional material cost premiums to retain retail access under EU Green Deal sustainability scoring frameworks. EFSA residue limit tightening accelerates substrate quality investments among growers competing for European retail channels. The Mazovia region concentrates breathable film and molded fiber tray suppliers reformulating barrier properties to eliminate petroleum-based components.
Australia
Costa Group anchors Australasian production with climate-controlled growing infrastructure that extends harvest windows year-round. The country's national food safety regulator enforces stringent cultivation practice standards for export qualification. Victoria's Gippsland region hosts scaled indoor fruiting operations serving Pacific Rim markets through established cold-chain corridors.
White Mushroom Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the white mushroom supply base. The vendor base fragments across substrate-dependent operators, proprietary strain licensors, and climate-controlled indoor specialists. Three strategic archetypes dominate: vertically integrated compost-to-shelf operators, biotechnology-focused germplasm developers, and regional fresh distributors with last-mile specialization. Consolidation pressure concentrates through restaurant chain procurement standardization and meal-kit assembly operator specification divergence.
Among the vertically integrated tier, Monterey Mushrooms exemplifies substrate-to-shelf control through captive composting and distribution infrastructure. Costa Group occupies a position representing climate-advantaged Southern Hemisphere production with extended harvest window capabilities. Shanghai Finc Bio-Tech anchors the biotechnology-specialist archetype through proprietary Agaricus bisporus strain development and scaled indoor farming operations.
| Leading Market Players |
|---|
| Bonduelle Group |
| Costa Group |
| Monterey Mushrooms, Inc. |
| Phillips Mushroom Farms |
| Drinkwater Mushrooms |
| Giorgio Fresh Co. |
| Greenyard |
| Shanghai Finc Bio-Tech |
| Fujian Yuxing |
| Others |
Value Network & Pricing Analysis
Fourteen-day harvest-to-shelf windows compress geographic radius for uncompromised quality delivery, concentrating pricing power among climate-controlled indoor operators with captive composting infrastructure while marginalizing substrate-dependent growers facing input cost volatility.
Pricing Analysis
After-sales subscription revenue through direct-to-consumer channels drives lifetime value capture beyond transactional fresh sales. Three-tier pricing structure across organic-certified premium, conventional standard, and commodity economy levels segments buyer willingness-to-pay by certification grade and harvest maturity specification. Pricing pressure stems from EFSA residue limit tightening that accelerates substrate quality investments among European growers competing for retail access. Restaurant chains in the United States and Canada exhibit lowest price sensitivity through volume commitment security, while Chinese urban retail consumers demonstrate highest elasticity as cold-chain maturation unlocks premium fresh distribution.
Supply Chain Analysis
The United States, China, and the Netherlands anchor global white mushroom production through contrasting operational archetypes. The United States concentrates quick-service procurement consolidation, China dominates proprietary strain development at scale, and the Netherlands leads sensor-integrated climate management diffusion. Substrate sourcing draws from wheat straw and poultry manure supplies tethered to grain commodity markets, while spore supply rests on proprietary Agaricus bisporus strain licensors creating germplasm access bottlenecks. Single-source vulnerability concentrates in biotechnology-controlled germplasm development. Distribution runs through supermarket retail networks consolidating volume procurement, with online subscription channels bypassing wholesale margin extraction through last-mile cold-chain specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities through recurring subscription revenue layers expand faster than transactional fresh sales, repositioning cultivation economics toward lifetime value capture and direct consumer relationship depth.
For Market Incumbents: Fortify substrate-to-shelf control through captive composting infrastructure that insulates margin structures from wheat straw and poultry manure price volatility. Deepen climate-controlled indoor capacity in Chester County and Yangtze River Delta corridors to compress harvest-to-shelf windows below competitor reach. Certification investment in USDA organic and EU REACH compliance creates retail channel gatekeeping advantages against substrate-dependent operators facing EFSA residue limit compression. For New Entrants and Emerging Players: Differentiate on proprietary strain development and scaled indoor farming operations that bypass spore supply concentration bottlenecks controlled by limited biotechnology licensors. Target tier-two and tier-three Chinese urban corridors where refrigerated logistics corridor extension enables premium fresh distribution beyond incumbent coastal megacity saturation. Direct-to-consumer subscription channels offer the most penetrable go-to-market angle through last-mile cold-chain specialization that bypasses traditional wholesale distribution relationships. For Investors and Strategic Acquirers: Long-term, this sits as a vertical consolidation play because restaurant chain procurement standardization and meal-kit assembly operator specification divergence concentrate competitive pressure on fragmented substrate-dependent operators. Acquisition target archetype: climate-controlled indoor specialists with proprietary strain development capabilities and established cold-chain infrastructure serving premium retail channels. Signal to watch: EFSA carbon accounting framework finalization that positions renewable-powered controlled-environment growers for preferential retail access under emerging sustainability scoring frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composting | Captive substrate production insulates margin structures from wheat straw and poultry manure commodity volatility. |
| Proprietary Strain Development | Controlled germplasm access bypasses spore supply concentration bottlenecks among limited biotechnology licensors. |
| Direct-to-Consumer Subscription Launch | Recurring revenue streams bypass wholesale margin extraction through specialized last-mile cold-chain fulfillment. |
| EU Green Deal Certification Alignment | Renewable-powered indoor farming positions growers for preferential retail access under sustainability scoring frameworks. |
| Sensor-Integrated Climate Management Deployment | IoT-enabled humidity and CO2 controllers compress capital barriers between artisan and commercial production tiers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA food safety modernization protocols, EFSA residue limit frameworks, EU REACH packaging mandates, and customs trade data. Primary interviews engaged cultivation operations managers, restaurant chain procurement directors, cold-chain logistics specialists, and retail category buyers across North American, European, and Asia-Pacific production clusters. Secondary validation drew from USDA organic certification databases, SAMR pesticide residue testing records, and SEC filings of publicly traded agricultural operators. Bottom-up volume triangulation against top-down value estimation ensures cross-verified output integrity.
Segmentation dimensions modeled span preservation format, distribution channel, end-user specification, and packaging material compliance across the analysis window. Analytical framework incorporates substrate input cost trajectories, cold-chain infrastructure maturity indices, and regulatory compliance threshold evolution. CAGRs derive from trend extrapolation of historical volume throughput and value capture patterns adjusted for structural shifts in procurement consolidation and channel fragmentation. Industry-specific forecast inputs include spore supply concentration dynamics and climate control technology diffusion rates.
Material uncertainties — compost input cost volatility, EFSA residue limit revision timing, and cold-chain infrastructure deployment pace — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory framework stability and buyer specification continuity that revision triggers could invalidate. Recalibration cycles align with material shifts in substrate sourcing regulations and carbon accounting standard finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Fruit Pomace Market
Fruits and Vegetables
Dried Figs Market
Fruits and Vegetables
Farro Market
Fruits and Vegetables
Persimmons Market
Fruits and Vegetables
Cranberries Market
Fruits and Vegetables
Basil Leaves Market
Fruits and Vegetables
Water Chestnut Market
Fruits and Vegetables
Israel Fruits and Vegetables Market
Fruits and Vegetables
Global Organic Fruits and Vegetables Market
Fruits and Vegetables
Jackfruit Market
Fruits and Vegetables
Spain Lime Market
Fruits and Vegetables
Processed Fruits and Vegetables Market
Fruits and Vegetables
Global Fresh Berries Market
Fruits and Vegetables
US Fruit Puree Market
Fruits and Vegetables
Fresh Lemons Market
Fruits and Vegetables
Annatto Market