
 Botanical Supplements Market | 2026-2036
Botanical Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Botanical Supplements Market Analysis
Premium standardized extracts is bifurcating the botanical supplements landscape into mass-market commodity grades and validated therapeutic tiers. Dabur India leverages its Ayurvedic heritage and captive herb cultivation to command premium positioning in domestic and export markets. BASF SE anchors European supply through pharmaceutical-grade extraction capabilities and botanical active ingredient portfolios. NOW Foods competes on transparency protocols, sustaining consumer trust via third-party testing and clean-label certifications.
Botanical supplements comprise bioactive compounds derived from terrestrial plants, algae, fungi, and seaweeds, typically standardized to marker compound concentrations for reproducible efficacy. These formulations serve preventive health, therapeutic adjuvant, and functional nutrition roles across consumer and clinical channels. Herbal extracts capture the dominant margin pool due to concentration efficiency and dosage precision, while essential oils expand fastest within personal care applications. Nutraceuticals remain the mature demand anchor, though food and beverages formulations accelerate as clean-label enrichment trends intensify.
The FDA's cGMP enforcement for dietary supplements, EFSA's health claims substantiation requirements, and India's FSSAI licensing for Ayurvedic products collectively elevate compliance costs and barrier thresholds. This regulatory triad rewards scaled manufacturers with dedicated quality infrastructure while squeezing informal suppliers from formal distribution channels. Stakeholders must monitor evolving pharmacovigilance mandates and adapt sourcing strategies to preempt supply disruption from habitat protection designations.
Market Dynamics
Standardization protocols are bifurcating the botanical supplements landscape into validated therapeutic grades and unverified commodity tiers, forcing manufacturers to invest in marker compound verification infrastructure or retreat to undifferentiated bulk supply.
Growth Catalysts
- FSSAI licensing for Ayurvedic products:India's regulatory framework legitimizes traditional formulations for export markets, accelerating formal channel penetration for domestic manufacturers.
- Clean-label enrichment mandates:Functional food and beverage manufacturers are integrating standardized extracts as natural alternatives to synthetic fortificants.
- Pharmaceutical-grade extraction:Supercritical CO2 and ethanol extraction technologies enable reproducible bioactive concentrations that satisfy clinical trial requirements.
Market Restraints
- Wild-harvest supply concentration:Habitat-dependent sourcing in the Western Ghats and Himalayan foothills creates batch-to-batch variability and extinction risk for high-value species.
- EFSA health claims substantiation:The European regulator's evidence thresholds block market access for products lacking randomized controlled trial data.
- Synthetic phytochemical substitutes:Laboratory-produced resveratrol and curcumin analogues threaten premium positioning of plant-derived equivalents.
Strategic Opportunities
- German pharmacy channel:The country's traditional medicine reimbursement framework rewards clinically substantiated botanicals with preferential formulary placement.
- Personal care convergence:Essential oil applications in dermatological formulations open margin-rich adjacent markets beyond oral supplements.
- Captive cultivation partnerships:Contract farming arrangements with Indian agricultural cooperatives secure supply chain traceability for premium positioning.
Industry Challenges
- Pharmacovigilance reporting systems:Adverse event documentation requirements under FDA cGMP enforcement strain quality infrastructure at mid-scale manufacturers.
- Herbarium authentication bottlenecks:DNA barcoding capacity constraints delay New Dietary Ingredient notifications and compress innovation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Botanical Supplements Market |
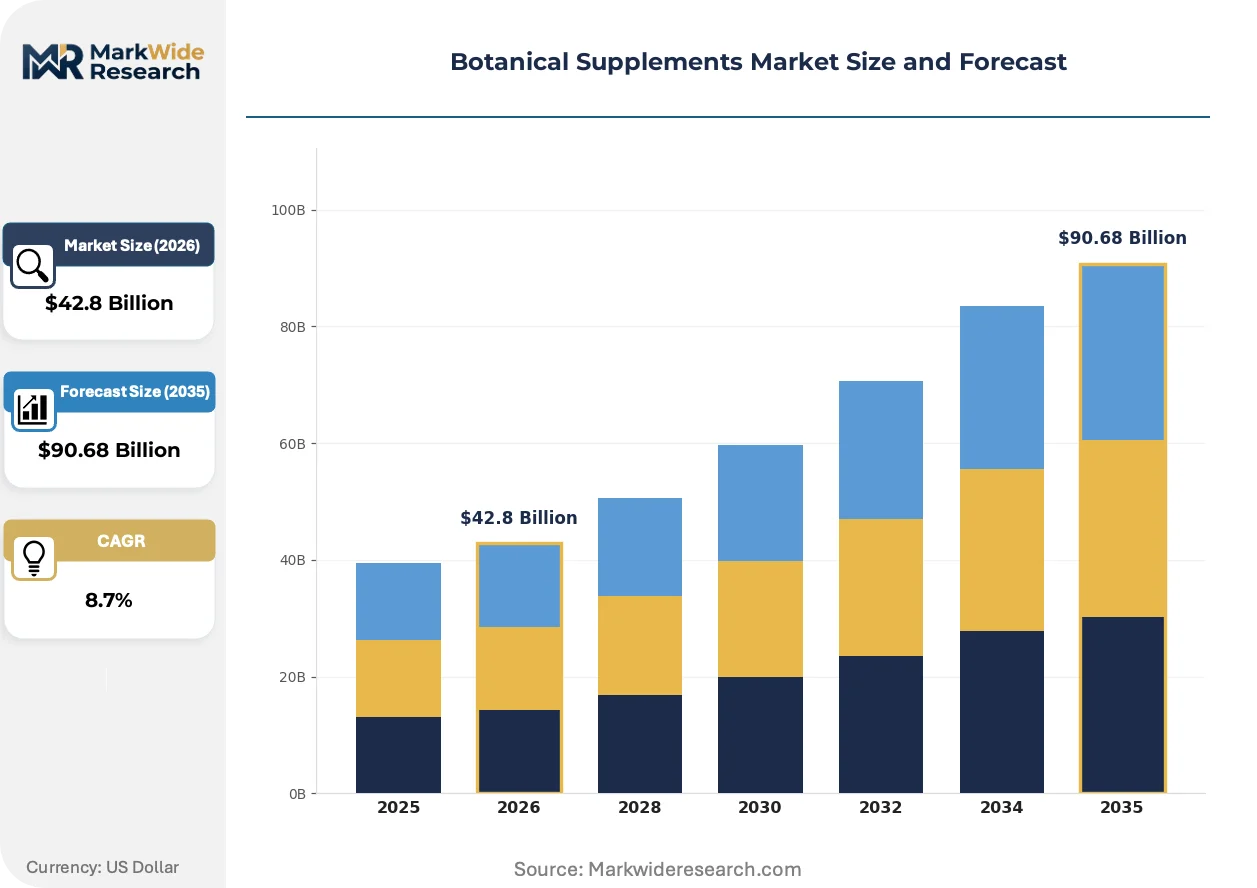
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $90.68 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Extracts, Essential Oils, Powders, Capsules Application: Nutraceuticals, Personal Care, Food & Beverages, Pharmaceuticals Ingredient Source: Plants, Algae, Fungi, Seaweeds Formulation: Liquid, Solid, Semi-Solid, Powdered |
| Companies Covered | Dabur India, BASF SE, Nestlé SA, Amway Corporation, NOW Foods, Herbalife Nutrition, Nature's Bounty, Ricola AG, Blackmores Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Botanical Supplements Market Emerging Trajectories
Bioprocessing advances are fragmenting traditional extraction economics while regulatory harmonization efforts compress cross-border commercialization timelines. Three developments are restructuring competitive positioning.
Supercritical fluid extraction is decomposing the cost advantage of conventional solvent-based processing. Nutraceutical contract manufacturers in Germany and Switzerland are retrofitting facilities to capture pharmaceutical-grade yields. This technology is decomposing margin structures for commodity extract suppliers unable to justify capital intensity.
REACH registration requirements for novel botanical substances are extending European market entry timelines by 18-24 months. The regulation forces manufacturers to front-load toxicological assessment costs before revenue generation. Concentrated extract categories face the steepest compliance burden, prompting some suppliers to deprioritize EU certification.
Direct-to-practitioner distribution is displacing retail pharmacy intermediation for clinical-grade botanicals. Functional medicine clinics and integrative health networks now source validated extracts through specialized wholesalers. This channel rotation is most pronounced in California and New York, where licensed naturopathic prescribing authority expands addressable demand.
Botanical Supplements Market Segmentation
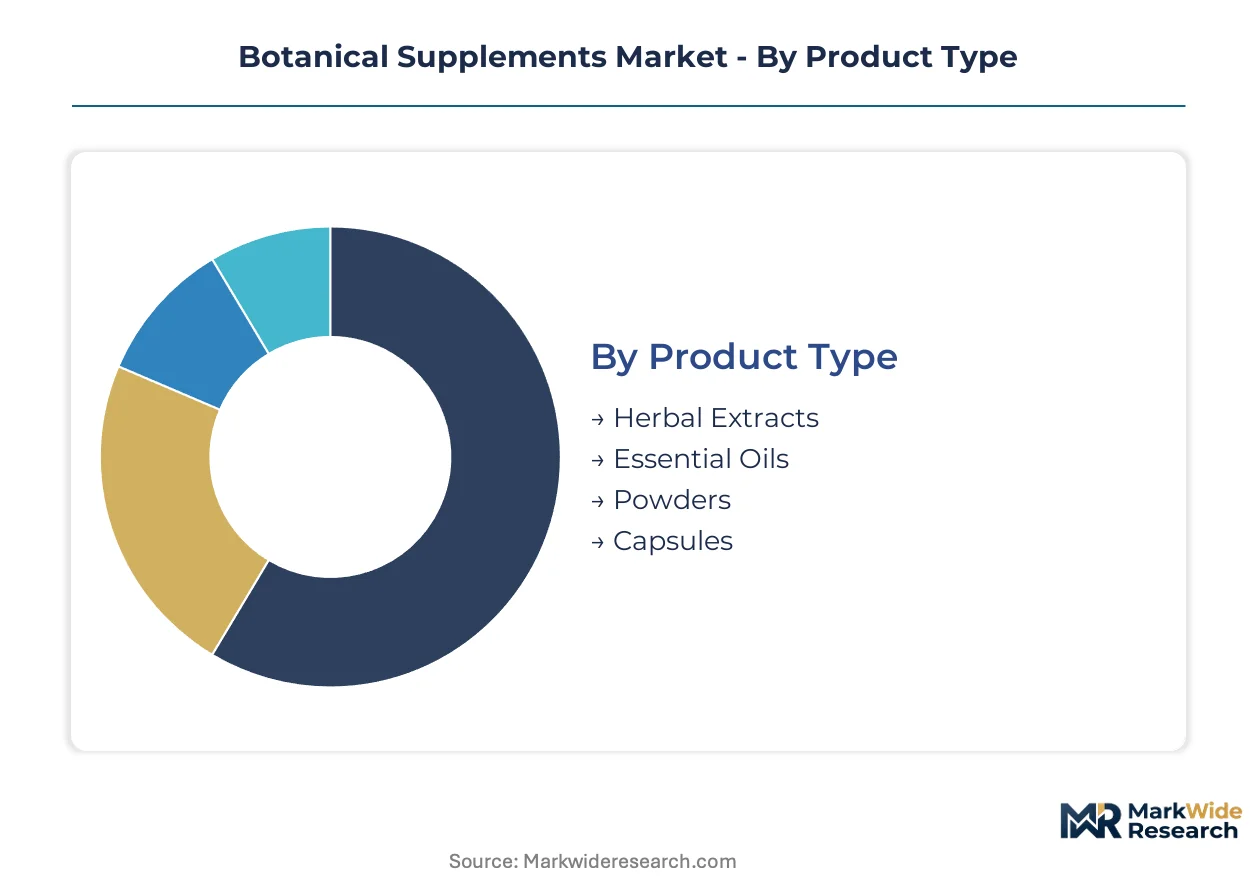
Segmentation in botanical supplements determines regulatory pathway, margin structure, and channel access. Standardization grade and end-use application dictate whether products enter pharmacy, food, or cosmetic distribution. Manufacturers must align formulation choices with jurisdiction-specific compliance frameworks.
Product Type:
Regulatory differentiation separates pharmaceutical-grade extracts from commodity botanicals through marker compound verification and cGMP documentation. FDA's New Dietary Ingredient notification applies variably across concentration thresholds.
- Herbal Extracts:Concentrated bioactive formulations standardized to specific phytochemical markers such as withanolides or boswellic acids. Demand concentrates in German pharmacy channels where reimbursement codes reward clinically substantiated potency grades; EFSA health claims substantiation blocks unverified entrants.
- Essential Oils:Volatile aromatic compounds extracted via steam distillation or cold pressing, characterized by terpene profiles and oxidation stability. Personal care manufacturers in France and Switzerland drive premium sourcing for dermatological applications; clean-label mandates accelerate substitution of synthetic fragrance precursors.
- Powders:Milled raw botanical material with particle size distribution affecting dissolution kinetics and bioavailability.
- Capsules:Encapsulated dry extracts or powders in gelatin or hydroxypropyl methylcellulose shells, offering dose precision and oxidative protection.
Herbal extracts handle the majority of throughput; essential oils are the fastest mover on share.
Application:
Cost tier stratification separates clinical-grade botanicals from commodity nutraceuticals through extraction infrastructure investment and pharmacovigilance capacity.
- Nutraceuticals:Dietary supplements delivering preventive health benefits through standardized daily doses. India's FSSAI licensing framework legitimizes Ayurvedic formulations for export; Dabur India leverages captive cultivation to command premium positioning in domestic and international markets.
- Personal Care:Topical formulations leveraging anti-inflammatory or antimicrobial botanical actives. Essential oil integration into dermatological products opens margin-rich adjacent markets beyond oral delivery; California functional medicine clinics source validated extracts through specialized wholesalers.
- Food & Beverages:Clean-label enrichment using natural alternatives to synthetic fortificants.
- Pharmaceuticals:Clinical-grade extracts meeting pharmacopeial monographs for adjuvant or standalone therapeutic use.
Nutraceuticals anchor volume throughput; personal care applications climb the fastest on margin contribution.
Ingredient Source:
Supply concentration in habitat-dependent geographies creates batch-to-batch variability and extinction risk for wild-harvested species.
- Plants:Terrestrial botanicals from cultivated or wild-harvested sources, comprising the dominant raw material base. Western Ghats and Himalayan foothills in India concentrate premium Ayurvedic sourcing; habitat protection designations threaten supply continuity for high-value species.
- Algae:Photosynthetic microorganisms cultivated in photobioreactors or open ponds, rich in omega fatty acids and antioxidant pigments. Contract farming arrangements with Indian agricultural cooperatives secure traceability for premium positioning.
- Fungi:Mushroom-derived polysaccharides and triterpenes from submerged fermentation or solid-state cultivation.
- Seaweeds:Marine macroalgae harvested from coastal waters or aquaculture operations, supplying iodine and sulfated polysaccharides.
Plants handle the majority of throughput; algae are expanding most quickly on cultivation technology maturation.
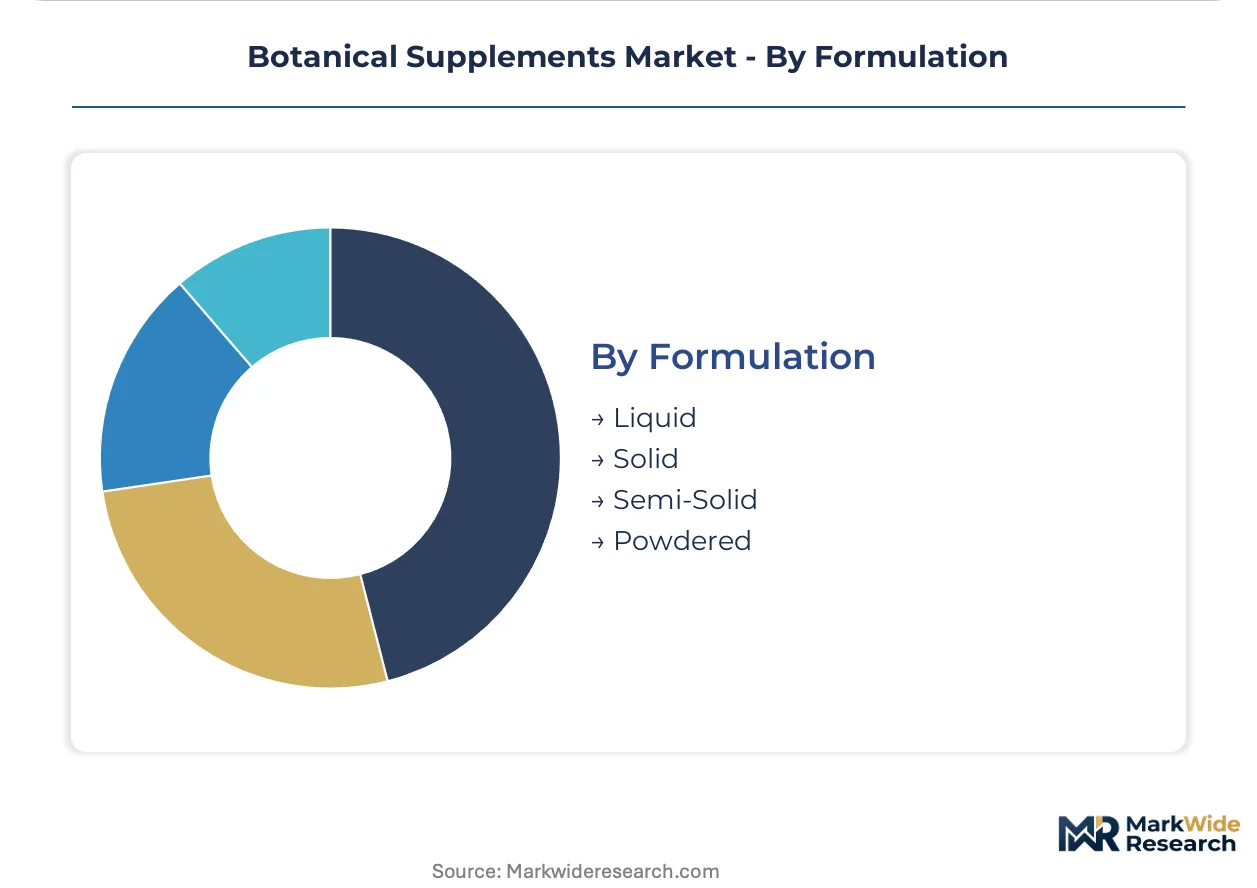
Formulation:
Customer type preferences separate practitioner-directed clinical grades from self-directed consumer formats through dosing precision and stability engineering.
- Liquid:Tinctures, glycerites, and fluid extracts offering rapid absorption and flexible dose titration. Direct-to-practitioner distribution in New York and California displaces retail pharmacy intermediation for clinical-grade botanicals; licensed naturopathic prescribing authority expands addressable demand.
- Solid:Tablets and caplets providing dose uniformity and extended shelf stability. Supercritical CO2 extraction enables reproducible bioactive concentrations that satisfy clinical trial requirements for solid dosage forms.
- Semi-Solid:Creams, ointments, and gels for topical delivery of anti-inflammatory or wound-healing botanicals.
- Powdered:Bulk extracts or whole-plant material for compounding, encapsulation, or food integration.
Solid formulations handle the majority of throughput; liquid formats gain share fastest on practitioner channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports standardized Ayurvedic extracts to Germany and the United States, while Switzerland and Japan import pharmaceutical-grade botanical actives for clinical formulations. Regulatory divergence across destination markets fragments certification requirements and extends commercialization timelines.
United States
Functional medicine clinics in California and New York drive practitioner-channel demand for validated extracts. FDA cGMP enforcement and New Dietary Ingredient notification requirements compress innovation timelines for domestic manufacturers. The Pacific Northwest concentrates wild-harvested supply operations for premium species.
Germany
Pharmacy reimbursement codes reward clinically substantiated botanicals with preferential formulary placement. EFSA health claims substantiation blocks market access for products lacking randomized controlled trial data. Bavaria hosts supercritical CO2 extraction facilities serving pharmaceutical-grade supply.
India
Ayurvedic tradition anchors domestic consumption and export positioning for premium botanical sourcing. FSSAI licensing legitimizes traditional formulations for formal channel penetration. The Western Ghats and Himalayan foothills concentrate wild-harvest operations facing habitat protection pressures.
Switzerland
Personal care manufacturers in Geneva and Basel drive premium essential oil sourcing for dermatological applications. REACH registration requirements extend market entry timelines for novel botanical substances. The Swissmedic framework governs clinical-grade extract quality standards.
Japan
Aging demographics sustain demand for preventive botanical formulations in nutraceutical applications. PMDA and METI oversight governs functional food ingredient approvals. The Kansai region concentrates extraction technology providers serving domestic pharmaceutical clients.
Botanical Supplements Market Vendor Landscape
Listed leaders compete with private specialists across standardization infrastructure and regulatory compliance capacity. The market structures around three tiers: multinational chemical conglomerates with pharmaceutical-grade extraction capabilities, heritage Ayurvedic houses with captive cultivation networks, and transparency-focused direct-to-consumer brands. Consolidation pressures favor scaled manufacturers with dedicated quality infrastructure. Dominant competitive moves include backward integration into captive herb cultivation and strategic partnerships with contract farming cooperatives.
Among heritage Ayurvedic specialists, Dabur India occupies a position exemplifying premium domestic and export positioning through integrated supply chain control. BASF SE anchors the European pharmaceutical-grade tier with extraction capabilities serving clinical trial requirements. NOW Foods represents the transparency-focused archetype, competing via third-party testing protocols and clean-label certifications that sustain consumer trust in self-directed channels.
| Leading Market Players |
|---|
| Dabur India |
| BASF SE |
| Nestlé SA |
| Amway Corporation |
| NOW Foods |
| Herbalife Nutrition |
| Nature's Bounty |
| Ricola AG |
| Blackmores Limited |
| Others |
Supply Flow & Price Mechanics
FDA cGMP enforcement and New Dietary Ingredient notification requirements simultaneously gate supply qualification and stratify price tiers across the botanical supplements landscape. Manufacturers lacking dedicated quality infrastructure face exclusion from formal distribution channels while certified operators command premium positioning.
Pricing Analysis
Functional food and beverage manufacturers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade and extraction technology, with pharmaceutical-grade supercritical CO2 extracts commanding substantial premiums over conventional solvent-based alternatives. Cost compression in commodity-grade powders is intensifying because synthetic phytochemical substitutes erode plant-derived positioning. Industrial OEM buyers exhibit highest price sensitivity, while German pharmacy channels demonstrate lowest sensitivity due to reimbursement frameworks.
Supply Chain Analysis
India and China anchor global supply for raw botanical materials and standardized extracts respectively. Western Ghats and Himalayan foothills in India concentrate premium Ayurvedic herb sourcing, while Chinese processors dominate extraction capacity for commodity grades. Raw material dependencies center on wild-harvested ashwagandha, cultivated turmeric, and spirulina from contract farming arrangements. Single-source vulnerability in habitat-dependent species threatens batch-to-batch consistency. Distribution runs through specialized wholesalers serving practitioner channels alongside mass-market retail intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among functional food and beverage manufacturers concentrates procurement leverage, shifting buyer power toward scaled end-users capable of mandating traceability documentation and volume commitments.
For Market Incumbents: Compound defensive positioning through backward integration into captive herb cultivation in Indian agricultural cooperatives and pharmaceutical-grade extraction infrastructure investment. Synthetic phytochemical substitutes threaten premium plant-derived tiers, making marker compound verification capacity the critical lever for margin defense. For New Entrants and Emerging Players: Direct-to-practitioner distribution gaps in California and New York functional medicine networks present under-served white-space. Personal care applications for essential oils in dermatological formulations offer the most penetrable adjacent market. A specialized wholesaler partnership model bypasses retail pharmacy intermediation entirely. For Investors and Strategic Acquirers: REACH registration requirements for novel botanical substances reshape the acquisition landscape toward targets with existing European toxicological dossiers. Long-term viability centers on scaled manufacturers with dedicated quality infrastructure and pharmacovigilance capacity. The signal to watch is FDA cGMP enforcement intensity against mid-scale informal suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Cultivation Partnerships | Contract farming with Indian cooperatives secures traceability for premium extract positioning. |
| Supercritical CO2 Extraction Scale-Up | Pharmaceutical-grade yield capabilities satisfy German pharmacy reimbursement requirements. |
| Direct-to-Practitioner Channel Development | Specialized wholesaler networks in California displace retail pharmacy intermediation. |
| EFSA Health Claims Substantiation | Randomized controlled trial data unlocks preferential European formulary placement. |
| Personal Care Formulation Expansion | Essential oil integration into dermatological products opens margin-rich adjacent markets. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across functional medicine clinics, Ayurvedic formulation houses, extraction technology providers, and FSSAI licensing authorities. Secondary validation drew from FDA cGMP inspection records, EFSA health claims registers, FSSAI product approvals, and customs trade data for standardized extract flows. Bottom-up volume triangulation against top-down value estimation anchored forecast integrity.
Across the analysis window, projections segmented by standardization grade, end-use application, formulation type, and ingredient source geography. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and channel migration patterns. Cultivation yield assumptions and extraction efficiency curves informed supply-side capacity modeling.
Underlying assumptions cover habitat protection designation stability, wild-harvest permit continuity, and synthetic substitute penetration rates, with deviation risk concentrated in pharmacovigilance mandate intensity and EFSA evidence threshold evolution. Recalibration cycles align with material shifts in FDA enforcement patterns and German reimbursement code revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Electrolyte Powder Market
Nutritional Supplements
Austria Protein Supplements Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
Europe Botanical Supplements Market
Nutritional Supplements
Royal Jelly Market
Nutritional Supplements
Energy Gel Products Market
Nutritional Supplements
Human Nutrition Market
Nutritional Supplements
Omega-3 Products Market
Nutritional Supplements
Food Grade Beta-Alanine Market
Nutritional Supplements
US Hangover Cure Products Market
Nutritional Supplements
Green Supplement Market
Nutritional Supplements
Calcium Malate Market
Nutritional Supplements
Asia-Pacific Omega-3 Products Market
Nutritional Supplements
Astragalus Propinquus Market
Nutritional Supplements
Lactoferrin Supplements Market
Nutritional Supplements
Bone Meal Supplement Market