
 Diagnostic Tools for Evs Market | 2026-2036
Diagnostic Tools for Evs Market Size, Share, and Industry Trends Forecast 2026-2036
Diagnostic Tools for Evs Market Outlook
Asset-light leasing models for high-end diagnostic equipment is fragmenting the competitive landscape, lowering barriers for independent service networks. Bosch Automotive Service Solutions leverages its captive financing arm to bundle hardware subscriptions with software updates. Snap-on Incorporated anchors its position through technician training programs that lock in recurring tool purchases. Launch Tech Co., Ltd. competes aggressively on price in emerging markets with modular diagnostic platforms.
Diagnostic tools for EVs encompass battery analyzers, diagnostic software, charging equipment testers, and sensor-based health monitoring systems that interface with high-voltage architectures through CAN bus and OBD-II protocols. These tools perform state-of-charge validation, cell balancing verification, and thermal runaway risk assessment to ensure safe, efficient electric vehicle operation. Battery analyzers and diagnostic software command the deepest margin pools due to firmware complexity and recurring update revenue. AI integration and cloud computing represent the fastest-expanding technology segments, though wireless communication retains volume leadership across aftermarket channels. Service centers and fleet operators now drive the majority of procurement, with automotive OEMs increasingly mandating proprietary diagnostic ecosystems.
The EPA and NHTSA in the United States enforce emissions-equivalent reporting and safety-critical system verification that shapes diagnostic tool functionality requirements. The EU's F-Gas Regulation and CE marking standards further dictate thermal management diagnostic protocols for battery cooling systems. Stakeholders must monitor regulatory divergence between jurisdictions, as incompatible certification requirements threaten to fragment product development roadmaps and inflate compliance costs.
Market Dynamics
High-voltage battery architectures are forcing diagnostic tool makers to recalibrate every hardware and software layer, as 800V platforms proliferate across passenger and commercial EV segments and invalidate legacy 400V testing protocols.
Growth Catalysts
- EU Battery Health Mandates:The European Union's standardized diagnostic protocol requirements for battery state-of-health reporting are compelling fleet operators to upgrade testing infrastructure at scale.
- Cell Chemistry Proliferation:LFP, NMC, and solid-state battery variants entering production lines require adaptable diagnostic platforms capable of multi-chemistry validation without hardware swaps.
- Stuttgart-Munich Corridor:Germany's automotive engineering cluster concentrates R&D investment and technician training programs, creating dense demand for advanced diagnostic tooling.
Market Restraints
- Semiconductor Input Volatility:Specialized ASICs and isolated ADCs for high-voltage measurement remain supply-constrained, extending lead times for diagnostic hardware manufacturers.
- Proprietary OEM Lock-in:Automotive manufacturers are restricting diagnostic port access and encrypting battery management system data, fragmenting the aftermarket service ecosystem.
- Technician Certification Bottlenecks:High-voltage safety training requirements under OSHA and EU machinery directives create workforce scarcity that limits tool utilization rates.
Strategic Opportunities
- India's EV Service Gap:The country's nascent electric two-wheeler and three-wheeler fleet lacks diagnostic infrastructure, creating first-mover advantage for modular, price-accessible platforms.
- AI-Cloud Convergence:Machine learning models trained on aggregated battery degradation data are enabling predictive maintenance subscriptions that recur beyond initial hardware sales.
- China MIIT Standardization:The ministry's push for unified diagnostic interfaces across domestic EV brands is opening the aftermarket to independent tool vendors previously excluded by proprietary systems.
Industry Challenges
- HV Safety Skill Shortage:Technicians qualified for high-voltage system isolation and arc-flash mitigation remain scarce relative to installed EV base growth, constraining service network expansion.
- Multi-Protocol Integration Complexity:Diagnostic tools must simultaneously interface with CAN FD, Ethernet-based automotive networks, and legacy OBD-II, multiplying firmware validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diagnostic Tools for Evs Market |
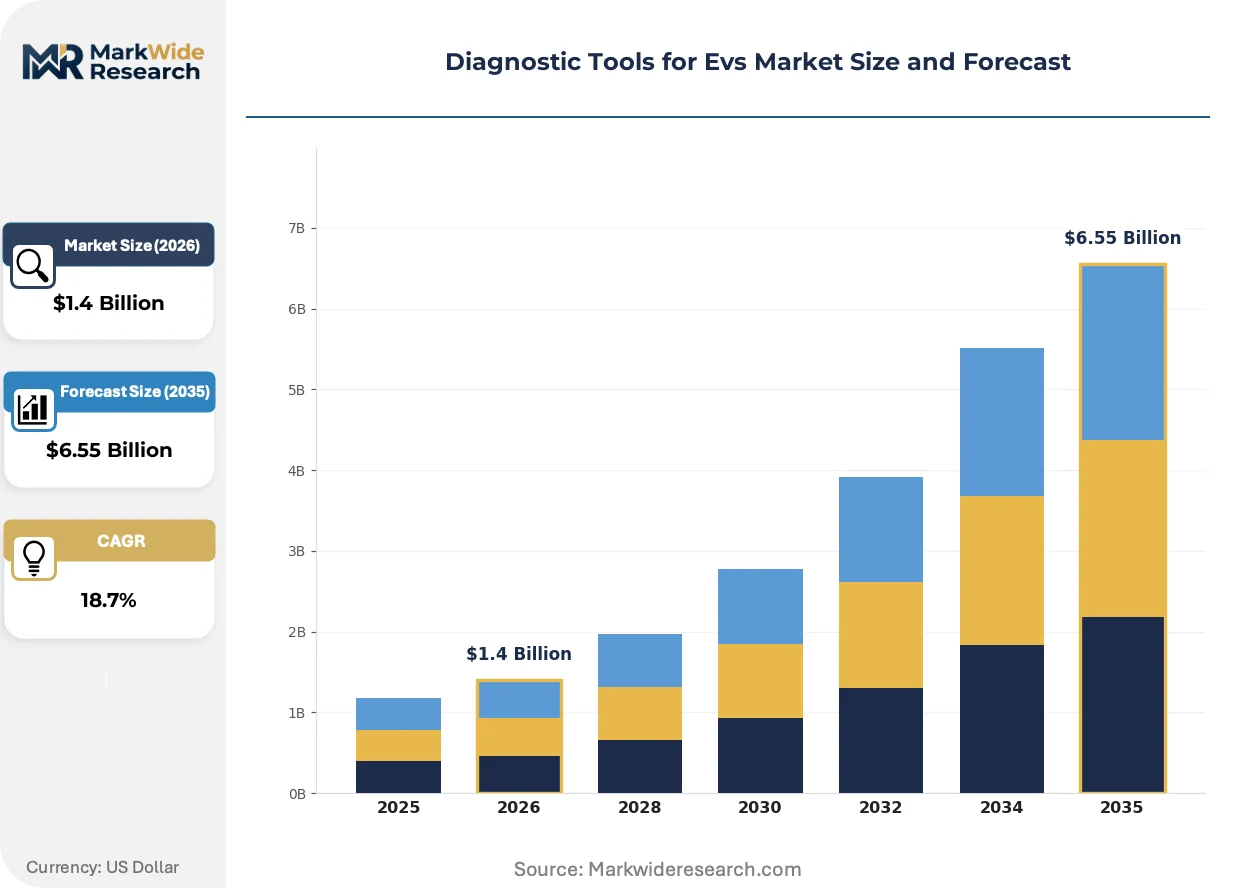
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $6.55 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Analyzers, Diagnostic Software, Charging Equipment, Testing Devices Technology: Wireless Communication, AI Integration, Sensor Technology, Cloud Computing End User: Automotive OEMs, Fleet Operators, Service Centers, Independent Mechanics Application: Vehicle Health Monitoring, Performance Diagnostics, Software Updates, Safety Checks |
| Companies Covered | Bosch Automotive Service Solutions, Autel Intelligent Tech, Snap-on Incorporated, Launch Tech Co., Ltd., Denso Corporation, FOXWELL, Innova Electronics, Topdon Technology, BlueDriver (Lemur Vehicle Monitors), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diagnostic Tools for Evs Market Strategic Shifts
Edge computing architectures are redistributing diagnostic intelligence from centralized servers toward vehicle-side and workshop-floor processors, compressing latency for safety-critical battery assessments.
Wireless over-the-air diagnostic modules are digitizing how battery health data flows from vehicle to service center. Fleet operators in California and the Netherlands are deploying these systems at scale to eliminate physical tethering during depot inspections. The technology is digitizing the economics of preventive maintenance by collapsing truck-roll requirements and enabling continuous monitoring without bay occupancy.
The EU F-Gas Regulation is tightening thermal management system leak detection requirements for battery cooling circuits. Diagnostic tool vendors must now integrate refrigerant identification and pressure-decay testing into battery analyzer platforms. European service centers are responding by consolidating thermal and electrical diagnostics into single-workstation workflows to maintain throughput.
Subscription-based hardware access is displacing capital purchase models among independent repair networks. Asset-light leasing through captive financing arms allows smaller service providers to access OEM-grade diagnostic capability without balance-sheet strain. This shift is most pronounced in Germany's Mittelstand automotive supplier ecosystem, where tooling refresh cycles have compressed from seven years to three.
Diagnostic Tools for Evs Market Segmentation
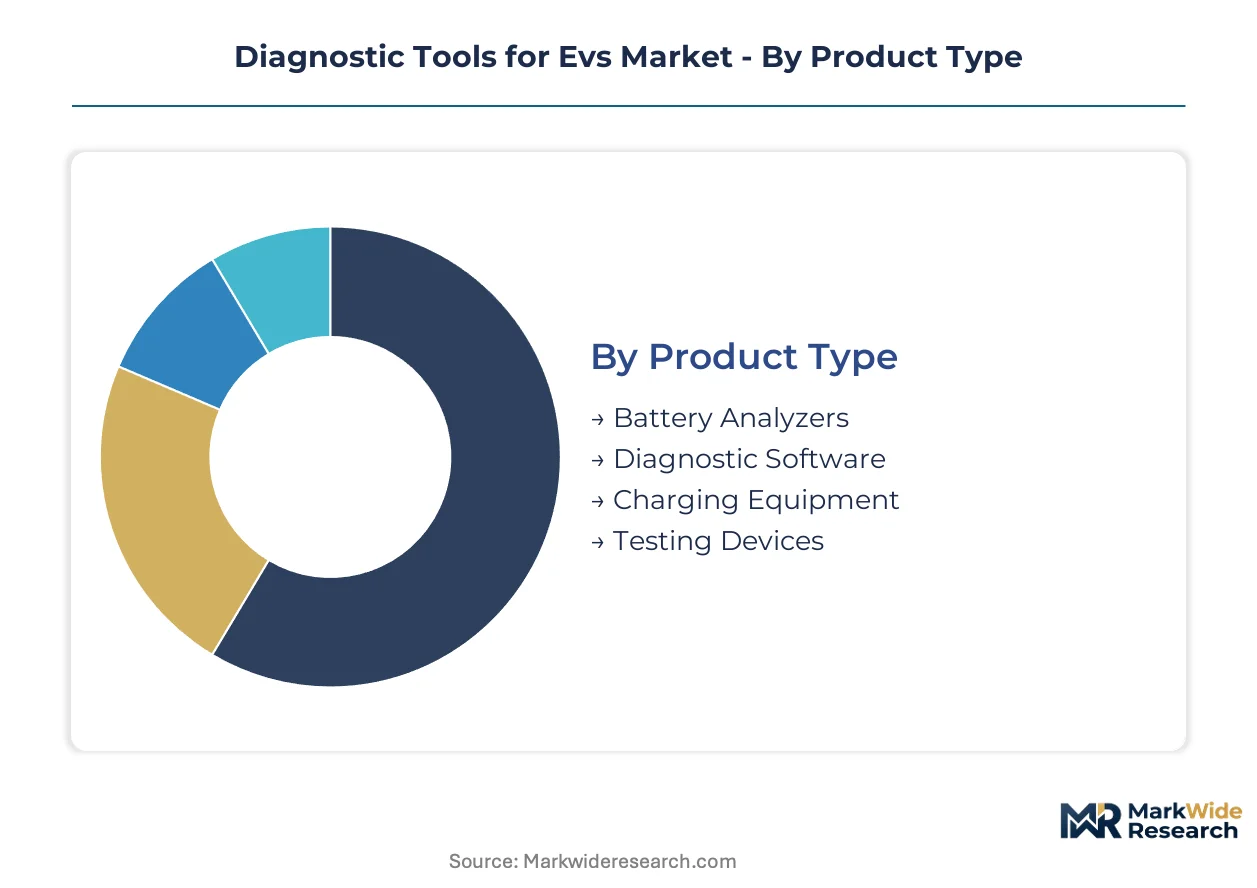
Diagnostic tool procurement cycles vary dramatically across segment boundaries. Battery analyzers refresh every three years while charging equipment testers extend to seven-year replacement windows. Understanding these velocity differentials shapes inventory planning and service network investment priorities.
Product Type:
Battery analyzers turn over fastest due to firmware obsolescence, while charging equipment testers enjoy the longest replacement cycles.
- Battery Analyzers:These devices perform state-of-charge validation, cell balancing verification, and thermal runaway risk assessment through high-voltage isolation architectures. Demand clusters around Germany's Stuttgart-Munich corridor where fleet operators face EU Battery Health Mandate compliance deadlines.
- Diagnostic Software:Cloud-deployed platforms with recurring subscription revenue models dominate margin capture. The EPA and NHTSA emissions-equivalent reporting requirements in the United States are compelling service centers to upgrade from perpetual licenses to continuously validated cloud stacks.
- Charging Equipment Testing Devices:Hardware validation tools for EVSE interoperability and safety certification. China's MIIT standardization push is expanding addressable market for independent vendors previously locked out by proprietary OEM ecosystems.
Battery analyzers dominate installed base. Diagnostic software is where expansion concentrates.
Technology:
Cost tiers separate premium AI-integrated platforms from commoditized wireless modules.
- AI Integration:Machine learning models trained on aggregated battery degradation datasets enable predictive maintenance subscriptions. Fleet operators in California deploy these systems to eliminate truck-roll requirements through continuous health monitoring.
- Cloud Computing:Centralized diagnostic intelligence with over-the-air update pipelines. The EU F-Gas Regulation refrigerant tracking requirements are forcing thermal management diagnostics onto cloud-connected platforms for audit trail compliance.
- Wireless Communication:Bluetooth and cellular modules for untethered vehicle-to-workshop data transmission. Volume leadership persists across aftermarket channels despite margin compression.
- Sensor Technology:Current, voltage, and temperature sensing arrays for cell-level monitoring. Modular architectures allow hardware reuse across LFP, NMC, and solid-state battery chemistries without full system replacement.
Wireless communication dominates installed base. AI integration is where expansion concentrates.
End User:
Application intensity varies from OEM captive programs to fragmented independent mechanic adoption.
- Service Centers:Multi-bay operations with standardized tooling protocols and technician certification programs. OSHA high-voltage safety training requirements constrain workforce scaling in the United States.
- Fleet Operators:Depot-based maintenance organizations with vehicle uptime optimization mandates. Asset-light leasing models through captive financing arms are displacing capital purchase approaches.
- Automotive OEMs:Proprietary diagnostic ecosystem builders restricting port access and encrypting battery management system data. Fragmentation of aftermarket service ecosystems intensifies competitive tension.
- Independent Mechanics:Price-sensitive single-location operators. India's nascent electric two-wheeler and three-wheeler fleet presents first-mover opportunity for modular, accessible platforms.
Service centers dominate installed base. Fleet operators are where expansion concentrates.
Application:
Customer type separates safety-critical regulatory compliance from elective performance optimization.
- Vehicle Health Monitoring:Continuous battery state-of-health tracking with predictive failure alerting. Edge computing architectures redistribute processing toward vehicle-side processors to compress latency.
- Safety Checks:High-voltage system isolation verification and arc-flash risk assessment. Technician certification bottlenecks under EU machinery directives limit utilization rates.
- Performance Diagnostics:Drive cycle analysis and efficiency optimization for range maximization. Enthusiast segment demand in Germany's automotive engineering corridor supports premium pricing.
- Software Updates:Firmware flashing for battery management system parameter adjustment. Over-the-air capabilities are digitizing economics of preventive maintenance.
Vehicle health monitoring dominates installed base. Safety checks are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Battery Health Mandates and China's MIIT standardization protocols are accelerating diagnostic infrastructure deployment across major automotive manufacturing economies. Fleet operators in Germany, the United States, and China face compliance deadlines that compress procurement cycles for battery analyzers and cloud-connected diagnostic platforms. The analysis identifies five countries where policy incentives and industrial clustering concentrate market development.
United States
Fleet operators in California deploy wireless over-the-air diagnostic modules at scale to eliminate truck-roll requirements and enable continuous battery health monitoring. EPA and NHTSA emissions-equivalent reporting requirements compel service centers to upgrade from perpetual software licenses to continuously validated cloud stacks. The Pacific Northwest hosts emerging edge computing R&D facilities redistributing diagnostic intelligence toward vehicle-side processors.
Germany
The Stuttgart-Munich automotive engineering corridor concentrates R&D investment and technician training programs, creating dense demand for advanced battery analyzers and thermal management diagnostics. EU F-Gas Regulation refrigerant tracking requirements force thermal diagnostics onto cloud-connected platforms for audit trail compliance. Bavarian service centers consolidate thermal and electrical diagnostics into single-workstation workflows to maintain throughput under tightening regulatory scrutiny.
China
MIIT standardization for unified diagnostic interfaces across domestic EV brands opens the aftermarket to independent tool vendors previously excluded by proprietary OEM ecosystems. The Yangtze River Delta manufacturing belt generates concentrated demand for modular diagnostic platforms serving electric two-wheeler and commercial vehicle production lines. Shanghai-based fleet operators pilot AI-integrated predictive maintenance subscriptions trained on aggregated battery degradation datasets.
India
The country's nascent electric two-wheeler and three-wheeler fleet lacks diagnostic infrastructure, creating first-mover advantage for modular, price-accessible platforms targeting independent mechanics. Central Electricity Authority regulations on battery safety testing are mandating standardized validation protocols for emerging EV service networks. Maharashtra and Gujarat industrial corridors attract diagnostic tool distributors establishing regional training centers for high-voltage safety certification.
Japan
METI guidelines on battery circularity and second-life applications are compelling precision diagnostic capabilities for state-of-health grading in repurposing markets. The Kansai region around Osaka hosts specialized sensor technology development for cell-level monitoring arrays. Toyota City and Nagoya manufacturing clusters drive demand for diagnostic tools interfacing with solid-state battery pilot production lines.
Diagnostic Tools for Evs Market Competitive Environment
On the supply side, the industry is consolidating around three strategic archetypes: diversified automotive conglomerates with captive financing arms, specialized diagnostic equipment manufacturers with technician certification lock-in programs, and modular platform vendors competing on price accessibility in emerging markets. Competitive positioning intensifies through asset-light leasing model proliferation and AI-cloud convergence for predictive maintenance subscriptions. Strategic moves concentrate on vertical integration into high-voltage measurement component supply and geographic expansion through localized training partnerships.
Within the diversified conglomerate tier, Bosch Automotive Service Solutions exemplifies supply-side consolidation through integrated hardware-software-financing bundles. Snap-on Incorporated anchors the specialized equipment archetype with established technician training infrastructure. Launch Tech Co., Ltd. occupies the modular platform position, representing price-accessible competition in markets with compressed procurement budgets. These three entities collectively illustrate how competitive positioning fragments across premium integrated solutions, certification-dependent recurring revenue models, and emerging market volume strategies.
| Leading Market Players |
|---|
| Bosch Automotive Service Solutions |
| Autel Intelligent Tech |
| Snap-on Incorporated |
| Launch Tech Co., Ltd. |
| Denso Corporation |
| FOXWELL |
| Innova Electronics |
| Topdon Technology |
| BlueDriver (Lemur Vehicle Monitors) |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Alpine freight corridor's container rate volatility feeds directly into landed cost spreads between German engineering clusters and emerging Asian assembly points, compressing margins for modular diagnostic platforms while amplifying price premiums on CE-certified battery analyzers dispatched through Rotterdam port terminals.
Pricing Analysis
Certification level creates the primary spread between ISO 6469-1 compliant high-voltage analyzers and uncertified workshop-grade units. Three-tier pricing structure separates OEM-grade bundled subscriptions from independent service center leases and unlicensed gray-market imports. Cost compression in the economy tier stems from Shenzhen-based modular platform vendors flooding India's electric two-wheeler aftermarket. Fleet operators demonstrate lowest price sensitivity due to uptime guarantee penalties, while independent mechanics in Maharashtra exhibit acute cost consciousness.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn Industrial Internet and Jabil Circuit holding capacity for isolated ADC assemblies and high-voltage protection modules. Geographic supply concentration centers on Taiwan for specialized ASICs, Germany for precision sensor arrays, and China for lithium-ion cell testing reference units. Raw material dependencies include gallium nitride substrates, polyimide films for high-voltage isolation, and rare-earth magnets for current transducers. Single-source vulnerability persists around automotive-grade isolated gate drivers from Infineon. Distribution runs through Bosch's captive service network, Snap-on's mobile franchise fleet, and Alibaba's B2B marketplace for emerging market independents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in the technician certification bottleneck, where qualified high-voltage specialists lag EV fleet growth by a three-to-one ratio, creating defendable niches for training-integrated tool vendors.
For Market Incumbents: Insulate recurring revenue streams by embedding diagnostic software subscriptions into OSHA-mandated technician recertification programs. Deepen backward integration into isolated ADC supply through captive foundry partnerships in Taiwan. Defend against modular platform erosion by restricting battery management system protocol access through encrypted OBD-II gateways. For New Entrants and Emerging Players: Establish a beachhead in India's electric three-wheeler service depots where diagnostic infrastructure remains undeveloped and procurement budgets favor lease-to-own hardware arrangements. Target Maharashtra and Gujarat industrial corridors with localized high-voltage safety training bundled at marginal cost. Deploy cloud-native diagnostic platforms with vernacular-language interfaces to bypass incumbent certification lock-in. For Investors and Strategic Acquirers: AI-cloud convergence specialists with trained battery degradation models represent the most defensible acquisition archetype for predictive maintenance recurring revenue. Long-term viability hinges on regulatory divergence between EU Battery Health Mandates and China's MIIT standardization protocols creating persistent multi-jurisdictional compliance demand. Watch for inflection when OSHA expands high-voltage training mandates to commercial vehicle segments beyond passenger cars.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Integration | Bundles diagnostic tool subscriptions with OSHA-mandated high-voltage safety recertification programs. |
| AI-Cloud Platform Development | Enables predictive maintenance subscriptions trained on aggregated battery degradation datasets from California fleet pilots. |
| Backward Integration into Isolated ADCs | Secures captive supply of automotive-grade high-voltage measurement components from Taiwan foundries. |
| India Market Localization | Addresses electric two-wheeler and three-wheeler service gaps through vernacular-language diagnostic interfaces. |
| EU F-Gas Compliance Bundling | Consolidates thermal management leak detection with electrical diagnostics for Bavarian service center throughput. |
Study Parameters
Initial hypotheses were tested against primary input from EV service center operations directors, fleet maintenance managers, diagnostic equipment procurement leads, and high-voltage safety training instructors, then refined through secondary validation against NHTSA safety filings, EU Battery Health Mandate regulatory texts, MIIT standardization drafts, and IHS Markit EV production databases. Bottom-up segment sizing triangulated with top-down market envelope checks.
Demand-supply balance framing anchored the analytical approach across the analysis window, with segmentation modeled across product type, technology tier, end-user archetype, and application intensity. CAGRs derived from logistic diffusion curves fitted to EV fleet penetration rates and diagnostic tool replacement velocity differentials. Key inputs included battery analyzer refresh cycles, charging equipment tester replacement windows, and cloud software subscription attach rates.
Macroeconomic conditions sit as an overlay; deviation in semiconductor input costs, freight corridor rates, or EV fleet electrification subsidies would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement timelines and technician certification expansion rates. Quarterly review of MIIT standardization implementation progress and OSHA training mandate scope expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Automotive Diagnostic Tools Market
Automotive Testing and Simulation
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market
Automotive Testing and Simulation
High-Speed Highway Pilot and Lane Change Scenario Test Platforms Market
Automotive Testing and Simulation
Automated Guided Cart Market
Automotive Testing and Simulation
Electric Vehicle Test Bench Market
Automotive Testing and Simulation
Automotive Weigh in Motion Market
Automotive Testing and Simulation
Tire Testing Machine Market
Automotive Testing and Simulation
ADAS Calibration and Alignment Equipment Systems Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Testing Equipment Market
Automotive Testing and Simulation
Automotive Crash Test Dummies Market
Automotive Testing and Simulation
Dynamometer Market
Automotive Testing and Simulation
Vehicle Radar Test System Market
Automotive Testing and Simulation
Automotive Test Equipment Market
Automotive Testing and Simulation
Vehicle Crash Testing Services Market
Automotive Testing and Simulation
Wheel Alignment Equipment Market