
 Torque Gauge Market | 2026-2036
Torque Gauge Market Size, Share, and Industry Trends Forecast 2026-2036
Torque Gauge Market Outlook
The capital-intensity gap between high-end sensor manufacturers and commoditized mechanical gauge producers is collapsing as MEMS-based electronic modules fall in price. AMETEK Calibration Inc. leverages its vertically integrated metrology labs to sustain premium positioning across aerospace certification channels. Mecmesin Ltd. anchors its European footprint with automated torque testing systems for medical device manufacturers. Snap-on Incorporated dominates North American automotive service channels through franchise-based tool distribution.
A torque gauge measures rotational force applied to fasteners, shafts, or assemblies, typically displaying values in newton-meters, inch-pounds, or foot-pounds with resolution thresholds as fine as 0.01 N·m in digital laboratory models. The instrument verifies that bolted joints meet specified clamp loads, preventing mechanical failure in safety-critical structures. Digital torque gauges lead the product type dimension due to data-logging capabilities and traceability requirements in regulated industries, while calibration tools command the highest margin pools as third-party accreditation becomes mandatory. Electronic technology displaces manual and pneumatic alternatives in quality control applications where SPC integration and real-time pass-fail documentation are non-negotiable.
FDA 21 CFR Part 820 quality system regulations mandate validated torque testing for medical device assembly, compelling manufacturers to maintain calibrated instrument fleets with documented measurement uncertainty budgets. ISO 6789 and NIST-traceable standards govern tool calibration intervals in automotive and aerospace sectors, creating recurring service revenue streams for gauge suppliers. ASTM E2428 provides torque sensor verification protocols that shape product design specifications for North American industrial customers. Stakeholders must monitor the divergence between cloud-connected smart gauges and standalone units as factory digitization investments reshape procurement criteria and aftermarket service expectations.
Market Dynamics
MEMS-based electronic torque sensing is collapsing the historical cost barrier between laboratory-grade digital instruments and mechanical dial gauges, compressing replacement cycles and forcing recalibration service providers to defend margin through vertical integration into metrology software.
Growth Catalysts
- ISO 6789 Calibration Mandates:Germany and Japan enforce shortened instrument replacement intervals, accelerating hardware refresh rates in automotive assembly corridors.
- China's EV Manufacturing Concentration:Electric vehicle battery pack assembly lines in Shenzhen and Shanghai deploy precision torque verification stations at scale.
- MEMS Sensor Cost Curves:Semiconductor miniaturization enables sub-dollar strain gauge integration, democratizing electronic measurement previously reserved for aerospace budgets.
Market Restraints
- Raw Material Concentration:Rare earth magnet supply for torque transducer cores concentrates in Chinese processing facilities, exposing downstream gauge assemblers to export quota volatility.
- Technical Performance Ceiling:MEMS-based modules struggle to match piezoelectric sensor resolution below 0.005 N·m, limiting penetration in surgical instrument calibration.
- Regulatory Friction from MDR:Europe's Medical Device Regulation extends conformity assessment timelines for torque testers used in orthopedic implant assembly.
Strategic Opportunities
- Cloud-Connected Smart Gauges:Factory digitization investments in Germany's Industrie 4.0 corridors create demand for SPC-integrated torque instruments with real-time pass-fail telemetry.
- FDA 21 CFR Part 820 Tailwinds:Validated torque testing mandates for medical device manufacturers compel fleet standardization around accredited instrument suppliers.
- Service Channel Innovation:Franchise-based tool distributors in the United States bundle calibration subscriptions with hardware sales, capturing recurring revenue streams.
Industry Challenges
- Metrology Talent Scarcity:ISO 17025-accredited calibration technicians command premium wages, constraining third-party service lab expansion.
- Legacy System Integration:Digital torque gauges face protocol friction when interfacing with decades-old manufacturing execution systems in mature automotive plants.
- Certification Timeline Compression:NIST-traceable calibration certificate turnaround pressures service providers to automate uncertainty budget documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Torque Gauge Market |
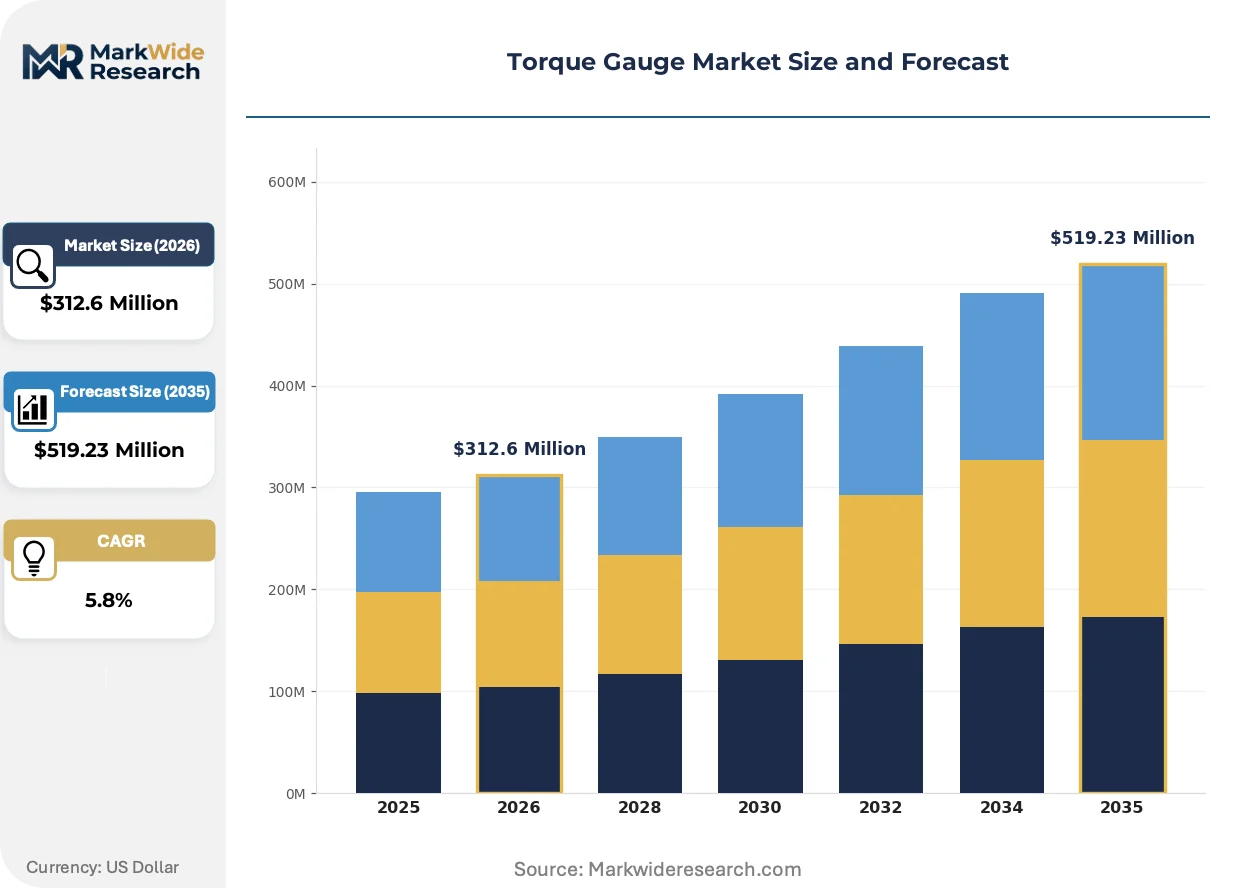
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $519.23 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Torque Gauges, Mechanical Torque Gauges, Calibration Tools, Torque Wrenches End User: Aerospace, Automotive, Manufacturing, Construction Technology: Electronic, Hydraulic, Pneumatic, Manual Application: Quality Control, Research and Development, Maintenance, Production |
| Companies Covered | AMETEK Calibration Inc., Mecmesin Ltd., Snap-on Incorporated, IMADA Inc., Futek Advanced Sensor Technology Inc., Mountz Inc., Hottinger Brüel & Kjær A/S, Norbar Torque Tools Ltd., Kistler Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Torque Gauge Market Strategic Shifts
Three convergent forces are reshaping torque gauge architecture: semiconductor cost compression, regulatory documentation requirements, and factory-floor connectivity mandates. These pressures favor electronic platforms over mechanical predecessors.
MEMS-based strain sensing is decomposing the traditional separation between portable field gauges and fixed laboratory stations. Automotive tier-one suppliers in Stuttgart and Wolfsburg now deploy identical electronic modules across assembly lines and quality labs, collapsing the SKU diversity that previously protected mechanical gauge margins. The technology is decomposing regional pricing stratification by enabling single-platform global sourcing.
Europe's MDR and the FDA's 21 CFR Part 820 are converging on electronic data integrity requirements for torque verification in medical device assembly. Manufacturers must maintain immutable audit trails of every fastening operation, rendering paper-based dial gauge readings non-compliant. German orthopedic implant producers and Massachusetts cardiovascular device firms are accelerating digital gauge procurement to satisfy notified body scrutiny.
Outcome-based calibration contracts are displacing transactional certificate sales in aerospace supply chains. Tier-two fastener distributors in Toulouse and Wichita now subscribe to annual instrument fleet management services rather than purchasing ad-hoc recalibration. This shift compresses vendor count and rewards gauge suppliers with captive metrology software ecosystems.
Torque Gauge Market Segmentation
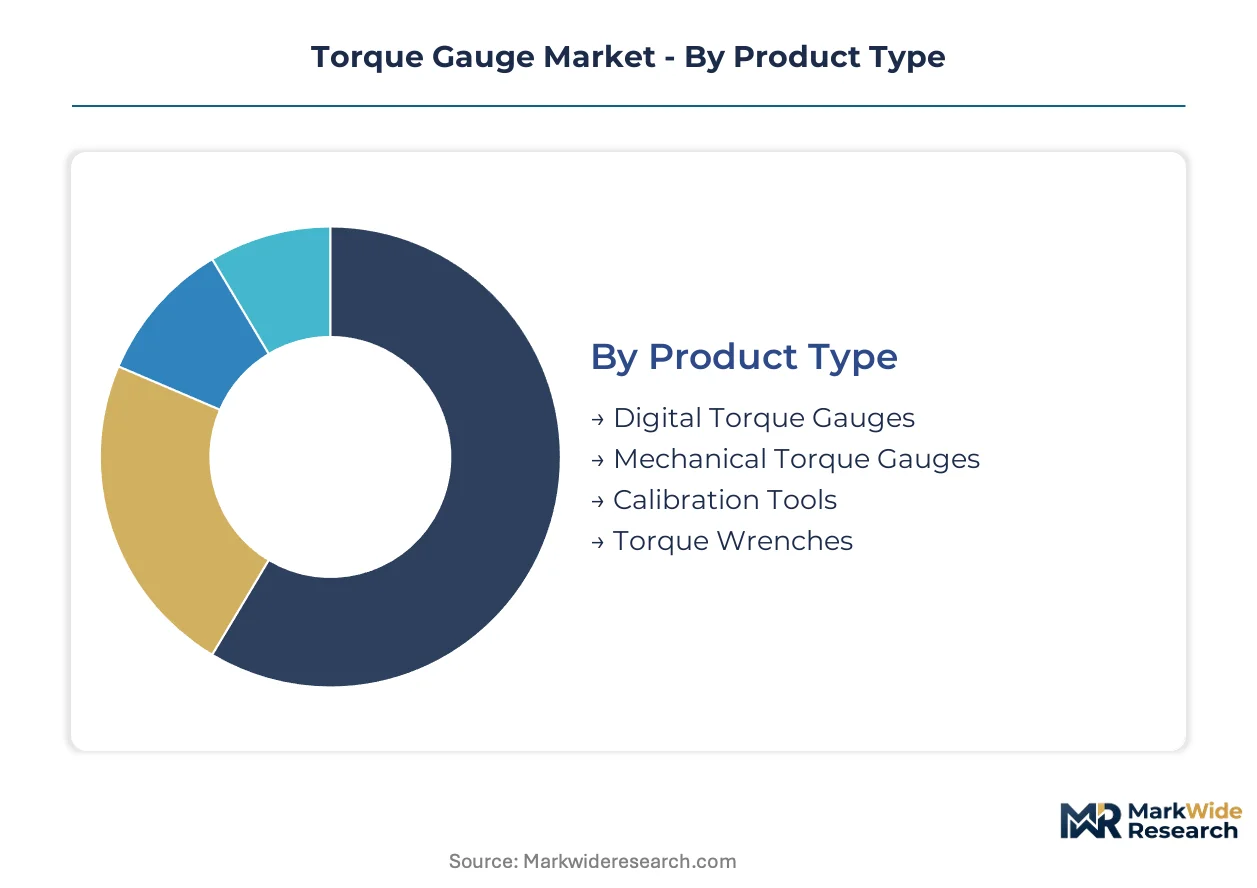
Torque gauge procurement divides sharply between regulated industries demanding traceable calibration chains and general manufacturing seeking functional verification. Segmentation reveals how ISO 6789 compliance tiers, MEMS cost curves, and end-use criticality reshape vendor positioning across product categories.
Product Type:
FDA 21 CFR Part 820 and ISO 6789 create divergent hardware requirements between laboratory-grade digital platforms and field-service mechanical alternatives.
- Digital Torque Gauges:MEMS-based strain sensing modules deliver 0.01 N·m resolution with integrated data-logging for SPC integration. Demand concentrates in Massachusetts cardiovascular device firms and German orthopedic implant producers facing immutable audit trail mandates under FDA and MDR frameworks.
- Calibration Tools:NIST-traceable reference standards and automated calibration stations command premium positioning through accredited uncertainty documentation. German automotive assembly corridors in Stuttgart and Wolfsburg drive replacement cycle compression under shortened ISO 6789 intervals.
- Mechanical Torque Gauges:Dial-indicator platforms persist in construction field applications where battery dependence and electronic fragility create operational risk.
- Torque Wrenches:Click-type and beam-style manual tools dominate North American franchise-based automotive service channels.
Established volume favors mechanical torque gauges; emerging adoption favors digital torque gauges.
End User:
End-use concentration tracks directly to fastening criticality in safety structures and regulatory inspection intensity.
- Automotive:Battery pack assembly lines in Shenzhen and Shanghai deploy precision verification stations at scale for electric vehicle production. China's EV manufacturing corridors anchor the fastest-expanding demand trajectory.
- Aerospace:Toulouse and Wichita fastener distributors subscribe to annual fleet management services rather than transactional calibration, compressing vendor count toward suppliers with captive metrology software ecosystems.
- Manufacturing:General industrial quality control applications favor cost-optimized electronic modules as MEMS prices collapse.
- Construction:Field torque verification for structural steel and heavy equipment relies on ruggedized mechanical gauges with minimal maintenance requirements.
Procurement scale concentrates in automotive; margin capture concentrates in aerospace.
Technology:
Technology selection hinges on resolution thresholds, environmental exposure, and integration architecture with legacy manufacturing execution systems.
- Electronic:Semiconductor miniaturization enables sub-dollar strain gauge integration, democratizing measurement precision previously reserved for aerospace budgets. Cloud-connected variants with real-time pass-fail telemetry gain traction in Germany's Industrie 4.0 corridors.
- Manual:Zero-power operation and mechanical simplicity sustain relevance in remote construction sites and developing manufacturing economies.
- Pneumatic:Assembly line integration for high-volume fastening operations persists in mature automotive plants with established compressed air infrastructure.
- Hydraulic:Extreme torque ranges for heavy machinery and oilfield equipment applications where electronic sensor saturation occurs.
Electronic platforms claim expanding share; manual systems defend installed base in cost-sensitive segments.
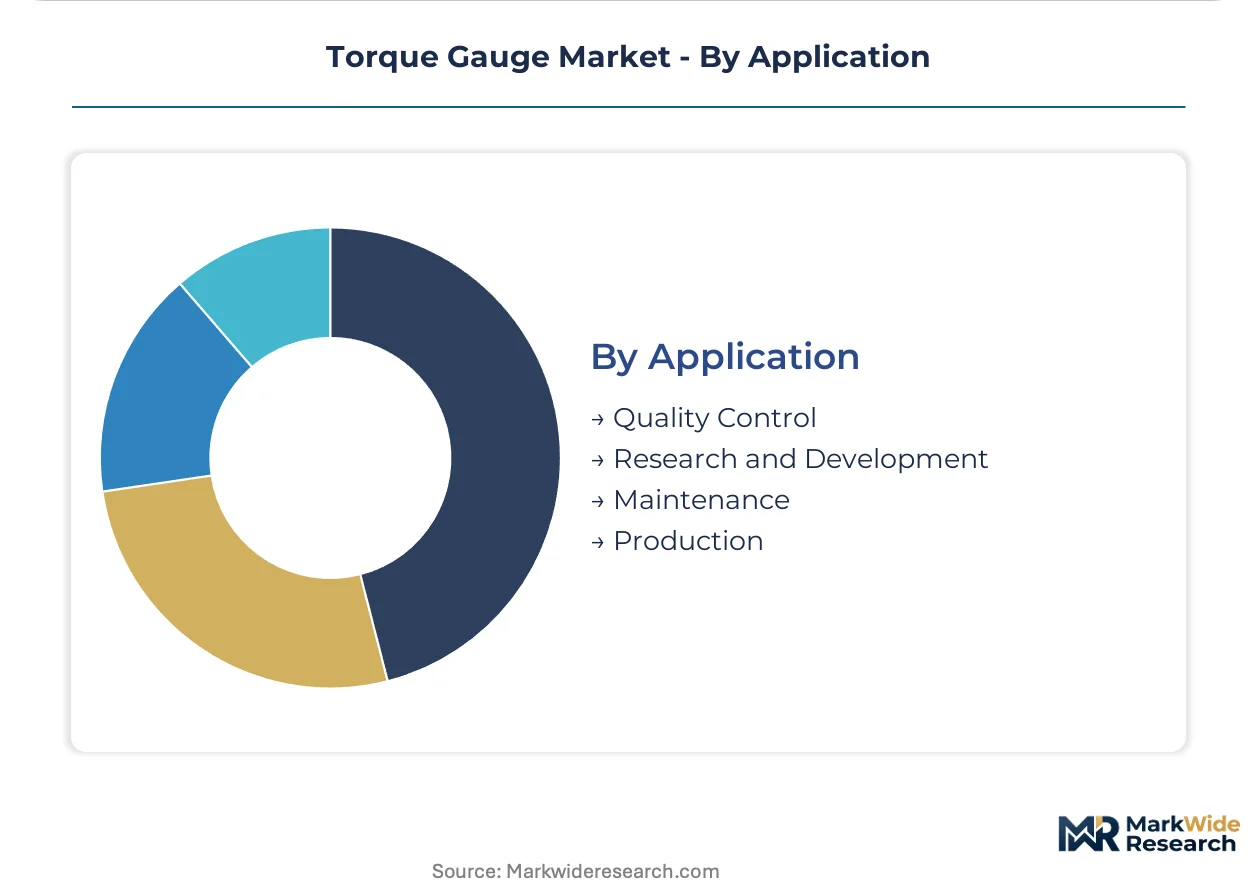
Application:
Application segmentation reflects the documentation burden imposed by quality system regulations and production volume economics.
- Quality Control:Statistical process control integration and real-time pass-fail documentation are non-negotiable in medical device and aerospace supply chains. Electronic gauges with immutable data trails dominate.
- Production:High-volume assembly line deployment favors ruggedized electronic modules with wireless telemetry for bottleneck monitoring.
- Maintenance:Field service applications balance portability against calibration interval requirements, favoring battery-operated digital platforms with extended certification periods.
- Research and Development:Laboratory environments demand highest-resolution piezoelectric sensors below 0.005 N·m where MEMS modules face performance ceilings.
Production volume anchors hardware sales; quality control specifications drive technology upgrading.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in precision instrumentation tilt toward manufacturing economies with dense automotive and medical device clusters. Germany and China run structural surpluses in calibrated torque verification equipment. The United States and Japan remain net importers of laboratory-grade digital platforms despite significant domestic assembly capacity.
China
Electric vehicle battery pack assembly in Shenzhen and Shanghai consumes precision torque verification stations at scale. SAMR's tightened metrology certification requirements compress replacement intervals for production-line instruments. BYD and CATL supplier parks in Guangdong Province anchor the fastest-expanding demand corridor for MEMS-based electronic gauges.
Germany
Stuttgart and Wolfsburg automotive corridors drive ISO 6789-mandated hardware refresh cycles among tier-one suppliers. KBA enforcement of shortened calibration intervals accelerates instrument turnover in final assembly plants. Bavarian medical device manufacturers in Tuttlingen and Erlangen deploy cloud-connected smart gauges to satisfy MDR audit trail requirements.
United States
Massachusetts cardiovascular device firms and Wichita aerospace fastener distributors demand validated torque testing with immutable data documentation. FDA 21 CFR Part 820 quality system regulations compel fleet standardization around NIST-traceable instrument suppliers. Snap-on's franchise network captures aftermarket calibration subscriptions across Midwest automotive service channels.
Japan
Precision manufacturing clusters in Aichi Prefecture and Kanagawa maintain stringent JIS calibration protocols for automotive and electronics assembly. METI's push for factory digitization favors SPC-integrated torque instruments with real-time telemetry. Toyota and Honda supplier parks in Nagoya anchor premium demand for piezoelectric sensor platforms below 0.005 N·m resolution.
India
Automotive component manufacturing in Pune and Chennai adopts electronic torque verification as OEM export compliance tightens. BIS implementation of ISO 6789-aligned standards accelerates replacement of mechanical dial gauges in quality labs. Medical device parks near Bengaluru and Hyderabad invest in calibrated instrument fleets to serve contract manufacturing for European and North American markets.
Torque Gauge Market Competitive Environment
Concentration sits with vertically integrated metrology specialists and franchise-based tool distributors. The vendor base separates into three functional tiers: aerospace-certified laboratory equipment suppliers, automotive service channel distributors, and cost-optimized electronic module assemblers. Consolidation pressure favors players with captive calibration service networks and cloud-connected software ecosystems. Strategic moves cluster around backward integration into sensor manufacturing and geographic expansion through distributor acquisition.
Among North American precision instrumentation specialists, AMETEK Calibration Inc. and Futek Advanced Sensor Technology Inc. exemplify the aerospace-certified tier with metrology lab integration. European torque verification specialists Mecmesin Ltd. and Norbar Torque Tools Ltd. occupy positions emphasizing automated testing systems and accredited calibration chains. Japanese precision sensor manufacturers IMADA Inc. and Kistler Holding AG represent the high-resolution piezoelectric segment serving semiconductor and medical device applications. These six entities anchor competitive positioning across the technology spectrum from MEMS-based field gauges to laboratory-grade reference standards.
| Leading Market Players |
|---|
| AMETEK Calibration Inc. |
| Mecmesin Ltd. |
| Snap-on Incorporated |
| IMADA Inc. |
| Futek Advanced Sensor Technology Inc. |
| Mountz Inc. |
| Hottinger Brüel & Kjær A/S |
| Norbar Torque Tools Ltd. |
| Kistler Holding AG |
| Others |
Value Chain & Pricing Dynamics
ISO 6789 calibration mandates in Germany and Japan simultaneously gate supplier qualification and stratify pricing tiers by certification depth, compressing margins for mechanical gauge assemblers while rewarding NIST-traceable laboratories with premium positioning. Automotive OEM procurement teams leverage shortened replacement intervals to consolidate vendor lists toward accredited metrology specialists with captive software ecosystems.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with laboratory-grade digital platforms commanding substantial premiums over field-service mechanical alternatives. Price differentiation rests on ISO 17025 accreditation status and MEMS sensor resolution thresholds, with aerospace-certified suppliers capturing least price-sensitive demand from FDA-regulated medical device manufacturers. Cost compression in electronic modules is intensifying because semiconductor miniaturization collapses historical performance-cost tradeoffs, forcing mechanical gauge producers into steepest price erosion. Franchise-based automotive service channels exhibit highest price sensitivity, while orthopedic implant manufacturers in Massachusetts and Tuttlingen demonstrate minimal elasticity for validated torque testing fleets.
Supply Chain Analysis
Inventory lead times for piezoelectric sensor cores extend substantially beyond MEMS-based alternatives, constraining responsiveness in high-resolution gauge production. Geographic supply concentration centers on China for rare earth magnet processing, Taiwan for semiconductor strain gauge fabrication, and Germany for precision mechanical components. Raw material dependencies encompass neodymium-doped magnetic alloys, silicon wafer substrates, and specialized aluminum housing alloys. Single-source vulnerability in Chinese rare earth export quotas exposes downstream assemblers to quota volatility and geopolitical disruption. Distribution runs through vertically integrated metrology labs for accredited calibration services, franchise tool networks for automotive aftermarket, and direct OEM supply agreements for EV battery pack assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among automotive OEM procurement teams and aerospace tier-one suppliers, compressing vendor counts and favoring gauge manufacturers with integrated calibration service networks over standalone hardware producers.
For Market Incumbents: Consolidate backward integration into MEMS sensor manufacturing to defend margin against commoditization pressure from cost-optimized electronic module assemblers. Expand captive metrology software ecosystems to capture recurring calibration subscription revenue from aerospace fastener distributors in Toulouse and Wichita. Deepen ISO 17025 accreditation coverage across regional service labs to maintain premium positioning as FDA and MDR audit trail mandates tighten. For New Entrants and Emerging Players: Lead with cloud-connected smart gauge platforms targeting Germany's Industrie 4.0 corridors, where factory digitization investments outpace incumbent software capabilities. Penetrate India's automotive component manufacturing clusters in Pune and Chennai as OEM export compliance tightens and BIS standards align with ISO 6789. Deploy direct sales teams to medical device contract manufacturers near Bengaluru and Hyderabad, offering validated torque testing packages with immutable data documentation as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized torque gauge divisions lacking cloud connectivity roadmaps. Long-term viability favors suppliers with software-defined service revenue exceeding hardware transaction dependency. Monitor NIST calibration certificate automation rates as the inflection indicator for service lab scalability and margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Sensor Manufacturing | Captures cost compression benefits from semiconductor miniaturization while protecting proprietary resolution thresholds. |
| Cloud-Connected Smart Gauge Platform Launch | Addresses Industrie 4.0 demand in Stuttgart and Wolfsburg corridors with real-time SPC telemetry. |
| ISO 17025 Accreditation Expansion | Secures premium positioning as FDA 21 CFR Part 820 and MDR tighten calibration documentation mandates. |
| Calibration Subscription Service Bundling | Mirrors aerospace tier-two distributor shift from transactional certificates to annual fleet management contracts. |
| Geographic Manufacturing Footprint in China | Positions near BYD and CATL supplier parks in Guangdong Province for EV battery pack assembly demand. |
Study Parameters
A standing panel of plant engineers at automotive tier-one suppliers, biomedical engineers at cardiovascular device firms, calibration lab technicians, and aftermarket service directors provided ongoing calibration against secondary data trends. Primary interviews with OEM procurement teams and metrology specialists were cross-referenced against customs records for torque gauge trade flows, SEC filings from precision instrumentation specialists, ISO accreditation registry databases, and automotive production statistics from IHS Markit. Bottom-up demand modeling from end-use segment deployment rates was triangulated against top-down market sizing from supplier revenue aggregation.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation dimensions including product type resolution tiers, end-use criticality levels, technology platform architectures, and regional regulatory compliance clusters. CAGRs were derived from instrument replacement cycle compression under ISO 6789 mandates and EV manufacturing capacity expansion trajectories. Industry-specific forecast inputs encompassed SAMR certification timeline changes and METI factory digitization investment disclosures.
Underlying assumptions cover stable rare earth export quota regimes and MEMS cost curve continuity, with deviation risk concentrated in geopolitical supply disruptions and MDR conformity assessment timeline extensions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Automotive Emission Analyzer Market
Automotive Testing and Simulation
NDT in Automotive & Transportation Market
Automotive Testing and Simulation
Driving Simulator Market
Automotive Testing and Simulation
Vehicle Testing Equipment Market
Automotive Testing and Simulation
ADAS Calibration and Alignment Equipment Systems Market
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
On Board Diagnostics Device Market
Automotive Testing and Simulation
Vehicle Emission Testers Market
Automotive Testing and Simulation
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
Automotive Weigh in Motion Market
Automotive Testing and Simulation
Automotive TIC Market
Automotive Testing and Simulation
Automotive Exhaust Analyzer Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Testing Equipment Market
Automotive Testing and Simulation
Automotive Prognostics Market
Automotive Testing and Simulation
Electric Vehicle Test Equipment Market