
 Automotive Test Equipment Market | 2026-2036
Automotive Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Test Equipment Market Intelligence
A shortage of calibration engineers with embedded software expertise is unwinding production timelines at European test houses. HORIBA leverages its emission analyzer portfolio to anchor relationships with Japanese OEMs expanding into Southeast Asia. Robert Bosch GmbH competes through vertical integration into sensor hardware that feeds its diagnostic platforms. Siemens sustains R&D intensity in hardware-in-the-loop simulation for autonomous system validation.
Automotive test equipment comprises instrumented systems that measure vehicle performance parameters such as exhaust gas composition, brake force distribution, battery state-of-health, and ECU communication protocols under controlled or road-representative conditions. These systems employ CAN/LIN bus interfaces, chassis dynamometers, and climatic wind tunnels to reproduce regulatory drive cycles and durability loads. Diagnostic scanners and emission analyzers occupy mature margin pools where replacement demand and retrofit upgrades stabilize revenue. Cloud-based and automated technology segments attract fastest-growing interest as OEMs seek remote fleet monitoring and unattended end-of-line validation. Battery testers are gaining structural weight alongside electrification programs, though the installed base remains smaller than combustion-focused categories.
EPA emission certification rules and NHTSA safety compliance mandates in the United States, Euro 7 standards enforced by EMA processes in Europe, and China's GB standards administered by MEE collectively dictate test protocol specifications and equipment refresh cycles. REACH and RoHS frameworks constrain material choices in sensor housings and cable assemblies, adding compliance cost layers for manufacturers serving multiple jurisdictions. Stakeholders must monitor how software-defined vehicle architectures reshape the boundary between hardware test equipment and virtual validation environments.
Market Dynamics
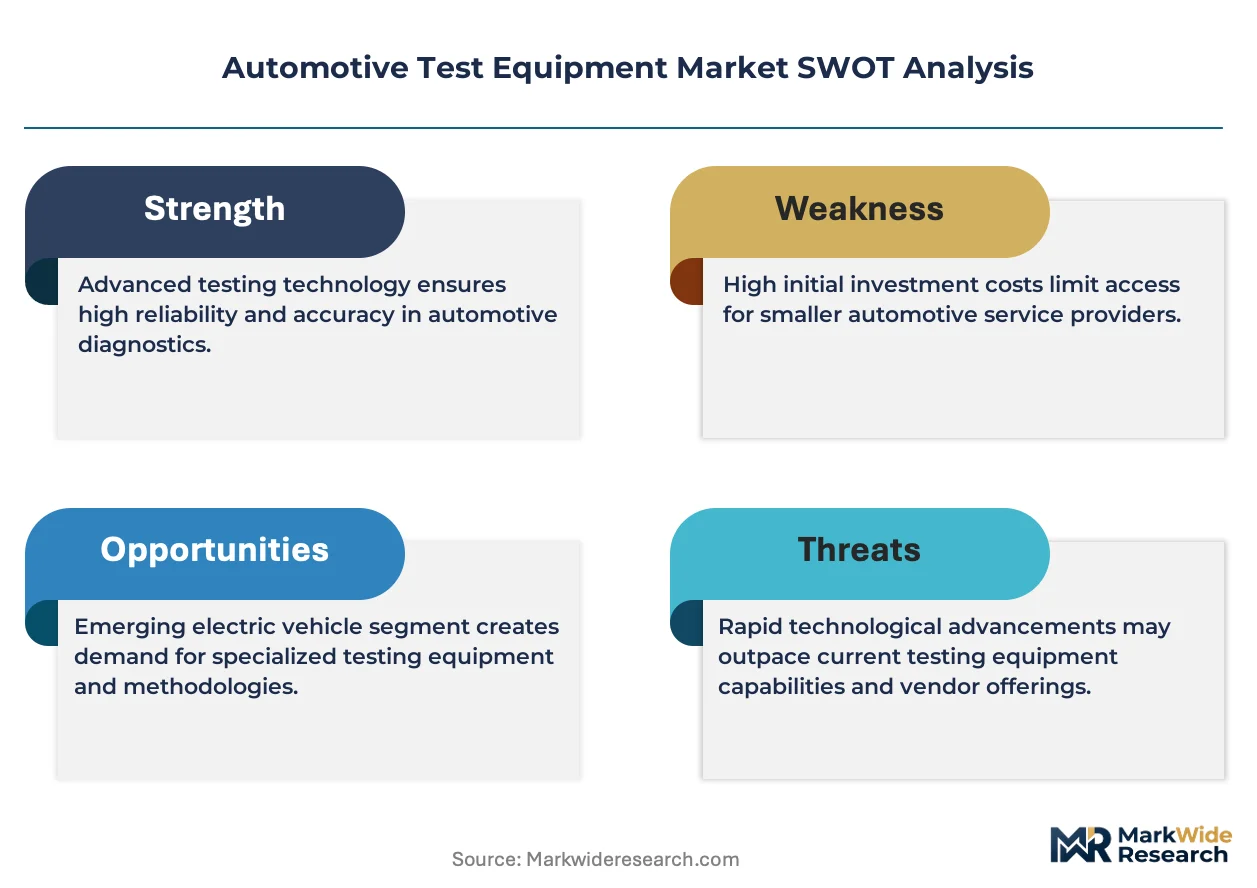
Electrification programs are forcing test houses to rebuild their installed base around battery cyclers and motor dynamometers, compressing the relevance of combustion-focused chassis rolls and tailpipe analyzers that anchored prior procurement cycles.
Growth Catalysts
- Euro 7 emission protocols:EMA-mandated laboratory recertification is compelling European OEMs to replace aging analyzers and upgrade test cell automation before enforcement deadlines.
- Power electronics:Silicon carbide inverter testing demands are pulling procurement toward high-frequency power analyzers and thermal cycling chambers for EV drivetrain validation.
- China:MEE-administered GB standards for new energy vehicle durability are accelerating test cell construction in Ningbo and Chongqing manufacturing clusters.
Market Restraints
- Sensor input costs:Noble metal prices for exhaust gas analyzer catalysts and lithium reference cells for battery testers create margin volatility for equipment manufacturers.
- Calibration engineer scarcity:European test houses face twelve-to-eighteen month hiring timelines for technicians with embedded software and power electronics expertise.
- WLTP protocol rigidity:The fixed drive cycle specification limits equipment differentiation and compresses pricing power for chassis dynamometer suppliers.
Strategic Opportunities
- India:BIS certification requirements for EV components are creating first-mover openings for battery tester suppliers as domestic OEMs establish validation capabilities.
- Hardware-in-the-loop convergence:Integration of power hardware simulation with software-defined vehicle architectures enables virtual-physical hybrid test cells.
- Cloud telemetry:Fleet-scale battery state-of-health monitoring creates recurring revenue streams beyond initial equipment sales.
Industry Challenges
- Multi-protocol integration:Test houses must synchronize CAN FD, Automotive Ethernet, and legacy LIN bus interfaces within unified validation platforms.
- Certification timeline compression:EPA and NHTSA parallel approval tracks for autonomous systems strain laboratory scheduling and engineer allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Test Equipment Market |
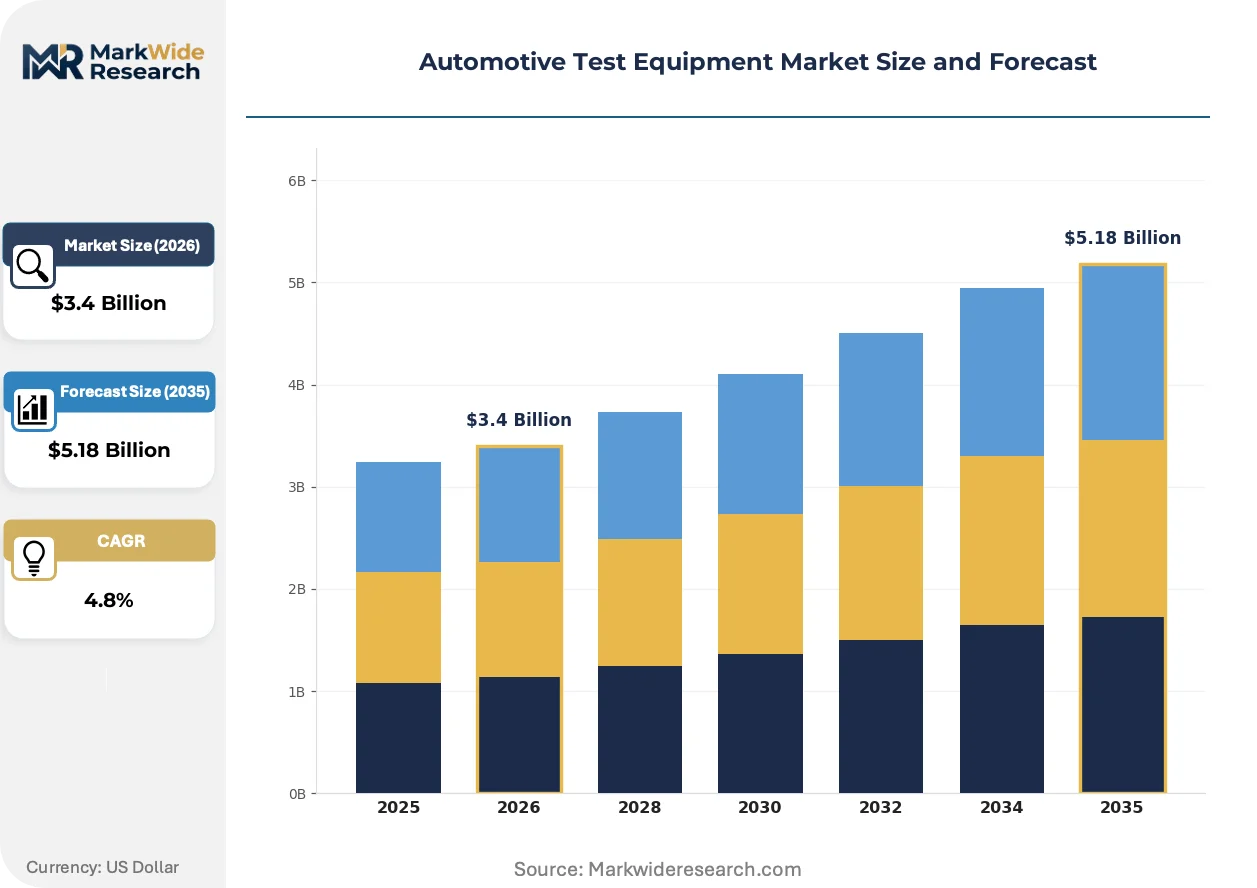
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.18 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Scanners, Emission Analyzers, Brake Testers, Engine Analyzers, Battery Testers Technology: Wireless, Wired, Cloud-Based, Handheld, Automated Application: Quality Control, Repair & Maintenance, Component Testing, Vehicle Inspection, Safety Compliance End User: OEMs, Repair Workshops, Testing Laboratories, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | HORIBA, Honeywell International Inc, Robert Bosch GmbH, AVL List GmbH, Softing AG, Siemens, ABB, Vector Informatik GmbH, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Test Equipment Market Strategic Shifts & Innovations
Test methodology is fragmenting across physical, virtual, and hybrid validation layers as software-defined vehicle architectures compress traditional hardware-dependent workflows.
Hardware-in-the-loop simulation is decomposing the boundary between physical test cells and virtual validation environments. Tier 1 suppliers and OEM validation teams are adopting HIL benches at pace to front-load ECU calibration before prototype assembly. This convergence is compressing capital allocation toward software licenses and real-time computing clusters rather than full vehicle dynamometer halls.
REACH and RoHS frameworks are constraining material selection for sensor housings and cable assemblies. ECHA substance restrictions are forcing redesigns of thermocouple sheaths and analyzer sampling lines. Equipment manufacturers serving multiple jurisdictions are absorbing compliance cost layers or segmenting product variants by regulatory zone.
Service unbundling is altering how test houses contract for equipment capability. End-of-line validation teams are separating hardware procurement from calibration and maintenance contracts, treating test cell uptime as an operational metric rather than capital asset ownership. This pattern is most visible in German and Japanese OEM supply chains where supplier accountability frameworks emphasize output guarantees over equipment title.
Automotive Test Equipment Market Segmentation
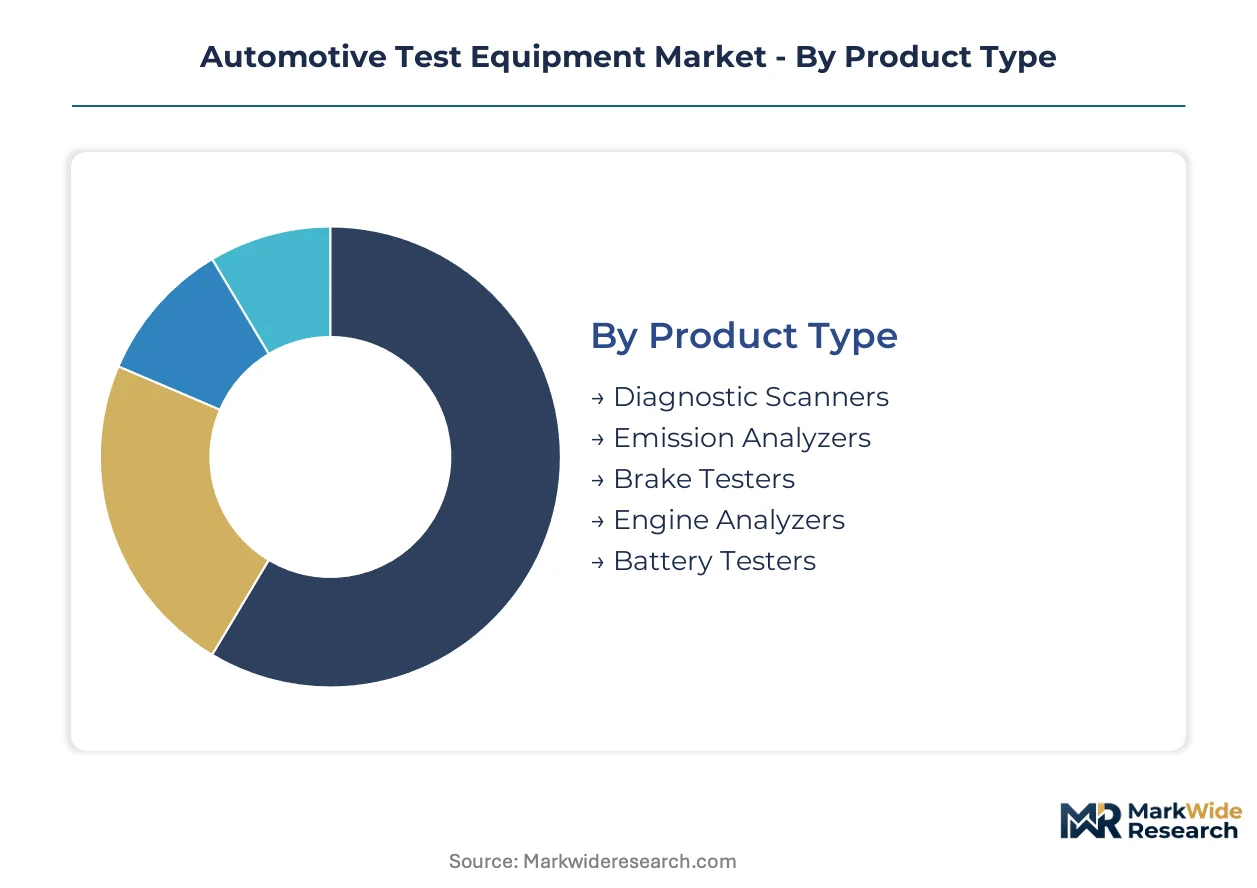
Test equipment procurement patterns diverge sharply across product categories, with regulatory mandates dictating refresh cycles for emission analyzers while electrification programs reshape investment toward battery and power electronics validation systems.
Product Type:
Euro 7 protocols and EPA certification rules differentiate equipment requirements across combustion and electric powertrain categories, forcing specialized procurement tracks for emission versus battery-focused test houses.
- Diagnostic Scanners:Handheld and benchtop units interface with CAN FD and Automotive Ethernet to extract fault codes from ECU networks across powertrain, chassis, and body domains. OEM end-of-line validation teams in Germany and the United States are consolidating scanner procurement with cloud telemetry platforms to enable fleet-wide anomaly detection.
- Emission Analyzers:Non-dispersive infrared and chemiluminescence detectors measure NOx, CO, and hydrocarbon concentrations against WLTP and EPA drive cycle protocols. European test houses face EMA-mandated recertification deadlines that compress replacement timelines for aging analyzer installations.
- Brake Testers:Roller dynamometers and plate-based systems quantify deceleration rates and hydraulic pressure distribution for NHTSA FMVSS compliance.
- Engine Analyzers:Combustion pressure transducers and crank-angle encoders map thermal efficiency across diesel and gasoline architectures.
- Battery Testers:Cyclers and impedance spectroscopy units evaluate state-of-health and thermal runaway thresholds for lithium-ion packs.
Emission analyzers handle the majority of throughput in European regulatory labs; battery testers are gaining share fastest as OEMs rebuild validation capacity around electrification programs.
Technology:
Customer type separates technology adoption curves, with OEM validation centers prioritizing automated and cloud-connected architectures while independent workshops favor handheld wireless units for field deployment flexibility.
- Wireless:Bluetooth and Wi-Fi enabled scanners eliminate cable routing constraints in crowded test cells and roadside inspection environments. Repair workshop networks in India are standardizing on wireless diagnostic tablets to reduce technician training overhead.
- Automated:Robotic sample handling and unattended test sequences reduce engineer presence requirements for 24-hour durability cycles. Testing laboratories in China are installing automated battery cyclers to meet MEE-administered GB standard throughput demands.
- Wired:Shielded CAN and Ethernet cabling maintains signal integrity for high-frequency power electronics measurements.
- Cloud-Based:Centralized data lakes aggregate test results across distributed validation sites for regression analysis.
- Handheld:Portable emission probes and scanner units support roadside inspection and dealership service lanes.
Wired systems anchor the installed base for precision-critical powertrain validation; automated platforms are expanding most quickly as labor scarcity drives unattended operation requirements.
Application:
Margin structure varies by application maturity, with vehicle inspection and safety compliance occupying regulated fee schedules while quality control commands premium pricing for custom test protocol development.
- Quality Control:End-of-line validation stations verify assembly tolerance stack-up and subsystem integration before vehicle release. OEM plants in the United States are integrating quality control test cells with manufacturing execution systems to enable real-time rework routing.
- Safety Compliance:Crash sled, brake, and lighting tests satisfy NHTSA FMVSS and UNECE type approval mandates. Third-party laboratories in Germany face KBA audit schedules that compress equipment utilization rates during certification peaks.
- Repair & Maintenance:Workshop diagnostic routines identify component degradation patterns for predictive service recommendations.
- Component Testing:Subsystem suppliers validate motor, inverter, and battery pack performance before OEM integration.
- Vehicle Inspection:Periodic roadworthiness checks enforce tailpipe emission and brake performance minimums.
Quality control absorbs the largest capital allocation per test cell; safety compliance is climbing fastest as autonomous system validation adds new protocol layers.
End User:
Volume concentration separates end user categories, with OEMs and vehicle assemblers commanding multi-cell installations while aftermarket providers operate single-unit deployments.
- OEMs:Captive validation centers house chassis dynamometers, climatic wind tunnels, and powertrain test cells for prototype development and homologation. German OEMs are consolidating equipment procurement under framework agreements that bundle hardware, calibration, and maintenance across global engineering centers.
- Testing Laboratories:Independent facilities serve multiple OEM clients with certified test protocols for EPA, NHTSA, and UNECE submissions. Commercial labs in China are expanding motor dynamometer capacity to capture GB standard validation work from domestic EV startups.
- Repair Workshops:Franchise and independent service bays deploy diagnostic scanners and emission analyzers for customer-facing troubleshooting.
- Vehicle Assemblers:Contract manufacturers operate end-of-line validation for OEM brand distribution.
- Aftermarket Providers:Parts retailers and remanufacturers test returned cores for warranty eligibility.
OEMs deploy the highest equipment density per site; testing laboratories are expanding footprint fastest as outsourcing trends concentrate specialized validation capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment consumption patterns diverge sharply by geography, with European laboratories prioritizing emission analyzer recertification while Chinese facilities concentrate investment in battery cyclers and motor dynamometers for new energy vehicle validation.
United States
EPA emission certification rules and NHTSA safety compliance mandates drive analyzer and brake tester procurement among Detroit-based OEMs. Testing laboratories near Ann Arbor and Los Angeles face compressed scheduling as autonomous system validation adds parallel approval tracks. The Southeast manufacturing corridor is absorbing new end-of-line validation cells as EV production shifts from legacy Midwest assembly footprints.
Germany
KBA audit schedules and EMA-mandated Euro 7 recertification deadlines are forcing replacement of aging analyzer installations at independent laboratories. Stuttgart and Munich engineering centers are consolidating equipment procurement under framework agreements that bundle hardware, calibration, and maintenance across global validation networks. German OEMs are outsourcing specialized power electronics testing to commercial labs as captive capacity strains under electrification program timelines.
China
MEE-administered GB standards for new energy vehicle durability are accelerating test cell construction in Ningbo and Chongqing manufacturing clusters. Domestic EV startups are contracting commercial laboratories for motor dynamometer validation as in-house capacity lags production ramp schedules. Yangtze River Delta testing facilities are expanding automated battery cycler installations to meet throughput demands from multiple OEM clients simultaneously.
Japan
METI industrial policy and JIS standard compliance requirements sustain demand for precision chassis dynamometers and emission analyzers among Tokyo and Nagoya-based OEMs. Japanese manufacturers expanding into Southeast Asian markets are leveraging domestic test equipment relationships to replicate validation protocols in Thai and Indonesian assembly plants. Hardware-in-the-loop simulation investment is concentrating in Kanagawa prefecture engineering centers.
India
BIS certification requirements for EV components are creating first-mover openings for battery tester suppliers as domestic OEMs establish validation capabilities. Tamil Nadu and Gujarat manufacturing clusters are installing initial end-of-line test cells for two-wheeler and passenger vehicle electrification programs. Independent workshops across Maharashtra are standardizing on wireless diagnostic tablets to reduce technician training overhead for emerging EV service requirements.
Automotive Test Equipment Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the Automotive Test Equipment Market. The upper tier combines emission analyzer portfolios with chassis dynamometer platforms to anchor multi-year framework agreements with OEM validation centers. Mid-scale specialists concentrate on single-technology dominance in battery cyclers, brake testers, or diagnostic scanners. Competitive moves center on backward integration into sensor hardware and geographic expansion through calibration service networks rather than pure equipment sales.
Within the integrated systems tier, HORIBA and Robert Bosch GmbH exemplify archetypes that anchor relationships through vertical control over critical sensor components. Siemens occupies a position representing the convergence of industrial automation expertise with automotive validation requirements. These three entities sit within distinct competitive vectors: HORIBA leverages emission measurement heritage, Bosch extends diagnostic platform integration, and Siemens advances hardware-in-the-loop simulation for software-defined vehicle architectures.
| Leading Market Players |
|---|
| HORIBA |
| Honeywell International Inc |
| Robert Bosch GmbH |
| AVL List GmbH |
| Softing AG |
| Siemens |
| ABB |
| Vector Informatik GmbH |
| Continental AG |
| Others |
Cost & Logistics Intelligence
Test cell utilization rates above 80 percent at German and Chinese validation centers concentrate procurement leverage among framework agreement holders, compressing price floors for mid-tier equipment suppliers while anchoring premium tiers to calibration service bundling.
Pricing Analysis
Long-term framework agreements dominate OEM procurement, with German and Japanese manufacturers bundling hardware, calibration, and maintenance across multi-year contracts that lock in volume commitments. Price differentiation separates CE-certified laboratory-grade systems from workshop-tier handheld units, with certification tier and after-sales service intensity as primary drivers. Pricing pressure stems from sensor input cost volatility in noble metals and lithium reference cells, squeezing margins on emission analyzers and battery testers. Independent testing laboratories exhibit highest price sensitivity due to capital constraints, while captive OEM validation centers prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints at Shanghai and Rotterdam elevate inbound logistics costs for analyzer sampling lines and thermocouple assemblies sourced from Chinese component suppliers. Manufacturing concentration in Germany, Japan, and China anchors precision sensor and chassis dynamometer production, with German suppliers drawing from captive machining capacity and Japanese producers resting on semiconductor-grade fabrication expertise. Single-source vulnerability in noble metal catalysts for exhaust gas analyzers creates exposure to platinum and palladium price swings. Distribution runs through direct OEM sales teams for large installations and regional distributor networks for aftermarket diagnostic equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Virtual validation environments and software-in-the-loop simulation platforms threaten to displace physical test cell investments, forcing incumbents to defend hardware relevance through hybrid architecture integration.
For Market Incumbents: Shield installed base relationships by embedding cloud telemetry and predictive maintenance software into legacy analyzer platforms, converting capital sales into recurring revenue streams. Deepen backward integration into sensor hardware to control input cost volatility and accelerate calibration service response times. Prioritize certification pre-approval with EPA and EMA to lock out challengers during Euro 7 and evolving autonomous system validation rulemaking.
For New Entrants and Emerging Players: Lead with automated battery cycler platforms targeting Indian and Southeast Asian EV component validation labs where domestic OEMs lack captive capacity and BIS certification requirements create first-mover windows. Penetrate the hardware-in-the-loop simulation segment through software-first positioning that sidesteps capital-intensive dynamometer manufacturing. Pursue white-label partnerships with established testing laboratories to bypass direct OEM sales channel barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors equipment suppliers with embedded software capabilities and recurring revenue models over pure hardware manufacturers exposed to cyclical refresh demand. Battery tester specialists and HIL simulation platforms offer strongest long-term viability as electrification and software-defined architectures reshape validation requirements. Watch EPA and EMA rulemaking timelines as inflection signals for equipment replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hardware-in-the-Loop Platform Integration | Converges physical and virtual validation to front-load ECU calibration before prototype assembly. |
| Cloud Telemetry Service Bundling | Transforms capital equipment sales into recurring revenue through fleet-scale battery monitoring. |
| Sensor Hardware Backward Integration | Captures margin pools in noble metal catalysts and lithium reference cell supply chains. |
| Automated Test Cell Deployment | Addresses European calibration engineer scarcity through unattended 24-hour durability cycles. |
| India Market Entry Partnership | Captures BIS certification-driven demand as domestic OEMs establish EV validation capabilities. |
Research Approach
A standing panel of OEM platform engineers, Tier 1 supplier procurement leads, testing laboratory operations directors, and aftermarket distributor network managers provided ongoing calibration against secondary data sources including EPA certification filings, EMA regulatory bulletins, vehicle production databases, and customs trade records. Primary field interviews across German, Chinese, and United States validation centers combined with bottom-up equipment shipment tracking and top-down market sizing triangulation to anchor volume and value estimates.
Consistency checks against external benchmarks validated projections across the analysis window, with segmentation modeling spanning product type, technology architecture, application maturity, and end-user scale. CAGRs derived from equipment replacement cycle analysis, regulatory deadline clustering, and electrification program capital allocation patterns incorporated powertrain mix shifts and software-defined vehicle content trajectories as structural inputs.
Forecasts assume regulatory continuity in EPA, EMA, and MEE-administered certification regimes; material policy shifts in emission standards or autonomous system approval pathways would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Vehicle Radar Test System Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
Transportation Predictive Analytics and Simulation Market
Automotive Testing and Simulation
Fleet Over-the-Air Software Update Validation Test Platforms Market
Automotive Testing and Simulation
Vehicle Emission Testers Market
Automotive Testing and Simulation
Tire Testing Machine Market
Automotive Testing and Simulation
Vehicle Crash Testing Services Market
Automotive Testing and Simulation
Automotive Chassis Dynamometer Market
Automotive Testing and Simulation
Automotive on-Board Diagnostics Market
Automotive Testing and Simulation
Torque Gauge Market
Automotive Testing and Simulation
On-Board Data Logger and Road Test Equipment System Market
Automotive Testing and Simulation
Global Track Geometry Measurement System (TGMS) Market
Automotive Testing and Simulation
Automotive Prognostics Market
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Automated Guided Cart Market
Automotive Testing and Simulation
On Board Diagnostics Device Market