
 On-Board Data Logger and Road Test Equipment System Market | 2026-2036
On-Board Data Logger and Road Test Equipment System Market Size, Share, and Industry Trends Forecast 2026-2036
On-Board Data Logger and Road Test Equipment System Market Insights
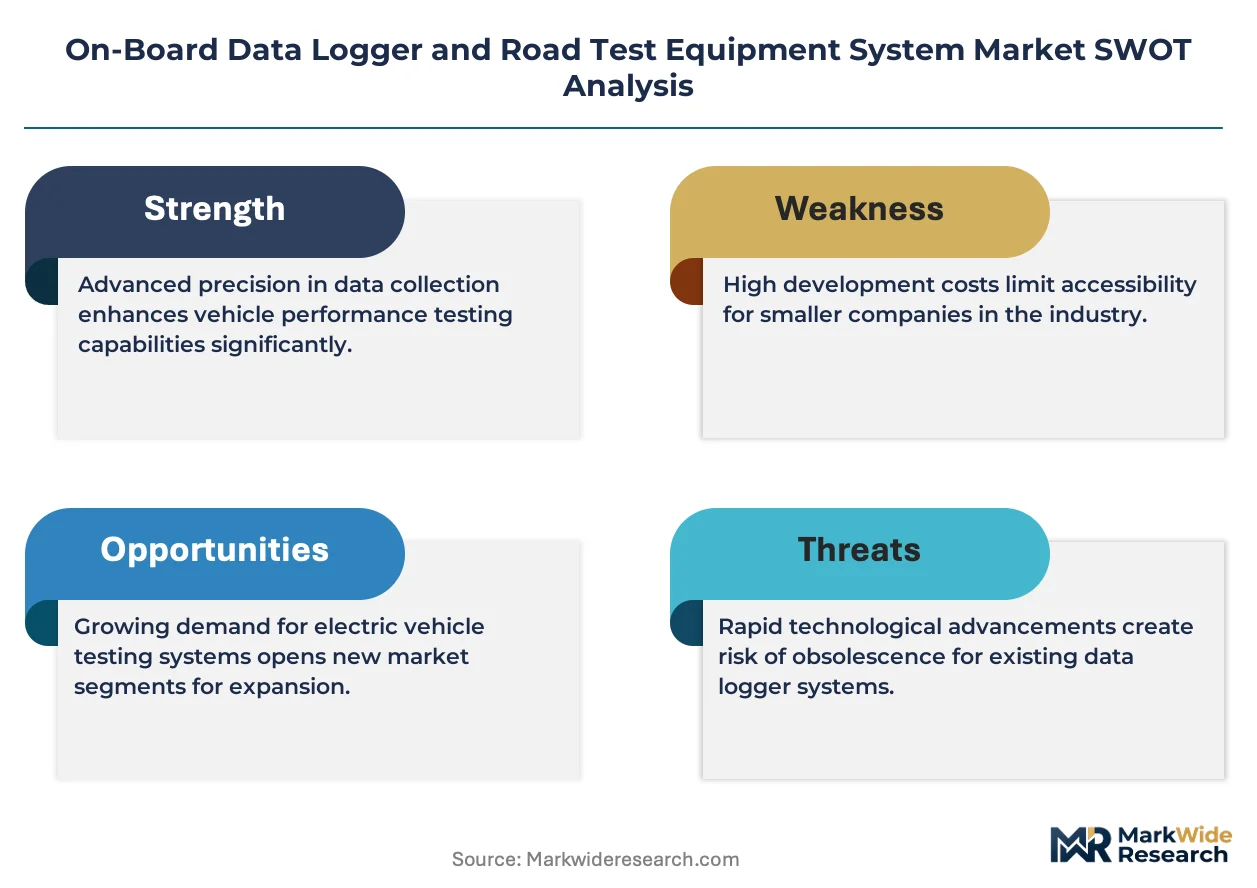
EU vehicle-type approval reform is hardening the cost-of-entry calculus for road test equipment vendors. Robert Bosch leverages its embedded systems heritage to dominate integrated diagnostic interface units for powertrain validation. Vector Informatik anchors its position through deep specialization in CAN Bus protocol tools that Tier-1 suppliers depend upon for network analysis. Continental competes by extending its sensor fusion capabilities from ADAS components into captive data logger hardware.
On-board data logger and road test equipment systems comprise ruggedized hardware-software platforms that capture, timestamp, and store vehicle telemetry at sampling rates exceeding 10 kHz, with primary purpose spanning powertrain calibration, crash reconstruction, and regulatory certification. Telemetry systems and sensor fusion technologies are capturing disproportionate R&D investment as electrified powertrains generate exponentially more validation data than internal combustion predecessors. Data logger devices remain the mature revenue base where margin pools have compressed, while diagnostic interface units serving safety compliance applications command premium pricing due to ISO 26262 functional safety certification requirements.
FDA maintains no direct jurisdiction, yet NHTSA crashworthiness mandates and EPA emission certification protocols in the United States create de facto product standards that equipment must satisfy for market access. ECE R79 steering-type approval and EU AI Act risk classifications for autonomous vehicle testing are converging to demand higher-integrity data provenance from road test systems. Stakeholders must monitor whether China's GB standards for intelligent connected vehicles achieve transnational recognition, as this would reshape which logger architectures achieve multi-jurisdiction deployment.
Market Dynamics
Electrified powertrain validation requirements are compressing development cycles and forcing equipment vendors to rearchitect sampling architectures for exponentially higher data throughput. The shift from internal combustion to battery-electric and hybrid platforms demands logger systems capable of capturing thermal, electrical, and mechanical telemetry simultaneously at rates conventional ICE testing never required.
Growth Catalysts
- EU Green Deal CO2 fleet targets:Mandatory emission reductions are accelerating equipment refresh cycles at TÜV-certified proving grounds and OEM validation centers across Germany.
- ADAS sensor fusion complexity:Lidar, radar, and camera convergence in Level 2+ systems requires synchronized multi-channel logging that legacy single-purpose devices cannot deliver.
- China's intelligent connected vehicle GB standards:Draft regulations for data recording in autonomous testing are creating preemptive demand for export-compliant logger architectures.
Market Restraints
- ISO 26262 functional safety certification costs:Diagnostic interface units for safety-critical applications require ASIL-D qualified components that extend development timelines and raise unit economics.
- Semiconductor supply concentration:FPGA and high-speed ADC sourcing dependencies in Taiwan and South Korea create vulnerability for specialized data acquisition hardware.
- Copper and rare earth magnet price volatility:Electric motor test stands and dynamometer systems face input cost pressure from commodity swings in mining-dependent materials.
Strategic Opportunities
- India's PLI scheme for automotive:Localized component manufacturing incentives are drawing test equipment vendors to establish calibration facilities near Chennai and Pune assembly clusters.
- Edge computing convergence with 5G V2X:Real-time telemetry preprocessing at the vehicle level opens service revenue models beyond hardware sales for logger vendors.
- EU AI Act risk classification for autonomous testing:High-risk system designations mandate auditable data provenance, creating premium positioning for tamper-evident logging platforms.
Industry Challenges
- Embedded systems firmware talent scarcity:Real-time operating system expertise for deterministic data capture remains concentrated among legacy automotive suppliers.
- Legacy fleet CAN Bus integration:Mixed-protocol environments requiring simultaneous LIN, FlexRay, and Ethernet logging complicate unified platform architectures.
- ECE R79 steering-type approval timelines:Extended homologation cycles for steer-by-wire systems delay revenue recognition for validation equipment contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-Board Data Logger and Road Test Equipment System Market |
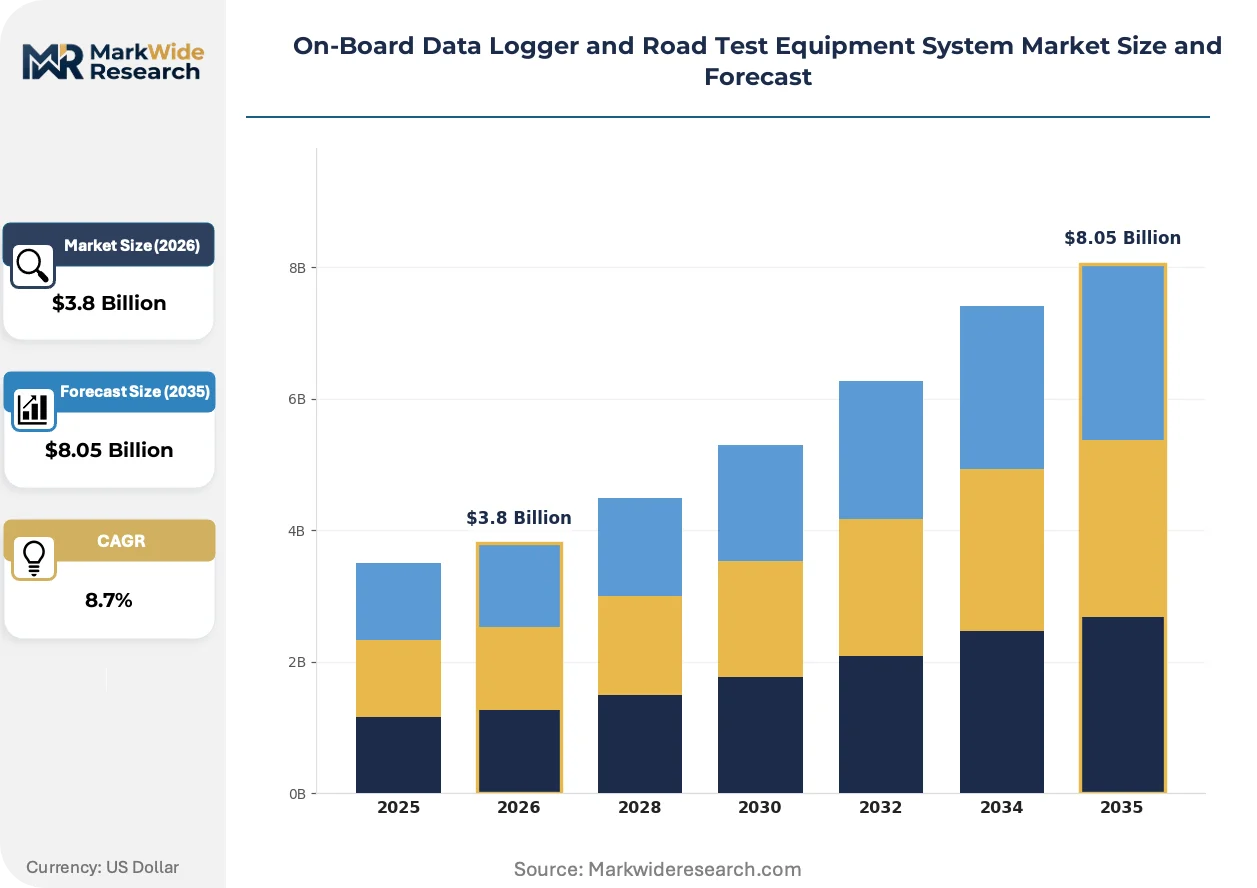
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Logger Devices, Telemetry Systems, Portable Testers, Diagnostic Interface Units Technology: Wireless Communication, CAN Bus, GPS Tracking, Sensor Fusion, Data Storage Media Application: Vehicle Dynamics Analysis, Emission Testing, Performance Tuning, Safety Compliance End User: Automobile Manufacturers, Tier-1 Suppliers, Research Institutes, Aftermarket Service Providers |
| Companies Covered | Robert Bosch, Vector Informatik, Continental, National Instruments, Keysight Technologies, HORIBA, Dewesoft, Intrepid Control Systems, Racelogic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-Board Data Logger and Road Test Equipment System Market Trends and Innovations
Telemetry architecture is bifurcating between centralized high-performance computing clusters and distributed edge nodes, with implications for how test data flows from vehicle to analysis workstation. This structural shift is redefining competitive advantage around data pipeline efficiency rather than raw sampling specifications alone.
Time-sensitive networking over Ethernet is integrating deterministic data transport into logger backbones previously dominated by proprietary fieldbus protocols. Tier-1 suppliers in Germany and Japan are deploying TSN-enabled validation fleets to synchronize camera, lidar, and inertial measurement streams with sub-microsecond precision. The technology is integrating discrete sensor islands into unified temporal domains that crash reconstruction and ADAS algorithm training demand.
ECE R79 and its pending amendments for automated lane-keeping systems are mandating steering-angle traceability that exceeds legacy logger resolution capabilities. Equipment vendors must now certify angular position sampling at 0.1-degree granularity across full temperature ranges. The regulation is forcing hardware redesigns for power steering test stands in Germany, Sweden, and Japan where type-approval testing concentrates.
Automotive OEMs are consolidating validation equipment procurement under centralized technical purchasing functions, displacing decentralized engineering-led acquisition. Tier-1 sensor suppliers and contract test houses face compressed negotiation leverage as buyer concentration intensifies. This pattern is most visible in Germany where Volkswagen, BMW, and Mercedes-Benz have established unified equipment frameworks for powertrain and chassis validation programs.
On-Board Data Logger and Road Test Equipment System Market Segmentation
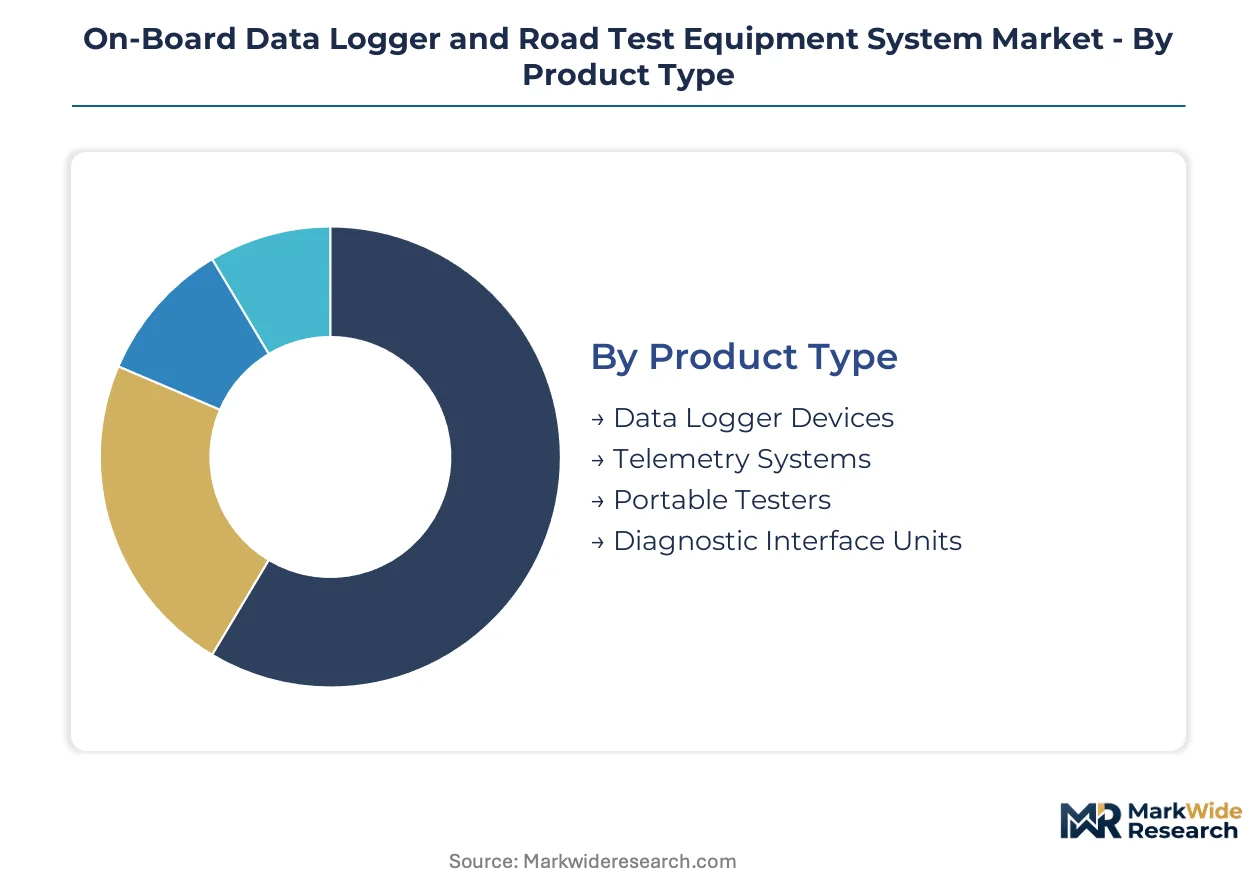
Equipment segmentation in this market directly determines certification pathways and procurement economics. Product type and technology choices govern whether systems require ISO 26262 ASIL-D qualification, ECE R79 type-approval compliance, or TÜV validation for EU market access.
Product Type:
Certification burden varies sharply: diagnostic interface units for safety-critical applications demand ASIL-D qualified components, while portable testers face lighter conformance requirements.
- Data Logger Devices:Ruggedized hardware-software platforms capturing vehicle telemetry at sampling rates exceeding 10 kHz. Demand concentrates in German OEM validation centers where ECE R79 steering-angle traceability mandates 0.1-degree granularity. Margin pools have compressed as this segment matures.
- Diagnostic Interface Units:Embedded systems linking vehicle networks to external analysis workstations. Premium pricing persists due to ISO 26262 functional safety certification requirements that extend development timelines and raise unit economics for Tier-1 suppliers.
- Telemetry Systems:Real-time data transmission architectures for remote monitoring applications.
- Portable Testers:Handheld validation equipment for field diagnostics and rapid deployment scenarios.
Leading the category by volume: Data Logger Devices. Growing fastest: Diagnostic Interface Units.
Technology:
Technology selection determines interoperability with legacy fleet architectures and compatibility with emerging Ethernet-based backbones.
- CAN Bus:Dominant vehicle network protocol for powertrain and chassis communication. German Tier-1 suppliers depend upon Vector Informatik's specialized tools for network analysis, though mixed-protocol environments complicate unified platform architectures.
- Sensor Fusion:Synchronized multi-channel logging for lidar, radar, and camera convergence in Level 2+ ADAS systems. R&D investment concentrates here as electrified powertrains generate exponentially more validation data than internal combustion predecessors.
- Wireless Communication:Over-the-air data transmission for remote fleet monitoring.
- GPS Tracking:Geospatial timestamping for route reconstruction and regulatory compliance.
- Data Storage Media:High-capacity solid-state architectures for high-frequency sampling retention.
Most entrenched by installed base: CAN Bus. Expanding most quickly: Sensor Fusion.
Application:
Application focus dictates whether equipment serves development-phase validation or regulatory certification workflows.
- Emission Testing:Exhaust gas analysis and CO2 measurement for type-approval compliance. EU Green Deal fleet targets accelerate equipment refresh cycles at TÜV-certified proving grounds across Germany, Sweden, and Italy.
- Safety Compliance:Crashworthiness and active safety system validation for NHTSA and ECE homologation. Premium positioning emerges for tamper-evident logging platforms under EU AI Act risk classifications for autonomous vehicle testing.
- Vehicle Dynamics Analysis:Chassis behavior characterization for ride and handling development.
- Performance Tuning:Powertrain optimization for motorsport and aftermarket calibration.
Highest regulatory pressure: Emission Testing. Gaining share fastest: Safety Compliance.
End User:
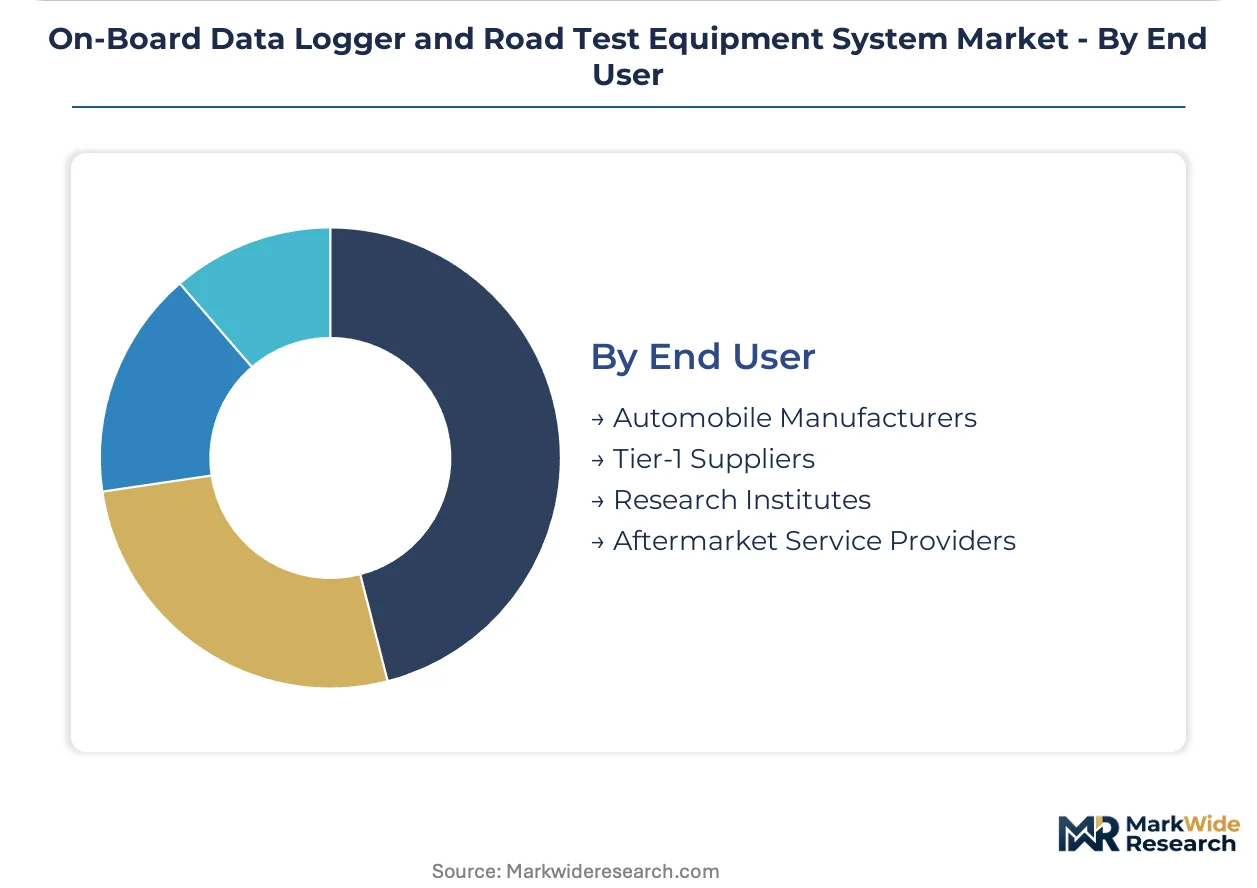
End-user concentration shapes procurement leverage and pricing architecture across the value chain.
- Automobile Manufacturers:Centralized technical purchasing functions at Volkswagen, BMW, and Mercedes-Benz displace decentralized engineering-led acquisition. Unified equipment frameworks for powertrain and chassis validation compress negotiation leverage for vendors.
- Tier-1 Suppliers:Sensor and subsystem specialists requiring synchronized logging for algorithm training. Procurement is shifting toward captive data logger hardware as Continental extends sensor fusion capabilities from ADAS components.
- Research Institutes:Academic and government validation facilities with specialized protocol requirements.
- Aftermarket Service Providers:Independent repair and calibration networks with cost-sensitive equipment needs.
Controlling procurement volume: Automobile Manufacturers. Climbing the fastest: Tier-1 Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German TÜV-certified proving grounds concentrate equipment procurement decisions for emission compliance and safety validation, while China's MIIT drafts GB standards that preemptively shape logger architectures for autonomous vehicle testing.
Germany
OEM headquarters in Munich and Stuttgart drive centralized technical purchasing for powertrain validation equipment. EU Green Deal CO2 fleet targets accelerate refresh cycles at proving grounds in Wolfsburg and Ingolstadt. TÜV-certified facilities in Lower Saxony and Bavaria validate ECE R79 steering-type approval with 0.1-degree angular position granularity.
United States
NHTSA crashworthiness mandates and EPA emission certification protocols create de facto product standards for market access. Detroit's automotive engineering clusters in Michigan source diagnostic interface units for safety-critical applications. California's autonomous vehicle testing programs in Silicon Valley demand tamper-evident logging platforms for regulatory submission.
China
MIIT's draft GB standards for intelligent connected vehicles reshape multi-jurisdiction deployment strategies for logger vendors. Battery-electric powertrain validation in Shanghai and Shenzhen generates exponentially higher data throughput requirements. The Yangtze River Delta concentration of EV manufacturers preemptively adopts export-compliant architectures.
Japan
METI oversight of automotive technology roadmaps influences domestic equipment procurement patterns. Nagoya's Chubu region hosts concentrated proving ground activity for steer-by-wire homologation. Tokyo-based Tier-1 suppliers deploy time-sensitive networking validation fleets for sensor fusion algorithm development.
India
PLI scheme incentives for automotive component manufacturing draw test equipment vendors toward Chennai and Pune assembly clusters. BIS standards alignment efforts for intelligent vehicle testing create emerging demand for certified data loggers. Karnataka's Bengaluru technology corridor attracts calibration facility investments from multinational suppliers.
On-Board Data Logger and Road Test Equipment System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment tiers, creating a bifurcated structure where integrated automotive suppliers leverage captive component relationships while independent vendors fight on sampling specifications and protocol breadth. The vendor base organizes around three archetypes: diversified industrial conglomerates with embedded systems heritage, protocol-specialist software-hardware hybrids, and sensor-integrated equipment divisions of Tier-1 suppliers. Dominant competitive moves include backward integration into FPGA sourcing and strategic partnerships for 5G V2X edge computing convergence.
Within the diversified conglomerate tier, Robert Bosch and Continental exemplify integrated suppliers extending component capabilities into captive data logger hardware. Vector Informatik occupies a position among protocol-specialist pure-plays anchoring network analysis tool dominance. These three companies represent contrasting strategic postures: embedded systems heritage, deep CAN Bus specialization, and sensor fusion extension respectively.
| Leading Market Players |
|---|
| Robert Bosch |
| Vector Informatik |
| Continental |
| National Instruments |
| Keysight Technologies |
| HORIBA |
| Dewesoft |
| Intrepid Control Systems |
| Racelogic |
| Others |
Pricing and Supply Chain Analysis
Time-sensitive networking adoption in German and Japanese validation fleets is compressing hardware refresh cycles while concentrating procurement leverage among centralized OEM technical purchasing functions. This protocol migration simultaneously elevates R&D cost burdens for Tier-1 suppliers and tightens margin pools for independent logger vendors caught between ASIL-D certification requirements and buyer consolidation.
Pricing Analysis
Short lead-time premiums for ASIL-D qualified diagnostic interface units command substantial markups over standard-grade data loggers with comparable sampling specifications. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262 certified safety-critical units from development-phase loggers and aftermarket portable testers. Cost compression in the mature data logger segment is intensifying because automotive OEMs have consolidated procurement under unified equipment frameworks. Aftermarket service providers exhibit highest price sensitivity, while Tier-1 suppliers absorbing safety compliance mandates show least elasticity.
Supply Chain Analysis
Regional distribution centers in Germany, Taiwan, and South Korea anchor hub-and-spoke fulfillment patterns for specialized data acquisition hardware. FPGA and high-speed ADC sourcing draws from concentrated semiconductor fabrication in Taiwan and South Korea, with copper and rare earth magnet dependencies for electric motor test stands. Single-source vulnerability in ASIC component supply creates exposure for vendors serving ECE R79 type-approval timelines. Distribution runs through OEM-direct technical purchasing channels and Tier-1 supplier captive procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASIL-D certification capacity scarcity props pricing power for qualified component suppliers while constraining entry for unvalidated competitors. This bottleneck reinforces incumbent positioning across safety-critical applications.
For Market Incumbents: Cement dominance in integrated diagnostic interface units by extending embedded systems heritage into 5G V2X edge computing convergence. Secure backward integration into FPGA sourcing to insulate against Taiwan semiconductor supply concentration. ASIL-D certification backlog at validation facilities threatens revenue recognition timelines; prioritize captive TÜV partnership channels to accelerate homologation throughput. For New Entrants and Emerging Players: EU AI Act risk classifications in Germany open a window for tamper-evident logging platforms serving autonomous vehicle testing audit requirements. White-space concentrates in India's PLI scheme corridors near Chennai and Pune, where localized calibration facility demand outpaces established vendor presence. Pursue sensor fusion specialization for Level 2+ ADAS algorithm training as the most penetrable application segment, leveraging protocol-agnostic architectures to bypass Vector Informatik's CAN Bus dominance. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified industrial conglomerates seeking embedded systems capabilities. Long-term viability favors vendors with ISO 26262 qualification infrastructure and proven TÜV relationship networks over pure-play sampling specification competitors. Watch China's MIIT GB standards finalization as the inflection signal determining which logger architectures achieve multi-jurisdiction deployment scalability.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Unlocks premium pricing in safety-critical diagnostic interface units for NHTSA and ECE homologation workflows. |
| 5G V2X Edge Computing Partnership | Creates service revenue models beyond hardware sales through real-time telemetry preprocessing at vehicle level. |
| FPGA Sourcing Backward Integration | Reduces vulnerability to Taiwan and South Korea semiconductor supply concentration for high-speed data acquisition. |
| India PLI Scheme Facility Localization | Positions calibration infrastructure near Chennai and Pune assembly clusters for cost-competitive regional access. |
| Time-Sensitive Networking Product Line | Captures German and Japanese Tier-1 demand for sub-microsecond sensor synchronization in ADAS validation fleets. |
Research Methodology
Document review covered SEC filings from test equipment vendors, EU regulatory filings for ECE R79 amendments, and MIIT draft GB standards documentation, complemented by interviews with OEM platform engineers, Tier-1 supplier procurement leads, TÜV certification specialists, and aftermarket service operations managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, customs records for semiconductor component trade flows, and hyperscaler capex disclosures for edge computing infrastructure. Bottom-up equipment shipment estimates triangulated against top-down OEM R&D spending allocations.
Historical volume trajectories cross-referenced against panel input from industry participants established baseline growth parameters across the projection horizon. Segmentation modeling incorporated product type, technology protocol, application workflow, and end-user procurement concentration dimensions. CAGRs derived from weighted average of scenario-based demand curves and supply-side capacity constraints. Electrified powertrain validation data throughput requirements and ADAS sensor fusion complexity served as primary forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for time-sensitive networking deployment would alter the outlook for legacy CAN Bus protocol tool demand. Forecasts reflect stated assumptions regarding EU Green Deal implementation pace and China GB standards transnational recognition. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Automotive Simulation Software Market
Automotive Testing and Simulation
Tire Testing Machine Market
Automotive Testing and Simulation
Automotive Exhaust Analyzer Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Testing Equipment Market
Automotive Testing and Simulation
Vehicle Simulation Software Market
Automotive Testing and Simulation
Electric Vehicle Edrive Test Equipment Market
Automotive Testing and Simulation
Automotive TIC Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
Vehicle Testing Equipment Market
Automotive Testing and Simulation
Automotive Simulation Market
Automotive Testing and Simulation
ADAS Calibration Equipment Market
Automotive Testing and Simulation
Vehicle Crash Testing Services Market
Automotive Testing and Simulation
Electric Vehicle Test Equipment Market
Automotive Testing and Simulation
Motor Testing Equipment Market
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market