
 Automotive Backlight Moldings Market | 2026-2036
Automotive Backlight Moldings Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Backlight Moldings Market Outlook
Tool-and-die engineering talent scarcity is reorganizing how molders scale capacity across automotive lighting supply chains. Rohm GmbH leverages its acrylic compounding heritage to dominate European headlamp diffuser supply. Motherson Group anchors high-volume polycarbonate programs through backward integration into injection molding cells. Shenzhen Abery Mold & Plastic competes on rapid tooling turnaround for tier-1 lighting module orders from domestic EV brands.
Automotive backlight moldings are precision-injected polymer components, typically specified to 0.05 mm tolerance and optical-grade surface finish, that channel and diffuse light from LED or halogen sources into uniform illumination for vehicle interior and exterior assemblies. Polycarbonate formulations lead in headlight applications where thermal stability above 120°C prevents deformation under sustained LED operation. Acrylic segments command margin pools in instrument panel clusters where optical clarity and UV resistance justify premium positioning. Tier-1 Suppliers represent the fastest-growing end-user channel as lighting module consolidation pushes molders to qualify directly for platform programs rather than through vehicle assembler procurement.
China's NMPA enforces GB standards on automotive lighting component flammability and photometric performance, while REACH and RoHS in Europe restrict halogenated flame retardants in interior-grade polypropylene. The US NHTSA Federal Motor Vehicle Safety Standard 108 governs headlamp beam pattern precision, indirectly dictating molding tolerance specifications for reflector and lens housings. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's recycled content mandates are reshaping material qualification timelines for virgin and post-industrial polymer feedstocks.
Market Dynamics
LED module consolidation is compressing supplier tiers and forcing molders to absorb optical engineering functions previously housed at lighting assemblers, restructuring margin distribution across the value chain.
Growth Catalysts
- GB Standard 8410 Flammability Mandates:China's NMPA enforcement of stricter interior polymer ignition resistance is accelerating tooling refresh cycles as molders recalibrate formulations for compliance.
- Polycarbonate Thermal Stability:Sustained LED operating temperatures above 120°C are specifying high-heat polymer grades in headlamp housings, expanding addressable tooling revenue per vehicle platform.
- Shenzhen-Shanghai Manufacturing Clusters:Concentration of domestic EV brand headquarters and tier-1 module plants is shortening logistics loops and compressing prototype-to-production timelines.
Market Restraints
- Specialized Tool-and-Die Labor Scarcity:Precision optical mold engineering expertise concentrates in aging European and Japanese workforces, constraining capacity scaling for new platform qualifications.
- Acrylic Monomer Feedstock Volatility:Methyl methacrylate supply disruptions transmit directly to instrument panel cluster molding margins, pressuring premium-grade pricing flexibility.
- REACH Flame Retardant Restrictions:ECHA limitations on halogenated additives in interior polypropylene are forcing reformulation cycles that delay material certification timelines.
Strategic Opportunities
- Post-Industrial Recycled Feedstocks:EU Green Deal recycled content mandates for automotive plastics are creating first-mover advantage for molders with validated closed-loop polycarbonate supply chains.
- Direct Tier-1 Qualification Pathways:Lighting module consolidation is opening channel bypass opportunities where molders qualify directly for platform programs rather than through vehicle assembler procurement.
- Dual Carbon Policy Alignment:China's MEE carbon intensity targets for industrial manufacturing are incentivizing low-energy injection molding cell upgrades with preferential permitting.
Industry Challenges
- Optical-Grade Surface Certification Bottlenecks:0.05 mm tolerance validation for LED diffuser applications requires extended metrology protocols that stretch engineering bandwidth.
- Multi-Material Bonding Integration:PC-acrylic hybrid assemblies for complex light guides demand process control capabilities beyond legacy single-resin molding footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Backlight Moldings Market |
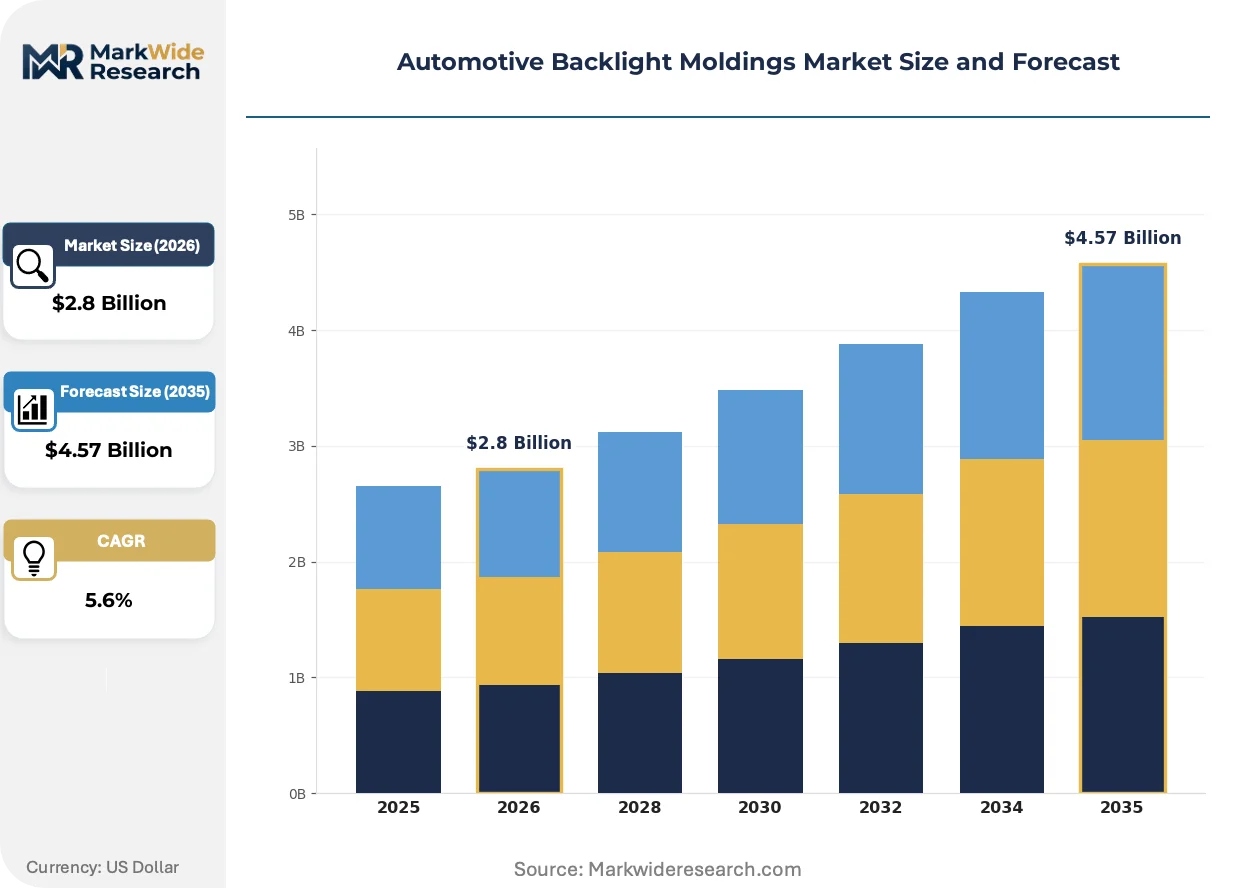
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Acrylic, Polypropylene, PVC Application: Interior Lighting, Exterior Lighting, Instrument Panel, Headlights End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Distribution Channel: Direct, Distributors, E-commerce, Specialty Retailers |
| Companies Covered | The Platinum Tool Group, Green Vitality Industry, NTF India, Rohm GmbH, Shenzhen Abery Mold & Plastic, Sino Mould, Fabrik Molded Plastics, WESEM, Motherson Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Backlight Moldings Market Strategic Shifts
Precision molding is converging with optical engineering as LED architectures shrink and performance specifications tighten, compressing the traditional separation between component fabrication and lighting system design.
Micro-lens array technology is miniaturizing. These sub-millimeter surface structures homogenize LED point-source output into uniform illumination planes. Tier-1 lighting module suppliers are specifying them for next-generation headlamp and tail-lamp assemblies. The technology is miniaturizing optical component footprints and enabling multi-function lighting in constrained packaging envelopes.
REACH Annex XVII restrictions on persistent organic pollutants are tightening material traceability requirements for automotive interior polymers. Molded component suppliers must now document virgin and recycled feedstock chains through to finished goods. European-based tier-1 lighting programs are most affected, with procurement teams extending qualification audits to sub-tier resin compounders.
Buyer consolidation among lighting module assemblers is compressing supplier negotiation leverage. Single-source platform awards now span multi-year vehicle lifecycles with fixed tooling amortization schedules. This pattern is most visible in German and Chinese premium EV platforms where module integration complexity favors consolidated supply bases.
Automotive Backlight Moldings Market Segmentation
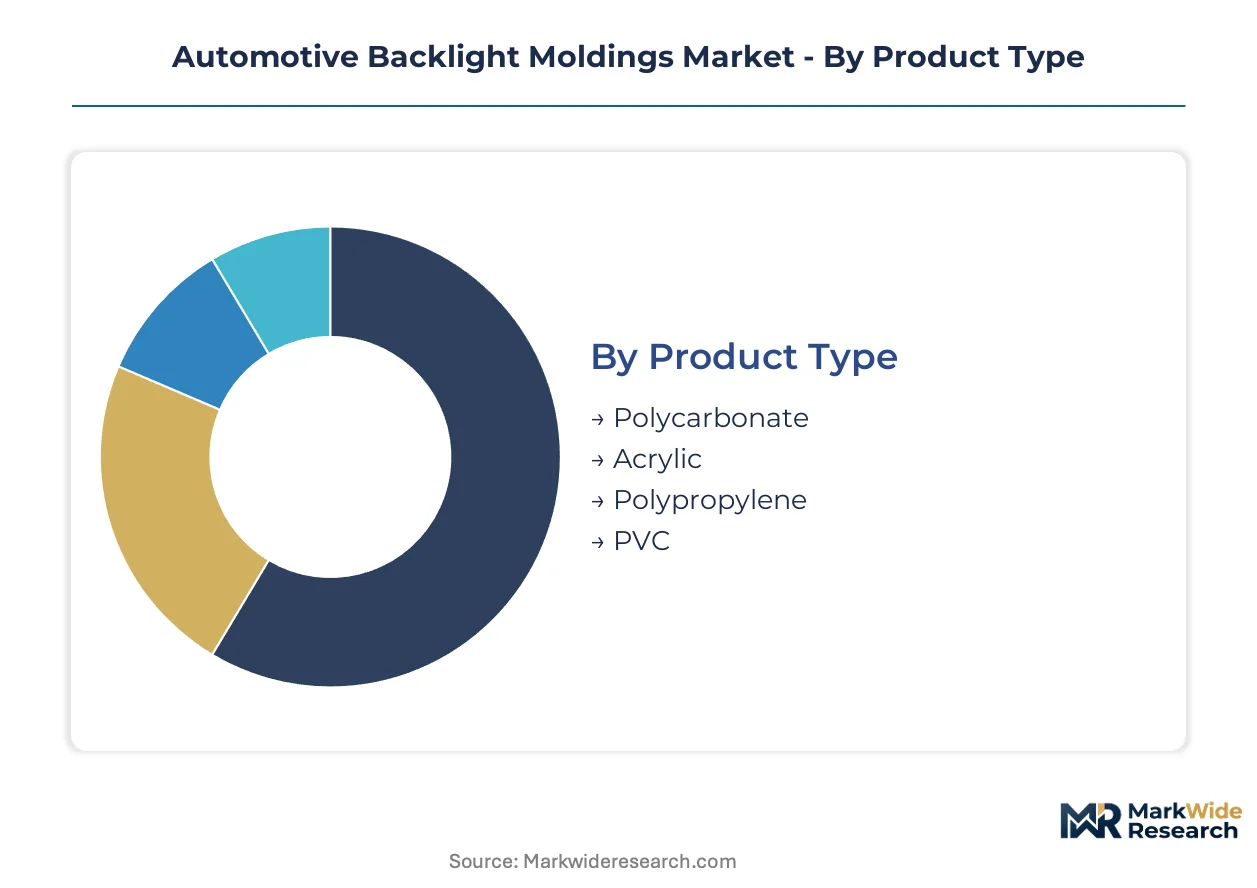
Segmentation in automotive backlight moldings reveals how material specifications, application requirements, and channel structures fragment procurement patterns across vehicle platforms. Understanding these divides exposes where tooling investments concentrate and which qualification pathways offer entry points for new suppliers.
Product Type:
Domestic formulation capacity in China and Germany anchors polycarbonate and acrylic supply, while polypropylene and PVC sourcing stretches across Southeast Asian compounders serving export-led tier-1 programs.
- Polycarbonate:High-heat grades withstand sustained LED operating temperatures above 120°C in headlamp housings. Demand concentrates in German premium EV platforms and Chinese domestic brand programs where thermal stability specifications are tightening.
- Acrylic:Optical-grade formulations deliver UV resistance and clarity for instrument panel clusters. Japanese and South Korean tier-1 suppliers specify these for premium interior lighting modules where surface finish tolerances hit 0.05 mm.
- Polypropylene:Interior-grade compounds balance cost and flammability compliance under China's GB Standard 8410.
- PVC:Legacy formulations persist in aftermarket replacement channels with lower optical performance thresholds.
Polycarbonate holds the largest share; momentum sits with acrylic as instrument panel complexity rises.
Application:
Cost tier stratification separates exterior lighting programs requiring thermal and impact certification from interior applications where optical clarity commands premium positioning.
- Headlights:Precision-molded housings and reflectors must maintain beam pattern integrity under NHTSA Federal Motor Vehicle Safety Standard 108. Programs in the US and Germany demand sub-0.05 mm tolerance validation that stretches engineering bandwidth at tier-1 suppliers.
- Instrument Panel:Light guide and indicator assemblies integrate micro-lens arrays for uniform illumination. Chinese EV brands in Shenzhen and Shanghai are compressing prototype-to-production timelines for these modules.
- Interior Lighting:Dome and ambient lighting moldings specify lower thermal thresholds but require REACH-compliant flame retardant formulations.
- Exterior Lighting:Tail-lamp and marker light housings balance UV stability with impact resistance across climate zones.
Headlights capture the highest tooling revenue per vehicle; instrument panel applications are climbing fastest on EV platform proliferation.
End User:
Customer type determines qualification depth, with direct tier-1 engagement requiring full optical engineering collaboration while aftermarket channels accept legacy specification tiers.
- Tier-1 Suppliers:Lighting module consolidation is compressing supplier tiers and forcing molders to absorb optical engineering functions. These stakeholders now specify directly for platform programs rather than routing through vehicle assembler procurement.
- OEMs:Captive molding operations at major vehicle manufacturers retain high-volume programs for strategic platform control.
- Vehicle Assemblers:Declining procurement leverage as module integration complexity favors consolidated supply bases.
- Aftermarket Providers:Replacement part channels prioritize tooling reuse and faster turnaround over optical-grade certification.
Tier-1 Suppliers dominate current qualification activity; OEMs retain strategic leverage on flagship platforms.
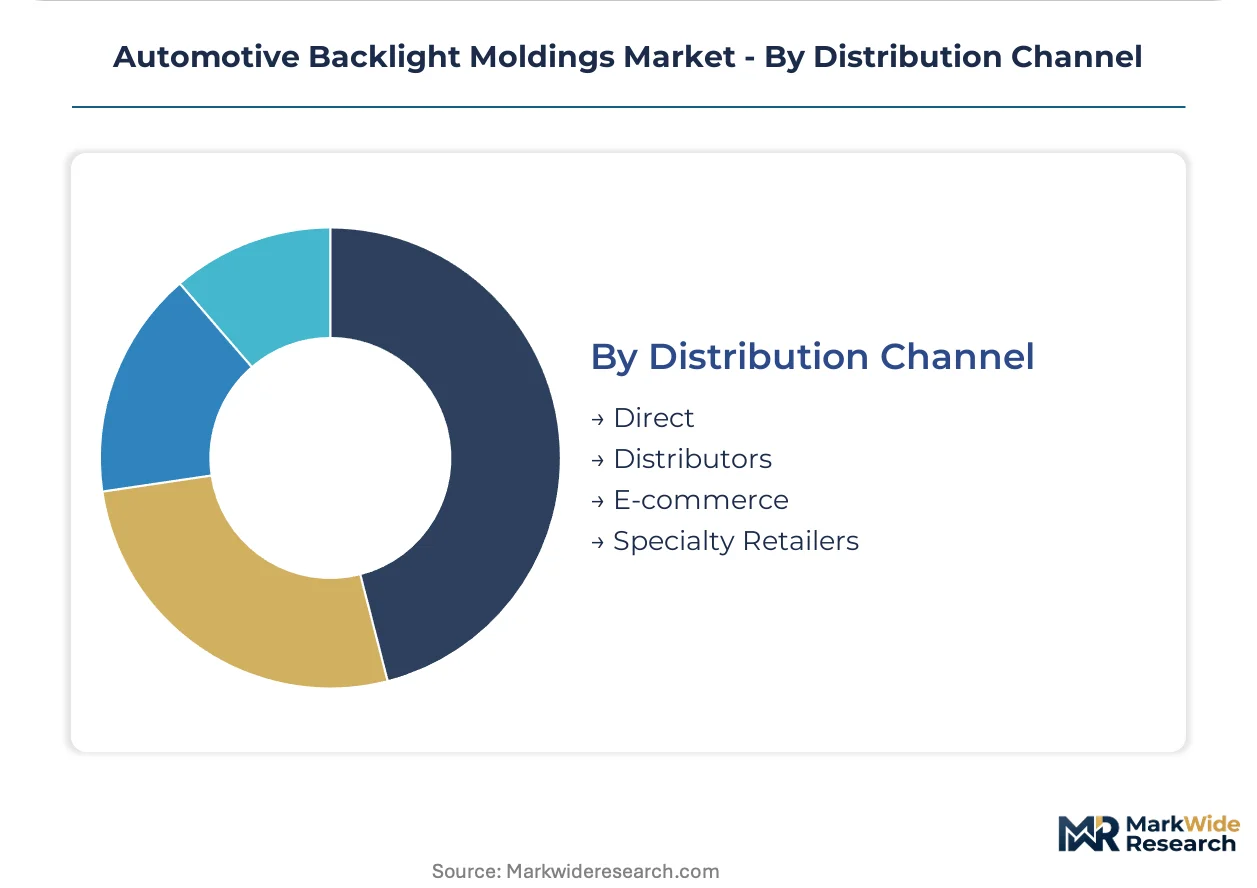
Distribution Channel:
Supply concentration in East Asian manufacturing clusters shortens logistics loops for direct channel relationships while distributor networks retain relevance for fragmented aftermarket demand.
- Direct:Platform-level contracts bind molders to tier-1 lighting module plants with multi-year tooling amortization schedules. Shenzhen-Shanghai corridor concentration enables just-in-sequence delivery for domestic Chinese EV production.
- Distributors:Regional inventory positioning serves fragmented aftermarket demand across secondary automotive markets.
- E-commerce:Replacement part channels for aging vehicle fleets in North America and Europe.
- Specialty Retailers:Custom and restoration segments requiring low-volume, high-mix tooling flexibility.
Direct channels command the highest program values; distributor networks retain volume in aftermarket replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA safety directives on optical clarity and heat resistance are tightening material certification requirements across the dominant manufacturing geography. LED-based interior lighting modules are driving fresh tooling orders across passenger vehicle platforms in East Asian manufacturing clusters.
China
Domestic EV brands in Shenzhen and Shanghai are compressing prototype-to-production timelines for instrument panel clusters. The NMPA enforces GB standards on automotive lighting component flammability and photometric performance. Manufacturing concentrates in the Shenzhen-Shanghai corridor where tier-1 module plants enable just-in-sequence delivery.
Germany
Premium EV platforms specify sub-0.05 mm tolerance validation for headlamp housings and reflectors. The KBA enforces type approval under UN ECE regulations that govern beam pattern precision. Production clusters in Bavaria and Baden-Württemberg host captive molding operations for strategic platform control.
United States
Headlamp beam pattern precision requirements under NHTSA Federal Motor Vehicle Safety Standard 108 dictate molding tolerance specifications. The EPA oversees material compliance for automotive polymers under TSCA. Tool-and-die engineering expertise concentrates in the Midwest automotive belt around Michigan and Ohio.
Japan
Optical-grade acrylic formulations for instrument panel clusters command premium positioning in domestic and export programs. METI oversees industrial standards under JIS frameworks for automotive lighting components. Manufacturing concentrates in the Chubu region around Nagoya and Kansai around Osaka.
South Korea
Tier-1 lighting module suppliers specify micro-lens array technology for next-generation headlamp assemblies. The MFDS maintains oversight of material safety in automotive interior applications. Production gravity sits in the Seoul Capital Area and Busan-Ulsan corridor for integrated module supply.
Automotive Backlight Moldings Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. European and Japanese specialists dominate optical-grade formulation expertise while Chinese fabricators compete on rapid tooling turnaround. Three archetypes define positioning: vertically integrated polymer compounders, precision injection molders with optical engineering capabilities, and high-volume contract manufacturers serving domestic EV platforms. M&A activity targets tooling engineering talent pools, while capacity expansion concentrates in Shenzhen-Shanghai logistics corridors.
Among European compounders, Rohm GmbH anchors the premium formulation tier through acrylic heritage. Motherson Group exemplifies the integrated molder archetype with backward integration into injection molding cells for polycarbonate programs. Shenzhen Abery Mold & Plastic represents the rapid-response tier serving domestic Chinese EV brands with shortened qualification pathways. These three occupy distinct competitive positions without direct overlap in customer segments or geographic focus.
| Leading Market Players |
|---|
| The Platinum Tool Group |
| Green Vitality Industry |
| NTF India |
| Rohm GmbH |
| Shenzhen Abery Mold & Plastic |
| Sino Mould |
| Fabrik Molded Plastics |
| WESEM |
| Motherson Group |
| Others |
Value Chain & Pricing Dynamics
China's GB Standard 8410 flammability mandates gate both supplier qualification and price stratification, as molders must recalibrate formulations to access interior-grade polypropylene programs while optical-grade acrylic commands premium positioning for instrument panel clusters.
Pricing Analysis
Price spreads between German premium EV platforms and Chinese domestic brand programs reflect tolerance-validation depth rather than material cost alone. Contract-based long-term offtake dominates tier-1 supplier relationships, with price differentiation anchored in certification grade and volume scale. Cost compression in instrument panel clusters is intensifying as Shenzhen-based EV brands compress prototype-to-production timelines. Aftermarket providers exhibit highest price sensitivity; German premium platforms show least.
Supply Chain Analysis
Just-in-sequence inventory strategies dominate the Shenzhen-Shanghai corridor where domestic EV headquarters cluster, while European tier-1 programs maintain strategic stockpiles of optical-grade polycarbonate. Supply concentrates in China, Germany, and Japan for polymer compounding and precision tooling. Methyl methacrylate monomer, high-heat polycarbonate grades, and specialized tool-and-die engineering constitute critical input dependencies. Single-source vulnerability runs through aging European and Japanese tool-and-die talent pools. Distribution runs through direct platform-level contracts binding molders to tier-1 lighting module plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory certification entrenchment creates switching costs that lock tier-1 suppliers into multi-year platform relationships.
For Market Incumbents: Shield margin pools by deepening backward integration into injection molding cells for polycarbonate programs and accelerating NMPA compliance certification ahead of formulation refresh cycles. Emerging Chinese fabricators threaten pricing power in rapid-turnaround segments. Capacity addition in the Shenzhen-Shanghai logistics corridor preserves just-in-sequence relationships with domestic EV brands. For New Entrants and Emerging Players: Differentiate on post-industrial recycled feedstock validation to capture EU Green Deal recycled content mandates before first-mover advantage closes. The aftermarket replacement channel offers most penetrable white-space given lower optical-grade certification thresholds. A direct tier-1 qualification pathway bypassing vehicle assembler procurement accelerates platform access. For Investors and Strategic Acquirers: China's dual carbon policy alignment reshapes the acquisition landscape by incentivizing low-energy injection molding cell upgrades with preferential permitting. Long-term viability centers on tooling engineering talent scarcity that concentrates value in precision optical mold capabilities. Target molders with validated closed-loop polycarbonate supply chains. Watch methyl methacrylate feedstock volatility as inflection indicator for acrylic segment margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Industrial Recycled Feedstock Validation | EU Green Deal mandates create first-mover advantage for closed-loop polycarbonate supply chains. |
| Direct Tier-1 Qualification Pathway | Lighting module consolidation opens channel bypass opportunities bypassing vehicle assembler procurement. |
| Low-Energy Injection Molding Cell Upgrade | China's MEE carbon intensity targets deliver preferential permitting for qualifying manufacturing investments. |
| Optical-Grade Surface Certification Investment | Sub-0.05 mm tolerance validation for LED diffusers stretches engineering bandwidth and locks in platform relationships. |
| Micro-Lens Array Technology Integration | Tier-1 suppliers specify sub-millimeter surface structures for next-generation headlamp and tail-lamp assemblies. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across tier-1 lighting module procurement teams, OEM platform engineers, polymer compounding technical directors, and aftermarket distribution channel managers. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standard 108 filings, NMPA GB standard enforcement records, REACH Annex XVII restriction updates, and vehicle production registration databases. Bottom-up tooling order aggregation and top-down polymer consumption estimates were triangulated to anchor volume figures.
Across the analysis window, projections model material type, application tier, end-user channel, and regional manufacturing cluster segmentation. CAGRs were derived from platform-level tooling amortization schedules and LED module penetration curves. Forecast inputs include polycarbonate thermal grade adoption rates and acrylic optical clarity specification tightening in instrument panel clusters.
The analysis sits within stated boundaries; outcomes outside sustained LED operating temperature thresholds or NMPA enforcement intensity would require recalibration. Forecasts reflect assumptions on polymer formulation certification timelines and tier-1 supplier consolidation trajectories. Revision becomes warranted when methyl methacrylate supply disruption frequency crosses volatility thresholds or when EU Green Deal recycled content mandates accelerate beyond modeled compliance curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Decorative Interior Trim Market
Automotive Interior & Exterior
Automotive Films Market
Automotive Interior & Exterior
Automotive Window and Exterior Sealing Systems Market
Automotive Interior & Exterior
Glazing for Automotive Market
Automotive Interior & Exterior
Bonnet Lock Plate and Latch Market
Automotive Interior & Exterior
Automotive Window Seals Market
Automotive Interior & Exterior
Automotive Exterior Trim Parts Market
Automotive Interior & Exterior
Float Glass for Automotive Market
Automotive Interior & Exterior
China Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Fabric Market
Automotive Interior & Exterior
Exterior Car Accessories Market
Automotive Interior & Exterior
Automotive Intelligent Rear-View Mirror Market
Automotive Interior & Exterior
Asia-Pacific Automotive Flooring Market
Automotive Interior & Exterior
Automotive Seat Recliners Market
Automotive Interior & Exterior
Car Canopies Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market