
 Automotive OE Bumper Cover Market | 2026-2036
Automotive OE Bumper Cover Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive OE Bumper Cover Market Intelligence
New production capacity investments in Mexico are tilting the supply landscape for North American automotive assembly. Magna International Inc. leverages its extensive manufacturing footprint to serve multiple OEMs across different continents. Plastic Omnium specializes in complex exterior modules, integrating lighting and sensor technologies. Faurecia SA competes through its focus on sustainable materials and advanced processing techniques for bumper systems.
An automotive OE bumper cover is the outer fascia of a vehicle's bumper system, supplied directly to original equipment manufacturers. These components are typically injection-molded from materials like Thermoplastic Olefin (TPO) and are designed for aesthetic appeal, aerodynamics, and pedestrian safety. Thermoplastic Olefin and Polypropylene dominate the material segment due to their cost-effectiveness and recyclability. The passenger vehicles application continues to be the largest segment, but demand from the electric vehicles category represents the fastest-growing opportunity due to specialized design needs.
Regulations from bodies like the US NHTSA and adherence to EU pedestrian protection standards directly influence bumper cover design and material selection. In China, GB standards for vehicle safety and material content dictate market access for suppliers. Suppliers must therefore navigate a complex matrix of regional safety requirements and material compliance to secure OEM contracts.
Market Dynamics
The central dynamic shaping the market is the evolution of the bumper cover from a passive, aesthetic component into an active, intelligent system. This shift is driven by the dual requirements of integrating sophisticated ADAS sensors for autonomous driving features while simultaneously adopting lightweight materials to meet stringent emissions and EV range standards.
Growth Catalysts
- Material Advancement:The widespread adoption of Thermoplastic Olefin (TPO) and polypropylene offers a compelling combination of low weight, high impact resistance, and recyclability, aligning with OEM efficiency targets and sustainability mandates.
- Regulatory Mandates:Stringent pedestrian safety regulations, particularly the EU's standards for leg and head impact absorption, compel the use of advanced, multi-material bumper cover designs that create consistent demand for innovative solutions.
- Electric Vehicle Proliferation:The electric vehicles segment requires unique bumper cover designs optimized for aerodynamics to maximize range and for seamless integration of sensors and charging port doors, creating a new, high-value demand stream.
Market Restraints
- Input Cost Volatility:The market is sensitive to price fluctuations in petrochemical feedstocks like propylene and ethylene, which are primary inputs for TPO and polypropylene, creating margin pressure for suppliers.
- Technical Integration Complexity:Integrating radar, LiDAR, and camera sensors behind polymer fascias without degrading their performance or aesthetics presents significant material science and radio-frequency engineering challenges.
- High Capital Investment:The large-scale injection molding tools and automated painting lines required for OE-quality bumper cover production represent a substantial capital barrier, concentrating the market among a few large suppliers.
Strategic Opportunities
- Sustainable Materials:There is a significant opportunity in developing and commercializing bumper covers made from recycled polymers or bio-based plastics, appealing to OEMs focused on circular economy principles and EU Green Deal compliance.
- Smart Bumper Modules:Moving beyond simple fascias to offer fully integrated front-end modules, complete with lighting, sensors, and cooling grilles, provides a path for suppliers to capture more value per vehicle.
- Specialized Vehicle Segments:Designing solutions for emerging autonomous shuttle and last-mile delivery robot markets, which have unique durability and low-speed impact requirements, opens a new customer category beyond traditional passenger cars.
Industry Challenges
- Regulatory Divergence:Managing design and material validation to simultaneously meet disparate safety and material content regulations, such as US NHTSA impact standards and China's GB standards, complicates global platform strategies.
- Software and Hardware Integration:The challenge for traditional plastics processors is developing the mechatronic and software expertise needed to guarantee the performance of sensor-integrated "smart bumpers," a critical OEM requirement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive OE Bumper Cover Market |
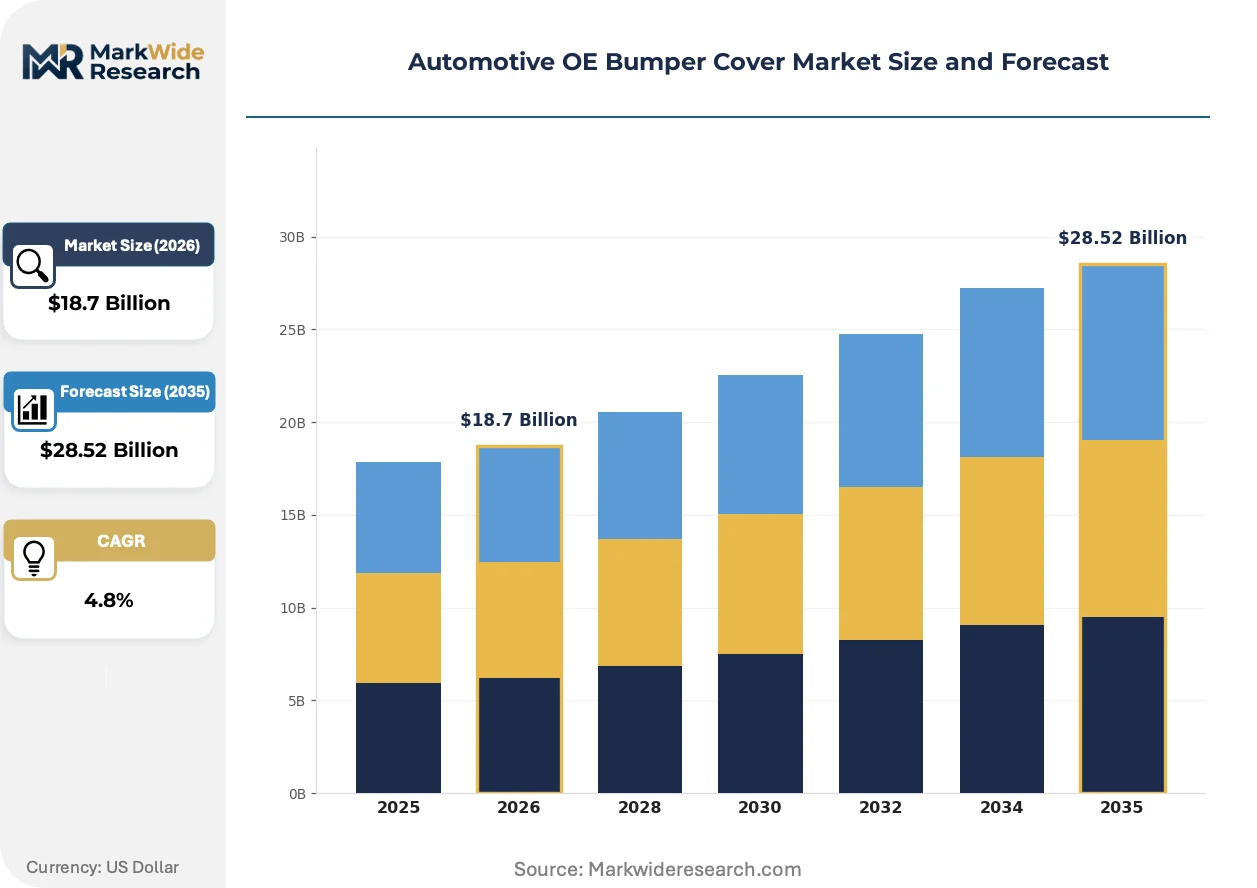
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Bumper Covers, Rear Bumper Covers, Combination Bumper Covers, Reinforced Bumper Covers Material: Thermoplastic Olefin, Polypropylene, Polycarbonate, Acrylonitrile Butadiene Styrene, Thermoplastic Polyurethane Application: Passenger Vehicles, Commercial Trucks, Specialty Vehicles, Electric Vehicles End User: Original Equipment Manufacturers, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Plastic Omnium, Magna International Inc., TONG YANG GROUP, TOYOTA BOSHOKU CORPORATION, TOYODA GOSEI Co., Ltd., Montaplast GmbH, Hyundai Mobis Co., Ltd., Faurecia SA, Flex-N-Gate Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive OE Bumper Cover Market Strategic Shifts & Innovations
The functional scope of the automotive bumper cover is expanding significantly, transforming it into a critical node for vehicle intelligence and efficiency. This evolution is driven by concurrent advances in material science, electronics integration, and new sourcing models demanded by original equipment manufacturers.
In-mold electronics technology integrates printed, flexible circuits directly onto the inner surface of the bumper fascia during the molding process. Premium and electric vehicle manufacturers are adopting this approach to achieve cleaner exterior designs and reduce the part count and assembly labor associated with separate sensor harnesses. This integration is collapsing the boundary between the structural exterior panel and the electronic hardware, creating a single, multifunctional module.
European Union's updated General Safety Regulation (GSR) mandates a suite of advanced driver-assistance systems, including enhanced emergency braking and pedestrian detection. This directly compels OEMs to integrate more capable and often more numerous sensors within the frontal area of the vehicle. The passenger vehicle segment is most affected, forcing suppliers to invest heavily in radio-frequency transparent materials and validation processes to ensure compliance for vehicles sold in the EU.
OEM sourcing strategies are pivoting from procuring individual components to sourcing complete, pre-assembled front-end modules. This shift favors large, system-level suppliers who can deliver a fully integrated unit comprising the bumper cover, grille, lighting, and all ADAS sensors, de-risking the integration process for the automaker. This trend is most pronounced in North America and Europe, where vehicle platform complexity and the push for faster assembly cycles are key priorities.
Automotive OE Bumper Cover Market Segmentation
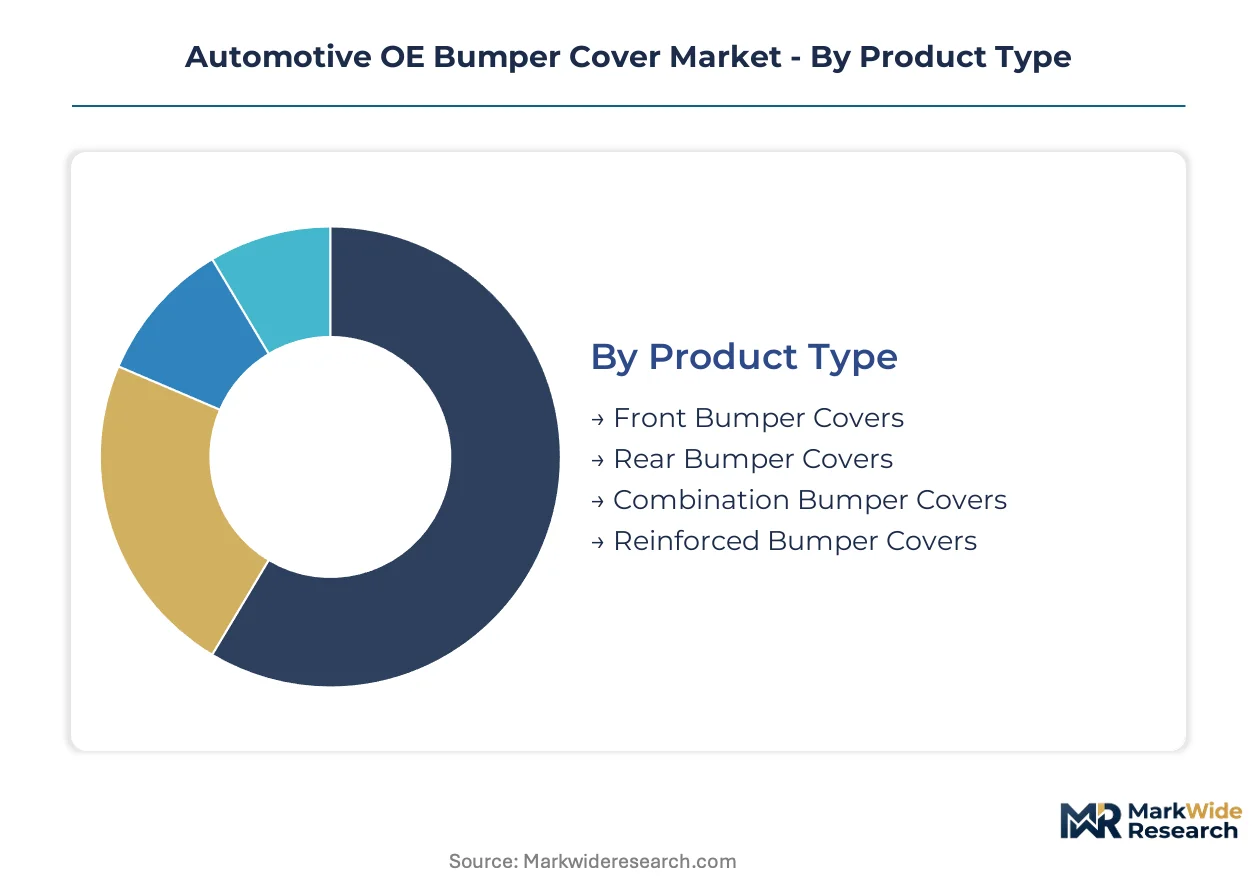
Understanding the segmentation of the automotive OE bumper cover market is critical for identifying specific demand patterns and technological requirements. Each segment presents distinct challenges and opportunities for material innovation, manufacturing processes, and integration with advanced vehicle systems.
Product Type:
The after-sales-service intensity for automotive OE bumper covers varies significantly across product types, influencing replacement cycles and repair complexity.
- Front Bumper Covers:These are the primary forward-facing exterior components, designed for aerodynamic efficiency and pedestrian impact absorption. Demand concentrates in the passenger vehicle segment, driven by aesthetic considerations and the integration of numerous ADAS sensors requiring precise fitment.
- Rear Bumper Covers:Positioned at the vehicle's rear, these covers primarily protect against low-speed impacts and integrate features like parking sensors and exhaust cutouts. The commercial truck sector shows consistent demand due to frequent loading dock interactions and the need for robust, easily replaceable components.
- Combination Bumper Covers:These components integrate multiple functional elements, such as lighting or grille sections, into a single molded unit. Their adoption reflects OEM desires for reduced assembly complexity and enhanced aesthetic consistency.
- Reinforced Bumper Covers:Designed with additional internal structures or thicker material sections, these covers offer enhanced impact resistance for specific vehicle models. Specialty vehicles and SUVs often utilize these for increased durability.
Front Bumper Covers holds the largest share; momentum sits with Reinforced Bumper Covers.
Material:
Material selection for bumper covers often involves a trade-off between cost, performance, and processing ease, reflecting distinct cost tiers.
- Thermoplastic Olefin:This material offers an excellent balance of low weight, high impact resistance, and recyclability, making it a preferred choice for many OEMs. Its widespread use in passenger vehicles aligns with stringent fuel efficiency and emissions standards.
- Polypropylene:A cost-effective and versatile polymer, polypropylene is widely used for bumper covers due to its good mechanical properties and ease of processing. Commercial trucks frequently utilize polypropylene for its durability and repairability.
- Polycarbonate:Known for its high strength and stiffness, polycarbonate is often used in applications requiring superior impact performance or specific aesthetic finishes. Premium vehicle segments sometimes incorporate this material for enhanced durability.
- Acrylonitrile Butadiene Styrene:ABS provides good rigidity and surface finish, making it suitable for specific design requirements where aesthetic precision is paramount. It finds application in various passenger car models.
- Thermoplastic Polyurethane:TPU offers exceptional flexibility and abrasion resistance, often chosen for its ability to withstand minor impacts without permanent deformation. Its use is expanding in electric vehicle designs for integrated sensor housing.
Thermoplastic Olefin commands the largest market presence, while Thermoplastic Polyurethane is experiencing the steepest expansion trajectory.
Application:
Application complexity drives distinct design and material requirements for bumper covers, segmenting demand by vehicle type.
- Passenger Vehicles:This segment represents the largest volume demand for bumper covers, driven by diverse models and design variations. Regulatory mandates for pedestrian safety and advanced driver-assistance systems heavily influence material and design choices for these vehicles.
- Commercial Trucks:Bumper covers for commercial trucks prioritize durability, repairability, and resistance to harsh operating conditions. The focus is on robust materials that can withstand frequent impacts and environmental stress.
- Specialty Vehicles:This category includes vehicles like emergency services, off-road, and recreational vehicles, requiring bumper covers optimized for specific functional demands. Durability and integration with specialized equipment are key considerations.
- Electric Vehicles:EV bumper covers demand unique aerodynamic properties to maximize range and seamless integration of charging ports and numerous sensors. Their specialized design needs make this a rapidly expanding segment.
Passenger Vehicles constitute the largest application segment, with Electric Vehicles gaining share fastest.
End User:
The market for OE bumper covers is structured around distinct customer types, each with unique procurement processes and quality demands.
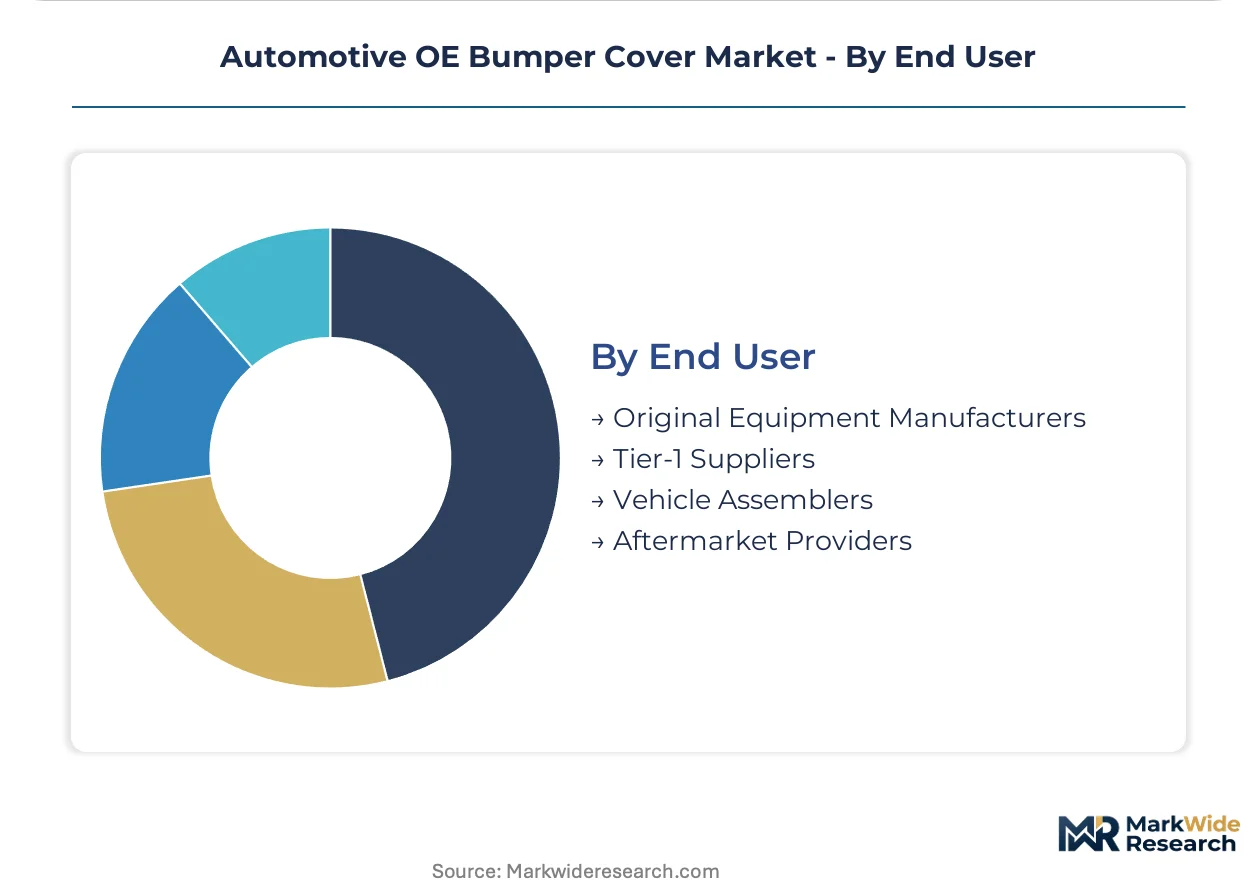
- Original Equipment Manufacturers:OEMs directly source bumper covers for new vehicle production, demanding high volumes, precise specifications, and integration with overall vehicle design. Their procurement strategies often involve long-term contracts with large suppliers.
- Tier-1 Suppliers:These suppliers provide integrated modules, including bumper covers, directly to OEMs, often incorporating lighting, sensors, and other components. They require high technical expertise and system integration capabilities.
- Vehicle Assemblers:Assemblers may procure bumper covers as part of broader sub-assemblies or directly for final vehicle integration. Their focus is on timely delivery and component compatibility for efficient production lines.
- Aftermarket Providers:This segment primarily deals with replacement bumper covers for repairs after accidents or damage. Quality and availability for a wide range of vehicle models are important for these providers.
Original Equipment Manufacturers represent the primary demand source, and Tier-1 Suppliers are crucial for integrated module delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automotive OE bumper cover market is underpinned by extensive logistics networks, including deep-water ports and integrated rail systems, facilitating component distribution across continents. These infrastructure assets support the complex supply chains required for high-volume automotive manufacturing. This enables efficient delivery of bumper covers to assembly plants worldwide.
China
Demand for OE bumper covers in China is driven by its massive vehicle production scale, particularly for electric vehicles. GB standards for vehicle safety and material content dictate market access for suppliers in China. The Yangtze River Delta region, a major automotive hub, sees significant investment in advanced manufacturing for these components.
United States
The United States market experiences demand for robust bumper covers due to its large passenger vehicle segment and SUV popularity. US NHTSA regulations for impact standards directly influence bumper cover design and material choices. The Detroit automotive cluster continues to drive innovation in material science for lightweight and durable bumper systems.
Germany
Germany's premium automotive sector requires high-performance bumper covers, integrating advanced sensor technologies and aesthetic precision. EU pedestrian protection standards compel the use of sophisticated, multi-material designs for vehicle fronts. Bavaria, a key automotive manufacturing state, focuses on developing smart bumper modules for luxury and electric vehicles.
Japan
Innovation in bumper cover design in Japan focuses on integrating advanced driver-assistance system sensors and optimizing aerodynamics for fuel efficiency. JIS standards for automotive components ensure material quality and performance in the Japanese market. The Aichi Prefecture, home to major automakers, is a center for material advancement in thermoplastic polymers.
Mexico
New production capacity investments in Mexico are tilting the supply landscape for North American automotive assembly. The country's automotive manufacturing policies support foreign direct investment in component production. The Bajío region, with its growing automotive cluster, attracts significant capital for injection molding and painting lines.
Automotive OE Bumper Cover Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, focusing on material science and manufacturing efficiency for OE bumper covers. The market structure is tiered, with large multinational suppliers offering integrated modules alongside specialized material producers. Strategic archetypes include global system integrators, regional specialists, and niche technology providers concentrating on advanced sensor integration. Dominant competitive moves involve capacity expansion in key automotive regions and strategic partnerships for technology co-development and material innovation.
Among the global system integrators, France-based Plastic Omnium S.A. exemplifies a focus on complex exterior modules, integrating lighting and sensor technologies directly into bumper systems. Canada-based Magna International Inc. represents a broad manufacturing footprint, serving multiple OEMs across different continents with diverse bumper cover solutions. This company leverages its extensive capabilities to provide comprehensive offerings. Another significant player, France-based Faurecia SA, occupies a position emphasizing sustainable materials and advanced processing techniques for its bumper systems portfolio, aligning with evolving environmental mandates.
| Leading Market Players |
|---|
| Plastic Omnium |
| Magna International Inc. |
| TONG YANG GROUP |
| TOYOTA BOSHOKU CORPORATION |
| TOYODA GOSEI Co., Ltd. |
| Montaplast GmbH |
| Hyundai Mobis Co., Ltd. |
| Faurecia SA |
| Flex-N-Gate Corporation |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstock price volatility influences margin pools for OE bumper cover suppliers. China's massive vehicle production scale affects global pricing dynamics for these components.
Pricing Analysis
EU pedestrian protection standards dictate the pricing tier structure for advanced bumper covers. Contract-based long-term offtake agreements with OEMs define the dominant pricing model. Price differentiation stems from material composition, integration complexity for ADAS sensors, and geographic delivery cost. Pricing pressure from OEM cost-cutting initiatives is intensifying. Passenger vehicle OEMs represent the most price-sensitive buyer segment due to high volume requirements.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common for large Tier-1 suppliers. Geographic supply concentration for OE bumper covers centers on China, Mexico, and Germany. Raw material dependencies include propylene and ethylene, primary inputs for TPO and polypropylene. Commodity price volatility for these petrochemical feedstocks represents a significant structural risk. Distribution runs through direct-to-OEM assembly plant deliveries, often through just-in-time systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive OE bumper cover market presents a fragmentation opportunity. Electric vehicle designs requiring specialized aerodynamic and sensor integration create distinct niches.
For Market Incumbents: Build technological moats around advanced material science for sensor integration. Invest in radio-frequency transparent materials to mitigate performance degradation from ADAS sensors. Consolidate market share through strategic acquisitions in key growth regions like Mexico, countering emerging regional specialists. Global regulatory divergence poses a constant threat to standardized product lines.
For New Entrants and Emerging Players: Build out specialized capabilities in sustainable materials like bio-based plastics. Target the rapidly expanding electric vehicle segment, focusing on unique aerodynamic and sensor housing requirements. Develop modular front-end solutions for emerging autonomous shuttle markets. A go-to-market angle could involve offering rapid prototyping and validation services for complex ADAS integrations.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-sized Tier-2 suppliers specializing in injection molding. Long-term viability rests on integrating mechatronic expertise with traditional plastics processing. Acquire companies with proven track records in in-mold electronics or advanced sensor integration. A signal to watch is the increasing patent activity in radio-frequency transparent polymer composites.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Mexico | Supports North American automotive assembly and regional supply chain resilience. |
| Investment in Bio-based Polymers | Aligns with EU Green Deal and OEM sustainability mandates. |
| ADAS Sensor Integration R&D | Ensures seamless performance of autonomous driving features behind bumper fascias. |
| Strategic Partnership with Electronics Firm | Acquires mechatronic expertise for smart bumper module development. |
| Development of Integrated Front-End Modules | Captures more value per vehicle by de-risking OEM assembly. |
Research Approach
Desk research of industry reports, regulatory filings, and trade publications preceded structured interviews with OEM procurement managers, Tier-1 engineering leads, and material science experts. This approach combined primary insights with secondary validation for comprehensive market understanding. Bottom-up data collection from production volumes triangulated with top-down market sizing estimates.
Constant macroeconomic conditions and stable regulatory frameworks were assumed across the analysis window, while material cost fluctuations were varied. The analytical framework modeled market dynamics by product type, material, application, and end-user. Compound annual growth rates were derived from historical trends and projected technological adoption curves. Key forecast inputs included electric vehicle production forecasts and material innovation timelines.
Stress conditions across petrochemical feedstock prices and global vehicle production volumes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Global Automotive Window Power Sunshade Market
Automotive Interior & Exterior
Automotive Ambient Lighting Market
Automotive Interior & Exterior
Automotive Air Conditioning Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Glove Box Market
Automotive Interior & Exterior
Automotive Seat Recliners Market
Automotive Interior & Exterior
Automotive Sound Proofing Material Market
Automotive Interior & Exterior
Automotive Door Handle Sensors Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Automotive Seat Climate Systems Market
Automotive Interior & Exterior
Automotive Chromium Finishing Market
Automotive Interior & Exterior
Automotive Window and Exterior Sealing Systems Market
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
Automotive Display Market
Automotive Interior & Exterior
Automotive Door Impact Bars Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market