
 Automotive Smart Dashboard Display Market | 2026-2036
Automotive Smart Dashboard Display Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Smart Dashboard Display Market Outlook
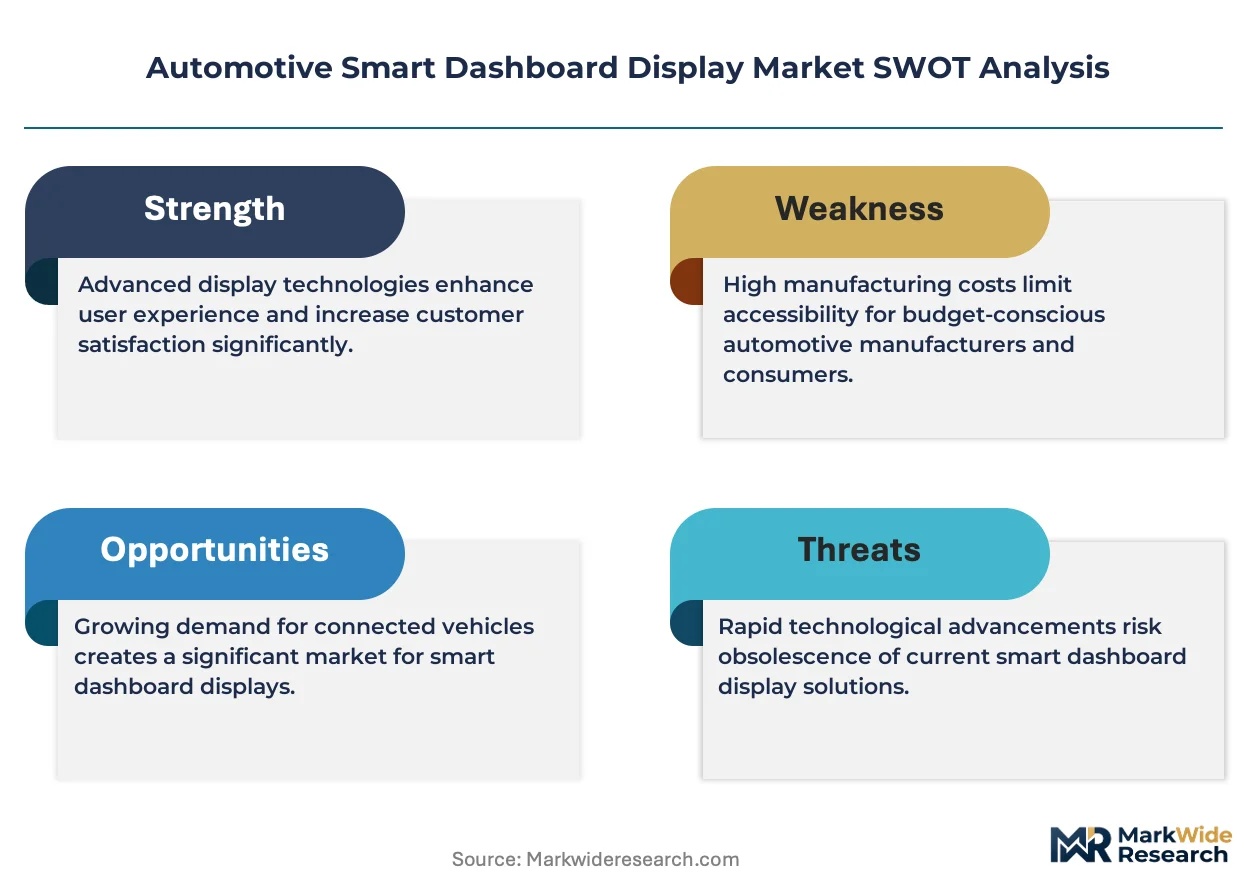
Multi-source display panel procurement is recalibrating as OEMs balance supply security against cost optimization. Denso Corporation leverages its captive semiconductor and display driver capabilities to anchor integrated cockpit system bids. Panasonic Corporation sustains manufacturing scale across LCD and OLED generations, competing for flagship vehicle programs in Japan and North America. Visteon Corporation specializes in software-defined digital cluster architectures, differentiating through over-the-air update readiness.
An automotive smart dashboard display integrates high-resolution screens, graphics processing units, and human-machine interface software to present vehicle telemetry, navigation, and infotainment content to drivers. These assemblies typically employ thin-film transistor backplanes with brightness ratings exceeding 1000 cd/m² for daylight readability, bonded cover lenses with anti-reflective coatings, and automotive-grade operating temperatures from -40°C to 85°C. Touchscreen Display configurations dominate current OEM fitment volumes, while OLED technology captures expanding share in premium segments where contrast ratio and form-factor flexibility command margin premiums. Digital Cluster replacements of analog gauges represent the fastest-growing product category as electrified vehicle platforms mandate reconfigurable instrumentation.
NHTSA guidelines on driver distraction limit visual complexity and glance duration, while EU Green Deal frameworks push display energy efficiency to preserve electric vehicle range. REACH and RoHS constraints from ECHA restrict hazardous substances in display manufacturing, elevating compliance costs for panel suppliers. Stakeholders must monitor evolving ISO 26262 functional safety grades and cybersecurity standards as software-defined cockpit architectures expand attack surfaces and liability exposure.
Market Dynamics
Platform electrification is compressing instrument cluster refresh cycles as EV architectures demand reconfigurable displays that communicate battery state, regenerative braking feedback, and charging telemetry through unified graphical interfaces.
Growth Catalysts
- EU Green Deal electrification mandates:Vehicle CO₂ reduction targets force OEMs to prioritize energy-efficient display technologies that preserve electric range, accelerating OLED adoption over conventional LCD backlights.
- Touchscreen Display penetration:Multi-modal haptic feedback and gesture control integration expand human-machine interface capabilities beyond visual output, creating pull for advanced driver assistance system coordination.
- Germany-Japan-US demand concentration:Premium OEM headquarters and EV specialist engineering centers in these countries concentrate procurement authority for flagship cockpit programs.
Market Restraints
- Automotive-grade semiconductor shortage:Display driver IC and GPU supply volatility from captive foundry allocation limits panel output scaling during demand surges.
- Raw material cost volatility:Indium tin oxide and rare earth phosphor price swings for OLED emitters compress margin predictability for panel suppliers.
- NHTSA distracted-driving enforcement:Glance-duration limits and visual complexity restrictions constrain feature expansion for infotainment-integrated clusters.
Strategic Opportunities
- Software-defined cockpit architectures:Over-the-air update capability for digital clusters creates recurring revenue potential through feature activation services.
- Commercial vehicle digitization:Fleet telematics integration and driver behavior monitoring open aftermarket retrofit demand for heavy-duty truck and bus operators.
- India automotive production expansion:Domestic OEM capacity growth and export hub development create localized display sourcing requirements.
Industry Challenges
- ISO 26262 functional safety certification:ASIL-B to ASIL-D grade validation for instrument cluster graphics pipelines extends development timelines and testing expenditure.
- Legacy vehicle electrical architecture integration:CAN bus bandwidth constraints and legacy power conditioning complicate retrofit of advanced displays into existing model lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Smart Dashboard Display Market |
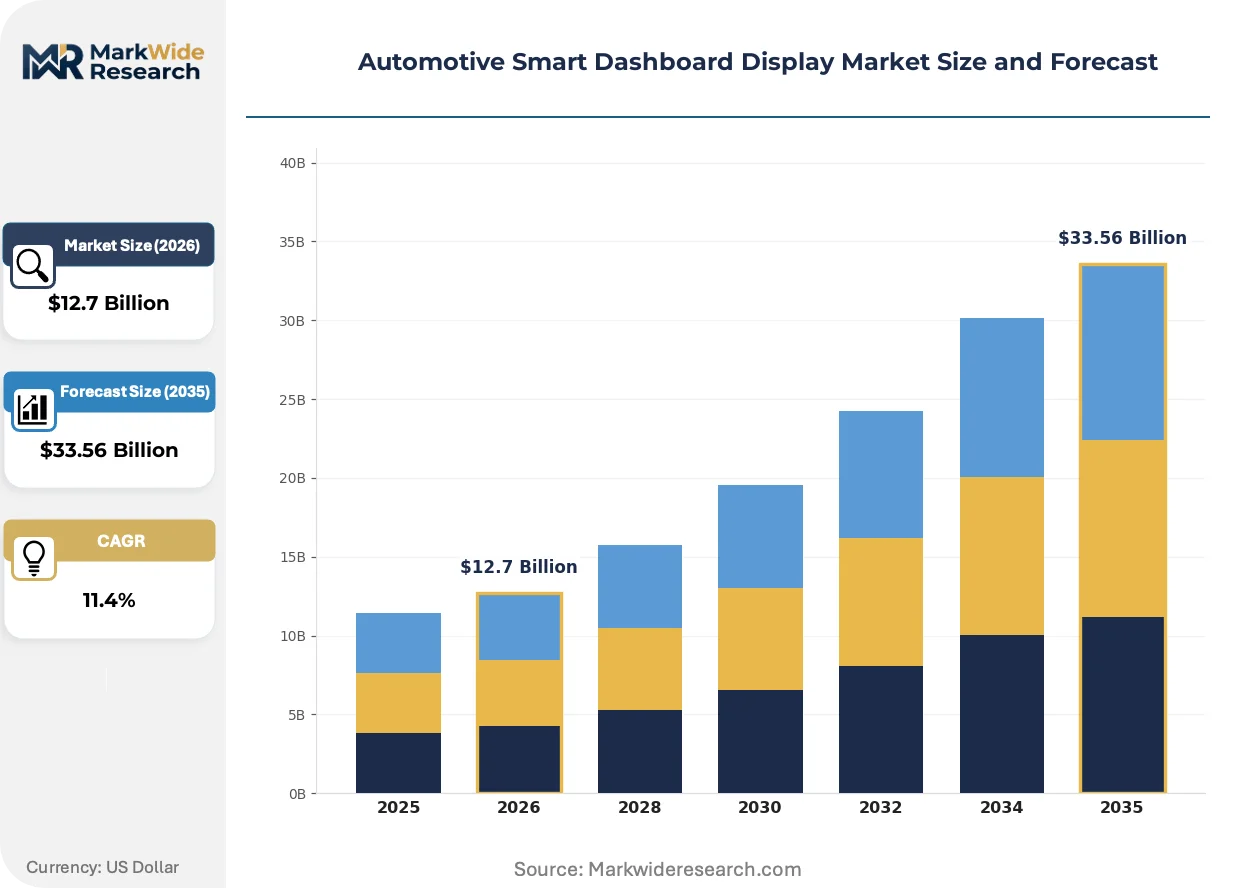
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $33.56 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head-Up Display, Digital Cluster, Touchscreen Display, Projection Display Technology: OLED, LCD, MicroLED, E-Ink End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Feature: Navigation, Entertainment, Vehicle Status, Connectivity |
| Companies Covered | Denso Corporation, Panasonic Corporation, Hyundai Mobis, Alps Alpine Co., Ltd., Nippon Seiki Co., Ltd., Robert Bosch GmbH, Visteon Corporation, LG Display Co. Ltd., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Smart Dashboard Display Market Strategic Shifts
Display technology convergence with autonomous driving sensor fusion is redefining cockpit information hierarchy, shifting priority from mechanical gauge replication to situational awareness visualization.
MicroLED backlighting is integrating local dimming zones exceeding 1000 segments to achieve contrast ratios rivaling emissive OLED without burn-in susceptibility. Tier 1 suppliers in Germany and Japan are sampling 12.3-inch curved modules for 2027 vehicle programs. This technology is integrating with augmented reality head-up display coordination to compress multiple information layers into coherent spatial presentations.
EU AI Act algorithmic transparency requirements are mandating explainable outputs for AI-generated driver alerts displayed on smart clusters. OEMs must document decision pathways for collision warnings and navigation suggestions. European premium brands are responding by segregating certified safety-critical graphics from infotainment rendering pipelines.
Fleet operators are consolidating procurement through direct contracts with display system integrators, bypassing traditional tiered automotive supply structures. Large logistics and ride-hail companies specify standardized cluster configurations across multi-brand vehicle purchases. This pattern is most visible in the United States where commercial fleet scale permits volume-based specification authority.
Automotive Smart Dashboard Display Market Segmentation
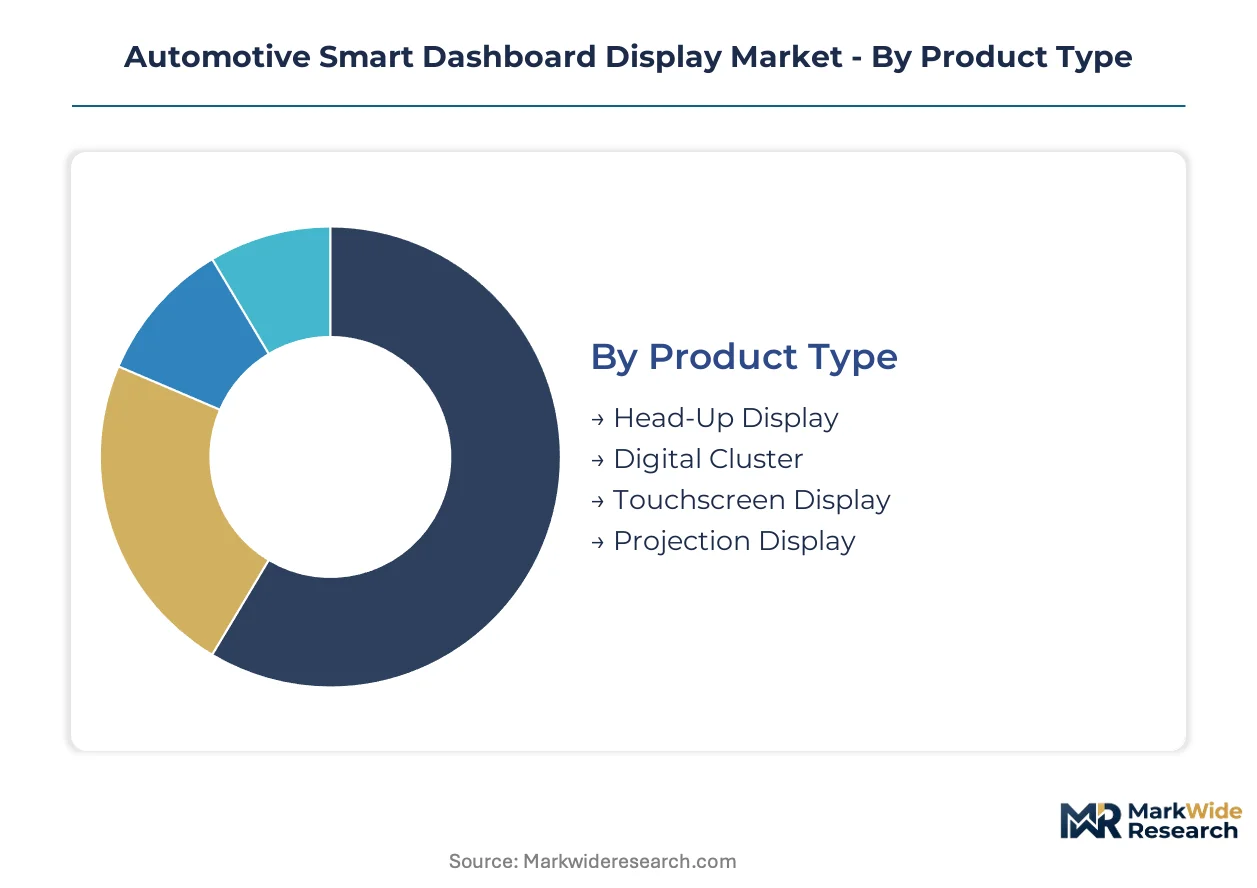
Automotive smart dashboard displays fragment across hardware form factors, display technologies, supply chain tiers, and functional software modules. Each segmentation axis carries distinct margin profiles, certification requirements, and procurement patterns that shape competitive positioning.
Product Type:
Customization intensity varies sharply across this category, from fully bespoke digital clusters engineered per vehicle platform to standardized projection modules.
- Digital Cluster:Reconfigurable screen assemblies replacing analog gauges with software-rendered instrumentation. EV platforms in Germany and Japan drive specification authority here, requiring battery state visualization and regenerative braking feedback that analog designs cannot deliver.
- Touchscreen Display:Central-stack and instrument-panel-integrated capacitive screens with multi-touch gesture recognition. NHTSA glance-duration limits constrain feature complexity for US-bound vehicles, while EU Green Deal energy budgets favor OLED backlighting variants.
- Head-Up Display:Windshield-projected information overlays reducing driver eye movement.
- Projection Display:Secondary screen surfaces enabling unconventional form factors.
Most installed capacity flows through Touchscreen Display. Expansion is steepest in Digital Cluster.
Technology:
Cost tier stratification separates premium emissive technologies from mature LCD volume production.
- LCD:Thin-film transistor backplanes with LED edge-lighting dominate current fitment volumes. Panasonic Corporation and Denso Corporation anchor supply security through captive driver IC capabilities and multi-source panel procurement.
- OLED:Organic emissive layers enable contrast ratios exceeding 1,000,000:1 and curved form factors. Premium OEM programs in Japan and Germany absorb margin premiums for daylight-readable brightness ratings above 1000 cd/m².
- MicroLED:Inorganic emissive micro-arrays sampling for 2027 vehicle programs with local dimming exceeding 1000 zones.
- E-Ink:Bistable electrophoretic displays for ultra-low-power status readouts.
LCD retains the largest installed base. OLED is gaining share fastest among electrified vehicle architectures.
End User:
Supply chain position determines specification authority and volume concentration.
- OEMs:Vehicle manufacturers with direct cockpit electronics procurement authority. Germany-based premium brands and Japan's EV specialists concentrate flagship program decisions.
- Tier-1 Suppliers:System integrators such as Visteon Corporation bundling display hardware with software-defined cluster architectures.
- Aftermarket Providers:Retrofit specialists serving commercial fleet telematics upgrades.
- Vehicle Assemblers:Contract manufacturers with limited design authority.
OEMs command the highest-value procurement decisions. Aftermarket Providers show the steepest expansion trajectory through fleet digitization mandates.
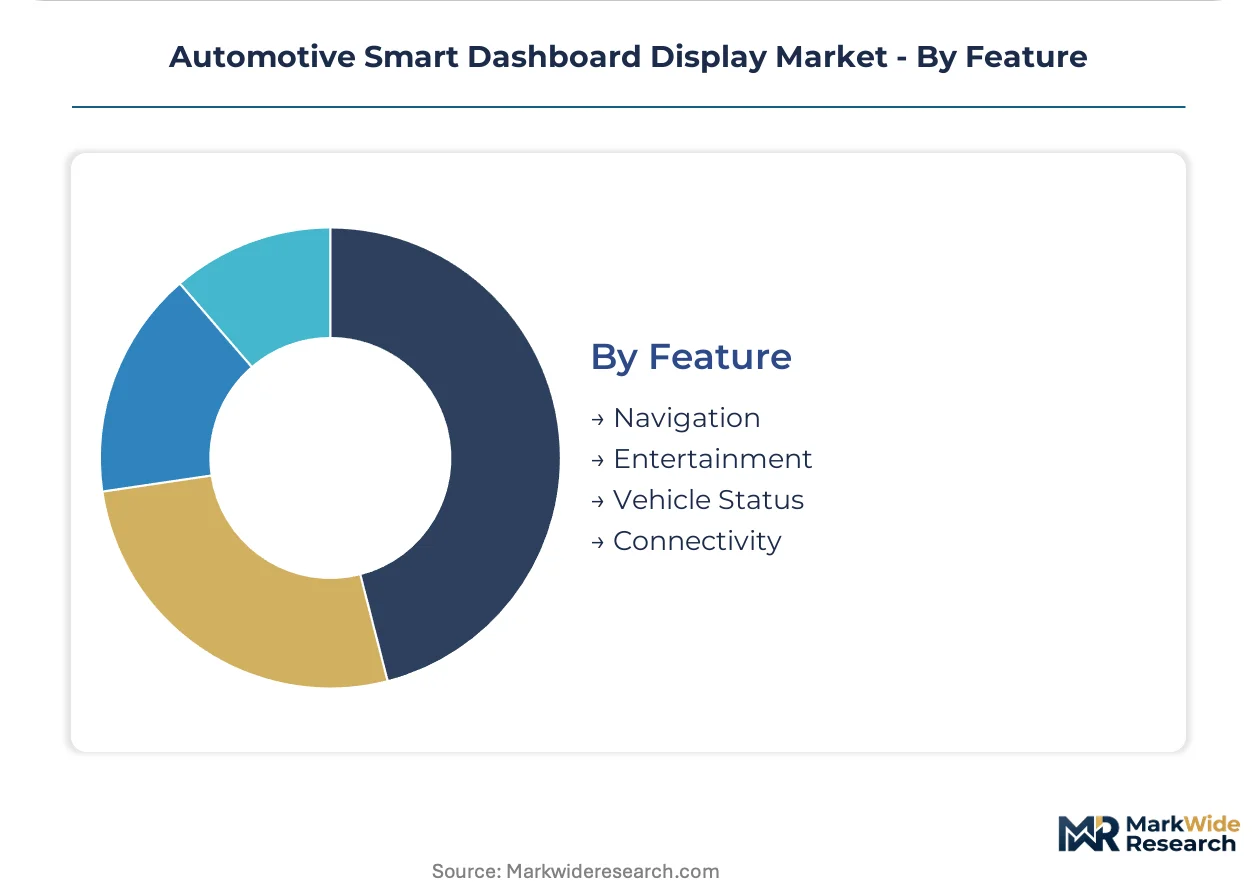
Feature:
Application maturity separates safety-critical instrumentation from discretionary infotainment.
- Vehicle Status:Speed, battery state, and warning indicator rendering subject to ISO 26262 ASIL-B to ASIL-D functional safety grades. EU AI Act transparency requirements now mandate explainable outputs for AI-generated alerts.
- Navigation:Turn-by-turn guidance with augmented reality head-up display coordination. NHTSA guidelines limit visual complexity to manage driver distraction liability.
- Entertainment:Streaming and media playback with lower safety certification burdens.
- Connectivity:Smartphone integration and over-the-air update readiness enabling recurring revenue models.
Vehicle Status absorbs the largest safety engineering investment. Connectivity carries the steepest expansion trajectory through software-defined cockpit architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive electronics corridor from Stuttgart to Ingolstadt concentrates flagship cockpit program decisions for premium OEMs. NHTSA guidelines and EU Green Deal frameworks shape divergent compliance requirements across Atlantic markets. EV platform electrification mandates in Japan and South Korea accelerate reconfigurable display adoption.
United States
NHTSA distracted-driving enforcement limits glance duration and visual complexity for infotainment-integrated clusters. The Inflation Reduction Act domestic content provisions incentivize localized display system assembly. Michigan's automotive engineering base anchors Tier-1 supplier development for Detroit Three electrification programs.
Germany
Premium OEM headquarters in Munich and Stuttgart drive specification authority for flagship digital cluster architectures. EU Green Deal CO₂ reduction targets force energy-efficient OLED adoption over conventional LCD backlights. Baden-Württemberg's supplier ecosystem integrates ISO 26262 functional safety certification into cockpit electronics pipelines.
Japan
EV specialist engineering centers in Nagoya and Tokyo mandate reconfigurable instrumentation for battery state visualization. METI semiconductor supply chain resilience initiatives reduce display driver IC import dependency. Kansai region display panel manufacturing scales OLED production for daylight-readable brightness ratings above 1000 cd/m².
South Korea
Domestic OEM electrification roadmaps compress instrument cluster refresh cycles for unified graphical interfaces. MFDS automotive-grade component standards align with international functional safety grades. Seoul Capital Area system integrators sample MicroLED modules with local dimming exceeding 1000 zones for 2027 vehicle programs.
India
Domestic OEM capacity growth and export hub development create localized display sourcing requirements. PLI scheme incentives attract component manufacturing for cockpit electronics assembly. Tamil Nadu and Maharashtra automotive corridors concentrate Tier-1 supplier facility expansion for Maruti Suzuki and Hyundai Motor India programs.
Automotive Smart Dashboard Display Market Competitive Environment
Global majors compete with regional champions across technology generations and safety certification tiers. The vendor base separates into captive semiconductor integrators, display panel specialists, and software-defined cockpit architects. Three archetypes dominate: integrated system suppliers with in-house driver IC capabilities, pure-play panel manufacturers scaling across LCD and OLED generations, and software-centric Tier-1s differentiating through over-the-air architectures. Competitive moves concentrate on strategic partnerships for GPU supply security and backward integration into display driver semiconductor fabrication.
Within the integrated system tier, Denso Corporation and Panasonic Corporation anchor Japanese supply security through captive component capabilities. Visteon Corporation occupies the software-defined architecture position, exemplifying over-the-air update readiness as a differentiation vector. These three entities represent distinct competitive positioning strategies: semiconductor integration, manufacturing scale across display generations, and software-centric cluster architectures.
| Leading Market Players |
|---|
| Denso Corporation |
| Panasonic Corporation |
| Hyundai Mobis |
| Alps Alpine Co., Ltd. |
| Nippon Seiki Co., Ltd. |
| Robert Bosch GmbH |
| Visteon Corporation |
| LG Display Co. Ltd. |
| Continental AG |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal CO₂ reduction mandates gate qualified supply for energy-efficient OLED panels and premium-tier pricing access for cockpit electronics that preserve electric vehicle range. OEM procurement teams now weight display energy budgets against daylight readability specifications, compressing margin structures for conventional LCD suppliers while elevating pricing power for certified low-power alternatives.
Pricing Analysis
Indium tin oxide and rare earth phosphor cost pass-through dominates panel pricing dynamics, with raw material volatility compressing predictability for OLED emitters. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified safety-critical clusters from infotainment-integrated displays and aftermarket retrofit modules. Pricing pressure stems from automotive-grade semiconductor shortage allocation constraints limiting display driver IC availability. Fleet operators exhibit highest price sensitivity through consolidated direct procurement, while premium OEMs in Germany and Japan absorb margin premiums for flagship curved OLED programs.
Supply Chain Analysis
Display driver IC supply rests on Japanese and South Korean specialty semiconductor foundries, with GPU procurement tethered to Taiwan and USA fabrication capacity. Indium tin oxide for transparent electrodes, rare earth phosphors for OLED emitters, and automotive-grade glass substrates constitute critical input dependencies. Single-source vulnerability concentrates in advanced node semiconductor fabrication for graphics processing units. Distribution runs through Tier-1 system integrators bundling hardware with software-defined cluster architectures for direct OEM fitment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU Green Deal electrification mandates and NHTSA distracted-driving guidelines compound demand for certified energy-efficient displays that simultaneously meet safety and sustainability thresholds.
For Market Incumbents: Deepen captive semiconductor capabilities to anchor integrated cockpit system bids against pure-play panel manufacturers. Denso Corporation's driver IC integration model offers template for backward integration into display driver fabrication. Priority lever sits with ISO 26262 ASIL-D certification pipelines that extend development timelines and lock out unqualified competitors. For New Entrants and Emerging Players: Fleet telematics integrators represent the most penetrable channel partner type for bypassing traditional tiered automotive supply structures. Aftermarket retrofit demand for heavy-duty truck and bus operators in the United States offers white-space entry with standardized cluster configurations. Direct contracting with logistics and ride-hail companies enables volume-based specification authority without OEM gatekeeping. For Investors and Strategic Acquirers: Roll-up economics work for software-defined cockpit architects because recurring revenue potential through over-the-air feature activation services creates valuation multiples unavailable to hardware-only suppliers. Target acquisition archetype combines display hardware manufacturing with software update infrastructure. Signal to watch is fleet operator procurement consolidation patterns bypassing traditional tiered supply structures.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Over-the-air update readiness enables recurring revenue through feature activation services. |
| Battery Supply Agreement | EV platform electrification mandates reconfigurable instrumentation for state visualization. |
| Platform Standardization | Unified graphical interfaces compress instrument cluster refresh cycles across vehicle lines. |
| Geographic Manufacturing Footprint | India PLI scheme incentives attract localized cockpit electronics assembly for export hubs. |
| Charging Infrastructure Partnership | Telematics integration links dashboard displays with charging network status and navigation. |
Study Parameters
Bottom-up vehicle production modeling reconciled against top-down display panel shipment tracking forms the analytical core of this study. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations specialists combine with secondary validation from vehicle production databases, IHS Markit registration data, customs/trade records, and SEC filings from listed component suppliers.
Historical trendline analysis of instrument cluster refresh cycles and display technology adoption curves informs projection frameworks across the analysis window. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from regression analysis of technology substitution patterns and regulatory mandate implementation timelines, with EV platform penetration rates and semiconductor supply elasticity as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act algorithmic transparency enforcement and NHTSA distracted-driving guideline revisions. Forecasts reflect documented assumptions regarding electrification roadmap adherence and display driver IC supply normalization. A small set of triggers—semiconductor foundry allocation shifts, rare earth export restrictions, and fleet procurement consolidation acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Floor Carpet Market
Automotive Interior & Exterior
Global Automotive Tinted Window Pane Market
Automotive Interior & Exterior
Automotive Steering Wheel Market
Automotive Interior & Exterior
Automotive Baggage Handling System Market
Automotive Interior & Exterior
Automotive Energy Absorption (EA) Pads Market
Automotive Interior & Exterior
Automotive Fuel Tank Covers Market
Automotive Interior & Exterior
Automotive Door Seal Market
Automotive Interior & Exterior
Interior Materials for Pet-Friendly Vehicle Cabins Market
Automotive Interior & Exterior
Global Automotive Carpeting Market
Automotive Interior & Exterior
North America Automotive Flooring Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Automotive Racing Seats Market
Automotive Interior & Exterior
Global Car Air Purifier Market
Automotive Interior & Exterior
Automotive Liftgate Market
Automotive Interior & Exterior
Automotive Encapsulated Glass Market
Automotive Interior & Exterior
Automotive Interior Cleaner Market