
 Automotive Reconfigurable Body Panel Market | 2026-2036
Automotive Reconfigurable Body Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Reconfigurable Body Panel Market Outlook
Specialized polymer composite engineering talent is collapsing across traditional automotive supply bases, forcing material suppliers to rebuild technical capabilities from adjacent industries. Covestro AG leverages its polyurethane chemistry heritage to anchor development of self-healing surface coatings for exterior panels. SABIC competes through backward integration into thermoplastic resin production, securing captive supply for modular panel programs. BASF SE differentiates by operating dedicated automotive application centers in proximity to German OEM engineering hubs.
Automotive reconfigurable body panels are interchangeable exterior and interior surface assemblies, typically manufactured from fiber-reinforced thermoplastic composites with wall thickness tolerances of 0.5 to 2.0 millimeters, designed to enable rapid vehicle platform customization without retooling primary body structures. Their primary commercial purpose is to reduce capital expenditure per vehicle variant while supporting mass personalization at assembly-line throughput rates. Exterior panels lead volume demand as OEMs seek to differentiate shared EV skateboard platforms through swappable fascias and closure panels. Composite materials represent the fastest-growing material category, displacing stamped metal where weight reduction targets exceed fifteen percent. Three-dimensional printing technology occupies emerging niches for custom panel low-volume production, though injection molding sustains margin concentration at scale.
The US NHTSA crashworthiness standards and the EU Green Deal circular-economy requirements are reshaping material selection criteria, with both frameworks pressuring manufacturers to demonstrate recyclability pathways for thermoplastic composites. REACH chemical authorization in Europe and EPA emissions guidelines in the United States further constrain adhesive and coating chemistries permitted in panel bonding processes. Stakeholders must monitor regulatory divergence between jurisdictions to avoid duplicative certification investments as reconfigurable architectures proliferate across vehicle programs.
Market Dynamics
Platform consolidation across electric vehicle architectures is compressing variant tooling costs, forcing exterior differentiation onto swappable panel systems rather than unique body-in-white structures. This structural shift concentrates supplier negotiation power with OEMs capable of standardizing skateboard chassis across multiple nameplates.
Growth Catalysts
- EU Green Deal circular-economy mandates:Recyclability requirements for thermoplastic composites accelerate material substitution away from thermoset alternatives that lack end-of-life pathways.
- EV platform sharing:Manufacturers deploying shared skateboard architectures across sedan, crossover, and utility variants require reconfigurable fascias to maintain brand differentiation without unique stamping investments.
- Thermoplastic composite processing advances:Reduced cycle times for injection-molded modular panels enable assembly-line throughput rates matching metal stamping volumes.
Market Restraints
- Specialized polymer engineering talent scarcity:Technical expertise in fiber-reinforced composite formulation concentrates in aerospace and wind energy sectors, not automotive supply bases.
- REACH chemical authorization constraints:Adhesive and coating chemistries permitted in panel bonding face narrowing approval windows, extending formulation validation timelines.
- Stamped metal cost floor:High-volume steel and aluminum closure panels retain cost advantages where weight reduction targets fall below fifteen percent thresholds.
Strategic Opportunities
- Three-dimensional printing integration:Additive manufacturing for custom low-volume panel production addresses niche personalization segments unreachable through injection molding economics.
- Aftermarket replacement channels:Damage-prone reconfigurable panels create recurring revenue streams through certified repair networks and direct-to-consumer cosmetic upgrade programs.
- German OEM engineering hub proximity:Application centers co-located with Stuttgart and Munich technical campuses capture platform development influence before specifications harden.
Industry Challenges
- Crashworthiness certification complexity:NHTSA pedestrian protection and offset collision standards require extensive physical testing of each panel variant, compressing program development schedules.
- Multi-material joining expertise gaps:Bonding dissimilar substrates—thermoplastic composites to aluminum closures, steel structural members—demands process engineering capabilities scarce in traditional body shop engineering teams.
- Recyclate quality consistency:Post-industrial and post-consumer thermoplastic composite streams exhibit property variability that challenges OEM surface finish and dimensional tolerance requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Reconfigurable Body Panel Market |
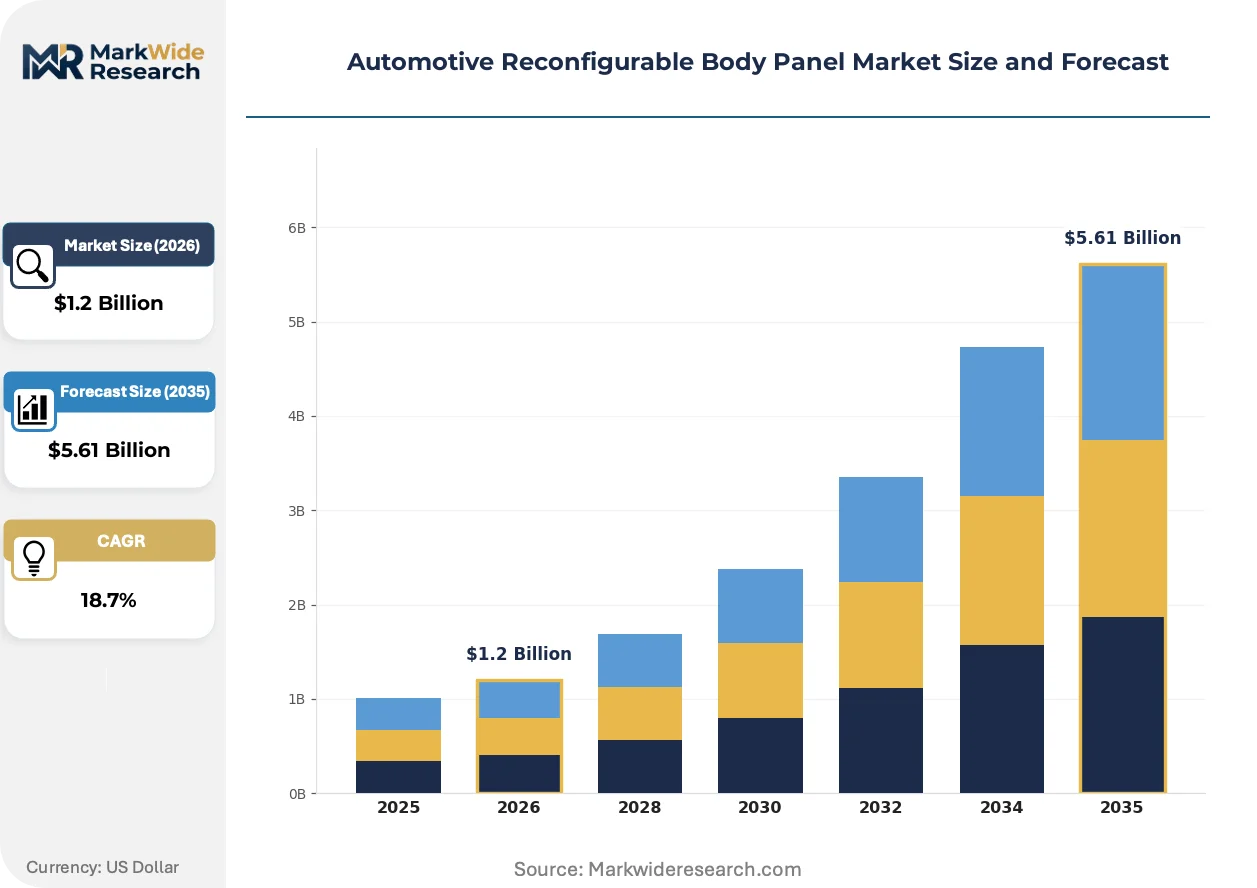
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $5.61 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Panels, Exterior Panels, Modular Panels, Custom Panels Material: Metal, Plastic, Composite, Fiberglass Technology: 3D Printing, Injection Molding, Laser Cutting, CNC Machining End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | SABIC, Toray Industries, Covestro AG, Owens Corning, Teijin Limited, Mitsubishi Chemical Corporation, Hexcel Corporation, Gurit Holding AG, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Reconfigurable Body Panel Market Strategic Shifts
Material science advances and regulatory pressure on vehicle lifecycle emissions are converging to reshape how exterior panels are specified, manufactured, and recovered. Three interconnected developments are restructuring competitive positioning across the supply base.
Thermoplastic composites with continuous fiber reinforcement are fragmenting the historical dominance of sheet molding compound in exterior panel applications. EV manufacturers pursuing shared platform strategies adopt these materials for their damage tolerance and repairability advantages over thermoset alternatives. The technology is fragmenting supplier hierarchies by enabling tier-two compounders to bypass traditional stamping-press equipment barriers and compete directly on material formulation performance.
REACH authorization timelines for novel adhesive chemistries are compressing bonding process development windows across European vehicle programs. ECHA's expanding candidate list of substances of very high concern forces reformulation of structural adhesives before full industrial validation cycles complete. German OEMs respond by accelerating in-house adhesive characterization capabilities to reduce dependency on external certification timelines.
Fleet procurement models for commercial vehicle operators are unbundling exterior panel replacement from full-service lease agreements. Logistics and last-mile delivery fleets in North America now specify separate maintenance contracts for damage-prone fascias and closure panels. This behavioral shift concentrates volume purchasing power with national fleet maintenance networks rather than dispersed dealer service operations.
Automotive Reconfigurable Body Panel Market Segmentation
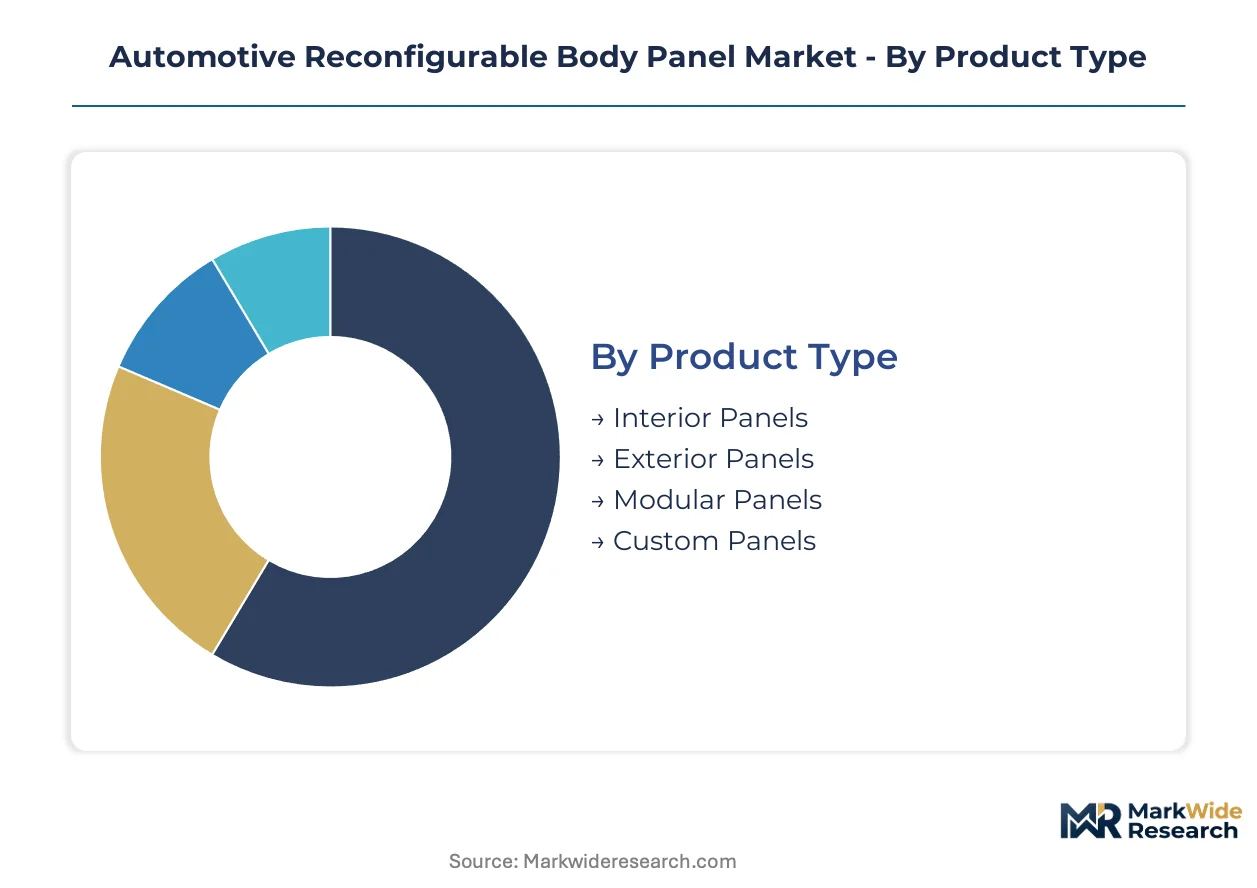
Segmentation in the automotive reconfigurable body panel market reveals distinct supply chain pathways. Each dimension channels differentiated products through specific procurement relationships and technical validation requirements.
Product Type:
Exterior panels flow primarily through OEM direct procurement channels, while interior and custom variants increasingly route through tier-1 integrators and aftermarket distributors.
- Interior Panels:Cabin surface assemblies manufactured from fiber-reinforced thermoplastics with acoustic dampening substrates. Demand concentrates in German OEM premium EV platforms where modular dashboard and door card systems reduce variant tooling costs for shared architectures.
- Exterior Panels:Fascia, closure, and body-side assemblies engineered for pedestrian impact compliance and aerodynamic consistency. German manufacturers prioritize these for skateboard platform differentiation, sourcing through captive composite stamping operations near Stuttgart engineering hubs.
- Modular Panels:Standardized attachment interfaces enabling rapid platform reconfiguration without body-in-white modification.
- Custom Panels:Low-volume specialty surfaces produced through additive or hybrid manufacturing for limited-edition vehicle programs.
By volume, Exterior Panels leads. By growth pace, Modular Panels is ahead.
Material:
Material selection stratifies across cost tiers, with premium lightweight composites commanding OEM engineering budgets and standardized metals serving cost-sensitive volume programs.
- Composite:Continuous fiber-reinforced thermoplastic matrices offering damage tolerance and repairability advantages over thermoset alternatives. EU Green Deal recyclability mandates accelerate substitution as German OEMs phase out non-recyclable sheet molding compounds.
- Plastic:Injection-molded thermoplastic compounds for interior trim and non-structural exterior applications. Volume demand clusters in high-variant EV programs where cycle time advantages over metal stamping justify material premiums.
- Metal:Stamped aluminum and steel closure panels retaining cost advantages below fifteen percent weight reduction thresholds.
- Fiberglass:Chopped-strand mat and woven roving composites for aftermarket repair panels and low-volume custom applications.
Composites dominate OEM engineering attention. Plastics sustain the broadest aftermarket channel penetration.
Technology:
Technology segmentation maps directly to volume scale, with high-throughput molding serving mass production and additive methods capturing personalization premiums.
- Injection Molding:High-pressure thermoplastic composite forming achieving cycle times matching metal stamping volumes. German OEMs specify these lines for reconfigurable fascia programs across shared EV platforms.
- 3D Printing:Fused deposition and selective laser sintering for custom panel geometries unreachable through conventional tooling. Demand localizes in North American fleet upgrade programs and European limited-series manufacturers.
- Laser Cutting:Precision trimming and feature creation for composite panel net-shape processing.
- CNC Machining:Subtractive finishing for tight-tolerance mating surfaces and attachment point refinement.
Injection Molding anchors production economics. 3D Printing is climbing the fastest as personalization premiums expand addressable markets.
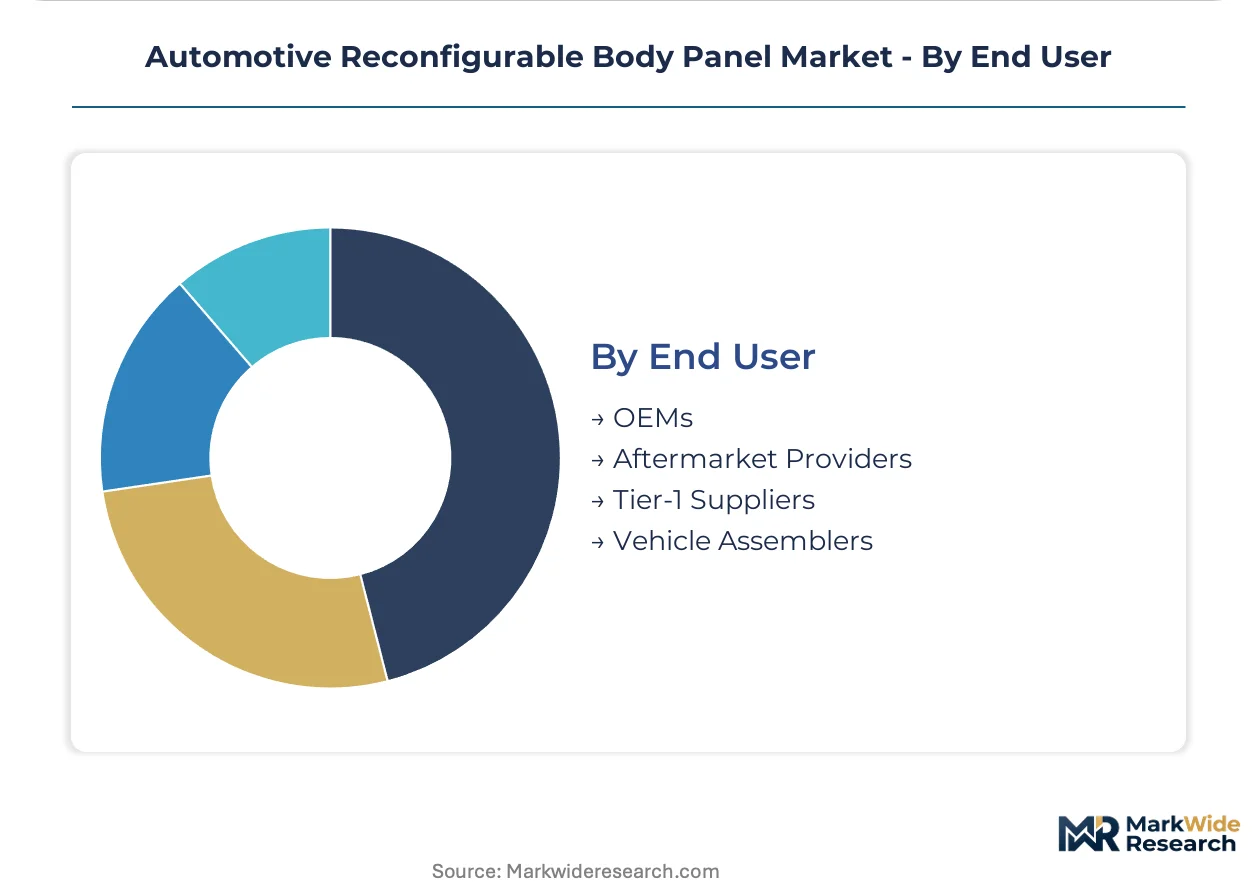
End User:
End user segmentation concentrates purchasing power with platform-owning OEMs, while aftermarket channels fragment across national fleet networks and dealer service operations.
- OEMs:Volkswagen Group, BMW AG, and Mercedes-Benz Group AG specify reconfigurable panels during platform development to amortize skateboard chassis investments across multiple nameplates. Their engineering hubs in Munich and Stuttgart harden specifications before supplier qualification.
- Aftermarket Providers:National fleet maintenance networks and certified repair channels for damage-prone fascias and closure panels. North American logistics operators now unbundle panel replacement from full-service lease agreements.
- Tier-1 Suppliers:System integrators managing composite panel bonding, painting, and sequencing for just-in-time assembly delivery.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations without in-house panel engineering capabilities.
OEMs command specification authority. Aftermarket Providers are gaining share fastest as fleet procurement models unbundle maintenance contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys reconfigurable panels primarily for EV platform differentiation, while the United States concentrates demand in fleet aftermarket channels and China pushes thermoplastic composite adoption for domestic weight-reduction mandates.
Germany
Volkswagen Group, BMW AG, and Mercedes-Benz Group AG specify modular exterior panels across shared skateboard architectures to amortize chassis development costs. EU Green Deal circular-economy requirements from ECHA accelerate thermoplastic composite substitution for non-recyclable thermosets. Engineering hubs in Stuttgart and Munich harden panel specifications before supplier qualification, concentrating procurement influence with OEM technical campuses.
United States
Logistics and last-mile delivery fleets unbundle exterior panel replacement from full-service lease agreements, creating concentrated purchasing power with national maintenance networks. NHTSA pedestrian protection and offset collision standards demand extensive physical testing of each panel variant. Detroit-area engineering centers coordinate composite bonding process development for domestic EV programs.
China
Domestic EV manufacturers adopt reconfigurable fascias to differentiate shared platforms across sedan, crossover, and utility variants. MIIT fuel consumption and new energy vehicle mandates pressure weight reduction targets exceeding fifteen percent thresholds. Yangtze River Delta manufacturing clusters house thermoplastic composite injection molding lines serving BYD and NIO platform programs.
Japan
Toyota Motor Corporation and Honda Motor Company integrate modular panels into multi-model EV architectures scheduled for late-decade launch. METI carbon neutrality roadmaps prioritize recyclable material pathways for automotive applications. Nagoya-area technical centers develop continuous fiber-reinforced thermoplastic formulations for exterior closure applications.
South Korea
Hyundai Motor Group and Kia Corporation specify swappable body panels across E-GMP platform derivatives to reduce variant tooling expenditure. Ministry of Trade, Industry and Energy green vehicle subsidies incentivize lightweight material adoption in domestic EV production. Seoul Capital Area supplier parks coordinate just-in-time composite panel sequencing for Ulsan and Asan assembly operations.
Automotive Reconfigurable Body Panel Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with material science conglomerates controlling resin supply and compounders competing on formulation performance. The upper tier commands specification influence through captive polymer production and proximity to German OEM engineering hubs. Mid-scale specialists differentiate through application-specific compounding expertise and regional aftermarket channel access. Dominant competitive moves include backward integration into thermoplastic resin production and co-location of technical service centers near Stuttgart and Munich development campuses.
Within the integrated materials tier, SABIC leverages its position as a Saudi Arabian petrochemical conglomerate with captive polymer supply, while Covestro AG exemplifies the polyurethane chemistry heritage archetype anchored in German industrial tradition. BASF SE occupies a position representing the diversified chemical major model with dedicated automotive application infrastructure. These three entities anchor competitive dynamics through differentiated approaches to material formulation, supply security, and technical service proximity.
| Leading Market Players |
|---|
| SABIC |
| Toray Industries |
| Covestro AG |
| Owens Corning |
| Teijin Limited |
| Mitsubishi Chemical Corporation |
| Hexcel Corporation |
| Gurit Holding AG |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Ninety-day thermoplastic resin lead times concentrate procurement leverage with German compounders holding strategic inventory positions near Stuttgart engineering hubs, compressing margin capture for distant suppliers unable to match just-in-line sequencing requirements.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between OEMs and resin suppliers, insulating volume programs from spot market volatility in polypropylene and carbon fiber feedstocks. Price differentiation separates REACH-compliant adhesive formulations from standard bonding chemistries, with certification premiums widening as ECHA authorization windows narrow. Cost compression in injection-molded exterior panels intensifies as Volkswagen Group and BMW AG consolidate specification authority across shared EV platforms. Fleet maintenance networks exhibit highest price sensitivity due to unbundled procurement models, while German OEM captive operations absorb material premiums for engineering influence.
Supply Chain Analysis
Strategic stockpiling of continuous fiber-reinforced thermoplastic pellets characterizes tier-one compounder behavior, contrasting with just-in-time resin delivery preferred by metal stamping incumbents transitioning to composite panel production. Supply concentrates in Germany, China, and South Korea, with Yangtze River Delta injection molding clusters feeding BYD platform programs and Ulsan supplier parks serving Hyundai Motor Group. Raw material flows draw from Saudi Arabian petrochemical complexes for base resins, Japanese carbon fiber facilities for reinforcement, and Belgian adhesive specialists for bonding systems. Single-source vulnerability in aerospace-grade carbon fiber supply creates structural risk for pedestrian-impact-rated exterior panels. Distribution runs through OEM direct procurement for exterior programs and national fleet maintenance networks for aftermarket replacement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating with German OEM platform teams capable of standardizing reconfigurable panel specifications across multiple nameplates, fragmenting supplier negotiation leverage as tier-one compounders compete for captive resin supply positions.
For Market Incumbents: Consolidate backward integration into thermoplastic resin production to defend margin positions against SABIC's petrochemical scale advantages. Secure captive supply of carbon fiber reinforcement from Japanese or South Korean sources before aerospace demand recovery tightens allocation. Prioritize co-location of application engineering centers within 50 kilometers of Stuttgart and Munich technical campuses to maintain specification influence during platform development windows. For New Entrants and Emerging Players: Anchor in North American fleet aftermarket channels where logistics operators have unbundled panel replacement from full-service lease agreements, creating concentrated demand aggregation points absent in fragmented dealer service networks. Target three-dimensional printing integration for low-volume custom programs serving limited-edition European manufacturers unable to justify injection molding tooling investments. Pursue direct procurement relationships with national fleet maintenance networks rather than competing for OEM qualification cycles. For Investors and Strategic Acquirers: Long-term, this sits as a materials-science consolidation play because thermoplastic composite formulation expertise concentrates in aerospace and wind energy sectors, creating acquisition targets with transferable technical capabilities. Watch for inflection when German OEMs accelerate phase-out of non-recyclable sheet molding compounds under EU Green Deal mandates, signaling material substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | SABIC's captive polymer supply secures volume allocation ahead of aerospace demand recovery. |
| Application Center Co-location | BASF SE's proximity to Munich engineering hubs captures specification influence before hardening. |
| Aftermarket Channel Development | Certified repair networks for damage-prone fascias create recurring revenue outside OEM procurement cycles. |
| Continuous Fiber Thermoplastic Scale-Up | Toray Industries' carbon fiber integration addresses pedestrian impact compliance without thermoset weight penalties. |
| REACH-Compliant Adhesive Certification | Covestro AG's polyurethane chemistry heritage accelerates structural bonding validation ahead of ECHA authorization deadlines. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with OEM platform engineers, tier-one supplier procurement leads, thermoplastic composite compounders, and aftermarket fleet maintenance operators; and secondary validation through vehicle production databases, IHS Markit registration data, ECHA REACH authorization filings, and SEC 10-K disclosures from listed material suppliers. Bottom-up triangulation across panel volume forecasts by vehicle program and top-down reconciliation against OEM lightweighting budget allocations anchored market sizing.
Across the analysis window, the forecasting framework modeled demand trajectories by propulsion architecture, panel application location, material category, and regional production cluster. CAGRs were derived from segment-level build-rate projections weighted by content-per-vehicle assumptions for shared EV skateboard platforms. Industry-specific inputs included EU fleet emissions compliance costs, thermoplastic composite processing cycle time improvements, and NHTSA pedestrian protection testing burden estimates.
Decision-makers should treat outputs as directional under assumptions of sustained EV platform sharing adoption and stable ECHA authorization timelines; material deviation in German OEM lightweighting budgets or REACH regulatory acceleration would warrant model refresh. Practitioners should keep alternative scenarios live as recyclate quality consistency and multi-material joining expertise gaps evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Cabin Insulation Material Market
Automotive Interior & Exterior
Automotive Door Impact Bars Market
Automotive Interior & Exterior
Automotive Solar Sunroof Market
Automotive Interior & Exterior
Automotive Window Seals Market
Automotive Interior & Exterior
Cup Holder Market
Automotive Interior & Exterior
Automotive Lighting Market
Automotive Interior & Exterior
Automotive Smart Window Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
Global Automotive Tinted Window Pane Market
Automotive Interior & Exterior
Automotive Display Market
Automotive Interior & Exterior
Automotive Steering Wheel Market
Automotive Interior & Exterior
Automotive Trim Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
Automotive Liftgate Market
Automotive Interior & Exterior
Automotive Door Latch Market
Automotive Interior & Exterior
Car Canopies Market