
 South Korea Automotive Sunroof Market | 2026-2036
South Korea Automotive Sunroof Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Automotive Sunroof Market Analytics
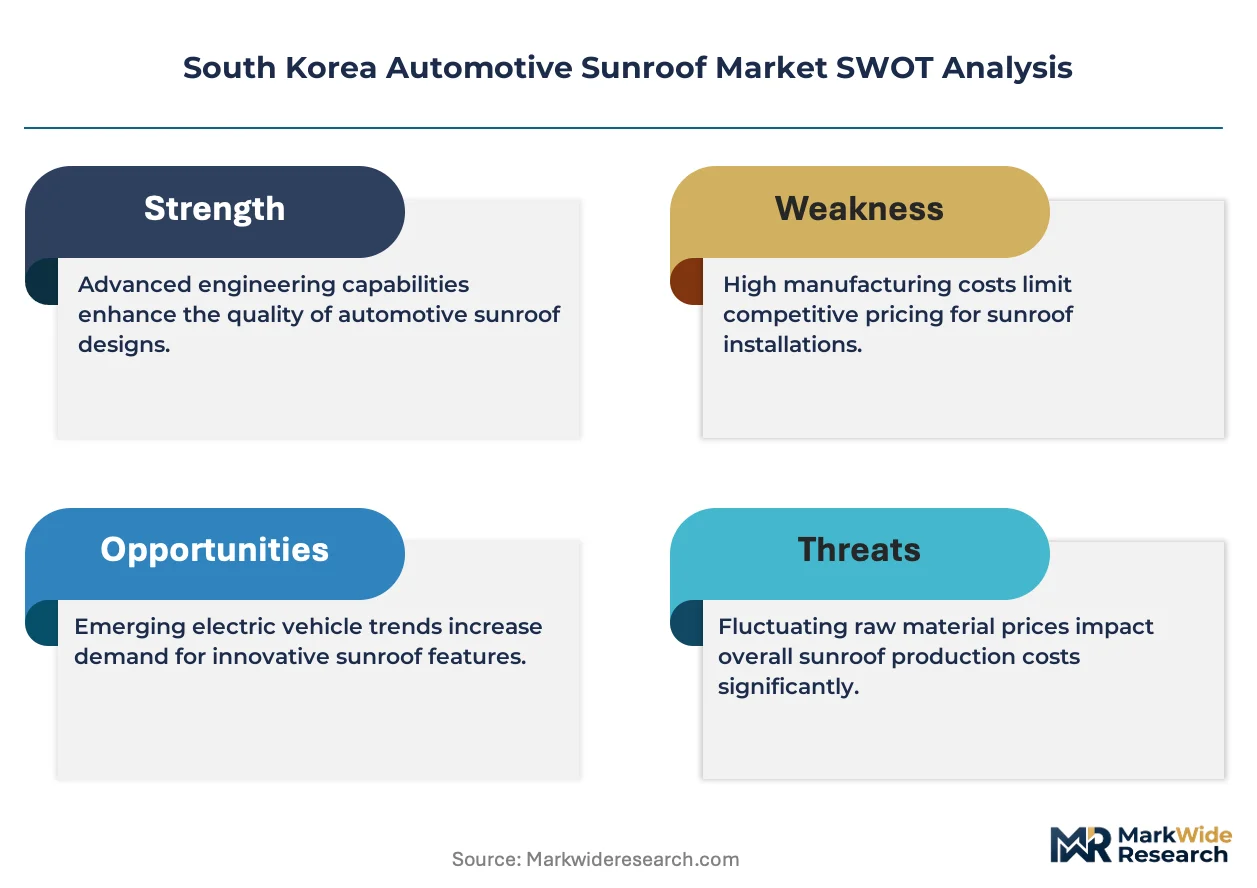
Polycarbonate glazing is realigning sunroof weight economics across South Korean vehicle programs. Webasto Group leverages its European engineering base to supply panoramic modules for domestic OEM platforms. Aisin Seiki anchors its position through integrated rail-and-motor subsystems manufactured at Korean affiliate facilities. Magna International competes on smart glass technology with electrochromic and suspended-particle device layers.
An automotive sunroof is an operable or fixed roof aperture, typically comprising tempered or laminated glass panels bonded to aluminum or reinforced thermoplastic frames, designed to admit light and ventilation while maintaining structural integrity and acoustic isolation. Panoramic configurations now dominate premium vehicle lines, while electric and smart actuation technologies capture expanding margin pools as manual mechanisms retreat to entry segments. Glass material commands the largest volume share, though fabric and composite alternatives gain traction in convertible-style applications where weight reduction and design flexibility matter most.
MFDS material safety guidelines, KATRI homologation protocols, and MOE volatile organic compound emissions standards collectively shape sunroof certification pathways and supplier qualification timelines in South Korea. Stakeholders must monitor evolving KNCAP pedestrian protection rules, as these will dictate glass breakage patterns and ejection mitigation requirements in future designs. The decisive variable ahead lies in whether domestic OEMs integrate sunroof control into centralized vehicle domain architectures or preserve dedicated switchgear electronics.
Market Dynamics
Polycarbonate glazing adoption is compressing traditional glass supply chains while KNCAP pedestrian protection mandates force redesigns of ejection mitigation systems across Hyundai and Kia vehicle programs.
Growth Catalysts
- Lightweighting mandates:The Ministry of Trade, Industry and Energy's fuel efficiency targets are accelerating polycarbonate and high-strength glass integration in sunroof assemblies.
- Seoul metropolitan corridor:Premium SUV and sedan buyers in this dense urban cluster treat panoramic sunroofs as standard comfort features, anchoring domestic OEM specification rates.
- KNCAP safety protocols:Evolving pedestrian protection rules are driving demand for advanced glass breakage patterns and reinforced frame designs.
Market Restraints
- Petrochemical input volatility:Polycarbonate resin prices fluctuate with benzene and propylene feedstock markets, squeezing module supplier margins.
- Glass supplier concentration:Tempered and laminated glass production clusters heavily in Gyeonggi province, creating geographic vulnerability to single-point disruptions.
- Sealing system technical limits:Acoustic isolation and water intrusion resistance degrade faster in polycarbonate panels versus traditional glass, limiting application breadth.
Strategic Opportunities
- Smart glass convergence:Electrochromic and suspended-particle device layers enable dynamic tint control, opening premium pricing tiers in domestic luxury segments.
- Busan-Ulsan corridor:Underpenetrated commercial vehicle and fleet markets in this southeastern industrial zone present volume expansion potential.
- MOE emissions standards:Volatile organic compound regulations favor low-solvent adhesive and sealant technologies, rewarding early compliant suppliers with qualification priority.
Industry Challenges
- Homologation timeline compression:KATRI certification protocols for new glazing materials extend development cycles, delaying platform integration.
- Domain architecture integration:Centralized vehicle electronics systems demand sunroof control software compatibility with broader OEM electrical architectures, raising engineering complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Automotive Sunroof Market |
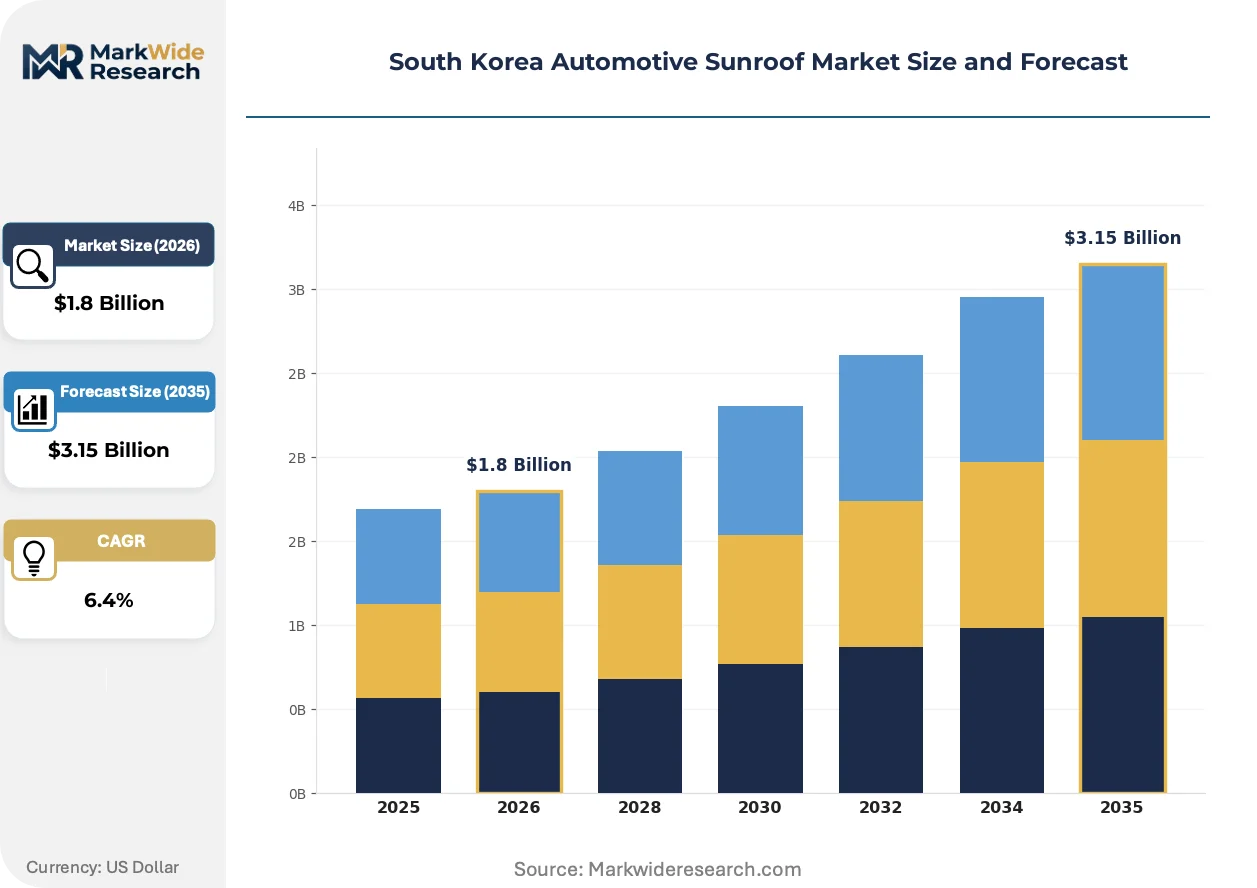
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panoramic, Conventional, Solar, Inbuilt Material: Glass, Fabric, Plastic, Metal Vehicle Type: SUV, Sedan, Hatchback, Coupe Technology: Manual, Electric, Semi-Automatic, Smart |
| Companies Covered | Aisin Seiki Co. Ltd., Johnan America Inc., Webasto Group, Signature Automotive Products, CIE Automotive, Inalfa Roof Systems Group BV, Yachio Industry Co. Ltd., Magna International, Inteva Products LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Automotive Sunroof Market Evolving Landscape
Electric actuation systems and intelligent glazing are displacing manual mechanisms across Korean vehicle platforms, while regulatory pressure on pedestrian safety accelerates material substitution cycles.
Polycarbonate panoramic modules deliver weight reductions exceeding forty percent versus conventional glass assemblies while maintaining optical clarity. Domestic OEMs specify these modules for mid-tier SUV and crossover lines where fuel economy ratings influence consumer purchase decisions. This material transition is consolidating supplier relationships around firms with captive polymer processing and optical coating capabilities, compressing the viable vendor base.
MFDS material safety guidelines now govern biocompatibility and thermal stability testing for all interior-exposed sunroof components, adding qualification layers beyond traditional automotive standards. The industrial consequence extends development timelines by twelve to eighteen months for new material introductions. Premium electric vehicle platforms face the steepest compliance burden, as these vehicles integrate larger fixed-glass roof panels with minimal framing.
Fleet procurement departments at domestic mobility service operators now specify sunroof content as a driver retention feature, shifting specification authority from traditional engineering teams to human resources and operations functions. Tier-one suppliers respond with modular platform designs that accommodate rapid feature bundling across vehicle classes. This pattern concentrates most visibly in Seoul-based corporate fleet operations serving technology sector employees.
South Korea Automotive Sunroof Market Segmentation
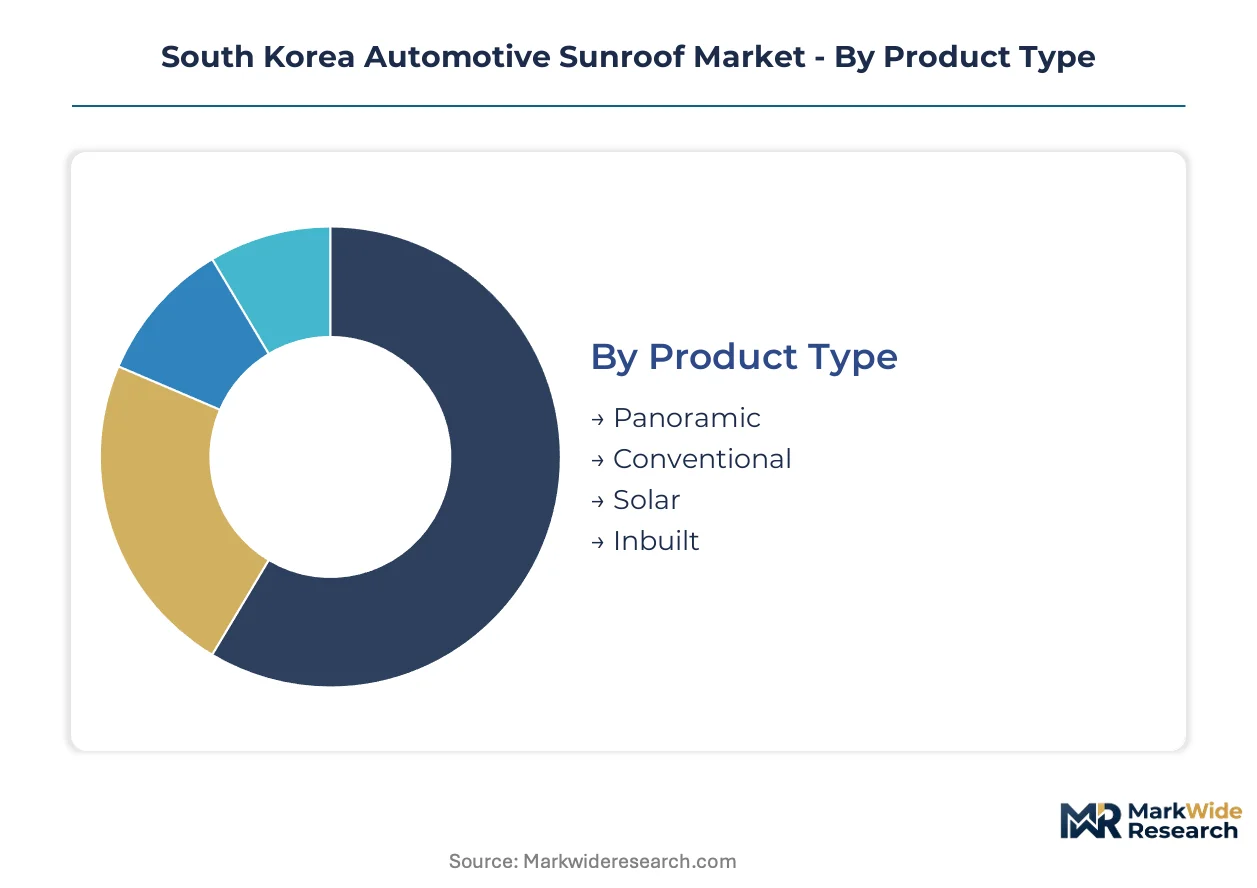
Sunroof specification patterns across South Korean vehicle programs reveal how upgrade cycles and platform refreshes redistribute demand across product categories. Domestic OEMs bundle feature tiers to accelerate trade-up behavior among Seoul metropolitan buyers.
Product Type:
Replacement cycles for complete sunroof modules now align with mid-cycle vehicle facelifts rather than full platform redesigns, compressing supplier development timelines.
- Panoramic:Multi-panel glass assemblies spanning front and rear seating rows, bonded to reinforced aluminum frames with integrated drainage channels. Seoul metropolitan SUV buyers treat this as a non-negotiable comfort specification, driving attachment rates above eighty percent in premium Hyundai and Kia crossovers.
- Conventional:Single-panel pop-up or sliding mechanisms with manual or electric actuation, historically dominant in compact sedans. Demand concentrates in entry-tier fleet vehicles where procurement departments prioritize acquisition cost over amenity content.
- Solar:Photovoltaic-integrated glass panels generating supplemental power for cabin ventilation or battery charging. Kia's EV9 and related electric platforms specify these modules to extend range credentials.
- Inbuilt:Flush-mounted sliding panels with internal roller blind systems, favored for acoustic performance in executive sedans. Hyundai's Genesis line sources these from Webasto for flagship variants.
Volume placements concentrate in Conventional; the faster expansion belongs to Panoramic.
Material:
Cost tier differentiation separates premium vehicle programs from mass-market platforms, with material selection directly determining weight budgets and fuel economy ratings.
- Glass:Tempered or laminated silica-based panels with acoustic interlayers and infrared-reflective coatings, commanding the largest installed base. Gyeonggi province glass clusters supply Hyundai Motor Company and Kia Corporation assembly lines under just-in-sequence arrangements.
- Fabric:Reinforced textile membranes in convertible-style retractable roof systems, specified for weight-critical applications where structural rigidity demands trade off against mass reduction targets.
- Plastic:Polycarbonate resin panels with hardcoat UV protection, delivering forty-plus percent weight savings versus glass equivalents. Ministry of Trade, Industry and Energy fuel efficiency mandates accelerate adoption in mid-tier SUV segments.
- Metal:Aluminum or steel structural frames and reinforcement members, rarely used as primary glazing but essential for crashworthiness in KNCAP-compliant designs.
Glass dominates current volume; polycarbonate variants are climbing the fastest as lightweighting mandates tighten.
Vehicle Type:
Application-specific requirements dictate sunroof sizing, sealing complexity, and actuation torque specifications across Korean OEM portfolios.
- SUV:Raised rooflines accommodate larger panoramic apertures, with domestic OEMs specifying these as standard equipment in compact and mid-size crossovers. Gyeonggi province assembly plants run dedicated sunroof installation cells for Hyundai Tucson and Kia Sportage lines.
- Sedan:Lower roof profiles constrain panel dimensions, favoring inbuilt or conventional mechanisms with reduced stack height. Executive-class Genesis G80 variants compete on acoustic isolation performance.
- Hatchback:Compact footprints and cost-sensitive positioning limit sunroof penetration to premium trim levels, with manual mechanisms retaining share in entry segments.
- Coupe:Styling-driven fixed-glass roof panels with minimal framing, specified for aesthetic differentiation in low-volume performance variants.
Volume concentrates in SUV; sedan applications show steepest expansion trajectory as Genesis brand push intensifies.
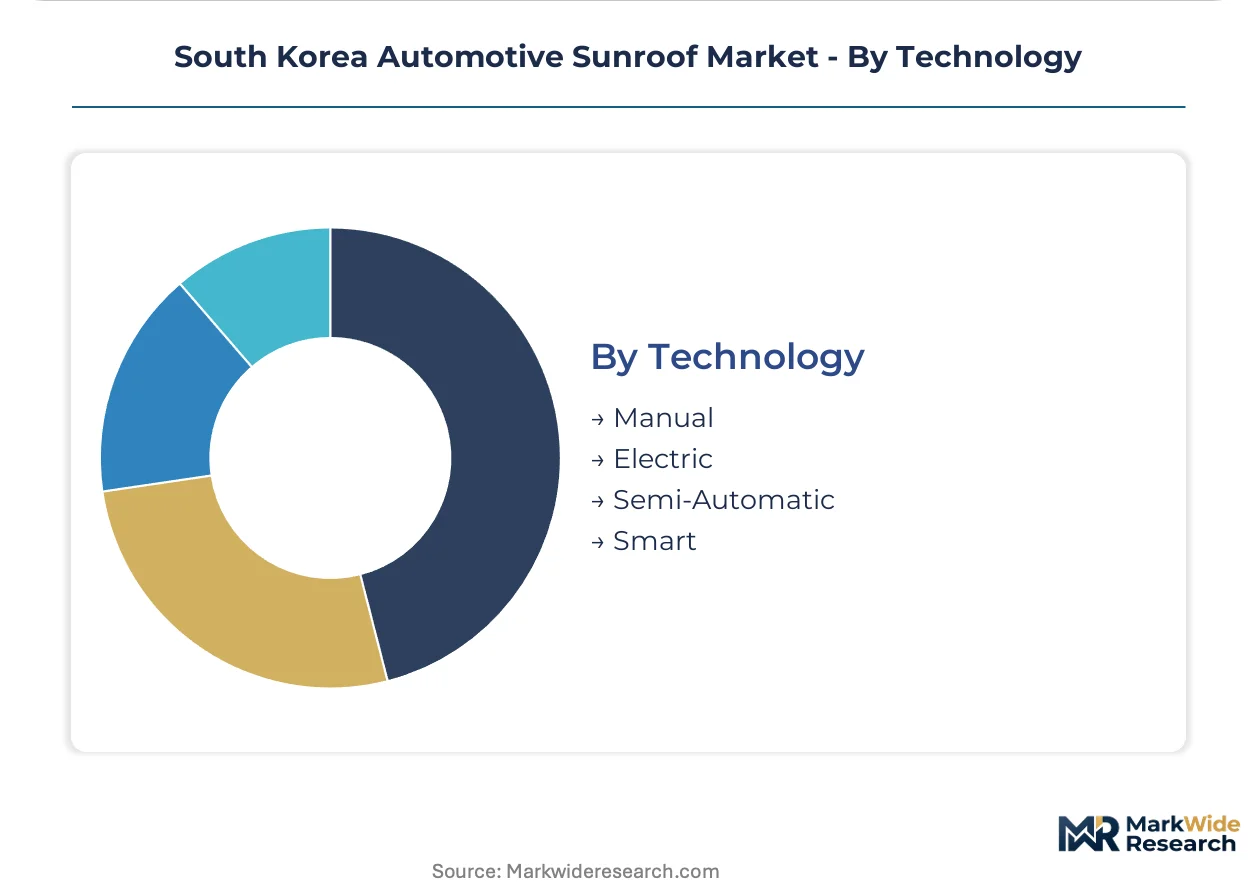
Technology:
Customer type stratification separates fleet procurement from retail purchase behavior, with technology tier serving as a visible differentiator in showroom positioning.
- Manual:Mechanical crank or lever actuation, surviving only in entry hatchback segments where feature deletion supports price-point defense. Kia Morning and related A-segment platforms retain these for price-leader variants.
- Electric:Motor-driven rail systems with one-touch operation and anti-pinch safety logic, now standard across SUV and sedan mainstream trims. Aisin Seiki supplies integrated motor-and-controller subsystems from Korean affiliate facilities.
- Semi-Automatic:Hybrid mechanisms requiring initial manual release before motorized closure, bridging cost and convenience in mid-tier segments.
- Smart:Connected actuation with voice control, rain-sensing automatic closure, and integration with vehicle domain architectures. Hyundai's latest EV platforms specify these for technology leadership positioning against Tesla and Chinese entrants.
Electric mechanisms capture current volume leadership; smart systems are gaining share fastest as domain architecture integration advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul metropolitan corridor buyers concentrate premium SUV and sedan demand, anchoring national specification rates. Gyeonggi province assembly clusters supply Hyundai Motor Company and Kia Corporation under just-in-sequence arrangements. Provincial industrial zones outside the capital region present underpenetrated fleet and commercial vehicle opportunities.
Seoul Capital Area
Premium SUV and sedan buyers in Seoul, Incheon, and Gyeonggi treat panoramic sunroofs as standard comfort features. MFDS material safety guidelines govern biocompatibility testing for all interior-exposed components. Pangyo and Songdo technology corridors drive fleet procurement specifications for driver retention features.
Busan-Ulsan Corridor
Underpenetrated commercial vehicle and fleet markets in this southeastern industrial zone present volume expansion potential. Ministry of Trade, Industry and Energy fuel efficiency targets apply equally to commercial platforms. Ulsan assembly complexes source conventional sunroof mechanisms for price-sensitive fleet variants.
Daegu-Gyeongbuk
Automotive component supplier networks cluster around Daegu for rail-and-motor subsystem manufacturing. KATRI homologation protocols extend development cycles for new glazing material introductions. Gumi industrial parks host affiliate facilities producing integrated actuation mechanisms.
Daejeon-Sejong
Government research institutes in this central administrative region influence KNCAP pedestrian protection rule evolution. Korea Automotive Testing and Research Institute headquarters shapes certification pathways for glass breakage patterns. Sejong administrative city procurement specifications filter into national fleet standards.
Gwangju-Honam
Smaller vehicle assembly operations in this southwestern region concentrate on entry-tier hatchbacks with manual sunroof mechanisms. MOE volatile organic compound emissions standards favor low-solvent adhesive technologies. Naju and surrounding industrial zones supply sealant and framing components under cost-competitive arrangements.
South Korea Automotive Sunroof Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium panoramic module supply consolidating around integrated system providers while conventional mechanism production fragments across component tiers. Korean OEMs maintain dual-source strategies for critical subsystems, preventing single-supplier dependency. Three archetypes dominate: European engineering-led module integrators, Japanese precision-component specialists with Korean affiliate manufacturing, and North American diversified suppliers competing on smart glass technology. Competitive moves center on polycarbonate processing capability acquisition and domain architecture software integration partnerships.
Among the named participants, Webasto Group represents the European engineering-led archetype with panoramic module integration capabilities, while Aisin Seiki Co. Ltd. exemplifies the Japanese precision-component model through its Korean affiliate manufacturing footprint. Magna International occupies a position within the North American diversified supplier tier. These three anchors illustrate how geographic origin and corporate structure map to distinct competitive positioning in Korean OEM supply hierarchies.
| Leading Market Players |
|---|
| Aisin Seiki Co. Ltd. |
| Johnan America Inc. |
| Webasto Group |
| Signature Automotive Products |
| CIE Automotive |
| Inalfa Roof Systems Group BV |
| Yachio Industry Co. Ltd. |
| Magna International |
| Inteva Products LLC |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between KNCAP-compliant panoramic modules and entry-tier conventional mechanisms manifests in both supplier margin structures and procurement routing. Premium assemblies command dedicated engineering support and just-in-sequence delivery from Gyeonggi province clusters, while price-sensitive fleet variants source through consolidated distributors with extended payment terms.
Pricing Analysis
Volume-margin splits separate commodity glass assemblies from polycarbonate panoramic modules with electrochromic layers. Three-tier pricing structure across premium, standard, and economy levels tracks KNCAP certification status and optical coating complexity. Cost compression in conventional mechanisms intensifies because polycarbonate resin feedstock volatility squeezes module supplier margins. Fleet procurement departments exhibit highest price sensitivity, while Genesis and premium SUV buyers prioritize feature content over acquisition cost.
Supply Chain Analysis
Regional distribution centers in Gyeonggi province operate hub-and-spoke patterns feeding Hyundai and Kia assembly plants under four-hour delivery windows. Manufacturing concentrates in South Korea, Germany, and Japan for precision rail-and-motor subsystems. Polycarbonate resin, tempered glass, and aluminum framing extrusions constitute critical input dependencies. Single-source vulnerability runs through benzene and propylene feedstock markets. Distribution runs through captive OEM logistics networks with Tier 1 direct plant delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polycarbonate processing capacity constraints prop pricing power for qualified suppliers, with KATRI homologation timelines creating additional supply bottlenecks. This supply-constrained dynamic favors incumbents with captive polymer capabilities and existing OEM qualification.
For Market Incumbents: Deploy polycarbonate optical coating capacity additions in Gyeonggi province to defend against Chinese entrants with cost-advantaged resin sourcing. Secure dual-source arrangements for benzene feedstock to mitigate petrochemical volatility. Deepen software integration partnerships with Hyundai and Kia domain architecture teams to lock in smart glass specification share. For New Entrants and Emerging Players: MFDS material safety guidelines in South Korea open a window for compliant adhesive and sealant specialists to displace incumbent suppliers with legacy solvent-based formulations. Target Busan-Ulsan commercial vehicle fleets with simplified conventional mechanisms priced below panoramic alternatives. Pursue qualification partnerships with domestic mobility service operators specifying driver retention features. For Investors and Strategic Acquirers: Re-rating potential sits with polycarbonate processing specialists given Ministry of Trade, Industry and Energy lightweighting mandates tightening across the analysis window. Long-term viability centers on suppliers with integrated optical coating and KATRI certification capabilities. Monitor KNCAP pedestrian protection rule evolution as the signal for glass breakage pattern redesign cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Polycarbonate Capacity Expansion | Gyeonggi province investments align with Ministry fuel efficiency targets and OEM lightweighting roadmaps. |
| Smart Glass Technology Licensing | Electrochromic layer partnerships with Magna and Webasto accelerate Genesis brand differentiation. |
| KATRI Certification Fast-Track | Reduced homologation timelines compress development cycles for new glazing material introductions. |
| Domain Architecture Integration | Software partnerships with Hyundai EV platforms secure long-term actuation system specification. |
| Busan-Ulsan Fleet Partnership | Commercial vehicle procurement relationships diversify revenue beyond Seoul metropolitan premium demand. |
Research Methodology
Multi-period observation of vehicle registration patterns, sunroof specification rates by trim level, and polycarbonate adoption curves anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, KATRI certification specialists, and aftermarket distributors. Secondary validation drew from Korea Automobile Manufacturers Association production data, Ministry of Trade, Industry and Energy fuel efficiency disclosures, and MFDS material safety guideline updates. Bottom-up module shipment estimates triangulated against top-down vehicle production forecasts.
Input-output matrices modeled content-per-vehicle trajectories across SUV, sedan, and hatchback segments by propulsion architecture and OEM tier. Segmentation dimensions included product type, material composition, vehicle class, and technology tier. CAGRs were derived from fitted growth curves calibrated to historical specification rate shifts and regulatory mandate timelines. Forecast inputs incorporated KNCAP pedestrian protection rule evolution and polycarbonate resin price elasticity assumptions.
The model assumes a particular technology adoption path; alternative pathways for smart glass domain integration would alter the outlook if centralized vehicle architectures bypass dedicated sunroof control modules. Forecasts reflect documented assumptions regarding homologation timeline compression and feedstock price stabilization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Exhaust Components Aftermarket Market
Automotive Components
Brake Cooling Duct and Hose Market
Automotive Components
Automotive Catalyst Market
Automotive Components
US Automotive Composites Market
Automotive Components
Automotive Sunroof Glass Market
Automotive Components
Automotive Headlight Bulb Market
Automotive Components
Europe Automotive Electric Actuators Market
Automotive Components
Automotive Grade Modules Market
Automotive Components
Automotive Buffers Market
Automotive Components
Automotive Spray Guns Market
Automotive Components
Automotive Gear Shifter Market
Automotive Components
UAE Automotive Composites Market
Automotive Components
China Automotive Actuators Market
Automotive Components
Global Automotive Composite Market
Automotive Components
Automotive Brake Rotor Market
Automotive Components
Automotive Wiper Blades Market