
 Electro Hydraulic Power Steering Market | 2026-2036
Electro Hydraulic Power Steering Market Size, Share, and Industry Trends Forecast 2026-2036
Electro Hydraulic Power Steering Market Foresight
OEM direct procurement channels are reshaping how electro hydraulic power steering systems reach vehicle assembly lines. ZF Friedrichshafen leverages its integrated actuator and pump manufacturing to control supply timelines for European luxury automakers. Robert Bosch GmbH anchors its position through ECU software dominance and steering column calibration expertise. JTEKT Corporation competes on precision valve technology for Asian commercial vehicle platforms.
Electro hydraulic power steering combines an electric motor-driven pump with conventional hydraulic assist circuitry, typically operating at pressures between 70 and 140 bar to reduce parasitic engine load versus belt-driven pumps. Its primary purpose is to deliver variable steering assistance that scales with vehicle speed and load while improving fuel economy in internal combustion and hybrid architectures. Passenger vehicle applications lead volume demand, though electric vehicle integration represents the fastest-growing segment as manufacturers adapt EHPS for range-sensitive platforms. Component-level margin pools concentrate in ECU and actuator assemblies, where firmware calibration and motor control algorithms create differentiation.
NHTSA crashworthiness standards and EPA fuel economy regulations in the United States compel automakers to adopt steering systems that reduce engine drag and enable advanced driver assistance integration. EMA and REACH frameworks in Europe govern material composition and end-of-life recyclability for hydraulic fluids and electronic subassemblies. Stakeholders must monitor how safety regulators reconcile steer-by-wire development timelines with continued EHPS investment in hybrid vehicle programs.
Market Dynamics
The transition from belt-driven hydraulic pumps to on-demand electric motor architectures is compressing parasitic engine losses across internal combustion and hybrid platforms. This shift concentrates procurement power with integrated actuator-ECU suppliers who control firmware calibration and motor control algorithms.
Growth Catalysts
- EU Green Deal tailpipe mandates:Commercial vehicle fleets in Germany and France face binding CO2 reduction targets that favor EHPS over conventional hydraulic systems for fuel economy gains.
- Hybrid powertrain proliferation:Range-sensitive hybrid architectures require steering systems that eliminate constant engine drag while maintaining hydraulic assist feel.
- Brazil and India fleet expansion:Heavy-duty truck operators in São Paulo and Mumbai are retrofitting EHPS to meet stricter emissions norms without sacrificing load-bearing capacity.
Market Restraints
- ECU and actuator supply concentration:Precision motor manufacturing and firmware development cluster in Germany and Japan, creating single-source vulnerability for tier-2 assemblers.
- Copper and rare-earth magnet cost volatility:Permanent magnet materials in electric motor rotors expose margin pools to commodity price swings.
- Steer-by-wire substitution trajectory:Pure electronic steering architectures threaten EHPS relevance in premium battery-electric vehicle programs targeting full redundancy.
Strategic Opportunities
- India commercial vehicle retrofit channel:Independent aftermarket distributors in Delhi and Chennai can capture fleet upgrade cycles as Bharat Stage VI norms tighten.
- EMA material compliance services:End-of-life recyclability mandates for hydraulic fluids and electronic subassemblies create service revenue streams for compliance specialists.
- Sensor fusion convergence:Integration of torque sensors with ADAS lane-keeping modules opens software-defined steering calibration contracts.
Industry Challenges
- Embedded software certification timelines:ISO 26262 functional safety validation for motor control algorithms extends product development cycles by 18-24 months.
- Hydraulic-electric integration complexity:Legacy brake and chassis engineering teams lack mechatronics expertise to optimize pump duty cycles across variable load profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electro Hydraulic Power Steering Market |
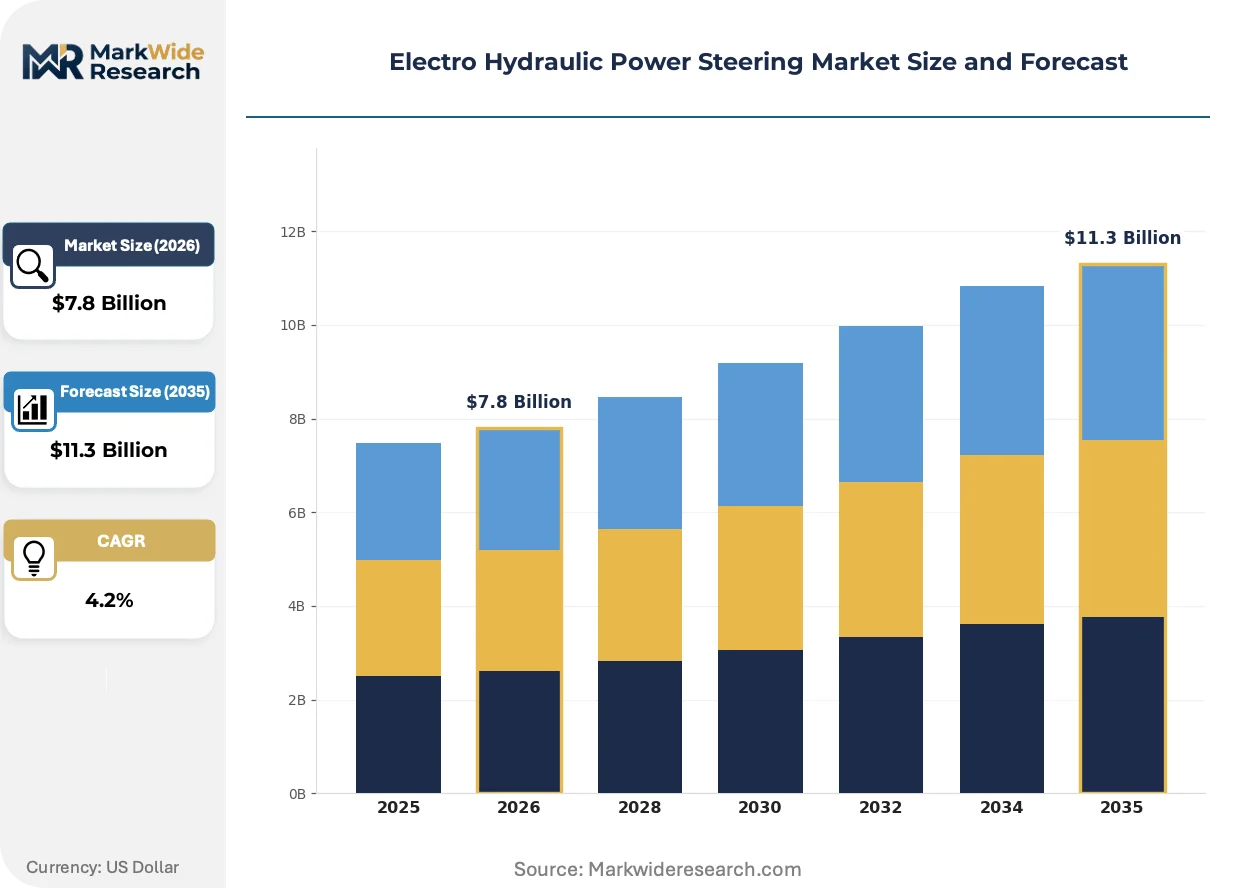
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.3 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Electric Vehicles Component: Actuator, Pump, ECU, Steering Column Vehicle Type: Luxury Cars, Sports Cars, SUVs, Trucks End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | ZF Friedrichshafen, Robert Bosch GmbH, JTEKT Corporation, Hyundai Mobis, Nexteer Automotive, Mando Corporation, NSK Ltd., Mitsubishi Electric, Delphi Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electro Hydraulic Power Steering Market Shifts & Advancements
Intelligent pump control algorithms and modular actuator designs are redefining how steering assistance scales with vehicle dynamics. Three developments dominate current engineering priorities.
Variable displacement pump technology is migrating from fixed-vane architectures to electronically controlled swashplate designs that modulate flow on demand. Asian commercial vehicle platforms in Japan and South Korea are adopting these units fastest to preserve hydraulic feel while cutting idle fuel draw. This migration from mechanical to software-defined flow control is compressing the addressable market for standalone hydraulic component suppliers.
REACH substance restrictions on hydraulic fluid formulations are forcing reformulation of mineral oil bases across European supply chains. ECHA authorization requirements for certain anti-wear additives have triggered supplier qualification programs at German and French OEMs. Commercial vehicle applications face the steepest compliance burden as longer service intervals demand more stable synthetic chemistries.
Fleet procurement teams are consolidating steering system sourcing under powertrain category managers rather than chassis commodity buyers. This organizational shift elevates total cost of ownership metrics over unit price in supplier selection for Brazilian and Indian heavy-duty operators. São Paulo-based logistics conglomerates now specify fuel economy guarantees in steering system service contracts, transferring efficiency risk to component vendors.
Electro Hydraulic Power Steering Market Segmentation
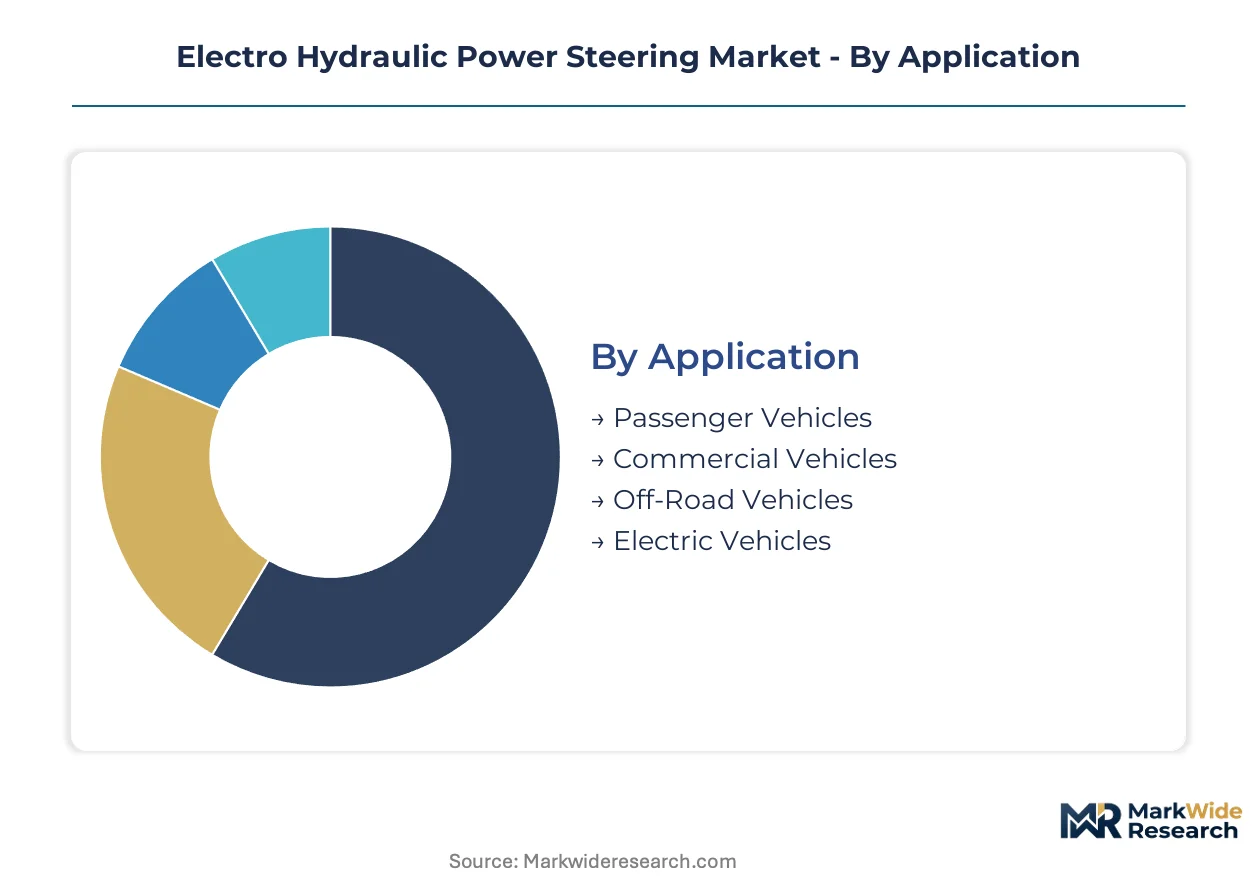
Electro hydraulic power steering systems serve divergent performance requirements across vehicle architectures, from precision-tuned sports cars to load-bearing commercial fleets. Segmentation reveals how component integration intensity, hydraulic pressure specifications, and software calibration complexity vary by application and customer type.
Application:
Application segmentation tracks how steering assistance demands scale with vehicle mass, duty cycle intensity, and powertrain electrification status.
- Passenger Vehicles:Systems operate at 70-90 bar with speed-sensitive variable assist algorithms. German and Japanese OEMs dominate procurement for premium sedan platforms where NVH refinement dictates pump control firmware sophistication.
- Commercial Vehicles:Heavy-duty architectures demand 120-140 bar sustained pressure for laden maneuverability. Fleet operators in São Paulo and Mumbai specify fuel economy guarantees in service contracts, transferring efficiency risk to vendors.
- Off-Road Vehicles:Construction and agricultural equipment requires sealed actuator housings against contamination. Applications concentrate in Midwest US manufacturing clusters and German agricultural machinery production.
- Electric Vehicles:Range-sensitive platforms favor on-demand pump architectures that eliminate parasitic drain during highway cruising. Asian battery-electric programs in South Korea and China are adapting EHPS for hybrid steering redundancy.
Passenger vehicles command the established base. The steepest expansion runs through electric vehicle integration.
Component:
Component-level margin pools concentrate where firmware calibration and precision manufacturing create supplier differentiation.
- Actuator:Brushless DC motor assemblies with rare-earth rotor magnets convert electrical input to hydraulic pressure. Japanese and German suppliers control permanent magnet sourcing and motor winding precision.
- Pump:Swashplate and vane architectures are migrating to electronically controlled displacement for on-demand flow. Asian commercial vehicle platforms adopt these fastest to preserve hydraulic feel while cutting idle fuel draw.
- ECU:Motor control algorithms and torque sensor signal processing require ISO 26262 functional safety certification. Development cycles extend 18-24 months for firmware validation, concentrating procurement with integrated actuator-ECU suppliers.
- Steering Column:Mechanical interface assemblies integrate torque sensors for ADAS lane-keeping convergence. Calibration expertise anchors supplier relationships with European luxury automakers.
ECU and actuator assemblies capture premium margin positions. Pump hardware faces compression as software-defined flow control displaces mechanical architectures.
Vehicle Type:
Vehicle type segmentation reflects how steering feel calibration and hydraulic assist magnitude map to price-positioning and performance expectations.
- Luxury Cars:Multi-mode steering profiles and active noise cancellation demand sophisticated pump control algorithms. German OEMs anchor demand through integrated chassis-electronics procurement strategies.
- Sports Cars:Precision road feedback and variable ratio rack designs prioritize hydraulic assist linearity over fuel economy. Italian and German performance marques specify fixed-displacement pumps with mechanical flow control.
- SUVs:Higher center-of-gravity vehicles require speed-sensitive boost curves to manage lane-change stability. North American and Chinese full-size SUV programs drive volume for mid-pressure actuator configurations.
- Trucks:Load-adaptive pressure compensation and trailer sway damping integrate with chassis control modules. Brazilian heavy-duty operators retrofit EHPS to meet Bharat Stage VI and Proconve P8 emissions norms.
SUVs anchor volume demand across mass-market positioning. Sports cars retain mechanical hydraulic loyalty longest.
End User:
End user segmentation tracks procurement authority migration from chassis commodity buyers to powertrain category managers.
- OEMs:Direct steering system specification for new vehicle programs concentrates with German and Japanese integrated suppliers. ZF Friedrichshafen and Robert Bosch GmbH anchor production clusters for premium applications.
- Aftermarket Providers:Independent distributors in Delhi and Chennai capture fleet upgrade cycles as Indian emissions norms tighten. Retrofit channels require fluid compatibility certification for legacy hydraulic circuits.
- Tier-1 Suppliers:Subassembly integration for vehicle assemblers depends on ECU firmware access and actuator manufacturing scale. Single-source vulnerability persists for precision motor manufacturing clustered in Germany and Japan.
- Vehicle Assemblers:Contract manufacturing operations in Brazil and India source complete steering modules from integrated system suppliers. São Paulo-based logistics conglomerates now consolidate steering procurement under powertrain category management.
OEM direct channels command specification authority. Aftermarket retrofit activity is climbing fastest in emerging market commercial fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal tailpipe mandates and EPA fuel economy standards are accelerating electro hydraulic power steering adoption across automotive manufacturing clusters. National emissions frameworks in Brazil and India are compelling commercial fleet operators toward retrofit channels. Production gravity for precision actuators and ECU assemblies concentrates in Germany, Japan, and South Korea.
Germany
Premium SUV and heavy-duty truck programs anchor demand for high-pressure EHPS architectures. KBA type-approval processes enforce ISO 26262 functional safety certification for steering system firmware. Stuttgart and Friedrichshafen production clusters integrate actuator manufacturing with ECU calibration for European luxury OEMs.
United States
Full-size SUV platforms and commercial truck fleets drive volume for mid-pressure actuator configurations. NHTSA crashworthiness standards compel steer-by-wire readiness while preserving EHPS investment in hybrid architectures. Midwest manufacturing corridors supply sealed actuator housings for off-road agricultural and construction equipment.
Japan
Precision valve technology and brushless DC motor winding expertise concentrate procurement power with integrated suppliers. METI energy efficiency guidelines favor on-demand pump architectures that eliminate parasitic engine losses. Nagoya and Tokyo industrial zones specialize in torque sensor integration for ADAS convergence applications.
Brazil
São Paulo-based logistics conglomerates are retrofitting heavy-duty fleets to meet Proconve P8 emissions norms without sacrificing load-bearing capacity. ANVISA oversees hydraulic fluid formulation standards for tropical operating conditions. Southeastern manufacturing zones supply complete steering modules to vehicle assemblers under powertrain category management.
India
Delhi and Chennai aftermarket distributors capture commercial vehicle upgrade cycles as Bharat Stage VI norms tighten. BIS certification requirements govern ECU electromagnetic compatibility for domestic assembly operations. Maharashtra and Tamil Nadu production hubs serve contract manufacturing operations for regional vehicle assemblers.
Electro Hydraulic Power Steering Market Competitive Landscape
On the supply side, the industry is consolidating around integrated actuator-ECU suppliers who control firmware calibration and motor control algorithms. Tier-1 assemblers face single-source vulnerability for precision permanent magnet manufacturing clustered in Germany and Japan. Three archetypes dominate: German diversified chassis-electronics conglomerates, Japanese precision valve and motor specialists, and Korean scale-driven system integrators. Competitive moves concentrate on backward integration into rare-earth magnet sourcing and strategic partnerships for ADAS sensor fusion convergence.
Within the diversified chassis-electronics tier, ZF Friedrichshafen and Robert Bosch GmbH represent integrated manufacturing archetypes. ZF anchors production clusters for premium applications through captive actuator and pump manufacturing. Robert Bosch occupies a position defined by ECU software dominance and steering column calibration expertise. JTEKT Corporation exemplifies the precision valve specialist archetype, with its geographic origin signaling concentration in Asian commercial vehicle platform supply.
| Leading Market Players |
|---|
| ZF Friedrichshafen |
| Robert Bosch GmbH |
| JTEKT Corporation |
| Hyundai Mobis |
| Nexteer Automotive |
| Mando Corporation |
| NSK Ltd. |
| Mitsubishi Electric |
| Delphi Technologies |
| Others |
Supply & Pricing Matrix
Stuttgart and Friedrichshafen production clusters anchor European EHPS manufacturing capacity, concentrating precision actuator and ECU assembly with integrated suppliers who command premium positioning through firmware exclusivity and motor control algorithm ownership.
Pricing Analysis
Certification level (ISO 26262 ASIL-D grade) creates the primary spread between premium integrated systems and commodity pump hardware. Three-tier pricing structure across premium, standard, and economy levels reflects firmware sophistication, permanent magnet quality, and hydraulic pressure ratings. Cost compression in economy-tier pump hardware is intensifying because Asian suppliers are scaling electronically controlled swashplate architectures. Fleet operators in São Paulo and Mumbai exhibit highest price sensitivity, while German luxury OEMs prioritize NVH refinement over unit cost.
Supply Chain Analysis
Export control regimes restricting rare-earth magnet technology flows between Japan, Germany, and China are fragmenting rotor material sourcing. EHPS manufacturing draws from neodymium-iron-boron magnets, copper windings, and synthetic hydraulic fluids concentrated in German and Japanese supplier networks. Single-source vulnerability persists for precision motor manufacturing clustered in Nagoya and Stuttgart industrial zones. Distribution runs through OEM direct procurement channels with captive Tier-1 subassembly integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive steering system demand follows hybrid powertrain investment cycles, with EHPS positioned for recovery as range-sensitive architectures delay full steer-by-wire adoption.
For Market Incumbents: Build firmware calibration moats through ISO 26262 ASIL-D certification depth and ADAS sensor fusion integration. Secure captive permanent magnet supply through backward integration into rare-earth sourcing partnerships. Defend against steer-by-wire substitution in premium battery-electric programs by anchoring hybrid steering redundancy contracts. For New Entrants and Emerging Players: Indian commercial vehicle aftermarket retrofit channels in Delhi and Chennai represent the most penetrable entry point as Bharat Stage VI enforcement tightens. Brazil's Proconve P8 fleet upgrade cycles offer second-mover access through fluid compatibility certification for legacy hydraulic circuits. Pursue powertrain category manager relationships rather than legacy chassis commodity buyers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated actuator-ECU suppliers with functional safety certification assets and ADAS convergence roadmaps. Long-term viability hinges on hybrid platform persistence through the projection horizon. Acquisition targets should demonstrate torque sensor integration capabilities and steering column calibration expertise. Monitor steer-by-wire development timelines at premium German and Korean OEMs as inflection indicators for EHPS relevance compression.| Strategic Initiative | Industry Significance |
|---|---|
| Rare-Earth Magnet Supply Agreement | Captive neodymium sourcing from Chinese and Australian producers insulates margin pools from commodity volatility. |
| ISO 26262 ASIL-D Certification Investment | Eighteen-month firmware validation cycles concentrate procurement with certified German and Japanese suppliers. |
| ADAS Sensor Fusion Partnership | Torque sensor integration with lane-keeping modules opens software-defined steering calibration contracts. |
| India Aftermarket Distribution Expansion | Delhi and Chennai retrofit channels capture commercial fleet upgrade cycles as emissions norms tighten. |
| Hydraulic Fluid Formulation Compliance | REACH-aligned synthetic chemistries secure European OEM qualification for extended service interval applications. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and fleet operations managers, then refined against vehicle production databases, IHS Markit registration data, customs trade records, and SEC filings from listed automotive suppliers. Bottom-up unit economics triangulated with top-down market sizing across vehicle class, propulsion architecture, and regional production clusters.
Demand-supply balance dynamics across the analysis window anchored volume projections, with segmentation modeling spanning passenger vehicle, commercial vehicle, off-road, and electric vehicle applications alongside component-level actuator, pump, ECU, and steering column disaggregation. CAGRs derived from fitted growth curves applied to production forecasts, with hybrid powertrain penetration rates and emissions regulation enforcement timelines as key automotive-specific inputs.
Practitioners should monitor steer-by-wire development commitments at premium OEMs and rare-earth magnet export control expansions for early signals of structural demand shifts. Forecasts reflect documented assumptions on hybrid platform persistence and regulatory enforcement intensity. Material shifts in battery-electric vehicle share trajectories or REACH substance restriction scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Japan Ball Bearing Market
Automotive Parts
Nigeria Automotive Engine Oils Market
Automotive Parts
ASEAN Automotive Bearings Market
Automotive Parts
France Automotive Pneumatic Actuators Market
Automotive Parts
High Speed Rolling Bearings Market
Automotive Parts
Needle Roller Bearings Market
Automotive Parts
Automotive Fuel Rail Market
Automotive Parts
Mechanical Performance Tuning Components Market
Automotive Parts
Automotive Parking Heater Market
Automotive Parts
Automotive Evaporators and Blowers Market
Automotive Parts
Bumper Beam Market
Automotive Parts
Plastic Fuel Tanks Market
Automotive Parts
Steering Wheel Armature Market
Automotive Parts
North America Automotive Foams Market
Automotive Parts
Exhaust Hanger Material Market