
 Automotive Wiping Systems Market | 2026-2036
Automotive Wiping Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wiping Systems Market Outlook
Electromechanical engineering talent scarcity is reorganizing supplier priorities across the automotive wiping systems value chain. Robert Bosch GmbH leverages its embedded sensor integration capabilities to anchor premium smart wiper contracts with German OEMs. Valeo Group sustains competitive positioning through manufacturing scale across multiple European production sites. Mitsuba Corp specializes in compact motor architectures that dominate Japanese kei-car and compact EV platforms.
Automotive wiping systems encompass blade assemblies, linkage mechanisms, drive motors, and washer fluid delivery equipment engineered to maintain optical clarity across vehicle glass surfaces, with modern units integrating rain sensors, heated elements, and aerodynamic profiles rated for operational speeds exceeding 200 km/h. Windshield wipers occupy the largest value share due to universal fitment mandates and replacement cycle density, while smart systems represent the fastest-expanding technology category as OEMs bundle ADAS-linked precipitation detection and predictive activation algorithms. Aftermarket providers compete on channel breadth and private-label availability, whereas OEMs and Tier-1 Suppliers concentrate on long-term program capture through design-in relationships.
NHTSA's Federal Motor Vehicle Safety Standard 104 governs windshield wiping and washing equipment in the United States, mandating minimum swept area and operational speed thresholds that shape product development baselines. ECE R43 and the EU's General Safety Regulation collectively enforce visibility maintenance standards across European type approvals, while China's GB standards and MIIT administrative rules define domestic market access requirements for wiper system suppliers. Stakeholders must monitor divergence between regional electromagnetic compatibility standards for smart wiper motors and the pace at which OEMs consolidate multi-function sensor modules into single-supplier architectures.
Market Dynamics
Electrification of vehicle platforms is fragmenting wiper system architectures as OEMs abandon belt-driven engine accessories for dedicated electric motor units with embedded control electronics.
Growth Catalysts
- EU General Safety Regulation:Mandates automatic activation of visibility systems under precipitation, compelling OEM integration of rain-sensing modules.
- Chinese NEV production concentration:Domestic manufacturers in Shanghai and Shenzhen are specifying intelligent wiper assemblies with LIN-bus connectivity as standard fitment.
- Silicon carbide MOSFETs:Power semiconductor advances enable compact, thermally efficient wiper motor designs that reduce assembly mass by one-third.
Market Restraints
- Rare earth magnet supply concentration:Neodymium procurement dependency on Chinese processing facilities exposes motor suppliers to price volatility and export restriction risk.
- ECE R43 testing burden:European type-approval requirements for swept area verification and durability cycling extend development timelines by four to six months.
- Camera-based visibility systems:Tesla and select OEMs are piloting hydrophobic coating and compressed air alternatives that eliminate mechanical wiping on rear glass.
Strategic Opportunities
- India PLI scheme for auto components:Tier-1 suppliers establishing local motor and linkage production can capture OEM localization mandates for Maruti Suzuki and Tata Motors programs.
- Sensor fusion convergence:Integration of precipitation detection with ADAS camera cleaning nozzles creates bundled module opportunities exceeding standalone wiper values.
- Direct-to-fleet digital channels:Commercial vehicle operators in Germany are procuring predictive maintenance-enabled wiper systems through OEM-agnostic platform subscriptions.
Industry Challenges
- Embedded software competency gaps:Traditional mechanical suppliers struggle to recruit firmware engineers capable of developing ASIL-compliant motor control algorithms.
- Multi-standard electromagnetic compatibility:Divergent CISPR 25 interpretations across US, European, and Chinese test houses force redundant validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wiping Systems Market |
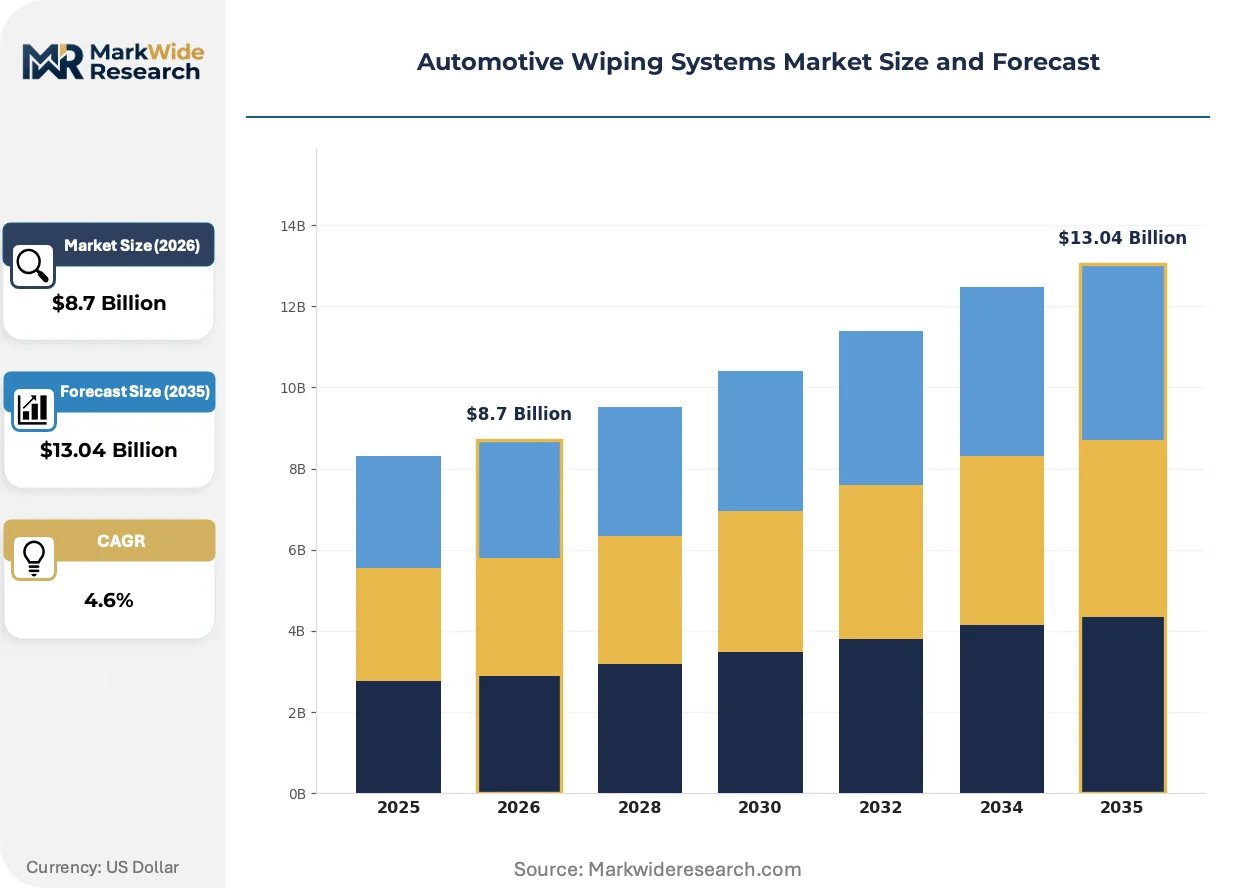
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Windshield Wipers, Rear Window Wipers, Headlight Wipers, Washer Pumps End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Electronic, Mechanical, Hybrid, Smart Systems Distribution Channel: Direct Sales, Online Retail, Specialty Stores, Wholesalers |
| Companies Covered | TRICO, Zhejiang Shenghuabo Electric Corporation, Robert Bosch GmbH, Minda Group, Lucas TVS Limited, Denso Corporation, Mitsuba Corp, Korea Wiper Blade Co Ltd, Valeo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wiping Systems Market Strategic Shifts
Active aerodynamics and predictive algorithms are displacing static wiper designs as vehicle speeds and sensor dependency intensify performance requirements.
Decomposition of conventional wiper motor architectures is accelerating as integrated smart actuators combine brushless DC motors with position feedback encoders and local processing units. Premium German and Korean OEMs are specifying these modules for 2027 platform launches. This convergence is decomposing the historical separation between body electronics and chassis suppliers.
REACH restrictions on perfluorinated compounds are forcing reformulation of water-repellent blade coatings across European supply chains. Compounders in Belgium and the Netherlands are commercializing silicone-based alternatives with equivalent durability profiles. Wiper blade aftermarket providers serving Nordic markets face compressed product refresh cycles to maintain regulatory compliance.
Fleet operators are consolidating wiper system procurement under total-cost-of-ownership frameworks that weight energy consumption and replacement intervals against unit price. Leasing companies in the Netherlands are embedding these specifications into vehicle acquisition criteria. This behavioral shift favors suppliers with validated lifecycle databases over low-bid aftermarket competitors.
Automotive Wiping Systems Market Segmentation
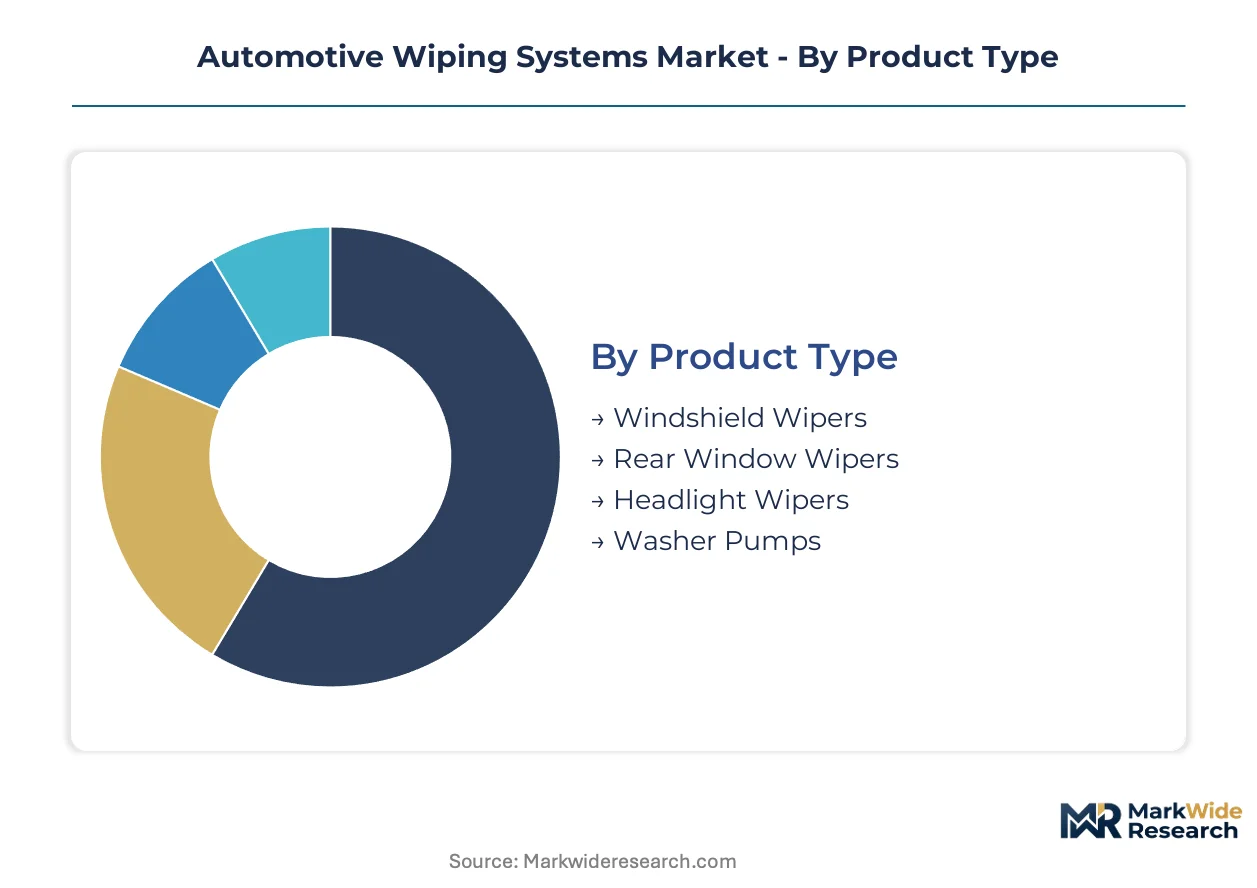
Segmentation in automotive wiping systems reveals how electrification and sensor integration are fragmenting traditional mechanical categories. Suppliers must now align product architectures with divergent OEM integration strategies and aftermarket replacement cycles.
Product Type:
Headlight wipers face the most acute substitution pressure as LED headlamp designs with integrated cleaning jets displace mechanical sweep units across European and Japanese platforms.
- Windshield Wipers:Universal fitment mandates drive baseline demand across all vehicle classes, with aerodynamic blade profiles now standard for speeds exceeding 200 km/h. OEMs in Germany and South Korea are bundling heated elements and rain-sensing modules as standard equipment on premium electric platforms.
- Rear Window Wipers:Compact motor architectures dominate hatchback and SUV applications, though camera-based visibility systems and hydrophobic coatings are eliminating mechanical units on select Tesla and luxury German EV rear glass configurations.
- Headlight Wipers:Regulatory requirements in Nordic markets sustain niche demand, but LED thermal management advances are reducing swept-area mandates.
- Washer Pumps:Integration with ADAS camera cleaning nozzles is expanding unit functionality beyond traditional windshield delivery.
Windshield wipers retain volume leadership; smart-integrated variants hold the steepest expansion curve.
End User:
Cost tier stratification separates design-in relationships from transactional procurement, with firmware-capable suppliers commanding premium positioning.
- OEMs:Long-term program capture requires ASIL-compliant motor control algorithms and LIN-bus connectivity for electric vehicle platforms. German OEMs are consolidating multi-function sensor modules into single-supplier architectures.
- Tier-1 Suppliers:Manufacturing scale across European production sites sustains competitive positioning for integrated smart actuator contracts.
- Aftermarket Providers:Channel breadth and private-label availability determine competitiveness, with Nordic markets facing compressed refresh cycles due to REACH restrictions on perfluorinated blade coatings.
- Vehicle Assemblers:Localization mandates in India and China are shifting procurement toward domestic motor and linkage production.
OEMs dominate value capture; Tier-1 suppliers are climbing fastest through sensor fusion convergence.
Technology:
Application intensity varies sharply between basic transportation and sensor-dependent autonomous platforms.
- Smart Systems:Embedded brushless DC motors with position feedback encoders and local processing units combine precipitation detection with predictive activation algorithms. Premium German and Korean OEMs are specifying these modules for upcoming platform launches.
- Electronic:Silicon carbide MOSFETs enable compact, thermally efficient motor designs that reduce assembly mass by one-third.
- Hybrid:Transitional architectures bridge mechanical linkage systems with electronic control units.
- Mechanical:Belt-driven engine accessories are being abandoned as OEMs migrate to dedicated electric motor units with embedded control electronics.
Mechanical systems retain installed-base dominance; smart systems are expanding most quickly through ADAS-linked program wins.
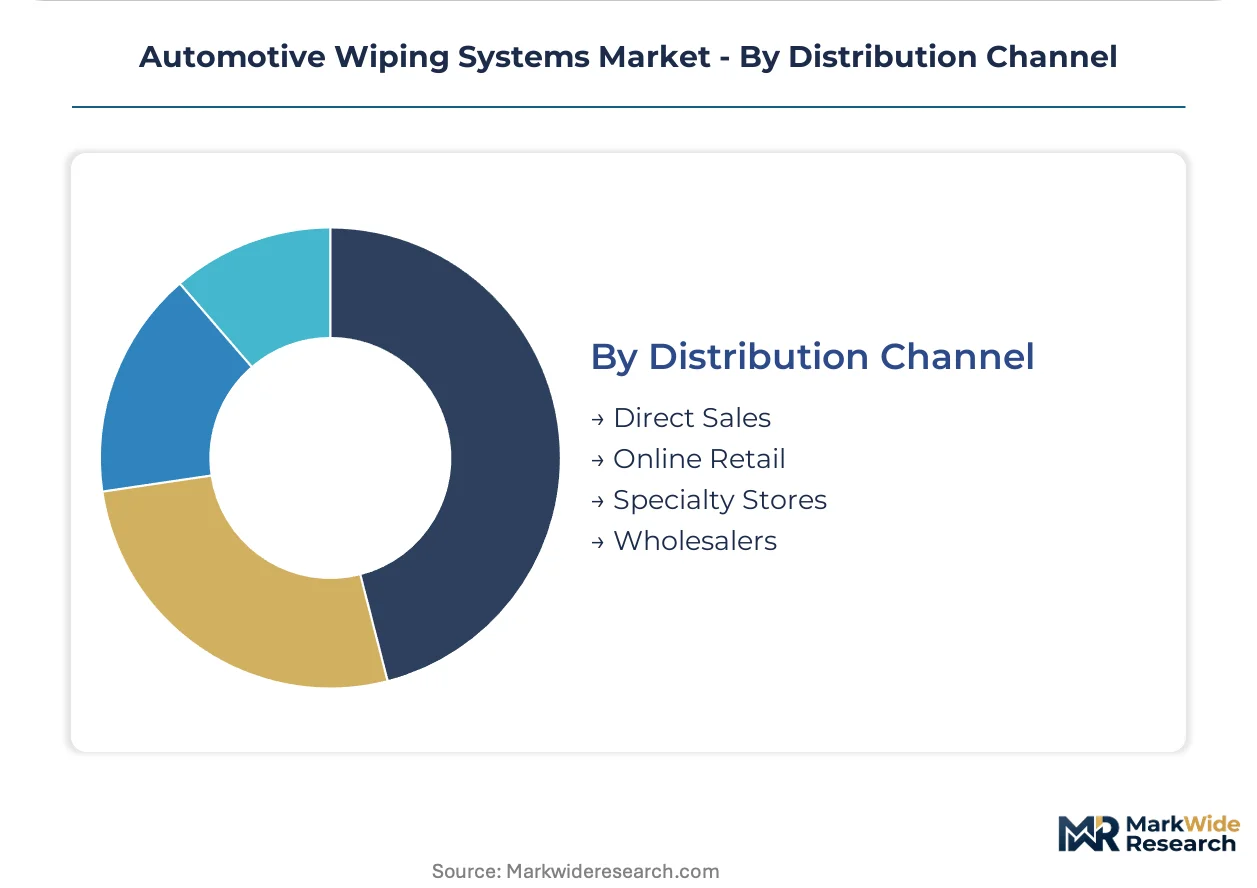
Distribution Channel:
Customer-type bifurcation separates fleet procurement frameworks from individual consumer purchasing patterns.
- Direct Sales:Fleet operators in the Netherlands and Germany are consolidating procurement under total-cost-of-ownership frameworks that weight energy consumption and replacement intervals against unit price.
- Wholesalers:Channel breadth supports aftermarket volume across fragmented regional markets.
- Specialty Stores:Technical consultation requirements sustain positioning for complex integrated systems.
- Online Retail:Private-label blade availability and standardized fitment databases are expanding price-transparent procurement.
Direct sales retain contract value leadership; online retail is gaining share fastest through platform subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA's Federal Motor Vehicle Safety Standard 104 governs baseline visibility equipment requirements in the United States, establishing swept-area and operational-speed thresholds that shape product development across North American programs. Regional regulatory divergence is intensifying as electrification accelerates platform-specific wiper architectures.
United States
Fleet operators in Michigan and Ohio are consolidating procurement under total-cost-of-ownership frameworks that weight energy consumption against replacement intervals. NHTSA's FMVSS 104 mandates minimum swept areas that constrain design flexibility for compact electric platforms. Detroit-area Tier-1 suppliers are scaling brushless DC motor production for 2026-2027 OEM program launches.
Germany
Premium OEMs in Stuttgart and Munich are specifying integrated smart actuator modules with LIN-bus connectivity for upcoming electric vehicle platforms. ECE R43 type-approval requirements extend development timelines by four to six months through swept-area verification protocols. Baden-Württemberg manufacturing clusters are concentrating electromechanical engineering talent for embedded sensor fusion programs.
China
Domestic NEV manufacturers in Shanghai and Shenzhen have standardized intelligent wiper assemblies with predictive activation algorithms. MIIT administrative rules and GB standards define market access requirements for motor suppliers. Yangtze River Delta production hubs are scaling silicon carbide MOSFET integration for compact, thermally efficient designs.
Japan
Kei-car and compact EV platforms rely on specialized compact motor architectures from established domestic suppliers. METI industrial policy supports electrification component localization. Nagoya-area manufacturing sites maintain cost-competitive production for high-volume hatchback applications.
India
Localization mandates from Maruti Suzuki and Tata Motors are shifting procurement toward domestic motor and linkage production. The PLI scheme for auto components incentivizes Tier-1 suppliers establishing captive manufacturing in Gujarat and Tamil Nadu. Chennai and Pune industrial corridors are attracting wiper system assembly investments from multinational component makers.
Automotive Wiping Systems Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in automotive wiping systems supply. The market structure concentrates around electromechanical engineering capability and embedded software competency rather than pure manufacturing scale. Three archetypes dominate: sensor-integrated smart system developers, compact motor specialists for volume platforms, and regional manufacturing-scale providers. Competitive moves center on firmware talent acquisition and multi-function sensor module consolidation into single-supplier architectures.
Within the integrated technology tier, Robert Bosch GmbH and Valeo Group exemplify full-capability positioning across embedded control electronics and OEM design-in relationships. Denso Corporation occupies a position bridging Japanese domestic kei-car supply with broader Asian platform expansion. Mitsuba Corp represents the compact motor specialization archetype. Korea Wiper Blade Co Ltd anchors regional manufacturing scale for Korean and adjacent export markets. Zhejiang Shenghuabo Electric Corporation and Minda Group exemplify emerging-market localization strategies. TRICO and Lucas TVS Limited occupy aftermarket-focused positions with channel breadth across replacement cycles.
| Leading Market Players |
|---|
| TRICO |
| Zhejiang Shenghuabo Electric Corporation |
| Robert Bosch GmbH |
| Minda Group |
| Lucas TVS Limited |
| Denso Corporation |
| Mitsuba Corp |
| Korea Wiper Blade Co Ltd |
| Valeo Group |
| Others |
Value Chain & Pricing Dynamics
Sixteen-week motor assembly lead times concentrate pricing power among integrated suppliers capable of buffering rare earth magnet inventory against Chinese export volatility. OEMs in Germany and South Korea absorb premium positioning for LIN-bus-enabled smart actuators, while aftermarket providers compete on channel breadth and private-label blade availability.
Pricing Analysis
Price spreads between German OEM supply contracts and Indian aftermarket blades reflect a three-tier pricing structure across premium, standard, and economy levels. Certification tier differentiation separates ASIL-compliant motor control algorithms from basic mechanical units, with volume scale and firmware capability commanding substantial premiums. Pricing pressure stems from silicon carbide MOSFET cost compression enabling lighter, more efficient motor designs. Fleet operators in the Netherlands exhibit lowest price sensitivity under total-cost-of-ownership frameworks, while independent aftermarket channels in India face acute margin compression.
Supply Chain Analysis
Strategic stockpiling of neodymium magnets and copper windings supersedes just-in-time preferences as motor suppliers hedge against Chinese processing facility disruptions. Manufacturing concentrates in Germany, China, and Japan, with Yangtze River Delta and Baden-Württemberg clusters anchoring smart actuator production. The supply chain draws from rare earth magnet processing, silicon carbide semiconductor fabrication, and specialized rubber compound formulation. Single-source vulnerability in neodymium procurement exposes tier-2 motor suppliers to price volatility. Distribution runs through OEM direct channels for platform programs and fragmented wholesale networks for aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive wiping systems are crossing a platform-economics inflection as LIN-bus standardization and sensor fusion convergence create winner-take-most dynamics around embedded software competency.
For Market Incumbents: Secure firmware engineering talent through targeted acquisition of brushless DC motor control specialists before ASIL-compliant algorithm scarcity intensifies. Consolidate multi-function sensor module architectures into single-supplier relationships with German and Korean OEMs to defend against camera-based visibility system substitution. Prioritize backward integration into silicon carbide MOSFET sourcing partnerships to compress motor assembly mass and sustain premium positioning. For New Entrants and Emerging Players: ECE R43 fast-track certification for swept-area verification protocols offers entry pathway into European aftermarket channels underserved by firmware-capable suppliers. Target India's PLI scheme localization mandates for Maruti Suzuki and Tata Motors programs, where domestic motor production requirements outstrip established supplier capacity. Pursue direct-to-fleet digital platform subscriptions in Germany as OEM-agnostic procurement consolidates under predictive maintenance frameworks. For Investors and Strategic Acquirers: Long-term, this sits as a component-consolidation play because OEMs are collapsing body electronics and chassis supplier boundaries into unified smart actuator architectures. Acquisition focus should center on mid-cap specialists with validated LIN-bus connectivity and embedded rain-sensing algorithms. Watch for inflection when camera-based visibility systems eliminate mechanical wiping on rear glass configurations across multiple OEM platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Module Integration | Bundles precipitation detection with ADAS camera cleaning nozzles for premium OEM contracts. |
| Silicon Carbide MOSFET Adoption | Enables compact motor designs reducing assembly mass by one-third for electric platforms. |
| India PLI Scheme Localization | Captures Maruti Suzuki and Tata Motors procurement mandates through domestic production. |
| Fleet Platform Subscription Model | Consolidates commercial vehicle procurement under predictive maintenance-enabled contracts. |
| REACH-Compliant Coating Reformulation | Maintains Nordic market access through silicone-based water-repellent blade alternatives. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations managers; and secondary validation against vehicle production databases, IHS Markit registration data, NHTSA FMVSS 104 regulatory filings, and ECE R43 type-approval records. Bottom-up motor assembly volume estimates triangulated against top-down OEM platform content-per-vehicle assumptions.
Across the analysis window, forecasts segmented by vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from installed-base replacement cycles, platform launch schedules, and electrification penetration curves. Industry-specific inputs incorporated silicon carbide MOSFET adoption trajectories and rare earth magnet price volatility indices.
Decision-makers should treat outputs as directional under assumptions of sustained NEV production growth and stable Chinese rare earth processing capacity; material deviation would warrant model refresh. Revision becomes warranted when camera-based visibility system adoption crosses mass-market OEM thresholds or when REACH restrictions expand beyond perfluorinated compounds to silicone-based alternatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Accelerator Pedal Module Market
Automotive Parts
Spain Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Magnesium Alloy Market
Automotive Parts
Suspension Bump Stopper Market
Automotive Parts
US Automotive Airfilters Market
Automotive Parts
Vehicle Jump Starter Market
Automotive Parts
Oil Filter Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market
Automotive Parts
Automotive Engine Cooling Fan Market
Automotive Parts
Automatic Gearbox Valves Market
Automotive Parts
Global Automotive Hydraulics System Market
Automotive Parts
Automotive Engine Oil Coolers Market
Automotive Parts
North America Automotive Foams Market
Automotive Parts
Automotive Brake Caliper Market
Automotive Parts
India Electric Hydraulic Power Steering Market
Automotive Parts
Friction Pads Market