
 Dual Fuel Engine Market | 2026-2036
Dual Fuel Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Dual Fuel Engine Market Insights
Buyer concentration in marine shipping is rebalancing as container lines consolidate fleet procurement while independent power producers fragment across decentralized energy projects. Wartsila Corp. anchors its position through deep manufacturing scale in large-bore marine engines. MAN Energy Solutions SE specializes in two-stroke low-pressure gas injection architectures for bulk carriers. Cummins Inc. competes aggressively in the mid-speed auxiliary engine segment where aftermarket service contracts generate recurring revenue streams.
A dual fuel engine combusts two distinct fuels within a single combustion cycle, typically diesel pilot ignition with natural gas main charge, operating at compression ratios between 12:1 and 17:1 depending on fuel blend. Diesel-gas configurations dominate heavy-duty trucking and stationary power applications where infrastructure density supports LNG or CNG availability. Gas-diesel architectures lead marine propulsion due to IMO Tier III NOx compliance without exhaust aftertreatment. Power generation end users increasingly specify biogas-compatible variants as landfill and anaerobic digestion projects multiply across agricultural clusters.
The International Maritime Organization enforces Carbon Intensity Indicator metrics that directly penalize vessels lacking dual fuel capability on major trade lanes. EPA Tier 4 Final and EU Stage V emissions frameworks for non-road engines push forklift and generator OEMs toward gas-diesel hybrids to avoid selective catalytic reduction complexity. Stakeholders must track evolving LNG bunkering infrastructure buildout rates against methanol and ammonia pathway investments when committing to engine platform selections for decade-long asset lifecycles.
Market Dynamics
The International Maritime Organization's Carbon Intensity Indicator framework is compressing vessel upgrade cycles and forcing shipowners toward dual fuel architectures before regulatory penalties activate on major trade lanes.
Growth Catalysts
- IMO 2023 Carbon Intensity Regulations:The Carbon Intensity Indicator penalizes conventional diesel-only vessels, creating immediate retrofit and newbuild demand for LNG-compatible propulsion systems across container and bulk carrier fleets.
- Biogas Infrastructure Expansion:Agricultural clusters in Denmark and the Netherlands are deploying anaerobic digestion facilities that feed pipeline-quality biomethane into stationary power engines.
- Low-Pressure Gas Injection:Two-stroke marine architectures achieve IMO Tier III NOx compliance without exhaust aftertreatment, eliminating capital and operational burdens of selective catalytic reduction systems.
Market Restraints
- LNG Bunkering Infrastructure Gaps:Port coverage remains concentrated in Rotterdam, Singapore, and Shanghai, leaving trans-Pacific and Africa-Asia routes with fuel availability risk.
- High-Pressure Fuel System Costs:Cryogenic pumps, vaporizers, and double-wall piping add 35-50% capital premium over conventional diesel installations.
- Pilot Fuel Dependency:Diesel-gas configurations require continuous pilot injection, exposing operators to residual fuel price volatility and sulfur regulation compliance costs.
Strategic Opportunities
- Methanol Pathway Preparation:Engine OEMs are designing combustion chambers and fuel systems with methanol compatibility, positioning platforms for IMO 2050 zero-carbon fuel transitions.
- Power-to-X Integration:Electrolyzer-coupled engine installations in Germany and Denmark convert surplus renewable electricity into synthetic methane for grid-balancing applications.
- Aftermarket Service Unbundling:Independent technical managers in Greece and Cyprus are acquiring cylinder head reconditioning and fuel valve overhaul capabilities, fragmenting OEM service monopolies.
Industry Challenges
- Cryogenic Fuel System Certification:Flag administrations and classification societies lack harmonized standards for LNG tank pressure relief and gas detection, extending type-approval timelines.
- Cross-Fuel Technician Training:Marine engineers require simultaneous competency in high-pressure diesel injection and cryogenic gas handling, constraining crew availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual Fuel Engine Market |
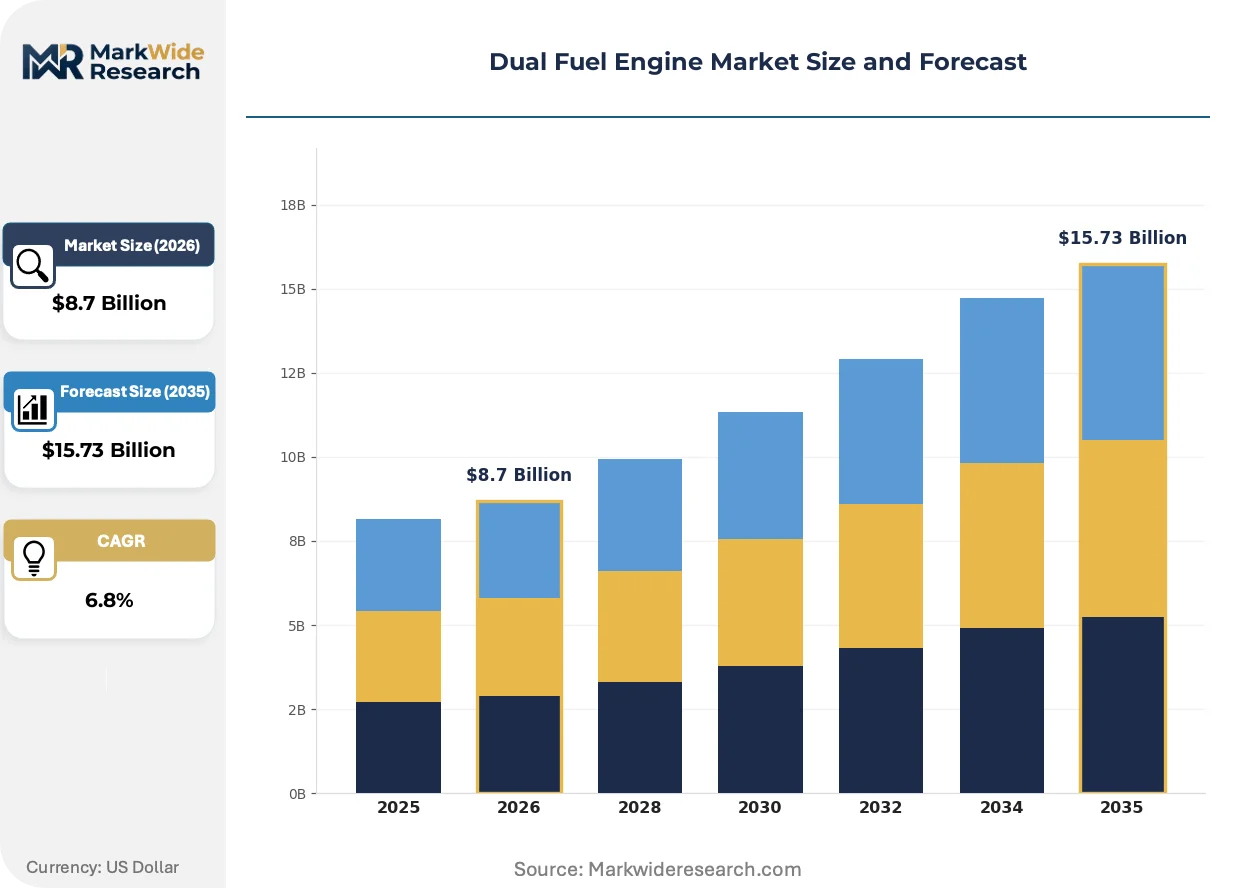
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Engine Type: Diesel-Gas, Gasoline-Diesel, Gas-Diesel, Dual-Fuel Hybrid Fuel Source: CNG, LNG, Biogas, Propane End User: Transportation, Industrial, Marine, Power Generation Application: Heavy-Duty Trucks, Buses, Generators, Forklifts |
| Companies Covered | Cummins Inc., Wartsila Corp., MAN Energy Solutions SE, Caterpillar Inc., Anglo Belgian Corp., Westport Fuel Systems Inc., Yanmar Holdings Co. Ltd., Kubota Corp., Heinzmann GmbH and Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual Fuel Engine Market Trends and Innovations
Combustion control systems and fuel-flexible hardware are converging to enable real-time fuel switching without load interruption, compressing the operational gap between single-fuel reliability and dual-fuel economics.
Adaptive ignition timing algorithms are automating cylinder-by-cylinder combustion optimization across varying natural gas methane numbers. Container lines operating Asia-Europe strings deploy these systems to maintain thermal efficiency when bunkering LNG with inconsistent calorific content. The technology is automating fuel quality compensation that previously required manual engineer intervention.
The European Union's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in LNG fuel system cooling loops, forcing engine OEMs to specify CO2 or ammonia-based alternatives. Shipyards in South Korea and Japan are redesigning engine room layouts to accommodate larger cascade refrigeration units. Bulk carrier newbuilds with 2026 delivery dates are most affected, with specification changes cascading through piping and ventilation contracts.
Charterers now embed fuel-flexibility clauses in time charter agreements, penalizing vessel unavailability during LNG bunkering windows. This contractual evolution concentrates fleet procurement decisions among technical departments rather than traditional commercial teams. The shift is most visible in Singapore and London chartering markets, where major commodity traders specify dual fuel capability as a baseline qualification for long-term fixtures.
Dual Fuel Engine Market Segmentation
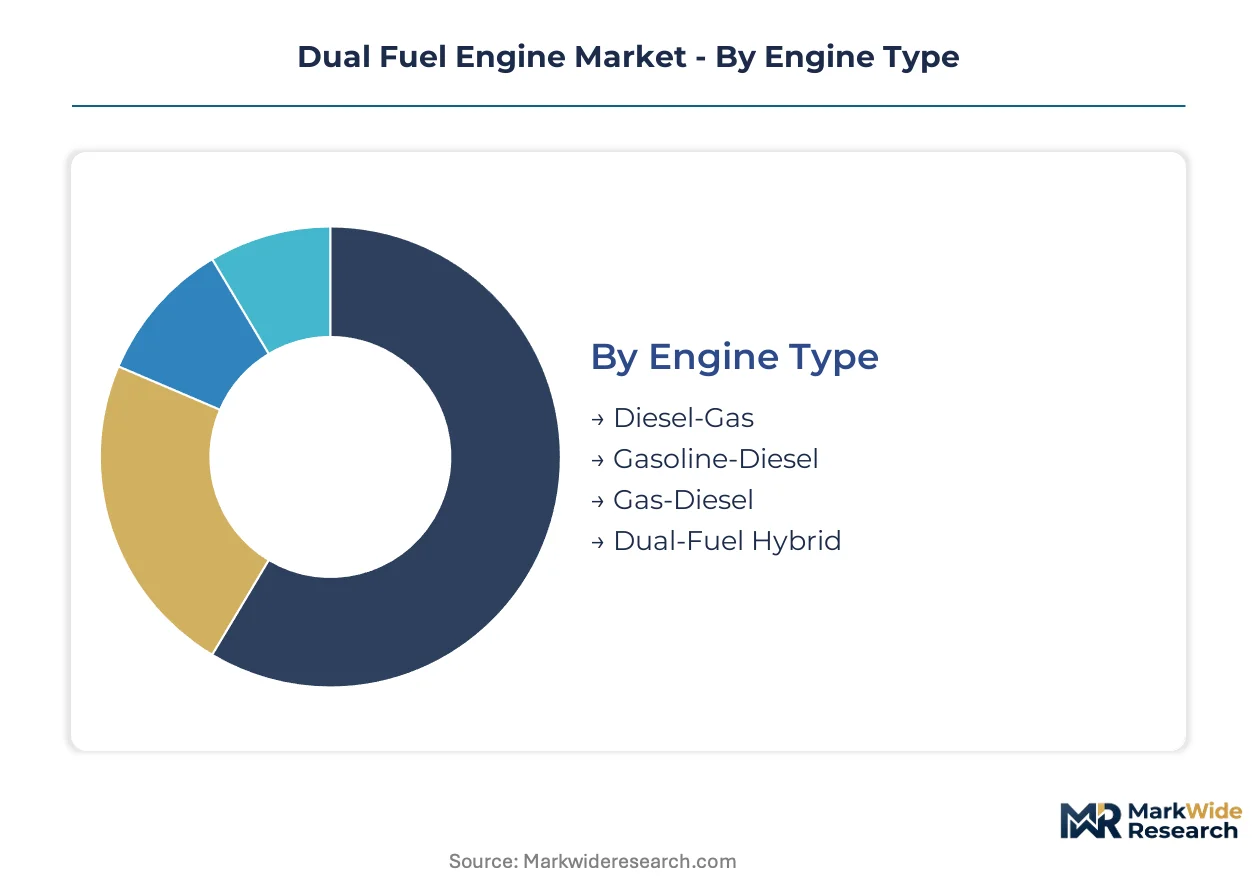
Dual fuel engine procurement hinges on fuel infrastructure availability and regulatory compliance timelines. Buyers weigh capital premiums against bunker fuel savings and carbon intensity penalties. Segmentation reveals where technology configurations align with specific operational economics and geographic fuel access.
Engine Type:
Buyers select architectures based on compression ratio requirements and pilot fuel dependency tolerance.
- Diesel-Gas:Compression ignition with natural gas as primary fuel and diesel pilot injection dominates heavy-duty trucking and stationary power. Fleets in Germany and California specify this configuration where CNG infrastructure density supports daily refueling cycles without range compromise.
- Gas-Diesel:Spark-ignited gas combustion with diesel backup achieves IMO Tier III NOx compliance without selective catalytic reduction. Norwegian and Japanese shipyards specify this architecture for bulk carriers operating on Rotterdam-Singapore LNG bunkering corridors.
- Gasoline-Diesel:Port fuel injection of gasoline with diesel compression ignition suits light commercial vehicles in markets with gasoline distribution dominance.
- Dual-Fuel Hybrid:Integrated electric motor and battery storage with dual-fuel combustion enables port maneuvering on electric power and open-water transit on gas-diesel.
Diesel-gas leads on scale; gas-diesel leads on momentum.
Fuel Source:
Supply infrastructure maturity determines viable fuel pathways for specific route structures and facility locations.
- LNG:Cryogenic storage at minus 162 degrees Celsius enables energy-dense marine bunkering. Singapore, Rotterdam, and Shanghai port authorities have built dedicated LNG loading infrastructure that supports container line fleet conversions on Asia-Europe strings.
- CNG:Compressed natural gas at 250 bar serves urban bus fleets and regional trucking where pipeline compression stations anchor refueling networks. Indian and Pakistani operators have deployed CNG-diesel hybrids for intercity coach services leveraging domestic gas production.
- Biogas:Upgraded biomethane from anaerobic digestion feeds stationary power engines in Danish and Dutch agricultural clusters.
- Propane:Liquefied petroleum gas infrastructure supports forklift and light commercial applications in North American distribution centers.
LNG leads on scale; biogas climbs the fastest.
End User:
Operational intensity and asset utilization rates drive technology specification and service contract structures.
- Marine:IMO Carbon Intensity Indicator compliance mandates dual fuel capability for newbuild container and bulk carrier fleets. Charterers in London and Singapore markets now embed fuel-flexibility clauses that penalize diesel-only vessel availability.
- Transportation:Long-haul trucking operators in Germany and California calculate total cost of ownership around CNG price spreads against diesel and carbon credit monetization.
- Power Generation:Grid-balancing and landfill gas projects in Denmark specify biogas-compatible variants with rapid start-stop capability.
- Industrial:Manufacturing facilities with captive natural gas supply deploy dual-fuel backup generators to avoid EPA Tier 4 Final aftertreatment complexity.
Marine leads on scale; power generation gains share fastest.
Application:
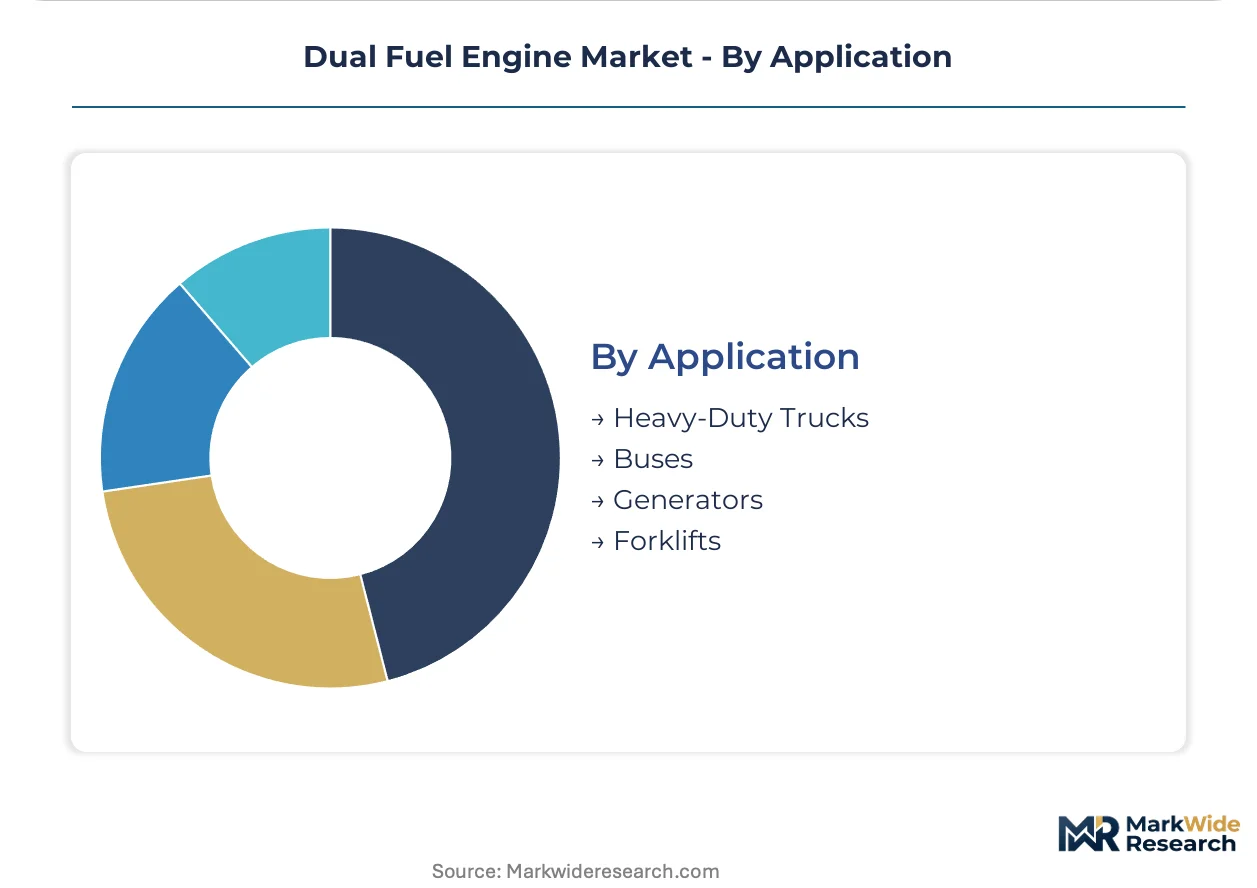
Duty cycle characteristics and load profile predictability determine engine sizing and fuel system configuration.
- Heavy-Duty Trucks:Long-haul tractors with 500-plus horsepower requirements specify high-pressure direct injection gas systems. North American fleet operators have standardized on 12-liter diesel-gas platforms for regional linehaul where weight tolerance accommodates CNG tankage.
- Generators:Stationary power applications prioritize fuel flexibility over power density. Data center operators in Germany specify biogas-ready gensets with 10-second start capability for grid emergency response.
- Buses:Urban transit with predictable depot refueling favors CNG-diesel configurations. Municipal fleets in India have deployed 9-liter platforms for 18-hour daily utilization with overnight compression filling.
- Forklifts:Warehouse material handling with indoor air quality constraints specifies propane or CNG variants to avoid diesel particulate filtration.
Heavy-duty trucks lead on scale; generators lead on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway's shipyards command premium positioning for LNG-compatible propulsion, while South Korean builders scale production for container line fleet renewals. Both markets illustrate how regulatory enforcement density shapes manufacturing geography.
Norway
Oslo-based shipowners retrofit bulk carriers ahead of IMO Carbon Intensity Indicator penalties. The Norwegian Maritime Authority accelerates type-approval timelines for cryogenic fuel systems. Bergen and Stavanger clusters host technical managers specializing in dual-fuel engine commissioning and crew certification programs.
South Korea
DSME and HHI shipyards integrate MAN Energy Solutions architectures into 24,000 TEU container newbuilds. The Korean Register of Shipping publishes harmonized gas-fuelled ship construction standards. Ulsan and Geoje manufacturing corridors concentrate cryogenic tank fabrication and high-pressure pump assembly capacity.
Japan
Imabari Shipbuilding and JMU specify low-pressure gas injection systems for coal carriers serving Australia-Japan routes. METI subsidizes LNG bunkering infrastructure at Tokyo Bay and Osaka Bay ports. Nagasaki and Kure retain specialized foundry capacity for large-bore two-stroke engine block casting.
Germany
MAN Energy Solutions anchors two-stroke development in Augsburg while Caterpillar's large engine center operates from Rostock. The Federal Maritime and Hydrographic Agency enforces EU Stage V compliance for inland waterway conversions. Hamburg and Bremen ports expand LNG truck-to-ship bunkering for feeder vessels.
United States
Cummins manufactures mid-speed auxiliary engines at its Seymour, Indiana facility for domestic tug and offshore supply vessel operators. EPA Tier 4 Final regulations push harbor craft toward gas-diesel configurations. Houston Ship Channel pilots test LNG bunkering protocols for chemical tankers serving Gulf Coast petrochemical complexes.
Dual Fuel Engine Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across engine architecture segments. Tier-one manufacturers with marine heritage anchor large-bore propulsion, while mid-speed specialists capture auxiliary and power generation niches. Strategic archetypes include integrated system providers, component specialists, and aftermarket service unbundlers. Capacity expansion and technology licensing dominate competitive moves as OEMs prepare methanol-ready platforms.
Among diversified industrial conglomerates, Caterpillar Inc. and Cummins Inc. exemplify scale-driven archetypes spanning on-highway, off-highway, and stationary power applications. Wärtsilä Corp. occupies a position as a focused marine and energy specialist with deep manufacturing integration. MAN Energy Solutions SE represents the two-stroke marine pure-play segment where low-pressure gas injection architectures dominate bulk carrier specifications.
| Leading Market Players |
|---|
| Cummins Inc. |
| Wartsila Corp. |
| MAN Energy Solutions SE |
| Caterpillar Inc. |
| Anglo Belgian Corp. |
| Westport Fuel Systems Inc. |
| Yanmar Holdings Co. Ltd. |
| Kubota Corp. |
| Heinzmann GmbH and Co. KG |
| Others |
Pricing and Supply Chain Analysis
Container line technical departments concentrate procurement authority for LNG-compatible propulsion systems, compressing vendor negotiation leverage and enforcing three-tier pricing structures across premium, standard, and economy certification levels.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for large-bore marine engines as DSME and HHI shipyards scale dual-fuel newbuild programs. Price differentiation hinges on IMO Tier III certification grade and after-sales service bundling intensity. Cost compression in mid-speed auxiliary segments is intensifying because Cummins and Anglo Belgian Corp. compete for tug and offshore supply vessel contracts. Independent power producers exhibit highest price sensitivity; Norwegian shipowners with carbon intensity penalty exposure show lowest.
Supply Chain Analysis
Single-source vulnerability sits with cryogenic pump and vaporizer suppliers concentrated in Germany, Japan, and South Korea. Engine block casting draws from specialized foundries in Nagasaki, Kure, and Ulsan. High-pressure fuel injection components rest on precision machining capacity in Augsburg and Rostock. Tariff exposure on stainless steel alloys and nickel-based superalloys threatens cost stability. Distribution runs through shipyard-integrated procurement channels with OEM direct-to-yard contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dual fuel engine procurement has shifted to a late-cycle quality story as charterers embed fuel-flexibility clauses demanding methanol-ready combustion architectures.
For Market Incumbents: Hedge methanol pathway uncertainty by designing combustion chambers with swappable fuel injection hardware. MAN Energy Solutions and Wärtsilä should accelerate backward integration into cryogenic tank fabrication to capture margin pools currently held by South Korean metalworkers. Defend against independent technical managers in Greece fragmenting aftermarket service monopolies through cylinder head reconditioning acquisitions. For New Entrants and Emerging Players: Digital retrofit platforms offer the lowest-friction entry vector for auxiliary engine monitoring and predictive maintenance software. White-space concentrates in biogas-compatible stationary power for Danish and Dutch agricultural clusters, plus CNG-diesel hybrid systems for Indian intercity coach operators. Pursue channel partnerships with MAN Energy Solutions-authorized service depots lacking in-house gas handling competency. For Investors and Strategic Acquirers: Marine engine OEMs with methanol-ready platforms are the most active acquirer category in this space. Five-to-ten year viability favors pure-play dual-fuel specialists over diversified conglomerates with stranded diesel-only R&D. Target acquisition archetype: independent technical managers in Cyprus and Singapore with certified cryogenic handling capabilities. Watch LNG bunkering infrastructure buildout rates at Rotterdam, Singapore, and Shanghai as inflection signal for newbuild contract velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Methanol-Ready Platform Development | Positions OEMs for IMO 2050 zero-carbon fuel transitions without engine replacement. |
| Cryogenic Fuel System Backward Integration | Captures margin pools from specialized tank fabricators in Ulsan and Geoje corridors. |
| Biogas Compatibility Certification | Unlocks Danish and Dutch agricultural cluster demand for anaerobic digestion power projects. |
| Aftermarket Service Unbundling | Greek and Cypriot technical managers fragment OEM monopolies through cylinder head reconditioning. |
| Power-to-X Electrolyzer Coupling | German and Danish installations convert surplus renewable electricity into synthetic methane for grid balancing. |
Research Methodology
Multiple input streams — shipowner technical department interviews, engine OEM product strategy disclosures, and port authority bunkering infrastructure databases — were reconciled against classification society type-approval records. Primary discussions with marine superintendents, shipyard procurement managers, and cryogenic fuel system engineers were validated through Lloyd's Register and Korean Register of Shipping filings, IMO Marine Environment Protection Committee minutes, and container line fleet renewal announcements. Bottom-up vessel orderbook aggregation was cross-checked with top-down market sizing from trade flow analysis.
Historical order patterns were cross-referenced against expert panel assessments of regulatory enforcement timelines across the projection horizon. Segmentation modeling incorporated engine architecture, fuel source pathway, end-use vertical, and regional bunkering infrastructure maturity. CAGRs were derived from fitted growth curves calibrated to known fleet replacement cycles and carbon intensity penalty phase-in schedules. Forecast inputs included LNG price spread volatility assumptions and methanol pathway investment announcements from MAN Energy Solutions and Wärtsilä.
The model assumes a particular technology adoption path; alternative pathways for ammonia combustion would alter the outlook if fuel supply infrastructure outpaces methanol buildout. Forecasts reflect assumptions about IMO regulatory enforcement consistency and LNG bunker availability expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Automotive Hydrogen Fuel Cell Market
Alternative Fuel Vehicles
Automotive Gas Cylinder Market
Alternative Fuel Vehicles
Automotive Flex Fuel Engine Market
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market
Alternative Fuel Vehicles
Fuel Cell Vehicle (FCV) Market
Alternative Fuel Vehicles
Global Ethanol-Based Vehicle Market
Alternative Fuel Vehicles
Automotive Low Emission Vehicle Market
Alternative Fuel Vehicles
Hydrogen Fuel Vehicle Market
Alternative Fuel Vehicles
Brazil Alternative Fuel Vehicles Market
Alternative Fuel Vehicles
Alternative Fuel Vehicle (AFV) Market
Alternative Fuel Vehicles
UK New Energy Vehicle TIC Services Market
Alternative Fuel Vehicles
Alternative Fuel and Hybrid Vehicle Market
Alternative Fuel Vehicles
India CNG Market
Alternative Fuel Vehicles
Global Low Emission Vehicle Market
Alternative Fuel Vehicles
India CNG Vehicles Market
Alternative Fuel Vehicles
CNG Tanks Market