
 Automotive Canister Market | 2026-2036
Automotive Canister Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Canister Market Outlook
High-density polyethylene is shifting toward reinforced polyamide in evaporative canister housings as thermal and chemical resistance requirements intensify. MAHLE leverages its captive resin compounding operations to secure material cost advantages across European vehicle programs. Robert Bosch GmbH sustains engineering intensity through integrated electronics-to-mechanical module development for hybrid powertrains. Continental AG anchors North American supply through dedicated extrusion and blow-molding capacity in Mexico.
An automotive canister is a sealed containment vessel, typically injection-molded from engineered thermoplastics or stamped from coated steel, designed to adsorb and store fuel vapors from the tank and carburetor vent lines through activated carbon media before controlled purge to the engine intake. Its primary purpose is preventing hydrocarbon emissions to atmosphere during vehicle soak, diurnal temperature cycling, and refueling events. Charcoal canisters retain the dominant volume position due to decades of validated carbon-bed designs and lowest unit cost, though composite material variants are gaining fastest as OEMs target mass reduction for electric range extension and fuel economy compliance. Passenger vehicles represent the deepest application segment with multi-canister architectures proliferating in plug-in hybrid architectures requiring separate tank and charge-port vapor management.
EPA emission certification under 40 CFR Part 86 and California Air Resources Board LEV III protocols mandate near-zero evaporative emissions, compelling canister volume expansion and activated carbon grade upgrades. Euro 6d standards administered by ECHA and national type-approval authorities in Germany and France impose equivalent diurnal and refueling vapor recovery thresholds, harmonizing product development roadmaps. China MIIT fuel consumption and evaporative emission rules under GB standards are converging with European test cycles, adding regulatory complexity for suppliers serving multiple qualification regimes. Stakeholders must monitor pending EPA reconsideration of supplemental federal test procedures and evaluate carbon sourcing strategies against emerging supply chain due diligence rules.
Market Dynamics
Stringent evaporative emission thresholds under EPA Tier 3 and Euro 6d are forcing canister volume expansion and carbon-grade upgrades across vehicle programs, compressing supplier qualification timelines and reshaping material procurement strategies toward reinforced composites.
Growth Catalysts
- EPA Tier 3 diurnal emission limits:Near-zero hydrocarbon mandates in the United States are expanding canister sizing requirements and driving activated carbon media upgrades across passenger vehicle platforms.
- Composite material substitution:Lightweight polyamide and glass-fiber reinforced housings are displacing high-density polyethylene as OEMs prioritize mass reduction for fuel economy and electric range compliance.
- Plug-in hybrid proliferation:Separate tank and charge-port vapor management architectures are doubling canister counts per vehicle in electrified powertrain configurations.
Market Restraints
- Activated carbon supply concentration:Specialized carbon sourcing for automotive-grade adsorption media concentrates among limited chemical processors, exposing qualification pipelines to raw material bottlenecks.
- Multi-regulatory certification burden:Divergent test protocols across EPA 40 CFR Part 86, CARB LEV III, and China MIIT GB standards force redundant validation cycles that extend program timelines.
- Steel canister cost floor:Stamped and coated metal housings retain unit cost advantages in economy vehicle segments, constraining composite penetration in price-sensitive procurement categories.
Strategic Opportunities
- India BIS emission convergence:Pending alignment of domestic evaporative standards with European test cycles creates first-mover positioning for suppliers establishing local compounding and molding capacity.
- Integrated electronics-mechanical modules:Convergence of purge valve actuation, pressure sensing, and canister housing into single supplier-managed subsystems enables tier-one margin capture.
- Refueling vapor recovery mandates:Unleaded gasoline ORVR requirements in additional state jurisdictions beyond California expand addressable hardware volumes for onboard canister systems.
Industry Challenges
- Resin formulation expertise scarcity:Automotive-grade polyamide compounding for thermal and hydrocarbon resistance requires polymer chemistry capabilities concentrated among limited material suppliers.
- Cross-platform carbon bed validation:Activated carbon lot-to-lot consistency testing across temperature and humidity extremes extends development cycles for global vehicle programs.
- Legacy steel-to-composite tooling transition:Existing stamping and coating equipment for metal canister production cannot be repurposed for thermoplastic injection molding, forcing parallel capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Canister Market |
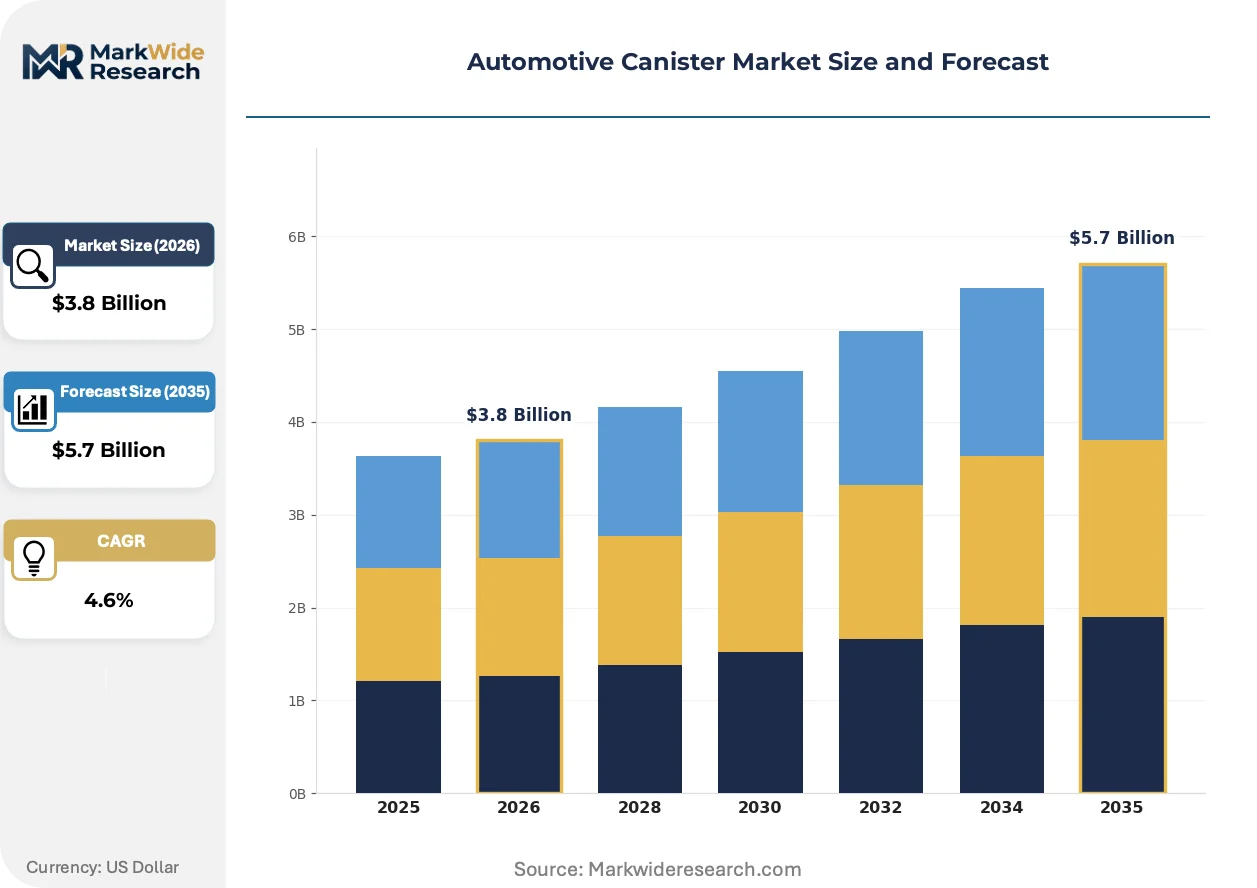
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Vapor Canisters, Charcoal Canisters, Fuel System Canisters, Evaporative Canisters End User: Original Equipment Manufacturers, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Material: Plastic, Metal, Composite, Aluminum Application: Passenger Vehicles, Commercial Vehicles, Light-Duty Vehicles, Heavy-Duty Vehicles |
| Companies Covered | MAHLE, Stant Corporation, Robert Bosch GmbH, UFI Filters S.p.A., HELLA GmbH & Co. KGaA, Continental AG, Aptiv PLC, Marelli, MANN+HUMMEL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Canister Market Strategic Shifts
Material science advances and embedded sensor integration are redefining canister architecture from passive containment vessels to intelligent emission control modules. Suppliers are racing to capture value from this functional expansion.
Reinforced polyamide compounds with glass-fiber loading are integrating into primary canister housings to meet elevated underhood thermal requirements. Hybrid and electric vehicle OEMs in Germany and Japan are specifying these materials for charge-port vapor management modules. This integration is compressing the traditional metal-to-plastic substitution timeline by collapsing separate thermal shield and housing functions into single molded components.
Euro 6d emission protocols administered by ECHA and national type-approval authorities are harmonizing diurnal and refueling vapor recovery thresholds across European markets. The industrial consequence is standardized carbon bed sizing and purge calibration across vehicle platforms previously optimized for national variations. Powertrain engineering teams in France and Germany are responding by consolidating canister specifications across model lines to reduce validation overhead.
Direct OEM engagement with resin compounders is displacing tiered material distribution for engineered thermoplastics used in canister production. Procurement teams at passenger vehicle manufacturers are establishing qualification relationships with polyamide suppliers that previously sold exclusively through distributors. This pattern is most visible in the United States where domestic content incentives under the Inflation Reduction Act are reshaping supplier relationship structures toward traceable, localized material sourcing.
Automotive Canister Market Segmentation
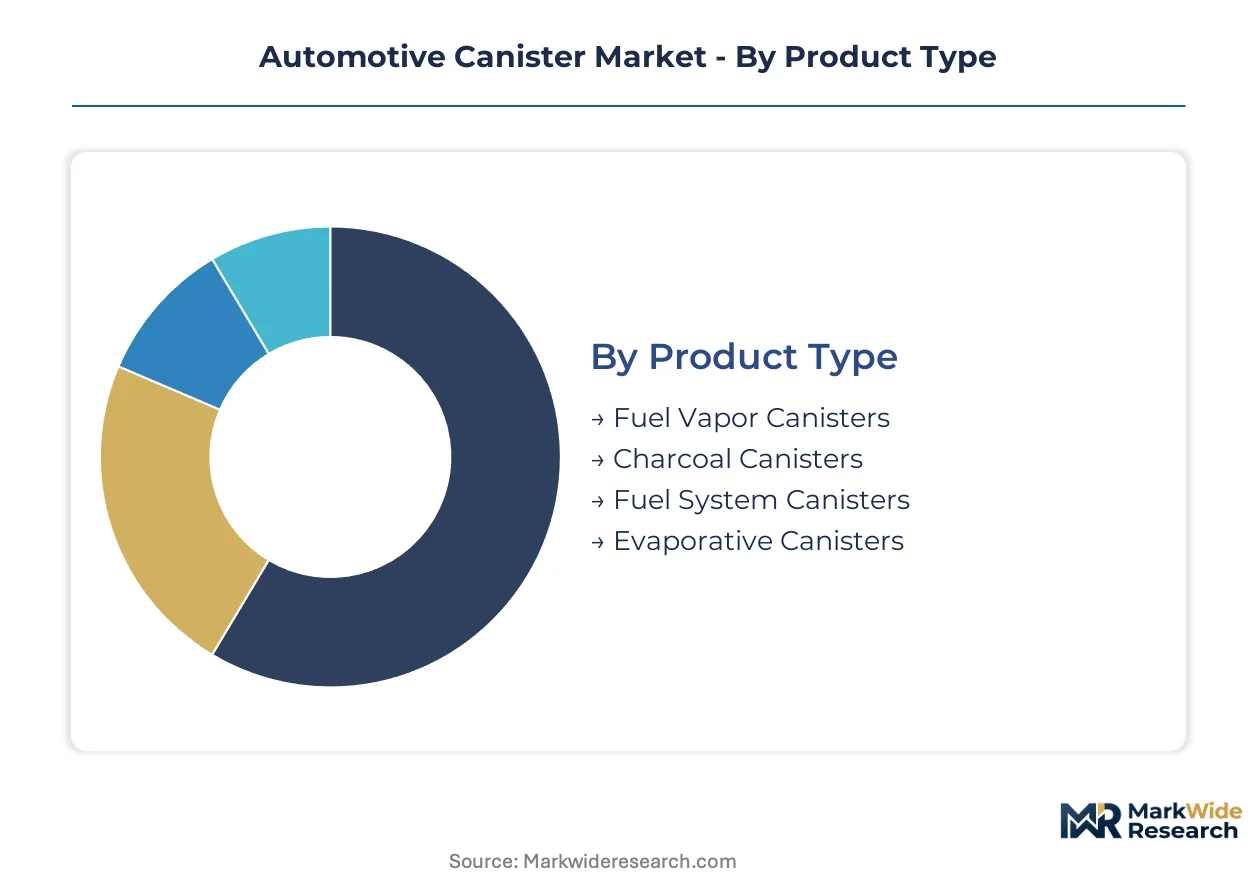
Automotive canister segmentation reveals how certification requirements cascade differently across product architectures, material grades, and supply chain tiers. Understanding these divisions exposes where EPA Tier 3 and Euro 6d compliance costs concentrate and which segments command qualification premiums.
Product Type:
EPA 40 CFR Part 86 and CARB LEV III impose distinct carbon bed volume and purge calibration requirements on each canister architecture, fragmenting validation protocols across product categories.
- Fuel Vapor Canisters:These systems integrate tank vent line adsorption with engine purge control, utilizing activated carbon media rated for diurnal emission cycling. German passenger vehicle OEMs specify expanded carbon capacities to meet Euro 6d diurnal thresholds, compressing development timelines for Tier-1 suppliers.
- Charcoal Canisters:Dominant volume position rests on decades of validated carbon-bed designs and lowest unit manufacturing cost. United States procurement concentrates in legacy internal combustion platforms where EPA Tier 3 compliance can be achieved with standardized carbon grades and conventional purge strategies.
- Fuel System Canisters:Modular architectures designed for integrated tank vapor management across multiple vent points.
- Evaporative Canisters:Specialized housings for diurnal and refueling emission control in hybrid powertrain configurations.
Leading the category by volume: Charcoal Canisters. Growing fastest: Fuel Vapor Canisters.
End User:
Cost tier stratification separates captive production programs from outsourced supply, with qualification burden shifting dramatically across the value chain.
- Original Equipment Manufacturers:Direct specification authority over carbon grade, housing material, and purge valve integration. Japanese OEMs are consolidating canister sourcing under single-supplier subsystem contracts to reduce validation overhead for hybrid architectures.
- Tier-1 Suppliers:Engineering accountability for module-level EPA and CARB certification, including purge valve actuation and pressure sensing integration. Mexico-based extrusion capacity anchors North American supply for Continental AG and MAHLE programs serving United States vehicle assembly.
- Aftermarket Providers:Replacement canister distribution for legacy vehicle fleets and emission repair facilities.
- Vehicle Assemblers:Final integration responsibility for canister-to-powertrain plumbing and diagnostic system validation.
Capturing the highest margins: Tier-1 Suppliers. Expanding most quickly: Original Equipment Manufacturers.
Material:
Supply concentration for engineered thermoplastics creates sourcing leverage points that favor compounders with captive resin operations.
- Plastic:High-density polyethylene dominates economy vehicle segments where thermal requirements permit. Reinforced polyamide is displacing conventional grades in German and Japanese charge-port vapor management modules as underhood temperatures rise.
- Metal:Stamped and coated steel housings retain cost advantages in price-sensitive procurement categories. United States full-size truck platforms continue specifying steel canisters where mass reduction yields minimal fuel economy benefit.
- Composite:Glass-fiber reinforced polyamide compounds specified for thermal and hydrocarbon resistance in electrified powertrains.
- Aluminum:Cast and machined housings for premium thermal management applications.
Highest volume: Plastic. Steepest expansion trajectory: Composite.
Application:
Vehicle duty cycle determines canister sizing, carbon grade, and purge frequency calibration across regulatory test protocols.
- Passenger Vehicles:Deepest application segment with multi-canister architectures proliferating in plug-in hybrid configurations requiring separate tank and charge-port vapor management. California LEV III standards drive canister volume expansion across United States compact and mid-size platforms.
- Commercial Vehicles:Heavy-duty diesel applications with reduced evaporative emission stringency but extended duty cycles demanding carbon durability. Refueling vapor recovery mandates in additional state jurisdictions beyond California expand hardware volumes.
- Light-Duty Vehicles:Pickup trucks and vans subject to EPA Tier 3 diurnal limits with larger fuel tanks requiring expanded carbon bed sizing.
- Heavy-Duty Vehicles:Class 8 trucks and vocational equipment with specialized venting architectures.
Dominating procurement volume: Passenger Vehicles. Gaining share fastest: Light-Duty Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement concentrates demand through California's LEV III standards and the Inflation Reduction Act's domestic content incentives, reshaping supplier qualification requirements across North American vehicle programs.
United States
Passenger vehicle OEMs in Detroit and California are expanding procurement of lightweight composite canisters as EPA Tier 3 emission norms tighten hydrocarbon evaporation limits. The Inflation Reduction Act's domestic content incentives are accelerating localized material sourcing relationships. Tier-1 suppliers anchor North American supply through dedicated extrusion and blow-molding capacity in Mexico serving United States vehicle assembly.
Germany
German passenger vehicle OEMs specify expanded carbon capacities to meet Euro 6d diurnal thresholds, compressing development timelines for Tier-1 suppliers. ECHA-administered protocols harmonize vapor recovery standards across European markets. Engineering teams in Stuttgart and Munich are consolidating canister specifications across model lines to reduce validation overhead.
Japan
Japanese OEMs are consolidating canister sourcing under single-supplier subsystem contracts to reduce validation overhead for hybrid architectures. METI fuel consumption regulations converge with European test cycles, adding regulatory complexity for suppliers. Automotive clusters in Toyota City and Hiroshima specify reinforced polyamide for charge-port vapor management modules.
China
MIIT fuel consumption and evaporative emission rules under GB standards are converging with European test cycles, compelling canister volume expansion. Domestic OEMs in Shanghai and Guangzhou are qualifying reinforced composite housings for plug-in hybrid architectures. The Yangtze River Delta hosts expanding activated carbon media processing capacity for regional vehicle programs.
India
Pending alignment of BIS evaporative standards with European test cycles creates first-mover positioning for suppliers establishing local compounding and molding capacity. Two-wheeler and passenger vehicle OEMs in Pune and Chennai are evaluating multi-canister architectures for emerging emission protocols. Automotive clusters in Maharashtra and Tamil Nadu attract Tier-1 investment for subsystem localization.
Automotive Canister Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with subsystem integrators capturing margin premiums from electronics-mechanical convergence while commodity housing fabricators compete on resin compounding scale. The supplier base concentrates among Tier-1 module integrators with captive carbon sourcing relationships and regional molding specialists serving single OEM programs. Three archetypes dominate: integrated subsystem suppliers managing purge valve-to-housing validation, resin compounders with captive automotive-grade polyamide operations, and regional stampers maintaining steel canister cost floors. Competitive intensity manifests through backward integration into activated carbon media processing and geographic co-location with OEM assembly plants.
Among German-based integrated suppliers, MAHLE and Continental AG exemplify the subsystem integrator archetype through module-level engineering accountability spanning purge valve actuation to housing specification. Robert Bosch GmbH occupies a position bridging electronics-to-mechanical development for hybrid powertrain configurations. These three entities represent distinct strategic postures within the Tier-1 supplier tier, anchoring competitive dynamics around material science capabilities and regulatory certification velocity rather than unit cost alone.
| Leading Market Players |
|---|
| MAHLE |
| Stant Corporation |
| Robert Bosch GmbH |
| UFI Filters S.p.A. |
| HELLA GmbH & Co. KGaA |
| Continental AG |
| Aptiv PLC |
| Marelli |
| MANN+HUMMEL |
| Others |
Value Chain & Pricing Dynamics
Composite material substitution in canister housings simultaneously compresses per-unit manufacturing costs and concentrates supply leverage among compounders with captive resin operations. This shift from high-density polyethylene to reinforced polyamide restructures procurement relationships toward direct OEM-compounder engagement while elevating qualification barriers for secondary suppliers.
Pricing Analysis
Volume-margin splits separate charcoal canister commoditization from composite subsystem premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and carbon bed complexity. Pricing pressure stems from EPA Tier 3 compliance costs compressing Tier-1 supplier margins. Economy vehicle segments exhibit highest price sensitivity, while electrified powertrain programs absorb premium housing costs for mass reduction benefits.
Supply Chain Analysis
Single-source vulnerability sits with activated carbon media processors concentrated in Germany, Japan, and the United States. Automotive-grade polyamide compounding draws from petrochemical feedstocks and glass fiber reinforcement supply anchored in European and Asian production clusters. Tariff exposure on engineered thermoplastics threatens qualification timelines for Mexico-based molding capacity serving North American assembly. Distribution runs through Tier-1 subsystem integrators managing purge valve-to-housing validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward integration into activated carbon processing and resin compounding determines cost position. Players are pursuing upstream control over material qualification pipelines to compress development timelines and capture margin from electronics-mechanical convergence.
For Market Incumbents: Acquire activated carbon processing assets to secure lot-to-lot consistency for EPA 40 CFR Part 86 certification. Consolidate purge valve integration capabilities to defend subsystem margins against modular competitors. Threat substitution from electronics specialists demands embedded sensor development investment. Capacity addition in Mexico anchors North American supply relationships against reshoring incentives. For New Entrants and Emerging Players: Enter via India BIS emission convergence ahead of domestic standard implementation. White-space concentrates in two-wheeler multi-canister architectures and regional compounding capacity for reinforced polyamide. Target Tier-2 supplier positioning in charge-port vapor management modules for Japanese hybrid platforms. Go-to-market leverage rests on carbon bed validation partnerships with established testing laboratories. For Investors and Strategic Acquirers: Exit pathways concentrate in subsystem integrators with EPA-CARB dual certification and captive resin operations. Long-term viability favors compounders with automotive-grade polyamide expertise transferable across electrified powertrain thermal management applications. Acquisition target archetype: regional molding specialists with OEM qualification relationships and underutilized extrusion capacity. Signal to watch: EPA reconsideration of supplemental federal test procedures accelerating carbon grade upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Processing | Captive activated carbon supply secures lot consistency for EPA Tier 3 validation cycles. |
| Composite Housing Capacity Expansion | Reinforced polyamide extrusion in Mexico serves United States domestic content incentives. |
| Electronics-Mechanical Module Convergence | Integrated purge valve actuation and pressure sensing enables Tier-1 margin capture from OEMs. |
| India Localization Partnership | Joint ventures with Pune and Chennai automotive clusters position ahead of BIS emission alignment. |
| Carbon Bed Validation Consolidation | Single-supplier subsystem contracts reduce Japanese OEM qualification overhead for hybrid architectures. |
Study Parameters
Independent corroboration across OEM platform engineering directors, Tier-1 supplier procurement leads, and activated carbon processing technical managers underwrites the qualitative findings. Secondary validation draws from EPA 40 CFR Part 86 certification databases, CARB LEV III compliance filings, vehicle production registration data, and customs records for engineered thermoplastic trade flows. Bottom-up segment sizing triangulates against top-down OEM procurement budget allocations across passenger vehicle programs.
Comparable-period anchoring extends historical carbon bed volume and housing material mix trends across the analysis window. Segmentation dimensions model propulsion architecture, content per vehicle, OEM tier positioning, and regional production cluster. CAGRs derive from regression analysis of canister counts per vehicle against emission standard phase-in schedules. Forecast inputs incorporate MIIT GB standard convergence timelines and Inflation Reduction Act domestic content incentive qualification thresholds.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EPA regulatory reconsideration and activated carbon supply disruption scenarios. Projections reflect assumptions regarding Euro 6d harmonization persistence and composite material substitution elasticity in economy vehicle segments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Trailing Arm Bushing Market
Automotive Parts
Indonesia Automotive Engine Oils Market
Automotive Parts
Argentina Automotive Actuators Market
Automotive Parts
Diesel Oxidation Catalyst Market
Automotive Parts
United States Automotive Parts Die Casting Market
Automotive Parts
Speed Bump Market
Automotive Parts
Brake Pad Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
Automotive Piston System Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market
Automotive Parts
Automotive Piston Engine System Market
Automotive Parts
HCV Brake Components Market
Automotive Parts
Commercial Vehicles LED Bar Lights Market
Automotive Parts
Automotive Aluminium Extrusion Market
Automotive Parts
Germany Automotive Parts Die Casting Market