
 Vehicle Barrier System Market | 2026-2036
Vehicle Barrier System Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Barrier System Market Analytics
The vehicle barrier system supply base is consolidating around two distinct tiers: engineered crash-rated solutions certified to ASTM F2656 and K-rating standards, and commodity perimeter controls for parking and traffic management. Delta Scientific Corporation leverages its California manufacturing footprint to dominate North American federal and diplomatic installations. Avon Barrier Corporation Ltd. anchors European demand through UK-certified hostile vehicle mitigation systems. Ameristar Security Products, Inc. competes on scale across commercial and utility applications with integrated access control bundling.
A vehicle barrier system is a physical security assembly—typically steel, aluminum, composite, or reinforced concrete—engineered to stop, delay, or redirect unauthorized vehicle intrusion through kinetic energy absorption, structural deformation, or geometric entrapment; crash-rated variants undergo full-scale impact testing against defined vehicle weights and velocities to protect personnel and critical assets. Active barriers such as retractable bollards and wedge barriers lead in transportation hub revenue due to operational flexibility and integration with credentialing systems, while passive concrete and steel fixed installations sustain margin pools in military and data center perimeters where permanent standoff is mandated. Composite materials represent the fastest-growing material segment as defense and aviation buyers prioritize corrosion resistance and rapid deployability.
The US Department of State's Bureau of Diplomatic Security and ASTM International shape product certification requirements, while the European Committee for Standardization's CEN crash-test protocols govern market access across EU member states. The Federal Aviation Administration mandates perimeter security compliance for commercial airports, and Saudi Arabia's General Authority of Civil Aviation has adopted comparable anti-ram standards for new terminal developments. Stakeholders must monitor evolving kinetic threat vehicle specifications and certification reciprocity between national standards bodies to avoid stranded product development investments.
Market Dynamics
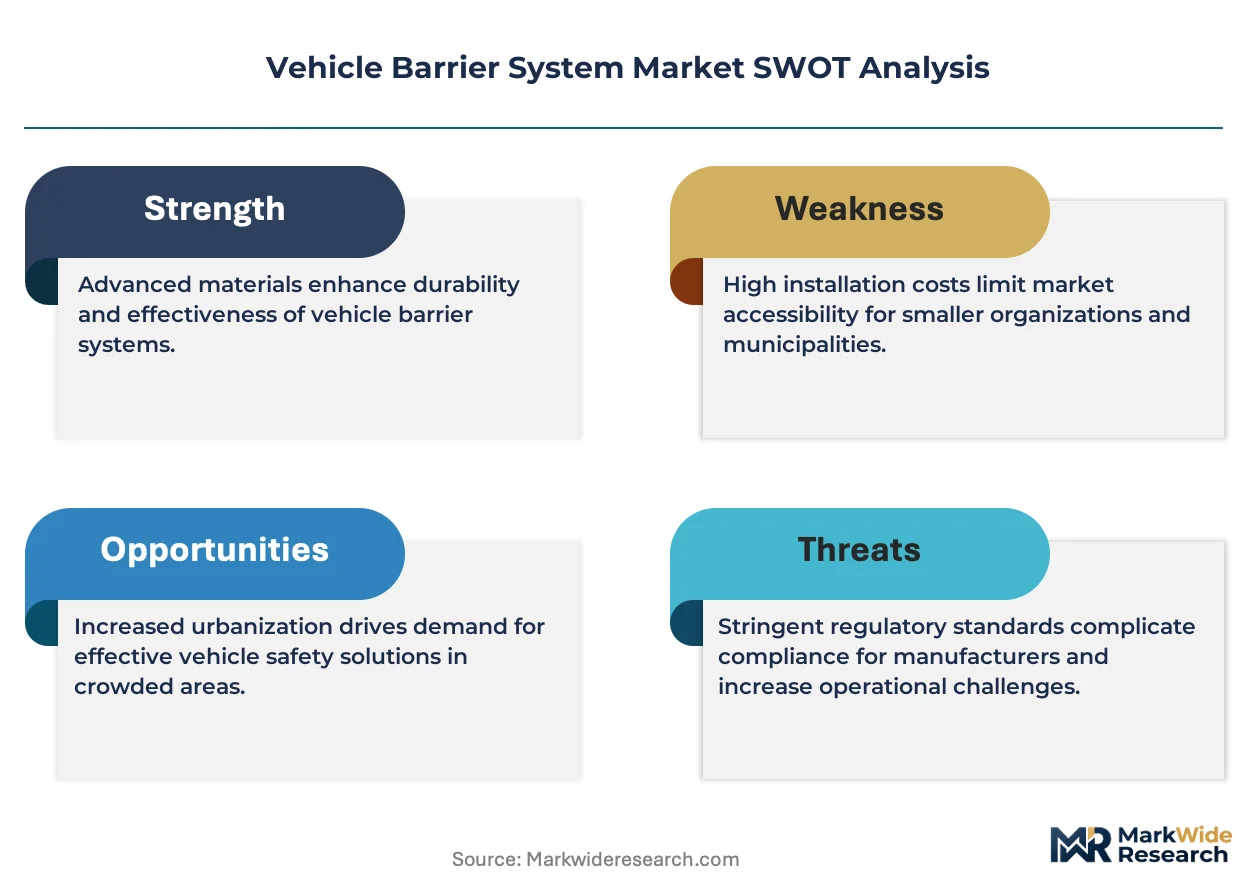
ASTM F2656 and CEN crash-test certification requirements are bifurcating the supply base into certified engineered solutions and commodity perimeter controls, forcing manufacturers to absorb full-scale impact testing costs or retreat to parking management applications.
Growth Catalysts
- FAA Anti-Ram Mandates:The Federal Aviation Administration mandates perimeter security compliance for commercial airports, accelerating procurement of K-rated barriers at US terminals undergoing expansion.
- Composite Material Advances:Blast-resistant composite cores with corrosion resistance are capturing defense and aviation contracts previously held by galvanized steel installations.
- Saudi GACA Standards:The General Authority of Civil Aviation adopted ASTM-equivalent anti-ram protocols for new terminal developments, opening procurement pipelines for certified foreign suppliers.
Market Restraints
- Steel Price Volatility:Hot-rolled steel input costs fluctuate with energy markets, compressing margins on fixed concrete-and-steel barrier installations where material represents 60% of project cost.
- Testing Concentration Risk:Full-scale crash certification facilities concentrate in the United States and Germany, creating bottlenecks for Asian and Middle Eastern manufacturers seeking market entry.
- Modular Barrier Substitution:Rapid-deploy surface-mounted systems threaten permanent foundation-based installations for temporary event security and construction site protection.
Strategic Opportunities
- India Critical Infrastructure:Bureau of Indian Standards is developing hostile vehicle mitigation codes for metro rail and government complexes, creating first-mover advantage for ASTM-certified exporters.
- Credentialing Integration:Convergence of retractable bollards with biometric access control and license plate recognition creates bundled security offerings for diplomatic compounds.
- EU Green Deal Procurement:Public sector tenders increasingly weight lifecycle carbon footprint, favoring aluminum and composite barriers over concrete in CSRD-aligned purchasing.
Industry Challenges
- Certification Timeline Compression:ASTM F2656 full-scale testing requires 6-12 months from prototype to certification, delaying product launches against faster-moving modular competitors.
- Legacy System Integration:Active barrier deployment at existing airports must interface with decades-old SCADA and access control architectures without facility-wide replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Barrier System Market |
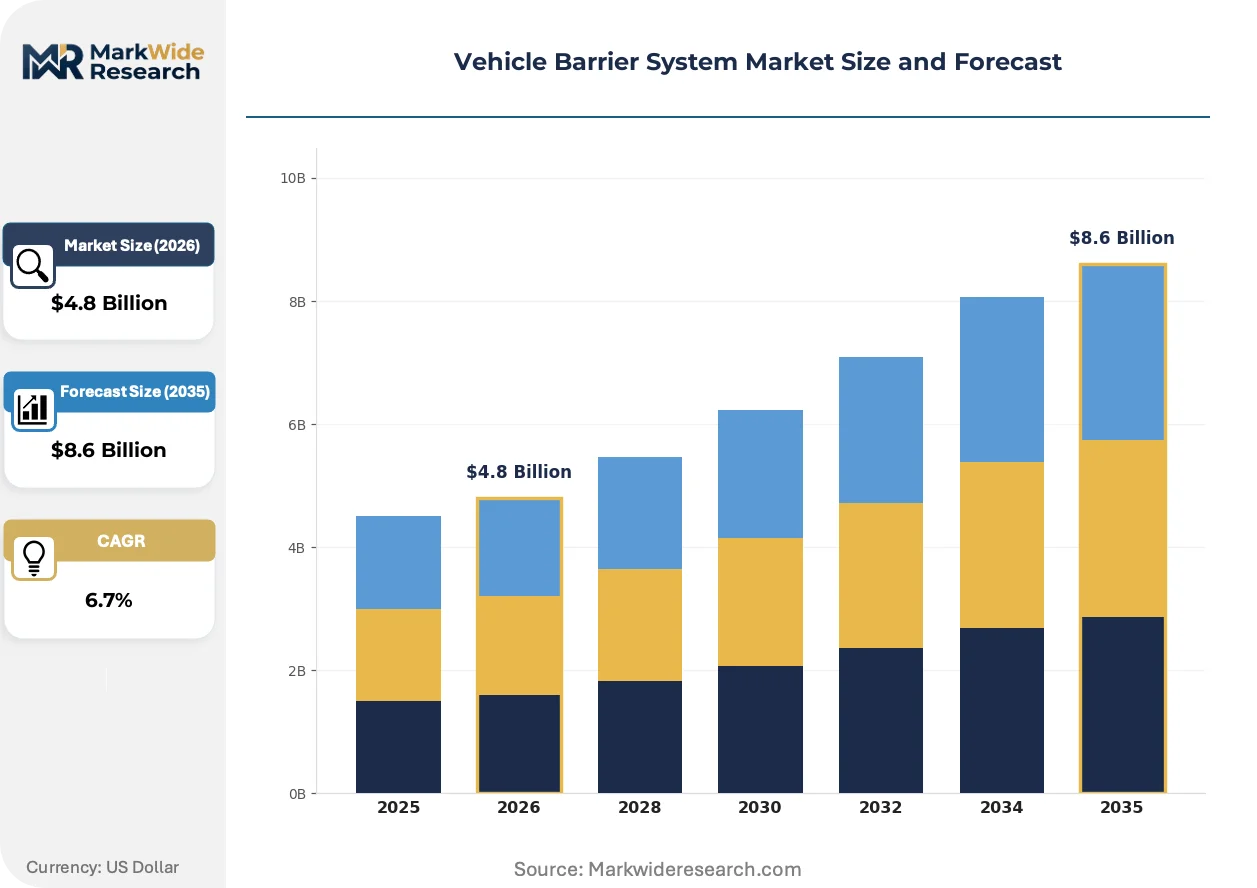
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Barriers, Passive Barriers, Crash Rated Barriers, Non-Crash Rated Barriers End User: Government, Commercial Facilities, Transportation Hubs, Military Installations Material: Steel, Aluminum, Composite, Concrete Installation Type: Permanent, Temporary, Mobile, Semi-Permanent |
| Companies Covered | Delta Scientific Corporation, Avon Barrier Corporation Ltd., ATG Access Ltd., Barrier1 Systems, Inc, FutureNet Security Solutions, Ameristar Security Products, Inc., RSSI Barriers, Boomgate Systems, FAAC S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Barrier System Market Evolving Landscape
Barrier system architecture is pivoting from static perimeter defense to intelligent, networked security nodes capable of real-time threat assessment and automated response sequencing.
Mobile deployable barrier systems using composite panels and rapid-anchor foundations are decentralizing procurement authority from centralized facilities management to field security teams at temporary venues and construction sites. Event organizers and critical infrastructure operators in Germany and the United Kingdom are adopting these systems for 48-hour deployment cycles. This shift is decentralizing the traditional specification chain where architects and security consultants controlled barrier selection.
The European Committee for Standardization's pending CEN/TS 17213 update will harmonize hostile vehicle mitigation test methods across EU member states, eliminating redundant national certification requirements. Manufacturers currently holding UK, French, and German national approvals face consolidation of testing protocols. High-threat installations in France, Belgium, and the Netherlands are delaying procurement decisions pending formal adoption, compressing near-term order flow.
Buyers are unbundling installation from hardware procurement, contracting directly with civil engineering firms for foundation work while sourcing barriers through competitive tender. This disintermediation erodes traditional manufacturer-installer relationships and exposes barrier suppliers to pure price competition on certified products. The pattern is most pronounced in US federal and Saudi aviation projects where construction management firms control subcontractor selection.
Vehicle Barrier System Market Segmentation
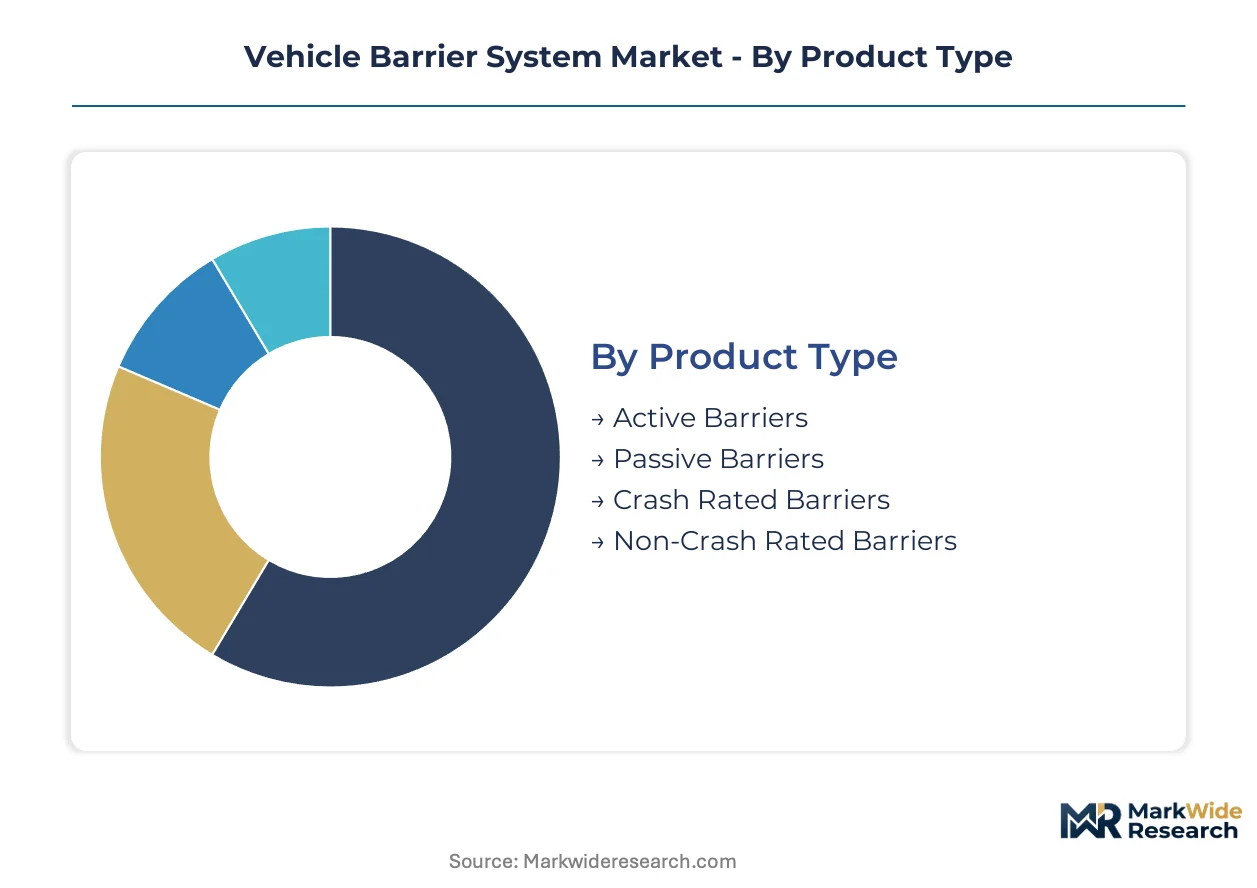
Barrier system procurement follows distinct specification chains across product categories, with crash certification status and operational mobility determining whether architects, security consultants, or facilities managers control purchasing decisions. Segmentation clarity enables suppliers to align testing investments and distribution channels with the actual decision-making units in each vertical.
Product Type:
Active barriers integrate with credentialing and surveillance systems for dynamic threat response, while passive installations provide permanent standoff without operational complexity; the integration depth varies sharply between these functional classes.
- Active Barriers:Retractable bollards, wedge barriers, and drop-arm gates incorporate hydraulic or electromechanical actuation systems for rapid deployment. Transportation hubs in the United States and Germany concentrate procurement here, driven by FAA and CEN mandates for operational flexibility at airport perimeters. Credentialing system integration adds 15-25% to unit economics but locks in multi-year service contracts.
- Passive Barriers:Fixed bollards, concrete planters, and steel planters rely on mass and geometry for kinetic energy absorption without moving parts. Military installations and data centers favor these for permanent standoff zones where operational simplicity outweighs flexibility. Foundation costs dominate project economics, with civil works representing 40-60% of installed cost.
- Crash Rated Barriers:Full-scale ASTM F2656 or CEN-tested systems with certified stopping capacity against defined vehicle weights and velocities.
- Non-Crash Rated Barriers:Visual deterrence and traffic management applications without impact certification, serving parking and pedestrian zone demarcation.
Crash rated barriers lead volumes today; active barriers are gaining share fastest.
End User:
Procurement authority and specification complexity vary dramatically across end user categories, with government buyers emphasizing certification reciprocity while commercial operators prioritize lifecycle cost.
- Government:Diplomatic compounds, courthouses, and legislative facilities require ASTM F2656 M50/P1 certification for anti-ram protection. The US Department of State's Bureau of Diplomatic Security maintains qualified product lists that constrain vendor eligibility. Procurement cycles extend 18-36 months with extensive witness testing requirements.
- Transportation Hubs:Airports and seaports combine perimeter security with throughput optimization, driving demand for active barriers with high-cycle reliability. Saudi Arabia's General Authority of Civil Aviation adoption of ASTM-equivalent standards has opened procurement to certified foreign suppliers at new terminal developments.
- Military Installations:Force protection standards mandate standoff distances with blast-resistant barrier specifications.
- Commercial Facilities:Corporate campuses and retail centers prioritize visual integration and insurance compliance over full crash certification.
Government segment commands premium pricing; transportation hubs show steepest expansion trajectory.
Material:
Material selection trades structural performance against corrosion resistance, deployability, and embodied carbon as procurement criteria diversify beyond initial cost.
- Composite:Blast-resistant cores of aramid fiber, glass-reinforced polymer, or ceramic composite deliver corrosion immunity and 60-70% weight reduction versus steel equivalents. Defense and aviation buyers in Germany and the United Kingdom are displacing galvanized steel for rapid deployability and reduced foundation requirements. EU Green Deal procurement weighting favors composites in CSRD-aligned tenders.
- Steel:Hot-rolled and galvanized steel dominates fixed installations where mass and ductility provide predictable deformation characteristics. Price volatility in energy-linked steel markets compresses margins on concrete-and-steel barrier projects where material represents the majority of direct costs.
- Aluminum:Lightweight corrosion resistance suits marine environments and rapid-redeploy systems.
- Concrete:Massive fixed barriers provide lowest per-unit stopping capacity cost for permanent military and utility perimeters.
Steel retains volume leadership; composite materials are climbing the fastest.
Installation Type:
Foundation requirements and procurement authority decentralization distinguish installation categories, with temporary systems enabling field-level purchasing decisions outside traditional specification chains.
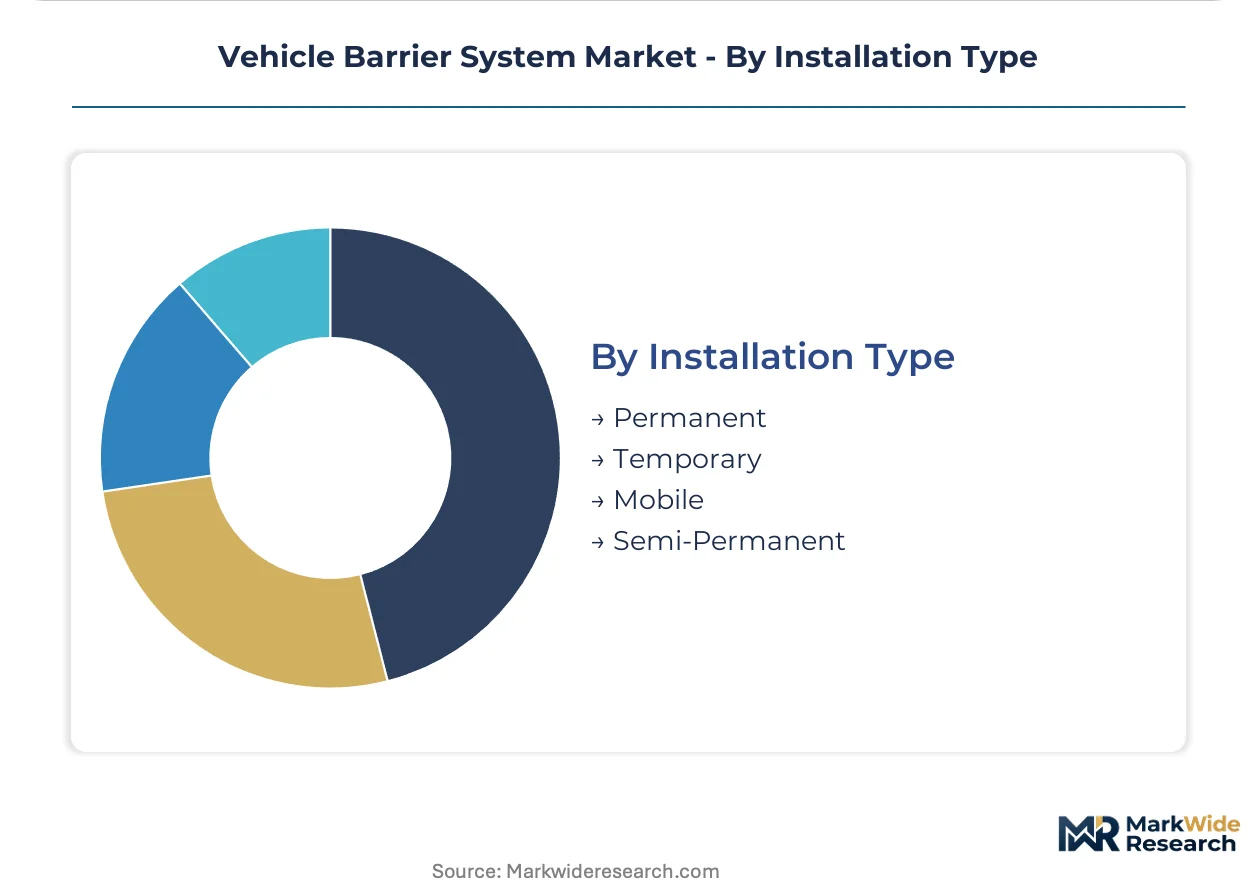
- Permanent:Foundation-embedded bollards and walls with poured concrete footings provide maximum stopping capacity and design life exceeding 25 years. Data centers and military perimeters mandate these for guaranteed standoff, with civil engineering firms increasingly contracted separately for foundation work.
- Mobile:Surface-mounted composite panels with rapid-anchor foundations enable 48-hour deployment cycles for temporary events and construction sites. Event organizers in Germany and the United Kingdom are decentralizing procurement authority from facilities management to field security teams.
- Temporary:Ballasted or anchored systems for defined-duration deployment without subsurface preparation.
- Semi-Permanent:Shallow foundation systems allowing relocation with moderate civil works.
Permanent installations dominate revenue; mobile systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in California, Bavaria, and the United Kingdom anchor certified barrier development. ASTM and CEN testing facilities concentrate near these workforce pools. Procurement pipelines align with counter-terrorism infrastructure spending in each concentration zone.
United States
Airport perimeter expansions at Dallas-Fort Worth and Denver International drive active barrier procurement. FAA mandates K-rated and ASTM F2656-certified systems for all commercial aviation facilities. Delta Scientific Corporation maintains manufacturing in Southern California to serve federal and diplomatic installations with rapid deployment capability.
Germany
Frankfurt Airport and Berlin Brandenburg terminal upgrades require CEN-tested hostile vehicle mitigation systems. The country's national regulator KBA influences crash-test protocol adoption across EU member states. Composite barrier specialists in Bavaria supply corrosion-resistant solutions for rapid-deploy applications at temporary event venues.
Saudi Arabia
NEOM and Red Sea Project developments incorporate anti-ram perimeter standards equivalent to ASTM protocols. The General Authority of Civil Aviation adopted foreign certification reciprocity for new terminal construction. Riyadh and Jeddah airport authorities source certified barriers from European and North American suppliers with local partnership structures.
United Kingdom
London financial district and government quarter renewals prioritize retractable bollard systems with credentialing integration. Avon Barrier Corporation Ltd. anchors domestic hostile vehicle mitigation supply from its base in the English Midlands. Temporary event security at Wimbledon and Premier League venues drives mobile composite barrier adoption.
India
Metro rail expansions in Delhi, Mumbai, and Bangalore prompt Bureau of Indian Standards to develop hostile vehicle mitigation codes. The central bank's infrastructure security guidelines influence procurement at financial data centers. ASTM-certified exporters target first-mover positioning as certification requirements formalize.
Vehicle Barrier System Market Competitive Landscape
Top-tier vendors anchor the crash-rated certification tier, while commodity perimeter controls occupy a price-competitive lower tier. The supply base consolidates around two strategic positions: engineered solutions with full-scale testing investments and scale-driven manufacturers bundling access control. Three archetypes dominate—certification specialists, integrated security platforms, and rapid-deploy composite innovators. Competitive moves concentrate on M&A for testing facility access and geographic expansion into Saudi and Indian procurement pipelines.
Within the certification-specialist tier, Delta Scientific Corporation and Avon Barrier Corporation Ltd. exemplify the geographic anchoring pattern—California-based and UK-based respectively—where proximity to ASTM and CEN testing infrastructure shapes competitive positioning. Ameristar Security Products, Inc. occupies a scale-driven position across commercial and utility applications. These three structures represent the dominant competitive archetypes: testing-proximate engineering, regional regulatory alignment, and integrated platform scale.
| Leading Market Players |
|---|
| Delta Scientific Corporation |
| Avon Barrier Corporation Ltd. |
| ATG Access Ltd. |
| Barrier1 Systems, Inc |
| FutureNet Security Solutions |
| Ameristar Security Products, Inc. |
| RSSI Barriers |
| Boomgate Systems |
| FAAC S.p.A. |
| Others |
Value Network & Pricing Analysis
FAA-mandated K-rated certification for airport perimeters forces manufacturers to absorb full-scale ASTM F2656 testing costs or retreat to commodity parking applications, compressing margins on non-certified tiers while concentrating pricing power with testing-proximate engineering specialists.
Pricing Analysis
Bundled installation services versus unbundled hardware procurement defines the dominant pricing split. Three-tier pricing structure across crash-certified, non-certified commercial, and commodity traffic management levels separates ASTM F2656 M50/P1 systems from standard K-rated barriers and visual-deterrent bollards. Price differentiation rests on certification tier and after-sales service bundling. Cost compression in fixed concrete-and-steel installations intensifies because hot-rolled steel input volatility erodes project margins where material represents the majority of direct costs. Commercial facilities managers show highest price sensitivity; diplomatic security buyers show lowest.
Supply Chain Analysis
Freight costs for full-scale crash-rated barrier systems concentrate manufacturing in California, Bavaria, and the English Midlands to maintain proximity to ASTM and CEN testing facilities. Raw material inputs draw from hot-rolled steel mills, aramid fiber composite suppliers, and hydraulic actuator manufacturers. Single-source vulnerability concentrates at full-scale crash certification facilities in the United States and Germany, creating bottlenecks for Asian and Middle Eastern market entrants. Distribution runs through construction management firms and security integrators rather than direct specification by architects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement shifts toward composite blast-resistant cores and credentialing-integrated active barriers reward certified engineering over commodity volume.
For Market Incumbents: Cement testing-proximate positioning by acquiring crash certification facility access or partnerships in Germany and the United States. Deepen backward integration into aramid fiber composite supply to defend margin position against steel price volatility. Prioritize credentialing system integration capabilities to lock in multi-year service contracts at transportation hubs. For New Entrants and Emerging Players: Direct-to-security-integrator digital channels bypass architect-controlled specification chains for rapid-deploy mobile barrier systems. Target temporary event security and construction site protection in Germany and the United Kingdom where procurement authority decentralizes to field security teams. Lead with 48-hour deployment cycle guarantees and surface-mounted foundation systems to disintermediate traditional civil engineering relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with composite material specialists holding CEN/TS 17213 pre-certification positioning ahead of EU protocol harmonization. Long-term viability favors manufacturers with dual ASTM and CEN testing capabilities across the projection horizon. Watch India's Bureau of Indian Standards hostile vehicle mitigation code finalization as the inflection signal for first-mover certification investments.| Strategic Initiative | Industry Significance |
|---|---|
| Crash Certification Facility Partnership | ASTM F2656 testing access in California or Germany eliminates 6-12 month market entry delays. |
| Composite Material Backward Integration | Aramid fiber supply control insulates margins from steel volatility and satisfies EU Green Deal procurement. |
| Credentialing System Integration | Biometric access control bundling at diplomatic compounds creates recurring service revenue streams. |
| Mobile Deployable Product Line Launch | Surface-mounted rapid-anchor systems capture temporary event security procurement outside traditional specification chains. |
| India Market Pre-Certification Investment | Bureau of Indian Standards code alignment positions ASTM-certified exporters for infrastructure security procurement. |
Research Methodology
Bottom-up transportation hub and critical infrastructure modeling reconciled against top-down crash-rated barrier production tracking forms the analytical core. Primary interviews with airport security directors, diplomatic compound facilities managers, hostile vehicle mitigation consultants, and construction management procurement officers combined with secondary validation against FAA compliance databases, ASTM certification registries, CEN technical committee documentation, and Saudi GACA procurement notices. Top-down trade data and bottom-up project pipeline tracking triangulate volume estimates.
Historical trendline analysis of certification timelines, material cost trajectories, and procurement cycle durations informs the projection framework. Segmentation dimensions span active versus passive barrier function, crash-rated versus non-certified tier, steel versus composite versus concrete material, and permanent versus mobile installation type. CAGRs derive from fitted growth curves against infrastructure security spending patterns and regulatory mandate adoption schedules. Forecast inputs include steel price volatility indices and testing facility capacity utilization.
The model assumes a particular technology adoption path; alternative pathways for rapid-deploy composite surface-mounted systems would alter the outlook if procurement authority permanently shifts from architects to field security teams. Forecasts reflect documented assumptions about certification reciprocity timelines and infrastructure spending continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Acoustic Vehicle Alerting System Market
Automotive Safety and Security Systems
North America Airbag Systems Market
Automotive Safety and Security Systems
Automotive Night Vision Sensors Market
Automotive Safety and Security Systems
Driving Armor Market
Automotive Safety and Security Systems
Automotive Mirror System Market
Automotive Safety and Security Systems
Vehicle Speed Monitoring System Market
Automotive Safety and Security Systems
Smart Airbag Coats Market
Automotive Safety and Security Systems
Automotive Shielding Market
Automotive Safety and Security Systems
Brazil Airbag Systems Market
Automotive Safety and Security Systems
Global Airbag Systems Market
Automotive Safety and Security Systems
Automotive Anti-Roll Bar Market
Automotive Safety and Security Systems
Automotive Seat Belt Sensor Market
Automotive Safety and Security Systems
Global Automotive Camera Cleaning System Market
Automotive Safety and Security Systems
Automotive Driver State Monitoring Systems Market
Automotive Safety and Security Systems
Automotive Lane Warning System Market
Automotive Safety and Security Systems
Automotive Rear Occupant Alert System Market