
 Global Augmented Reality Software Market | 2026-2036
Global Augmented Reality Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Augmented Reality Software Market Foresight
North American hyperscaler capacity expansion is recalibrating how AR software platforms reach enterprise buyers. Microsoft Corporation leverages its Azure cloud backbone to anchor industrial AR deployments across manufacturing verticals. Meta Platforms Inc. competes through its Quest ecosystem and spatial computing investments in consumer-facing applications. Apple Inc. differentiates via proprietary silicon-software integration for premium AR visualization experiences.
Augmented Reality Software comprises program layers that overlay digital information onto physical environments through camera-fed spatial mapping, real-time rendering engines, and sensor fusion algorithms. These systems serve industrial and commercial purposes by enabling hands-free guidance, remote collaboration, and immersive product visualization. Cloud-based deployment leads solution architecture as enterprises prioritize scalable infrastructure over on-premise installations. AR Software Development Kits occupy the fastest-growing solution tier as developers demand standardized toolchains for cross-platform builds. Gaming applications sustain mature revenue streams while manufacturing applications capture expanding margin pools from enterprise licensing models.
The EU AI Act and GDPR impose algorithmic transparency and data localization requirements on AR platforms operating in Europe. The FDA regulates AR-based surgical visualization tools as Class II medical devices in the United States, creating compliance barriers for healthcare entrants. China's MIIT and GB standards govern network security protocols for cloud-rendered AR content. Stakeholders must monitor how divergent data sovereignty regimes fragment platform architecture decisions across major deployment geographies.
Market Dynamics
Enterprise manufacturing adoption is compressing AR software deployment cycles as industrial firms prioritize hands-free assembly guidance and remote expert assistance over traditional training methods. Cloud-rendered spatial computing is displacing on-premise installations, forcing platform vendors to architect for hyperscaler infrastructure.
Growth Catalysts
- EU AI Act compliance mandates:European manufacturers must deploy algorithmically transparent AR systems for quality assurance, creating procurement pull for auditable software stacks.
- Industrial metaverse investments:Automotive and aerospace firms in Germany and China are funding AR-guided digital twin implementations for assembly line optimization.
- 5G network slicing:Ultra-low latency connectivity in South Korea and Japan enables real-time cloud rendering for field service applications.
Market Restraints
- GPU supply concentration:Taiwan-based foundry capacity constraints limit edge-rendering hardware availability for AR headset manufacturers.
- FDA Class II device classification:Surgical visualization tools face month-long approval timelines that deter healthcare software entrants.
- LiDAR sensor cost volatility:Precision depth-sensing components experience price swings that compress margins on mid-tier AR devices.
Strategic Opportunities
- India manufacturing digitization:PLI scheme incentives for electronics assembly create first-mover advantage for AR-guided quality control platforms.
- Spatial computing-robotics convergence:Integration of AR overlays with cobot programming interfaces opens industrial automation workflows.
- Outcome-based licensing models:Manufacturers in Brazil and Mexico are piloting per-use AR software pricing for seasonal production ramps.
Industry Challenges
- Computer vision engineer scarcity:Spatial mapping algorithm development faces talent bottlenecks in European and North American labor markets.
- Legacy MES integration complexity:Manufacturing execution systems require custom API bridges for real-time AR data ingestion.
- Cross-jurisdiction patent thickets:Optical waveguide and gesture recognition IP portfolios create licensing friction for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Augmented Reality Software Market |
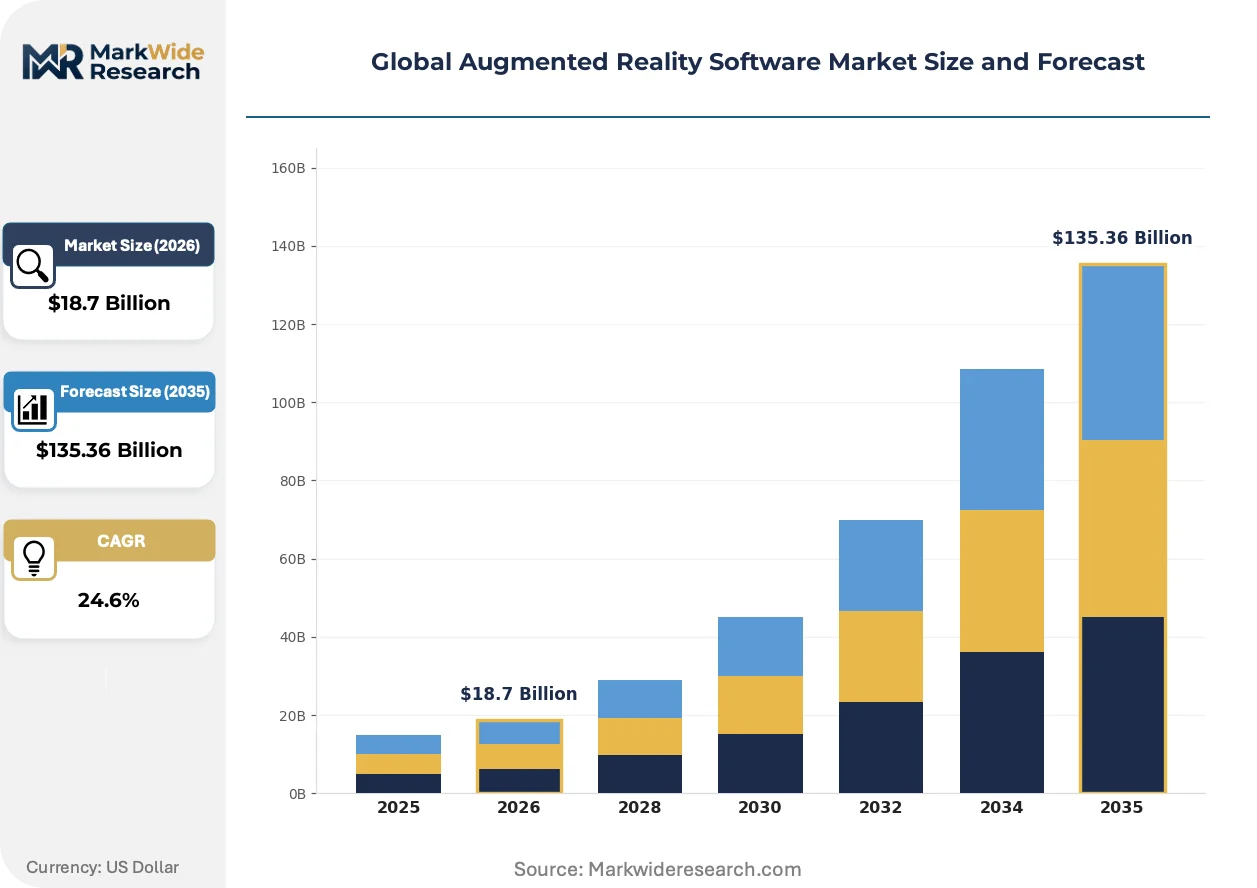
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
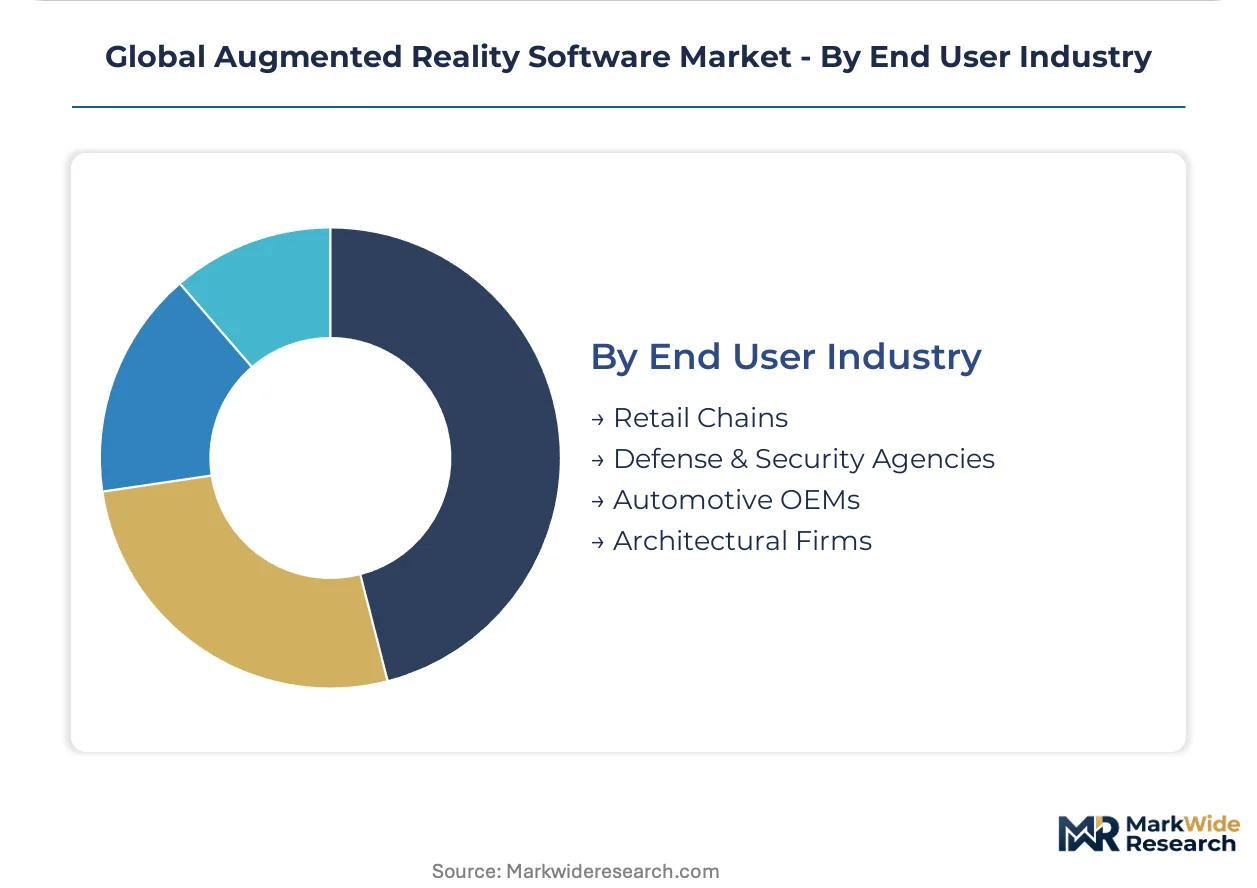
| Segmentation | Deployment: Cloud-based, On-premise, Hybrid, Edge Computing Solution Type: AR Software Development Kit, AR Browsers, AR Visualization Tools, Location-based AR Platforms Application: Gaming, Education, Manufacturing, Real Estate, Marketing End User Industry: Retail Chains, Defense & Security Agencies, Automotive OEMs, Architectural Firms |
| Companies Covered | Microsoft Corporation, Meta Platforms Inc., Apple Inc., Google LLC, PTC Inc., Unity Technologies, Snap Inc., Qualcomm Technologies Inc., Niantic Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Augmented Reality Software Market Shifts & Advancements
Edge-native rendering architectures are fragmenting how AR software platforms distribute computational load between devices and cloud infrastructure. Vendors are racing to optimize latency-critical pipelines for manufacturing and medical use cases.
Edge AI inference is decentralizing spatial mapping workloads from centralized data centers to on-device neural processing units. Automotive suppliers in Germany are deploying these architectures for real-time quality inspection on assembly lines. This shift is compressing dependency on persistent cloud connectivity for safety-critical AR applications.
The EU AI Act's risk-based classification system is mandating explainability features for high-stakes AR deployments in healthcare and industrial safety. European software vendors must embed algorithmic transparency modules that log decision pathways. Medical device manufacturers are responding by restructuring product teams to include compliance engineers earlier in development cycles.
Buyer procurement patterns are consolidating around integrated platform subscriptions that bundle AR software with device management and content creation tools. Industrial buyers in the United States are displacing point-solution vendors with full-stack providers. This concentration is most visible in aerospace supply chains, where prime contractors mandate unified AR ecosystems across tier-one suppliers.
Global Augmented Reality Software Market Segmentation
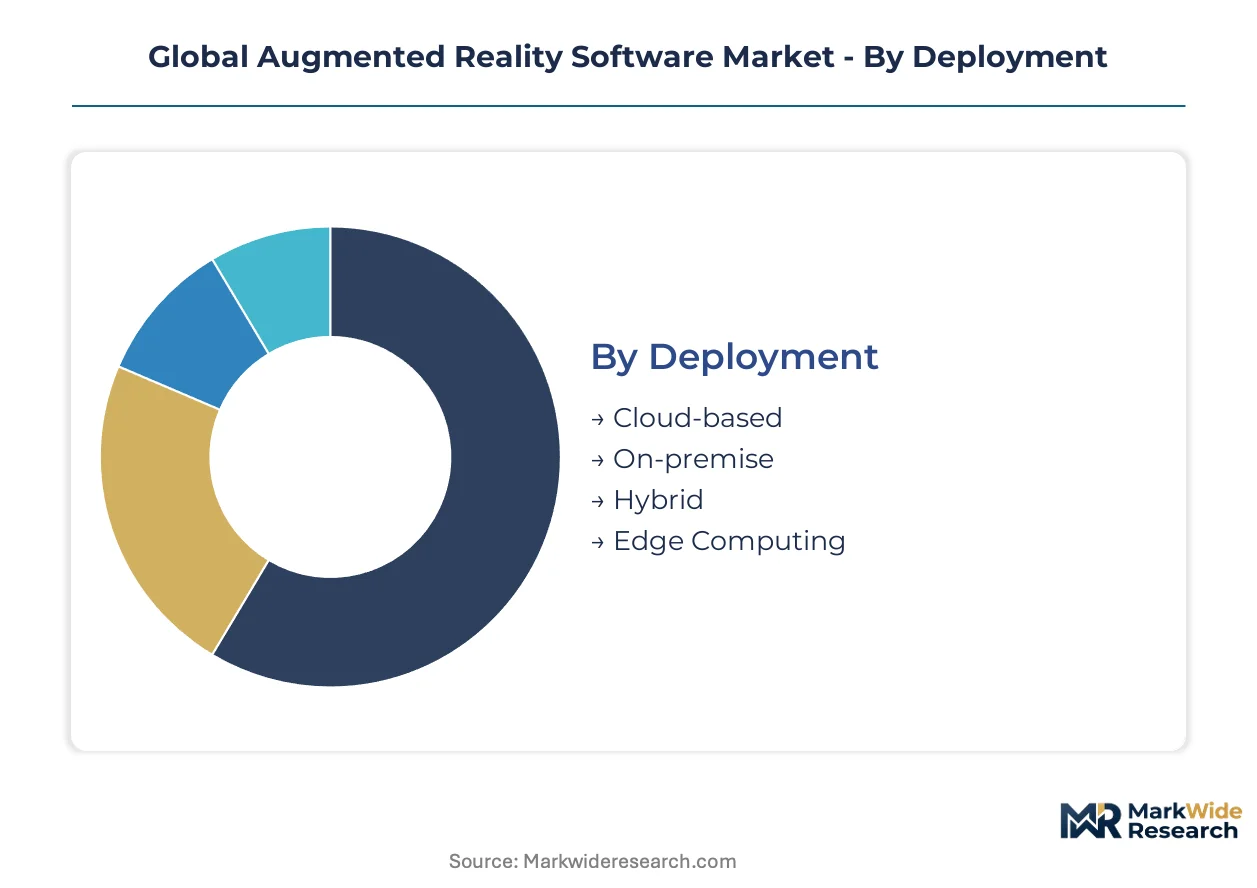
AR software segmentation reveals how computational architecture, developer tooling, and industry-specific workflows fragment purchasing decisions. Vendors must align pricing and integration depth against deployment constraints and end-user technical maturity.
Deployment:
Cloud infrastructure scalability versus data sovereignty requirements splits enterprise procurement strategies across hyperscaler regions.
- Cloud-based:Centralized rendering pipelines leverage AWS, Azure, and GCP infrastructure to stream spatial content to lightweight endpoints. German automotive suppliers prioritize these deployments for multi-site assembly guidance, though GDPR data localization clauses force EU-region server commitments.
- On-premise:Air-gapped installations host sensitive spatial mapping data within facility firewalls. Defense contractors in the United States mandate these configurations for classified maintenance workflows under ITAR compliance protocols.
- Hybrid:Split architectures process non-sensitive rendering in cloud instances while retaining proprietary CAD overlays locally. Japanese electronics manufacturers favor this model for protecting supplier intellectual property.
- Edge Computing:Distributed processing nodes execute inference at 5G base stations or factory floor gateways. South Korean telecom operators deploy these for sub-20ms latency in real-time remote assistance.
Cloud-based deployments lead on scale; edge computing leads on momentum.
Solution Type:
Developer toolchain standardization versus turnkey application accessibility determines buyer technical resource requirements and implementation velocity.
- AR Software Development Kit:Cross-platform libraries abstract camera access, plane detection, and occlusion handling for Unity and Unreal Engine builds. Chinese mobile game studios consume these most aggressively, though fragmentation between ARKit and ARCore APIs complicates multi-platform releases.
- AR Browsers:Web-based runtimes execute markerless experiences without native app installation. Retail chains in France deploy these for in-store navigation to bypass app store friction.
- AR Visualization Tools:Pre-configured viewers render 3D product models at scale for sales and design review. Architectural firms in the United States license these for client walkthroughs of unbuilt commercial spaces.
- Location-based AR Platforms:Geofenced content management systems anchor digital objects to GPS coordinates. Museum operators in Italy utilize these for cultural heritage site augmentation.
AR Software Development Kits lead on scale; AR Visualization Tools lead on momentum.
Application:
Use case technical complexity and measurable ROI visibility shape software licensing models and customer lifetime value profiles.
- Manufacturing:Guided assembly and quality inspection overlays integrate with MES and PLM systems. Aerospace suppliers in Germany capture defect reduction metrics that justify enterprise-wide seat expansions.
- Gaming:Location-based multiplayer and persistent world mechanics drive consumer download volumes. Studios in China monetize through in-app purchases tied to spatial collectible scarcity.
- Education:Interactive anatomy and physics simulations replace traditional laboratory equipment. Medical schools in Brazil deploy these to circumvent cadaver availability constraints.
- Real Estate:Furnished unit visualization and construction progress documentation accelerate pre-sales cycles. Developers in the UAE leverage these for off-plan luxury property marketing.
- Marketing:Branded face filters and product try-on experiences generate social media engagement metrics. Beauty retailers in South Korea measure conversion lift against control cohorts.
Manufacturing leads on scale; education leads on momentum.
End User Industry:
Procurement authority centralization and technical integration depth vary sharply across buyer organizational structures.
- Automotive OEMs:Global platform standardization mandates cascade AR requirements through tiered supply chains. Volkswagen Group's industrial cloud specifications compel software vendors to support OPC UA interoperability.
- Defense & Security Agencies:CMMC and FedRAMP compliance gates restrict vendor eligibility for maintenance and training contracts. The United States Army's IVAS program represents the largest single AR software procurement in this category.
- Retail Chains:Franchise-model dispersion complicates centralized AR deployment decisions. Inditex's Zara pilots self-service fitting room mirrors while leaving individual market activation to regional operators.
- Architectural Firms:Project-based revenue cycles favor consumption-based licensing over perpetual seats. Foster + Partners maintains internal AR development capabilities for signature project visualization.
Automotive OEMs lead on scale; defense and security agencies lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where AR software vendors architect their compliance infrastructure. Firms face divergent cost-of-compliance gaps between jurisdictions with stringent algorithmic transparency mandates and those prioritizing innovation velocity over oversight density.
United States
Defense procurement and enterprise manufacturing anchor demand. The FDA's Class II device classification for surgical visualization tools creates compliance barriers that filter market entrants. Microsoft's Azure cloud backbone supports industrial AR deployments across aerospace supply chains in Seattle and defense corridors around Washington D.C.
Germany
Automotive OEM platform standardization drives software procurement at scale. The EU AI Act's risk-based classification mandates explainability modules for quality-assurance AR systems. Volkswagen Group's industrial cloud specifications in Wolfsburg and BMW's Munich operations compel vendor support for OPC UA interoperability standards.
China
MIIT network security protocols and GB standards govern cloud-rendered AR content distribution. Mobile game studios in Shenzhen and Beijing consume AR Software Development Kits aggressively for location-based multiplayer mechanics. State-backed industrial digitization programs accelerate manufacturing AR pilots in the Yangtze River Delta.
India
PLI scheme incentives for electronics assembly create procurement pull for AR-guided quality control platforms. The country's national electronics regulator imposes data localization requirements on cloud-rendered industrial applications. Karnataka's Bengaluru cluster hosts emerging AR development capabilities serving domestic manufacturing digitization.
South Korea
5G network slicing enables sub-20ms latency for real-time cloud rendering in field service applications. The national telecommunications regulator governs spectrum allocation for industrial AR deployments. Seoul-based telecom operators partner with manufacturing conglomerates in Gyeonggi Province for edge-native rendering pilots.
Global Augmented Reality Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized vertical integration and cloud-native delivery models. The market structure consolidates around hyperscaler-backed platforms with sufficient capital to absorb compliance engineering costs. Three archetypes dominate: cloud infrastructure anchors, spatial computing specialists, and cross-platform toolchain providers. Competitive moves concentrate on strategic partnerships with industrial OEMs and portfolio diversification into adjacent robotics interfaces.
Among United States-based technology conglomerates, Microsoft Corporation, Meta Platforms Inc., and Apple Inc. anchor distinct competitive positions. Microsoft exemplifies the cloud-infrastructure archetype through Azure-anchored industrial deployments. Meta occupies the spatial computing tier with Quest ecosystem investments. Apple represents proprietary silicon-software integration for premium visualization experiences. These three entities collectively shape procurement standards that cascade through tiered supply chains.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Meta Platforms Inc. |
| Apple Inc. |
| Google LLC |
| PTC Inc. |
| Unity Technologies |
| Snap Inc. |
| Qualcomm Technologies Inc. |
| Niantic Inc. |
| Others |
Supply & Pricing Matrix
Aerospace prime contractors in Germany and the United States command enterprise AR software procurement through multi-year platform subscriptions that bundle device management, content creation tools, and compliance modules into unified pricing frameworks.
Pricing Analysis
Distributor margins compress as hyperscaler marketplaces displace traditional value-added resellers in enterprise AR software procurement. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth and GDPR compliance certification. Pricing pressure stems from open-source AR SDK proliferation eroding baseline toolkit revenues. Small-to-mid manufacturing firms exhibit highest price sensitivity; defense agencies demonstrate lowest due to FedRAMP mandate requirements.
Supply Chain Analysis
Regional distribution centers in Singapore, Frankfurt, and Dallas anchor hub-and-spoke patterns for AR headset hardware and edge computing nodes. Taiwan and South Korea supply GPU and NPU silicon; China dominates LiDAR sensor manufacturing. Single-source vulnerability concentrates in TSMC foundry capacity for neural processing units. Distribution runs through hyperscaler logistics networks and industrial distributor channels serving automotive and aerospace verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AR software vendors face a geographic-arbitrage imperative as EU AI Act compliance costs in Germany and France run substantially higher than innovation-first regimes in South Korea and Japan.
For Market Incumbents: Extend platform integration depth into manufacturing execution systems before specialized vertical vendors capture tier-one automotive relationships. Microsoft and PTC should deepen OPC UA interoperability investments to lock out emerging cloud-native entrants. Hyperscaler-backed players must absorb GDPR algorithmic transparency engineering costs that mid-cap specialists cannot shoulder. For New Entrants and Emerging Players: Begin with India's PLI-subsidized electronics assembly corridor where AR-guided quality control platforms face minimal incumbent saturation. Target tier-two automotive suppliers in Pune and Chennai with consumption-based licensing models. Pursue direct sales partnerships with state-backed industrial digitization programs rather than channel distributor relationships. For Investors and Strategic Acquirers: Cloud infrastructure providers are the most active acquirer in this space, seeking edge-native rendering capabilities to complete industrial metaverse portfolios. Long-term viability hinges on regulatory compliance engineering scale rather than pure feature velocity. Watch for FDA Class II device clearance announcements as inflection indicators for healthcare AR software valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft's Azure-anchored industrial deployments compel vendor support for unified AR ecosystems across aerospace supply chains. |
| Geographic Expansion | Edge computing nodes in South Korea's Gyeonggi Province enable sub-20ms latency for real-time remote assistance pilots. |
| Regulatory Compliance Investment | EU AI Act explainability modules for German automotive suppliers create procurement barriers for non-compliant software stacks. |
| Strategic Partnership | Telecom operators in Seoul partner with manufacturing conglomerates for 5G network slicing in field service applications. |
| Acquisition of Specialist Firm | Spatial computing specialists with proprietary waveguide IP attract hyperscaler interest amid patent thicket licensing friction. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged CTOs at industrial software vendors, IT procurement officers at German automotive OEMs, platform engineers at hyperscaler AR divisions, and integration specialists serving aerospace supply chains. Secondary validation drew from SEC filings, hyperscaler capex disclosures, EU AI Act regulatory texts, and FDA 510(k) clearance databases. Bottom-up deployment estimates triangulated against top-down enterprise software spending benchmarks.
Segment-weighting approaches distributed value across cloud-based, on-premise, hybrid, and edge computing deployment models. Organization size tiers, vertical industry adoption patterns, and regional regulatory cluster intensity shaped the analytical framework. CAGRs derived from logistic diffusion curves fitted to enterprise pilot-to-production conversion timelines. GPU supply constraints and 5G infrastructure rollout schedules entered as scenario-modifying inputs.
Several conditions sit outside the modeled scope, including consumer gaming AR monetization dynamics, military-classified program expenditures, and hardware-only headset revenues. Forecasts reflect documented assumptions around enterprise digitization budget trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Learning Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Book Market
Virtual Reality (VR) and Augmented Reality (AR)
Commercial Augmented Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented and Virtual Reality (AR VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Tourists Virtual Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Mirror Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mobile Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Mobile Infrastructure Market