
 Virtual Mirror Market | 2026-2036
Virtual Mirror Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Mirror Market Analysis
Modular hardware-software bundles is expanding buyer choice in the virtual mirror space. Perfect Corp. leverages its computer vision library to anchor premium positioning in beauty try-on deployments. Zugara competes through gesture recognition specialization for apparel retailers. FittingBox sustains geographic dominance across European eyewear chains with localized sizing databases.
A virtual mirror integrates camera arrays, depth sensors, and real-time rendering engines to overlay digital assets onto physical reflections with sub-100-millisecond latency. The system serves commercial environments where reducing product returns and shortening purchase cycles deliver measurable ROI. AR Mirrors capture the largest installed base among product types, while Gesture Recognition technology drives the fastest upgrade cycles as retailers replace touch-based hygiene-sensitive interfaces. Home Decor applications sit at the margin pool frontier, since furniture brands command higher per-unit software licensing fees than mass apparel.
The EU AI Act and GDPR constrain how virtual mirrors process biometric data in European retail environments, forcing vendors to deploy edge-computing architectures that minimize cloud transmission. The Federal Trade Commission in the United States scrutinizes virtual try-on claims for accuracy, shaping how vendors validate fit predictions. Stakeholders must monitor evolving biometric consent frameworks across multiple jurisdictions to determine where localization investments yield sustainable market access.
Market Dynamics
Gesture recognition interfaces are displacing touch-based virtual mirror installations across retail environments, driven by post-pandemic hygiene protocols and faster hardware refresh cycles in United States department stores.
Growth Catalysts
- EU AI Act transparency mandates:European retailers accelerate edge-computing deployments to process biometric data locally, expanding hardware replacement demand across France, Germany, and Italy.
- Apparel return rate compression:Virtual fitting stations reduce garment return processing costs for mid-market fashion chains, justifying per-store technology investments.
- Depth sensor miniaturization:Smaller LiDAR modules enable countertop mirror formats for boutique cosmetics retailers previously excluded from kiosk-scale deployments.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in real-time rendering chips creates procurement bottlenecks for virtual mirror vendors scaling production.
- Biometric consent fragmentation:Divergent state-level privacy laws across the United States force redundant compliance engineering for national retail rollouts.
- Cloud-to-edge migration costs:Re-architecting software stacks for local processing demands specialized firmware talent scarce outside Shenzhen and Taipei.
Strategic Opportunities
- Home decor licensing premiums:Furniture brands in the United States pay higher per-unit software fees than mass apparel retailers, creating margin expansion potential.
- India specialty retail penetration:Department store modernization in Mumbai and Delhi offers first-mover positioning before localized sizing databases mature.
- 5G-enabled mobile mirrors:Convergence of millimeter-wave connectivity and smartphone AR frameworks bypasses dedicated hardware for pop-up retail activations.
Industry Challenges
- Computer vision talent scarcity:Real-time occlusion handling and lighting normalization require specialized engineers concentrated in Silicon Valley and Beijing.
- Legacy POS integration friction:Virtual mirrors must synchronize with decade-old inventory management systems prevalent in mid-tier United States retail chains.
- Biometric certification timelines:ISO/IEC 30107-3 presentation attack detection validation delays product launches by 8-14 months for vendors targeting European financial services clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Mirror Market |
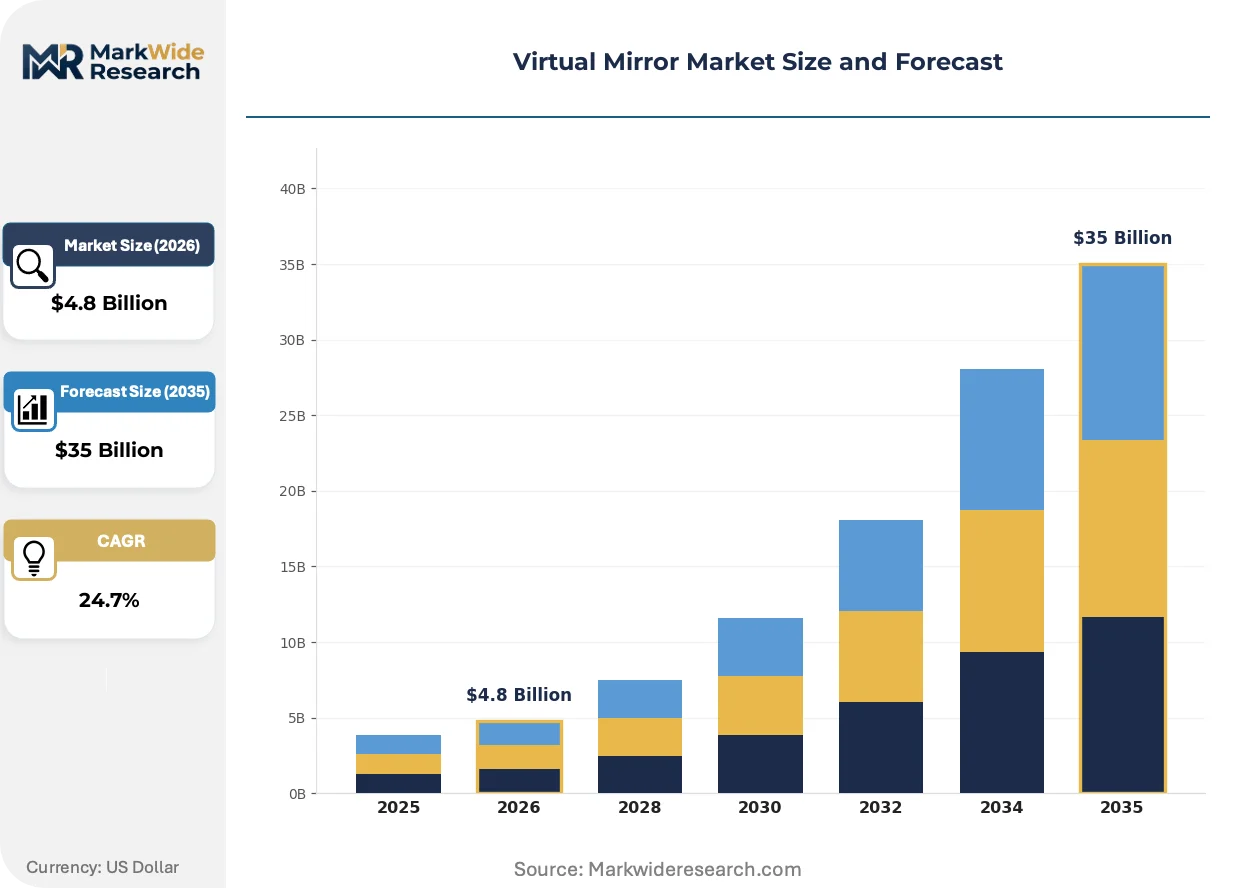
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $35 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Mirrors, AR Mirrors, Digital Signage, Interactive Displays End User: Retail Stores, Beauty Salons, Fitness Centers, Showrooms Technology: Gesture Recognition, Voice Control, Computer Vision, Augmented Reality Application: Virtual Try-On, Home Decor, Fitness Training, Customer Engagement |
| Companies Covered | Perfect Corp., Zugara, FittingBox, My Size, Metail, ModiFace, MemoMi Labs, Virtusize, Cisco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Mirror Market Emerging Trajectories
Edge AI inference is compressing latency benchmarks while fragmenting vendor architectures, forcing strategic bets between cloud-dependent and fully localized processing stacks.
Neural radiance fields (NeRF) are decentralizing 3D asset creation for virtual mirrors, eliminating dependency on pre-rendered product photography. United States luxury cosmetics chains adopt NeRF pipelines to generate try-on assets from sparse manufacturer images, compressing content production cycles from weeks to hours. This capability is decentralizing competitive advantage from studios with proprietary scanning hardware to retailers with in-house ML operations teams.
The EU AI Act's automated decision system disclosure requirements are reshaping European deployment architectures, mandating explainability layers for fit recommendation algorithms. Retailers in France and Germany now demand vendor documentation of training data provenance and confidence scoring methodologies. Beauty applications face the strictest scrutiny, as skin-tone matching algorithms fall under high-risk biometric classification.
Subscription-based hardware-as-a-service contracts are displacing capital expenditure models among United States mid-market apparel retailers. Chains with 50-200 locations prefer operational expenditure structures that bundle maintenance, content updates, and sensor recalibration. This shift concentrates vendor risk on uptime guarantees and accelerates consolidation toward vertically integrated providers with captive service networks.
Virtual Mirror Market Segmentation
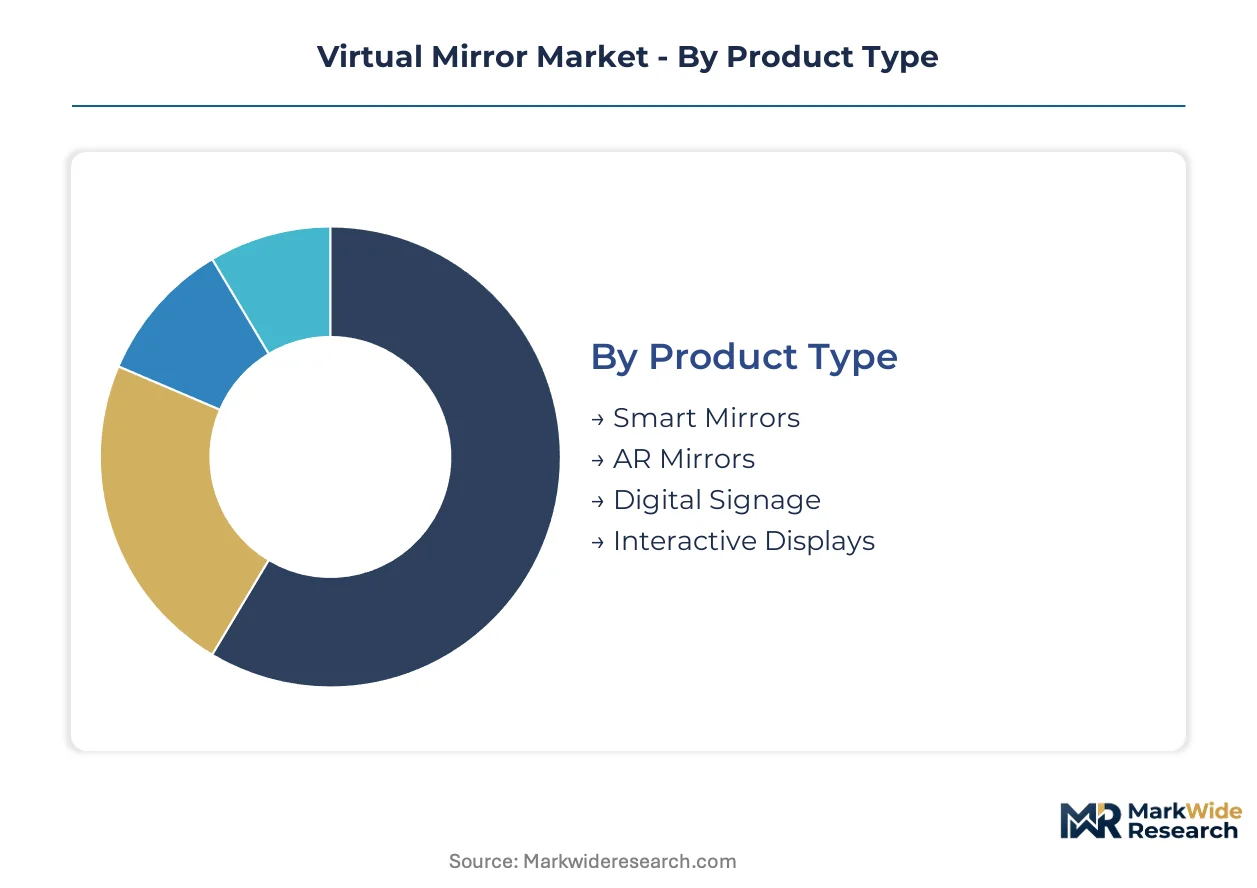
Hardware refresh cycles and software licensing models diverge sharply across virtual mirror segments. Retailers prioritize segments with measurable return-on-investment compression for garment returns and faster checkout throughput.
Product Type:
Upgrade cycles vary by sensor density and rendering engine requirements, with hygiene-sensitive installations driving faster replacement timelines.
- Smart Mirrors:These units combine reflective glass with embedded displays and basic proximity sensors for weather, news, and inventory integration. Demand concentrates in United States department stores seeking minimal-friction customer touchpoints, constrained by legacy electrical infrastructure in pre-2010 retail builds.
- AR Mirrors:Camera arrays and depth sensors overlay digital assets onto physical reflections with sub-100-millisecond latency. United States specialty cosmetics chains accelerate hardware refresh cycles here, prioritizing gesture-based interfaces that eliminate touch surfaces.
- Digital Signage:Passive display networks rotate promotional content without interactive biometric capture.
- Interactive Displays:Touch-screen kiosks with modular mounting systems serve pop-up retail activations and temporary showroom installations.
AR Mirrors sit at the top of the volume ranking, with Smart Mirrors climbing the fastest as mid-market retailers adopt entry-tier hardware bundles.
End User:
Cost tier differentiation separates enterprise-grade deployments from boutique installations with limited IT support bandwidth.
- Retail Stores:Department stores and apparel chains deploy multi-sensor kiosks at scale, with United States-based chains commanding the largest installed base. FTC scrutiny of fit-prediction accuracy shapes vendor validation protocols for this segment.
- Beauty Salons:Smaller countertop units with skin-tone matching algorithms dominate here. GDPR and EU AI Act biometric classifications force edge-computing architectures for European salon deployments, raising per-unit hardware costs.
- Fitness Centers:Motion-tracking mirrors for form correction and workout visualization.
- Showrooms:Large-format installations for furniture and automotive configurators.
Retail Stores anchor volume leadership, while Beauty Salons gain share fastest on post-pandemic hygiene protocol adoption.
Technology:
Application maturity determines whether vendors pursue cloud-dependent or fully localized processing stacks.
- Gesture Recognition:Infrared and depth-camera arrays track hand and body movements without physical contact. United States department stores prioritize this interface for hygiene compliance, driving fastest upgrade cycles among all technology categories.
- Computer Vision:Real-time occlusion handling and lighting normalization enable accurate virtual try-on rendering. Silicon Valley and Beijing engineering clusters concentrate specialized talent for this technology, creating procurement bottlenecks for vendors outside these hubs.
- Voice Control:Natural language interfaces for hands-free operation in fitness and home decor contexts.
- Augmented Reality:Spatial anchoring and surface detection for persistent digital overlays.
Computer Vision commands the largest deployment base, with Gesture Recognition expanding most quickly on hygiene-driven hardware refreshes.
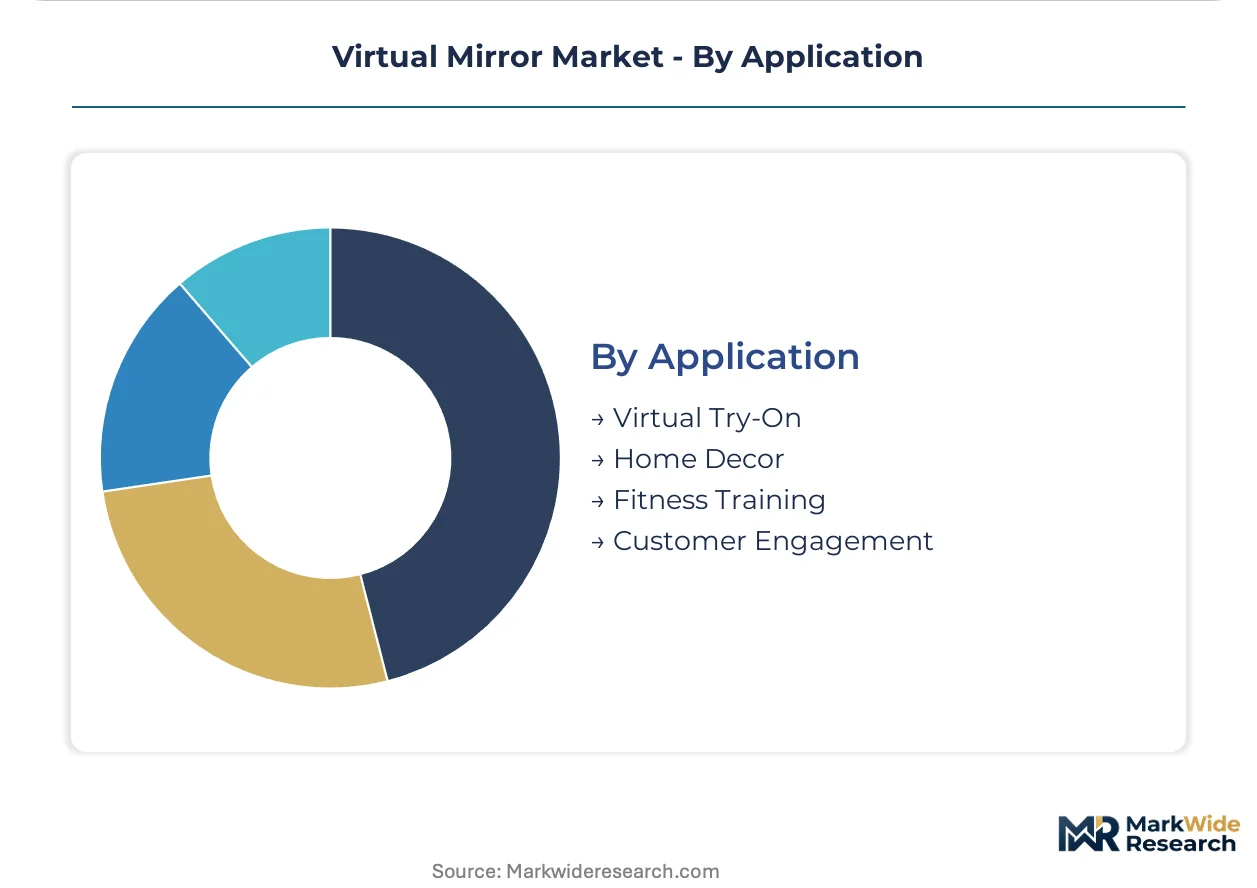
Application:
Margin pool concentration separates high-value software licensing from commoditized hardware sales.
- Virtual Try-On:Beauty and apparel fitting algorithms reduce return processing costs for mid-market fashion chains. United States retailers justify per-store investments through measurable garment return compression, while EU AI Act transparency mandates reshape European deployment architectures.
- Home Decor:Furniture visualization commands higher per-unit software licensing fees than mass apparel. United States furniture brands lead adoption here, with room-scale spatial mapping requiring more sophisticated sensor configurations than wearable try-on.
- Fitness Training:Form correction and rep counting for gym and home gym environments.
- Customer Engagement:Gamified interactions and loyalty program integration at retail touchpoints.
Virtual Try-On leads by deployment volume, with Home Decor showing the steepest expansion trajectory on premium licensing economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The virtual mirror industry traces its commercial origins to Silicon Valley and Shenzhen, where early computer vision startups converged with consumer electronics manufacturing clusters to prototype gesture-based retail interfaces during the mid-2010s.
United States
Department stores in New York and Los Angeles drive hardware refresh cycles for gesture recognition installations, prioritizing hygiene-compliant interfaces post-pandemic. FTC scrutiny of fit-prediction accuracy shapes vendor validation protocols for national retail rollouts. Silicon Valley engineering clusters concentrate scarce computer vision talent for real-time occlusion handling.
China
Shenzhen and Taipei firmware engineering hubs supply edge-computing architectures for localized biometric processing. MIIT standards on data localization constrain cloud-dependent mirror deployments, favoring domestic vendors with captive semiconductor supply chains. Yangtze River Delta retail chains pilot 5G-enabled mobile mirror activations for pop-up showrooms.
Germany
EU AI Act transparency mandates accelerate edge-computing hardware replacement across Frankfurt and Munich retail corridors. KBA and federal data protection authorities enforce biometric consent frameworks that exceed baseline GDPR requirements. Bavaria-based automotive showrooms adopt large-format configurators with spatial anchoring capabilities.
France
CNIL enforcement actions on automated decision systems reshape beauty salon deployments, forcing explainability layers for skin-tone matching algorithms. Paris department stores demand vendor documentation of training data provenance for high-risk biometric classifications. Île-de-France cosmetics chains anchor European premium positioning for virtual try-on stations.
India
Department store modernization in Mumbai and Delhi offers first-mover positioning before localized sizing databases mature for apparel applications. BIS certification requirements for imported sensor arrays create procurement friction for international vendors. Karnataka and Maharashtra retail corridors concentrate pilot deployments for countertop mirror formats targeting boutique cosmetics retailers.
Virtual Mirror Market Vendor Landscape
Premium-margin players sit above commodity-margin players across software licensing depth and sensor integration sophistication. The vendor base stratifies between vertically integrated hardware-software bundles and modular component suppliers. Three archetypes dominate: computer vision specialists anchoring beauty try-on deployments, gesture recognition pure-plays serving apparel hygiene protocols, and eyewear-focused sizing database operators with geographic lock-in. Consolidation pressures favor M&A between sensor manufacturers and rendering engine developers, while capacity expansion concentrates in Shenzhen and Taipei firmware engineering clusters.
Within the computer vision specialist tier, Perfect Corp. and ModiFace exemplify premium positioning through proprietary rendering libraries. Zugara occupies a position among gesture recognition pure-plays, while FittingBox anchors the eyewear sizing database archetype with European chain penetration. These three companies represent distinct competitive vectors: beauty algorithm depth, contactless interface specialization, and vertical industry data moats.
| Leading Market Players |
|---|
| Perfect Corp. |
| Zugara |
| FittingBox |
| My Size |
| Metail |
| ModiFace |
| MemoMi Labs |
| Virtusize |
| Cisco Systems |
| Others |
Supply Flow & Price Mechanics
EU AI Act transparency mandates gate qualified supply and premium-tier pricing access for vendors serving European beauty salons and retail chains, forcing edge-computing hardware bundles that command licensing premiums over cloud-dependent alternatives while excluding uncertified competitors from high-margin biometric processing contracts.
Pricing Analysis
Subscription-based hardware-as-a-service contracts now dominate United States mid-market apparel retail, with chains preferring operational expenditure structures that bundle sensor recalibration and content updates. Price differentiation separates gesture-enabled AR mirror installations from basic smart mirror formats, with hygiene certification tiers and after-sales service bundling as key drivers. Pricing pressure stems from GPU supply concentration constraining vendor margins, while boutique cosmetics retailers exhibit highest price sensitivity against enterprise department store buyers.
Supply Chain Analysis
Freight costs for LiDAR modules and depth sensors from Shenzhen and Taipei firmware hubs elevate landed costs for European and North American deployments. Component sourcing draws from Taiwan semiconductor foundries, South Korea display panel manufacturers, and China-based camera array assemblers. Single-source vulnerability in NVIDIA rendering chips creates procurement bottlenecks. Distribution runs through vertically integrated providers with captive service networks rather than modular component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The virtual mirror market functions as a regulatory compounder, with EU AI Act biometric classification mandates accelerating hardware replacement cycles and reshaping vendor competitive positions across European retail corridors.
For Market Incumbents: To counter gesture recognition pure-plays eroding touch-based installed bases, anchor defensive positioning through backward integration into edge-computing semiconductor supply chains and accelerate ISO/IEC 30107-3 biometric certification timelines. Prioritize captive firmware engineering capacity in Shenzhen and Taipei to reduce cloud-to-edge migration costs and sustain service-level guarantees under subscription contract structures. For New Entrants and Emerging Players: NeRF-based 3D asset pipelines offer a technology-first wedge for penetrating United States luxury cosmetics chains seeking compressed content production cycles. Target India's department store modernization in Mumbai and Delhi before localized sizing databases mature, deploying countertop mirror formats with minimal legacy POS integration requirements. Pursue direct partnerships with furniture brands in the United States home decor segment where per-unit software licensing fees exceed mass apparel economics. For Investors and Strategic Acquirers: Valuations sit cheapest among computer vision specialists lacking proprietary rendering libraries or gesture recognition pure-plays without vertical service networks. Long-term viability over the mid-decade window hinges on regulatory compliance infrastructure rather than hardware differentiation alone. Monitor ISO/IEC 30107-3 certification completion rates as the signal indicating which vendors can access European financial services and high-risk biometric classification contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Architecture Deployment | EU AI Act compliance enables market access for biometric processing in French and German retail chains. |
| NeRF Pipeline Integration | United States luxury cosmetics retailers compress content production from weeks to hours using sparse manufacturer images. |
| Hardware-as-a-Service Contract Transition | Mid-market United States apparel chains shift capital expenditure risk to vendor uptime guarantees. |
| Gesture Recognition Interface Refresh | Post-pandemic hygiene protocols in United States department stores accelerate replacement cycles. |
| Localized Sizing Database Development | India market entry requires proprietary fit algorithms before international database maturity. |
Methodological Framework
Multiple input streams — primary interviews with virtual mirror vendor executives, retail technology procurement officers, and computer vision engineering leads; secondary validation against SEC filings, EU regulatory databases, and hyperscaler capex disclosures; plus customs records for sensor array trade flows — were reconciled through bottom-up and top-down triangulation to construct segment-level estimates.
Historical shipment data for AR mirror and smart mirror installations were cross-referenced against panel input from retail chain technology directors to model adoption curves across the projection horizon. The analytical framework segmented by product type, end user, technology, and application while incorporating regulatory compliance tier and geographic data localization requirements as industry-specific forecast inputs. CAGRs were derived from weighted average growth assumptions across these dimensions.
The model holds under stable EU AI Act enforcement and continued GPU supply concentration; deviation in biometric consent fragmentation across United States state jurisdictions or accelerated edge-AI chip diversification would shift vendor competitive positioning and hardware refresh timelines. Stakeholders should weight assumptions against their own operating context and regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Automotive AR and VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
AR/VR Chip Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Location-Based Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Japan Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Retail Market
Virtual Reality (VR) and Augmented Reality (AR)
India Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Germany Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive Augmented Reality (AR) HUD System Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual and Augmented Reality in Tourism Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) in Healthcare Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Glasses Market