
 Augmented Reality Automotive Market | 2026-2036
Augmented Reality Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Augmented Reality Automotive Market Analysis
The AR software stack is fragmenting across proprietary operating systems, open middleware layers, and vehicle-specific rendering engines. Continental AG leverages its sensor fusion expertise to anchor hardware-software integration for head-up displays. Robert Bosch GmbH competes through manufacturing scale in optical combiner production. WayRay AG specializes in holographic windshield technology for premium OEM programs.
Augmented Reality Automotive denotes systems that overlay digital information—speed, navigation vectors, hazard alerts—onto the driver's field of view through head-up displays, smart glasses, or windshield projection, typically operating at latency thresholds below 50 milliseconds to prevent motion sickness and preserve reaction times. Head-Up Displays dominate current revenue as mature TFT and DLP projection modules achieve cost parity with conventional instrument clusters. Smart Glasses represent the fastest-growing technology segment as micro-LED waveguide displays reduce unit weight below 80 grams for fleet maintenance applications. Software Solutions command the widest margin pools where recurring licensing models attach to vehicle lifecycle data streams.
NHTSA distraction guidelines, EU General Safety Regulation pedestrian detection mandates, and ISO 26262 functional safety standards collectively shape product certification timelines and OEM procurement criteria. The EU AI Act's risk classification for real-time driver monitoring systems adds compliance layers to biometric-integrated AR interfaces. Stakeholders must monitor regulatory divergence between U.S. voluntary guidelines and binding European type-approval requirements when allocating R&D across regional product variants.
Market Dynamics
Windshield-projected AR interfaces are compressing development cycles as NHTSA distraction guidelines and EU General Safety Regulation mandates force simultaneous compliance across dual certification tracks, fragmenting R&D resource allocation.
Growth Catalysts
- EU pedestrian visibility mandates:The EU General Safety Regulation requires augmented hazard alerts for vulnerable road users, forcing HUD integration into vehicle type-approval pathways.
- Micro-LED waveguide maturation:Display luminance thresholds above 10,000 nits now enable daylight-readable AR overlays without mechanical visors.
- Germany's engineering corridor concentration:OEM-Tier-1 co-location around Stuttgart and Munich accelerates holographic combiner prototyping cycles.
Market Restraints
- Optical combiner supply concentration:DLP and laser-scanning module production clusters in East Asian foundries, creating single-source vulnerability for European HUD programs.
- ISO 26262 ASIL-D certification costs:Functional safety validation for windshield-projected critical alerts consumes 18-24 month development buffers.
- Windshield glass specification lock-in:PVB interlayer refractive index tolerances restrict aftermarket retrofit compatibility to OEM-specified glass suppliers.
Strategic Opportunities
- Fleet maintenance smart glasses:Micro-LED waveguides below 80 grams enable technician AR guidance for electric vehicle battery servicing workflows.
- EU AI Act biometric integration:Real-time driver monitoring systems classified as high-risk AI create compliance-driven demand for gaze-tracking HUDs.
- Insurance-telematics convergence:Usage-based pricing models reward vehicles with AR hazard anticipation, creating channel partnerships between insurers and HUD suppliers.
Industry Challenges
- Optical engineer scarcity:Freeform surface design expertise for wide-field-of-view combiners concentrates in German and Japanese research institutes.
- Legacy CAN bus integration:AR rendering engines must translate 500 kbps vehicle data streams into sub-50 millisecond visual latency without fiber optic backbone retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Augmented Reality Automotive Market |
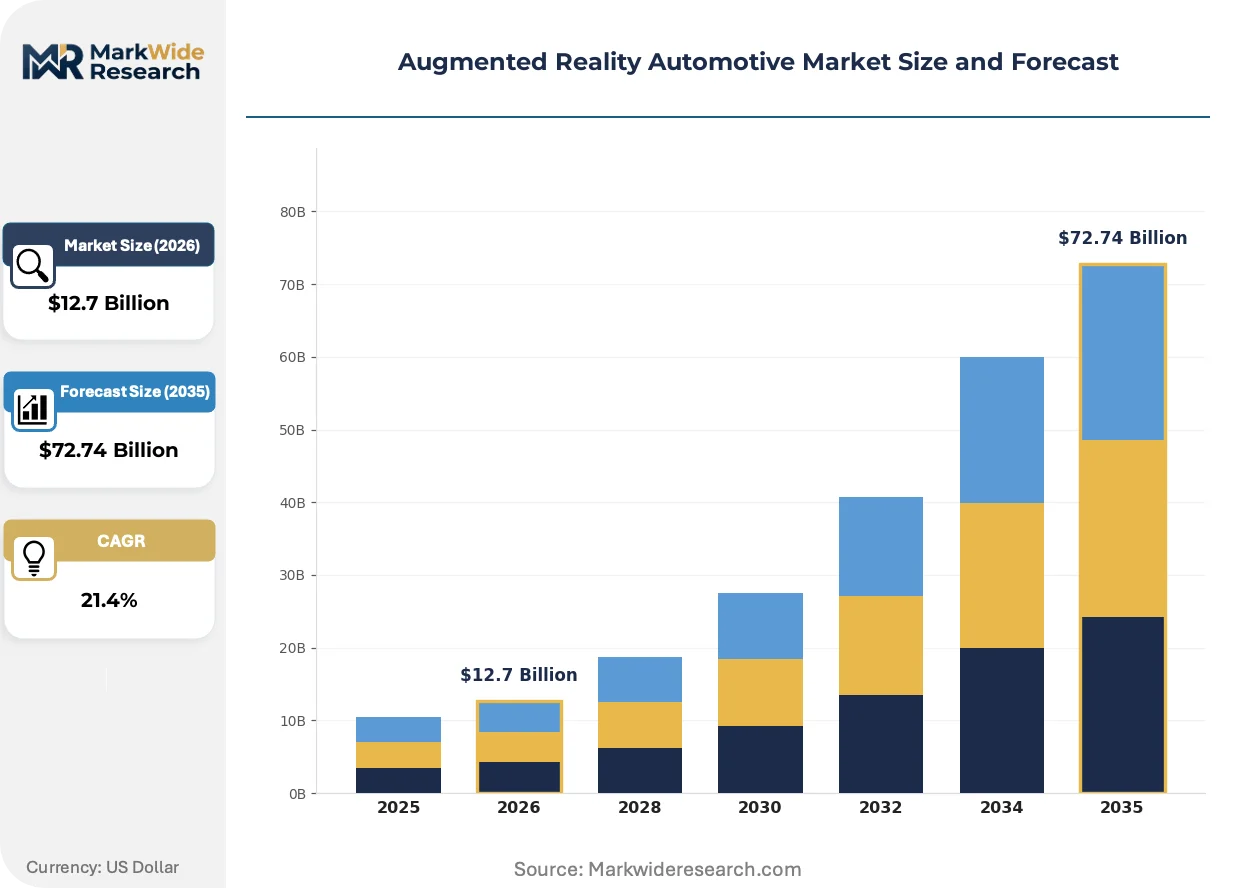
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $72.74 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Navigation, Maintenance, Training, Entertainment Technology: Head-Up Displays, Smartphone Integration, Smart Glasses, Mixed Reality End User: OEMs, Aftermarket Providers, Fleet Operators, Consumers Product Type: Software Solutions, Hardware Kits, Integration Services, Development Platforms |
| Companies Covered | Panasonic Connect, WayRay AG, Continental AG, BMW Group, Xreal, Denso Corporation, Robert Bosch GmbH, Volkswagen AG, Visteon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Augmented Reality Automotive Market Emerging Trajectories
Holographic waveguide technology is collapsing the boundary between head-up displays and full-windshield immersion, while regulatory divergence between voluntary U.S. guidelines and binding European type-approval forces parallel certification investments.
Freeform holographic optical elements are hybridizing conventional geometric optics with diffractive architectures, enabling 15-degree horizontal fields of view in compact package volumes. Premium OEM programs in Germany and California are qualifying these combiners for 2027 model year integration. The technology is hybridizing hardware roadmaps previously split between TFT-LCD and laser-scanning approaches, compressing supplier qualification timelines.
The EU AI Act's risk classification framework for biometric driver monitoring is mandating algorithmic transparency documentation for gaze-tracking HUDs. Automotive suppliers must submit conformity assessments to notified bodies before type-approval, extending procurement lead times. German OEMs are responding by pre-integrating edge-AI processing units to localize biometric inference and reduce cloud dependency.
After-sales service unbundling is fragmenting AR software licensing from hardware procurement, with Tier-1 suppliers retaining recurring revenue from navigation and hazard alert updates. Fleet operators in the United States are resisting perpetual license models, preferring consumption-based pricing tied to active vehicle mileage. This tension is most visible in long-haul trucking segments where HUD utilization correlates directly with route complexity.
Augmented Reality Automotive Market Segmentation
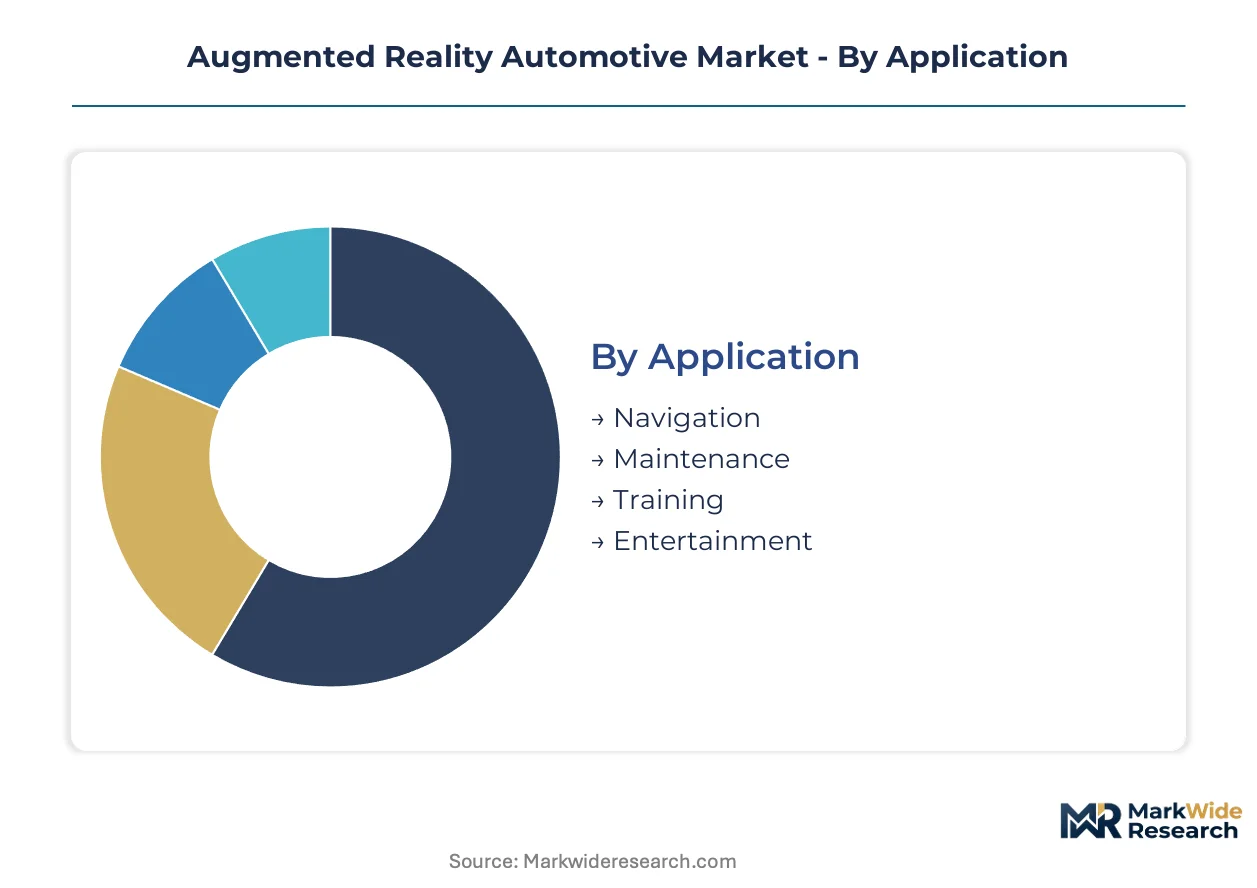
AR automotive systems fragment across hardware maturity curves and software monetization models. Each segmentation axis reveals divergent margin structures, certification requirements, and customer procurement behaviors that shape supplier strategy.
Application:
Navigation commands the largest installed base, while maintenance and training applications are climbing the fastest as fleet electrification creates new technician guidance requirements.
- Navigation:Head-up display overlays project turn-by-turn vectors and hazard alerts onto the driver's forward field of view. Demand concentrates in Germany and the United States where NHTSA guidelines and EU General Safety Regulation mandates force OEM integration into type-approval pathways.
- Maintenance:Technician smart glasses deliver AR-guided battery servicing workflows for electric vehicle fleets. Adoption is expanding most quickly among fleet operators managing mixed ICE-EV vehicle pools where specialized high-voltage training gaps persist.
- Training:Immersive simulation modules reduce driver onboarding time for commercial fleets through repeated exposure to rare hazard scenarios without road risk.
- Entertainment:Passenger-facing AR content remains nascent due to NHTSA distraction guidelines limiting non-essential visual elements in driver sightlines.
Established volume favors Navigation; emerging adoption favors Maintenance.
Technology:
Cost tiers separate mature projection modules from emerging waveguide architectures, with manufacturing scale determining competitive viability.
- Head-Up Displays:TFT-LCD and DLP projection modules achieve cost parity with conventional instrument clusters through East Asian foundry scale. Procurement concentrates among German OEMs qualifying holographic combiners for premium vehicle programs.
- Smart Glasses:Micro-LED waveguide displays now deliver daylight-readable luminance above 10,000 nits in packages below 80 grams. Fleet maintenance applications in the United States are driving unit volume as technician guidance workflows prove ROI through reduced service times.
- Smartphone Integration:Screen mirroring and AR navigation apps leverage existing device penetration but suffer from NHTSA distraction guideline compliance gaps for windshield mounting.
- Mixed Reality:Full-windshield holographic immersion remains pre-commercial, constrained by ISO 26262 ASIL-D certification timelines stretching 18-24 months.
Manufacturing scale advantages Head-Up Displays; steepest expansion trajectory belongs to Smart Glasses.
End User:
Customer type determines pricing power, with recurring software licensing attaching to OEM and fleet contracts while consumer purchases favor one-time hardware transactions.
- OEMs:Direct supplier relationships with Tier-1 HUD manufacturers bundle hardware procurement with multi-year navigation and hazard alert update licenses. EU type-approval requirements lock in windshield glass specifications, creating captive supply chains.
- Fleet Operators:Long-haul trucking and delivery fleets in the United States resist perpetual license models, preferring consumption-based pricing tied to active mileage and route complexity.
- Aftermarket Providers:Retrofit HUD installations face PVB interlayer refractive index compatibility constraints limiting addressable vehicles to OEM-specified glass configurations.
- Consumers:Direct purchases concentrate in smartphone-integrated AR apps and low-cost HUD accessories with minimal regulatory compliance overhead.
Contractual recurring revenue concentrates with OEMs; pricing pressure intensifies for Aftermarket Providers.
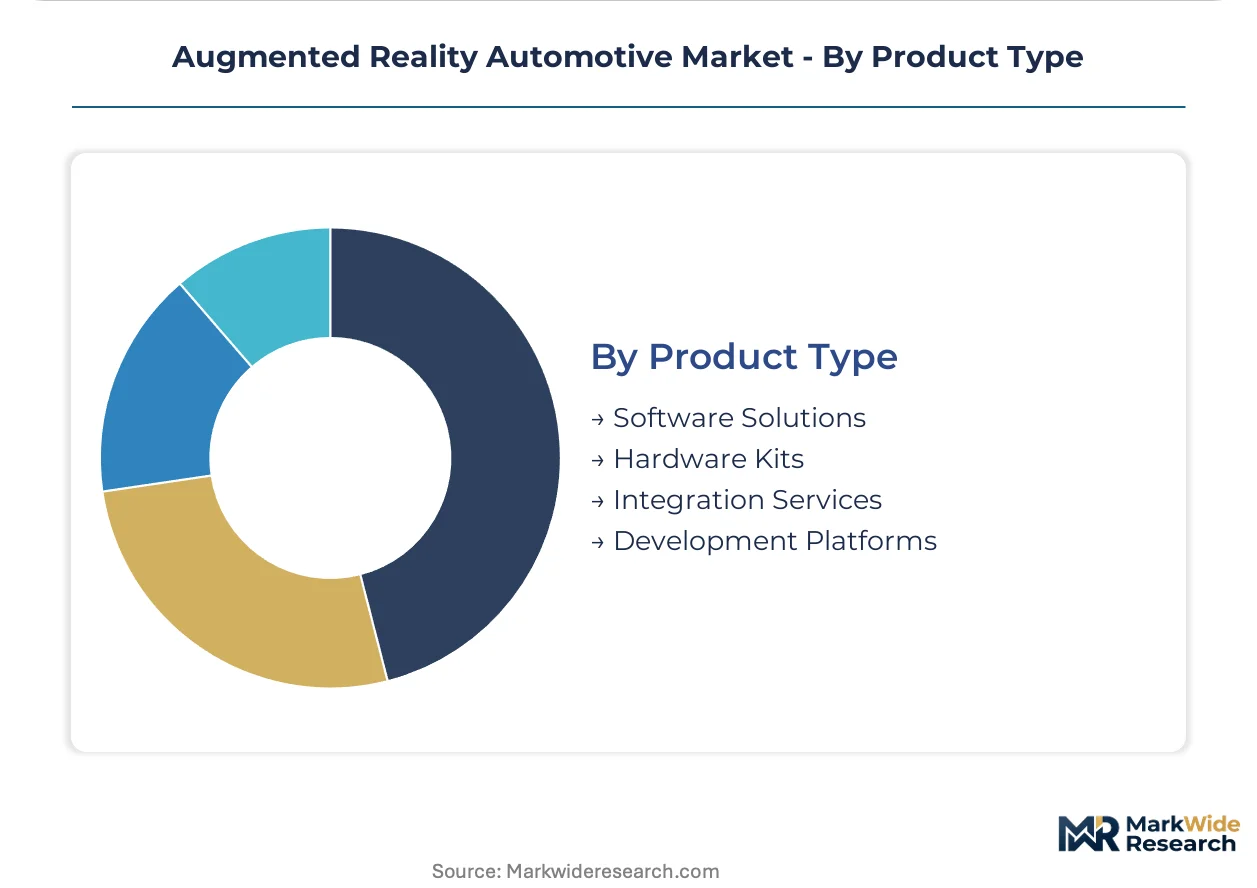
Product Type:
Margin pools diverge sharply between hardware commoditization and software retention economics.
- Software Solutions:Navigation engines, hazard alert algorithms, and gaze-tracking biometric systems command the widest margins through recurring licensing models. EU AI Act high-risk AI classification for driver monitoring systems adds compliance-driven demand layers.
- Hardware Kits:Projection modules, optical combiners, and sensor fusion assemblies face cost pressure from DLP and laser-scanning production concentration in East Asian foundries.
- Integration Services:Vehicle-specific calibration and CAN bus legacy system adaptation consume engineering resources without scale economies.
- Development Platforms:SDKs and middleware layers for OEM-Tier-1 co-development programs concentrate around Stuttgart and Munich engineering corridors.
Recurring licensing economics favor Software Solutions; supply concentration challenges Hardware Kits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEM procurement teams and United States fleet operators drive the majority of AR automotive system demand, with engineering talent concentration and regulatory divergence pulling supplier investment toward Stuttgart, Munich, Detroit, and Silicon Valley.
Germany
Stuttgart and Munich host the densest OEM-Tier-1 co-development corridors for holographic combiner prototyping. KBA type-approval requirements for EU General Safety Regulation pedestrian visibility mandates force windshield-integrated AR into vehicle certification pathways. Baden-Württemberg engineering clusters around Continental AG and Robert Bosch GmbH anchor optical component supply chains for premium vehicle programs.
United States
NHTSA distraction guidelines create dual-track compliance pressure alongside European standards for exporters, fragmenting R&D allocation. Long-haul trucking fleets in the Midwest and Southeast resist perpetual software licenses, pushing consumption-based pricing models tied to route mileage. Michigan and California engineering centers concentrate legacy CAN bus integration expertise for sub-50 millisecond latency requirements.
China
MIIT standards for intelligent connected vehicles accelerate domestic HUD adoption across passenger vehicle segments. Shenzhen and Shanghai micro-LED foundries achieve daylight-readable luminance thresholds above 10,000 nits, reducing dependence on East Asian optical module imports. GB standards for driver information systems increasingly reference ISO 26262 functional safety benchmarks.
Japan
METI technology roadmaps prioritize AR integration for aging-driver assistance applications in rural prefectures. Nagoya-area automotive electronics suppliers develop compact DLP projection modules for kei-car segment cost constraints. JIS standards for vehicle display legibility shape procurement criteria for domestic OEM programs.
South Korea
Seoul Capital Area display panel manufacturers supply TFT-LCD modules to German Tier-1 integrators under captive supply arrangements. MFDS automotive safety guidelines align with ISO 26262 ASIL-D certification timelines for windshield-projected critical alert systems. Busan-Ulsan shipbuilding expertise transfers to freeform optical surface design for wide-field-of-view combiners.
Augmented Reality Automotive Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Tier-1 automotive suppliers with captive OEM relationships dominate hardware procurement volumes, while optical technology specialists capture premium positioning through holographic windshield innovation. Consolidation pressure intensifies as ISO 26262 certification costs favor scaled players with 18-24 month development buffers. Strategic moves concentrate on backward integration into optical combiner production and geographic co-location with German engineering corridors.
Within the integrated Tier-1 tier, Continental AG exemplifies sensor fusion-to-display system bundling, while Robert Bosch GmbH represents manufacturing scale advantages in optical component production. WayRay AG occupies a specialist position in holographic windshield technology for premium OEM qualification programs. These three entities anchor the competitive structure without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| Panasonic Connect |
| WayRay AG |
| Continental AG |
| BMW Group |
| Xreal |
| Denso Corporation |
| Robert Bosch GmbH |
| Volkswagen AG |
| Visteon Corporation |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor's container rate volatility feeds directly into optical combiner landed costs, compressing margins for European HUD integrators while amplifying price spreads between captive OEM supply and aftermarket retrofit tiers.
Pricing Analysis
Cost-plus contracts with rare-earth magnet indexation dominate DLP module procurement, locking German Tier-1 suppliers into margin volatility while ISO 26262 ASIL-D certification grade separates premium holographic combiners from standard TFT-LCD alternatives. Pricing pressure stems from East Asian foundry scale advantages in laser-scanning production, eroding European optical component margins. Fleet operators exhibit highest price sensitivity through consumption-based licensing resistance, whereas OEM captive programs tolerate premium hardware bundling for type-approval compliance.
Supply Chain Analysis
Tariff exposure between China and Germany dominates optical component sourcing strategies for windshield-projected AR systems. DLP and micro-LED waveguide production concentrates in China, South Korea, and Taiwan, drawing from gallium nitride substrates, precision glass substrates, and rare-earth phosphor dependencies. Single-source vulnerability in freeform surface design expertise creates qualification bottlenecks. Distribution runs through Tier-1 automotive supplier networks with direct OEM platform integration, bypassing traditional aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AR automotive systems are approaching a platform-economics inflection where middleware interoperability between OEM operating systems and Tier-1 sensor fusion stacks determines ecosystem control, with the shift toward open rendering engines fragmenting previously proprietary software architectures.
For Market Incumbents: Entrench sensor fusion-to-display bundling through backward integration into holographic combiner production, defending against waveguide specialists capturing premium windshield real estate. Prioritize KBA type-approval pre-certification investments to compress OEM procurement lead times and lock out second-source qualification attempts.
For New Entrants and Emerging Players: Build out fleet maintenance smart glasses distribution through technician workflow software partnerships, targeting Midwest long-haul trucking depots where high-voltage EV servicing training gaps persist. Lead with consumption-based pricing models that align HUD utilization with route complexity billing.
For Investors and Strategic Acquirers: Optical engineering boutiques with freeform surface design capabilities and existing Continental AG or Robert Bosch GmbH supplier relationships represent the most defensible acquisition profile across the analysis window. Monitor EU AI Act notified body queue lengths as the inflection signal for biometric-integrated HUD compliance demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Middleware Platform Standardization | Open rendering engine adoption reduces OEM lock-in and fragments proprietary software margins. |
| Holographic Combiner Backward Integration | In-house production of freeform optical elements secures supply continuity for ASIL-D programs. |
| EU AI Act Compliance Pre-Investment | Edge-AI processing localization addresses high-risk AI classification for gaze-tracking systems. |
| Fleet Maintenance Channel Partnership | Technician workflow integration captures recurring software licensing outside OEM captive structures. |
| Micro-LED Foundry Scale Expansion | Daylight-readable luminance thresholds above 10,000 nits enable outdoor AR overlay deployment. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, Tier-1 HUD procurement leads, aftermarket distributor operations, and fleet maintenance supervisors anchored the qualitative base. Primary interviews triangulated against vehicle production databases, IHS Markit registration data, SEC 10-K automotive segment disclosures, and KBA type-approval filings. Bottom-up unit economics across holographic combiner, TFT-LCD, and waveguide display architectures reconciled with top-down OEM program spending estimates.
Scenario-bracketing framed demand trajectories across the projection horizon, modeling vehicle class, propulsion architecture, content per vehicle, and regional production cluster segmentation dimensions. CAGRs derived from installed base replacement cycles and new program launch density, with ISO 26262 certification timeline buffers and EU AI Act compliance lag explicitly incorporated as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by waveguide specialists or accelerated MIIT standard adoption in China would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality (XR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market
Virtual Reality (VR) and Augmented Reality (AR)
India Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Social VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive Augmented Reality (AR) HUD System Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Holographic AR Display Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Internet of Senses Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market