
 3D Virtual Reality Glasses Market | 2026-2036
3D Virtual Reality Glasses Market Size, Share, and Industry Trends Forecast 2026-2036
3D Virtual Reality Glasses Market Intelligence
The bundling of 3D virtual reality glasses with exclusive software titles and subscription services is expanding consumer choice and platform loyalty. Meta Platforms leverages its social media ecosystem to build a content-driven VR environment. Sony Group Corporation dominates the console-tethered VR segment through its PlayStation platform. Meanwhile, HTC Corporation specializes in high-fidelity PC-VR systems for enterprise and enthusiast users.
3D virtual reality glasses are wearable devices that use stereoscopic displays, one for each eye, to create a sense of depth and immersion. These systems typically incorporate head-tracking sensors and high-refresh-rate screens, often 90Hz or higher, to deliver a seamless visual experience. Among product types, Head-Mounted Displays represent the largest segment by volume. The gaming application continues to be the primary commercial driver, with immersive entertainment following as a key growth area.
Market access is contingent on adherence to electronic device regulations. Manufacturers must secure FCC certification in the United States for radio frequency emissions and CE marking in Europe for safety and health standards. Global IEC 62368-1 standards for audio/video and IT equipment safety are also critical for component sourcing and final product approval. Future competitive advantage will hinge on balancing advanced feature integration with ergonomic design and extended battery life.
Market Dynamics
The market's central dynamic is the technological push for higher immersion versus the pull of ergonomic and cost constraints. This tension shapes development priorities, forcing trade-offs between display resolution, processing power, device weight, and final consumer price.
Growth Catalysts
- Esports Integration:The formalization of esports leagues in markets like South Korea provides a dedicated and demanding user base for high-performance VR hardware, particularly for training and immersive spectating applications.
- Micro-OLED Display Adoption:Advancements in micro-OLED technology enable the production of lighter, more compact headsets with superior pixel density and color accuracy, directly addressing user comfort and visual fidelity concerns.
- Enterprise Training Demand:The aerospace, manufacturing, and healthcare sectors are increasingly using VR for complex procedural training, creating a stable B2B demand channel for high-fidelity simulation-ready devices.
Market Restraints
- High Component Costs:The manufacturing costs for high-resolution, low-latency displays and precision optical lenses remain a primary barrier, keeping premium VR systems out of reach for mass-market consumers.
- Content Exclusivity:Platform-exclusive software titles fragment the content library, forcing consumers into specific hardware ecosystems and limiting the overall software attach rate for the market.
- Vestibular Mismatch Issues:A significant portion of users experience motion sickness or discomfort due to latency and sensory conflicts, which limits session duration and discourages long-term adoption.
Strategic Opportunities
- Telepresence and Social Platforms:Beyond gaming, a substantial opportunity exists in developing VR for remote collaboration, virtual events, and social interaction, targeting both enterprise and consumer communication markets.
- Therapeutic Applications:Untapped potential in healthcare includes using VR for pain management, exposure therapy for phobias, and physical rehabilitation, opening pathways for clinical use and insurance reimbursement.
- Location-Based Entertainment (LBE):VR arcades and dedicated installations in theme parks and family entertainment centers offer consumers a way to experience high-end VR without the cost of ownership.
Industry Challenges
- Specialized Developer Talent:A persistent shortage of software engineers and designers with expertise in optimizing 3D assets and interaction models for the unique performance constraints of VR hardware slows content creation.
- Lack of Interoperability:The absence of universal standards for accessories, tracking systems, and data formats creates friction for developers and locks consumers into proprietary hardware ecosystems.
- Standalone Device Battery Life:For untethered headsets, balancing processing power, display brightness, and battery capacity remains a core engineering challenge that directly impacts user experience and session length.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Virtual Reality Glasses Market |
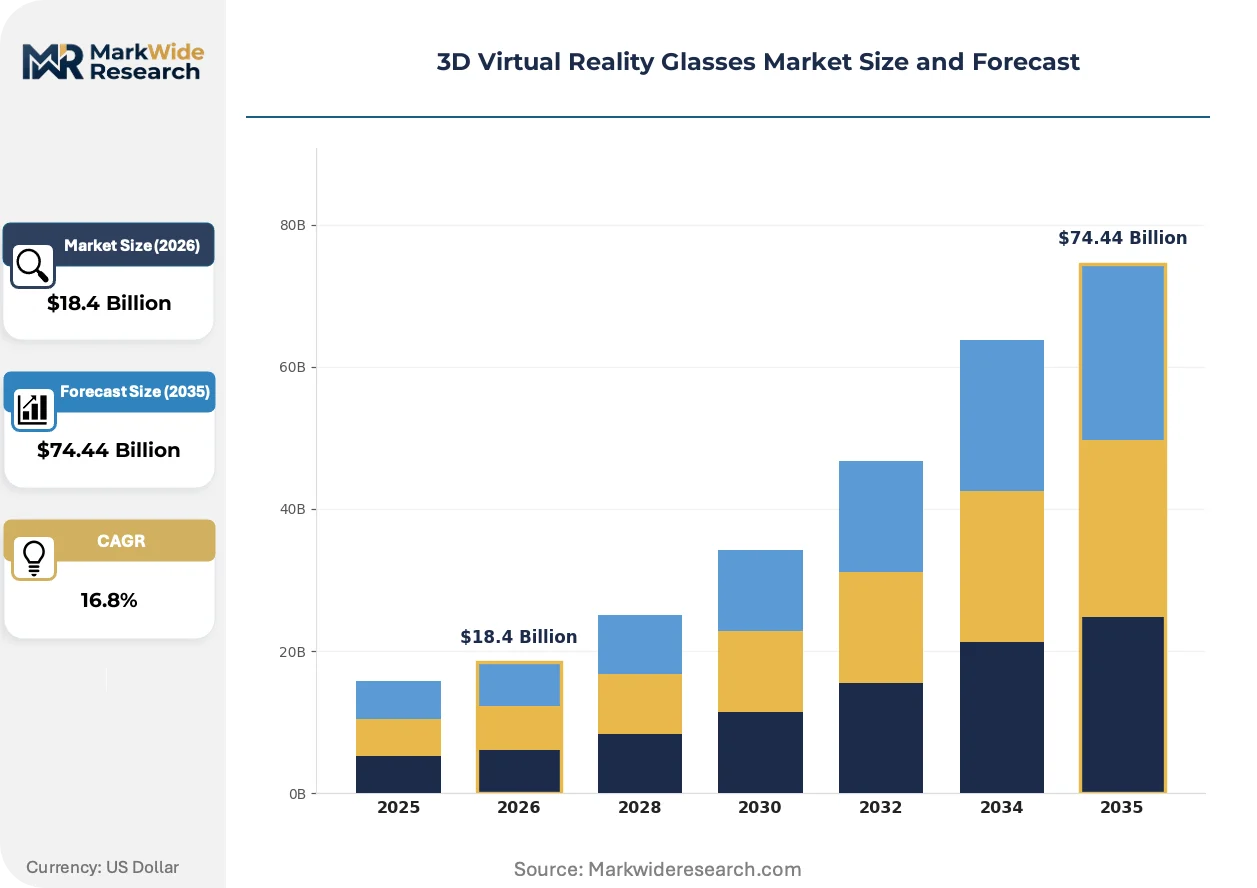
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $74.44 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Glasses, Head-Mounted Displays, VR Goggles, Mixed Reality Glasses, Gesture Control Glasses Technology: Optical See-Through, Video See-Through, Augmented Reality, Stereoscopic 3D, Light Field Application: Gaming, Education, Real Estate, Military Training, Immersive Entertainment, Virtual Tours End User: Software Developers, Design Studios, Educational Institutions, Simulation Centers, Training Organizations |
| Companies Covered | Samsung Electronics, Sony Group Corporation, Meta Platforms, Microsoft Corporation, HTC Corporation, Seiko Epson Corporation, Apple Inc., Razer Inc., Carl Zeiss AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Virtual Reality Glasses Market Strategic Shifts & Innovations
The competitive landscape is shifting from a hardware-centric race to a platform-based battle for ecosystem control. Success now depends on curating a compelling content library and fostering a loyal developer and user community to drive network effects.
Foveated rendering, a technique that uses eye-tracking to render only the user's focal point in high detail, is a key innovation. This method is being rapidly adopted by developers of next-generation standalone and PC-tethered headsets to maximize graphical fidelity. The technology is electrifying the pursuit of photorealistic visuals on power-constrained mobile chipsets, enabling experiences previously exclusive to high-end PCs.
New regulations, including the European Union's Radio Equipment Directive (RED), impose stricter compliance requirements on wireless devices. The directive mandates rigorous testing for radio frequency emissions, receiver performance, and cybersecurity vulnerabilities in products using Wi-Fi and Bluetooth. Manufacturers of standalone VR glasses targeting the EU must now integrate these compliance costs and timelines into their product development cycles.
Consumer purchasing behavior is evolving from one-time hardware sales toward subscription-based access models. This shift disrupts traditional retail channels by bundling hardware with a rotating library of games and applications for a recurring monthly fee. This trend is most visible within the console-tethered and consumer-focused standalone VR segments, mirroring business models from the broader software and media industries.
3D Virtual Reality Glasses Market Segmentation
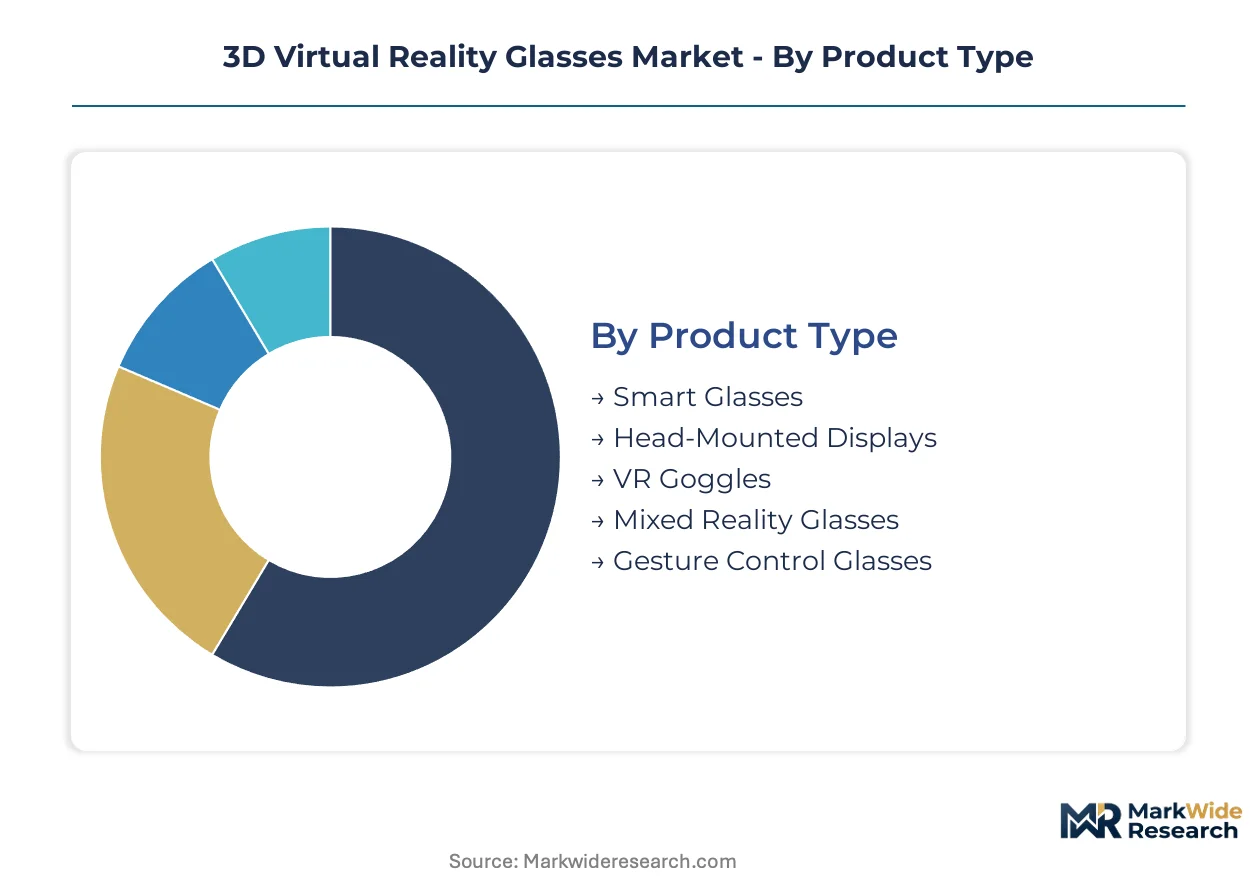
Understanding the distinct segments within the 3D Virtual Reality Glasses Market reveals how diverse user needs and technological capabilities shape product development and adoption. Each segment represents a unique value proposition, influencing investment priorities and market strategies across the industry.
Product Type:
Consumer preference for form factor and feature set dictates purchasing decisions across product types, influencing market share distribution.
- Head-Mounted Displays:These devices incorporate stereoscopic displays, head-tracking sensors, and high-refresh-rate screens, typically 90Hz or higher, for a seamless visual experience. Demand concentrates within the gaming sector for immersive experiences, particularly in markets like South Korea.
- VR Goggles:Often simpler and more portable, these devices typically use a smartphone as their display and processing unit, providing an accessible entry point into virtual reality. Their demand is strong for casual entertainment and basic virtual tours, appealing to a broad consumer base.
- Smart Glasses:These devices overlay digital information onto the real world, often featuring transparent displays and integrated cameras for augmented reality applications.
- Mixed Reality Glasses:Combining elements of both virtual and augmented reality, these glasses allow users to interact with virtual objects within their physical environment.
- Gesture Control Glasses:These advanced wearables integrate sensors that track hand and finger movements, enabling intuitive interaction with virtual interfaces without physical controllers.
Volume sits with Head-Mounted Displays; growth tilts toward Mixed Reality Glasses, representing the fastest-growing trajectory.
Technology:
The intended application dictates the underlying technological approach for rendering virtual environments, impacting visual fidelity and user interaction.
- Stereoscopic 3D:This foundational technology presents slightly different images to each eye, creating the illusion of depth and immersion essential for virtual reality experiences. Demand for Stereoscopic 3D remains high in entertainment and gaming, forming the core of consumer VR.
- Light Field:Capturing light rays from all directions, this advanced technology aims to create truly photorealistic 3D environments, potentially eliminating the need for traditional stereoscopic rendering. Its demand is emerging in high-fidelity simulation and professional design applications.
- Optical See-Through:This technology uses transparent lenses to project virtual images directly into the user's field of view, allowing interaction with digital content while seeing the real world.
- Video See-Through:Utilizing external cameras to capture the real world and then overlaying virtual content onto the video feed, this method offers flexibility in blending digital and physical realities.
- Augmented Reality:This technology superimposes computer-generated images onto a user's view of the real world, enhancing perception with digital information.
The evolution of display technologies is enhancing user immersion and expanding application possibilities.
Application:
The scale of user engagement and revenue generation varies significantly across diverse application areas, highlighting commercial priorities.
- Gaming:As the primary commercial driver, this application leverages VR for profoundly immersive interactive experiences, from competitive esports to narrative-driven adventures. Esports integration provides a dedicated user base, especially in regions with advanced infrastructure.
- Immersive Entertainment:This segment includes virtual concerts, cinematic VR, and interactive storytelling, offering passive or semi-interactive experiences beyond traditional gaming. Location-Based Entertainment venues are increasingly adopting this for shared, high-end experiences.
- Education:VR is used for interactive learning simulations, virtual field trips, and complex subject visualization, enhancing student engagement and comprehension.
- Real Estate:Virtual tours of properties allow potential buyers to explore spaces remotely, reducing the need for physical visits and expanding market reach.
- Military Training:High-fidelity simulations provide realistic training environments for soldiers, improving tactical skills and situational awareness in safe settings.
- Virtual Tours:Beyond real estate, VR enables virtual exploration of museums, historical sites, and travel destinations, offering accessible cultural experiences.
Market expansion is driven by established consumer uses while specialized B2B applications present significant long-term value.
End User:
Specific operational requirements and technical expertise differentiate the purchasing priorities of various end-user groups, shaping demand for specialized features.
- Software Developers:These users require robust development kits, powerful computing resources, and flexible hardware to create and optimize content for VR platforms. Their demand drives the overall growth and innovation within the VR ecosystem.
- Simulation Centers:These facilities utilize VR for highly precise and realistic training scenarios across industries like aerospace, healthcare, and manufacturing. Enterprise training demand creates a stable B2B channel for high-fidelity devices.
- Design Studios:These entities leverage VR for product prototyping, architectural visualization, and collaborative design reviews, enhancing efficiency and reducing physical mock-up costs.
- Educational Institutions:Schools and universities adopt VR for experiential learning, scientific visualization, and remote collaboration, providing engaging instructional tools.
- Training Organizations:Businesses and professional bodies use VR to deliver scalable and consistent training modules for employee skill development and procedural instruction.
Content creators drive ecosystem value, while specialized institutional users ensure consistent demand for high-fidelity devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The market for 3D virtual reality glasses presents a clear divide between regions driving technological innovation and those leading in consumer adoption. Asia-Pacific nations primarily anchor consumption and manufacturing, while North America and Europe focus on advanced R&D and establishing regulatory frameworks. This dynamic interplay shapes market development and investment priorities globally.
United States
Demand for 3D virtual reality glasses in the United States is strong within the gaming sector and for enterprise training applications. FCC certification is mandatory for radio frequency emissions from these electronic devices. Silicon Valley continues to be a central hub for VR hardware and software development, fostering innovation across the ecosystem.
South Korea
South Korea exhibits significant demand for immersive entertainment and advanced consumer technology, driven by its robust esports infrastructure. The country's Ministry of Science and ICT actively supports digital content and VR technology initiatives. Seoul serves as a key center for competitive esports leagues and cutting-edge VR content creation.
Germany
Germany sees substantial demand from industrial sectors for enterprise training, particularly in manufacturing and automotive applications. CE marking compliance is essential for products sold within the European Union, ensuring safety and health standards. Munich is a prominent cluster for industrial VR applications and research into high-fidelity simulation.
China
China's market for 3D virtual reality glasses is fueled by immersive entertainment and a rapidly expanding consumer base. Manufacturers must adhere to GB standards for product quality and safety before market entry. Shenzhen remains a global powerhouse for electronics manufacturing and large-scale VR hardware production.
Japan
Japan demonstrates consistent demand for gaming and entertainment-focused VR experiences, alongside applications in design studios for prototyping. The Ministry of Economy, Trade and Industry (METI) guides industrial policy and product safety standards for consumer electronics. Tokyo leads in VR content development and consumer electronics innovation for the domestic market.
3D Virtual Reality Glasses Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a complex market structure within the 3D virtual reality glasses sector. The competitive environment blends established technology giants with agile hardware manufacturers. Strategic archetypes include platform ecosystem builders, high-fidelity hardware developers, and accessible device providers. Companies engage in continuous portfolio diversification and strategic partnerships to expand their market reach.
Platform ecosystem builders like Meta Platforms leverage extensive digital infrastructure to create comprehensive content environments. Sony Group Corporation exemplifies the console-tethered segment, integrating VR into existing gaming platforms and expanding its consumer base. HTC Corporation represents high-fidelity PC-VR systems, targeting enterprise and enthusiast users with advanced hardware solutions.
| Leading Market Players |
|---|
| Samsung Electronics |
| Sony Group Corporation |
| Meta Platforms |
| Microsoft Corporation |
| HTC Corporation |
| Seiko Epson Corporation |
| Apple Inc. |
| Razer Inc. |
| Carl Zeiss AG |
| Others |
Cost & Logistics Intelligence
The semiconductor manufacturing cost index, reflecting specialized chipsets and micro-OLED displays, directly cascades through the 3D virtual reality glasses supply chain, influencing final product pricing tiers. This cost structure compels manufacturers to balance advanced feature integration with accessible consumer pricing.
Pricing Analysis
Margin compression across the premium VR headset segment traces to intense competition and high component costs for displays and optical lenses. The dominant pricing structure involves per-unit transactional sales for hardware, often bundled with subscription-based content services. Price differentiation drivers include brand premium and the level of customization offered for enterprise solutions. Buyer price sensitivity is highest among casual consumers seeking entry-level VR goggles, while simulation centers prioritize performance over cost.
Supply Chain Analysis
Direct sales channels and specialized distributors handle high-performance 3D virtual reality glasses demand for enterprise and enthusiast users. Geographic supply concentration for critical components rests heavily in South Korea, China, and Japan. Raw material dependencies include specialized optical glass, micro-OLED display panels, and high-performance processors. Single-source vulnerability for advanced display technologies represents a significant structural risk. The distribution model for consumer devices often involves established electronics retailers and online platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a supply-constrained story, with micro-OLED display manufacturing capacity bottlenecks propping pricing for high-resolution devices.
For Market Incumbents: Acquire intellectual property portfolios related to foveated rendering and advanced eye-tracking algorithms. This move helps to mitigate the threat of emerging specialized hardware developers. Invest in a dedicated certification investment program for global IEC 62368-1 standards. Such an investment protects market share against regulatory shifts and ensures broader market access.
For New Entrants and Emerging Players: Launch via specialized B2B integrators targeting the enterprise training application. This strategy penetrates the less price-sensitive simulation centers segment. Focus on developing high-fidelity PC-VR systems for specific industrial niches like aerospace or healthcare. A go-to-market angle emphasizing customized software solutions and robust after-sales support builds early client loyalty.
For Investors and Strategic Acquirers: Distressed-cycle entries favor agile hardware developers in Asia-Pacific with strong intellectual property in display technology. Long-term viability for this market hinges on overcoming vestibular mismatch issues and extending battery life for standalone devices. A signal to watch for inflection is the widespread adoption of foveated rendering in consumer-grade headsets.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Display Manufacturing Investment | Securing next-generation micro-OLED panel supply mitigates component scarcity and ensures visual fidelity for future products. |
| Content Ecosystem Expansion | Bundling exclusive software titles with hardware drives platform loyalty and expands the user base for Meta Platforms. |
| Ergonomic Design R&D | Improving device comfort and reducing weight directly addresses vestibular mismatch issues and extends user session duration. |
| Regulatory Compliance Streamlining | Efficiently obtaining FCC certification and CE marking speeds market entry and reduces compliance costs for new devices. |
| Location-Based Entertainment Partnerships | Collaborating with theme parks offers consumers high-end VR experiences without the burden of individual ownership. |
Research Approach
Document review covered industry reports, academic publications, and regulatory filings, complemented by interviews with VR hardware engineers, content developers, and enterprise procurement managers. This primary research gathered insights on technological advancements and market adoption patterns. Secondary data sources included company annual reports, patent databases, and trade association statistics. Bottom-up and top-down triangulation validated the market size and growth projections.
Historical adoption trends cross-referenced with expert panel inputs formed the basis of the analytical framework used across the analysis window. Segmentation dimensions modeled included product type, technology, application, and end-user, with an industry-specific focus on display resolution tiers. Compound annual growth rates were derived from a weighted average of historical trends and projected future demand. Key forecast inputs included micro-OLED production capacities and gaming software release schedules.
Component scarcity, regulatory shifts, and rapid technological obsolescence are the dominant revision risks for market forecasts. Forecasts reflect assumptions regarding consumer adoption rates and enterprise spending on training solutions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
India Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Italy Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Industrial Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Fitting Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Mobile Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Holographic AR Display Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Retail Market
Virtual Reality (VR) and Augmented Reality (AR)
Global VR for Medical Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Florida Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market