
 Global VR for Medical Market | 2026-2036
Global VR for Medical Market Size, Share, and Industry Trends Forecast 2026-2036
Global VR for Medical Market Outlook
The capital-intensity divergence between full-stack headset manufacturers and lean software developers is bifurcating competitive dynamics across the medical VR landscape. Meta Platforms, Inc. leverages its consumer VR manufacturing scale to subsidize healthcare-grade hardware development. AppliedVR, Inc. specializes in FDA-cleared pain management software that runs on third-party headsets. Osso VR anchors its position in orthopedic surgical simulation through partnerships with residency programs.
Virtual reality for medical applications encompasses head-mounted displays, haptic controllers, spatial computing software, and cloud-based content delivery platforms engineered for clinical precision, typically operating at sub-20-millisecond motion-to-photon latency to prevent simulator sickness. The technology serves to replicate anatomical environments for preoperative planning, accelerate motor skill acquisition, and deliver non-pharmacological analgesia. Hardware captures the largest revenue share due to recurring replacement cycles of headsets and tracking sensors in hospital settings. Software is expanding fastest as reimbursement codes for digital therapeutics mature across multiple jurisdictions. Services, including implementation consulting and clinician training, command premium margins where vendors bundle them with enterprise licensing agreements.
FDA breakthrough device designations shape product development roadmaps by offering expedited review pathways for VR-based surgical planning and chronic pain interventions. EMA's Medical Device Regulation and Japan's PMDA software-as-a-medical-device framework create parallel compliance requirements that vendors must navigate for multi-territory commercialization. ISO 13485 quality management standards and IEC 62304 software lifecycle processes form the baseline for regulatory submissions in most developed markets. Stakeholders must monitor evolving reimbursement decisions by CMS and analogous national health technology assessment bodies to determine which clinical indications will sustain scaled deployment.
Market Dynamics
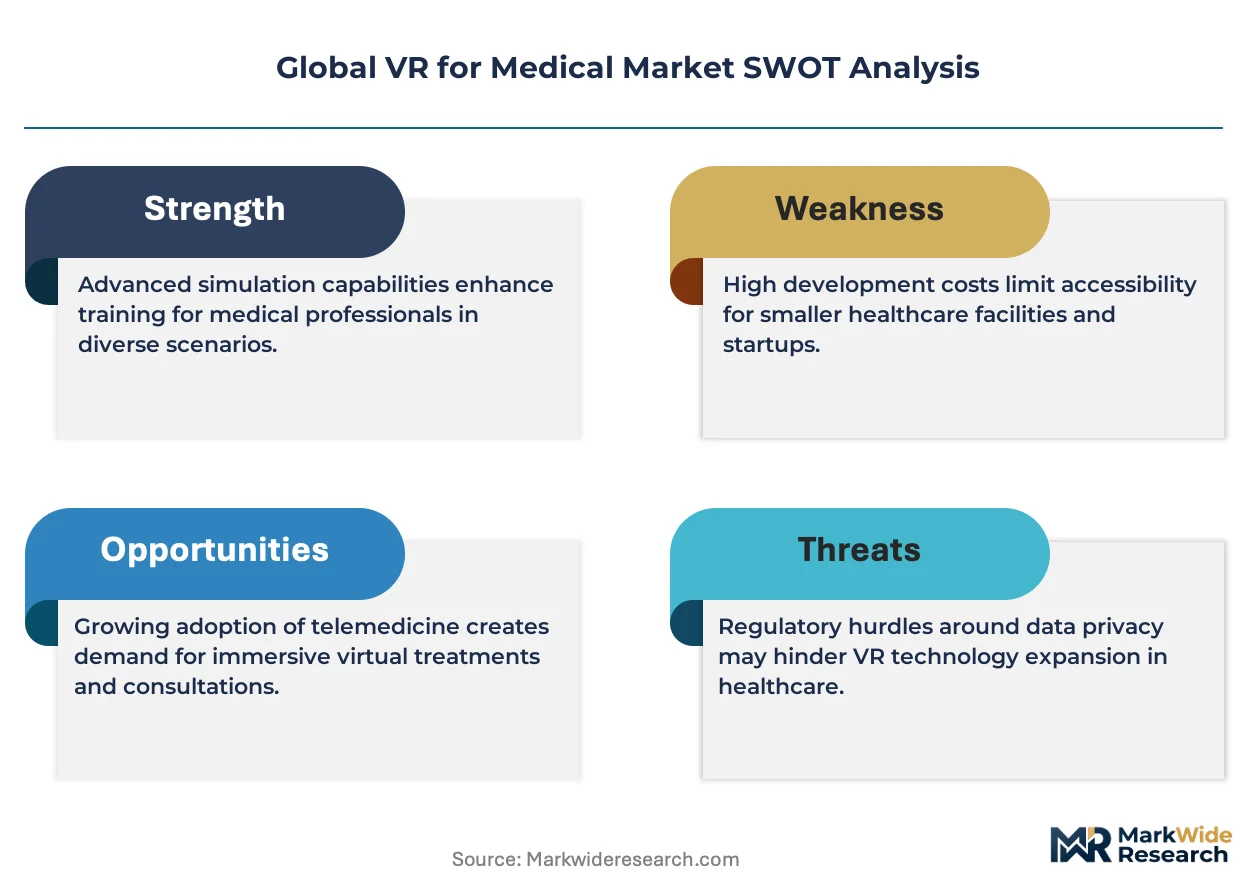
FDA breakthrough device designations are compressing clinical validation timelines from years to months, forcing surgical simulation vendors to accelerate hardware-software integration cycles before reimbursement codes stabilize.
Growth Catalysts
- Japan's PMDA software-as-a-medical-device framework:The streamlined pathway accelerates commercialization for VR therapeutics targeting chronic pain and rehabilitation, drawing venture capital into digital health infrastructure.
- Haptic feedback integration:Force-feedback controllers enabling tactile tissue resistance in orthopedic training modules are expanding addressable use cases beyond visual simulation.
- Academic medical center procurement:Residency programs in the United States are embedding immersive training suites into accreditation requirements, creating institutional demand pull.
Market Restraints
- Headset component concentration:Micro-OLED display manufacturing concentrates in South Korean and Taiwanese fabs, exposing supply chains to single-source fragility.
- Motion-to-photon latency thresholds:Sub-20-millisecond synchronization requirements demand specialized compute hardware that inflates unit economics for mid-tier hospitals.
- EMA Medical Device Regulation complexity:Parallel conformity assessment procedures for hardware-software combinations extend time-to-market for European commercialization.
Strategic Opportunities
- German rehabilitation clinic networks:Bundled reimbursement for digital therapeutics under statutory health insurance creates a testbed for VR-based motor recovery protocols.
- Cloud-native content delivery:Edge computing architectures are reducing on-premise infrastructure requirements, enabling subscription models for smaller surgical practices.
- AI-generated patient anatomy:Synthetic imaging datasets are compressing content production costs for rare procedure simulation libraries.
Industry Challenges
- Clinical validation workforce scarcity:Biomedical engineers with dual expertise in immersive technology and regulatory science command premium compensation that strains mid-stage vendors.
- Legacy EMR integration complexity:Hospital information systems built on HL7 v2 standards require custom middleware development for VR training analytics synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global VR for Medical Market |
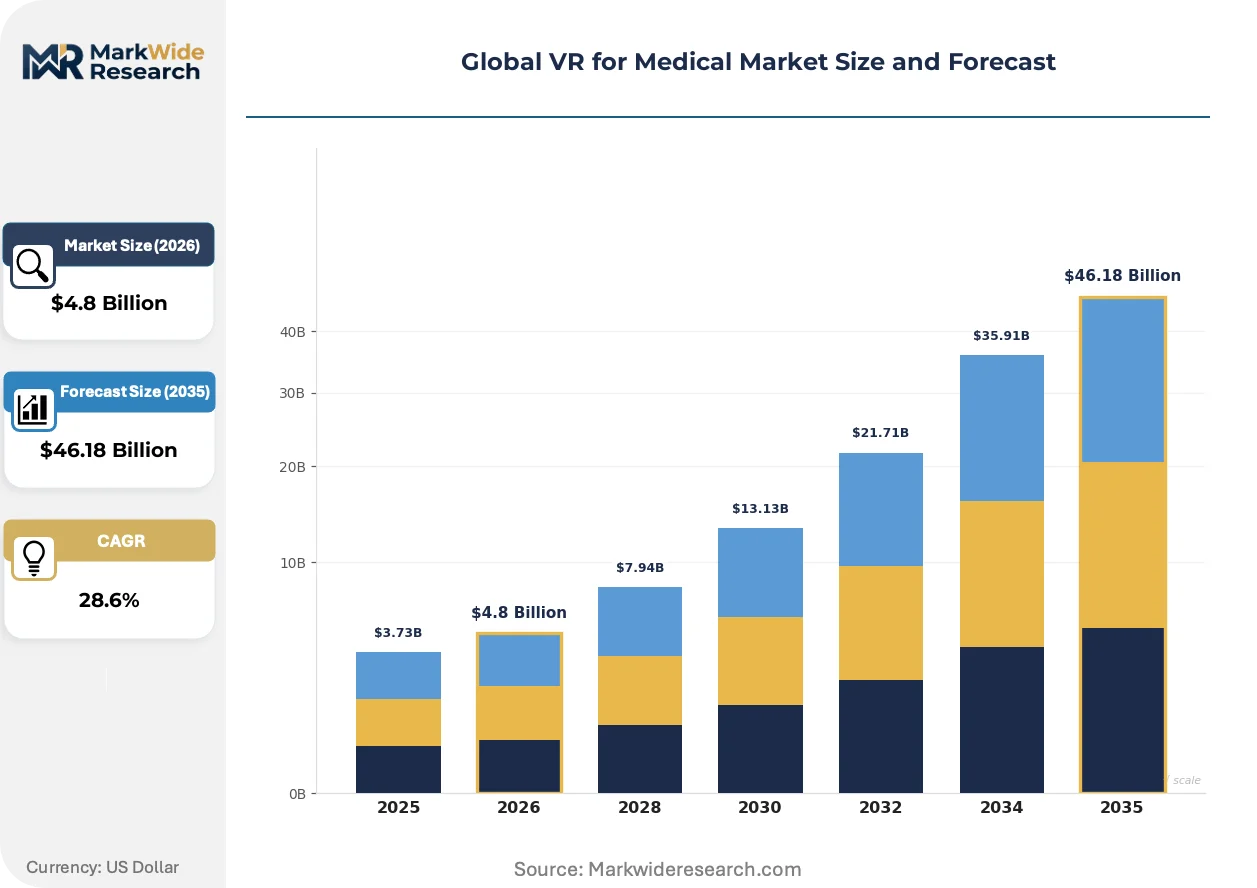
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Accessories Application: Patient Education, Surgery Simulation, Pain Management, Rehabilitation End User: Hospitals, Clinics, Medical Schools, Research Institutions Technology: Oculus, HTC Vive, Microsoft HoloLens, Others |
| Companies Covered | Meta Platforms, Inc., HTC Corporation, AppliedVR, Inc., Osso VR, Surgical Theater, MindMaze, XRHealth, Siemens Healthineers, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global VR for Medical Market Strategic Shifts
Spatial computing architectures are fragmenting the vendor landscape into headset-agnostic software specialists and vertically integrated hardware platforms, with regulatory clearance speed determining competitive survival.
Pass-through mixed reality is bifurcating surgical simulation from pure virtual environments, enabling overlay of patient-specific imaging onto physical operating room setups. Academic medical centers in the United States are piloting these hybrid systems for neurosurgical planning. The technology is compressing the distinction between preoperative rehearsal and intraoperative navigation, forcing vendors to choose between depth in simulation fidelity or breadth in clinical workflow integration.
The EU AI Act's risk classification framework is redefining software validation requirements for VR systems incorporating machine-generated anatomical models. Medical device manufacturers must now document training data provenance and algorithmic transparency for CE marking renewal. Surgical planning applications deploying generative anatomy synthesis face the steepest compliance burden, with German notified bodies issuing the first conformity assessments under the expanded scope.
Hospital procurement committees are unbundling hardware acquisition from content licensing, reversing the bundled enterprise agreements that dominated early market development. Third-party VR software vendors now sell directly to surgical department heads through specialty distributors, bypassing traditional capital equipment procurement channels. This disintermediation is most pronounced in Japan, where university hospitals maintain separate budgets for digital health innovation outside radiology and cardiology capital cycles.
Global VR for Medical Market Segmentation
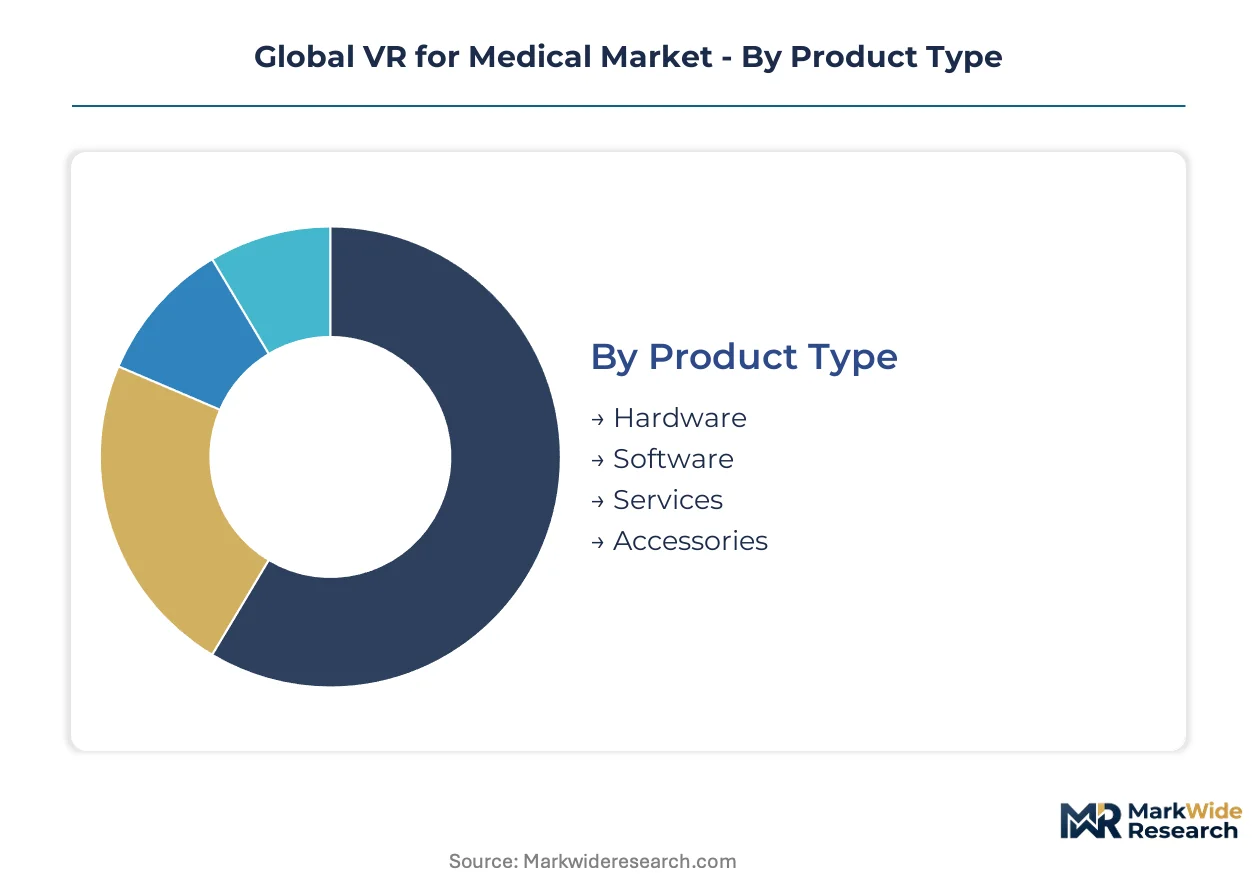
Segmentation reveals how procurement authority, reimbursement pathways, and technical specifications fragment commercial opportunities across the medical VR value chain. Understanding these divides enables vendors to calibrate R&D investment against addressable revenue pools and regulatory complexity.
Product Type:
Software faces intensifying substitution pressure from cloud-native platforms that displace perpetual licenses with subscription economics, while hardware maintains defensive moats through proprietary sensor calibration and FDA-cleared firmware stacks.
- Hardware:Head-mounted displays, haptic controllers, and tracking sensors engineered for sub-20-millisecond latency. Demand concentrates in academic medical centers across the United States where residency accreditation mandates immersive training infrastructure. Replacement cycles drive recurring revenue as hospital IT departments depreciate headsets over 36-month schedules.
- Software:Spatial computing platforms, surgical simulation content libraries, and therapeutic intervention modules requiring IEC 62304-compliant development processes. German rehabilitation clinics are expanding procurement fastest under statutory health insurance reimbursement for digital therapeutics.
- Services:Implementation consulting, clinician onboarding, and regulatory submission support bundled with enterprise agreements.
- Accessories:Disposable hygiene interfaces, prescription lens inserts, and force-feedback peripherals.
Hardware anchors the volume base while software gains share at the steepest rate as reimbursement codes for digital therapeutics mature across multiple jurisdictions.
Application:
Cost tier stratification separates capital-intensive surgical simulation suites from lightweight software-only therapeutic deployments, with reimbursement status determining which indications sustain scaled investment.
- Patient Education:Preoperative visualization tools reducing anxiety and improving informed consent comprehension. United States health systems embed these modules into orthopedic and cardiac service lines where patient satisfaction scores influence value-based contracting.
- Surgery Simulation:Motor skill acquisition environments for laparoscopic, orthopedic, and neurosurgical procedures. Japanese university hospitals are piloting these systems for residency training under PMDA software-as-a-medical-device pathways.
- Pain Management:Non-pharmacological analgesia delivered through immersive distraction environments. FDA breakthrough device designations for chronic pain applications are compressing validation timelines.
- Rehabilitation:Motor recovery protocols for stroke and traumatic injury patients. German bundled reimbursement models create sustainable revenue streams for clinic networks.
Surgery simulation commands the highest per-unit pricing while pain management is expanding most quickly through FDA breakthrough pathways and emerging CPT codes.
End User:
Customer type determines procurement channel complexity, with integrated delivery networks imposing enterprise IT standards that filter vendor selection while standalone clinics enable direct departmental purchasing.
- Hospitals:Tertiary and community health systems with capital equipment procurement committees and EMR integration requirements. United States academic medical centers are embedding immersive training into accreditation-mandated curricula.
- Clinics:Outpatient rehabilitation and pain management facilities with lighter IT infrastructure. German statutory health insurance reimbursement enables standalone clinic adoption of therapeutic VR.
- Medical Schools:Undergraduate and graduate medical education programs with simulation center budgets. Japanese medical schools are expanding procurement under national digital health infrastructure investments.
- Research Institutions:Clinical validation sites and technology translation centers with grant-funded pilot programs.
Hospitals anchor the volume base while clinics are gaining share fastest as cloud-native delivery reduces on-premise infrastructure requirements.
Technology:
Supply concentration in micro-OLED fabrication and proprietary tracking architectures fragments vendor ecosystems between vertically integrated platforms and headset-agnostic software specialists.
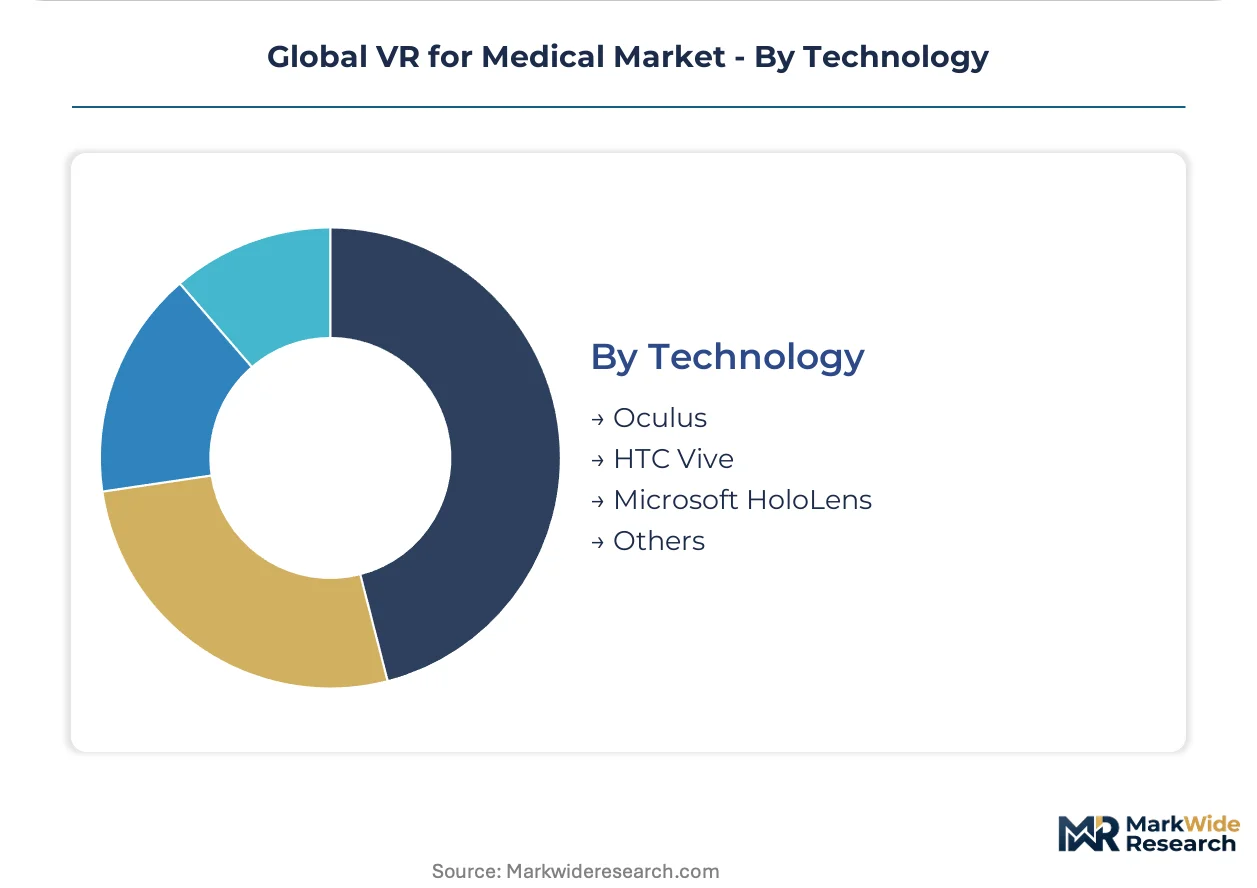
- Oculus:Consumer-scale manufacturing subsidizing healthcare-grade hardware development with integrated content distribution platforms. United States health systems leverage existing procurement relationships with Meta Platforms for enterprise VR deployments.
- HTC Vive:Enterprise-focused tracking precision and open SDK architectures enabling third-party surgical simulation development. German surgical planning vendors favor this platform for optical tracking accuracy in orthopedic applications.
- Microsoft HoloLens:Pass-through mixed reality enabling overlay of patient-specific imaging onto physical operating environments. Japanese neurosurgical centers are piloting these systems for preoperative rehearsal.
- Others:Emerging headset manufacturers and specialized haptic-integrated platforms.
Oculus anchors the volume base through manufacturing scale while Microsoft HoloLens is gaining share fastest as pass-through mixed reality compresses the distinction between simulation and intraoperative navigation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys VR medical systems primarily for surgical simulation accreditation, while Germany channels investment into statutory-insurance-reimbursed rehabilitation clinics and Japan emphasizes software-as-a-medical-device pathways for pain management therapeutics.
United States
Academic medical centers in Massachusetts and California are embedding immersive training suites into residency accreditation requirements. FDA breakthrough device designations compress clinical validation timelines for chronic pain interventions. The Cleveland Clinic and Mayo Clinic anchor procurement concentration in the Midwest, where integrated delivery networks negotiate enterprise licensing agreements.
Germany
Bundled reimbursement for digital therapeutics under statutory health insurance is accelerating clinic network adoption of motor recovery protocols. EMA Medical Device Regulation conformity assessments for hardware-software combinations extend time-to-market for European commercialization. The Ruhr region and Bavaria host the densest concentration of rehabilitation facilities piloting VR-based stroke rehabilitation.
Japan
University hospitals in Tokyo and Osaka are expanding procurement under PMDA software-as-a-medical-device frameworks. National digital health infrastructure investments prioritize non-pharmacological analgesia for aging populations. The Kanto region anchors demand concentration as medical schools embed immersive training into curricula.
United Kingdom
NHS England technology appraisals are evaluating VR surgical planning for orthopedic service line integration. MHRA guidance on software-as-a-medical-device classification creates parallel compliance pathways for therapeutic and diagnostic applications. London's academic health science centers pilot pass-through mixed reality for neurosurgical rehearsal.
South Korea
Micro-OLED display fabrication in Gyeonggi Province supplies critical headset components to global medical VR manufacturers. MFDS software medical device regulations align with international standards to accelerate domestic developer commercialization. Seoul's digital health cluster anchors R&D investment in haptic feedback integration for surgical training.
Global VR for Medical Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with full-stack headset manufacturers leveraging consumer scale against lean software developers targeting FDA-cleared therapeutic niches. Meta Platforms and HTC Corporation anchor the hardware-integrated tier through manufacturing scale and enterprise tracking precision respectively. AppliedVR and Osso VR exemplify the software-specialist archetype, building regulatory moats around specific clinical indications rather than device ecosystems. Strategic moves concentrate on hardware-software bundling reversals and cloud-native delivery partnerships that displace perpetual licensing.
Within the software-specialist tier, AppliedVR and Osso VR exemplify divergent positioning around therapeutic versus surgical applications. Meta Platforms, Inc. anchors the integrated-hardware archetype through manufacturing scale that subsidizes healthcare-grade development. These three entities represent the dominant competitive patterns: regulatory-first software specialization, consumer-scale hardware leverage, and residency-program partnership anchoring.
| Leading Market Players |
|---|
| Meta Platforms, Inc. |
| HTC Corporation |
| AppliedVR, Inc. |
| Osso VR |
| Surgical Theater |
| MindMaze |
| XRHealth |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Others |
Value Chain & Pricing Dynamics
FDA breakthrough device designation pathways gate both supply qualification and price differentiation simultaneously, as hardware vendors must clear clinical validation thresholds before entering academic medical center procurement channels while software specialists leverage regulatory moats to command subscription premiums.
Pricing Analysis
Long-term enterprise licensing agreements dominate hospital procurement, with three-tier pricing structure across premium, standard, and economy levels tied to IEC 62304 certification grade and EMR integration depth. Price differentiation stems from FDA clearance tier and haptic controller bundling. Cost compression in mid-tier hardware is intensifying because Meta Platforms subsidizes healthcare-grade development through consumer manufacturing scale. Standalone clinics exhibit highest price sensitivity; academic medical centers with accreditation mandates show lowest.
Supply Chain Analysis
Inbound logistics costs from East Asian component hubs fluctuate with container availability on transpacific trade lanes, compressing margins for headset assemblers dependent on just-in-time micro-OLED delivery. Manufacturing concentrates in South Korea, Taiwan, and China. Component sourcing draws from Japanese precision optics, German force-feedback engineering, and domestic firmware calibration. Single-source vulnerability in micro-OLED fabrication exposes vendors to allocation constraints. Distribution runs through specialty medical device distributors and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is opening as hospital procurement committees unbundle hardware from content licensing, creating specialist niches for regulatory-first software developers and cloud-native delivery platforms.
For Market Incumbents: Fortify defensive positions by deepening backward integration into haptic controller manufacturing and securing exclusive residency program partnerships. The threat of headset-agnostic software specialists eroding hardware attach rates demands countermeasures through proprietary sensor calibration ecosystems. Certification investment in ISO 13485 quality management systems remains the critical lever for European market access. For New Entrants and Emerging Players: Anchor in German rehabilitation clinic networks where statutory health insurance reimbursement creates immediate revenue visibility. The most penetrable white-space sits in cloud-native surgical simulation for mid-tier orthopedic practices lacking on-premise infrastructure. A direct-to-department sales model bypassing traditional capital equipment committees offers viable go-to-market positioning. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-as-a-medical-device sub-segments as cloud delivery displaces perpetual licensing infrastructure. Long-term viability favors lean developers with FDA-cleared therapeutic modules over full-stack hardware platforms facing component concentration risks. Acquisition targets should demonstrate dual expertise in immersive technology and regulatory science. The signal to watch is CMS reimbursement code finalization for chronic pain digital therapeutics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Expedited review compresses validation timelines for VR-based surgical planning and analgesia interventions. |
| Residency Program Partnership | Accreditation-mandated immersive training creates institutional lock-in and recurring hardware replacement cycles. |
| Cloud-Native Content Delivery | Edge computing architectures enable subscription models that displace capital-intensive on-premise simulation suites. |
| Haptic Feedback Integration | Force-feedback controller development expands addressable use cases beyond visual simulation into tactile skill acquisition. |
| Reimbursement Strategy | CPT code emergence for digital therapeutics determines which clinical indications sustain scaled commercial deployment. |
Study Parameters
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at FDA-cleared VR developers, then refined against secondary validation from FDA 510(k) filings, EMA Medical Device Regulation submission databases, CMS reimbursement code proposals, and hospital procurement records. Bottom-up unit economics modeling triangulated against top-down market sizing across hardware, software, and services revenue pools.
Variance decomposition across product type, application, end user, technology platform, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against macro healthcare IT spending trends. Forecast inputs incorporated PMDA software-as-a-medical-device approval velocity and academic medical center capital budget cycles.
Underlying assumptions cover reimbursement code finalization timelines and micro-OLED supply allocation stability, with deviation risk concentrated in EMA MDR conformity assessment delays and CMS coverage determination reversals. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global AR and VR Smart Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Florida Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Wireless AR Glass Market
Virtual Reality (VR) and Augmented Reality (AR)
Spatial Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
US Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Collaboration Platform Market
Virtual Reality (VR) and Augmented Reality (AR)
Commercial Augmented Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
VR in Sports Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market