
 Tourists Virtual Reality Headsets Market | 2026-2036
Tourists Virtual Reality Headsets Market Size, Share, and Industry Trends Forecast 2026-2036
Tourists Virtual Reality Headsets Market Analytics
Standalone headset architecture is reshaping how tourist VR systems deploy in the field. Meta Platforms leverages its wireless ecosystem to dominate cruise ship and resort installations. Sony sustains premium positioning through high-resolution OLED panels optimized for cinematic destination content. Pico Interactive anchors the Chinese market with cost-effective hardware for domestic scenic spots.
Tourists virtual reality headsets are wearable display systems featuring dual high-density screens, spatial audio arrays, and six-degrees-of-freedom tracking, designed to transport users to simulated or captured destinations without physical travel. Standalone units lead volume shipments due to elimination of external computing dependencies, while tethered configurations retain margin pools in high-end location-based entertainment venues. Educational Tours represents the fastest-growing application as UNESCO heritage sites commission bespoke 360-degree content for remote access programs.
FCC certification governs radio frequency emissions for devices sold in the United States, while CE marking mandates electrical safety and electromagnetic compatibility across European markets. The EU AI Act imposes risk-classification obligations on generative destination content, forcing operators to audit algorithmic outputs. Stakeholders must monitor evolving interoperability standards between proprietary content platforms and open tourism distribution networks.
Market Dynamics
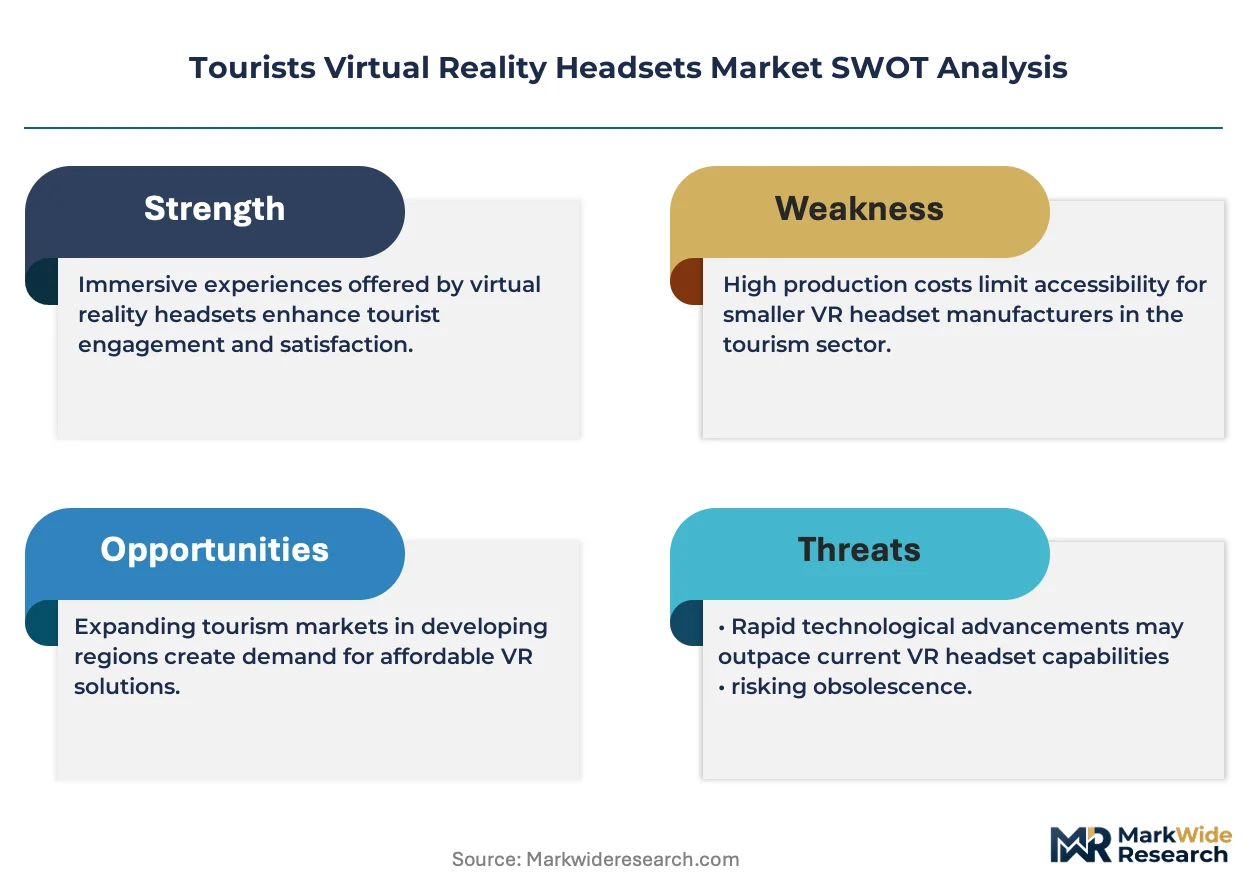
Standalone headset architecture is collapsing the infrastructure requirements for tourist VR deployments, eliminating tethered computing dependencies and enabling rapid installation at heritage sites, cruise terminals, and resort properties.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for generative destination content create standardized audit frameworks that reduce legal uncertainty for content operators deploying interactive cultural experiences.
- Museum digital transformation programs:UNESCO heritage sites commission bespoke 360-degree capture projects, converting physical collections into remotely accessible immersive archives with recurring licensing revenue potential.
- Spatial audio arrays:Six-degrees-of-freedom tracking combined with binaural sound design elevates presence fidelity, driving replacement cycles for legacy stereoscopic systems at location-based entertainment venues.
Market Restraints
- OLED panel supply concentration:Premium display substrate manufacturing clusters in East Asian foundries expose hardware vendors to single-source risk and input cost volatility during semiconductor allocation cycles.
- FCC certification timelines:Radio frequency emissions testing for wireless standalone units creates 4-6 month pre-market delays, compressing product launch windows against content release schedules.
- Motion sickness susceptibility:Latency thresholds below 20 milliseconds remain technically demanding for untethered chipsets, limiting session duration and repeat visitation rates among sensitive demographic segments.
Strategic Opportunities
- German state tourism board funding:Destination preview VR programs receive direct public investment, creating subsidized deployment channels for hardware vendors targeting European cultural institutions.
- Educational Tours vertical expansion:Remote access programs for K-12 and university curricula represent underpenetrated demand with institutional procurement budgets and multi-year contract structures.
- CE marking harmonization:Electrical safety and electromagnetic compatibility standards enable single-certification market access across 27 member states, reducing regulatory fragmentation costs versus multi-jurisdiction approaches.
Industry Challenges
- 360-degree cinematography talent scarcity:Specialized capture technicians capable of stitching spherical video at heritage sites command premium wages, constraining content production velocity for site-specific commissions.
- Proprietary platform interoperability:Content locked to Meta's wireless ecosystem or Sony's cinematic distribution networks creates switching costs that fragment tourism distribution networks and complicate multi-vendor deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tourists Virtual Reality Headsets Market |
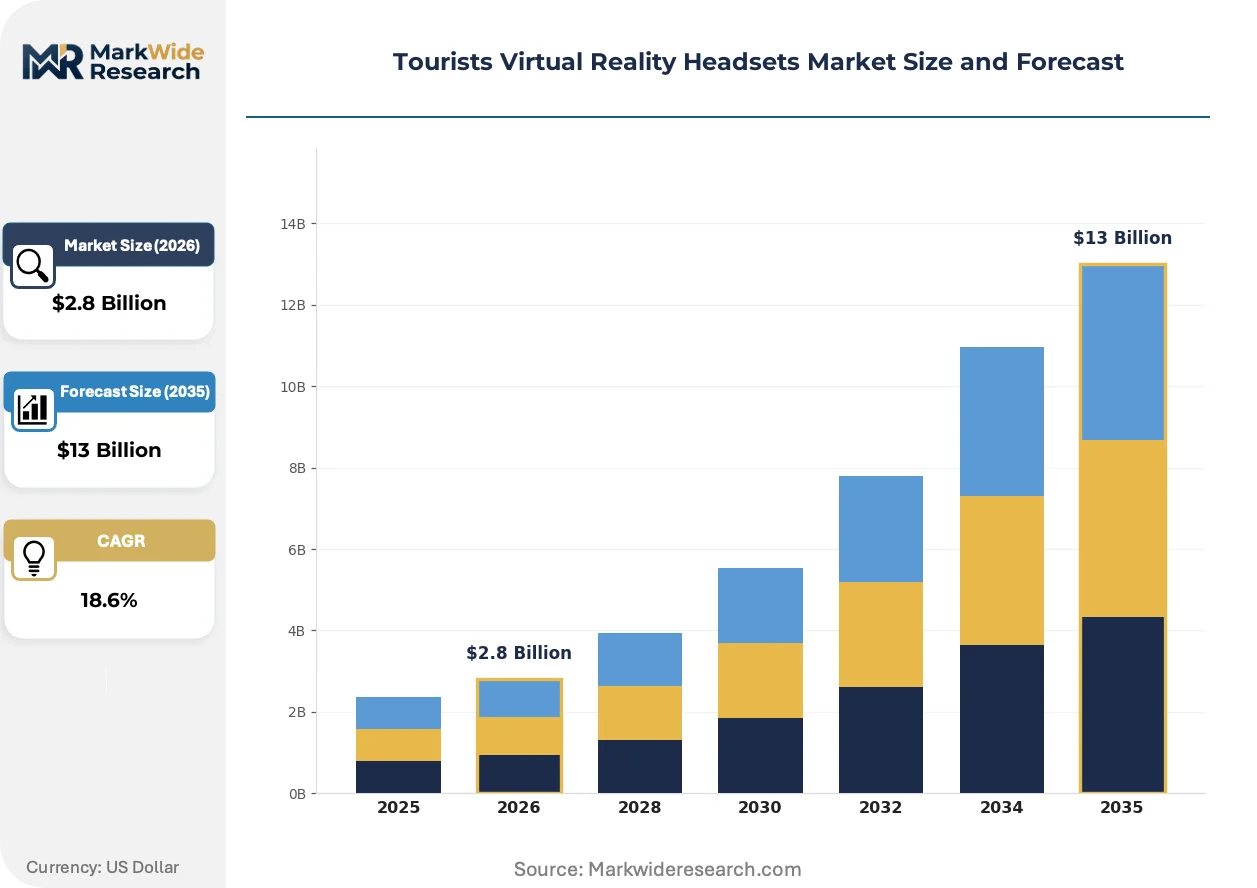
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Tethered, Smartphone-Compatible, Augmented Reality Application: Leisure Activities, Educational Tours, Adventure Experiences, Cultural Exploration End User: Travel Agencies, Tour Operators, Content Creators, Individual Travelers Technology: Visual Simulators, Motion Tracking, 360-Degree Viewing, Haptic Feedback |
| Companies Covered | Sony Corporation, Samsung Electronics Co., Ltd., HTC Corporation, Google LLC, Pico Interactive Inc., DPVR (Beijing) Technology Co., Ltd., LIVI (Guangzhou) Virtual Reality Technology Co., Ltd., Meta Platforms Inc., Apple Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tourists Virtual Reality Headsets Market Evolving Landscape
Wireless chipset efficiency gains and cloud-rendered streaming pipelines are compressing hardware form factors while expanding content fidelity, fundamentally altering deployment economics for field-based tourist VR systems.
Pass-through mixed reality is collapsing the boundary between physical site navigation and digital overlay content, enabling heritage sites to annotate architectural features in real-time. Museum curators in Barcelona and Kyoto pilot these hybrid experiences for visitor flows exceeding 10,000 daily entries. The technology compresses capital requirements by eliminating dedicated VR rooms in favor of adaptive gallery spaces.
The EU AI Act imposes risk-classification obligations on generative destination content that simulates historical figures or reconstructs destroyed monuments. Operators must audit algorithmic outputs for factual accuracy and cultural sensitivity before deployment. German state museums and Italian archaeological sites face the steepest compliance curves given their volume of AI-enhanced reconstruction projects.
Visitor acquisition through direct-to-consumer preview content is displacing traditional travel agency distribution for destination selection. Tourism boards in Bavaria and Tuscany commission cinematic VR previews distributed through social platforms rather than intermediaries. This channel shift concentrates hardware procurement decisions within ministry-level digital transformation budgets rather than venue operating expenditures.
Tourists Virtual Reality Headsets Market Segmentation
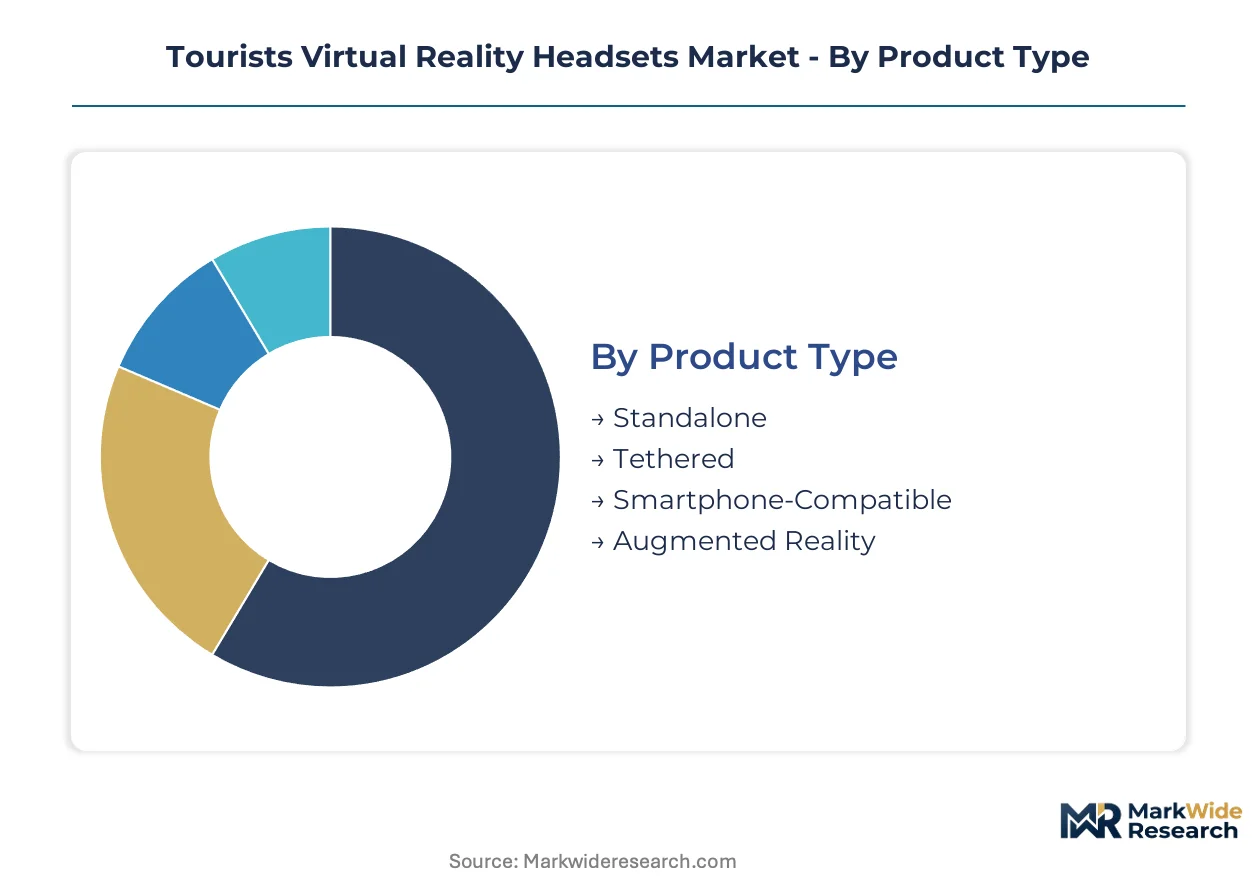
Segmentation in tourist VR headsets reveals divergent hardware lifecycles and procurement patterns across deployment contexts. Museums and cruise operators prioritize replacement cadences differently than individual consumers or content studios.
Product Type:
Standalone units turn over fastest as field deployments expose hardware to wear cycles, while tethered systems in fixed entertainment venues persist longer due to controlled operating environments.
- Standalone:Wireless architecture integrates compute, display, and battery in a single housing. German state tourism boards fund destination preview programs deploying these units at visitor centers and heritage sites, driving volume procurement through public digital transformation budgets.
- Tethered:External processing dependencies deliver superior graphical fidelity through PC or console connections. High-end location-based entertainment venues in Barcelona and Kyoto retain these configurations for premium cinematic destination content despite infrastructure overhead.
- Smartphone-Compatible:Slot-in designs leverage existing device displays for cost-sensitive deployments at smaller museums and regional scenic spots.
- Augmented Reality:Pass-through optics overlay digital reconstructions onto physical heritage architecture, enabling hybrid visitor flows without dedicated VR rooms.
Standalone dominates installed base. Augmented Reality is where expansion concentrates.
Application:
Cost tier separation runs deepest here, with institutional educational budgets commanding premium hardware against price-sensitive leisure rental pools.
- Educational Tours:UNESCO heritage sites commission bespoke 360-degree capture for remote access curricula, creating multi-year institutional contracts with recurring content licensing structures. K-12 and university procurement channels favor enterprise-grade durability specifications.
- Leisure Activities:Cruise terminals and resort properties deploy consumer-tier hardware for guest entertainment, prioritizing rapid sanitization protocols and theft-resistant mounting over technical specifications.
- Adventure Experiences:Motion platform integrations at theme parks demand specialized haptic synchronization and reinforced chassis designs for high-throughput operation.
- Cultural Exploration:Museum galleries emphasize passive observation of reconstructed environments with minimal locomotion requirements, reducing technical complexity and hardware failure rates.
Leisure Activities commands the largest hardware volume. Educational Tours is climbing the fastest.
End User:
Customer type determines procurement sophistication, with enterprise buyers negotiating fleet management platforms against individual traveler direct-to-consumer purchases.
- Travel Agencies:Traditional intermediaries commission cinematic VR previews for client acquisition, shifting hardware procurement decisions into ministry-level destination marketing budgets in Bavaria and Tuscany.
- Tour Operators:Field-based deployment at archaeological sites and heritage trails requires ruggedized hardware with extended battery configurations for remote operation.
- Content Creators:Production studios specializing in 360-degree capture drive demand for reference-grade tethered systems with precise color calibration for post-production workflows.
- Individual Travelers:Pre-trip preview purchases through consumer electronics retail represent price-sensitive demand with minimal service attachment.
Tour Operators dominate installed base. Travel Agencies is gaining share fastest.
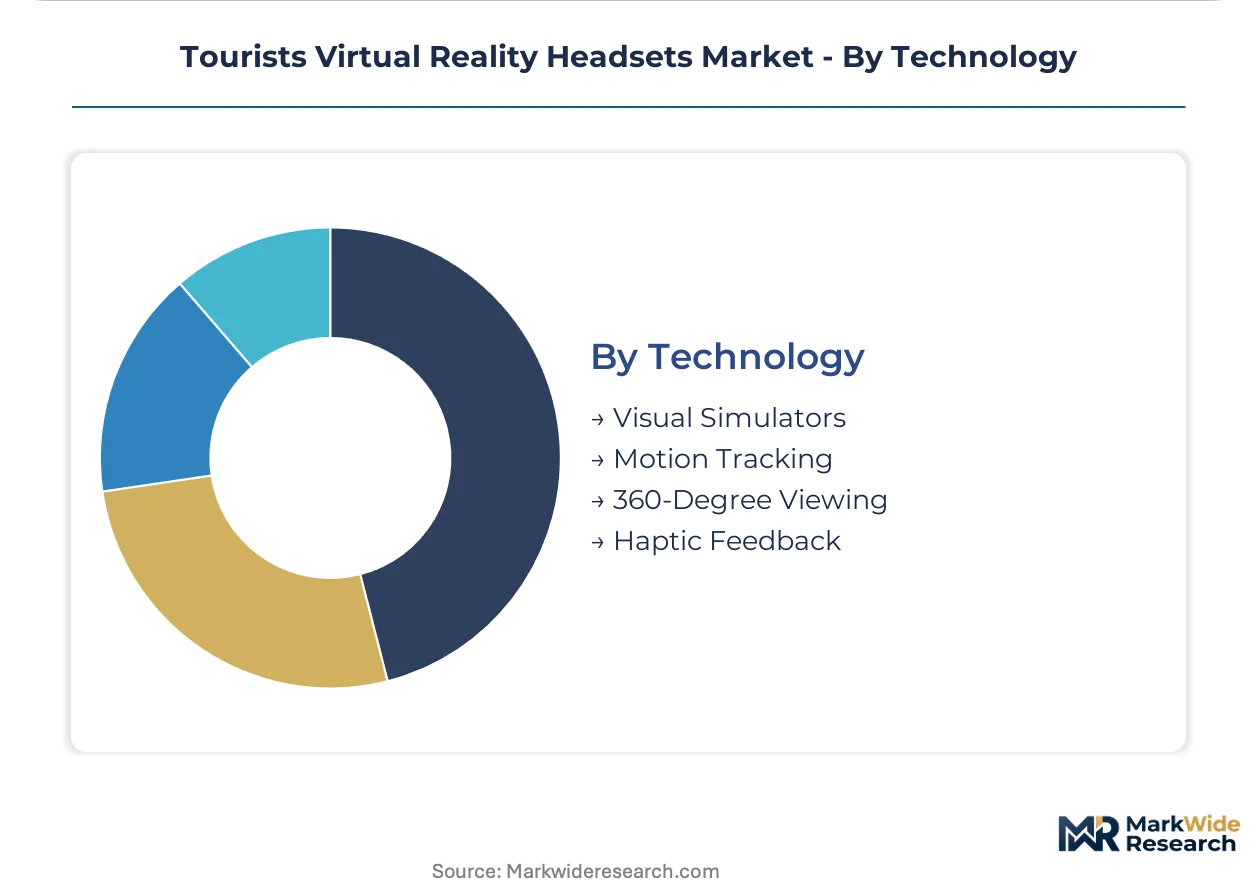
Technology:
Maturity gradients separate proven visual and tracking stacks from emerging haptic interfaces still seeking standardized implementation.
- 360-Degree Viewing:Spherical video capture and stereoscopic playback constitute the foundational content format for destination preview applications, with stitching algorithms now commoditized across production pipelines.
- Motion Tracking:Six-degrees-of-freedom positional systems enable room-scale exploration of reconstructed heritage environments, with inside-out camera arrays eliminating external beacon dependencies for standalone deployments.
- Visual Simulators:Real-time rendered environments with dynamic lighting support interactive historical reconstructions subject to EU AI Act algorithmic audit requirements.
- Haptic Feedback:Force-feedback gloves and vest arrays remain nascent in tourism deployments, constrained by hygiene protocols and session throughput limitations at high-volume venues.
360-Degree Viewing dominates installed base. Motion Tracking is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hardware shipments flow into museum and heritage site installations across France, Italy, and Spain, establishing a north-south corridor for standalone VR deployment in European cultural institutions.
Germany
Bavarian state tourism boards fund destination preview programs at visitor centers, driving volume procurement through public digital transformation budgets. The EU AI Act imposes algorithmic transparency requirements on generative reconstruction content. Munich and Berlin anchor development clusters for 360-degree capture studios serving UNESCO heritage commissions.
United States
Cruise operators and resort properties in Florida and California deploy consumer-tier hardware for guest entertainment, prioritizing rapid sanitization protocols. FCC certification mandates 4-6 month pre-market timelines for wireless standalone units. Los Angeles hosts production studios specializing in cinematic destination content for tourism board distribution.
China
Domestic scenic spots in Sichuan and Yunnan provinces adopt cost-effective hardware for regional visitor experiences. MIIT radio transmission standards govern wireless chipset approvals for standalone devices. Shenzhen manufacturing clusters supply display substrates and optical components to global hardware vendors.
Japan
Museum curators in Kyoto pilot pass-through mixed reality for hybrid visitor flows exceeding 10,000 daily entries. METI digital transformation subsidies support heritage site technology upgrades. Tokyo production studios drive demand for reference-grade tethered systems with precise color calibration workflows.
France
Archaeological sites in Provence commission AI-enhanced reconstruction projects subject to EU AI Act risk-classification obligations. ANSM and CNIL guidance shapes data handling for visitor biometric tracking. Paris clusters concentrate 360-degree cinematography talent for spherical video production.
Tourists Virtual Reality Headsets Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hardware, content distribution, and venue installation segments. The vendor base separates into platform-integrated ecosystems, component-specialist fabricators, and regional system integrators. Three archetypes dominate: wireless ecosystem operators, premium display substrate vendors, and cost-optimized hardware specialists. Competitive moves center on strategic partnerships for content licensing and geographic expansion through public tourism board procurement channels.
Within the wireless ecosystem tier, Meta Platforms Inc. and Pico Interactive Inc. represent contrasting geographic anchor points, with the former exemplifying platform-integrated deployment models and the latter occupying a position in cost-optimized regional supply. Sony Corporation anchors the premium-tier vector through high-resolution display specialization. Samsung Electronics Co., Ltd. and HTC Corporation sit within the diversified technology conglomerate archetype, leveraging cross-divisional component access. Google LLC exemplifies cloud-integrated content distribution positioning.
| Leading Market Players |
|---|
| Sony Corporation |
| Samsung Electronics Co., Ltd. |
| HTC Corporation |
| Google LLC |
| Pico Interactive Inc. |
| DPVR (Beijing) Technology Co., Ltd. |
| LIVI (Guangzhou) Virtual Reality Technology Co., Ltd. |
| Meta Platforms Inc. |
| Apple Inc. |
| Others |
Value Network & Pricing Analysis
Overcapacity in East Asian display foundries is compressing component pricing for headset manufacturers while simultaneously eroding supplier bargaining power against large-scale procurement contracts from German state tourism boards and cruise operators.
Pricing Analysis
Current-generation standalone wireless headsets command substantial premiums over prior-generation tethered systems and early smartphone-compatible slot-in designs. Pricing stratifies across premium, standard, and economy tiers based on display resolution specifications and CE marking certification for EU AI Act compliance. Cost compression in the mid-tier is intensifying because Pico Interactive and domestic Chinese vendors are flooding regional scenic spots with hardware priced for rapid deployment cycles. Individual travelers exhibit the highest price sensitivity through consumer electronics retail channels, while museum procurement committees prioritize durability specifications over unit cost.
Supply Chain Analysis
Export-control regimes limiting advanced semiconductor manufacturing equipment flows to Chinese foundries are reshaping sourcing strategies for wireless chipsets and high-density display substrates. Supply concentrates in Taiwan for OLED panel fabrication, South Korea for memory components, and China for final assembly and optical module integration. Manufacturing draws from gallium nitride power semiconductors, rare-earth magnet arrays for spatial audio, and lithium-polymer battery cells. Single-source vulnerability runs through advanced node semiconductor fabrication. Distribution runs through direct procurement contracts with public tourism boards and venue operators rather than traditional electronics retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German state tourism boards and UNESCO heritage site consortia, fragmenting procurement decisions away from individual venue operators toward ministry-level digital transformation budgets with multi-year contract structures.
For Market Incumbents: Insulate premium positioning through captive OLED panel supply agreements with Taiwanese foundries and accelerated EU AI Act compliance certification for generative destination content. Vertical integration into 360-degree capture studios in Munich and Los Angeles defends against content-locked platform competitors. Channel control through exclusive partnerships with Bavarian and Tuscan tourism boards reinforces installed base retention. For New Entrants and Emerging Players: French archaeological sites in Provence and smaller regional museums across Italy represent underpenetrated demand pockets with limited incumbent presence. Educational Tours procurement channels for K-12 and university curricula offer the most penetrable entry path due to institutional budget cycles and durability-focused specifications. A go-to-market angle emphasizing rapid CE marking completion and algorithmic audit transparency for EU AI Act compliance differentiates against established vendors with legacy content pipelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-rendered streaming pipelines as edge computing reduces standalone hardware processing requirements. Long-term viability favors acquisition targets with established 360-degree capture studio capabilities and existing UNESCO heritage site relationships rather than pure hardware fabricators. The signal to watch is German state tourism board funding allocation shifts between destination preview hardware subsidies and generative AI content development grants.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Algorithmic audit frameworks unlock public museum procurement channels across Germany, France, and Italy. |
| 360-Degree Capture Studio Acquisition | Content production capabilities differentiate hardware vendors in UNESCO heritage commission competitions. |
| Wireless Chipset Supply Agreement | Direct foundry relationships insulate against export-control disruptions affecting Chinese vendors. |
| Educational Tours Channel Partnership | Institutional procurement budgets offer multi-year contract structures with lower price sensitivity. |
| Pass-Through Mixed Reality Development | Hybrid physical-digital experiences reduce capital requirements for heritage site deployments in Kyoto and Barcelona. |
Research Methodology
Initial hypotheses were tested against primary input from museum curators, cruise line technology procurement officers, 360-degree cinematography studio executives, and German state tourism board digital transformation leads and refined through secondary validation against SEC filings from Meta Platforms and Sony Corporation, EU AI Act regulatory documentation, FCC equipment authorization databases, and UNESCO heritage site technology tender records. Bottom-up demand modeling from venue installation counts and top-down market sizing from hardware shipment aggregations were triangulated for convergence.
Demand-supply balance dynamics across the projection horizon informed analytical framework construction with segmentation across standalone, tethered, smartphone-compatible, and augmented reality product architectures; Educational Tours, Leisure Activities, Adventure Experiences, and Cultural Exploration applications; and 360-degree viewing, motion tracking, visual simulators, and haptic feedback technology stacks. CAGRs were derived from installed base replacement cycles and content commissioning velocity. Forecast inputs incorporated EU AI Act implementation timelines and German public digital transformation budget allocations.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by display substrate vendors or platform-locked ecosystem expansions would shift outcomes. Material shifts in FCC certification timelines, EU AI Act risk-classification enforcement intensity, or East Asian semiconductor allocation priorities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Content Creation Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Connected Service Market
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Spatial Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual and Augmented Reality in Tourism Market
Virtual Reality (VR) and Augmented Reality (AR)
Enterprise AR Software Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Fence Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive Augmented Reality (AR) HUD System Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Smart Glasses for Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Holographic AR Display Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Head Show Market
Virtual Reality (VR) and Augmented Reality (AR)
Data Glove Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality Market