
 Global Augmented and Virtual Reality (AR VR) Market | 2026-2036
Global Augmented and Virtual Reality (AR VR) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Augmented and Virtual Reality (AR VR) Market Analysis
A capital-intensity divergence between cloud-rendering infrastructure and consumer hardware is rotating competitive advantage toward vertically integrated platforms. Meta Platforms leverages its social graph and content ecosystem to sustain headset adoption. Microsoft anchors enterprise demand through mixed-reality workplace tools. Sony Group Corporation competes in gaming immersion with specialized display and haptic expertise.
Augmented and Virtual Reality denotes computer-generated perceptual environments overlaying or replacing physical sensory input through stereoscopic displays, spatial tracking sensors, and real-time rendering engines operating at sub-20-millisecond motion-to-photon latency. Head-Mounted Displays dominate hardware value capture due to optics miniaturization costs, while Software Platforms concentrate margin pools through recurring licensing and developer ecosystem control. Gaming leads application revenue among consumer segments, whereas Healthcare and Education segments expand fastest as procedural training and remote collaboration protocols mature.
The FDA regulates AR VR medical devices through software-as-medical-device pathways, while the EU AI Act classifies biometric inference systems as high-risk, mandating conformity assessments before CE marking. China's MIIT enforces GB standards for near-eye display safety and radio transmission in wearable devices. Stakeholders must monitor divergence between open interoperability standards and proprietary platform ecosystems as the primary strategic variable.
Market Dynamics
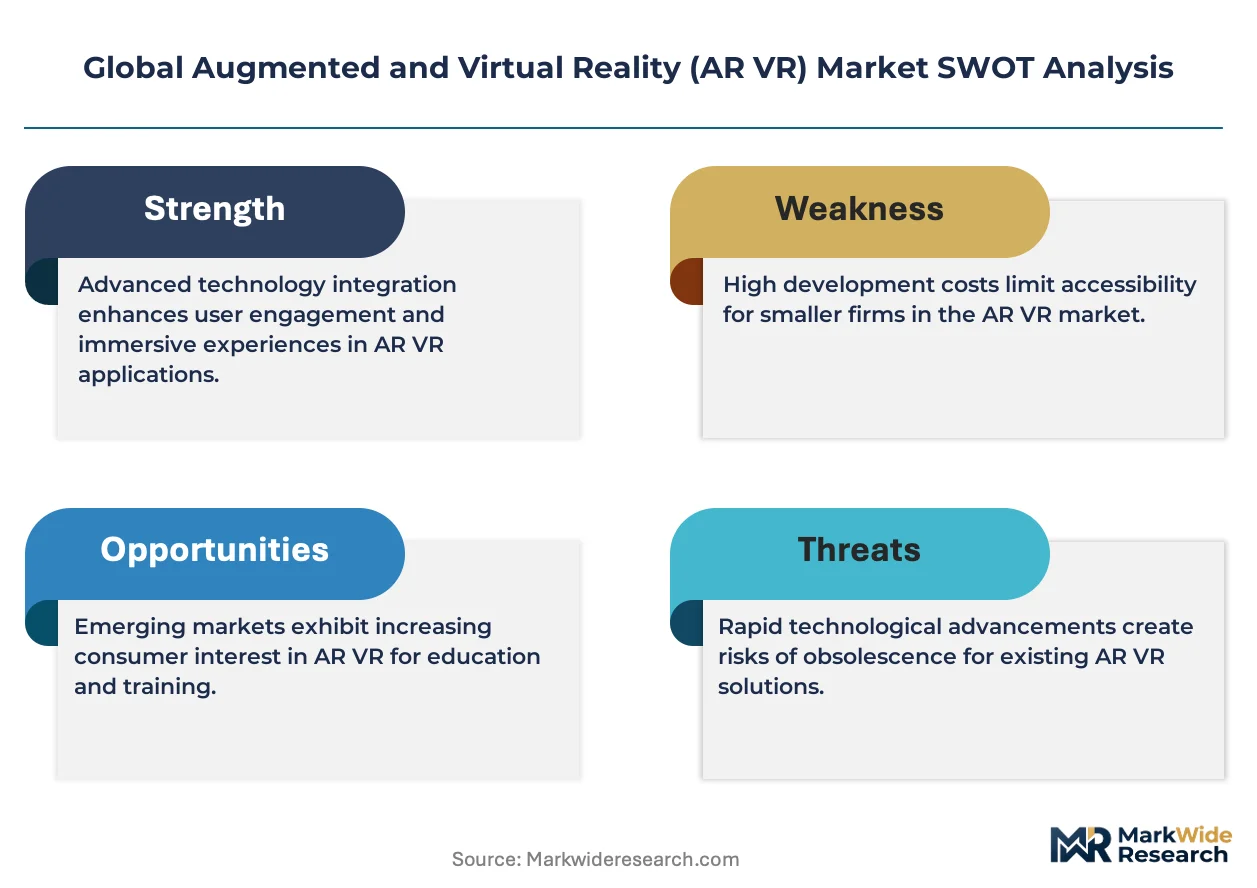
Cloud-rendering infrastructure is concentrating competitive advantage among vertically integrated platforms that control both hardware and software layers, squeezing modular component suppliers into margin compression.
Growth Catalysts
- EU AI Act high-risk classification:Biometric inference systems face mandatory conformity assessments before CE marking, creating certified vendor demand from healthcare and enterprise buyers seeking compliant supply chains.
- Surgical training protocols:Healthcare providers in Germany, the United States, and China are embedding AR VR modules into residency programs, institutionalizing recurring procurement cycles.
- Optics miniaturization:Waveguide and pancake lens manufacturing advances are reducing headset weight below 200 grams, unlocking all-day enterprise wearability previously blocked by comfort barriers.
Market Restraints
- Display panel supply concentration:Micro-OLED fabrication capacity clusters in East Asian foundries, creating single-source vulnerability for premium headset manufacturers.
- FDA software-as-medical-device pathway friction:Extended reality diagnostic tools face 18-24 month validation timelines, delaying revenue recognition for healthcare-focused developers.
- Motion-to-photon latency floor:Sub-20-millisecond rendering requirements demand specialized ASIC architectures that lock out general-purpose GPU alternatives, raising BOM costs.
Strategic Opportunities
- Remote diagnostics in rural India:Telemedicine infrastructure gaps create first-mover advantage for AR-enabled specialist consultation platforms bypassing physical clinic scarcity.
- GB standard compliance in China:MIIT near-eye display safety certifications function as non-tariff barriers that reward domestic manufacturing partnerships.
- Spatial computing convergence:Integration of lidar, neural rendering, and haptic feedback is opening industrial maintenance applications previously served by printed manuals.
Industry Challenges
- Real-time rendering engineer scarcity:Talent pipelines for sub-20-millisecond pipeline optimization remain underdeveloped relative to demand from game engine and medical simulation developers.
- Legacy EMR integration complexity:Hospital IT departments face 12-18 month API harmonization projects to connect AR VR surgical planning tools with existing patient record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Augmented and Virtual Reality (AR VR) Market |
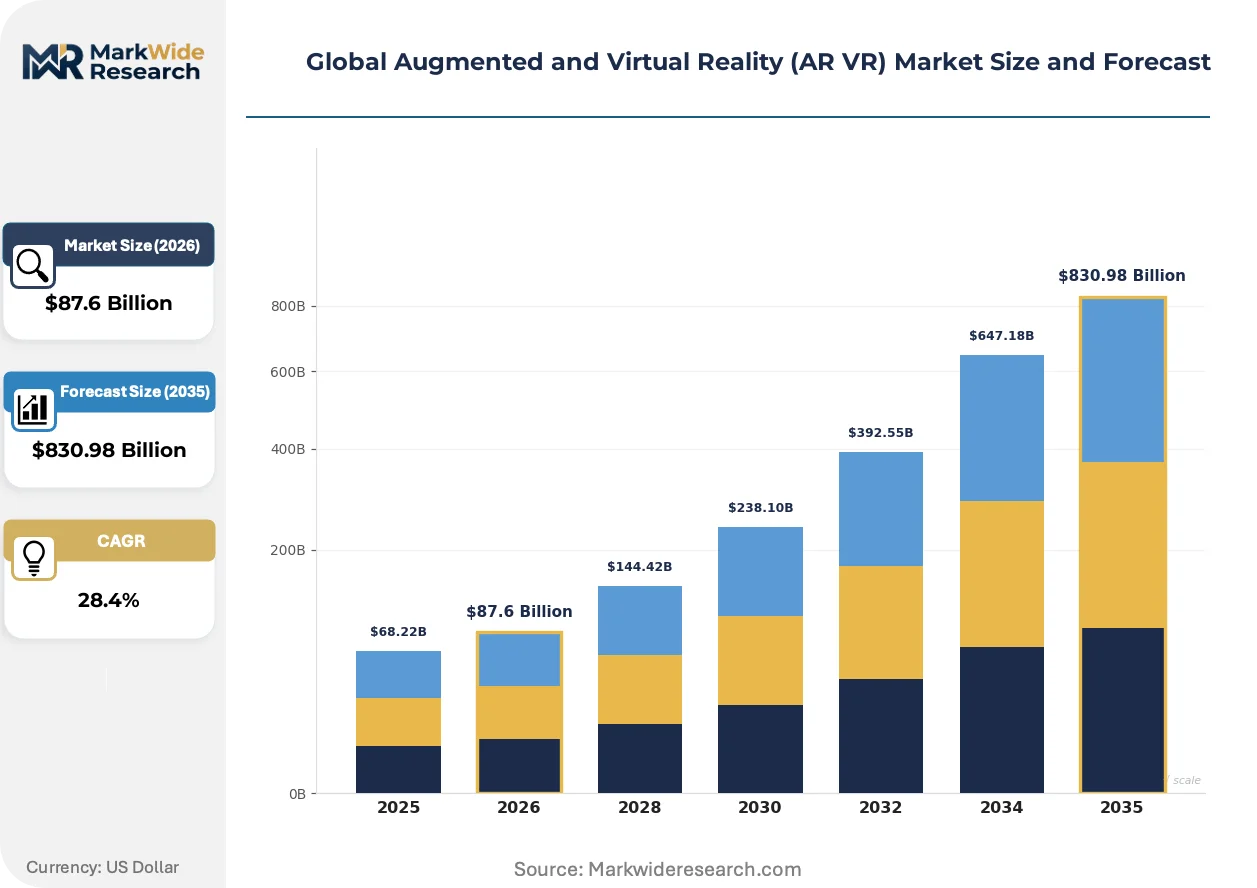
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $830.98 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head-Mounted Displays, Handheld Devices, Software Platforms, Accessories Application: Gaming, Education, Healthcare, Real Estate End User: Consumers, Enterprises, Healthcare Professionals, Educational Institutions Technology: Augmented Reality, Virtual Reality, Mixed Reality, 360-Degree Video |
| Companies Covered | Meta Platforms, Microsoft, Google, Sony Group Corporation, Samsung Electronics, Apple, HTC Corporation, Magic Leap, Qualcomm Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Augmented and Virtual Reality (AR VR) Market Emerging Trajectories
Rendering architectures and regulatory frameworks are simultaneously tightening, forcing platform owners to rebuild compliance and performance stacks rather than iterate incrementally.
Pancake optics is supplanting Fresnel lenses in premium headset designs. Enterprise buyers in surgical training and architectural visualization are specifying pancake-based devices for reduced form factors. This transition is compressing margins for legacy optics suppliers locked into Fresnel tooling investments.
The EU AI Act's biometric inference classification is mandating third-party conformity assessments for gaze-tracking and emotion-recognition features. Medical device manufacturers must now document algorithmic transparency before CE marking. German healthcare procurement offices are prioritizing pre-certified vendors, shifting contract awards toward compliant platforms.
Subscription-based developer tools are replacing perpetual licenses in enterprise AR VR procurement. Industrial training departments in the United States are bundling hardware, software, and content updates into single annual contracts. This unbundles capital expenditure into operational budgets, accelerating approval cycles for pilot programs.
Global Augmented and Virtual Reality (AR VR) Market Segmentation
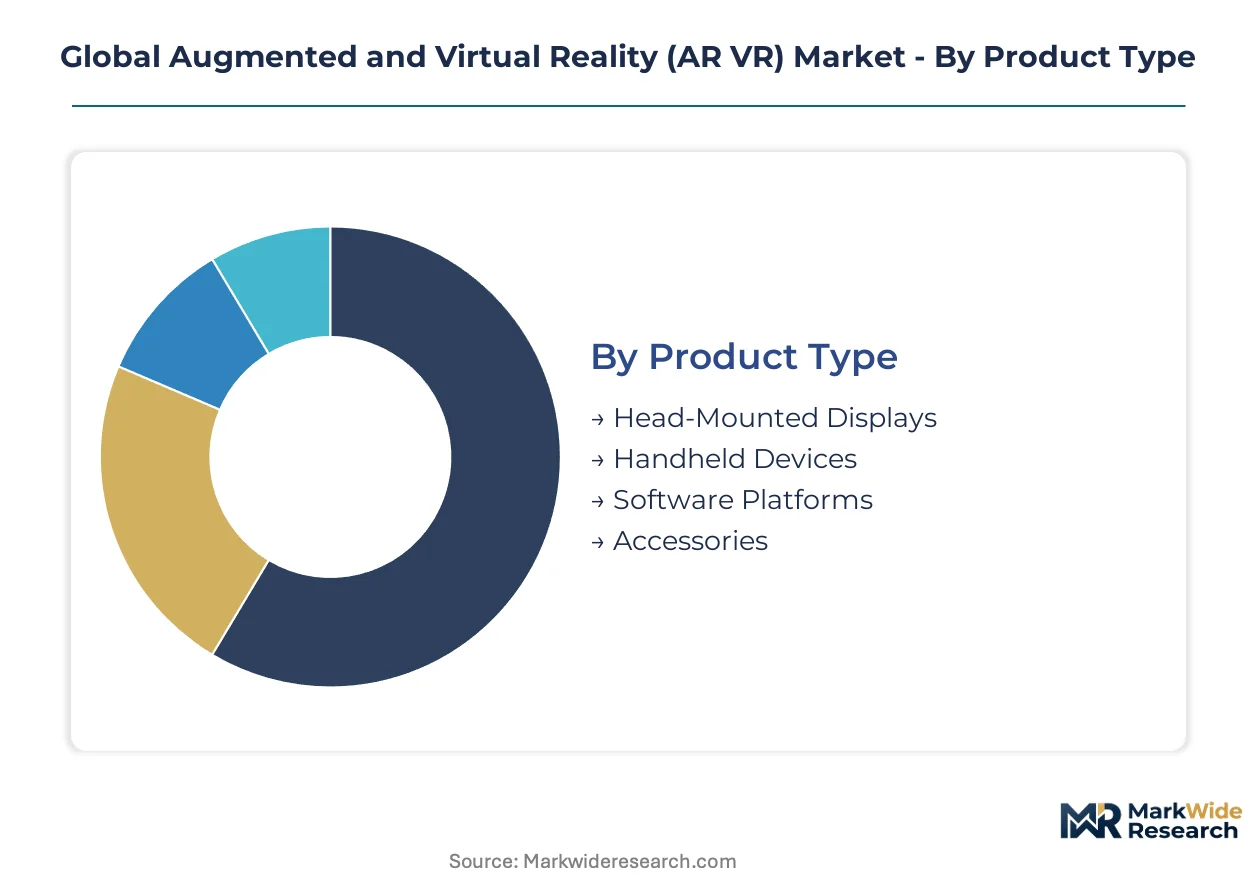
AR VR market segmentation reveals divergent margin structures across hardware and software layers. Product type splits expose capital intensity gaps between optics manufacturing and recurring platform revenue. Application segments track regulatory maturity, with healthcare procurement cycles lagging gaming by several years.
Product Type:
Head-Mounted Displays dominate export flows from East Asian manufacturing clusters, while Software Platforms concentrate development talent in the United States and Germany.
- Head-Mounted Displays:Pancake optics and waveguide architectures reduce device weight below 200 grams. Demand concentrates among German automotive manufacturers and United States surgical training centers seeking all-day wearability.
- Software Platforms:Cloud-rendering engines and developer SDKs generate recurring licensing revenue. United States enterprise buyers bundle these into annual operational budgets, accelerating procurement approvals.
- Handheld Devices:Smartphone-tethered viewers serve price-sensitive consumer segments in India and Southeast Asia.
- Accessories:Haptic controllers and spatial trackers complement enterprise deployments in Chinese manufacturing facilities.
Head-Mounted Displays holds the largest share; momentum sits with Software Platforms.
Application:
Cost tier stratification separates premium surgical simulation from mass-market gaming deployments.
- Gaming:Real-time rendering engines prioritize sub-20-millisecond latency for immersive experiences. Consumer demand clusters in the United States, Japan, and South Korea where console and PC gaming infrastructure is mature.
- Healthcare:FDA software-as-medical-device pathways and EU AI Act conformity assessments impose 18-24 month validation timelines. German hospital procurement offices now prioritize pre-certified vendors, institutionalizing compliance as a selection criterion.
- Education:AR-enabled vocational training expands in China's industrial provinces under MIIT-supported pilot programs.
- Real Estate:Architectural visualization tools reduce physical staging costs for developers in Dubai and Singapore.
Gaming commands current revenue; healthcare is expanding most quickly as procedural training protocols mature.
End User:
Volume concentration favors consumer segments, though enterprise procurement cycles offer superior contract visibility.
- Consumers:Gaming and entertainment applications drive unit shipments through retail channels in the United States and China.
- Enterprises:Mixed-reality workplace tools from Microsoft anchor demand for remote collaboration and industrial maintenance protocols.
- Healthcare Professionals:Surgical training residencies in Germany, the United States, and China embed AR VR modules, creating recurring institutional procurement.
- Educational Institutions:Vocational schools in China's Guangdong and Jiangsu provinces deploy AR-enabled equipment training under government-supported digitalization initiatives.
Consumers generate highest unit volumes; Healthcare Professionals show steepest expansion trajectory as residency programs institutionalize technology adoption.
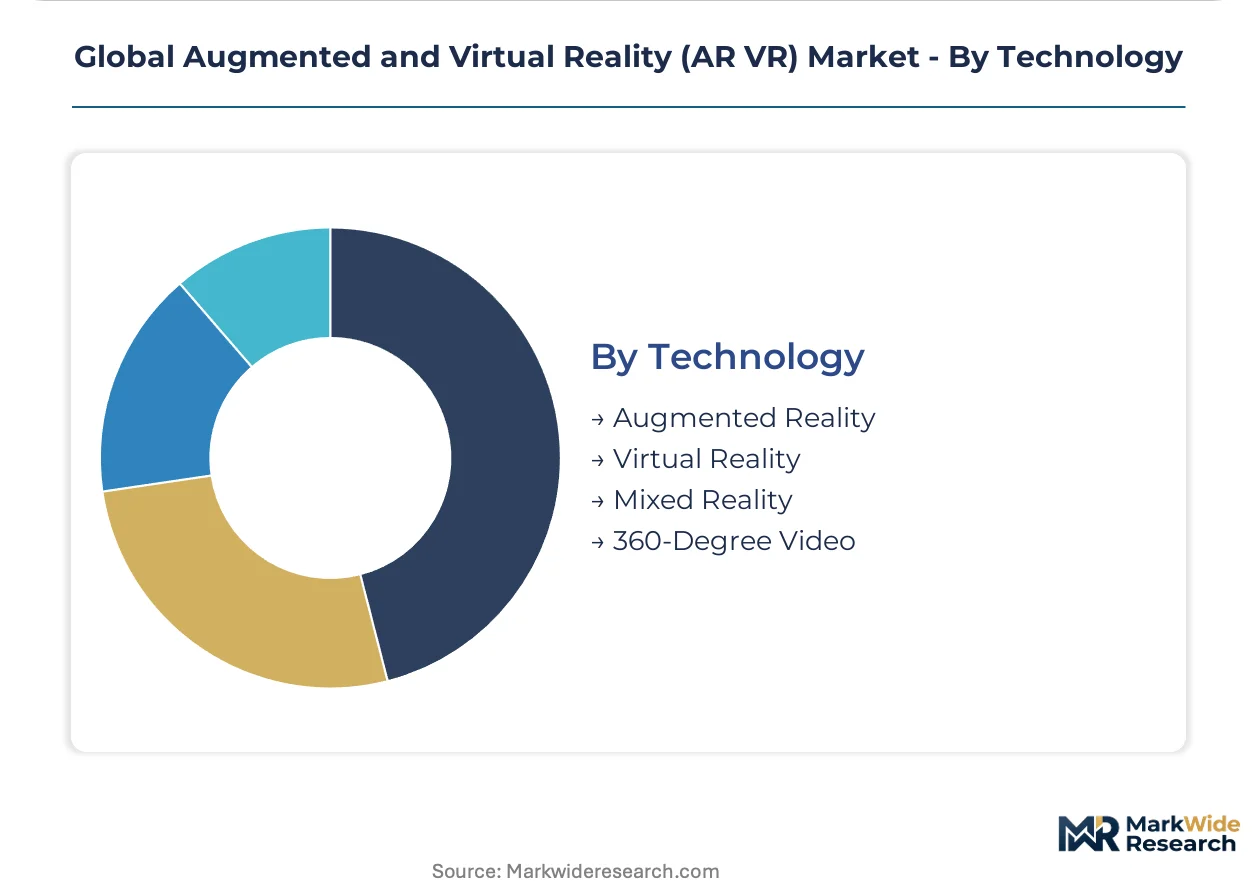
Technology:
Supply concentration in display panel fabrication favors vertically integrated platform owners over modular component assemblers.
- Augmented Reality:Transparent waveguide optics overlay digital information onto physical environments. Enterprise demand concentrates in German manufacturing and United States logistics operations for hands-free workflow guidance.
- Virtual Reality:Fully immersive environments replace visual input through stereoscopic displays. Gaming applications in the United States and Japan drive premium headset adoption.
- Mixed Reality:Spatial computing blends physical and digital elements through lidar and neural rendering. Industrial maintenance applications in China's state-owned enterprises bypass printed manual workflows.
- 360-Degree Video:Spherical capture systems serve real estate and tourism marketing in Dubai and Singapore.
Virtual Reality holds installed base leadership; Mixed Reality is gaining share fastest as spatial computing converges with enterprise automation priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in India by roughly three-to-one for comparable enterprise headset configurations, reflecting divergent procurement sophistication and regulatory compliance burdens across these markets.
United States
FDA software-as-medical-device pathways and enterprise mixed-reality workplace contracts drive procurement from healthcare systems and Fortune 500 industrial operators. HIPAA compliance requirements and FCC radio transmission standards shape vendor qualification protocols. The San Francisco Bay Area and Seattle metropolitan clusters concentrate cloud-rendering engineering talent and platform development headquarters.
China
MIIT near-eye display safety certifications and GB standards for wearable radio equipment create non-tariff barriers favoring domestic manufacturing partnerships. State-owned enterprise automation mandates accelerate mixed-reality deployment in industrial maintenance. The Yangtze River Delta and Pearl River Delta regions host micro-OLED foundry capacity and optics miniaturization supply chains.
Germany
EU AI Act high-risk classification for biometric inference systems and MDR conformity assessments institutionalize compliance as a hospital procurement criterion. Automotive manufacturers specify pancake-optic headsets for all-day factory-floor wearability. The Bavaria and Baden-Württemberg industrial corridors anchor surgical training residency programs and precision optics engineering clusters.
Japan
METI-supported digital transformation subsidies and PMDA medical device registration pathways support healthcare AR VR adoption in aging-care facilities. Gaming infrastructure maturity sustains consumer headset demand through specialized retail channels. The Kanto region around Tokyo concentrates display panel R&D and haptic controller manufacturing.
India
Telemedicine infrastructure gaps in rural districts create first-mover opportunity for AR-enabled specialist consultation platforms bypassing physical clinic scarcity. BIS certification requirements for electronic imports shape hardware distribution strategies. The Karnataka and Maharashtra state clusters host software development centers serving global platform owners.
Global Augmented and Virtual Reality (AR VR) Market Vendor Landscape
Concentration sits with vertically integrated platform owners controlling both hardware and software layers. The vendor base spans three tiers: social-graph-anchored consumer ecosystems, enterprise workplace-tool specialists, and component-technology licensors. Modular headset assemblers face margin compression as cloud-rendering infrastructure concentrates among captive platforms. Dominant competitive moves include backward integration into optics manufacturing and strategic partnerships with healthcare systems seeking pre-certified supply chains.
Within the platform-owner tier, Meta Platforms exemplifies social-graph-driven consumer ecosystem control, while Microsoft occupies a position anchoring enterprise mixed-reality workplace demand. Sony Group Corporation represents specialized gaming immersion expertise through display and haptic technology concentration. These three entities collectively illustrate the competitive divergence between consumer entertainment, enterprise productivity, and healthcare training verticals.
| Leading Market Players |
|---|
| Meta Platforms |
| Microsoft |
| Sony Group Corporation |
| Samsung Electronics |
| Apple |
| HTC Corporation |
| Magic Leap |
| Qualcomm Technologies |
| Others |
Supply Flow & Price Mechanics
Pancake optics displacing Fresnel lenses in premium headset designs simultaneously relocates manufacturing gravity toward East Asian precision optics clusters and compresses margins for legacy suppliers locked into depreciated tooling investments. This substitution dynamic concentrates pricing power among vertically integrated platform owners while fragmenting component vendor economics.
Pricing Analysis
Configured-to-order enterprise deployments command substantial premiums over standard consumer configurations, with surgical training systems and mixed-reality workplace tools bundling hardware, software, and certification documentation into annual operational budgets. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated medical devices from enterprise productivity headsets and smartphone-tethered consumer viewers. Price differentiation stems from certification grade and vertical integration depth, with compliant healthcare platforms resisting cost compression while modular assemblers face margin erosion. Healthcare procurement offices exhibit lowest price sensitivity due to regulatory compliance requirements, whereas Indian telemedicine platforms and Southeast Asian consumer segments prioritize unit economics.
Supply Chain Analysis
Micro-OLED inventory cycles and waveguide lead times extending 16-20 weeks constrain headset production planning, forcing manufacturers into long-term foundry commitments. Supply concentrates in China, South Korea, and Taiwan for display panels, precision optics, and ASIC architectures. The chain draws from gallium nitride substrates, rare-earth phosphors, and specialized polymer films for optical waveguides. Single-source vulnerability in East Asian micro-OLED fabrication creates structural risk for premium headset manufacturers lacking captive supply arrangements. Distribution runs through direct enterprise sales teams for healthcare and industrial accounts, consumer electronics retail chains for gaming segments, and government procurement channels for educational deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against flat-screen telepresence and AI-generated simulation platforms that threaten to commoditize immersive training applications. Incumbents must fortify positions through compliance moats and captive supply chains.
For Market Incumbents: Compound platform stickiness by embedding FDA and EU AI Act conformity assessments into core product architectures, creating switching costs for healthcare systems. Deepen backward integration into pancake optics manufacturing to escape margin compression from East Asian component suppliers. Prioritize certification investment over feature expansion, as German hospital procurement offices now institutionalize compliance as a primary selection criterion.
For New Entrants and Emerging Players: Anchor in rural Indian telemedicine infrastructure gaps, where specialist consultation scarcity creates first-mover advantage for AR-enabled diagnostic platforms bypassing physical clinic limitations. Target vocational training applications in China's Guangdong and Jiangsu provinces under MIIT-supported digitalization initiatives. Pursue white-label partnerships with domestic Chinese manufacturers seeking GB standard compliance for near-eye display safety certifications.
For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors vertically integrated owners with captive cloud-rendering infrastructure and healthcare certification pipelines. Long-term viability hinges on controlling both hardware cost structures and software ecosystem lock-in. Acquisition target archetype: mid-cap surgical simulation developers with FDA software-as-medical-device clearances and established German hospital procurement relationships. Monitor EU AI Act third-party conformity assessment backlogs as an inflection signal for compliant vendor scarcity premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies cloud-rendering engines with healthcare compliance stacks for German hospital procurement. |
| Regulatory Certification Pathway | Secures FDA software-as-medical-device clearance and EU AI Act conformity for biometric inference systems. |
| Backward Integration | Captures pancake optics manufacturing to reduce dependency on East Asian waveguide suppliers. |
| Hospital System Partnership | Institutionalizes recurring procurement through embedded surgical training residency programs. |
| Geographic Expansion | Establishes MIIT-compliant manufacturing partnerships to access China's state-owned enterprise automation mandates. |
Methodological Framework
Operator-level perspectives from surgical training directors, hospital procurement managers, cloud-rendering engineers, and industrial maintenance supervisors anchored the qualitative base for this analysis. Primary interviews with these stakeholders combined with secondary validation against SEC filings from platform owners, FDA software-as-medical-device registration databases, EU AI Act conformity assessment records, and MIIT GB standard certification listings. Bottom-up demand modeling across healthcare, gaming, and enterprise segments triangulated against top-down market sizing from trade flow data and hyperscaler capex disclosures.
Sensitivity analysis tested forecast robustness across adoption rate scenarios for surgical training protocols and enterprise mixed-reality deployment timelines. The analytical framework modeled segmentation dimensions including product type, application vertical, end-user category, and technology architecture across the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical technology adoption patterns, with inputs including optics miniaturization cost trajectories, regulatory validation timeline distributions, and cloud-rendering infrastructure expansion schedules.
Decision-makers should treat outputs as directional under assumptions of sustained EU AI Act enforcement and continued East Asian display panel supply concentration; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Tourists Virtual Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
India Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Location Based VR Market
Virtual Reality (VR) and Augmented Reality (AR)
US Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Content Creation Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
AR in Healthcare Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Amusement Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Wireless AR Glass Market
Virtual Reality (VR) and Augmented Reality (AR)
Commercial Augmented Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Telepresence Market
Virtual Reality (VR) and Augmented Reality (AR)
Extended Reality (XR) Market
Virtual Reality (VR) and Augmented Reality (AR)
AR-VR Head Display Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market