
 Software Licensing Market | 2026-2036
Software Licensing Market Size, Share, and Industry Trends Forecast 2026-2036
Software Licensing Market Outlook
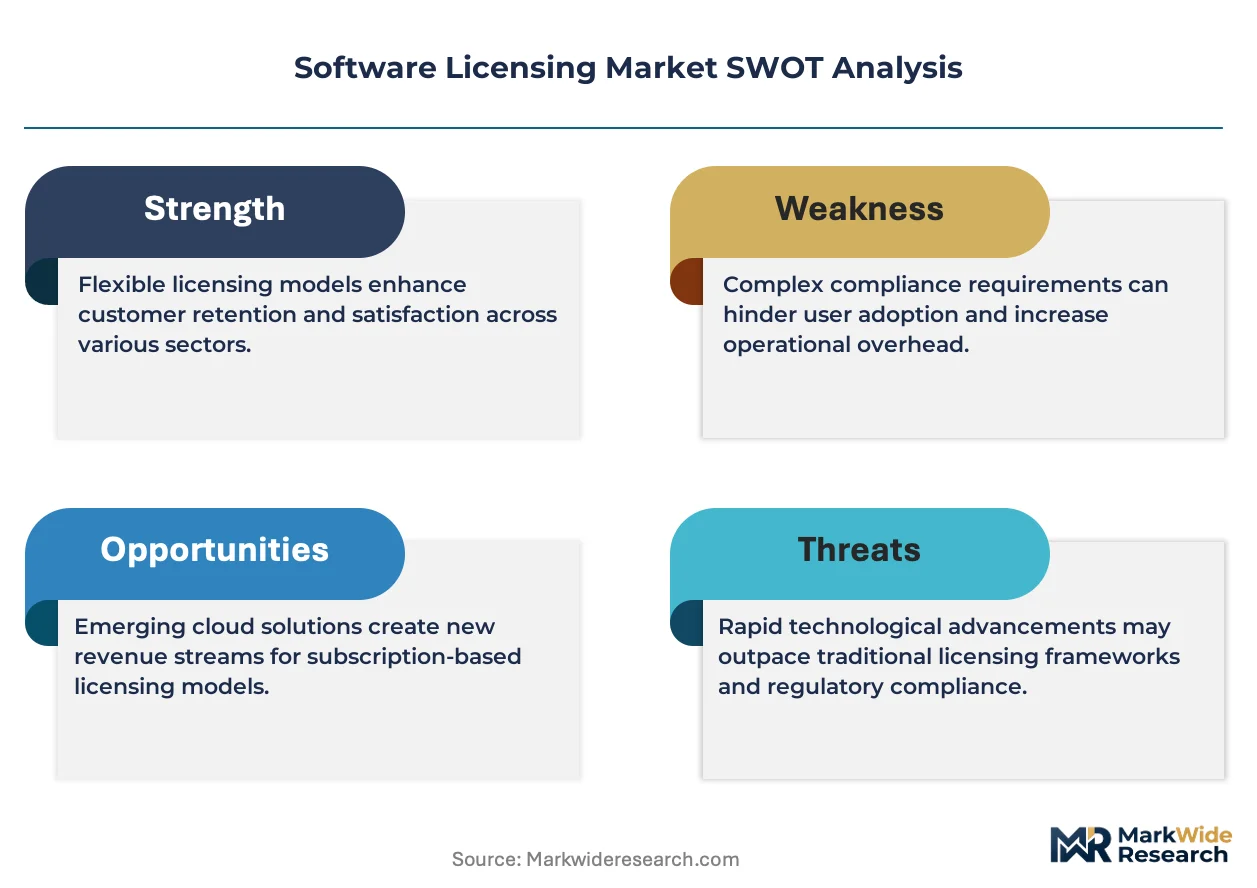
Platform licensing revenue is reshaping margin pools across the software value chain as vendors pivot from perpetual sales to recurring monetization. Microsoft Corporation leverages its cloud ecosystem to anchor enterprise subscription retention. Oracle Corporation specializes in database and application licensing that sustains high-margin maintenance streams. IBM Corporation positions its hybrid cloud portfolio to compete for workloads migrating off traditional on-premises estates.
Software licensing encompasses the legal frameworks, access controls, and monetization mechanisms governing how end-users obtain rights to install, execute, and distribute software programs, encompassing license key validation, usage metering, and entitlement management as core functional parameters. Subscription license models now lead growth as organizations prioritize operational flexibility over capital-intensive perpetual purchases, while cloud-based deployment captures expanding margin pools by embedding license management within hosted infrastructure services. On-premises licensing remains mature among regulated industries requiring localized data sovereignty, though hybrid architectures are bridging these configurations.
FDA oversight of software-as-medical-device in the United States, EU AI Act compliance requirements for automated decision-making systems in Europe, and China's GB standards for cybersecurity review of critical information infrastructure collectively elevate compliance automation as a procurement priority. GDPR data processing agreements in Europe further embed licensing terms within broader vendor governance frameworks. Stakeholders must monitor how fragmented regulatory timelines across jurisdictions will force licensing architecture decisions before harmonization emerges.
Market Dynamics
Enterprise migration from perpetual licenses to subscription models is compressing vendor revenue recognition cycles while expanding recurring revenue pools across the software value chain. This structural pivot forces licensing architecture redesigns that embed usage metering and dynamic entitlement management directly into cloud-hosted delivery platforms.
Growth Catalysts
- GDPR Data Processing Agreements:European enterprises now mandate automated compliance validation within vendor contracts, expanding demand for license management platforms that embed audit trails and consent tracking.
- Hybrid Cloud Workload Migration:Financial services and healthcare sectors in the United States are consolidating on-premises and multi-cloud licensing under unified entitlement systems to reduce vendor sprawl.
- Container Orchestration:Kubernetes-native licensing models enable per-pod metering that aligns software costs with actual compute consumption, attracting DevOps-centric procurement teams.
Market Restraints
- Regulatory Fragmentation:Divergent FDA software-as-medical-device pathways, EU AI Act conformity assessments, and China's GB cybersecurity reviews force vendors to maintain parallel licensing architectures.
- Technical Debt in Legacy Systems:Mainframe and client-server estates running COBOL and early Java stacks resist API-based license validation, trapping maintenance revenue in declining formats.
- Substitution by Open Source:PostgreSQL, MongoDB Community Edition, and Apache Kafka erode commercial database and middleware licensing volumes in price-sensitive segments.
Strategic Opportunities
- AI Governance Integration:The EU AI Act's risk-based classification system creates demand for licensing modules that restrict model training data access and inference volume by user tier.
- Edge Computing Deployment:Manufacturing and energy utilities in Germany and Japan require localized license servers that operate disconnected from cloud authentication services.
- Outcome-Based Entitlement:Healthcare providers in the United States are negotiating contracts where EHR access fees scale with patient throughput rather than seat count.
Industry Challenges
- Skills Gap in License Optimization:Enterprise IT procurement teams lack expertise in interpreting complex Bring-Your-Own-License terms across AWS, Azure, and Google Cloud Platform.
- Integration Complexity:SAP and Oracle estate migrations to S/4HANA and Fusion Cloud require reconciliation of decades of custom license agreements against new subscription metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software Licensing Market |
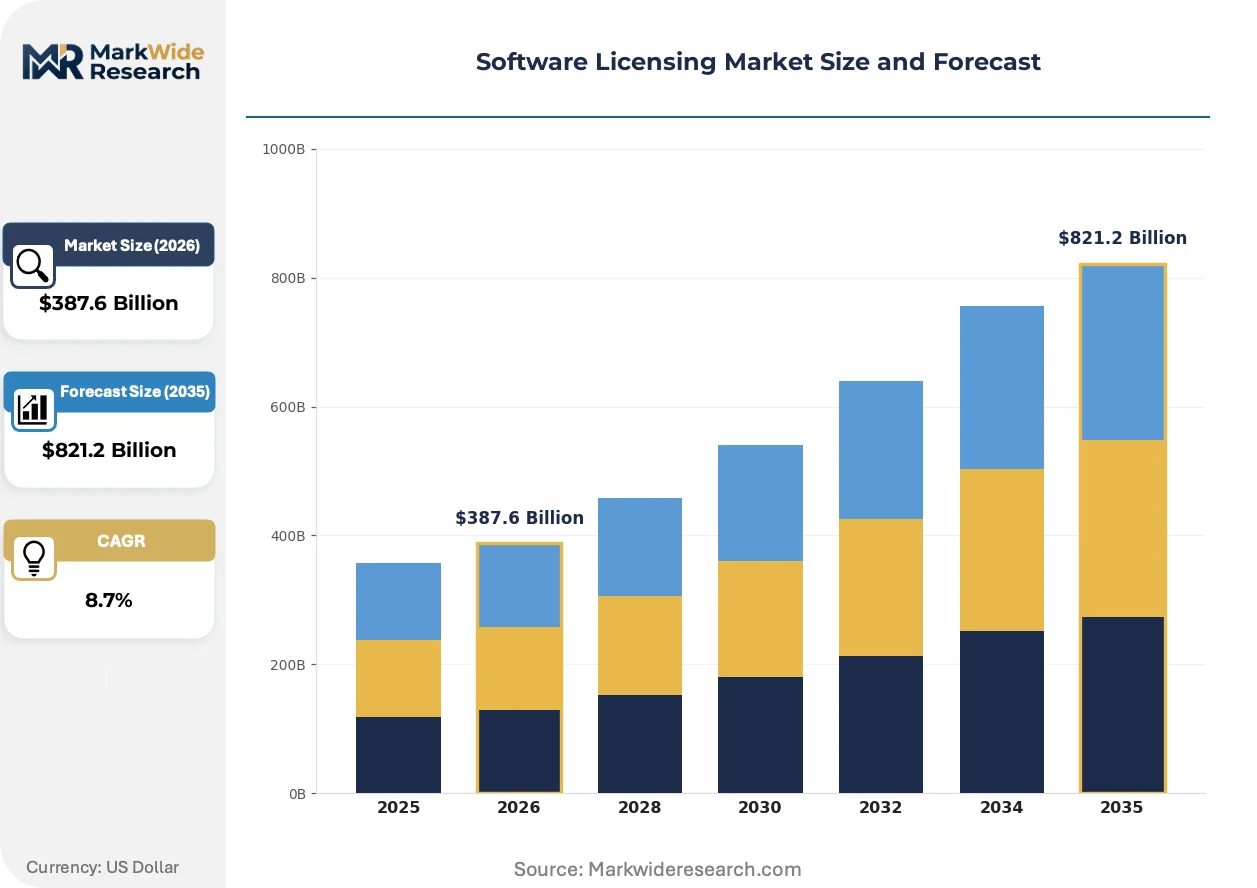
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | License Type: Perpetual License, Subscription License, Concurrent License, Open Source License Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: SMBs, Enterprises, Public Sector, Educational Institutions Product Offering: Desktop Software, Mobile Applications, Web Applications, Development Tools |
| Companies Covered | Flexera Software, Microsoft Corporation, IBM Corporation, Oracle Corporation, ServiceNow, Snow Software, Thales Group, DXC Technology, USU Software AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software Licensing Market Strategic Shifts
Software monetization mechanics are converging with infrastructure automation, embedding license governance directly into CI/CD pipelines and cloud control planes. This integration eliminates manual compliance checks while enabling real-time usage elasticity.
Blockchain-based license registries are rendering obsolete traditional hardware dongles and static key files for high-value engineering and design software. Aerospace and automotive manufacturers in Germany and Japan are piloting distributed ledger verification to prevent unauthorized CAD and simulation tool proliferation. The technology compresses audit cycles from quarters to minutes.
The EU AI Act's transparency mandates for high-risk automated decision systems are forcing vendors to embed explainability logs within license terms. Financial services deployers in France and the Netherlands must now document algorithmic training data provenance as a condition of software access. This regulatory layer adds compliance cost but creates differentiation for vendors with pre-certified governance modules.
Consumption-based procurement is displacing fixed-term subscriptions in data-intensive verticals. Media streaming platforms and genomics research facilities in the United States negotiate tiered access where license fees scale with petabytes processed. This model transfers utilization risk from buyer to vendor while demanding sophisticated metering infrastructure.
Software Licensing Market Segmentation
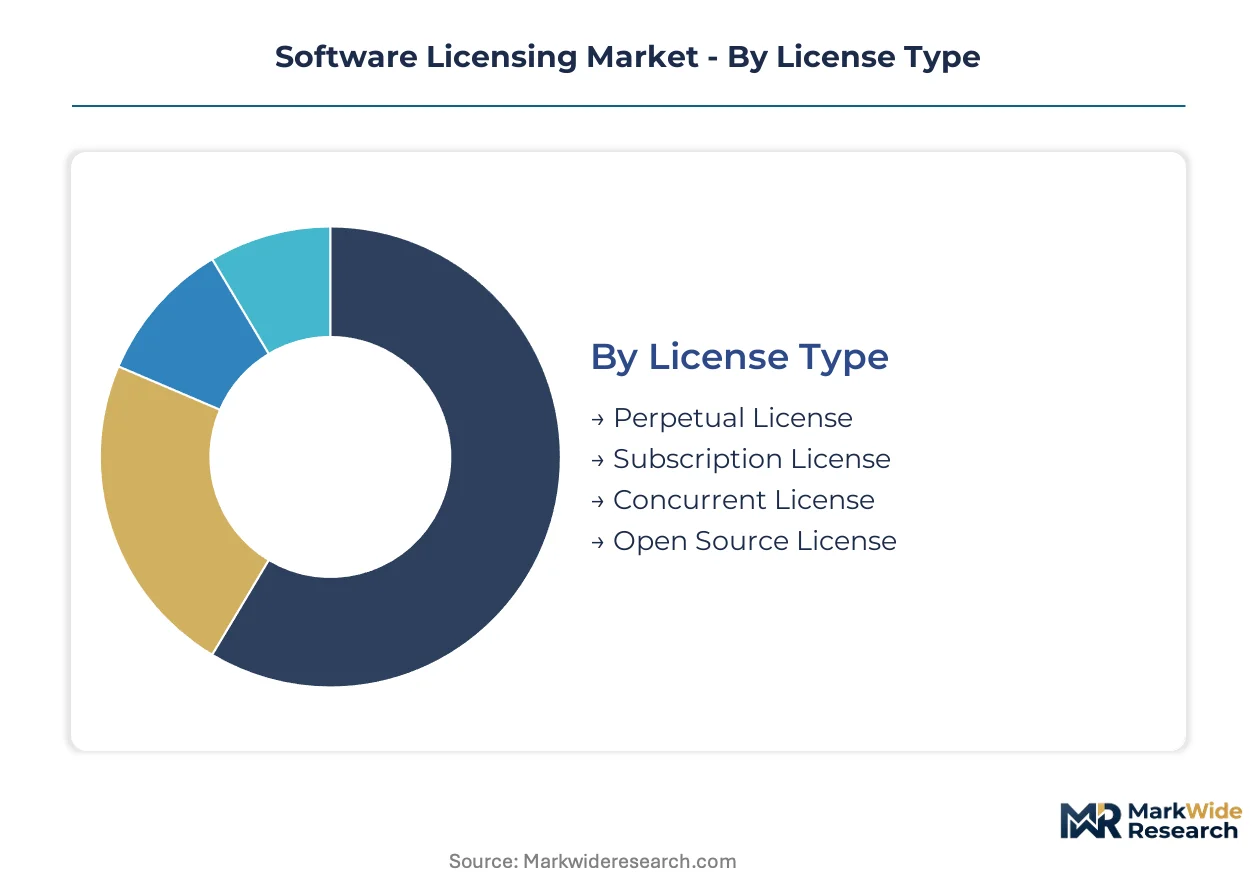
Segmentation in software licensing reveals how procurement cycles, compliance burdens, and technical architectures vary across customer profiles. License type and deployment model determine revenue recognition velocity, while end-user scale and product form factor shape entitlement complexity and vendor support economics.
License Type:
Cycle times diverge sharply: perpetual licenses lock capital for years while subscription models refresh annually and open source bypasses procurement entirely. Concurrent licenses occupy a middle ground with quarterly true-ups.
- Perpetual License:One-time purchase grants indefinite usage rights with annual maintenance fees for updates and support. Financial services firms in the United States retain perpetual database licenses to avoid recurring operational expenditure classification and satisfy capital reserve requirements.
- Subscription License:Time-bound access with recurring fees that bundle software, maintenance, and cloud infrastructure. Healthcare providers in Germany negotiate subscription EHR contracts to align software costs with annual budget cycles and reduce upfront capital allocation.
- Concurrent License:Floating access pool where multiple users share a fixed seat count, metered by simultaneous active sessions. Engineering departments at automotive manufacturers in Japan deploy concurrent CAD licenses to cover shift workers without per-seat overprovisioning.
- Open Source License:Permissive or copyleft terms permitting free modification and redistribution, typically requiring attribution or derivative disclosure. Government agencies in France adopt open source productivity suites to reduce vendor lock-in and satisfy public procurement transparency mandates.
Perpetual licenses dominate installed base across legacy enterprise estates. Subscription models are where expansion concentrates as procurement teams prioritize operational flexibility.
Deployment Model:
Cost tiers separate clearly: on-premises demands heavy capital investment, cloud shifts to operational spending, hybrid splits the difference, and managed services add premium overhead for outsourced operations.
- On-Premises:Software installed and operated within customer-controlled data centers with full infrastructure ownership. Defense contractors in the United States mandate on-premises deployment to satisfy FedRAMP authorization boundaries and classified network isolation requirements.
- Cloud-Based:Fully hosted delivery where vendors manage infrastructure, scaling, and availability through multi-tenant architectures. Retail chains in the United Kingdom accelerate cloud ERP adoption to eliminate data center refresh cycles and redirect IT headcount toward customer analytics.
- Hybrid:Split workloads across on-premises and cloud environments with unified identity and policy management. Pharmaceutical manufacturers in Switzerland deploy hybrid clinical trial management to keep patient data on-premises while leveraging cloud analytics for biomarker discovery.
- Managed Services:Vendor or third-party assumes operational responsibility including patching, backup, and performance tuning. Municipal governments in Canada contract managed services for tax collection systems to overcome internal skills gaps and stabilize support costs.
On-premises retains concentration in regulated verticals requiring data sovereignty. Cloud-based deployment is gaining share fastest as vendor roadmaps prioritize SaaS-native feature development.
End User:
Volume scales inversely with deal complexity: SMBs transact through self-service portals, enterprises demand custom terms, public sector requires lengthy compliance verification, and educational institutions negotiate site-wide blanket licenses.
- SMBs:Organizations with limited IT staff purchasing standardized packages through channel partners or direct digital storefronts. Professional services firms in Australia adopt SMB-tier accounting software with pre-configured workflows to accelerate deployment without implementation consultants.
- Enterprises:Large organizations with dedicated procurement teams negotiating multi-year agreements with volume discounts and custom service levels. Telecommunications operators in South Korea consolidate enterprise-wide software estates under single-vendor frameworks to simplify license compliance auditing.
- Public Sector:Government agencies subject to competitive bidding rules, security certification requirements, and political budget cycles. State healthcare authorities in Italy procure patient management systems through EU tender processes that mandate interoperability with national health card infrastructure.
- Educational Institutions:Universities and schools accessing discounted academic licensing with teaching and research use rights. Technical universities in the Netherlands license engineering simulation suites for classroom instruction and graduate research under campus-wide agreements.
Enterprises dominate contract value concentration. SMBs represent the steepest expansion trajectory as vendor self-service platforms reduce customer acquisition costs.
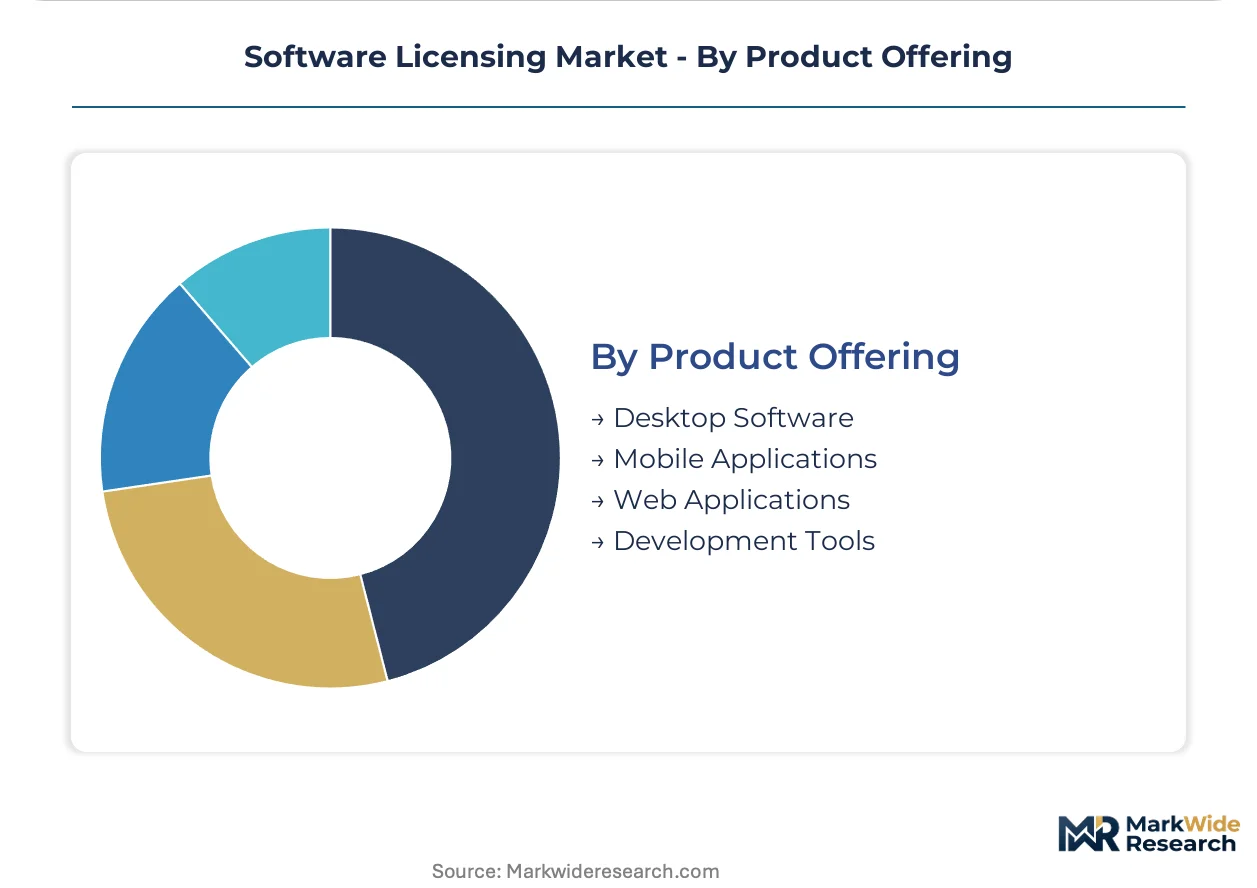
Product Offering:
Maturity gradients separate segments: desktop software carries decades of technical debt, mobile demands continuous OS adaptation, web applications iterate fastest, and development tools anchor ecosystem loyalty.
- Desktop Software:Installed applications running on Windows, macOS, or Linux with local file system access and offline functionality. Architecture firms in Spain maintain desktop BIM software for complex 3D modeling that exceeds browser-based rendering capabilities.
- Mobile Applications:Native or cross-platform apps distributed through Apple App Store and Google Play with device-specific optimization requirements. Logistics coordinators in Singapore rely on mobile fleet management apps for real-time delivery tracking and driver communication.
- Web Applications:Browser-delivered software with automatic updates, collaborative features, and reduced client-side maintenance. Marketing agencies in Brazil standardize on web-based design tools to enable real-time client collaboration without version control conflicts.
- Development Tools:IDEs, compilers, debuggers, and DevOps platforms supporting software creation and deployment pipelines. Fintech startups in Sweden subscribe to cloud-native development toolchains to accelerate microservices deployment and automated testing cycles.
Desktop software retains concentration in performance-intensive professional workflows. Web applications are climbing the fastest as browser capabilities mature and collaboration features become procurement priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity as procurement teams prioritize vendor consolidation and compliance automation over cost minimization. Indian and Brazilian enterprises exhibit higher sensitivity, driving adoption of open-source alternatives and concurrent licensing models to stretch limited IT budgets.
United States
Defense contractors and financial services firms anchor demand for FedRAMP-authorized on-premises deployment with strict data sovereignty requirements. FDA oversight of software-as-medical-device elevates compliance automation to a procurement mandate. The Washington DC-Baltimore corridor concentrates federal systems integrators modernizing legacy license estates.
Germany
Automotive manufacturers and industrial machinery producers drive consumption-based licensing for CAD and simulation workloads. The EU AI Act's conformity assessment requirements force vendors to embed explainability logs within license terms. Munich and Stuttgart host engineering clusters piloting blockchain-based license registries for distributed manufacturing teams.
China
State-owned enterprises and critical information infrastructure operators procure under GB cybersecurity review standards that mandate localized license servers. MIIT cloud service regulations redirect procurement toward domestic vendors with sovereign data handling certifications. Beijing and Shanghai concentrate hyperscaler facilities embedding license management within multi-tenant architectures.
India
IT services exporters and fintech startups prioritize subscription models to align software costs with project-based revenue cycles. RBI data localization guidelines for payment systems restrict cross-border license authentication flows. Bengaluru and Hyderabad anchor cloud-native development clusters negotiating Kubernetes-native per-pod metering arrangements.
Japan
Precision manufacturers and pharmaceutical firms demand edge-deployed license servers for disconnected factory floor operations. METI supply chain security guidelines embed software provenance verification within vendor qualification processes. The Nagoya-Toyota industrial corridor pilots localized entitlement systems for autonomous production line equipment.
Software Licensing Market Competitive Environment
Cloud-native platform vendors and legacy enterprise software incumbents split the market between recurring revenue architectures and maintenance-dependent installed bases. Consolidation pressures concentrate around entitlement management capabilities that span hybrid deployment models. Two archetypes dominate: ecosystem-anchored hyperscalers bundling licensing within infrastructure services, and specialized compliance-automation vendors embedding audit functionality. Competitive moves center on strategic partnerships with cloud infrastructure providers and portfolio diversification into AI governance modules.
Within the ecosystem-anchored tier, Microsoft Corporation and Oracle Corporation exemplify divergent retention strategies. Microsoft leverages its cloud infrastructure dominance to anchor enterprise subscription renewals through integrated productivity and security bundles. Oracle occupies a position sustaining high-margin maintenance streams through database and application licensing that resists migration to alternative platforms. IBM Corporation sits within the hybrid-cloud specialist archetype, positioning its portfolio to capture workloads migrating from traditional on-premises estates.
| Leading Market Players |
|---|
| Flexera Software |
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| ServiceNow |
| Snow Software |
| Thales Group |
| DXC Technology |
| USU Software AG |
| Others |
Value Chain & Pricing Dynamics
The Trans-Pacific fiber-optic cable corridor carries license management traffic between US hyperscaler data centers and Asian manufacturing clusters, with latency-sensitive authentication costs creating pricing premiums for edge-deployed entitlement servers that software vendors pass to defense contractors and financial services buyers seeking FedRAMP-compliant on-premises alternatives.
Pricing Analysis
Annual maintenance and support renewals generate lifetime value multiples exceeding initial license fees for perpetual estate holders. Pricing stratifies across enterprise subscription tiers, concurrent license pools, and open-source support contracts, with customization depth and compliance certification grade as primary differentiation drivers. Cost compression in SMB-tier SaaS subscriptions intensifies as self-service platforms reduce vendor sales overhead. Government agencies exhibit lowest price sensitivity due to security certification requirements, while Indian IT services exporters negotiate Kubernetes-native per-pod metering to align software costs with project revenue volatility.
Supply Chain Analysis
Export control restrictions under US EAR regulations limit cryptographic module distribution to certain license management hardware vendors, fragmenting authentication device supply chains. Software entitlement infrastructure draws from Taiwan for semiconductor components, Ireland for EU data residency compliance hosting, and the United States for FedRAMP-authorized cloud regions. Single-source vulnerability concentrates in hardware security module manufacturing. Distribution runs through hyperscaler marketplaces, systems integrator channels, and direct vendor portals with varying support tier attachments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise migration from perpetual to subscription models represents early-cycle expansion, with container-native metering and AI governance modules as underpenetrated adoption frontiers.
For Market Incumbents: Pre-empt open-source substitution by embedding compliance automation directly into subscription bundles, addressing PostgreSQL and MongoDB Community Edition erosion in data management tiers. Acquire Kubernetes-native entitlement specialists to defend against per-pod metering disruption from cloud-native challengers. Prioritize vertical integration into hardware security module design to reduce authentication infrastructure dependency.
For New Entrants and Emerging Players: Establish a beachhead in EU AI Act compliance tooling for high-risk automated decision systems, where explainability log integration remains underserved by incumbent license platforms. Target German automotive manufacturers with blockchain-based distributed license registries for CAD and simulation workloads. Deploy through hyperscaler marketplace listings to bypass enterprise procurement cycle friction.
For Investors and Strategic Acquirers: The EU AI Act's risk-based classification system reshapes the acquisition landscape toward vendors with pre-certified governance modules. Long-term viability concentrates on entitlement management platforms spanning hybrid deployment architectures. Target acquisition archetypes include compliance-automation specialists with audit trail capabilities and edge-computing license server providers for manufacturing verticals. Monitor FDA software-as-medical-device pathway clarifications as signal for healthcare licensing compliance demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft embeds license management within Azure AD to anchor enterprise retention cycles. |
| Acquisition of Specialist Firm | Oracle sustains maintenance streams by absorbing database workload optimization vendors. |
| Strategic Partnership | IBM partners with Red Hat to capture hybrid cloud entitlement migration from on-premises estates. |
| Geographic Expansion | Snow Software extends presence into Bengaluru to serve IT services exporters with project-aligned metering. |
| Product Launch | ServiceNow launches AI governance modules embedding EU AI Act conformity assessment workflows. |
Study Parameters
Desk research of SEC 10-K filings, hyperscaler capex disclosures, and open-source foundation governance records preceded structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners across North America, Europe, and Asia-Pacific. Primary fieldwork validated deployment model adoption rates and subscription renewal velocity assumptions. Secondary triangulation drew from customs records of software entitlement hardware imports, EU tender databases for public sector procurement patterns, and FDA software-as-medical-device submission logs. Bottom-up segment sizing and top-down macroeconomic anchoring were reconciled across analysis approaches.
Assumptions held fixed include regulatory timeline adherence for EU AI Act implementation and sustained hyperscaler marketplace growth as a distribution channel, while cloud migration velocity and open-source substitution rates were modeled as scenario-dependent variables. The analytical framework segmented by deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs were derived from license transaction volume trajectories and recurring revenue recognition patterns. Forecast inputs incorporated Kubernetes adoption curves in DevOps-centric enterprises and FedRAMP authorization queue processing rates.
Sensitivities concentrate around regulatory fragmentation persistence and open-source database performance parity milestones. Forecasts reflect documented assumptions regarding enterprise procurement cycle elongation and compliance automation budget allocation. Cross-checking against hyperscaler earnings call commentary on enterprise commitment value is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Automated Testing Software Market
Software & Services
Design Collaboration Software Market
Software & Services
Sourcing Software Market
Software & Services
Professional Service Automation Market
Software & Services
Oracle Services Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Live Software Market
Software & Services
Smartphone Applications Market
Software & Services
Asia Pacific Content Services Platform Market
Software & Services
Europe Yacht Management Software Market
Software & Services
Camp Management Software Market
Software & Services
Global IVR Software Market
Software & Services
Global Application Release Automation Market
Software & Services
Credit Management Software Market
Software & Services
Office Software Market
Software & Services
Latin America Human Resource (HR) Technology Market