
 US Virtual Reality Market | 2026-2036
US Virtual Reality Market Size, Share, and Industry Trends Forecast 2026-2036
US Virtual Reality Market Insights
Subscription-based hardware leasing and asset-light deployment models is tilting competitive access toward mid-tier healthcare systems and educational institutions that previously faced capital barriers. Meta Platforms, Inc. leverages its vertically integrated ecosystem spanning headsets, operating systems, and content stores to sustain pricing power across consumer and enterprise tiers. NVIDIA Corporation anchors high-fidelity rendering pipelines through its GPU architectures and cloud streaming infrastructure, while Qualcomm Incorporated specializes in mobile-optimized chipsets that dominate standalone headset power envelopes.
Virtual reality denotes a computer-generated immersive environment delivered through head-mounted displays with stereoscopic optics, sub-20ms motion-to-photon latency thresholds, and six-degrees-of-freedom positional tracking for real-time user embodiment in synthetic spaces. Headsets command the dominant hardware value pool, though software layers capture expanding margin as platform fees and enterprise licensing models mature. Healthcare applications within the end-user dimension exhibit the steepest trajectory, driven by FDA-cleared surgical simulation protocols and chronic pain management programs that replace pharmacological interventions.
FCC spectrum allocations for unlicensed millimeter-wave bands shape wireless headset performance standards, while FDA premarket notification pathways determine clinical VR product commercialization timelines. OSHA ergonomic guidelines for extended immersive work sessions increasingly influence enterprise procurement specifications. Stakeholders must monitor how NHTSA rules on driver distraction intersect with automotive VR entertainment integrations before committing to in-vehicle platform development.
Market Dynamics
FDA premarket notification pathways for VR-based medical devices are compressing commercialization timelines and redirecting R&D investment toward clinical-grade hardware specifications.
Growth Catalysts
- Healthcare reimbursement expansion:CMS coverage determinations for VR therapeutic interventions in chronic pain management are expanding addressable patient populations beyond self-pay segments.
- OSHA ergonomic guideline evolution:Draft standards for extended immersive work sessions are legitimizing enterprise VR procurement through documented safety protocols.
- Bay Area talent concentration:Hardware engineering expertise and venture capital networks in California's technology corridor accelerate product iteration cycles for headset manufacturers.
Market Restraints
- Display panel supply concentration:Micro-OLED fabrication capacity concentrates among Asian semiconductor foundries, creating input bottlenecks for high-resolution headset production.
- Motion-to-photon latency thresholds:Sub-20 millisecond synchronization requirements between positional tracking and visual rendering impose hard technical constraints on wireless chipset architectures.
- FCC spectrum allocation friction:Unlicensed millimeter-wave band congestion in dense urban deployments degrades untethered headset performance consistency.
Strategic Opportunities
- Rural healthcare system penetration:Subscription-based hardware leasing models are dismantling capital barriers for mid-tier hospital networks in underserved states.
- Surgical simulation credentialing:Residency program accreditation bodies are incorporating VR proficiency benchmarks into formal training requirements.
- 5G edge computing convergence:Cloud-rendered immersive streams are enabling lightweight headset form factors by offloading GPU-intensive processing to distributed server infrastructure.
Industry Challenges
- Clinical validation timelines:FDA 510(k) clearance pathways for novel therapeutic VR applications require multi-site randomized controlled trials that extend development cycles.
- Interoperability fragmentation:Proprietary tracking systems and content distribution platforms create integration friction for healthcare IT departments managing mixed-vendor deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Virtual Reality Market |
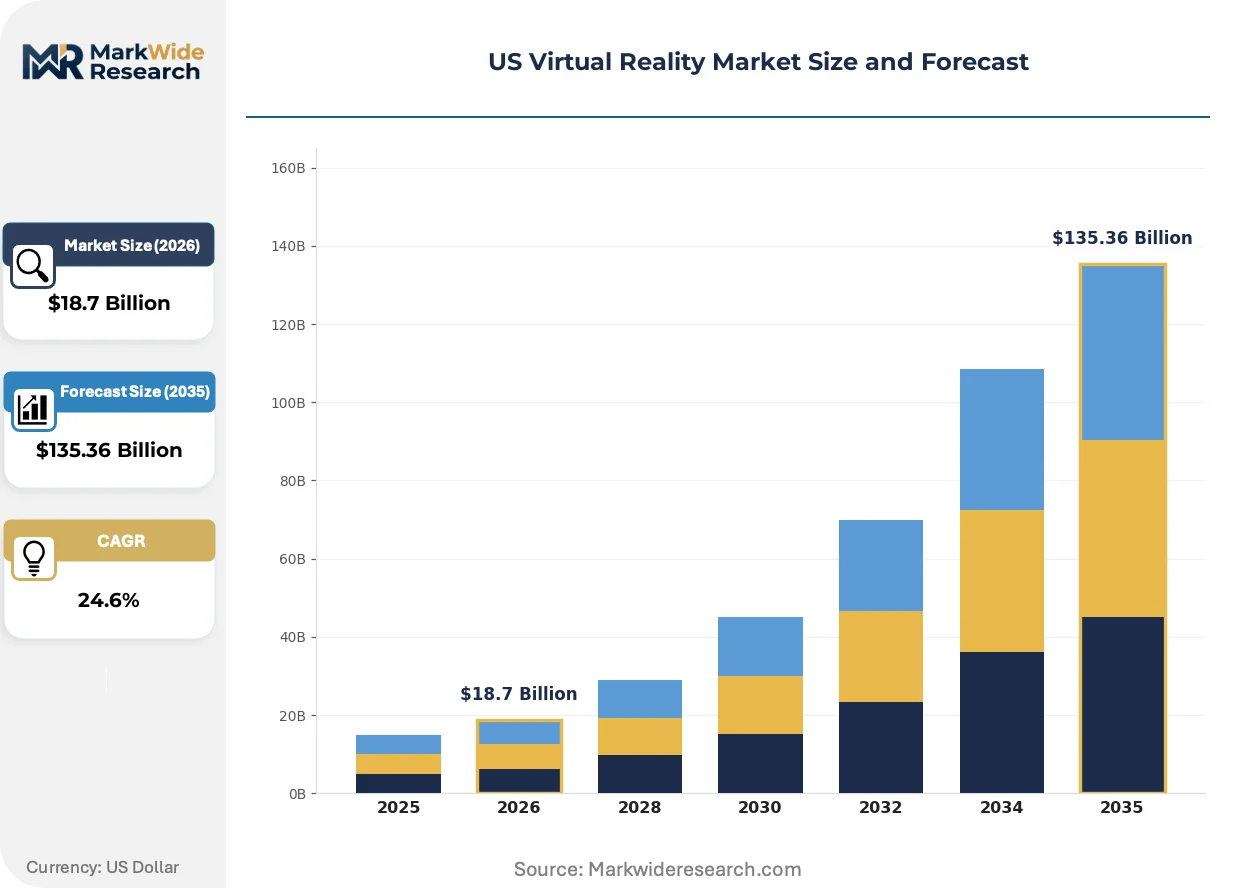
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headsets, Software, Accessories, Controllers End User: Gaming, Education, Healthcare, Military Deployment: Cloud-based, On-premises, Hybrid, Standalone Technology: Augmented Reality, Mixed Reality, 3D Audio, Haptic Feedback |
| Companies Covered | Meta Platforms, Inc., Microsoft Corporation, Google LLC, Unity Technologies, NVIDIA Corporation, Qualcomm Incorporated, Apple Inc., Valve Corporation, Magic Leap, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Virtual Reality Market Trends and Innovations
Computational architectures for immersive rendering are bifurcating between cloud-dependent streaming and on-device inference, with enterprise buyers arbitraging latency against mobility requirements.
Pass-through mixed reality is hybridizing optical architectures by integrating outward-facing cameras with pancake lens systems. Surgical training programs at academic medical centers are adopting these headsets for blended simulation environments. The technology is hybridizing previously distinct VR and AR procurement categories into unified immersive hardware budgets.
FDA draft guidance on VR-based medical devices is formalizing software-as-a-medical-device classification criteria. Hardware manufacturers must now submit electromagnetic compatibility and biocompatibility testing for headsets intended for sterile field deployment. California-based developers are front-loading clinical evidence packages to preempt regulatory review delays.
Asset-light deployment models are displacing perpetual licensing for enterprise VR platforms. Healthcare systems in Texas and Florida are prioritizing per-procedure pricing for surgical simulation content over upfront content library purchases. This shift concentrates vendor risk on utilization forecasting rather than capital recovery timelines.
US Virtual Reality Market Segmentation
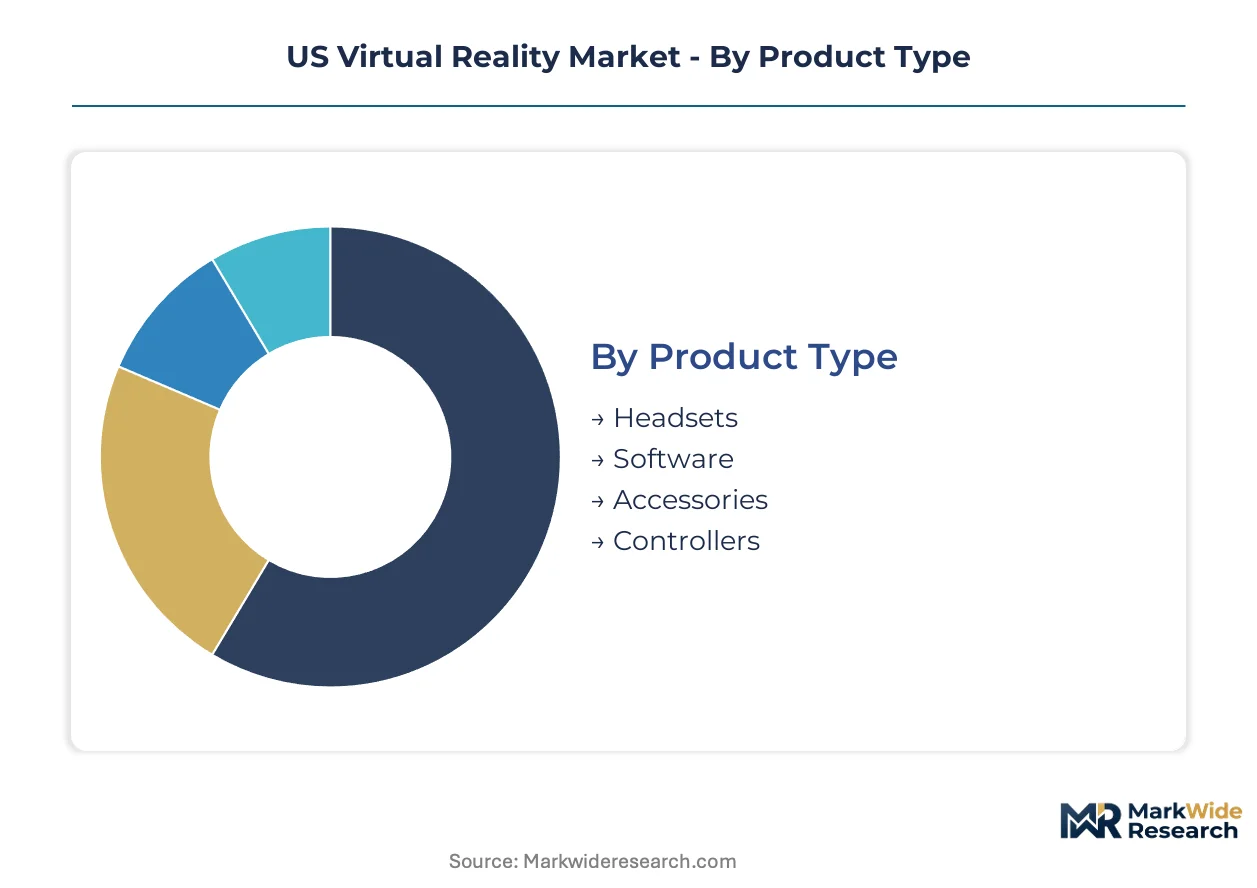
Segmentation reveals how capital intensity, regulatory pathways, and latency requirements fragment procurement patterns across buyer types. Hardware specifications diverge sharply between FDA-cleared clinical deployments and consumer entertainment use cases.
Product Type:
Cost tier stratification separates capital-intensive hardware purchases from recurring software subscriptions and peripheral attachments.
- Headsets:Stereoscopic head-mounted displays with sub-20ms motion-to-photon latency and six-degrees-of-freedom positional tracking anchor the hardware value pool. Demand concentrates in California's Bay Area technology corridor, where FDA-cleared surgical simulation protocols drive specifications toward clinical-grade biocompatibility and electromagnetic compatibility testing.
- Software:Platform operating systems, content distribution stores, and enterprise licensing modules capture expanding margin as subscription models displace perpetual licenses. Healthcare systems in Texas and Florida prioritize per-procedure pricing for surgical simulation content over upfront library purchases.
- Accessories:External sensors, charging stations, and protective cases extend hardware lifecycle value.
- Controllers:Hand-tracking peripherals with haptic feedback enable precision interaction in therapeutic rehabilitation and military training scenarios.
Headsets command the established base. The steepest expansion runs through software as platform fees and enterprise licensing models mature.
End User:
Application-specific requirements reshape hardware specifications, with clinical and defense deployments imposing certification burdens absent from consumer segments.
- Gaming:Consumer entertainment drives volume through standalone headset affordability and content store attach rates.
- Education:K-12 and university deployments prioritize durable hardware specifications and bulk procurement frameworks.
- Healthcare:Surgical training and therapeutic rehabilitation represent the fastest-expanding buyer segment, with FDA premarket notification pathways compressing commercialization timelines for VR-based medical devices. CMS coverage determinations for chronic pain management interventions expand addressable patient populations beyond self-pay segments.
- Military:Combat simulation and equipment maintenance training require ruggedized hardware with classified network compatibility.
Gaming anchors installed volume. Healthcare climbs the fastest as reimbursement expansion and residency accreditation requirements formalize VR proficiency benchmarks.
Deployment:
Customer type and mobility requirements determine whether processing localizes on-device, distributes to edge infrastructure, or centralizes in enterprise data centers.
- Cloud-based:GPU-intensive rendering offloads to distributed server infrastructure, enabling lightweight headset form factors. 5G edge computing convergence supports untethered surgical simulation in academic medical centers.
- On-premises:Healthcare IT departments and defense contractors mandate local data sovereignty for patient records and classified training scenarios.
- Hybrid:Mixed architectures balance latency-sensitive tracking against compute-intensive rendering pipelines.
- Standalone:Mobile-optimized chipsets dominate power envelopes for wireless consumer and field military deployments.
On-premises deployments retain the established base in regulated sectors. Cloud-based architectures gain share fastest as millimeter-wave spectrum allocations mature.
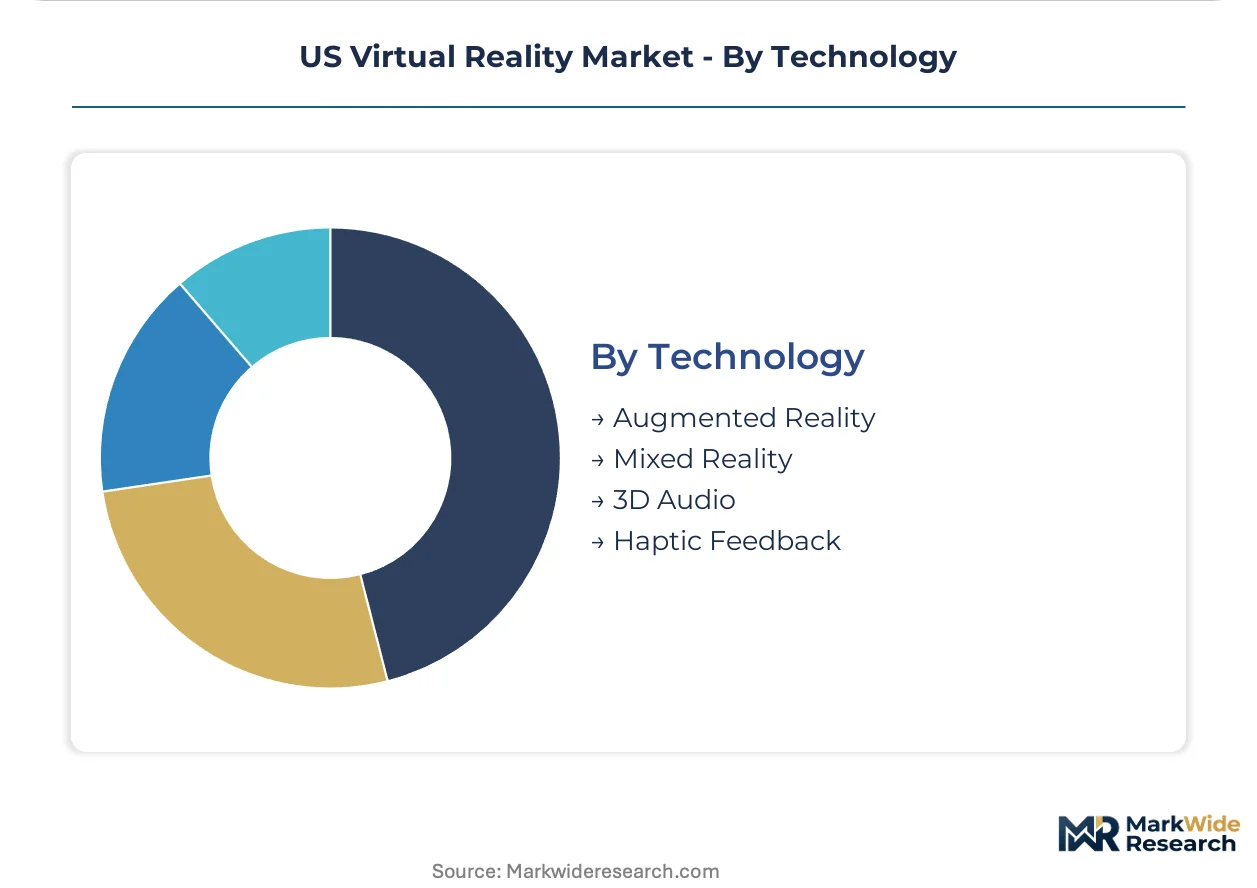
Technology:
Maturity curves separate optical display innovations from sensory feedback layers still navigating technical constraints.
- Augmented Reality:Optical see-through displays overlay synthetic content on physical environments.
- Mixed Reality:Pass-through camera systems hybridize with pancake lens architectures, unifying previously distinct VR and AR procurement categories into immersive hardware budgets at academic medical centers.
- 3D Audio:Spatial sound processing enhances embodiment precision in surgical training and combat simulation.
- Haptic Feedback:Tactile response systems remain constrained by actuator miniaturization limits for extended immersive sessions.
Mixed Reality commands the established base as pass-through architectures displace pure VR headsets. Haptic Feedback expands most slowly pending actuator breakthroughs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal reimbursement policies and state-level healthcare innovation incentives are redistributing VR procurement across American metropolitan corridors. The analysis examines five sub-regional clusters where hardware engineering density, clinical adoption velocity, and venture deployment patterns concentrate differentially.
California Bay Area
FDA-cleared surgical simulation protocols and chronic pain management programs drive enterprise headset specifications toward clinical-grade biocompatibility standards. The state's medical device regulatory sandbox accelerates premarket notification timelines for VR-based therapeutic platforms. San Francisco and San Jose anchor the densest hardware engineering talent pools, where Meta Platforms and Apple Inc. maintain competing headset development campuses.
Greater Boston
Academic medical center residency programs are incorporating VR proficiency benchmarks into formal surgical training accreditation requirements. Massachusetts digital health tax incentives reduce capital barriers for mid-tier hospital networks adopting subscription-based hardware leasing. Cambridge and the Route 128 corridor concentrate venture-backed startups developing haptic feedback controllers for therapeutic rehabilitation.
Texas Triangle
Per-procedure pricing models for surgical simulation content are displacing upfront library purchases across Houston and Dallas-Fort Worth health systems. The state's medical malpractice liability framework creates favorable conditions for VR-based surgical credentialing programs. Austin's technology corridor attracts hardware engineering talent from coastal markets seeking lower operational costs.
Pacific Northwest
OSHA ergonomic guideline adoption for extended immersive work sessions is legitimizing enterprise VR procurement through documented safety protocols. Washington state's clean energy mandates align with low-power chipset requirements for wireless standalone headsets. Seattle and Bellevue host cloud computing infrastructure supporting GPU-intensive rendering pipelines for untethered surgical simulation.
Southeast Florida
CMS coverage determinations for VR therapeutic interventions in chronic pain management are expanding Medicare-reimbursable patient populations beyond self-pay segments. Florida's medical tourism infrastructure integrates VR preoperative visualization into orthopedic and cardiovascular service lines. Miami's health system networks are piloting pass-through mixed reality headsets for blended surgical planning environments.
US Virtual Reality Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated platform ecosystems and specialized component architectures. Hardware value pools concentrate among headset manufacturers with captive operating systems and content distribution infrastructure. Three strategic archetypes dominate: consumer-facing platform operators with integrated hardware-software-content stacks; semiconductor specialists optimizing mobile-optimized chipsets for power-constrained standalone devices; and enterprise-focused simulation developers with FDA-cleared therapeutic protocols. Competitive moves center on backward integration into display panel supply chains and strategic partnerships with academic medical centers for clinical validation.
Within the integrated platform tier, Meta Platforms, Inc. and Apple Inc. exemplify competing approaches to ecosystem control, with the former emphasizing open content distribution and the latter prioritizing proprietary hardware-software optimization. NVIDIA Corporation anchors the semiconductor specialist archetype through GPU architectures supporting high-fidelity rendering pipelines. These three entities collectively represent the dominant competitive anchors shaping procurement specifications across consumer entertainment and clinical deployment segments.
| Leading Market Players |
|---|
| Meta Platforms, Inc. |
| Microsoft Corporation |
| Google LLC |
| Unity Technologies |
| NVIDIA Corporation |
| Qualcomm Incorporated |
| Apple Inc. |
| Valve Corporation |
| Magic Leap, Inc. |
| Others |
Pricing and Supply Chain Analysis
Port of Oakland container throughput dynamics transmit cost volatility from Asian micro-OLED foundries through to Bay Area headset assemblers, compressing margins for non-vertically integrated manufacturers while amplifying FDA-grade certification premiums for clinical-tier hardware.
Pricing Analysis
Certification level creates the primary spread between clinical and consumer tiers, with FDA 510(k)-cleared headsets commanding substantial premiums over entertainment-grade equivalents. Subscription-based SaaS-tiered pricing for surgical simulation content is displacing perpetual licenses across Texas and Florida health systems. Cost compression in mid-tier hardware stems from Qualcomm's mobile-optimized chipset commoditization. Price-sensitive mid-tier hospital networks prioritize per-procedure software models, while academic medical centers exhibit lowest sensitivity due to accreditation-driven procurement mandates.
Supply Chain Analysis
Micro-OLED display substrates and gallium nitride power amplifiers feed from Taiwan, South Korea, and Japan, creating geographic concentration in advanced semiconductor fabrication. Rare earth magnet dependencies for compact haptic actuators draw from Chinese processing facilities. Single-source vulnerability concentrates in micro-OLED backplane lithography equipment. Distribution runs through California-based contract manufacturers serving Meta and Apple assembly lines, with secondary nodes in Austin for defense-ruggedized variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of hardware engineers with sub-20ms motion-to-photon latency optimization expertise constrains product iteration velocity, privileging incumbents with captive Bay Area talent pools over capital-rich challengers.
For Market Incumbents: Build regulatory data moats through preemptive FDA Q-Sub engagement for mixed-reality surgical platforms. Accelerate backward integration into micro-OLED supply through strategic partnerships with Taiwanese foundries. Counter emerging cloud-rendering entrants by emphasizing on-premises data sovereignty for hospital IT departments. For New Entrants and Emerging Players: Rural healthcare systems in the Texas Triangle and Southeast Florida represent the most penetrable entry point for subscription-leased surgical simulation hardware. Target GPO contract managers at mid-tier hospital networks seeking per-procedure pricing alternatives. Pursue white-label partnerships with established semiconductor reference design houses to bypass multi-year headset development cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from defense contractors spinning non-core VR training divisions amid portfolio rationalization. Long-term viability hinges on sustained CMS reimbursement expansion for chronic pain therapeutic protocols. Monitor FDA draft guidance publication velocity as inflection signal for clinical-grade hardware valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Notification | Accelerates commercialization timelines for VR-based surgical simulation platforms through streamlined regulatory pathways. |
| Academic Medical Center Partnership | Secures clinical validation data and residency program accreditation influence for therapeutic hardware specifications. |
| Micro-OLED Supply Agreement | Locks fabrication capacity for high-resolution displays amid Asian foundry concentration constraints. |
| Cloud-Edge Rendering Infrastructure | Enables lightweight headset form factors through 5G millimeter-wave spectrum utilization in dense urban corridors. |
| Per-Procedure Pricing Model | Aligns vendor revenue with hospital utilization patterns across Texas and Florida health system networks. |
Research Methodology
A standing panel of biomedical engineers, hospital purchasing committee chairs, FDA regulatory consultants, and venture capital partners provided ongoing calibration across the study period. Primary interview data combined with secondary validation from FDA 510(k) clearance databases, CMS national coverage determination records, and hyperscaler capex disclosures for cloud rendering infrastructure. Bottom-up unit economics for headset bill-of-materials triangulated against top-down venture deployment patterns in the Bay Area technology corridor.
Scenario-bracketing around reimbursement expansion velocity and micro-OLED yield improvement curves anchored the projection framework across the analysis window. Segmentation dimensions modeled include hardware tier, deployment architecture, end-user vertical, and regional healthcare innovation incentive density. CAGRs derived from historical FDA clearance timeline compression and residency program accreditation mandate adoption rates, with cross-reference to FCC spectrum allocation proceedings for wireless performance standards.
Macroeconomic conditions sit as an overlay; deviation in federal healthcare reimbursement policy or Taiwan semiconductor foundry utilization rates would shift the trajectory materially. Cross-checking against hospital capital equipment procurement cycle data from GPO contract repositories is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality for Consumer Market
Virtual Reality (VR) and Augmented Reality (AR)
Tourists Virtual Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Dressing Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Florida Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Canada Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Para-Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Smart Glasses for Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Location-Based Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Firefighter Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Commercial Augmented Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
India Desktop Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market