
 Europe Virtual Reality Market | 2026-2036
Europe Virtual Reality Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Virtual Reality Market Foresight
Germany's industrial corridor is reshaping enterprise VR deployment through precision manufacturing partnerships. Meta Platforms leverages its social ecosystem to sustain consumer headset penetration across Western Europe. Sony Corporation anchors premium entertainment experiences through its PlayStation VR platform. Varjo Technologies Oy specializes in ultra-high-resolution headsets for professional simulation and design review.
Virtual Reality denotes a computer-generated immersive environment delivered through head-mounted displays with sub-20ms motion-to-photon latency, spatial audio rendering, and six-degrees-of-freedom tracking for real-time user interaction in enclosed digital spaces. Hardware dominates procurement budgets as enterprises replace first-generation tethered systems with wireless all-in-one headsets. Healthcare applications represent the fastest-growing segment as hospitals in France and the Netherlands deploy VR for pain management and surgical planning. Gaming retains the largest installed base among individual end users, though margin pools are shifting toward enterprise software licensing.
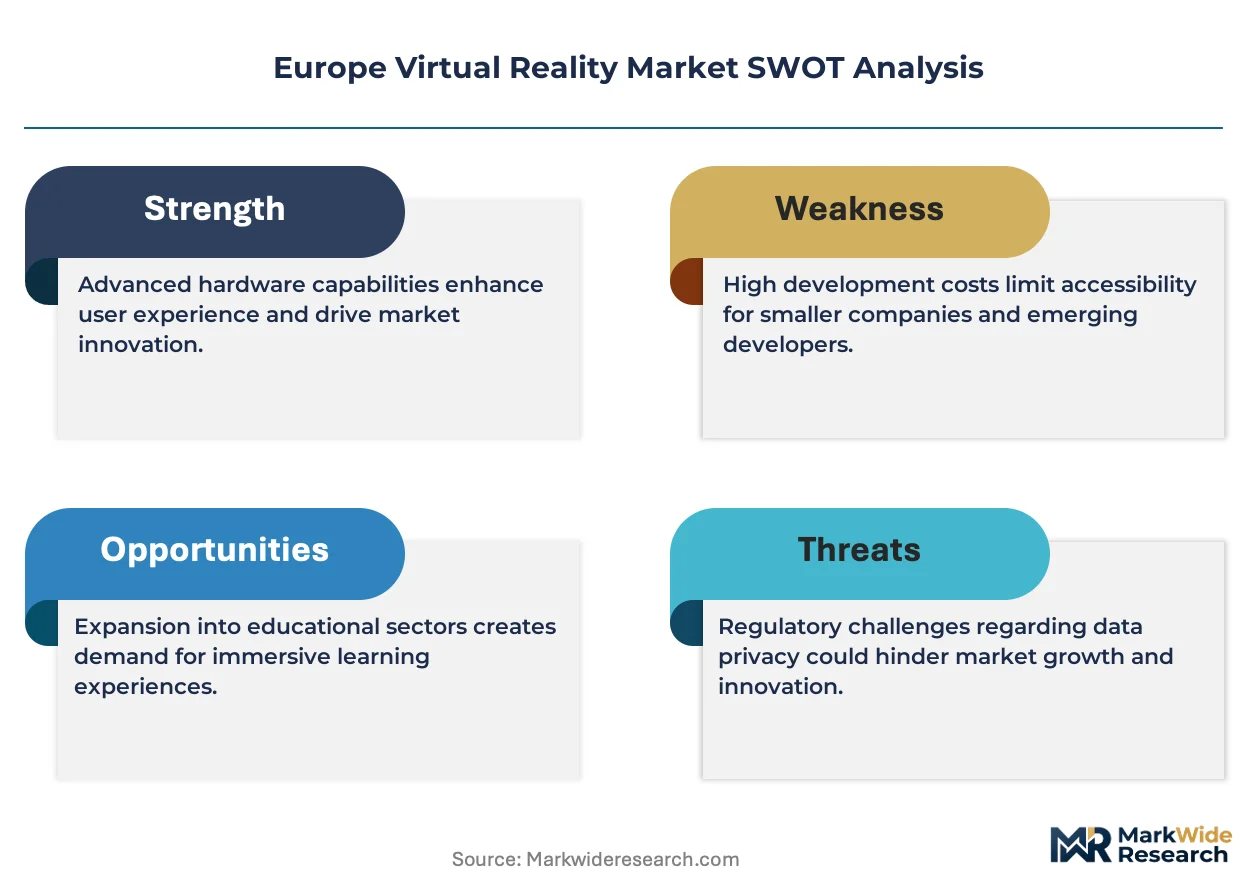
EMA guidelines on digital therapeutics and the EU AI Act's risk-classification framework for biometric data processing are tightening compliance requirements for healthcare VR deployments. CE marking under the MDR governs medical-grade headsets, while GDPR restricts biometric data retention periods for consumer platforms. Stakeholders must monitor how the EU Green Deal's embodied carbon rules affect headset manufacturing supply chains and end-of-life recycling obligations.
Market Dynamics
Enterprise procurement in Germany's automotive and industrial engineering sectors is compressing replacement cycles for first-generation tethered VR systems, forcing vendors to accelerate wireless all-in-one development roadmaps.
Growth Catalysts
- EU AI Act compliance architecture:Risk-classification frameworks for biometric data processing are mandating transparent data governance, pushing healthcare VR vendors toward medical-grade certification pipelines that accelerate hospital adoption.
- France surgical training expansion:Teaching hospitals are integrating immersive headsets into residency programs, creating institutional procurement channels that standardize VR-assisted operative education.
- Wireless display streaming:Wi-Fi 6E and local edge computing are eliminating cable constraints in industrial simulation labs, reducing setup friction and expanding deployment footprints.
Market Restraints
- GDPR biometric data retention limits:Consumer platforms face compressed data storage windows for gaze tracking and facial mapping, increasing compliance engineering costs and limiting feature persistence.
- Display panel supply concentration:Micro-OLED and pancake lens modules depend on East Asian fabrication capacity, exposing European headset assemblers to logistics bottlenecks and currency volatility.
- Latency floor in wireless architectures:Sub-20ms motion-to-photon thresholds remain difficult to guarantee across congested enterprise Wi-Fi environments, constraining high-precision simulation use cases.
Strategic Opportunities
- Netherlands pain management protocols:Academic medical centers are piloting VR distraction therapy for chronic pain and pediatric procedures, establishing reimbursement precedents for digital therapeutics.
- EU Green Deal embodied carbon rules:End-of-life recycling obligations and supply chain disclosure requirements are creating first-mover advantages for vendors with modular headset designs and circular material flows.
- Spatial computing convergence:Integration of hand tracking, eye tracking, and passthrough mixed reality is opening architectural visualization and factory planning applications previously served by dedicated CAD immersion suites.
Industry Challenges
- CE marking timeline under MDR:Medical-grade headset certification requires extensive clinical validation documentation, stretching product launch schedules and freezing development capital for 18-24 month cycles.
- Enterprise integration complexity:Industrial VR deployments must interface with legacy PLM and MES systems through custom API middleware, demanding scarce systems integration expertise concentrated in German engineering consultancies.
- Optical engineering talent scarcity:Waveguide and varifocal display design requires specialized physics and materials science capabilities, with European university pipelines producing fewer than 200 qualified graduates annually.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Virtual Reality Market |
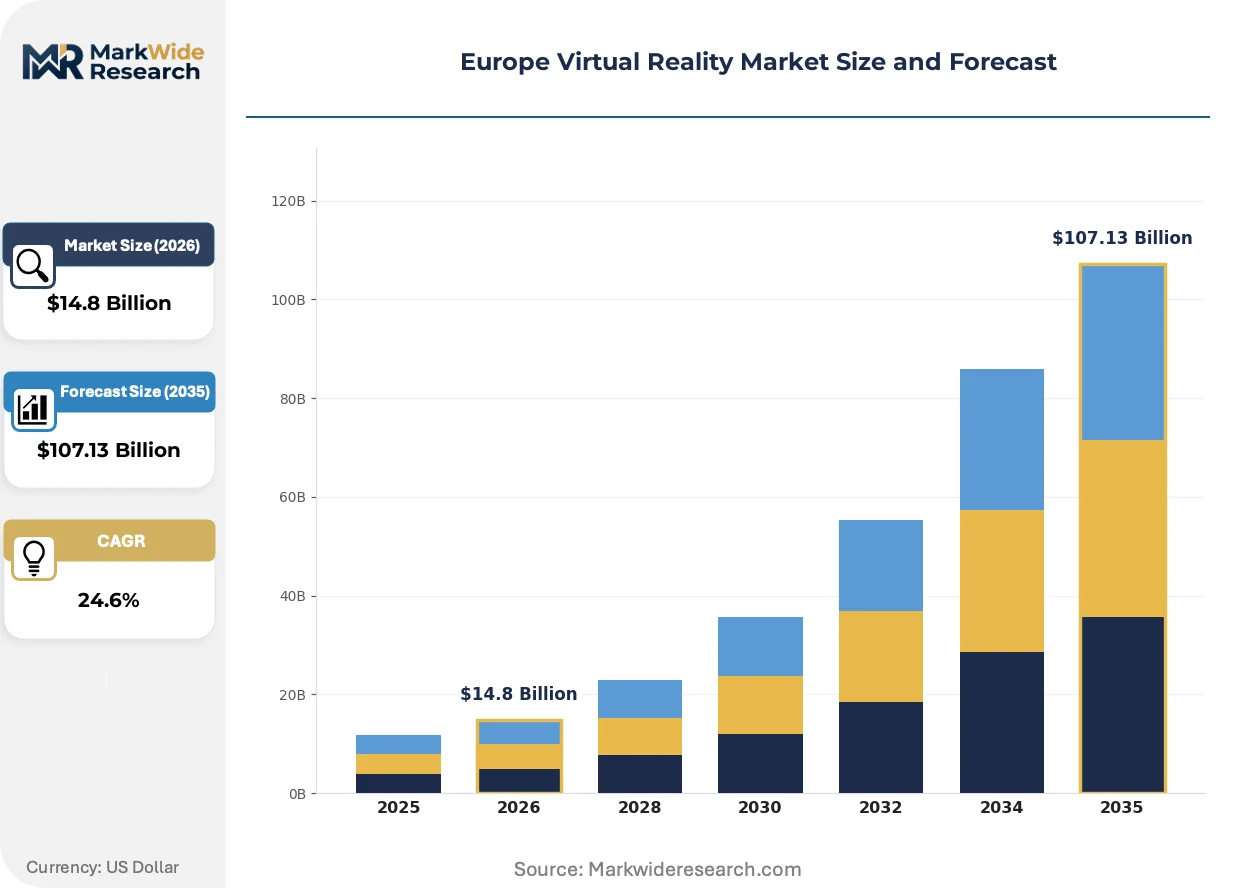
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $107.13 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Accessories, Content Application: Gaming, Healthcare, Education, Military End User: Individuals, Enterprises, Institutions, Developers Technology: Augmented Reality, Mixed Reality, 360-Degree Video, Others |
| Companies Covered | Meta Platforms, Inc., Sony Corporation, Microsoft Corporation, HTC Corporation, Apple Inc., Qualcomm Incorporated, Valve Corporation, Varjo Technologies Oy, Pico Interactive, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Virtual Reality Market Shifts & Advancements
Wireless all-in-one architectures are displacing PC-tethered systems as the default enterprise specification, while regulatory pressure on biometric data handling is forcing hardware redesigns and software stack rearchitectures.
Optical stack technology is migrating from Fresnel lenses to pancake lens assemblies with local dimming arrays. German automotive design studios and French aerospace engineering centers are specifying these configurations for extended wear comfort during 4-8 hour simulation sessions. The shift is compressing bill-of-materials differentiation between mid-tier and premium headset tiers, forcing vendors to compete on thermal management and audio spatialization instead.
EMA guidelines on digital therapeutics are tightening clinical evidence requirements for VR-based pain management and cognitive rehabilitation. Device manufacturers must now submit randomized controlled trial data for CE marking under the MDR, extending development timelines but creating regulatory moats against consumer-grade hardware entrants. French and Dutch hospital procurement committees are prioritizing certified therapeutic platforms over general-purpose headsets.
Hospital procurement committees are unbundling hardware acquisition from software licensing and clinical training services. French university hospital systems now issue separate RFPs for headset supply, therapeutic content platforms, and implementation support, fragmenting vendor relationships and compressing margin pools at the device layer. This pattern is most visible in the Netherlands, where regional health authorities aggregate purchasing across multiple institutions.
Europe Virtual Reality Market Segmentation
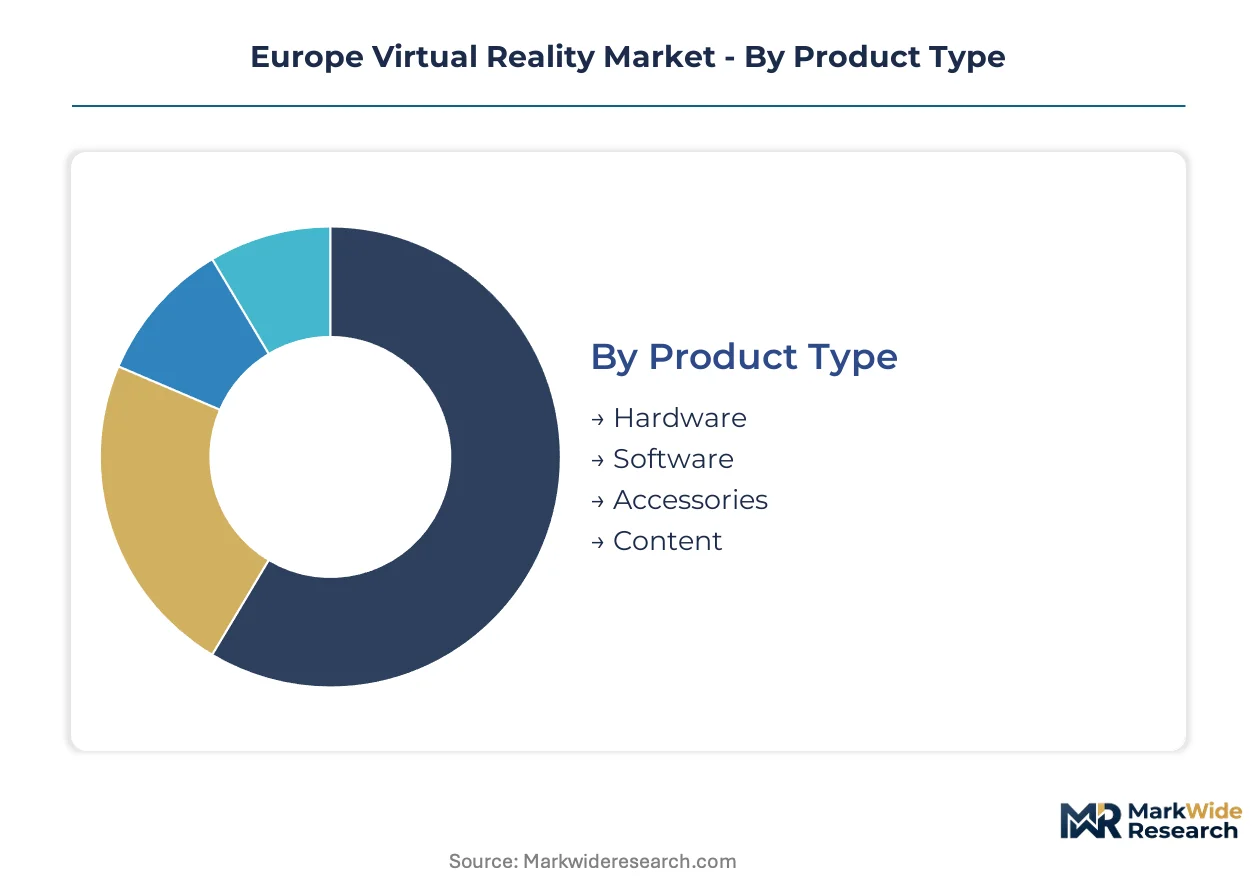
VR market segmentation in Europe reflects divergent procurement logics across consumer entertainment and regulated enterprise environments. Hardware specifications, clinical certification requirements, and integration complexity create distinct purchasing criteria that reshape vendor positioning across national markets.
Product Type:
The use-case spectrum spans immersive training simulations requiring medical-grade precision through consumer entertainment platforms prioritizing cost accessibility.
- Hardware:Head-mounted displays with pancake lens assemblies and local dimming arrays dominate German automotive design studio procurement for 4-8 hour simulation sessions. CE marking under the MDR and EU AI Act biometric data compliance are compressing development timelines for healthcare-focused headset manufacturers.
- Software:Enterprise licensing platforms for surgical training and industrial simulation command premium pricing through recurring subscription models. French teaching hospitals and Netherlands academic medical centers are unbundling software procurement from hardware acquisition, fragmenting vendor relationships.
- Accessories:Haptic controllers, base stations, and prescription lens inserts extend headset functionality for specialized professional deployments.
- Content:Therapeutic VR applications for pain management and cognitive rehabilitation face tightened EMA clinical evidence requirements.
Established volume favors Hardware; emerging adoption favors Software.
Application:
Cost tier stratification separates mass-market entertainment from capital-intensive regulated deployments requiring extensive clinical validation.
- Gaming:Consumer entertainment retains the largest installed base among individual end users across Western Europe. Meta Platforms leverages its social ecosystem to sustain headset penetration despite compressed margin pools shifting toward enterprise software licensing.
- Healthcare:Surgical training programs in French teaching hospitals and VR distraction therapy pilots in Netherlands academic medical centers are establishing reimbursement precedents for digital therapeutics. EMA guidelines and MDR CE marking requirements are extending product launch schedules.
- Education:Immersive learning modules for vocational training and university curricula face procurement budget constraints in Southern European markets.
- Military:Simulation systems for tactical training and equipment maintenance operate through classified procurement channels with extended replacement cycles.
Margin concentration sits with Healthcare; volume scale remains with Gaming.
End User:
Customer type determines integration complexity, with industrial deployments demanding scarce systems engineering expertise concentrated in German consultancies.
- Individuals:Consumer purchasers prioritize wireless all-in-one architectures and social platform integration over specification depth.
- Enterprises:German automotive and industrial engineering sectors are compressing replacement cycles for first-generation tethered systems. Custom API middleware requirements for PLM and MES integration demand specialized implementation support.
- Institutions:French university hospital systems and Netherlands regional health authorities are aggregating purchasing across multiple institutions through fragmented RFP structures.
- Developers:Content creation tool licensing and SDK access support ecosystem expansion for therapeutic and simulation applications.
Procurement scale favors Enterprises; ecosystem expansion depends on Developers.
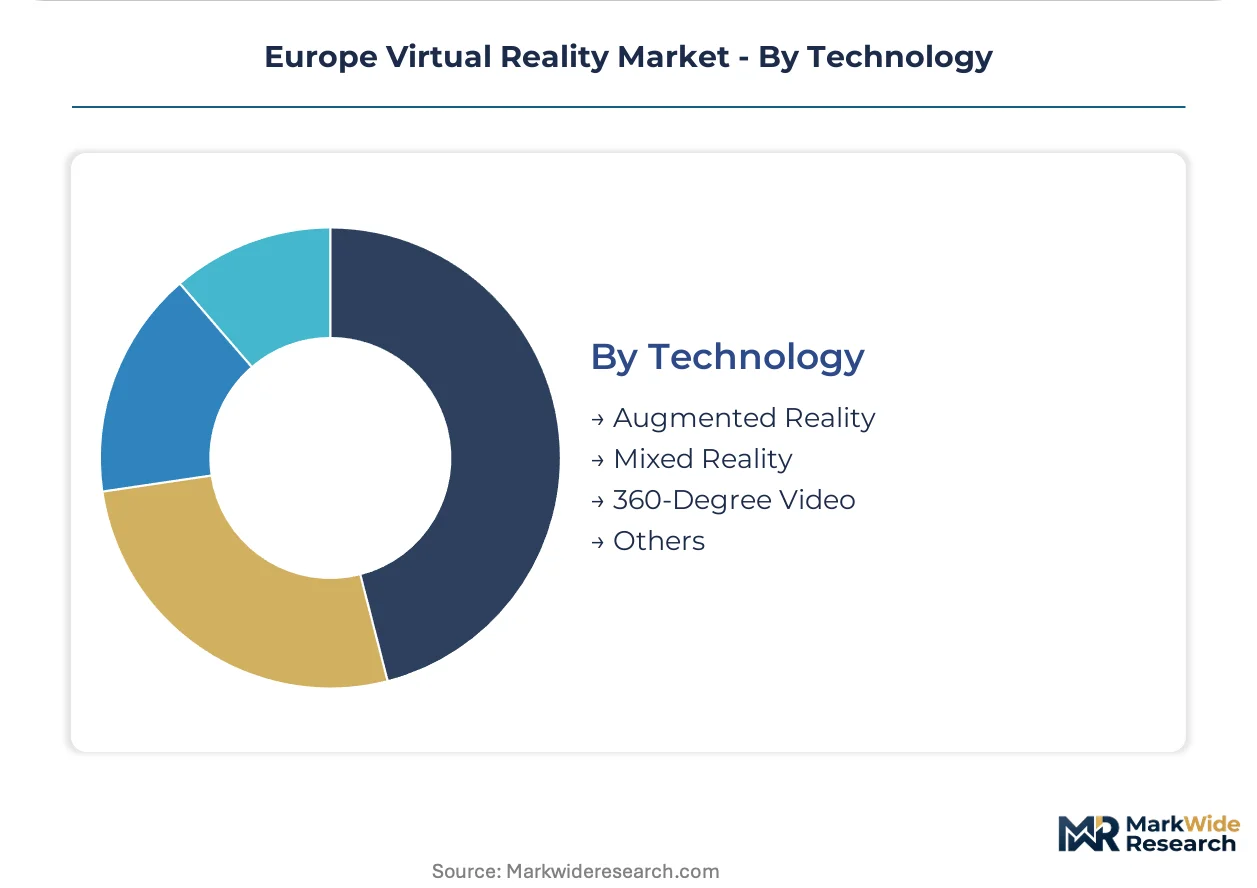
Technology:
Maturity gradients separate established display architectures from emerging spatial computing convergence requiring specialized optical engineering talent.
- Augmented Reality:Passthrough mixed reality integration is opening architectural visualization and factory planning applications previously served by dedicated CAD immersion suites.
- Mixed Reality:Hand tracking, eye tracking, and spatial audio rendering combine for real-time interaction in enclosed digital spaces with sub-20ms motion-to-photon latency requirements.
- 360-Degree Video:Cinematic and live-event capture platforms serve tourism and real estate marketing applications with lower technical barriers to entry.
- Others:Experimental holographic and light-field display technologies remain pre-commercial for volume deployment.
Deployment readiness favors Mixed Reality; steepest expansion trajectory sits with Augmented Reality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian fabrication capacity for micro-OLED and pancake lens modules concentrates supply-side leverage over European headset assemblers. German automotive engineering labs and French teaching hospitals anchor demand-side procurement clusters. GDPR and EU AI Act compliance requirements reshape vendor go-to-market strategies across national markets.
Germany
Automotive design studios in Munich and Stuttgart specify pancake lens assemblies for 4-8 hour simulation sessions. The KBA coordinates with EU AI Act implementation for biometric data governance in industrial VR deployments. Bavarian precision manufacturing partnerships compress replacement cycles for first-generation tethered systems.
France
Teaching hospitals in Paris and Lyon integrate immersive headsets into surgical residency programs. ANSM enforces EMA guidelines on digital therapeutics for VR-based pain management certification. Île-de-France aerospace engineering centers specify ultra-high-resolution displays for design review applications.
Netherlands
Academic medical centers in Amsterdam and Rotterdam pilot VR distraction therapy for chronic pain and pediatric procedures. The Dutch Data Protection Authority applies GDPR biometric data retention limits to consumer gaze-tracking platforms. Eindhoven-region health authorities aggregate purchasing across multiple institutions through fragmented RFP structures.
United Kingdom
London-based financial services firms deploy VR for virtual trading floor simulations and client immersive presentations. The Information Commissioner's Office enforces GDPR restrictions on facial mapping data storage windows. Cambridge and Oxford research clusters advance waveguide display engineering for next-generation headsets.
Sweden
Industrial engineering consultancies in Stockholm specialize in PLM and MES integration middleware for enterprise VR deployments. The Swedish Medical Products Agency aligns with MDR CE marking timelines for medical-grade headset certification. Gothenburg automotive suppliers specify wireless all-in-one architectures for factory planning applications.
Europe Virtual Reality Market Competitive Landscape
Social ecosystem platforms and industrial-grade specialists split the market across consumer entertainment and regulated enterprise environments. The vendor base organizes around three strategic archetypes: ecosystem-integrated consumer platforms, premium professional simulation providers, and component-level semiconductor suppliers. Competitive positioning depends on wireless architecture roadmaps and medical-grade certification pipelines. M&A activity concentrates on optical engineering talent acquisition and therapeutic content platform consolidation.
Within the ecosystem-integrated tier, Meta Platforms, Inc. exemplifies consumer-scale penetration through social platform leverage. Sony Corporation anchors premium entertainment positioning through its PlayStation VR platform heritage. Varjo Technologies Oy occupies the ultra-high-resolution professional simulation niche for automotive and aerospace design review. These three archetypes represent the dominant competitive vectors shaping procurement committee evaluations across German industrial labs and French hospital systems.
| Leading Market Players |
|---|
| Meta Platforms, Inc. |
| Sony Corporation |
| Microsoft Corporation |
| HTC Corporation |
| Apple Inc. |
| Qualcomm Incorporated |
| Valve Corporation |
| Varjo Technologies Oy |
| Pico Interactive |
| Others |
Supply & Pricing Matrix
Single-source dependency on East Asian micro-OLED fabrication determines both pricing tier spreads and supply chain shape, compressing margin buffers for European headset assemblers while forcing premium-tier vendors toward captive supply arrangements.
Pricing Analysis
EU AI Act compliance dictates the pricing tier structure across the European VR market. Pricing stratifies across premium, standard, and economy tiers based on certification grade and biometric data governance architecture. Cost compression in the standard tier is intensifying because MDR CE marking requirements extend development timelines and freeze capital. Enterprise healthcare buyers exhibit the least price sensitivity due to reimbursement pathways for digital therapeutics, while individual consumers remain highly price-sensitive and delay purchases amid wireless architecture transitions.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwanese and South Korean EMS providers specializing in optical module assembly and headset final integration. Micro-OLED display panels, pancake lens assemblies, and haptic controller subassemblies draw from concentrated East Asian fabrication capacity. Single-source vulnerability in waveguide optics exposes European vendors to logistics bottlenecks and currency volatility. Distribution runs through German industrial engineering consultancies and French hospital procurement consortiums for enterprise tiers, with consumer channels anchored in electronics retail partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European VR market constitutes a high-growth disruption driven by wireless all-in-one architecture maturation and EU AI Act regulatory inflection compressing compliance timelines for biometric data processing.
For Market Incumbents: Pre-empt margin erosion in the standard headset tier by accelerating backward integration into optical module supply and securing MDR certification pipelines before CE marking timelines extend. Defend against emerging Chinese OEM entrants by locking German automotive design studios into multi-year simulation platform contracts with embedded software licensing. For New Entrants and Emerging Players: Pursue white-space opportunities in Netherlands pain management protocols and Swedish industrial PLM integration middleware where incumbent presence remains thin. Target academic medical centers with unbundled therapeutic content platforms rather than competing on hardware specifications. Establish go-to-market partnerships with German engineering consultancies possessing scarce MES integration expertise. For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward medical-grade certification assets and optical engineering talent pools. Long-term viability across the analysis window favors vendors with regulatory moats in healthcare VR and modular headset designs aligned with EU Green Deal recycling obligations. Target acquisition archetypes include waveguide display specialists and therapeutic content platforms with randomized controlled trial data. Monitor EMA reimbursement decisions for VR-based digital therapeutics as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| MDR CE Marking Pathway | Medical-grade headset certification creates regulatory moats against consumer-grade entrants in French hospital systems. |
| Backward Integration into Optical Modules | Captive supply of pancake lens assemblies reduces exposure to East Asian fabrication bottlenecks and currency volatility. |
| Wireless Architecture Platform Integration | Wi-Fi 6E and edge computing convergence eliminates cable constraints for German automotive simulation labs. |
| Hospital System Partnership | Direct procurement relationships with Netherlands academic medical centers establish reimbursement precedents for digital therapeutics. |
| Sustainability Repositioning | Modular headset designs and circular material flows align with EU Green Deal embodied carbon disclosure requirements. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with VR hardware engineering directors, hospital procurement committee chairs, biomedical engineers, and German automotive simulation lab managers; and secondary validation against EMA digital therapeutics guidelines, MDR CE marking databases, EU AI Act implementation documents, and hyperscaler headset shipment disclosures. Bottom-up and top-down triangulation cross-validated segment-level assumptions against aggregate market trajectories.
Forecast inputs span hardware replacement cycles, software licensing attach rates, and healthcare reimbursement pathway progression across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and technology maturity tier. CAGRs were derived from logistic diffusion curves fitted to enterprise adoption patterns and consumer upgrade velocity. Industry-specific inputs incorporate EU AI Act compliance cost burdens and optical engineering talent pipeline constraints.
Sensitivities concentrate around East Asian supply disruptions, MDR certification timeline extensions, and EMA reimbursement decisions for VR-based pain management. Forecasts reflect documented assumptions regarding wireless architecture adoption curves and hospital procurement unbundling trends. Quarterly review of CE marking approval queues and micro-OLED panel pricing indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
India Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
AR/VR Chip Market
Virtual Reality (VR) and Augmented Reality (AR)
Wireless AR Glass Market
Virtual Reality (VR) and Augmented Reality (AR)
Japan Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Tourists Virtual Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality for Consumer Market
Virtual Reality (VR) and Augmented Reality (AR)
Social VR Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Telepresence Market
Virtual Reality (VR) and Augmented Reality (AR)
VR All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Holographic AR Display Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market