
 Global Virtual Mobile Infrastructure Market | 2026-2036
Global Virtual Mobile Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virtual Mobile Infrastructure Market Foresight
Enterprise cybersecurity talent scarcity is collapsing implementation timelines for virtual mobile infrastructure across Fortune 500 IT departments. Cisco Systems leverages its networking hardware installed base to bundle VMI solutions through existing channel relationships. VMware anchors enterprise virtualization mindshare by extending hypervisor expertise into mobile workload isolation. Trend Micro differentiates through integrated threat intelligence feeds that correlate mobile container anomalies with endpoint detection systems.
Virtual mobile infrastructure delivers containerized operating system environments that stream encrypted application layers to endpoint devices without local data persistence, typically operating through 128-bit or higher AES-encrypted tunnels. The architecture isolates corporate applications from personal device storage, eliminating malware lateral movement paths while preserving native user experience. Cloud deployment configurations now lead solution uptake as enterprises abandon capital-intensive on-premises mobile device management stacks. Secure access and data isolation modules command premium positioning within solution offerings due to their direct mapping to GDPR and sector-specific data residency mandates. Remote workforce enablement and secure BYOD use cases are expanding fastest as hybrid work policies institutionalize across BFSI and government agencies.
FDA 21 CFR Part 11 compliance requirements in pharmaceutical field operations, EU GDPR Article 32 security processing obligations, and India's CERT-In mobile security directives collectively shape product certification roadmaps and procurement eligibility. ISO 27001 and SOC 2 Type II attestations function as baseline table stakes for vendor shortlisting in regulated verticals. Stakeholders must monitor evolving zero-trust maturity frameworks from NIST and ENISA to anticipate which authentication and continuous verification capabilities will become mandatory in enterprise RFP criteria.
Market Dynamics
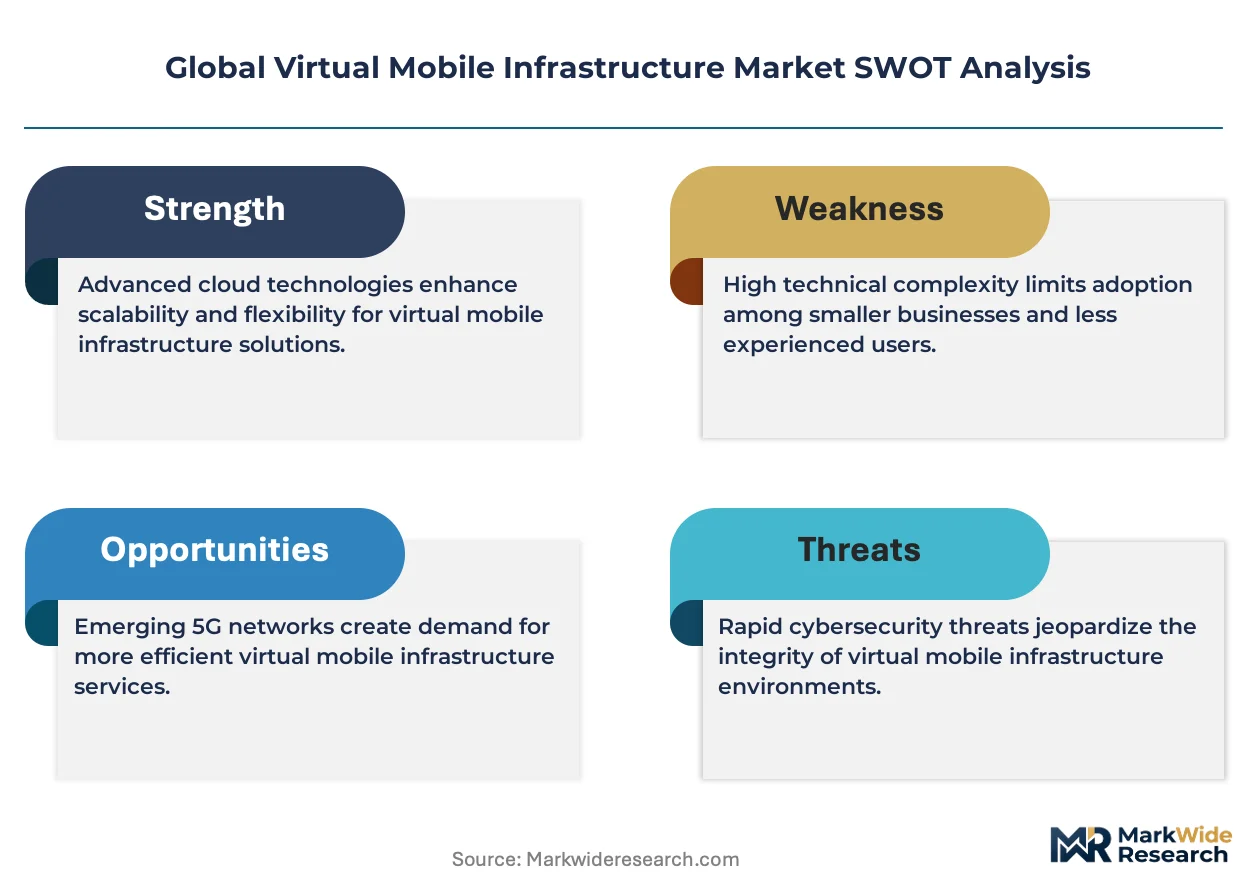
Zero-trust security mandates from NIST and ENISA are compressing enterprise procurement cycles for containerized mobile infrastructure, forcing vendors to pre-certify solutions against continuous verification frameworks before RFP submission.
Growth Catalysts
- GDPR Article 32 Security Processing:EU data residency obligations are accelerating cloud-based VMI deployments as enterprises seek encrypted application streaming to avoid local data persistence risks.
- Hybrid Workforce Institutionalization:BFSI and government agencies in the United States, Germany, and India are mandating secure BYOD frameworks for contractor and field-based access.
- 128-bit AES Tunneling:Hardware-accelerated encryption standards are reducing latency penalties that previously constrained virtualized mobile workload adoption.
Market Restraints
- Enterprise Cybersecurity Talent Scarcity:Fortune 500 IT departments lack sufficient zero-trust architecture expertise to execute VMI implementations within compressed timelines.
- Capital-Intensive On-Premises Legacy Stacks:Sunk costs in existing mobile device management infrastructure create switching friction for cloud migration.
- FDA 21 CFR Part 11 Compliance Complexity:Pharmaceutical field operations face extended validation timelines for electronic records in virtualized environments.
Strategic Opportunities
- India CERT-In Mobile Security Directives:India's regulatory push for sovereign data control creates first-mover advantage for vendors with local cloud infrastructure partnerships.
- Convergence of VMI and Endpoint Detection Systems:Integrated threat intelligence feeds correlating mobile container anomalies with enterprise security operations centers represent unclaimed white space.
- Outcome-Based Licensing Models:Per-user-per-month pricing for secure access modules is displacing perpetual licenses in mid-market procurement.
Industry Challenges
- ISO 27001 and SOC 2 Type II Certification Timelines:Vendor attestation requirements in regulated verticals extend sales cycles by six to twelve months.
- Hypervisor-to-Mobile Workload Integration Complexity:Enterprise virtualization expertise does not translate directly to mobile container orchestration without specialized retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virtual Mobile Infrastructure Market |
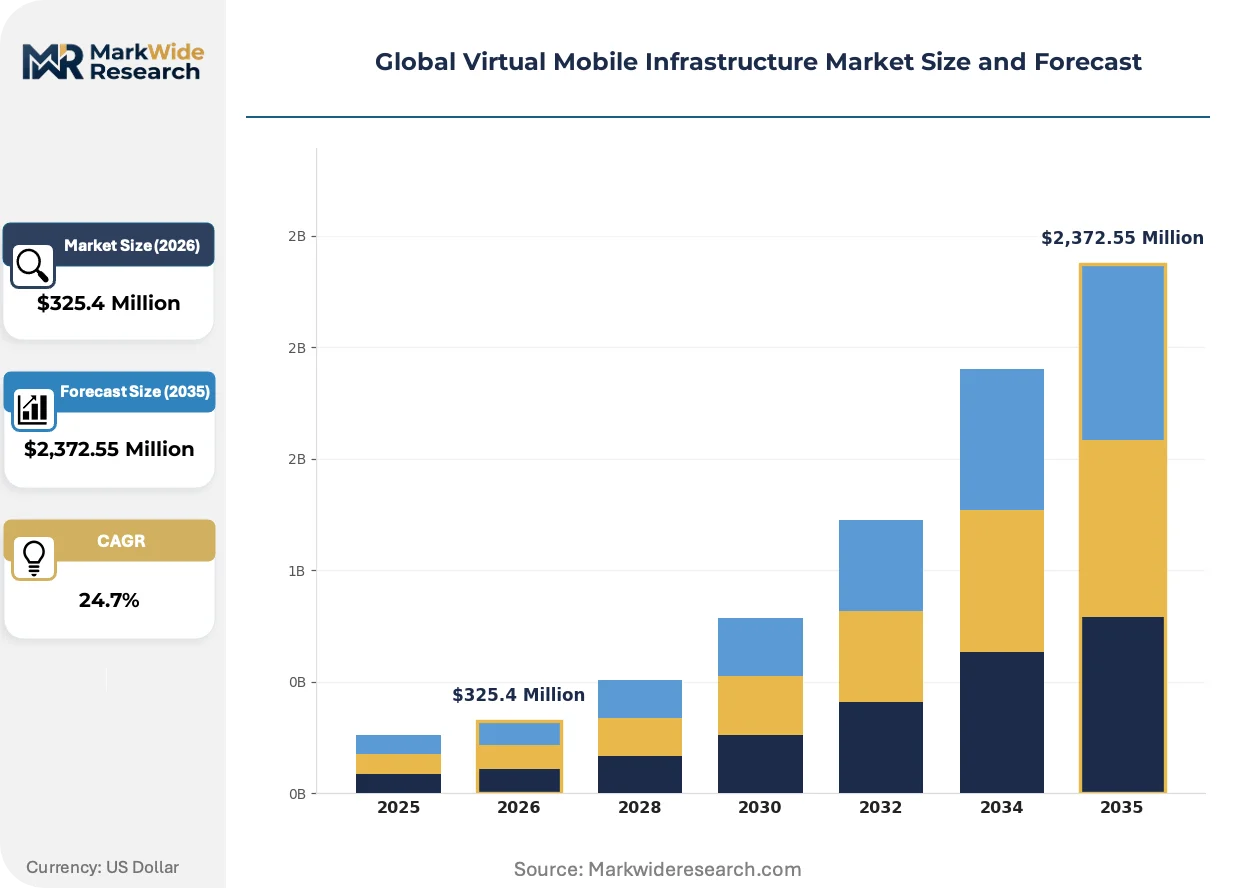
| Market Size in 2026 | $325.4 Million |
| Market Size in 2035 | $2,372.55 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud, On-Premises, Hybrid, Hosted Solution Offering: Secure Access, Mobile Application Virtualization, Data Isolation, Remote Browsing, File Sharing Use Case: Enterprise Mobility, Secure BYOD, Remote Workforce Enablement, Field Operations, Contract Workforce End User Industry: BFSI, Government Agencies, IT & Telecom, Education, Manufacturing |
| Companies Covered | Cisco Systems, VMware, Microsoft, Oracle, Citrix Systems, IBM, Trend Micro, Avast Software, Sierraware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virtual Mobile Infrastructure Market Shifts & Advancements
Containerized operating system environments are displacing traditional mobile device management architectures as enterprises prioritize data isolation over device control. This shift is compressing vendor roadmaps toward cloud-native delivery models.
Edge-optimized VMI streaming protocols are fragmenting the competitive landscape between low-latency regional cloud deployments and centralized hyperscaler architectures. Financial services institutions in Singapore and Switzerland are piloting sub-50-millisecond application response thresholds for trading floor mobility. This performance tiering is enabling premium pricing for secure access modules that guarantee GDPR-aligned data residency.
NIST zero-trust maturity frameworks are mandating continuous verification capabilities that exceed static certificate-based authentication. Federal contractors in the United States must now demonstrate step-up authentication for privileged mobile access to controlled unclassified information. Defense industrial base suppliers are reengineering procurement specifications to disqualify solutions lacking real-time behavioral analytics.
Enterprise buying committees are consolidating vendor relationships around integrated platform plays rather than point solutions for mobile security. CIOs in German automotive and pharmaceutical clusters are requiring VMI vendors to bundle identity management and endpoint detection within single contracts. This bundling preference is squeezing standalone container specialists without adjacent cybersecurity portfolios.
Global Virtual Mobile Infrastructure Market Segmentation
VMI procurement patterns diverge sharply across deployment models and use cases, with regulated industries prioritizing data residency controls while mid-market buyers chase operational flexibility. Understanding these segment boundaries clarifies where vendors must certify against compliance frameworks versus compete on price-to-performance ratios.
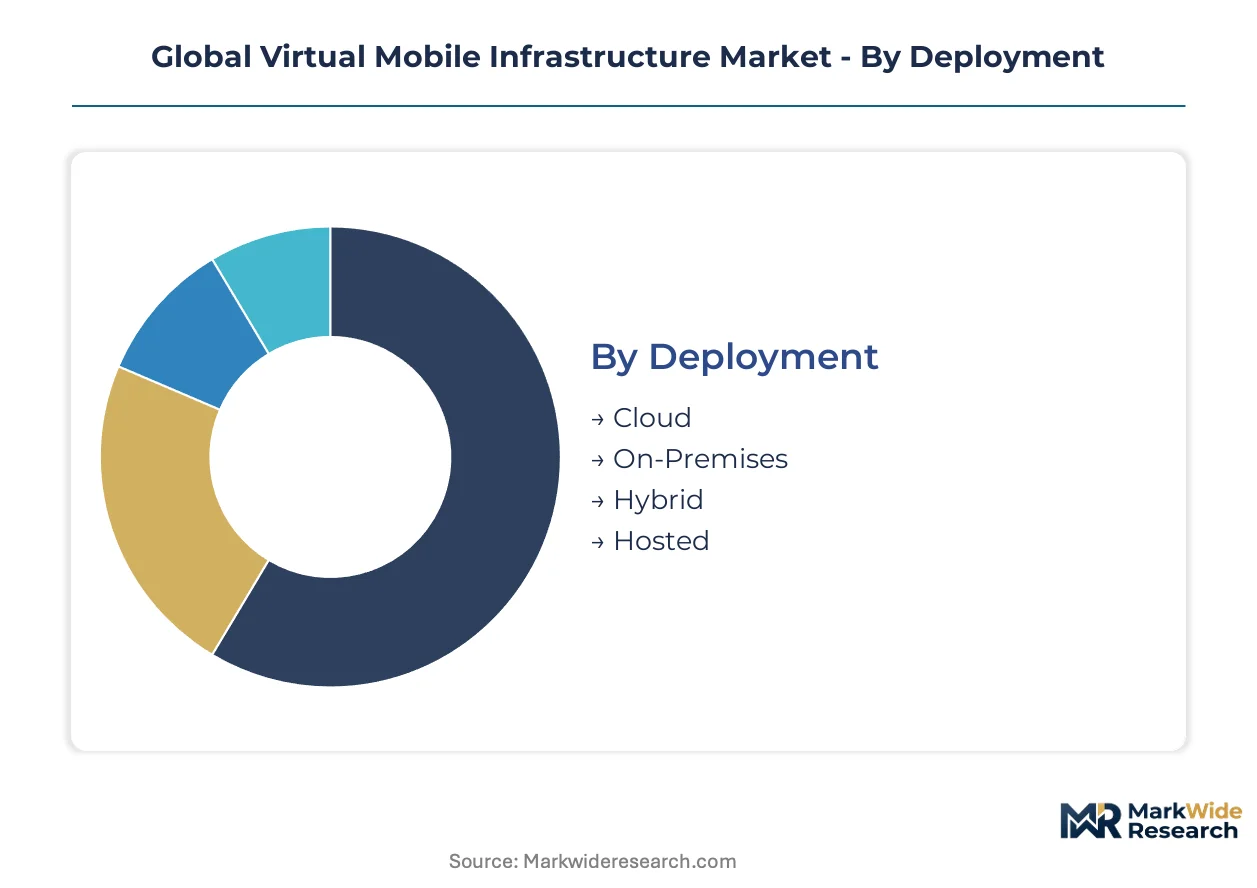
Deployment:
Cloud configurations dominate cross-border enterprise rollouts, while on-premises and hybrid architectures concentrate in jurisdictions with strict data sovereignty requirements.
- Cloud:Multi-tenant architectures with regional edge nodes stream encrypted application layers without local data persistence. Demand concentrates in Germany and Singapore where GDPR-aligned data residency pairs with sub-50-millisecond latency thresholds for trading floor mobility.
- On-Premises:Dedicated infrastructure within enterprise data centers maintains full control over encryption key management and audit logging. Indian pharmaceutical manufacturers and US defense contractors favor this model to satisfy CERT-In directives and NIST zero-trust mandates for controlled unclassified information.
- Hybrid:Split workloads between private infrastructure and public cloud burst capacity accommodate seasonal contractor access spikes.
- Hosted:Single-tenant managed services in third-party facilities reduce capital expenditure for mid-market BFSI institutions in Switzerland and the UAE.
Cloud holds the largest share; momentum sits with hybrid configurations bridging compliance and scalability.
Solution Offering:
Security modules command pricing premiums when mapped to specific regulatory obligations, while productivity tools compete on user experience metrics.
- Secure Access:Continuous verification frameworks with step-up authentication for privileged sessions. US federal contractors require real-time behavioral analytics to access controlled unclassified information, disqualifying static certificate-based alternatives from procurement shortlists.
- Data Isolation:Containerized operating environments that eliminate malware lateral movement paths by separating corporate applications from personal device storage. EU pharmaceutical field operations deploy these modules to satisfy GDPR Article 32 security processing obligations without local data persistence risks.
- Mobile Application Virtualization:Streamed app layers preserving native user experience across device types.
- Remote Browsing:Isolated web sessions preventing endpoint exposure to malicious content.
- File Sharing:Encrypted document synchronization with granular access controls for contractor collaboration.
Secure Access generates the highest average contract values; Data Isolation is climbing fastest on regulatory tailwinds.
Use Case:
Enterprise mobility and secure BYOD deployments scale through channel partnerships, while field operations and contract workforce solutions require vertical-specific customization.
- Secure BYOD:Frameworks enabling personal device access to corporate resources without MDM agent installation. German automotive clusters mandate these solutions for supplier network access, bundling identity management and endpoint detection within single procurement contracts.
- Field Operations:Offline-capable containers with periodic synchronization for pharmaceutical representatives and utility inspectors. FDA 21 CFR Part 11 compliance complexity extends validation timelines, favoring vendors with pre-certified electronic records modules.
- Enterprise Mobility:Broad workforce enablement across corporate-issued and personal device fleets.
- Remote Workforce Enablement:Scalable access for distributed employees without VPN dependency.
- Contract Workforce:Time-bound provisioning with automatic deprovisioning upon project completion.
Enterprise Mobility maintains installed base dominance; Secure BYOD is expanding most quickly as hybrid work policies institutionalize.
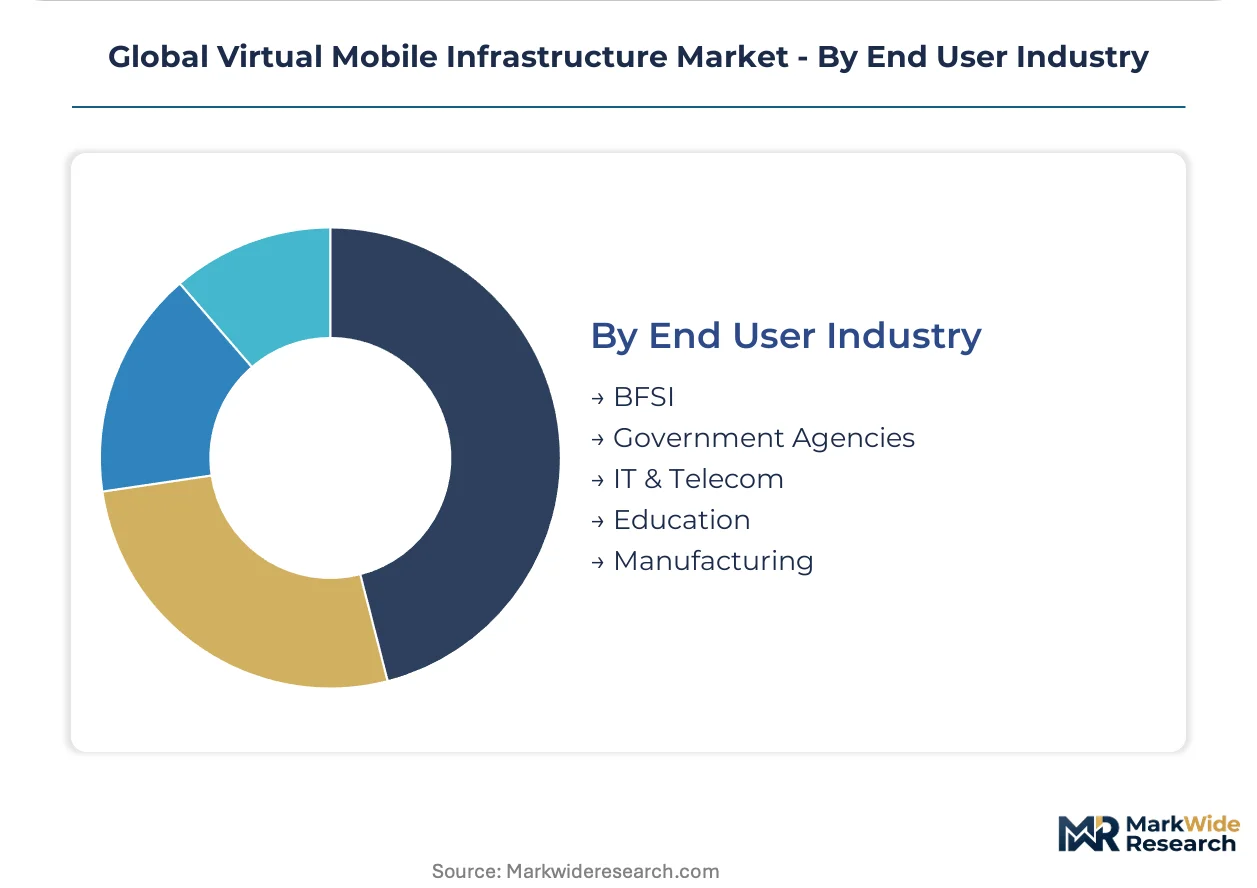
End User Industry:
BFSI and government agencies drive certification requirements that cascade into adjacent sectors, while manufacturing and education prioritize cost efficiency over compliance depth.
- BFSI:Trading floor mobility with guaranteed latency thresholds and transaction audit trails. Swiss and Singaporean financial institutions pilot sub-50-millisecond response tiers, enabling premium pricing for secure access modules with guaranteed performance.
- Government Agencies:NIST zero-trust maturity frameworks mandate continuous verification exceeding static authentication. US federal procurement specifications now disqualify solutions lacking real-time behavioral analytics for privileged mobile access.
- IT & Telecom:Internal workforce enablement and client-facing managed security services.
- Education:Student and faculty BYOD with limited compliance overhead.
- Manufacturing:Shop floor mobility with tolerance for higher latency in non-critical applications.
BFSI contributes the highest revenue per seat; Government Agencies show the steepest expansion trajectory on zero-trust mandate deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NIST zero-trust mandates from the United States anchor procurement velocity, while GDPR Article 32 obligations in Germany and CERT-In directives in India reshape deployment architectures across three continents.
United States
Federal contractors demand continuous verification frameworks for controlled unclassified information access. NIST zero-trust maturity requirements now disqualify static certificate-based authentication from defense procurement shortlists. The Washington-Baltimore corridor concentrates vendor certification activity as systems integrators race to meet federal RFP deadlines.
Germany
Automotive clusters mandate secure BYOD frameworks for supplier network access without MDM agent installation. GDPR Article 32 security processing obligations accelerate cloud-based deployments with encrypted application streaming. Stuttgart and Munich host the densest concentration of pharmaceutical field operations deploying pre-certified electronic records modules.
India
Pharmaceutical manufacturers favor on-premises infrastructure to satisfy CERT-In mobile security directives for sovereign data control. Hybrid workforce policies across IT services firms drive mid-market procurement of per-user-per-month licensing models. Bengaluru and Hyderabad emerge as pilot sites for local cloud infrastructure partnerships.
Singapore
Financial institutions pilot sub-50-millisecond application response thresholds for trading floor mobility. Hardware-accelerated encryption standards reduce latency penalties that previously constrained virtualized mobile workload adoption. The city-state's regulatory sandbox enables premium pricing for secure access modules with guaranteed performance tiers.
Switzerland
Private banking and wealth management sectors require GDPR-aligned data residency with transaction audit trails. Hosted single-tenant managed services reduce capital expenditure for mid-market BFSI institutions. Zurich and Geneva concentrate demand for secure access modules bundling identity management and endpoint detection.
Global Virtual Mobile Infrastructure Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with networking hardware vendors and enterprise virtualization platforms commanding procurement mindshare through existing channel relationships. The structure rewards bundled platform plays over point solutions, as CIOs consolidate vendor relationships around integrated cybersecurity portfolios. Two archetypes dominate: infrastructure incumbents extending installed base advantages, and security specialists differentiating through threat intelligence integration. Competitive moves concentrate on pre-certification against zero-trust frameworks and geographic partnerships for local cloud infrastructure.
Within the infrastructure incumbent tier, Cisco Systems and VMware exemplify platform consolidation strategies, with the former leveraging networking hardware relationships and the latter extending hypervisor expertise into mobile workload isolation. Trend Micro occupies a position among security-centric specialists, differentiating through integrated threat intelligence feeds that correlate mobile container anomalies with enterprise security operations centers.
| Leading Market Players |
|---|
| Cisco Systems |
| VMware |
| Microsoft |
| Oracle |
| Citrix Systems |
| IBM |
| Trend Micro |
| Avast Software |
| Sierraware |
| Others |
Supply & Pricing Matrix
Hyperscale cloud capacity utilization in the United States and Germany creates steep unit economics advantages that compress price floors for mid-market VMI providers while elevating margin capture for vendors with dedicated sovereign infrastructure partnerships in India and Singapore. This scale asymmetry concentrates procurement power among enterprise buyers with multi-thousand seat contracts, forcing smaller vendors toward niche certification premiums or exit.
Pricing Analysis
Geographic price spreads between North American enterprise deployments and Indian mid-market rollouts exceed three-to-one for equivalent secure access modules, reflecting differential compliance overhead and local cloud infrastructure maturity. The dominant pricing structure runs on per-user-per-month SaaS tiers with volume breakpoints at 500, 5,000, and 50,000 seats. Price differentiation hinges on ISO 27001 certification tier and guaranteed latency thresholds below 50 milliseconds. Pricing pressure stems from outcome-based licensing models displacing perpetual licenses in mid-market procurement. Government agencies and BFSI institutions show least price sensitivity due to zero-trust mandate deadlines, while education and manufacturing verticals drive hardest bargain.
Supply Chain Analysis
Inventory lead times for hardware-accelerated encryption modules stretch six to fourteen weeks, constraining rapid scaling for vendors dependent on specialized semiconductor components. Supply concentrates in Taiwan, South Korea, and the United States for trusted platform modules and hardware security elements. Raw material dependencies include advanced lithography silicon, cryptographic co-processors, and specialized memory substrates. Single-source vulnerability runs through TSMC's advanced node production for security-hardened chipsets. Distribution runs through systems integrators and managed security service providers rather than direct vendor-to-enterprise channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as zero-trust mandate deadlines fragment procurement criteria across federal, financial services, and pharmaceutical verticals, creating specialist niches that resist platform consolidation.
For Market Incumbents: Compound installed base advantages by embedding VMI modules within existing networking and virtualization contracts before standalone container specialists achieve certification velocity. Defensive priorities center on pre-certification against NIST zero-trust maturity frameworks and ENISA continuous verification protocols. Channel control through systems integrator exclusivity agreements represents the critical lever against emerging cloud-native entrants. For New Entrants and Emerging Players: Differentiate on sovereign cloud infrastructure partnerships in India and Singapore where local data residency requirements disqualify hyperscaler-dependent incumbents from procurement shortlists. The most penetrable white space sits in mid-market BFSI institutions seeking hosted single-tenant managed services with bundled identity management. Go-to-market angle should emphasize per-user-per-month pricing with automatic compliance attestation against GDPR Article 32 and CERT-In directives. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors security-centric specialists with integrated threat intelligence feeds over infrastructure incumbents facing hypervisor-to-mobile workload integration complexity. Long-term viability over the next decade hinges on convergence with endpoint detection systems and security operations center orchestration. Acquisition target archetype: vendors with pre-certified electronic records modules for pharmaceutical field operations. Signal to watch: defense industrial base procurement specifications mandating real-time behavioral analytics as table stakes.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certification Against Zero-Trust Frameworks | NIST and ENISA compliance accelerates federal and European procurement eligibility before RFP issuance. |
| Sovereign Cloud Infrastructure Partnership | Local data center alliances in India satisfy CERT-In directives and create switching costs against hyperscaler entrants. |
| Integrated Threat Intelligence Development | Correlation of mobile container anomalies with enterprise SOCs captures unclaimed premium pricing in security modules. |
| Outcome-Based Licensing Transition | Per-user-per-month models displace perpetual licenses and expand addressable market into mid-market BFSI procurement. |
| Edge-Optimized Streaming Protocol Investment | Sub-50-millisecond latency guarantees unlock premium tiers for Singapore and Swiss trading floor mobility deployments. |
Research Methodology
A spread of perspectives from chief information security officers, federal procurement officers, pharmaceutical IT directors, and managed security service providers converged on the working assumptions shaping demand trajectories and vendor selection criteria. Primary fieldwork combined structured interviews with secondary validation through SEC filings, hyperscaler capex disclosures, and federal procurement databases. Bottom-up deployment modeling triangulated against top-down market sizing from regulatory mandate timelines and workforce policy shifts.
Segmentation dimensions modeled span deployment architecture, solution offering module, enterprise size tier, and end-user industry vertical across the projection horizon. CAGRs were derived from regression analysis against historical enterprise mobility adoption curves and regulatory compliance deadline clustering. Industry-specific forecast inputs include NIST zero-trust implementation timelines and GDPR enforcement pattern shifts across European member states.
The analysis sits within stated boundaries; outcomes outside sustained federal funding continuity or abrupt data sovereignty policy reversals would require recalibration. Forecasts reflect assumptions about certification velocity and channel partnership density that could compress or extend vendor consolidation timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Wireless AR Glass Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Ski Machines Market
Virtual Reality (VR) and Augmented Reality (AR)
France Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mixed Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Location-Based VR Entertainment Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market