
 Global Mobile Augmented Reality Market | 2026-2036
Global Mobile Augmented Reality Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Augmented Reality Market Foresight
Market Context
ISO/IEC 27001 certification for data security and privacy management is bifurcating vendor eligibility across enterprise AR deployments. Apple Inc. leverages its vertical integration of custom silicon and spatial computing frameworks to dominate premium mobile AR experiences. Google LLC anchors the broader ecosystem through ARCore distribution across Android's global installed base, while Qualcomm Technologies Inc. competes by supplying specialized XR chipsets that power third-party hardware.
Technical Definition and Structural Segments
Mobile augmented reality overlays computer-generated perceptual information onto real-world environments viewed through smartphone or tablet cameras, relying on simultaneous localization and mapping (SLAM), depth sensing, and real-time rendering pipelines to fuse virtual objects with physical space. Markerless technology leads deployment scale due to reduced friction in consumer activation, while location-based AR sustains the fastest growth trajectory as urban mapping density improves and GPS-denied indoor positioning matures. Gaming applications occupy established revenue pools, yet industrial training segments concentrate margin expansion where safety-critical simulations command premium licensing.
Regulatory Framework
The EU AI Act, GDPR, and FCC equipment authorization standards collectively shape compliance burdens for cross-platform AR services, with biometric data processing triggering enhanced scrutiny in European jurisdictions and radio frequency emissions subject to pre-market testing in the United States. China's NMPA and MIIT impose parallel content moderation and hardware certification requirements that fragment go-to-market pathways. Stakeholders must monitor evolving interoperability mandates between iOS and Android deployment platforms as antitrust pressure intensifies on gatekeeper ecosystems.
Market Dynamics
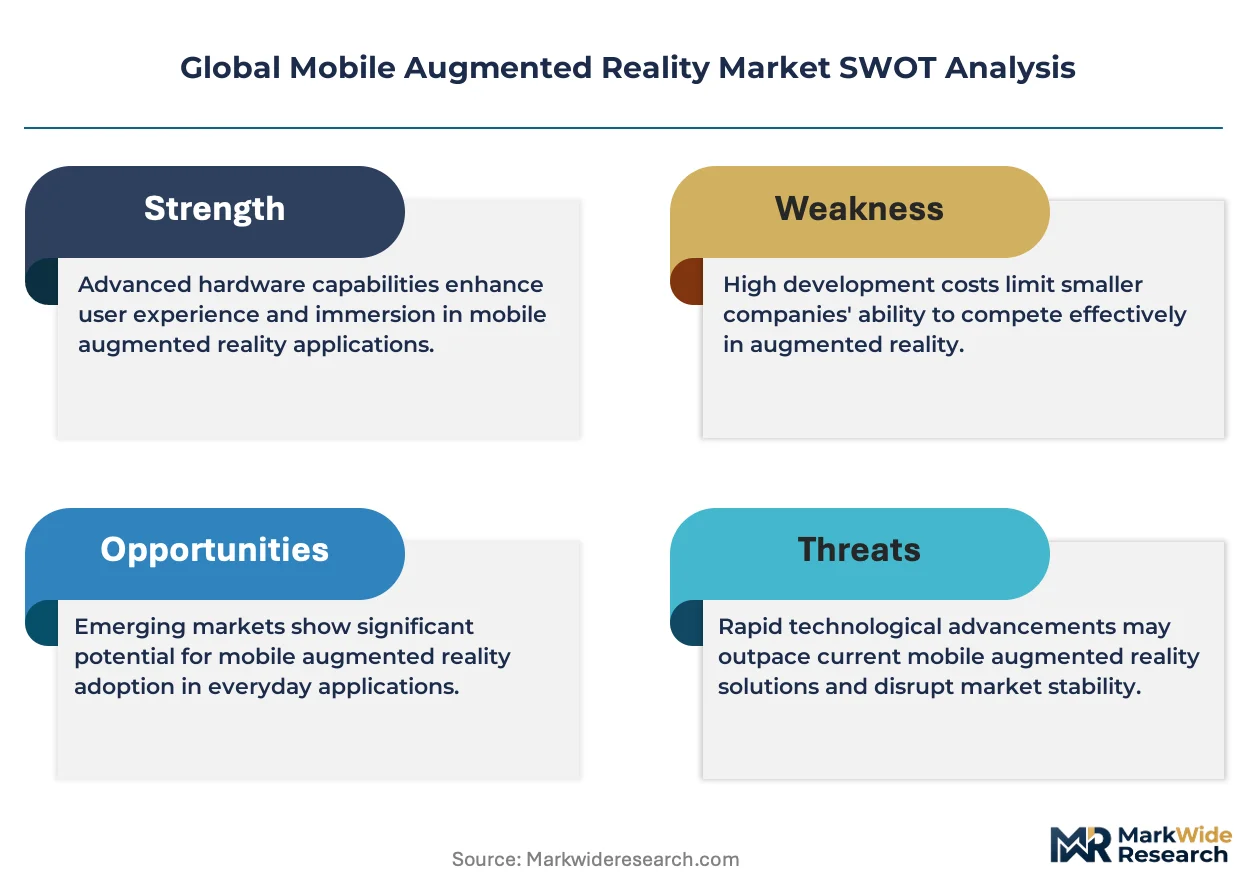
SLAM algorithm standardization and EU AI Act transparency mandates are compressing vendor margins while fragmenting deployment pathways across iOS and Android ecosystems.
Growth Catalysts
- Retail Try-On Adoption:Apparel and cosmetics brands deploy markerless AR to reduce return logistics costs. Consumer activation friction drops below three seconds on flagship smartphones.
- GDPR-Driven Privacy Differentiation:European enterprises prioritize ISO/IEC 27001-certified AR platforms for workforce training. Compliance becomes a procurement gate.
- Industrial Safety Simulation:Oil and gas operators license premium AR training modules for hazardous environment rehearsal. Licensing fees exceed consumer application ARPU by an order of magnitude.
Market Restraints
- Custom Silicon Concentration:Qualcomm and Apple dominate XR-capable SoC supply. Alternative chipset vendors lack the GPU-NPU integration density for real-time occlusion rendering.
- Biometric Data Friction:GDPR Article 9 and China's Personal Information Protection Law impose consent-layer complexity on face-tracking AR applications. Deployment timelines extend by regulatory review cycles.
- Indoor Positioning Cost:GPS-denied SLAM requires lidar or time-of-flight sensor arrays. Hardware bill-of-materials inflation compresses mid-tier device AR attach rates.
Strategic Opportunities
- German Industrial Cluster Penetration:Mittelstand manufacturers underinvest in AR-assisted maintenance. Tool vendors can embed spatial guidance into existing technician workflows.
- 5G-Edge Convergence:Split rendering architectures offload heavy compute to MEC nodes. Latency-sensitive industrial AR applications unlock subscription pricing models.
- India PLI Scheme Tailwind:Smartphone production-linked incentives accelerate local AR-capable device manufacturing. Domestic content moderation requirements favor regional platform development.
Industry Challenges
- Spatial Computing Talent Scarcity:Computer vision engineers with SLAM optimization expertise command compensation premiums. Enterprise AR vendors poach from gaming studios.
- Cross-Platform Certification Burden:FCC equipment authorization and NMPA hardware certification require divergent test protocols. Single-SKU global launches become technically infeasible.
- Legacy System Integration Complexity:Industrial AR overlays must interface with proprietary SCADA and MES architectures. Custom middleware development consumes 40% of deployment budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Augmented Reality Market |
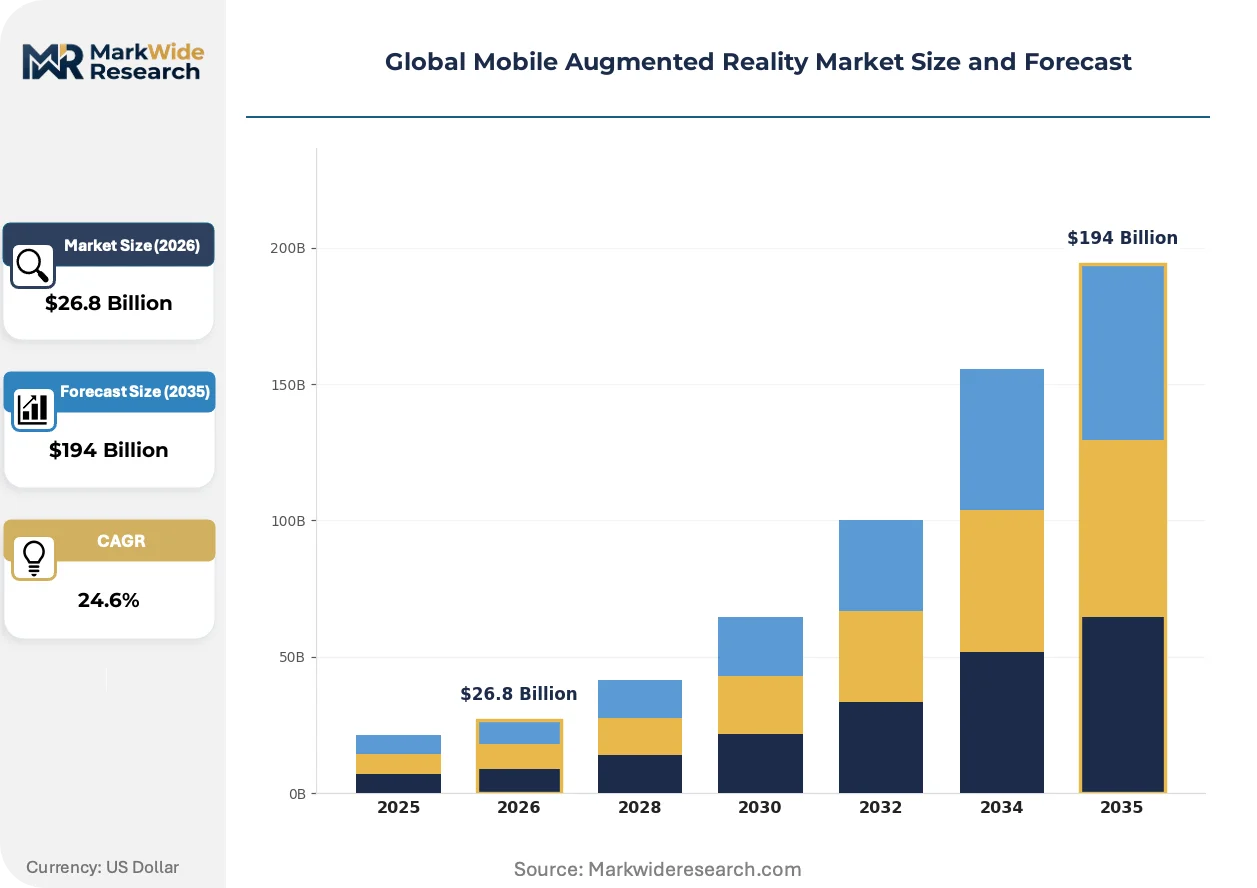
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $194 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Marker-Based, Markerless, Projection-Based, Superimposition-Based, Location-Based Application: Gaming, Retail, Education, Industrial Training, Tourism End User: Entertainment Providers, Educational Institutions, Manufacturing Units, Travel Agencies, Advertising Firms Deployment Platform: iOS, Android, Windows, Web-Based, Wearable Devices |
| Companies Covered | Apple Inc., Google LLC, Microsoft Corporation, Samsung Electronics Co. Ltd., Qualcomm Technologies Inc., Magic Leap Inc., PTC Inc., Snap Inc., Niantic Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Augmented Reality Market Shifts & Advancements
Neural radiance fields and on-device generative models are compressing 3D asset pipelines while elevating real-time rendering fidelity expectations across consumer and enterprise segments.
Neural radiance fields (NeRF) is fragmenting traditional photogrammetry workflows for 3D scene reconstruction. E-commerce catalog managers now generate product models from sparse image sets without structured light scanning. The technology compresses content production timelines from weeks to hours, enabling rapid AR campaign deployment.
The EU AI Act's risk classification framework imposes documentation burdens on biometric inference systems. AR applications employing face analysis for virtual try-on must maintain algorithmic audit trails. German and French regulators are prioritizing enforcement in retail and employment screening contexts, forcing vendors to segregate European data processing infrastructure.
Buyer procurement patterns for enterprise AR are pivoting toward outcome-based service contracts with guaranteed uptime SLAs. Industrial maintenance departments reject perpetual licenses in favor of per-intervention pricing tied to technician performance metrics. This shift is most pronounced in United States manufacturing clusters where CFO scrutiny of training technology ROI has intensified.
Global Mobile Augmented Reality Market Segmentation
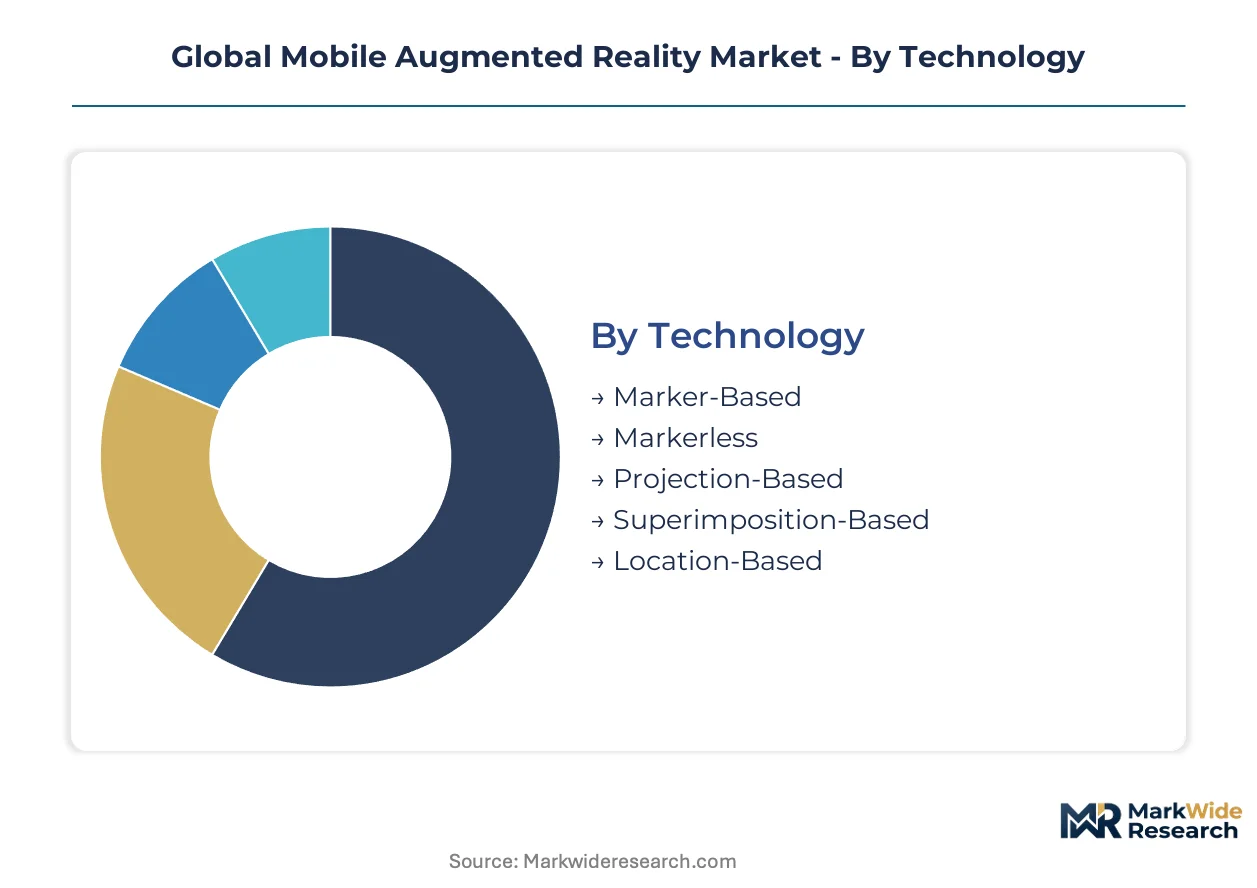
Technology and application splits in mobile AR reveal divergent margin profiles, with industrial training commanding premium licensing while consumer gaming drives volume scale. Deployment platform concentration shapes vendor go-to-market economics and certification burden allocation.
Technology:
Margin pools concentrate in location-based and markerless implementations where sensor fusion complexity creates vendor differentiation.
- Markerless:SLAM-based spatial anchoring eliminates consumer activation friction through environmental feature detection rather than printed targets. Retail cosmetics and apparel brands in the United States and Germany prioritize this modality for try-on applications where sub-three-second launch times reduce abandonment.
- Location-Based:GPS-denied indoor positioning via visual-inertial odometry enables persistent AR experiences tied to physical coordinates. Urban mapping density improvements in Chinese and German city centers sustain the steepest expansion trajectory for tourism and navigation use cases.
- Marker-Based:Image recognition triggers remain cost-effective for educational content where hardware constraints dominate procurement decisions.
- Projection-Based:Spatial light modulation enables shared AR experiences without individual device ownership, finding niche adoption in museum installations.
- Superimposition-Based:Object replacement techniques serve industrial maintenance workflows where CAD overlay accuracy exceeds aesthetic rendering requirements.
The dominant share belongs to markerless technology, while location-based is closing the gap fastest.
Application:
Volume leadership sits with gaming, yet profit pool depth favors industrial training where safety-critical simulation commands subscription pricing.
- Industrial Training:Hazardous environment rehearsal modules for oil and gas operators in the United States carry licensing fees exceeding consumer ARPU by an order of magnitude. ISO/IEC 27001 certification requirements from European procurement departments further segment vendor eligibility.
- Gaming:Established revenue pools from location-based entertainment and mobile titles anchor installed base scale across iOS and Android ecosystems in China and the United States.
- Retail:Return logistics cost reduction drives cosmetics and apparel AR deployment, with GDPR-compliant data processing becoming a procurement gate in Germany and France.
- Education:Marker-based content dominates K-12 budget constraints, though higher education institutions in Germany pilot location-based campus navigation.
- Tourism:Urban heritage visualization depends on municipal mapping partnerships, with deployment concentrated in Chinese cultural sites and European historic districts.
Gaming retains volume leadership, though industrial training is expanding most quickly.
End User:
Procurement sophistication varies sharply, with manufacturing units demanding outcome-based contracts while entertainment providers optimize for activation velocity.
- Manufacturing Units:Mittelstand firms in Germany underinvest in AR-assisted maintenance, creating whitespace for tool vendors embedding spatial guidance into existing technician workflows. Per-intervention pricing models displace perpetual licenses under intensified CFO scrutiny.
- Entertainment Providers:Location-based entertainment venues in the United States and China prioritize throughput optimization and hardware durability in high-traffic deployments.
- Educational Institutions:Budget fragmentation across K-12 and higher education segments favors low-cost marker-based solutions over sensor-intensive alternatives.
- Travel Agencies:Destination preview applications concentrate in premium tour operator segments where customer acquisition costs justify content production investment.
- Advertising Firms:Campaign-duration AR activations prioritize rapid asset pipeline compression through neural radiance field techniques.
Manufacturing units command the deepest commercial engagement, while advertising firms are gaining share fastest.
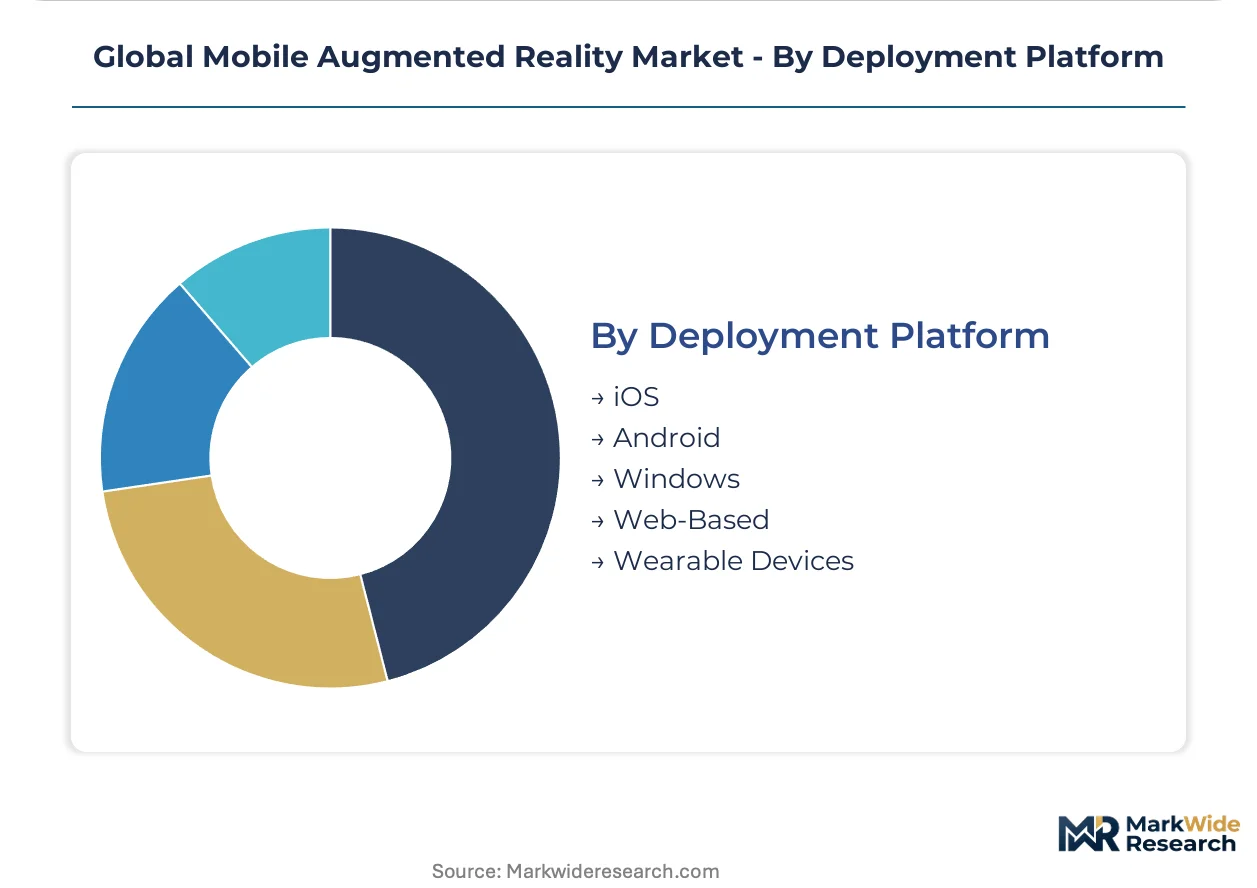
Deployment Platform:
Certification burden fragmentation across FCC, NMPA, and CE marking regimes shapes platform-specific vendor economics.
- iOS:Apple's vertical integration of custom silicon and spatial computing frameworks dominates premium experience segments. ARKit distribution leverages uniform hardware specifications that reduce testing matrix complexity for developers targeting United States and European markets.
- Android:ARCore's global installed base anchors volume scale, though device fragmentation complicates SLAM performance optimization across Qualcomm and alternative chipset configurations.
- Wearable Devices:Specialized XR chipsets from Qualcomm enable hands-free industrial applications where smartphone form factors impose safety constraints.
- Web-Based:Cross-platform delivery avoids app store certification delays, sacrificing rendering fidelity for deployment speed in advertising use cases.
- Windows:Enterprise device management integration supports mixed-reality headsets in manufacturing training environments with existing Microsoft infrastructure.
iOS holds the dominant share in premium segments, while wearable devices are climbing the fastest in industrial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement departments in Germany, the United States, and China concentrate the highest-value AR training contracts, while consumer activation volumes cluster in Chinese and American smartphone markets where ARCore and ARKit distribution densities peak.
United States
Oil and gas operators in Texas and Louisiana license premium AR safety simulation modules for hazardous environment rehearsal. FCC equipment authorization standards govern pre-market testing for radio frequency emissions in XR hardware. Houston's energy corridor anchors industrial AR deployment, with per-intervention pricing models displacing perpetual software licenses under intensified CFO scrutiny.
Germany
Mittelstand manufacturers underinvest in AR-assisted maintenance, creating whitespace for tool vendors embedding spatial guidance into existing technician workflows. GDPR Article 9 imposes consent-layer complexity on face-tracking AR applications, extending deployment timelines by regulatory review cycles. Bavaria's automotive clusters pilot location-based AR for factory floor navigation, with ISO/IEC 27001 certification becoming a procurement gate.
China
Smartphone production-linked incentives under India's PLI scheme accelerate local AR-capable device manufacturing, while domestic content moderation requirements favor regional platform development. NMPA and MIIT impose parallel hardware certification and content moderation requirements that fragment go-to-market pathways. Shenzhen's electronics manufacturing ecosystem supplies specialized XR chipsets, though GPU-NPU integration density remains concentrated among dominant vendors.
Japan
Industrial robotics integrators in Nagoya and Osaka demand CAD overlay accuracy exceeding aesthetic rendering requirements for maintenance workflows. METI standards shape interoperability expectations for enterprise AR deployments. Tokyo's location-based entertainment venues prioritize throughput optimization and hardware durability in high-traffic deployments.
India
Smartphone production-linked incentives accelerate local AR-capable device manufacturing, with domestic content moderation requirements favoring regional platform development. BIS certification and TRAI data localization mandates impose compliance burdens on biometric data processing. Karnataka's Bangalore tech corridor concentrates computer vision engineering talent, though SLAM optimization expertise commands compensation premiums.
Global Mobile Augmented Reality Market Competitive Landscape
Player mix skews toward vertically integrated technology conglomerates controlling custom silicon and spatial computing frameworks. The vendor base concentrates around three strategic archetypes: ecosystem platform owners anchoring distribution scale, specialized XR chipset suppliers enabling third-party hardware, and industrial software vendors embedding AR into legacy enterprise systems. Dominant competitive moves include backward integration into sensor fusion IP and geographic expansion through regulatory-compliant data infrastructure.
Among North American technology conglomerates, Apple Inc. and Microsoft Corporation exemplify the ecosystem-platform archetype through captive control over hardware-software integration. Google LLC anchors volume scale through ARCore distribution across fragmented Android installed bases. Qualcomm Technologies Inc. occupies a position as the specialized component supplier, with XR-capable SoC production concentrated among a narrowing set of fabricators.
| Leading Market Players |
|---|
| Apple Inc. |
| Google LLC |
| Microsoft Corporation |
| Samsung Electronics Co. Ltd. |
| Qualcomm Technologies Inc. |
| Magic Leap Inc. |
| PTC Inc. |
| Snap Inc. |
| Niantic Inc. |
| Others |
Supply & Pricing Matrix
Capacity utilization at advanced semiconductor foundries in Taiwan and South Korea shapes both component availability floors and the pricing power of XR-capable SoC vendors. Scale economies in neural processing unit integration compress marginal costs for flagship-tier chipsets while inflating mid-tier hardware bill-of-materials, bifurcating mobile AR device economics across premium and mass-market deployment tiers.
Pricing Analysis
Cost-plus contracts with Taiwanese foundries index wafer prices to spot-market polysilicon rates, embedding commodity volatility into XR chipset procurement. Three-tier pricing structure across premium spatial computing, standard ARCore-compatible, and economy marker-based tiers separates vendors by GPU-NPU integration density. Cost compression in mid-tier SLAM modules intensifies as Qualcomm and Apple dominate custom silicon supply. Manufacturing units in Germany exhibit lowest price sensitivity due to safety-critical simulation requirements, while K-12 educational institutions in India face acute budget constraints.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for XR-capable SoCs, while China's Shenzhen ecosystem concentrates time-of-flight sensor module assembly. The supply chain draws from gallium arsenide substrates, rare-earth magnet components, and specialized optical-grade polymers. Single-source vulnerability in EUV lithography equipment creates chokepoint exposure for advanced node production. Distribution runs through Qualcomm's direct OEM channel for Android handset integration and Apple's captive supply chain for ARKit-enabled devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile AR market exhibits cyclical recovery characteristics as enterprise training budgets rebound from post-pandemic compression and 5G-edge infrastructure deployment accelerates capital allocation toward latency-sensitive industrial applications.
For Market Incumbents: Compound ecosystem lock-in through backward integration into sensor fusion intellectual property and captive control over spatial computing frameworks. Defend against emerging web-based AR challengers by deepening ARKit and ARCore certification requirements that fragment cross-platform deployment pathways. Prioritize ISO/IEC 27001 infrastructure investment to capture GDPR-driven procurement gates in European manufacturing clusters.
For New Entrants and Emerging Players: Anchor in German Mittelstand maintenance workflows where legacy system integration complexity has deterred platform incumbents. Target per-intervention pricing models for oil and gas safety simulation modules, where outcome-based contracting creates whitespace beneath established licensing fee structures. Pursue regulatory-compliant data infrastructure partnerships to bypass NMPA and MIIT fragmentation barriers in Chinese industrial markets.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized industrial software vendors with embedded AR capabilities over consumer application studios facing platform gatekeeper dependency. Long-term viability hinges on acquisition targets possessing SCADA middleware expertise and existing technician workflow integration. Watch for inflection signals in 5G-edge MEC node deployment density across United States manufacturing corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| Neural Radiance Field Pipeline Integration | NeRF compression reduces e-commerce asset production timelines from weeks to hours for retail cosmetics brands. |
| ISO/IEC 27001 Certification Investment | European procurement departments mandate certified AR platforms for workforce training compliance gates. |
| 5G-Edge Split Rendering Architecture | MEC node offloading unlocks subscription pricing for latency-sensitive industrial maintenance applications. |
| Biometric Data Infrastructure Segregation | EU AI Act audit trail requirements force regional data processing investment for face-tracking AR vendors. |
| Qualcomm XR Chipset Supply Agreement | Specialized SoC access enables hands-free wearable AR for safety-constrained oil and gas environments. |
Research Methodology
The analysis maps markerless SLAM implementations, location-based urban navigation, and industrial safety simulation modules, each validated through platform engineering leads at ecosystem owners, procurement officers at Mittelstand manufacturers, and regulatory compliance directors at cross-border AR service providers. Primary interview insights triangulate against SEC hyperscaler capex disclosures, Sensor Tower ARKit and ARCore adoption metrics, FCC equipment authorization filings, and EU AI Act implementation guidance documents. Bottom-up segment sizing reconciles with top-down smartphone installed base projections across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including hyperscaler spatial computing R&D disclosures and industrial training technology procurement databases. The analytical framework models technology type, application vertical, deployment platform, and end-user procurement sophistication across the projection horizon. CAGRs derive from logistic diffusion curves fitted to enterprise adoption timelines and consumer activation velocity data. Industry-specific inputs include SLAM algorithm standardization trajectories and GPS-denied indoor positioning cost curves.
Material uncertainties — regulatory enforcement intensity under EU AI Act biometric provisions, foundry capacity allocation shifts for NPU-dense SoCs, and 5G MEC node deployment pacing — sit outside the modeled envelope. Forecasts reflect assumptions about sustained enterprise training budget recovery and stable platform gatekeeper economics. Recalibration cycles align with material shifts in semiconductor supply availability and antitrust rulings affecting iOS-Android interoperability mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
India Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Mirror Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Enterprise Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Connected Service Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality for Consumer Market
Virtual Reality (VR) and Augmented Reality (AR)
Location Based VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
AR in Education Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Augmented Reality (AR) and Mixed Reality (MR) Market