
 Intellectual Property Software Market | 2026-2036
Intellectual Property Software Market Size, Share, and Industry Trends Forecast 2026-2036
Intellectual Property Software Market Intelligence
Proprietary on-premise infrastructure is shifting toward API-native cloud architectures, compressing implementation timelines and flattening total cost curves. Clarivate Derwent Innovation leverages its legacy bibliographic depth to anchor high-value analytics subscriptions across European pharmaceutical clients. Patsnap competes aggressively on AI-enabled prior-art search speed, while Wellspring IP Management specializes in university technology transfer workflows where grant compliance intersects with patent prosecution.
Intellectual property software comprises modular platforms for creating, prosecuting, monitoring, and commercializing patent, trademark, copyright, and trade secret assets, typically integrating structured bibliographic data with natural language processing engines that parse claim language against prior-art corpuses. Its primary commercial purpose is to reduce legal risk exposure and accelerate monetization of intangible assets across invention lifecycles. Cloud-based deployment now leads solution type adoption as corporate legal departments demand elastic compute for portfolio analytics, though on-premise retains stronghold status among government agencies with data-sovereignty constraints. Patent management solutions capture the deepest margin pools due to prosecution complexity and renewal fee structures, while trademark management grows fastest among consumer brand portfolios expanding into Southeast Asian registration regimes.
The USPTO's electronic filing mandates and the EU's Unitary Patent System reshape platform requirements, forcing vendors to synchronize docketing rules across multiple national patent offices simultaneously. ISO 27001 certification and GDPR Article 32 technical measures increasingly gate procurement decisions for cross-border IP law firms handling client invention disclosures. Stakeholders must monitor how generative AI training data disputes rewrite prior-art disclosure obligations and platform liability frameworks.
Market Dynamics
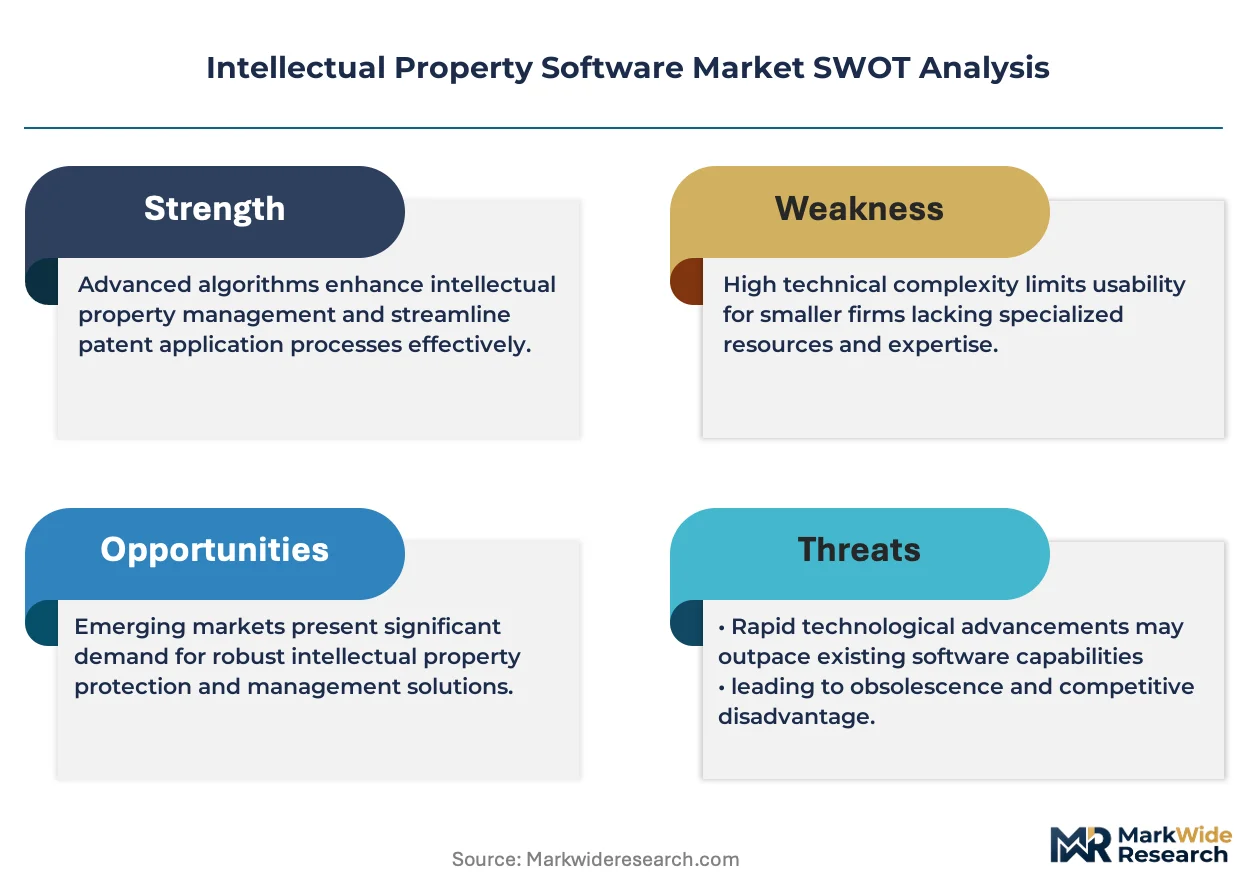
API-native cloud architectures are compressing implementation timelines from months to weeks while flattening total cost curves across corporate legal departments. This infrastructure shift reconfigures competitive positioning by rewarding vendors with elastic compute capacity and punishing legacy on-premise incumbents.
Growth Catalysts
- EU AI Act transparency mandates:The regulation forces vendors to embed compliance tools directly into IP platforms, creating built-in demand for audit-ready workflow modules.
- Life sciences patent portfolio expansion:Pharmaceutical and biotech firms now drive enterprise adoption as R&D pipelines thicken and prosecution complexity multiplies.
- Germany's automotive-chemical patent clustering:Dense filing activity around Munich and Ludwigshafen concentrates demand for localized docketing and annuity management services.
Market Restraints
- Data sovereignty compliance costs:Government agencies in defense and national security sectors mandate on-premise deployment, fragmenting vendor R&D across incompatible infrastructure stacks.
- ISO 27001 certification barriers:Cross-border IP law firms gate procurement on technical security measures, excluding smaller vendors lacking audit resources.
- Generative AI training data liability:Unclear prior-art disclosure obligations expose platforms to retroactive infringement claims as training corpus disputes multiply.
Strategic Opportunities
- Southeast Asian trademark registration regimes:Consumer brand portfolios expanding into Indonesia, Vietnam, and Thailand create demand for multi-jurisdictional filing automation.
- USPTO-EPO docketing synchronization:The Unitary Patent System mandates simultaneous rule compliance across national offices, favoring platforms with real-time regulatory update engines.
- University technology transfer workflow digitization:Grant compliance intersecting with patent prosecution creates specialized demand for integrated invention disclosure and licensing modules.
Industry Challenges
- Patent attorney-AI tool integration friction:Practitioners resist workflow disruption from automated claim drafting, slowing platform adoption despite efficiency gains.
- Legacy ERP system interoperability:Corporate legal departments struggle to synchronize IP data with existing financial and HR systems, extending implementation timelines.
- Multi-jurisdictional renewal fee complexity:Annuity management across 150+ national patent offices demands continuous regulatory monitoring that strains mid-tier vendor capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intellectual Property Software Market |
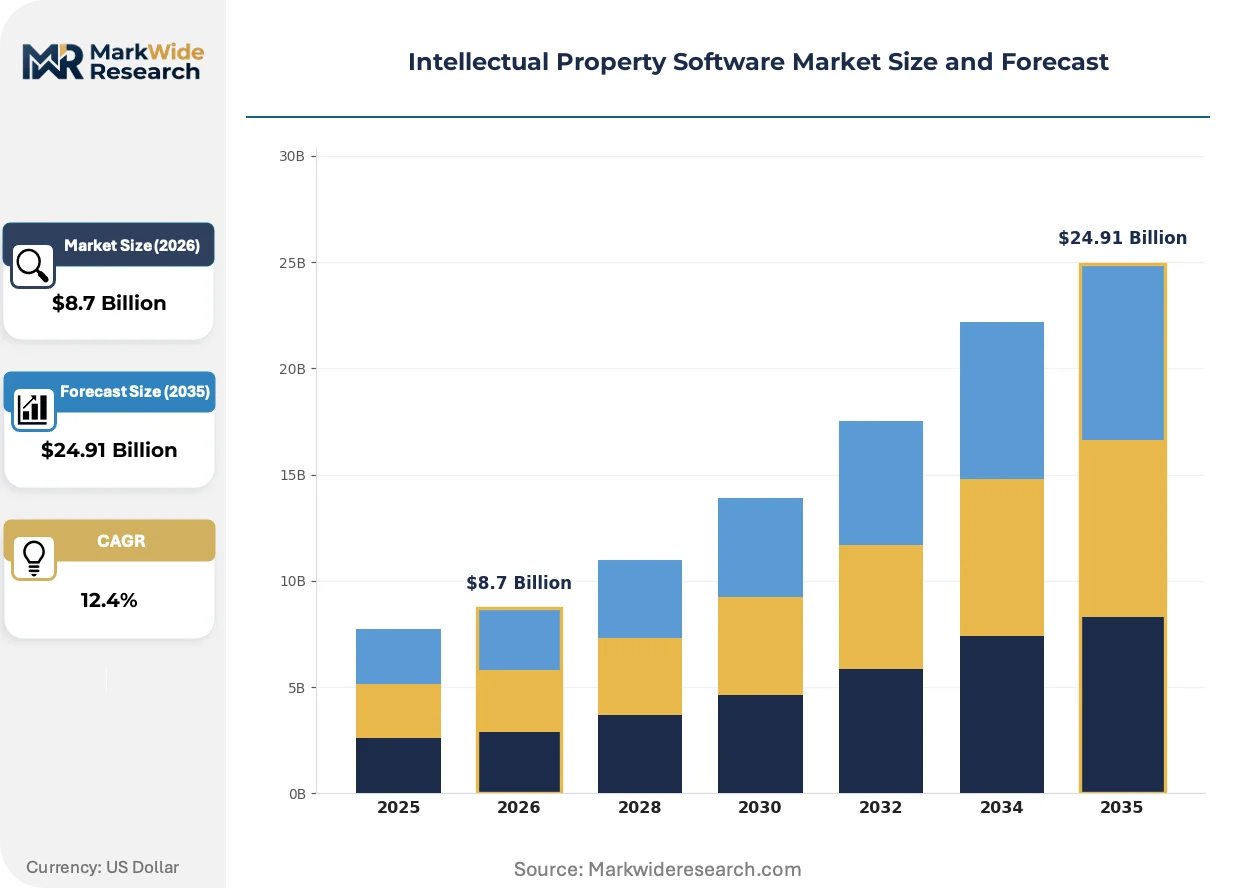
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $24.91 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Virtual Private Cloud Solution Type: Patent Management, Trademark Management, Copyright Management, Trade Secret Management Application: Portfolio Management, Licensing Management, Patent Analytics, Compliance Tracking End User: IP Law Firms, Corporate Legal Departments, Government Agencies, Research Institutes |
| Companies Covered | Questel Orbit, Novelus IP, Patsnap, DocketTrak, Google Patents, Clarivate Derwent Innovation, Relecura, Wellspring IP Management, LexisNexis IP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intellectual Property Software Market Strategic Shifts & Innovations
Natural language processing engines are parsing claim language against prior-art corpuses with accelerating precision, compressing the invention-to-filing cycle for competitive advantage. This capability convergence is redrawing vendor differentiation around speed-to-insight rather than bibliographic depth alone.
Transformer-based semantic search is rewriting how prior-art relevance scores are calculated, replacing Boolean keyword matching with contextual similarity ranking. Mid-sized law firms now adopt these tools within eighteen-month procurement cycles, collapsing the traditional three-year technology refresh window. The compression is enabling flat-fee prior-art search offerings that displace hourly billing models.
The EU AI Act's risk-based classification system imposes documentation burdens on high-stakes patent analytics tools deployed in medical device and pharmaceutical prosecution. Vendors must now maintain algorithmic audit trails and human-in-the-loop verification logs. German automotive patent departments are responding by consolidating vendor relationships to reduce compliance fragmentation.
Corporate legal departments now unbundle IP analytics from full-platform subscriptions, purchasing API-accessible search modules on consumption-based terms. This procurement pattern disrupts traditional seat-license pricing and favors vendors with modular microservice architectures. The shift is most visible among US-based Fortune 500 manufacturers with distributed R&D footprints.
Intellectual Property Software Market Segmentation
IP software buyers diverge sharply on infrastructure sovereignty versus elastic scalability, forcing vendors to maintain parallel development tracks. Segmentation reveals how procurement priorities split across compliance-heavy government users and speed-focused corporate legal departments.
Deployment:
Cost tier separates buyers most cleanly, with infrastructure expenditure thresholds dictating architecture choices across organization sizes.
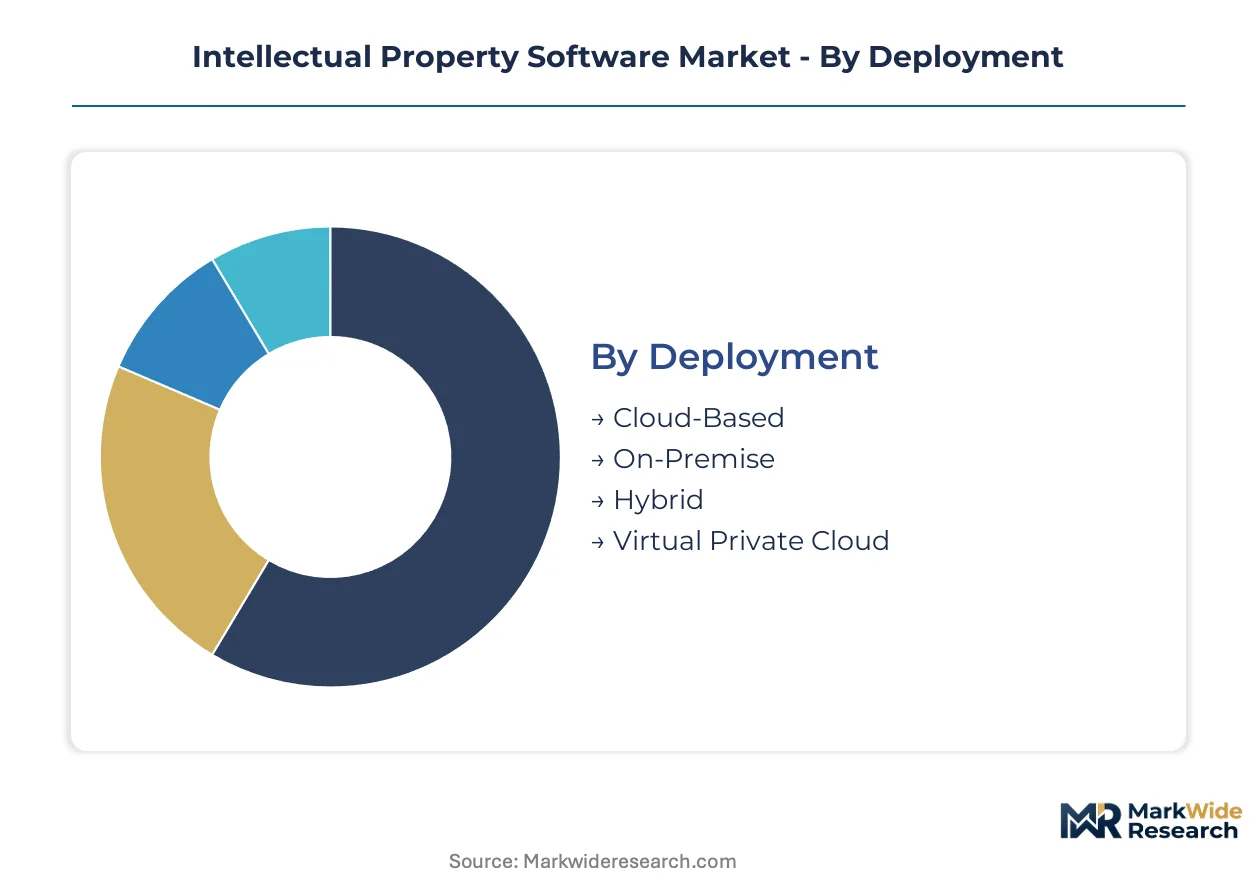
- Cloud-Based:Elastic compute architectures enable consumption-based pricing and API-native integration with corporate ERP systems. Demand concentrates among Fortune 500 manufacturers with distributed R&D footprints in Germany, the United States, and Japan, driven by ISO 27001 certification requirements gating procurement decisions.
- On-Premise:Air-gapped installations with full data sovereignty satisfy defense and national security mandates. Government agencies in the United States, France, and China mandate this architecture, fragmenting vendor R&D across incompatible infrastructure stacks and elevating compliance costs.
- Hybrid:Split workloads balance sensitive prosecution data on local servers with analytics in cloud environments.
- Virtual Private Cloud:Isolated tenant environments within hyperscaler infrastructure address GDPR Article 32 technical measures for cross-border law firms.
Volume sits with Cloud-Based deployments; growth tilts toward Virtual Private Cloud as GDPR enforcement tightens.
Solution Type:
Maturity curves divide this category, with established modules competing against emerging segments gaining regulatory tailwinds.
- Patent Management:Prosecution docketing, annuity fee calculation, and claim drafting tools anchor enterprise subscriptions. Life sciences companies in Basel, Boston, and Singapore drive deepening adoption as portfolio complexity multiplies, though generative AI training data liability exposures constrain automation appetite.
- Trademark Management:Multi-jurisdictional filing automation and watch services address brand expansion into Indonesia, Vietnam, and Thailand. Consumer goods portfolios in Milan, Seoul, and São Paulo generate fastest-expanding demand as registration regimes proliferate.
- Copyright Management:Digital rights tracking for media and software assets with automated infringement detection.
- Trade Secret Management:Invention disclosure workflows and access logging for formula and process protection.
Revenue concentrates in Patent Management; Trademark Management expands most quickly on Southeast Asian filing volume.
Application:
Customer workflow integration depth determines purchasing patterns, with standalone analytics unbundling from full-platform commitments.
- Portfolio Management:Centralized dashboards tracking prosecution status, maintenance deadlines, and competitive positioning across asset classes. Corporate legal departments in automotive and chemical sectors around Munich and Ludwigshafen prioritize this capability for renewal fee optimization.
- Patent Analytics:Transformer-based semantic search and prior-art relevance scoring compress invention-to-filing cycles. Mid-sized law firms in London, Chicago, and Tokyo now procure these tools on eighteen-month refresh cycles, displacing hourly billing with flat-fee search offerings.
- Licensing Management:Royalty tracking and term compliance for outbound technology agreements.
- Compliance Tracking:EU AI Act documentation and algorithmic audit trail maintenance for high-risk medical device prosecution.
Procurement frequency is highest for Patent Analytics; contract value peaks with Portfolio Management.
End User:
Organizational mission shapes technical requirements, with profit motives diverging from public-interest mandates.
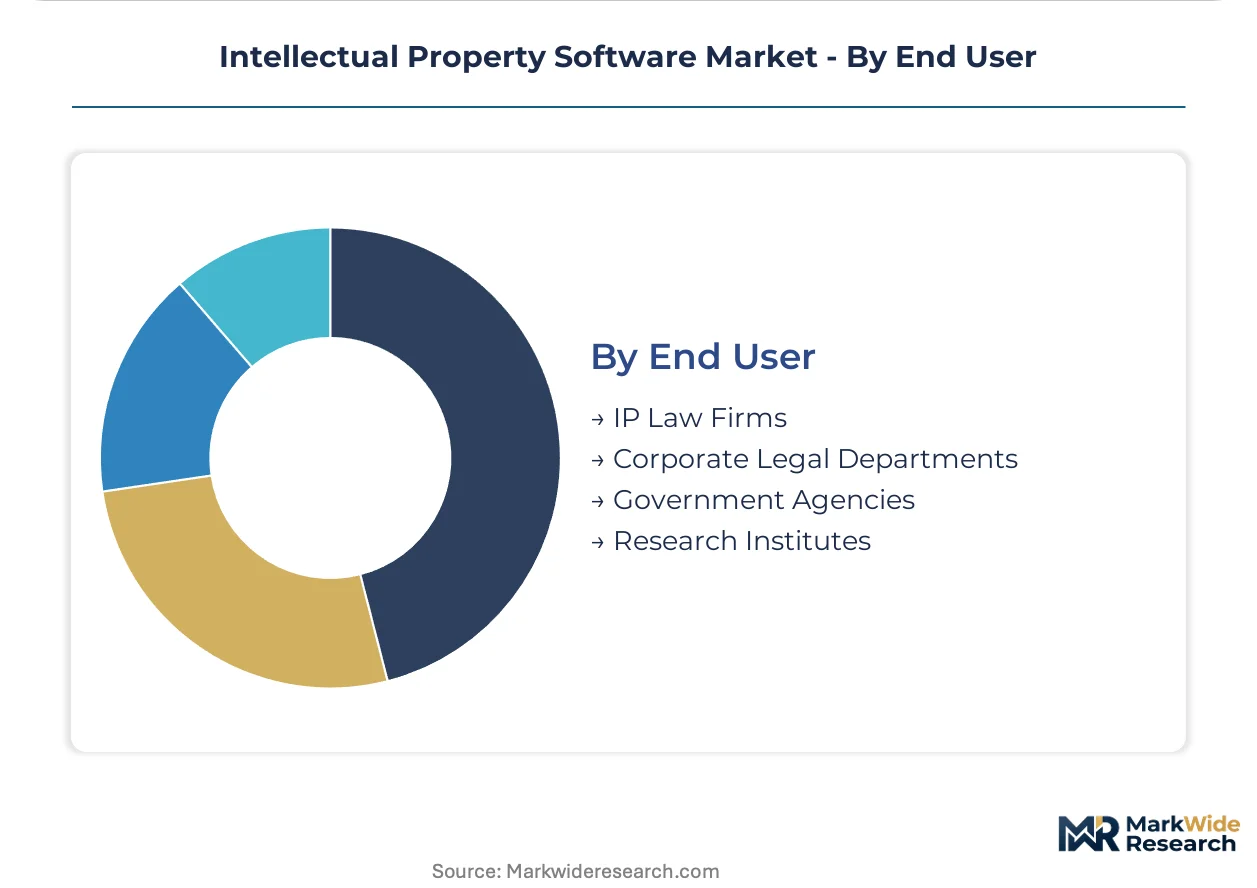
- Corporate Legal Departments:Direct integration with R&D financial systems and HR invention disclosure portals. Technology, pharmaceutical, and automotive verticals in California, New Jersey, and Baden-Württemberg dominate spend, demanding real-time USPTO-EPO docketing synchronization.
- IP Law Firms:Multi-client data segregation and white-label reporting for portfolio owners. Cross-border practices handling US, European, and Japanese filings gate procurement on GDPR Article 32 and ISO 27001 certification, excluding smaller vendors lacking audit resources.
- Government Agencies:Public patent office examination tools and inventor subsidy program administration.
- Research Institutes:Grant compliance intersection with technology transfer and licensing workflow digitization.
Spending scale favors Corporate Legal Departments; specialized module demand clusters with Research Institutes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in jurisdictions with dense patent filing activity and stringent regulatory frameworks. The United States, Germany, Japan, China, and the United Kingdom collectively anchor procurement volumes for IP software platforms.
United States
Corporate legal departments in California and New Jersey drive cloud-based deployment adoption. The USPTO's electronic filing mandates compress implementation timelines for docketing synchronization tools. Boston's biotech corridor generates specialized demand for portfolio analytics modules.
Germany
Automotive and chemical patent clustering around Munich and Ludwigshafen concentrates demand for localized annuity management. The EU AI Act's transparency requirements force vendors to embed compliance documentation into prosecution workflows. Baden-Württemberg's industrial R&D centers prioritize real-time EPO synchronization capabilities.
Japan
Electronics manufacturers in Tokyo and Osaka sustain demand for prior-art search acceleration. METI's intellectual property strategy guidelines emphasize digital transformation of patent offices. The Nagoya automotive hub requires multi-jurisdictional filing automation for Southeast Asian expansion.
China
Domestic patent filing volume growth in Beijing and Shanghai drives platform localization requirements. SAMR's data security regulations mandate sovereign cloud architectures for sensitive prosecution data. The Yangtze River Delta's semiconductor clusters seek integrated trade secret management modules.
United Kingdom
London-based IP law firms gate procurement on GDPR Article 32 technical measures for cross-border client data. The UK's post-Brexit patent system divergence creates demand for dual USPTO-EPO docketing engines. Cambridge's life sciences research institutes specialize in technology transfer workflow digitization.
Intellectual Property Software Market Key Industry Players
API-native architecture migration dominates the current landscape as vendors compress implementation timelines from months to weeks. The vendor base splits between legacy bibliographic data incumbents and AI-native challengers. Three archetypes emerge: full-platform suite providers, specialized analytics module vendors, and university technology transfer specialists. Competitive intensity centers on M&A activity for NLP engine capabilities and strategic partnerships with hyperscaler cloud infrastructure providers.
Within the full-platform tier, Clarivate Derwent Innovation anchors high-value analytics subscriptions across European pharmaceutical clients. Patsnap exemplifies the AI-native challenger archetype with its emphasis on semantic search velocity. Wellspring IP Management occupies a specialized position serving research institutes where grant compliance intersects with patent prosecution workflows.
| Leading Market Players |
|---|
| Questel Orbit |
| Novelus IP |
| Patsnap |
| DocketTrak |
| Google Patents |
| Clarivate Derwent Innovation |
| Relecura |
| Wellspring IP Management |
| LexisNexis IP |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure costs cascade through IP software pricing tiers, with hyperscaler compute fees in Frankfurt, Virginia, and Singapore anchoring subscription rates for Fortune 500 legal departments while on-premise licensing premiums reflect air-gapped deployment complexity for defense agencies.
Pricing Analysis
Volume concentrates in consumption-based API modules while margin pools sit with full-platform enterprise subscriptions. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth and analytics sophistication. Pricing pressure stems from mid-tier vendors competing on semantic search speed, compressing flat-fee prior-art offerings. Corporate legal departments in automotive and chemical sectors exhibit highest price sensitivity due to R&D budget scrutiny, while government agencies accept premium rates for data sovereignty compliance.
Supply Chain Analysis
Dual-sourcing requirements from corporate procurement mandate qualified redundancy across NLP engine providers and cloud infrastructure vendors. Software development concentrates in the United States, Germany, and India, with bibliographic data feeds anchored in the United Kingdom and the Netherlands. Raw material dependencies include transformer model training compute, patent corpus licensing, and regulatory update feeds. Single-source vulnerability sits with legacy bibliographic database providers. Distribution runs through direct enterprise sales teams and hyperscaler marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-native architectures are displacing legacy on-premise installations, forcing vendors to rebuild delivery models around microservice elasticity rather than monolithic deployment.
For Market Incumbents: Deploy modular microservice architectures to unbundle analytics from full-platform subscriptions. Incumbents must accelerate ISO 27001 certification renewal and deepen integration partnerships with hyperscaler infrastructure providers. The threat from AI-native challengers like Patsnap demands defensive repositioning around bibliographic data moats rather than feature parity races.
For New Entrants and Emerging Players: Capture university technology transfer workflows where grant compliance intersects with patent prosecution. Southeast Asian trademark filing automation presents the most penetrable geography as consumer brands expand into Indonesia, Vietnam, and Thailand. A vertical-specific go-to-market anchored in EPO-USPTO docketing synchronization tools bypasses incumbent lock-in.
For Investors and Strategic Acquirers: EU AI Act enforcement actions against non-compliant analytics vendors are the leading indicator that algorithmic audit trail capabilities will separate viable platforms from stranded assets. Long-term viability favors acquirers of NLP engine specialists with transformer-based semantic search IP. The signal to monitor is consolidation of vendor relationships by German automotive patent departments seeking compliance fragmentation reduction.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-native architectures compress implementation timelines from months to weeks for corporate legal departments. |
| Acquisition of Specialist Firm | NLP engine capabilities anchor competitive differentiation as semantic search displaces Boolean keyword matching. |
| Strategic Partnership | Hyperscaler alliances enable elastic compute for portfolio analytics demanded by Fortune 500 manufacturers. |
| Geographic Expansion | Localized docketing modules capture patent filing clusters around Munich and Ludwigshafen in Germany. |
| Product Launch | EU AI Act compliance documentation tools address risk-based classification mandates for medical device prosecution. |
Research Approach
Document review covered patent office filing statistics, vendor SEC disclosures, and regulatory guidance documents from the USPTO and EPO, complemented by interviews with IP law firm managing partners, corporate legal department heads, university technology transfer officers, and cloud infrastructure procurement leads. Secondary validation drew from ISO certification registries, GDPR enforcement actions, and EU AI Act implementation timelines. Bottom-up triangulation across deployment models and solution types was cross-checked against top-down market sizing from bibliographic data provider revenue disclosures.
Market value and volume outputs were generated through segmented modeling across cloud-based, on-premise, hybrid, and virtual private cloud deployments, intersected with patent management, trademark management, copyright management, and trade secret management solution types. CAGRs were derived from elasticity-adjusted adoption curves weighted by regulatory mandate timing. Forecast inputs included USPTO electronic filing mandate compliance deadlines and EU Unitary Patent System docketing rule synchronization requirements.
The model holds under stable regulatory enforcement intensity and continued hyperscaler infrastructure investment; deviation in generative AI training data liability rulings or data sovereignty mandate expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Gym Software Market
Software & Services
North America Saas-Based Expense Management Market
Software & Services
Exploration and Production Accounting System Software Market
Software & Services
Global Script Writing Software Market
Software & Services
Global Project Software Market
Software & Services
Global Inspection Management Software Market
Software & Services
Lead Mining Software Market
Software & Services
Instant Messaging Software Market
Software & Services
Output Management Software Market
Software & Services
CGI Software Market
Software & Services
Global Self-Service BI Market
Software & Services
Camp Management Software Market
Software & Services
Dynamic Slotting and Storage Optimization Software Market
Software & Services
Software Testing Tools Market
Software & Services
Disk Space Analyzer Software Market
Software & Services
Global Architecture Design Software Market