
 Augmented Learning Market | 2026-2036
Augmented Learning Market Size, Share, and Industry Trends Forecast 2026-2036
Augmented Learning Market Outlook
The augmented learning market is restructuring around a sharp split between premium enterprise-grade platforms with full AI integration and commodity mobile applications serving casual self-learners. Meta Platforms, Inc. leverages its VR hardware ecosystem to anchor immersive training deployments for corporate clients. Microsoft Corporation competes through cloud-based AI services that power adaptive learning pathways across educational institutions. Duolingo sustains its position in language acquisition through freemium distribution and gamified retention mechanics.
Augmented learning fuses digital overlays, spatial computing, and real-time feedback to create interactive educational environments that blend physical and virtual content. These systems typically operate through AR software rendering 3D models at 60 frames per second with sub-10 millisecond latency to prevent motion sickness and maintain cognitive engagement. Software platforms command the deepest margin pools due to recurring subscription revenue and low marginal delivery costs. Corporate training represents the fastest-expanding end user category as enterprises replace physical simulation facilities with scalable virtual alternatives. Wearable devices remain supply-constrained by component shortages and certification timelines.
The U.S. Federal Aviation Administration and the European Union's AI Act both impose operational requirements on immersive training systems used in safety-critical professions. The EU AI Act mandates human oversight for high-risk educational algorithms, while the FAA certifies AR-based maintenance training for aviation technicians. China's Ministry of Industry and Information Technology enforces GB standards for head-mounted display hardware deployed in institutional settings. Stakeholders must track evolving certification requirements across jurisdictions to avoid market access delays as regulatory fragmentation intensifies.
Market Dynamics
AI integration is compressing content development cycles from months to weeks while defense and healthcare training budgets in the United States redirect toward immersive simulation technologies. This structural acceleration is forcing platform providers to rebuild around real-time adaptive engines rather than static course libraries.
Growth Catalysts
- FAA AR Maintenance Certification:The Federal Aviation Administration certifies augmented reality systems for aviation technician training, creating institutional demand for compliant platforms.
- Healthcare Simulation Migration:Medical training centers replace physical cadaver labs with spatial computing environments that reduce recurring procurement costs.
- Edge Rendering Architectures:5G-enabled distributed processing eliminates headset tethering, expanding deployable use cases for field-based workforce training.
Market Restraints
- Microdisplay Supply Concentration:OLEDoS and MicroLED panels for near-eye displays concentrate among Japanese and South Korean component suppliers, creating allocation bottlenecks.
- EU AI Act Compliance Burden:The European Union's AI Act mandates human oversight for high-risk educational algorithms, extending certification timelines for adaptive learning systems.
- Capital Intensity of Photonics:Waveguide manufacturing for see-through displays requires precision lithography equipment with 7-10 year depreciation cycles.
Strategic Opportunities
- India's National Education Policy:The country's vocational training expansion creates demand for localized AR content in manufacturing and agriculture skills.
- Generative AI Convergence:Large language models fused with spatial computing enable dynamic scenario generation for emergency response training.
- Direct Enterprise Licensing:Platform providers bypass channel partners to sell seat-based subscriptions directly to corporate learning management systems.
Industry Challenges
- Spatial Computing Talent Scarcity:The shortage of developers proficient in Unity and Unreal Engine for AR deployment extends project timelines.
- Legacy LMS Integration Friction:Enterprise customers require custom API bridges to connect immersive platforms with established compliance tracking systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Augmented Learning Market |
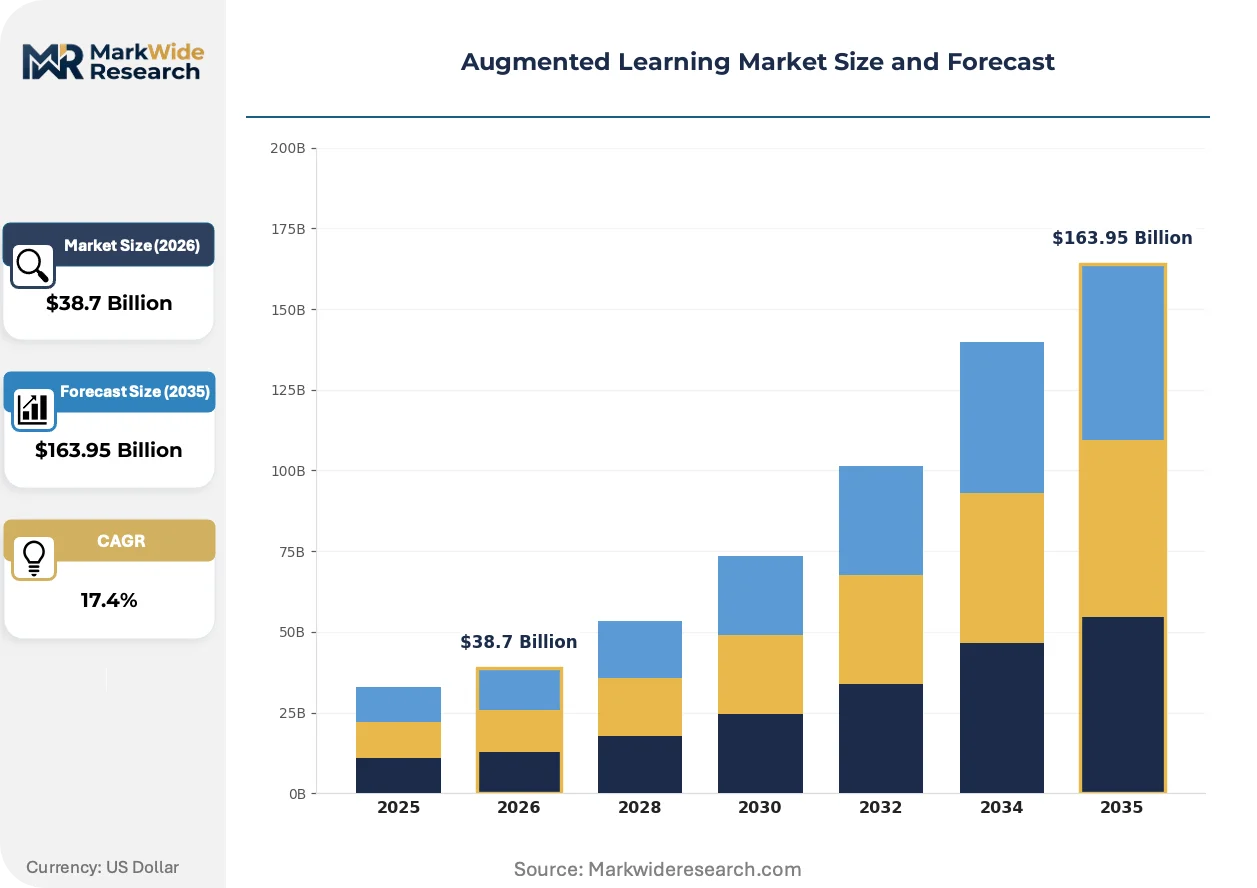
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $163.95 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Applications, Software Platforms, Wearable Devices, VR Headsets End User: Educational Institutions, Corporate Training, Self-learners, Hobbyists Technology: AR Software, Computer Vision, 3D Modeling, AI Integration Application: Skill Development, Language Learning, Simulation Training, Interactive Experiences |
| Companies Covered | Duolingo, Microsoft Corporation, Meta Platforms, Inc., Kahoot!, Pearson, HTC Corporation, Skillsoft Corporation, Adobe Inc., Blackboard Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Augmented Learning Market Strategic Shifts
Real-time rendering pipelines and generative content engines are restructuring how training material reaches end users. Platform architecture decisions made now will determine which providers capture recurring revenue versus one-time deployment fees.
Spatial anchors with persistent world-mapping capabilities are unifying physical facility layouts with digital training overlays. Industrial maintenance teams at energy and utilities firms deploy these systems to reduce technician error rates during complex equipment servicing. The technology is unifying previously siloed CAD data, IoT sensor feeds, and procedural documentation into single-view operator guidance.
The EU AI Act's human-in-the-loop mandate for high-risk educational algorithms is forcing platform redesigns across European deployments. Providers must engineer audit trails and intervention protocols that satisfy notified body assessments. Aviation and medical device manufacturers face the steepest compliance costs, with some redirecting initial rollout priorities toward less regulated corporate skill-building segments.
Enterprise buyers now demand consumption-based pricing tied to measurable competency outcomes rather than per-seat subscriptions. This reconfiguration pressures vendors to embed assessment engines that verify skill transfer rather than course completion. The shift is most visible in United States defense contracting, where training effectiveness metrics determine contract renewals and extension options.
Augmented Learning Market Segmentation
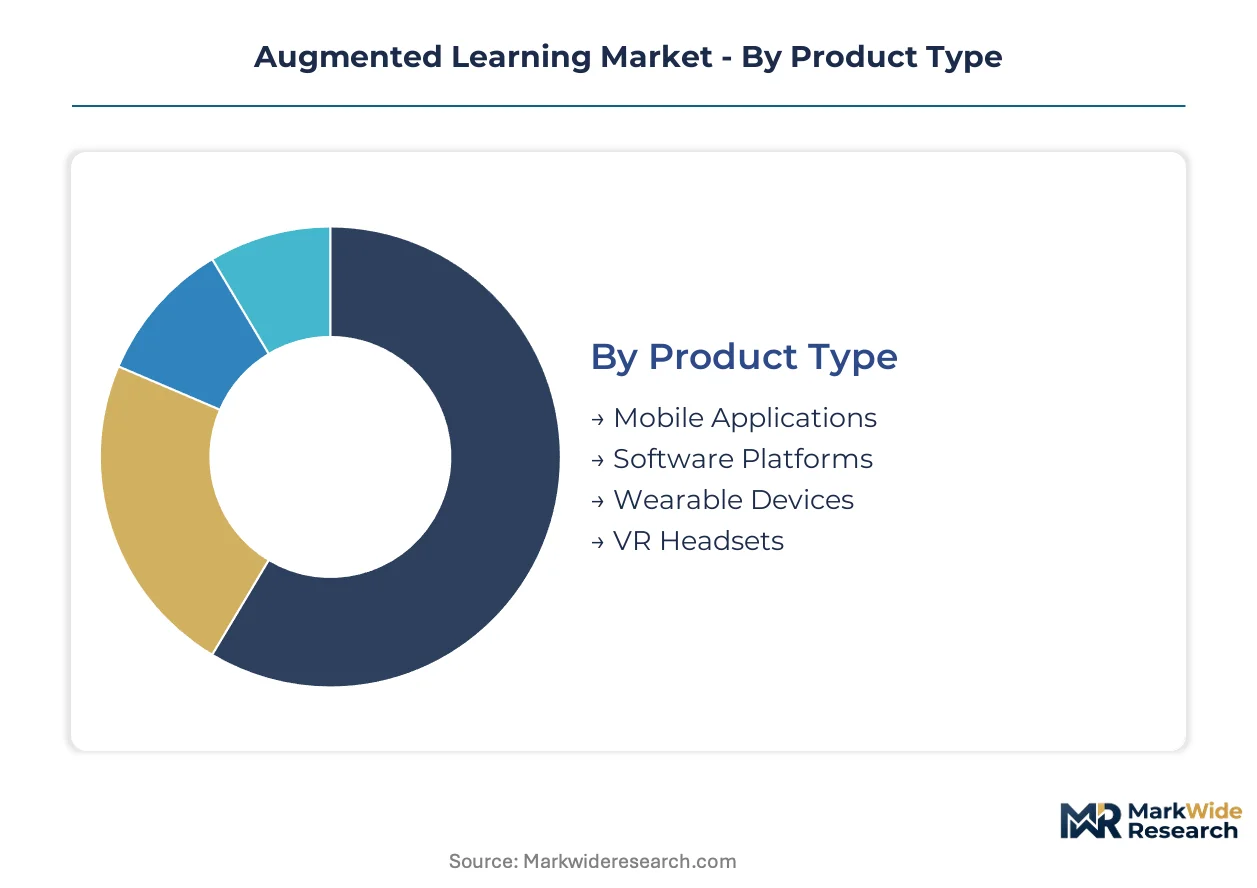
Augmented learning platforms fragment across four critical dimensions where buyer priorities diverge sharply. Enterprise procurement teams evaluate integration depth and compliance certification, while individual learners prioritize accessibility and subscription cost. Technology architecture choices lock vendors into specific margin structures and renewal dynamics.
Product Type:
Enterprise buyers weight total cost of ownership against deployment scalability when selecting platform formats.
- Software Platforms:Cloud-native architectures deliver recurring subscription revenue with sub-5% marginal delivery cost per additional seat. Siemens and Boeing deploy these systems for workforce upskilling programs requiring FAA-compliant audit trails. Volume sits with software platforms; growth tilts toward wearable devices.
- Wearable Devices:OLEDoS and MicroLED near-eye displays operate at 60 frames per second with sub-10 millisecond latency to prevent motion sickness. Supply constraints from Japanese and South Korean component suppliers create allocation bottlenecks extending fulfillment timelines.
- Mobile Applications:Freemium distribution models dominate language acquisition and casual skill-building segments with gamified retention mechanics.
- VR Headsets:Tethered configurations face displacement pressure from 5G-enabled edge rendering architectures eliminating physical constraints.
Margin pools concentrate in software platforms; hardware categories grapple with component shortage volatility.
End User:
Budget authority and procurement complexity separate institutional buyers from individual purchasers.
- Corporate Training:Learning management system integration requirements drive API customization for compliance tracking. United States defense contractors now demand consumption-based pricing tied to measurable competency outcomes rather than per-seat subscriptions.
- Educational Institutions:K-12 and university procurement cycles align with fiscal year budgeting, creating predictable seasonal demand patterns.
- Self-learners:Price-sensitive subscription behavior favors monthly billing over annual commitments.
- Hobbyists:Discretionary spending on creative and recreational applications shows higher churn rates than professional use cases.
Contract value peaks with corporate training; user count concentrates among self-learners.
Technology:
Development talent scarcity and integration maturity determine vendor competitiveness.
- AI Integration:Large language models fused with spatial computing compress content development cycles from months to weeks. The EU AI Act mandates human oversight protocols extending certification timelines for European deployments.
- AR Software:Real-time rendering pipelines at 60 frames per second require specialized Unity and Unreal Engine proficiency currently in short supply.
- Computer Vision:Spatial anchors with persistent world-mapping capabilities unify physical facility layouts with digital training overlays for industrial maintenance teams.
- 3D Modeling:CAD data integration into single-view operator guidance reduces technician error rates during complex equipment servicing.
AI integration commands premium pricing; computer vision faces talent-constrained expansion.
Application:
Safety-critical certification requirements separate regulated from unregulated deployment contexts.
- Simulation Training:Medical training centers replace physical cadaver labs with spatial computing environments that reduce recurring procurement costs. The FAA certifies AR-based maintenance training for aviation technicians, creating institutional demand for compliant platforms.
- Skill Development:India's National Education Policy vocational expansion creates demand for localized AR content in manufacturing and agriculture competencies.
- Language Learning:Gamified retention mechanics sustain engagement through bite-sized daily interaction models.
- Interactive Experiences:Museum and cultural institution deployments prioritize narrative immersion over competency verification.
Simulation training carries the steepest compliance burden; interactive experiences face the lowest barriers to entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle anchors North American enterprise demand through Microsoft's cloud infrastructure and Boeing's aviation training facilities. Defense contractors in the metro area redirect procurement budgets toward FAA-certified AR maintenance platforms. Healthcare simulation centers at the University of Washington Medical Center replace physical cadaver labs with spatial computing environments.
United States
Defense contracting drives institutional procurement, with the Pentagon demanding consumption-based pricing tied to measurable competency outcomes. The FAA certifies AR-based maintenance training for aviation technicians, creating compliance-driven demand for platform providers. Siemens deploys workforce upskilling programs across industrial corridors in the Midwest and Southeast.
Germany
Industrial automation clusters in Bavaria and Baden-Württemberg integrate spatial anchors for equipment maintenance training. The EU AI Act mandates human oversight protocols for high-risk educational algorithms, extending certification timelines for adaptive learning systems. Volkswagen and BMW maintenance facilities in Wolfsburg and Munich deploy persistent world-mapping for technician guidance.
China
The Ministry of Industry and Information Technology enforces GB standards for head-mounted display hardware in institutional settings. Manufacturing skills training in the Yangtze River Delta absorbs localized AR content for vocational competencies. State-backed technology zones in Shenzhen and Hangzhou concentrate headset component assembly despite OLEDoS supply constraints.
India
The National Education Policy vocational expansion creates demand for AR content in manufacturing and agriculture skills. State governments in Maharashtra and Karnataka pilot spatial computing deployments in industrial training institutes. Bangalore's technology corridor hosts domestic platform development for cost-sensitive educational procurement.
United Kingdom
London's financial services sector adopts immersive simulation for compliance and risk management training. The Information Commissioner's Office interprets GDPR requirements for biometric data collection in educational headsets. University medical schools in Oxford and Cambridge replace traditional anatomy instruction with 3D visualization platforms.
Augmented Learning Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and enterprise integration capability. Software platforms with FAA-compliant audit trails command recurring subscription revenue with sub-5% marginal delivery costs. Three archetypes dominate: cloud-native AI integrators, VR hardware ecosystem anchors, and freemium mobile distributors. Competitive moves concentrate on direct enterprise licensing bypassing channel partners, and generative AI convergence compressing content development cycles.
Within the cloud-native tier, Microsoft Corporation exemplifies premium positioning through adaptive learning pathways across educational institutions. Meta Platforms, Inc. anchors immersive training deployments through VR hardware ecosystem control. Duolingo occupies the freemium archetype, representing gamified retention mechanics in language acquisition. These three entities collectively illustrate the market's tripartite structure: infrastructure-heavy platforms, hardware-tethered ecosystems, and lightweight mobile applications.
| Leading Market Players |
|---|
| Duolingo |
| Microsoft Corporation |
| Meta Platforms, Inc. |
| Kahoot! |
| Pearson |
| HTC Corporation |
| Skillsoft Corporation |
| Adobe Inc. |
| Blackboard Inc. |
| Others |
Value Chain & Pricing Dynamics
Cloud-native platform providers rolled up through private-equity consolidation exercise pricing discipline through subscription lock-in, while hardware vendors absorb component volatility through long-term foundry agreements that buffer end-user price exposure.
Pricing Analysis
Outcome-based pricing tied to verified competency metrics anchors enterprise procurement decisions in the United States defense contracting sector. Three-tier pricing structure across FAA-certified premium platforms, standard institutional licenses, and economy mobile subscriptions separates buyers by compliance burden and integration depth. Cost compression in the wearable device tier is intensifying because OLEDoS panel allocation favors consumer electronics over industrial headsets. Self-learners exhibit the highest price sensitivity, while aviation and medical device manufacturers accept premium positioning for audit-ready certification trails.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and South Korean component suppliers dominating OLEDoS and MicroLED microdisplay fabrication for near-eye displays. Waveguide manufacturing for see-through optics draws from precision lithography equipment concentrated in Germany and Taiwan, while final headset assembly clusters in China's Shenzhen and Hangzhou technology zones. Tariff exposure on optical components threatens margin stability for hardware vendors serving European enterprise buyers. Distribution runs through direct enterprise licensing agreements that bypass channel partners for corporate learning management system integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in microdisplay fabrication prop pricing power for platform providers with secured component allocations, compressing margins for hardware-dependent entrants lacking foundry relationships.
For Market Incumbents: Deploy generative AI convergence to compress content development cycles from months to weeks, defending against cloud-native challengers with adaptive learning engines. Deepen backward integration into spatial computing talent pipelines through Unity and Unreal Engine certification partnerships, countering developer scarcity that extends project timelines for competitors. Fortify FAA-compliant audit trail capabilities as regulatory fragmentation intensifies across jurisdictions. For New Entrants and Emerging Players: Capture India's National Education Policy vocational expansion through localized AR content development for manufacturing and agriculture skills, where incumbent presence remains thin. Exploit legacy LMS integration friction by engineering pre-built API bridges for Siemens and Boeing-scale enterprise deployments, bypassing custom development burdens that delay incumbent sales cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-native software platforms with recurring subscription revenue and sub-5% marginal delivery costs in the United States and Germany, where defense and industrial automation budgets redirect toward immersive simulation. Monitor EU AI Act certification timeline extensions as an inflection signal for European deployment prioritization shifts toward less regulated corporate skill-building segments.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Convergence | Large language models fused with spatial computing compress emergency response training scenario generation cycles. |
| Direct Enterprise Licensing | Seat-based subscriptions sold directly to corporate learning management systems bypass channel partner margin extraction. |
| FAA Certification Investment | AR-based maintenance training compliance creates institutional demand moats in aviation technician upskilling. |
| Spatial Computing Talent Pipeline | Unity and Unreal Engine certification partnerships address developer scarcity extending industrial deployment timelines. |
| Edge Rendering Architecture Deployment | 5G-enabled distributed processing eliminates headset tethering for field-based workforce training expansion. |
Study Parameters
SEC filings, FAA certification databases, and EU regulatory submissions formed the secondary backbone, cross-referenced against primary interviews with corporate training directors, spatial computing platform engineers, and healthcare simulation center procurement leads. Bottom-up triangulation across component supplier disclosures and top-down validation through defense contracting budget allocations ensured segmentation accuracy across software platforms, wearable devices, and mobile applications.
Historical trendline analysis of enterprise learning management system procurement patterns informed the projection framework across product type, end user, technology, and application dimensions throughout the forecast period. CAGRs were derived from elasticity modeling of defense and healthcare training budget redirection toward immersive simulation technologies, incorporating edge rendering architecture adoption curves and generative AI content generation velocity as industry-specific inputs.
The model holds under sustained microdisplay supply constraints and stable regulatory certification timelines; deviation in OLEDoS allocation priorities or EU AI Act enforcement intensity would shift deployment velocity assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Location-Based VR Entertainment Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
AR in Education Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Smart Augmented Reality Glasses for B2B Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Fitting Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Commercial Augmented Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Fence Market
Virtual Reality (VR) and Augmented Reality (AR)
Mixed Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Construction Market
Virtual Reality (VR) and Augmented Reality (AR)
Para-Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Wireless AR Glass Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Ski Machines Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Glasses Market