
 UK Metaverse Market | 2026-2036
UK Metaverse Market Size, Share, and Industry Trends Forecast 2026-2036
UK Metaverse Market Insights
The gap between premium immersive infrastructure and commodity virtual environments is broadening. Meta Platforms leverages its social graph and hardware ecosystem to anchor high-fidelity experiences. NVIDIA Corporation sustains its position through GPU architectures and Omniverse tooling for industrial digital twins. Epic Games differentiates via Unreal Engine's real-time rendering capabilities adopted by automotive and architectural visualizers.
The UK Metaverse Market encompasses persistent, spatially computed digital environments where users interact through avatars, requiring sub-20ms latency, 90Hz minimum refresh rates, and blockchain-verified asset ownership for commercial integrity. Virtual Reality and Artificial Intelligence command structural priority as headset penetration rises and generative AI reduces content production costs. Online Gaming and Digital Commerce represent mature revenue pools, while Virtual Events and Education emerge as faster-growing segments where margin pools shift toward platform operators and content creators.
The UK Information Commissioner's Office enforces GDPR-aligned data governance for biometric and behavioral tracking in immersive spaces. The Digital Regulation Cooperation Forum coordinates oversight across competition, content safety, and consumer protection dimensions. Stakeholders must monitor evolving liability frameworks for user-generated content and anticipate Ofcom's forthcoming duties under the Online Safety Bill as they allocate platform investment.
Market Dynamics
The UK Metaverse Market is being reshaped by the collision between GDPR-mandated data minimization and the data-hungry requirements of spatial computing. Platform operators must architect systems that preserve immersive fidelity while satisfying the Information Commissioner's Office biometric processing restrictions.
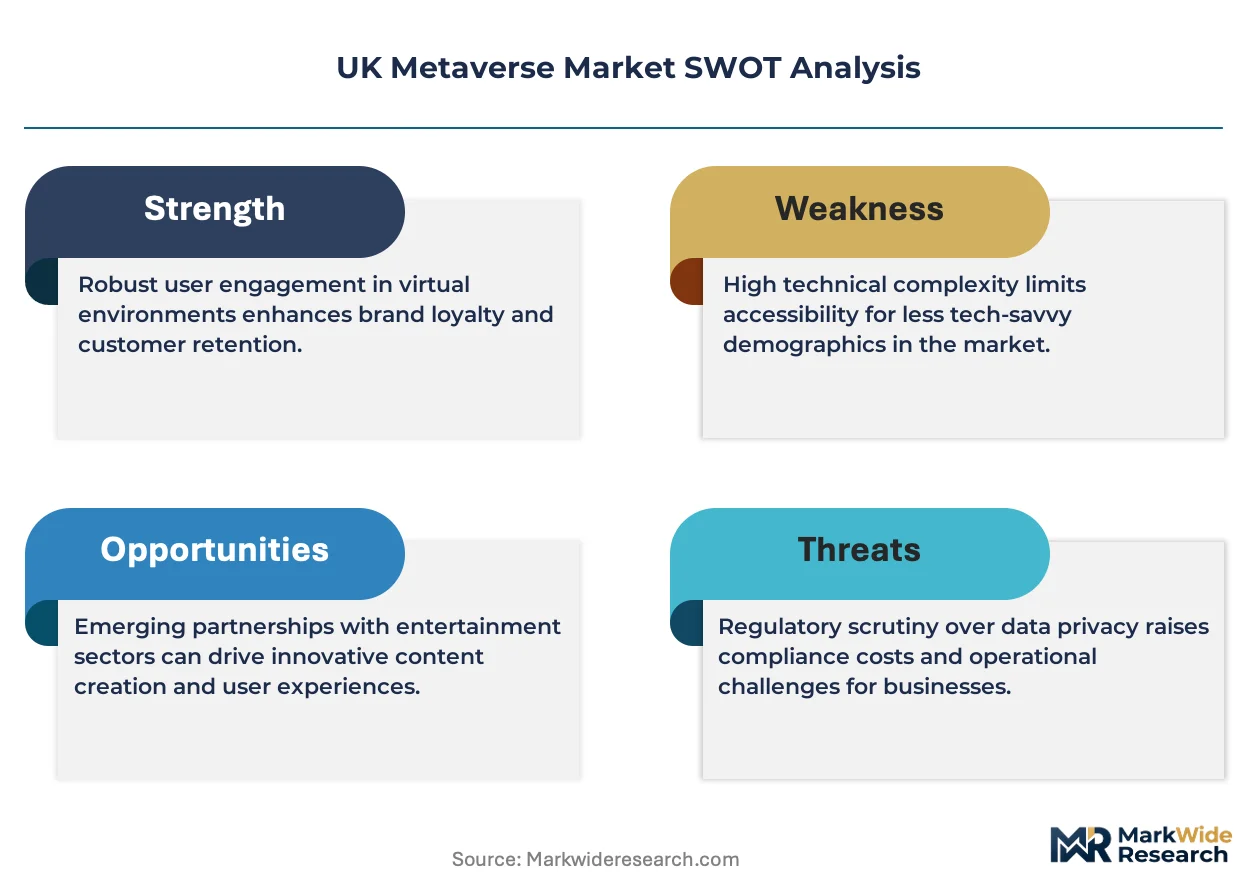
Growth Catalysts
- Enterprise Training Mandates:Manufacturing and logistics sectors deploy persistent virtual environments for hazardous equipment simulation. The Health and Safety Executive's emphasis on risk-reduction protocols accelerates budget allocation toward immersive training infrastructure.
- GDPR-Compliant Design Standards:The UK Information Commissioner's Office guidance on behavioral tracking in virtual spaces creates competitive differentiation for privacy-preserving avatar systems. Platforms demonstrating verifiable data governance secure procurement contracts from financial services buyers.
- Spatial Computing Hardware Cycles:Sub-20ms latency requirements drive refresh rate specifications for headset manufacturers. London's creative technology clusters concentrate demand for high-fidelity rendering capabilities.
Market Restraints
- GPU Supply Concentration:Foundry capacity constraints for advanced semiconductor architectures limit headset production scaling. Taiwan-based manufacturing bottlenecks transmit directly to UK hardware availability timelines.
- Biometric Data Liability Exposure:The Online Safety Bill's forthcoming duties create unquantified compliance costs for platforms processing eye-tracking and gait analysis. Ofcom's enforcement framework remains partially undefined.
- Substitute Platform Migration:Video conferencing and asynchronous collaboration tools retain enterprise budget share. Zoom and Microsoft Teams investments delay immersive environment procurement cycles.
Strategic Opportunities
- Northern England Industrial Corridors:Manchester and Leeds manufacturing hubs show underpenetrated demand for digital twin visualization. Regional development funding targets immersive technology adoption for supply chain optimization.
- AI-Generated Content Pipelines:Generative AI convergence with real-time engines reduces 3D asset production costs. Independent creators gain capacity to populate persistent worlds without traditional studio infrastructure.
- Virtual Events Infrastructure:Corporate conference budgets reallocate toward hybrid immersive formats. Exhibition organizers in Birmingham and Glasgow test persistent venue environments for recurring trade show series.
Industry Challenges
- Immersive Developer Talent Scarcity:Unreal Engine and Unity specializations command premium compensation. UK universities produce insufficient graduates with spatial computing and shader programming expertise.
- Legacy System Integration Complexity:Enterprise resource planning and customer relationship management platforms require custom API development for avatar-based interaction layers. Implementation timelines extend 18-24 months for major financial institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Metaverse Market |
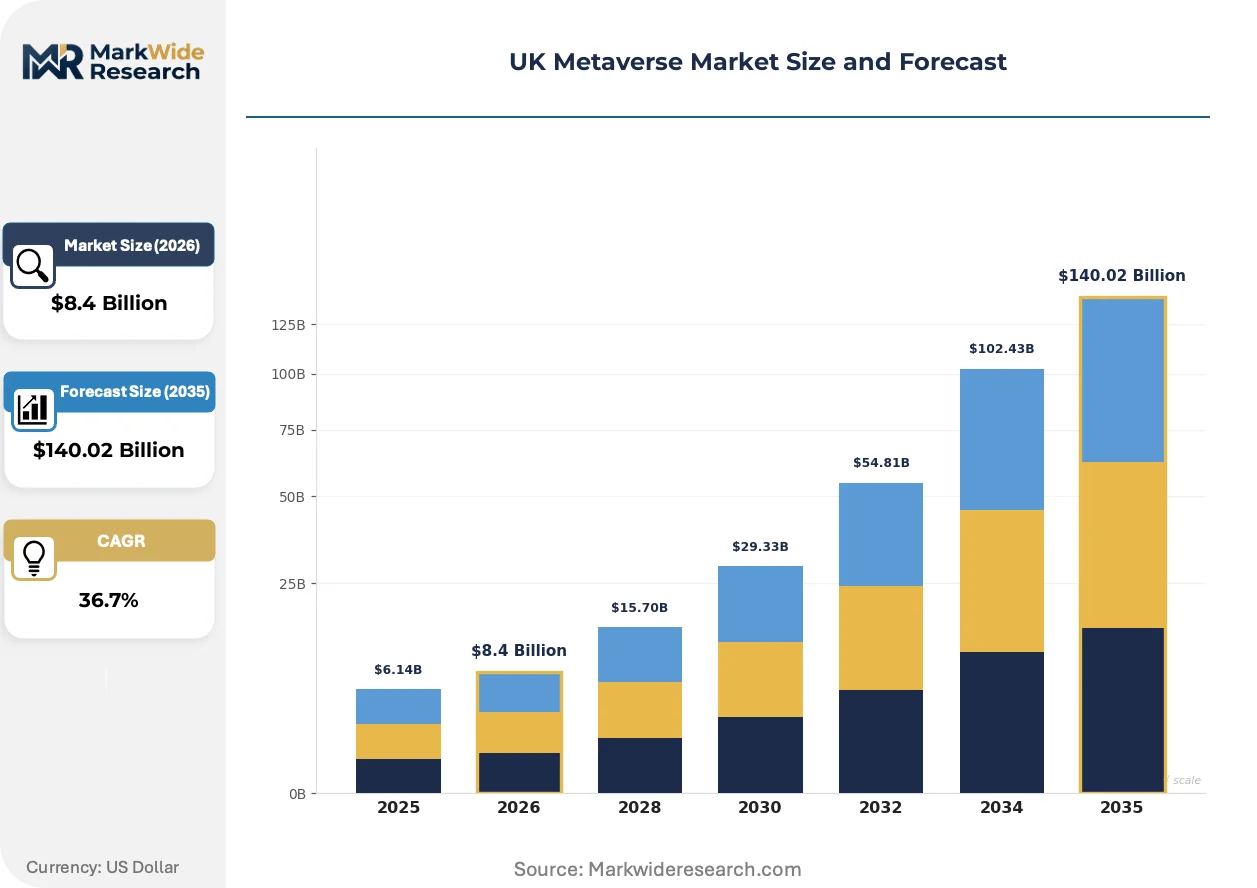
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $140.02 Billion |
| CAGR (2026 – 2036) | 36.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Blockchain, Artificial Intelligence, Virtual Reality, Augmented Reality, Mixed Reality, 5G Application: Virtual Events, Online Gaming, Digital Commerce, Social Interaction, Education, Real Estate End User: Content Creators, Advertisers, eCommerce Platforms, Educational Institutions, Real Estate Firms, Entertainment Providers Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Meta Platforms, Roblox Corporation, NVIDIA Corporation, Epic Games, Microsoft, Unity Technologies, Improbable, Hadean, LandVault, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Metaverse Market Trends and Innovations
Spatial computing architectures are absorbing generative AI capabilities at the content production layer. This convergence compresses asset creation timelines while raising new questions about intellectual property provenance in persistent environments.
Neural rendering techniques are absorbing traditional polygon-based visualization methods in automotive and architectural applications. Jaguar Land Rover and Foster + Partners deploy AI-assisted lighting and material synthesis for real-time client reviews. The structural consequence is collapsing the distinction between pre-rendered marketing content and interactive design exploration, with the technology is absorbing budget allocations previously reserved for static visualization studios.
The UK Information Commissioner's Office Age-Appropriate Design Code extends enforcement attention toward child-accessible immersive spaces. Platforms must implement default privacy settings and data minimization for under-18 avatar interactions. EdTech providers targeting schools in Scotland and Wales reconfigure consent workflows and parental dashboard visibility to satisfy expanded duties.
Corporate procurement patterns favor outcome-based immersive training contracts over perpetual software licensing. Siemens and Rolls-Royce negotiate performance metrics tied to knowledge retention and incident reduction rather than seat counts. This shift concentrates vendor risk with platform operators while transferring operational accountability from internal L&D departments to external immersive specialists.
UK Metaverse Market Segmentation
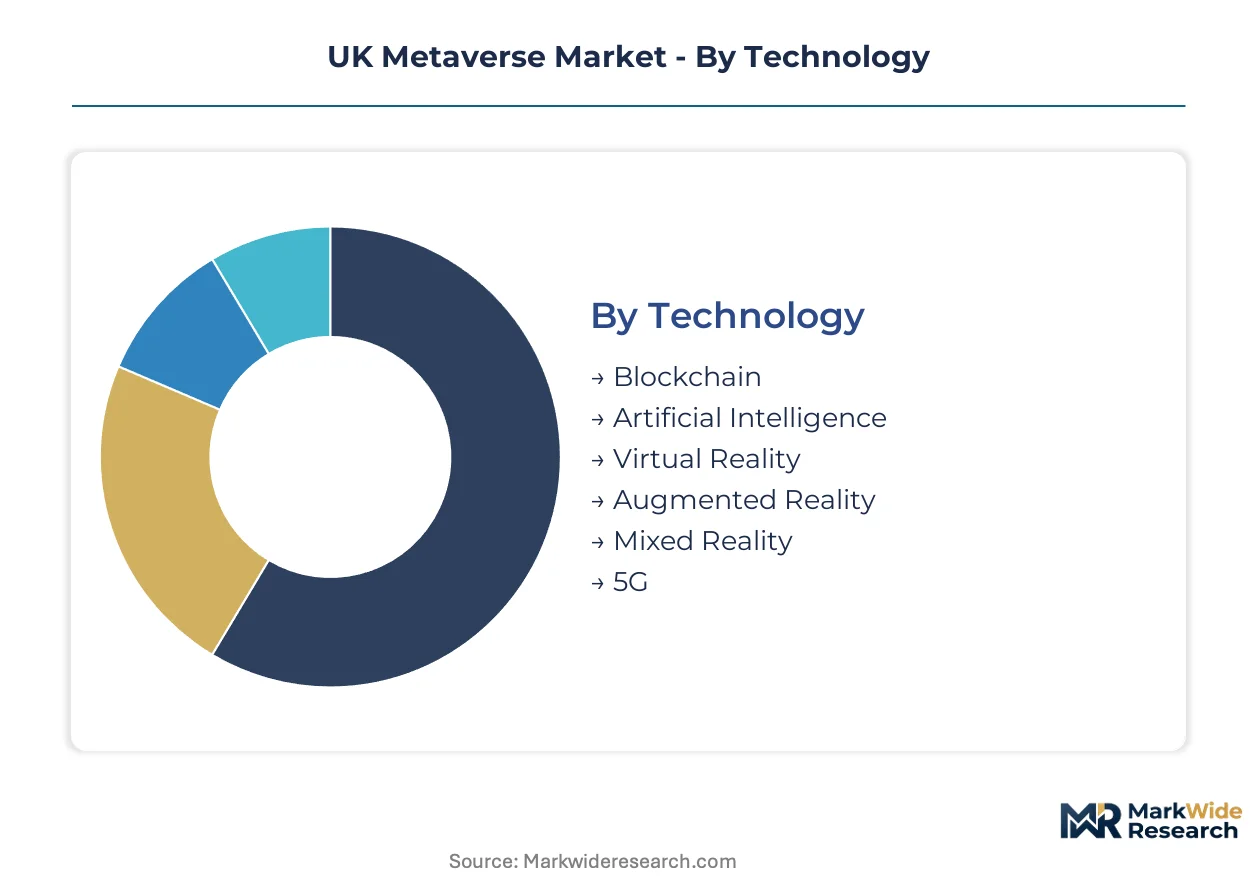
The UK Metaverse Market fragments across four structural dimensions that determine procurement priorities and vendor positioning. Technology investments concentrate where latency requirements and data governance obligations intersect. Application demand diverges between established revenue pools and emerging immersive formats reshaping enterprise workflows.
Technology:
Capital intensity varies sharply across technology layers, with hardware-dependent segments demanding substantial upfront infrastructure commitment.
- Virtual Reality:Headset hardware and motion tracking systems require dedicated GPU clusters and sub-20ms latency architecture. Manufacturing training programs in Birmingham and Manchester drive procurement of enterprise-grade VR suites for hazardous equipment simulation.
- Artificial Intelligence:Generative models compress 3D asset production timelines while raising compute costs for real-time inference. London financial services firms deploy AI-driven avatar systems that satisfy Information Commissioner's Office behavioral tracking restrictions.
- Blockchain:Distributed ledger infrastructure verifies asset ownership and transaction integrity across persistent environments.
- Augmented Reality:Spatial overlay technologies bridge physical and digital workspaces for field service applications.
- Mixed Reality:Passthrough camera arrays and depth sensing enable blended interaction models.
- 5G:Network slicing and edge distribution reduce latency for mobile immersive experiences.
Virtual Reality absorbs the bulk of installed capacity; Artificial Intelligence is expanding most quickly.
Application:
Customer maturity separates established monetization models from experimental deployments still seeking scalable unit economics.
- Online Gaming:Persistent multiplayer worlds generate recurring revenue through virtual goods and subscription access. UK studios in Brighton and Guildford leverage established player bases to test blockchain-integrated economies.
- Digital Commerce:Virtual storefronts and immersive product visualization convert browsing behavior across fashion and furniture verticals. London luxury retailers deploy AR try-on to reduce return rates and extend dwell time.
- Virtual Events:Hybrid conference formats reallocate corporate hospitality budgets toward persistent venue environments.
- Education:Institutional procurement in Scotland and Wales targets STEM visualization and remote laboratory access.
- Social Interaction:Avatar-based communication platforms compete with asynchronous messaging for youth engagement.
- Real Estate:Digital twin visualization accelerates pre-construction sales cycles for commercial developments.
Online Gaming commands the largest revenue base; Virtual Events is climbing the fastest as corporate procurement normalizes hybrid formats.
End User:
Buyer sophistication determines contract structure, with enterprise procurement favoring outcome-based pricing over perpetual licensing.
- eCommerce Platforms:Marketplace operators integrate immersive product visualization to reduce cart abandonment and return processing costs. ASOS and Boohoo deploy AR sizing tools that compress fit-related customer service volume.
- Educational Institutions:Universities and vocational colleges procure simulation environments for healthcare and engineering training. Imperial College London and University of Manchester allocate capital grants toward persistent virtual laboratory infrastructure.
- Content Creators:Independent studios and individual producers populate virtual worlds with 3D assets and interactive experiences.
- Advertisers:Brand marketers test immersive storytelling formats and virtual product placement.
- Real Estate Firms:Developers and brokerages visualize unbuilt properties for pre-sale marketing.
- Entertainment Providers:Broadcasters and streaming services experiment with live immersive content distribution.
eCommerce Platforms dominate current procurement volume; Educational Institutions are gaining share fastest as capital grant programs accelerate.
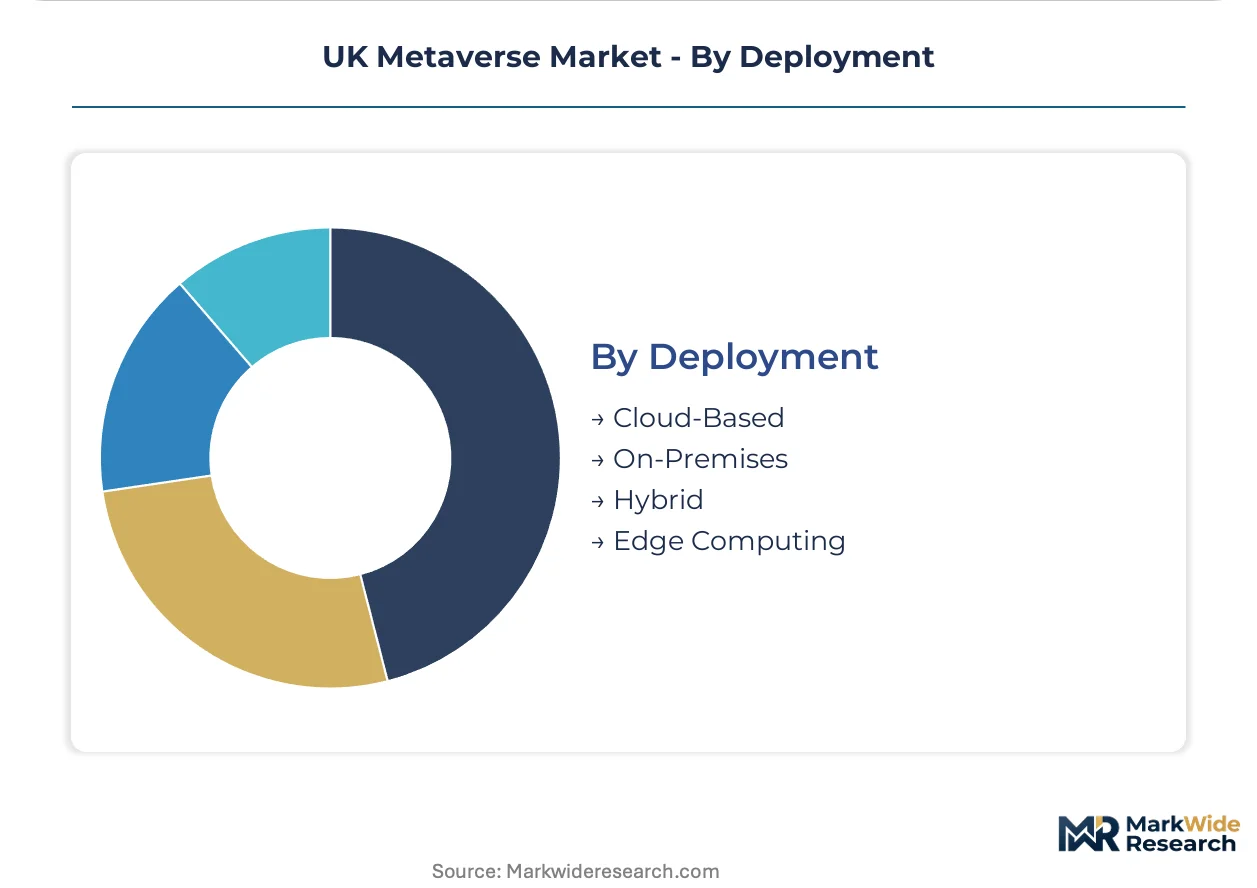
Deployment:
Data sovereignty requirements and latency sensitivity drive architectural choices between centralized and distributed infrastructure.
- Cloud-Based:Scalable compute and storage resources support variable demand patterns without capital commitment. Financial services buyers in London mandate UK-sovereign cloud regions to satisfy data residency obligations under GDPR.
- On-Premises:Dedicated hardware installations preserve full control over biometric data processing and security architecture. Defence contractors and classified research facilities require air-gapped environments for sensitive simulation work.
- Hybrid:Split workloads balance elastic scaling with localized processing for latency-critical functions.
- Edge Computing:Distributed nodes reduce round-trip times for location-based immersive experiences and industrial digital twins.
Cloud-Based deployment holds the majority of new installations; Edge Computing is scaling fastest as 5G infrastructure densifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's financial services and creative technology clusters concentrate UK Metaverse demand through enterprise-grade immersive infrastructure procurement and spatial computing R&D investment.
London and the Southeast
Financial services firms in the City and Canary Wharf deploy AI-driven avatar systems for client engagement and compliance training. The UK Information Commissioner's Office biometric processing guidance shapes platform procurement specifications. Tech clusters in Shoreditch and King's Cross attract spatial computing startups focused on GDPR-compliant design architectures.
The Midlands
Manufacturing hubs in Birmingham and Coventry drive demand for hazardous equipment simulation and digital twin visualization. Regional development funding targets immersive technology adoption for automotive supply chain optimization. The Advanced Manufacturing Research Centre in Sheffield tests persistent virtual environments for production line planning.
North England
Manchester and Leeds manufacturing corridors show accelerating procurement of enterprise VR suites for logistics training and warehouse simulation. The Health and Safety Executive's risk-reduction protocols direct budget toward immersive safety infrastructure. MediaCityUK in Salford hosts broadcasters experimenting with live immersive content distribution.
Scotland
Edinburgh and Glasgow universities procure persistent virtual laboratory infrastructure for healthcare and engineering training. The Scottish Government's capital grant programs accelerate EdTech procurement for STEM visualization. Exhibition organizers in Glasgow test persistent venue environments for recurring trade show series.
Wales
Cardiff-based educational institutions reconfigure consent workflows and parental dashboard visibility to satisfy the Information Commissioner's Office Age-Appropriate Design Code. Welsh Government funding supports immersive technology adoption in vocational colleges. Swansea's creative sector experiments with generative AI pipelines for 3D asset production.
UK Metaverse Market Competitive Landscape
Premium-margin players sit above commodity-margin players across data governance capabilities and rendering fidelity specifications. The vendor base stratifies between social graph-anchored platform operators, GPU-dependent infrastructure providers, and real-time engine specialists. Three archetypes dominate: hardware-software integrated ecosystems, enterprise-focused simulation platforms, and creator-economy content infrastructures. Competitive moves concentrate on strategic partnerships with cloud sovereignty providers and portfolio diversification into privacy-preserving avatar systems.
Within the hardware-software integrated tier, Meta Platforms and NVIDIA Corporation occupy positions defined by social graph density and GPU architecture control respectively. Epic Games exemplifies the real-time engine specialist archetype through Unreal Engine adoption patterns. Microsoft sits within the enterprise productivity integration vector, leveraging existing workplace software relationships. Improbable and Hadean represent UK-based infrastructure specialists focused on distributed simulation architectures.
| Leading Market Players |
|---|
| Meta Platforms |
| Roblox Corporation |
| NVIDIA Corporation |
| Epic Games |
| Microsoft |
| Unity Technologies |
| Improbable |
| Hadean |
| LandVault |
| Others |
Pricing and Supply Chain Analysis
The UK Information Commissioner's Office Age-Appropriate Design Code gates qualified supply for child-accessible immersive platforms and anchors premium-tier pricing for EdTech providers demonstrating verifiable compliance workflows. Platforms lacking certified data governance architectures face procurement exclusion from Scottish and Welsh educational institutions, compressing margins in the standard tier while concentrating pricing power with privacy-preserving specialists.
Pricing Analysis
Outcome-based contracts tied to knowledge retention metrics anchor enterprise immersive training procurement. Three-tier pricing structure across premium, standard, and economy levels separates GDPR-certified platforms with UK-sovereign cloud regions from commodity virtual environment providers. Cost compression in the standard tier is intensifying because substitute collaboration tools retain budget share. Manufacturing buyers in Birmingham and Manchester show highest price sensitivity; London financial services firms prioritize data residency compliance over per-seat economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for enterprise VR suites, while value-added resellers serve mid-market educational institutions. GPU architectures draw from Taiwan and South Korea foundry capacity; headset assembly concentrates in China and Vietnam. Supply chain risk centers on single-source vulnerability for advanced semiconductor lithography. Distribution runs through specialized AV integrators for on-premises deployments and hyperscaler marketplaces for cloud-based immersive infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Metaverse Market has become a vertical-integration race as platform operators pursue backward integration into GPU-dependent rendering infrastructure to secure supply and defend margin position.
For Market Incumbents: Deepen control over spatial computing hardware ecosystems to offset foundry concentration risk. Incumbents should anchor enterprise procurement relationships through UK-sovereign cloud certifications before emerging simulation specialists capture manufacturing training budgets in Northern England industrial corridors. For New Entrants and Emerging Players: Generative AI-assisted 3D asset pipelines offer a technology-first wedge for independent creators lacking traditional studio infrastructure. New entrants should target underpenetrated demand in Manchester and Leeds logistics training centers, positioning through outcome-based pricing that transfers operational accountability from internal L&D departments. For Investors and Strategic Acquirers: Ofcom's forthcoming enforcement framework publication under the Online Safety Bill is the leading indicator that biometric data liability exposure will consolidate vendor risk with capitalized platform operators. Investors should prioritize acquisition targets with demonstrated GDPR-compliant avatar architectures and existing procurement relationships with London financial services buyers.| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-Preserving Avatar Development | Platforms satisfying ICO biometric restrictions secure financial services procurement contracts in London. |
| UK-Sovereign Cloud Certification | Data residency compliance anchors enterprise pricing premiums against commodity virtual environment providers. |
| Generative AI Content Pipeline Integration | AI-assisted 3D asset production reduces creator studio infrastructure requirements for persistent world population. |
| Outcome-Based Training Contract Structuring | Performance metrics tied to incident reduction transfer operational accountability from internal L&D departments. |
| Northern England Geographic Expansion | Regional development funding accelerates immersive technology adoption in Manchester and Leeds manufacturing corridors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across platform engineering directors, immersive training procurement officers at manufacturing firms, EdTech solution architects, and data protection compliance leads. UK Information Commissioner's Office guidance documents, Health and Safety Executive risk-reduction protocols, and Digital Regulation Cooperation Forum coordination frameworks supplied regulatory boundary conditions. Bottom-up segment sizing triangulated against top-down market aggregation.
Data-stream reconciliation across technology adoption curves, enterprise procurement pattern analysis, and hardware shipment tracking informed the projection framework. Segmentation dimensions modeled include technology layer, application vertical, end-user archetype, and deployment architecture across the analysis window. CAGRs derived from fitted growth curves applied to baseline penetration estimates, with spatial computing hardware refresh cycles and generative AI content production cost trajectories serving as primary forecast inputs.
Several conditions sit outside the modeled scope, including potential regulatory acceleration under the Online Safety Bill and unanticipated foundry capacity disruptions for advanced GPU architectures. Forecasts reflect assumptions about sustained enterprise training budget allocation and EdTech capital grant continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Social VR Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Fitting Room Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Construction Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Data Glove Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Collaboration Platform Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
5G and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality Market