
 Saudi Arabia Cardiovascular Devices Market | 2026-2036
Saudi Arabia Cardiovascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Cardiovascular Devices Market Analytics
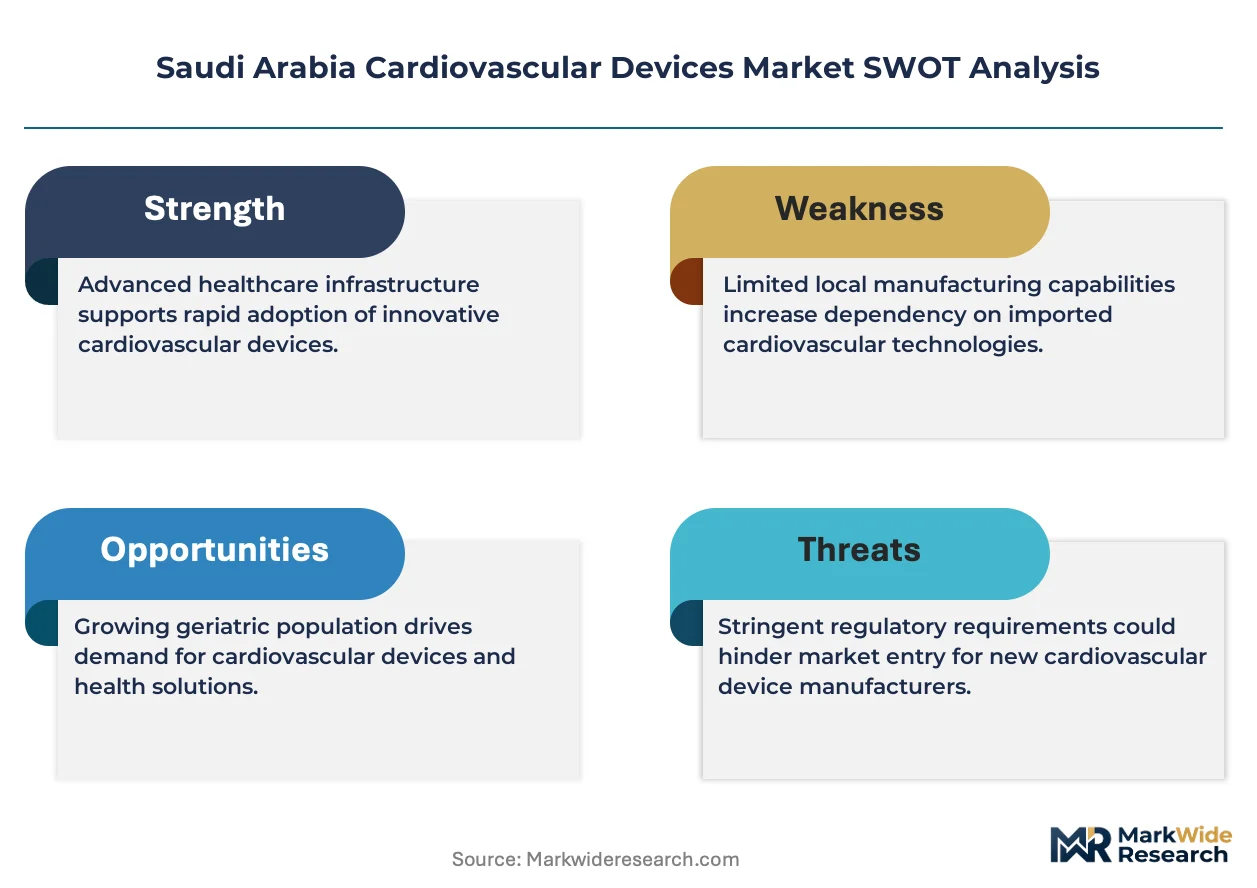
SFDA medical device registration is hardening the cost-of-entry calculus for cardiovascular device suppliers seeking Saudi market access. Medtronic leverages its established regulatory affairs infrastructure to navigate pre-market approval pathways faster than smaller rivals. Abbott Laboratories sustains competitive positioning through deep catheter and stent specialization aligned with local cardiac intervention growth. Siemens Healthineers anchors its presence through integrated imaging-cath lab systems that dominate Saudi hospital procurement tenders.
Cardiovascular devices encompass implantable and interventional instruments engineered from biocompatible alloys, polymers, and drug-eluting coatings to restore or regulate cardiac function, typically requiring ISO 10993 biocompatibility validation and precision manufacturing tolerances below 50 microns. These devices serve to treat structural heart defects, arrhythmias, and occlusive vascular conditions through minimally invasive or surgical implantation procedures. Stents and catheters command the largest revenue share within product categories, reflecting high procedural volumes in coronary artery disease interventions across Saudi Arabia's expanding cardiac center network. Drug-eluting technology platforms capture premium positioning as interventional cardiologists prioritize restenosis reduction, while biodegradable stent research advances toward next-generation regulatory approvals.
SFDA implements medical device marketing authorization tied to ISO 13485 quality management certification, while the Saudi Food and Drug Authority's post-market surveillance mandates adverse event reporting that shapes product liability exposure for manufacturers. The Saudi Standards, Metrology and Quality Organization enforces electromagnetic compatibility and electrical safety testing that adds compliance layers for pacemaker and implantable cardioverter-defibrillator suppliers. Stakeholders must monitor how SFDA's anticipated alignment with EU MDR technical documentation requirements will reshape dossier preparation costs and timeline assumptions for market entry decisions.
Market Dynamics
SFDA's tightening pre-market approval pathways are compressing market entry timelines for cardiovascular device suppliers, while Saudi Vision 2030's hospital privatization agenda concentrates procurement authority within Riyadh's tertiary cardiac center cluster.
Growth Catalysts
- Bioresorbable scaffold technology:Drug-eluting platforms with magnesium-based alloys are gaining traction among interventional cardiologists seeking restenosis reduction without permanent metallic implants.
- Saudi Vision 2030 healthcare privatization:The framework redirects public investment toward specialized cardiac centers, expanding cath lab infrastructure and procedural capacity across the Kingdom.
- SFDA post-market surveillance mandates:Adverse event reporting requirements are elevating quality benchmarks, favoring suppliers with established regulatory affairs infrastructure and ISO 13485 certification.
Market Restraints
- Import dependency for precision components:Biocompatible polymers and drug-eluting coatings rely on concentrated European and North American specialty chemical suppliers, exposing procurement to currency volatility and shipping delays.
- SFDA dossier preparation complexity:Anticipated alignment with EU MDR technical documentation requirements is extending pre-market approval timelines and inflating regulatory consulting expenditures for new entrants.
- Biodegradable stent technical limitations:Current magnesium alloy platforms exhibit insufficient radial strength and premature degradation rates, constraining adoption in complex coronary lesions.
Strategic Opportunities
- Eastern Province cath lab expansion:Dammam and Khobar hospital clusters remain undersupplied relative to Riyadh, creating first-mover positioning for integrated imaging-cath lab system suppliers.
- Remote patient monitoring convergence:Implantable cardioverter-defibrillators paired with cloud-based arrhythmia detection platforms address post-discharge surveillance gaps in Saudi Arabia's dispersed population centers.
- SASO electromagnetic compatibility harmonization:Saudi Standards, Metrology and Quality Organization testing alignment with IEC 60601-1-2 streamlines multi-product portfolio approvals for pacemaker manufacturers.
Industry Challenges
- Interventional cardiologist training bottlenecks:Complex structural heart procedures require specialized fellowship pathways that Saudi medical education institutions have not yet scaled to match device deployment rates.
- Legacy hospital information system integration:Cath lab hemodynamic recording systems face interoperability friction with Saudi Ministry of Health electronic health record platforms, delaying real-time procedural data capture.
- Biocompatibility testing capacity constraints:ISO 10993 cytotoxicity and sensitization studies depend on a limited number of SFDA-recognized laboratories, creating queue delays for novel coating submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Cardiovascular Devices Market |
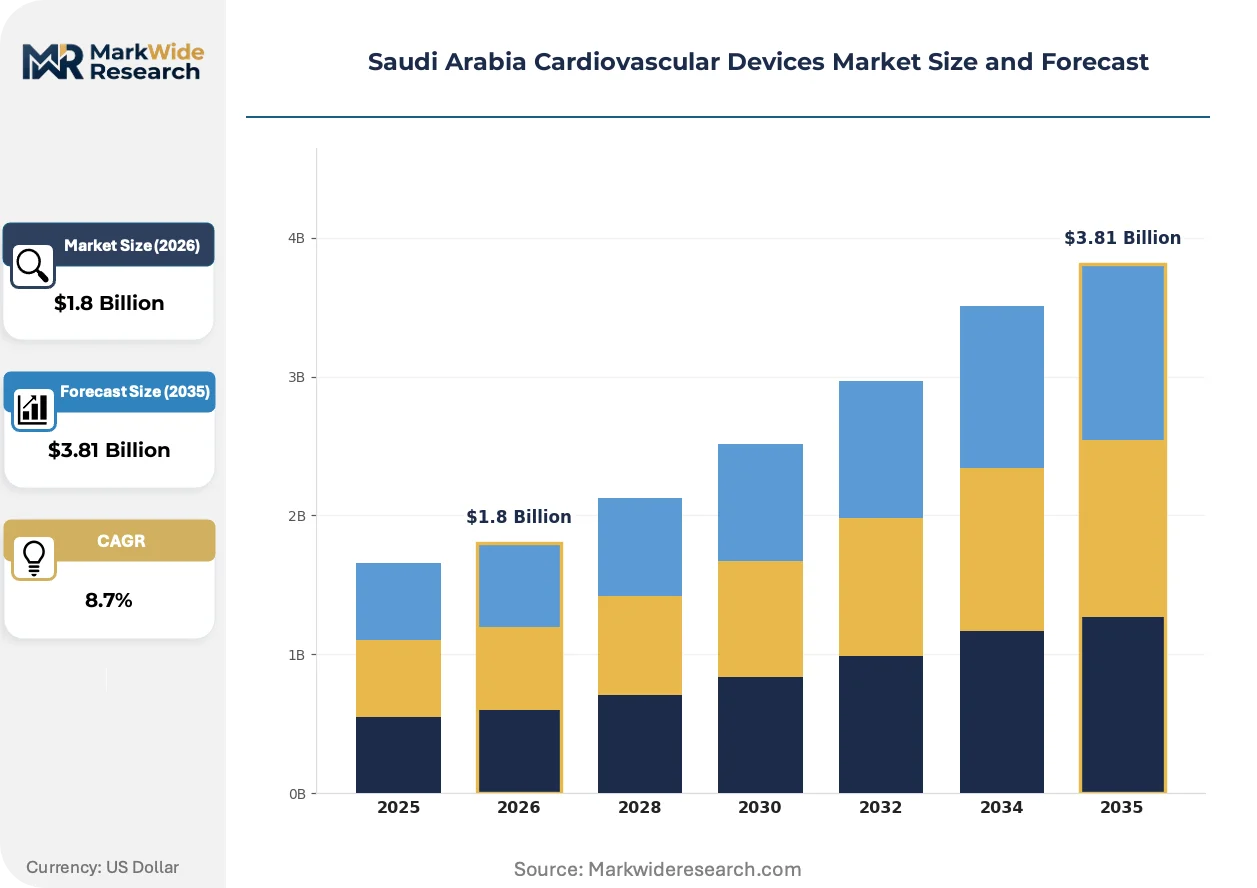
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Pacemakers, Catheters, Valves End User: Hospitals, Cardiac Clinics, Outpatient Centers, Research Institutes Technology: Biodegradable, Drug-Eluting, Bio-Mechanical, Radiofrequency Application: Atrial Fibrillation, Heart Failure, Coronary Artery Disease, Peripheral Vascular Disease |
| Companies Covered | Siemens Healthineers AG, Boston Scientific Corporation, Abbott Laboratories, Cardinal Health Inc., Edwards Lifesciences Corporation, Medtronic, Johnson & Johnson MedTech, LivaNova PLC, GE Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Cardiovascular Devices Market Evolving Landscape
Cardiovascular device innovation in Saudi Arabia is absorbing digital integration pressures and materials science advances that reshape how cardiac interventions are planned, executed, and monitored across the Kingdom's expanding hospital network.
Drug-eluting stent platforms are absorbing next-generation polymer coating technologies designed for controlled sirolimus analogue release. Saudi interventional cardiologists in Riyadh's tertiary centers are adopting these platforms at accelerating rates for diabetic patient cohorts. The technology is absorbing premium positioning within hospital tenders as restenosis reduction becomes a decisive procurement criterion.
SFDA's anticipated technical documentation alignment with EU MDR requirements is compressing dossier preparation standards for implantable cardioverter-defibrillator submissions. Manufacturers must now compile clinical evidence packages that satisfy both Saudi and European notified body expectations simultaneously. Pacemaker suppliers with existing MDR certifications are leveraging this overlap to accelerate SFDA marketing authorization timelines.
Hospital procurement committees are consolidating vendor relationships around single-source integrated cath lab contracts. Imaging system-catheter-stent bundled offerings are displacing discrete equipment purchases in Saudi Arabia's privatizing healthcare sector. This concentration is most visible in Riyadh's King Faisal Specialist Hospital and Research Centre procurement patterns, where Siemens Healthineers and Abbott Laboratories have secured multi-year supply agreements.
Saudi Arabia Cardiovascular Devices Market Segmentation
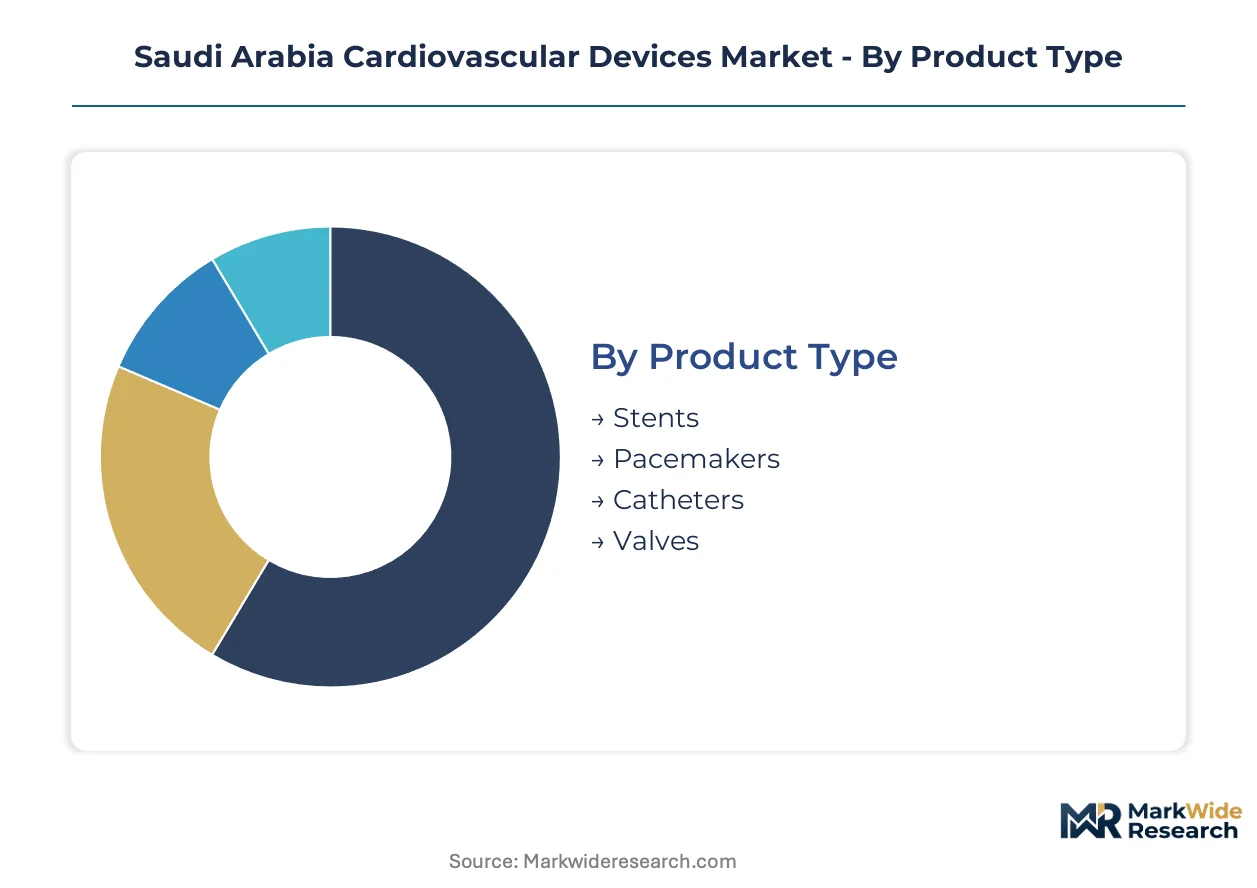
Segmentation in Saudi Arabia's cardiovascular device market reveals how SFDA regulatory pathways, cath lab infrastructure expansion, and interventional procedure specialization concentrate procurement decisions across distinct technology and care delivery categories.
Product Type:
Product specifications determine reimbursement tiers and SFDA approval complexity, with metallic composition and drug-coating chemistry driving hospital tender evaluations.
- Stents:Drug-eluting and bare-metal platforms fabricated from cobalt-chromium or platinum-chromium alloys dominate coronary intervention volumes. Demand concentrates in Riyadh's tertiary cardiac centers where diabetic patient cohorts drive preference for sirolimus-analogue release formulations. Restenosis reduction metrics shape procurement committee scoring.
- Catheters:Diagnostic and interventional catheters engineered from nylon, PEBAX, or polyurethane polymers with hydrophilic coatings enable transradial and transfemoral access approaches. Eastern Province hospital clusters exhibit undersupply relative to procedural growth, creating first-mover positioning for integrated delivery system suppliers.
- Pacemakers:Dual-chamber and leadless implantable pulse generators with lithium-iodine battery chemistry address bradycardia and heart block indications. SFDA electromagnetic compatibility testing adds compliance layers for multi-product portfolio approvals.
- Valves:Transcatheter aortic and mitral replacement systems manufactured from bovine or porcine pericardial tissue mounted on nitinol frames serve structural heart defect corrections. Interventional cardiologist training bottlenecks constrain deployment rates despite expanding eligible patient populations.
Stents lead on scale; catheters lead on momentum.
End User:
Procurement authority concentrates differently across facility types as Saudi Vision 2030 redirects investment toward specialized cardiac infrastructure.
- Hospitals:Tertiary medical centers with catheterization laboratory suites and on-site cardiothoracic surgery backup capture the highest-acuity procedural volumes. King Faisal Specialist Hospital and Research Centre procurement patterns favor multi-year integrated imaging-system contracts.
- Cardiac Clinics:Dedicated interventional cardiology facilities expanding under Vision 2030 privatization drive device procurement for elective percutaneous coronary interventions. These centers prioritize stent and catheter inventory turnover efficiency.
- Outpatient Centers:Ambulatory settings with diagnostic electrophysiology capabilities handle pacemaker follow-up and arrhythmia monitoring. Remote patient monitoring platform integration addresses post-discharge surveillance gaps in dispersed population centers.
- Research Institutes:Academic medical centers conduct bioresorbable scaffold and next-generation drug-eluting coating trials. ISO 10993 biocompatibility testing queue delays affect novel submission timelines for these institutions.
Hospitals anchor procurement volume; cardiac clinics are expanding most quickly.
Technology:
Materials science differentiation creates tiered pricing structures and clinical outcome positioning within SFDA marketing authorization pathways.
- Drug-Eluting:Polymer-based sirolimus, everolimus, or zotarolimus release systems from durable or biodegradable carriers suppress neointimal hyperplasia. Saudi interventional cardiologists prioritize these platforms for diabetic and small-vessel lesion subsets.
- Biodegradable:Magnesium alloy scaffolds with controlled corrosion rates aim to restore vascular function without permanent metallic implants. Current technical limitations in radial strength and premature degradation constrain adoption in complex coronary anatomies.
- Bio-Mechanical:Tissue-engineered and mechanical prosthetic valves with bileaflet or tilting-disc designs address structural heart disease. Durability versus anticoagulation burden trade-offs shape patient selection protocols.
- Radiofrequency:Ablation catheter systems delivering thermal energy for atrial fibrillation substrate modification. Electroanatomic mapping integration determines procedural efficiency and recurrence rates.
Drug-eluting platforms dominate current revenue; biodegradable approaches hold steepest expansion trajectory contingent on technical resolution.
Application:
Disease prevalence and intervention reimbursement rates direct capital allocation across therapeutic areas.
- Coronary Artery Disease:Atherosclerotic plaque burden in native vessels and bypass grafts drives stent and atherectomy device utilization. Riyadh's cath lab density exceeds other provinces, concentrating procedural volumes.
- Atrial Fibrillation:The most common sustained arrhythmia indication propels electrophysiology mapping and ablation system demand. Pulmonary vein isolation procedure growth outpaces trained operator supply.
- Heart Failure:Cardiac resynchronization therapy and ventricular assist device indications expand with aging demographics and diabetes comorbidity burdens. Implantable hemodynamic monitors address hospitalization reduction goals.
- Peripheral Vascular Disease:Lower extremity and renal artery interventions utilize specialized balloon and stent platforms. This segment captures lower reimbursement intensity relative to coronary applications.
Coronary artery disease commands the largest device expenditure; atrial fibrillation interventions are gaining share fastest on ablation technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kingdom's cardiovascular device infrastructure traces its modern lineage to the 1970s oil-boom hospital construction wave, when tertiary cardiac centers first established catheterization capabilities in Riyadh. SFDA regulatory frameworks subsequently matured to govern this specialized equipment category.
Riyadh
King Faisal Specialist Hospital and Research Centre anchors the Kingdom's highest-acuity cardiac procedural volume. SFDA marketing authorization pathways for implantable devices concentrate regulatory expertise in this administrative capital. The Riyadh tertiary hospital cluster now exceeds all other provinces in cath lab density per capita.
Eastern Province
Dammam and Khobar hospital infrastructure remains undersupplied relative to coronary intervention demand growth. Saudi Aramco's healthcare investment programs are expanding cardiac center capacity across this hydrocarbon-producing region. The Eastern Province cluster is absorbing integrated imaging-cath lab system deployments at accelerating rates.
Western Region
Jeddah's commercial hub status attracts medical device distributor headquarters and logistics operations. MOHAP-aligned facilities in Mecca and Medina manage seasonal pilgrimage-related cardiac emergency surges. The Western Region corridor is prioritizing remote patient monitoring platform integration for dispersed population coverage.
NEOM Northwest
The giga-project's healthcare district is commissioning next-generation cardiac centers with AI-augmented diagnostic capabilities. NEOM regulatory sandbox provisions may streamline novel device trial protocols distinct from standard SFDA pathways. This greenfield development is attracting first-mover positioning from integrated system suppliers.
Asir and Southern Regions
Mountainous terrain and lower population density create post-discharge surveillance gaps for implantable device patients. Telemedicine infrastructure investments under Vision 2030 are extending cardiac specialist reach into these historically underserved provinces. The Southern Region cluster is adopting cloud-based arrhythmia detection platforms to bridge geographic barriers.
Saudi Arabia Cardiovascular Devices Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with established regulatory affairs infrastructure. Market access consolidation favors suppliers possessing ISO 13485 certification and existing EU MDR dossiers that accelerate SFDA parallel submissions. Two strategic archetypes dominate: integrated imaging-intervention system providers and specialized interventional device manufacturers. Dominant competitive moves include multi-year hospital supply agreement consolidation and cath lab infrastructure partnership arrangements with privatizing healthcare entities.
Among diversified health technology conglomerates, Siemens Healthineers AG and GE Healthcare exemplify the integrated-system archetype through bundled imaging-catheterization platform offerings. Medtronic and Abbott Laboratories occupy positions within the specialized interventional device tier, with the former representing established regulatory navigation capabilities and the latter exemplifying deep catheter and stent specialization. Boston Scientific Corporation sits within the structural heart and electrophysiology specialist category. These named entities serve as anchors for understanding how scale, specialization, and regulatory readiness stratify competitive positioning across Saudi Arabia's privatizing cardiac center procurement landscape.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Cardinal Health Inc. |
| Edwards Lifesciences Corporation |
| Medtronic |
| Johnson & Johnson MedTech |
| LivaNova PLC |
| GE Healthcare |
| Others |
Value Network & Pricing Analysis
Specialized interventional cardiologist density in Riyadh's tertiary center cluster creates labor-cost differentials that widen pricing-tier spreads between premium drug-eluting platforms and standard bare-metal alternatives across Saudi Arabia's cardiovascular device procurement landscape.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Saudi hospital procurement tenders, with SFDA certification grade and cath lab integration complexity serving as primary price differentiation drivers. Cost compression in economy-tier bare-metal stent categories is intensifying because Eastern Province distributors compete for volume share against established Riyadh suppliers. Academic medical centers exhibit lowest price sensitivity due to research trial budgets, while privatizing cardiac clinics under Vision 2030 face tightest procurement constraints.
Supply Chain Analysis
Single-source vulnerability sits with cobalt-chromium alloy suppliers concentrated in Germany and the United States, exposing Saudi device manufacturers to tariff exposure from transatlantic trade friction. Biocompatible polymer coatings and drug-eluting chemical precursors draw from Swiss and Japanese specialty chemical producers, with logistics chokepoints at Rotterdam and Singapore transshipment hubs. Distribution runs through Jeddah-based medical device distributors holding SFDA import licenses, with secondary routing to Riyadh and Dammam hospital clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's cardiovascular device market functions as a regulatory compounder where SFDA's anticipated EU MDR alignment is accelerating pre-market approval investments and consolidating procurement authority among certified suppliers.
For Market Incumbents: Anticipate biodegradable scaffold technical limitations eroding metallic stent margins by diversifying into remote patient monitoring platform bundles that pair implantable devices with cloud-based arrhythmia detection. Secure multi-year integrated cath lab contracts with King Faisal Specialist Hospital and Research Centre before Eastern Province infrastructure expansion completes. Certification investment in ISO 13485 quality management systems remains essential for defending position against emerging entrants lacking established regulatory affairs infrastructure. For New Entrants and Emerging Players: Distributor partnerships with Jeddah-based medical device logistics specialists offer the most penetrable channel for bypassing incumbent-held Riyadh procurement committees. Target Eastern Province cath lab expansion in Dammam and Khobar hospital clusters where undersupply relative to procedural growth creates first-mover positioning for integrated imaging-catheter delivery systems. Pursue go-to-market angles emphasizing SASO electromagnetic compatibility pre-certification to accelerate multi-product portfolio approvals. For Investors and Strategic Acquirers: Diversified health technology conglomerates with existing EU MDR dossiers are the most active acquirer in this space, seeking bolt-on interventional device specialists to leverage SFDA parallel submission pathways. Acquisition target archetypes include ISO 13485-certified catheter manufacturers with established Saudi distributor relationships and biodegradable scaffold research pipelines. Watch for SFDA post-market surveillance mandate enforcement intensity as the inflection indicator signaling regulatory barrier height and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Marketing Authorization Acceleration | Pre-built EU MDR dossiers compress pre-market approval timelines against rival submissions. |
| Integrated Cath Lab System Partnerships | Bundled imaging-catheter-stent offerings displace discrete equipment purchases in privatizing hospitals. |
| Eastern Province Infrastructure Positioning | First-mover integrated system deployments capture Dammam and Khobar hospital expansion demand. |
| Remote Patient Monitoring Platform Development | Cloud-based arrhythmia detection addresses post-discharge surveillance gaps in dispersed Southern Region populations. |
| Bioresorbable Scaffold R&D Investment | Magnesium alloy technical resolution unlocks next-generation regulatory approvals and premium positioning. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against SFDA marketing authorization databases, hospital procurement tender records, and SASO electromagnetic compatibility testing registries. Bottom-up device shipment estimates triangulated against top-down healthcare expenditure allocations across the analysis window.
Comparable-period anchoring tied projection assumptions to historical cath lab infrastructure deployment rates and interventional procedure volume trajectories. Segmentation modeling spanned product type, end-user facility category, materials technology platform, and therapeutic application area. CAGRs derived from fitted growth curves incorporating SFDA regulatory timeline assumptions, Vision 2030 healthcare privatization spending schedules, and interventional cardiologist workforce expansion projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biodegradable scaffold technical resolution timelines and SFDA-EU MDR alignment implementation pace. Forecasts reflect documented assumptions regarding cath lab density expansion rates and import dependency patterns for precision components. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiac Surgery Devices Market
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
North America Interventional Cardiology and Peripheral Vascular Devices Market
Cardiovascular Devices
Germany Cardiovascular Devices Market
Cardiovascular Devices
Ventricular Fibrillation Treatment Market
Cardiovascular Devices
Global Intravascular Catheters Market
Cardiovascular Devices
Thoracic Vascular Stent Grafts Market
Cardiovascular Devices
Vascular Snare Market
Cardiovascular Devices
Italy Cardiovascular Devices Market
Cardiovascular Devices
Venous Reservoirs Market
Cardiovascular Devices
MRI-Guided Cardiac Ablation Market
Cardiovascular Devices
Single-Use Hemoperfusion Device Market
Cardiovascular Devices
Peripheral Vascular Devices Market
Cardiovascular Devices
Interventional Cardiology Market
Cardiovascular Devices
Vascular Access Systems Market
Cardiovascular Devices
Human Non-Invasive Blood Pressure (NIBP) Recording System Market