
 Biguanides Market | 2026-2036
Biguanides Market Size, Share, and Industry Trends Forecast 2026-2036
Biguanides Market Outlook
Pharmaceutical-grade biguanide certification is rotating toward extended-release and bioequivalence-validated formulations. Teva Pharmaceutical Industries Ltd leverages its vertically integrated API-to-tablet infrastructure to sustain cost leadership in regulated markets. Cipla Limited anchors its position through deep manufacturing scale in India, while Merck & Co. differentiates via original formulation heritage and brand strength in diabetes care.
Biguanides comprise a class of oral hypoglycemic agents centered on the guanide structural core, with metformin hydrochloride representing the predominant active moiety used in immediate-release and extended-release matrices for glycemic control. Metformin formulations command the largest revenue pool within the product type dimension, while extended-release tablets capture disproportionate margin as patients and payers prioritize adherence and tolerability. Diabetes management remains the dominant therapy area, though polycystic ovary syndrome applications represent a faster-growing prescriptive segment where off-label protocols are formalizing.
FDA bioequivalence standards and EMA pharmacovigilance frameworks govern market access for generic biguanide entrants, with India's CDSCO aligning its dissolution testing protocols to accelerate export approvals. The EU F-Gas Regulation and REACH chemical stewardship requirements indirectly shape API manufacturing location decisions for European supply. Stakeholders must monitor how pharmacovigilance data accumulation around metformin safety profiles influences prescriber confidence and payer reimbursement thresholds across major regulated markets.
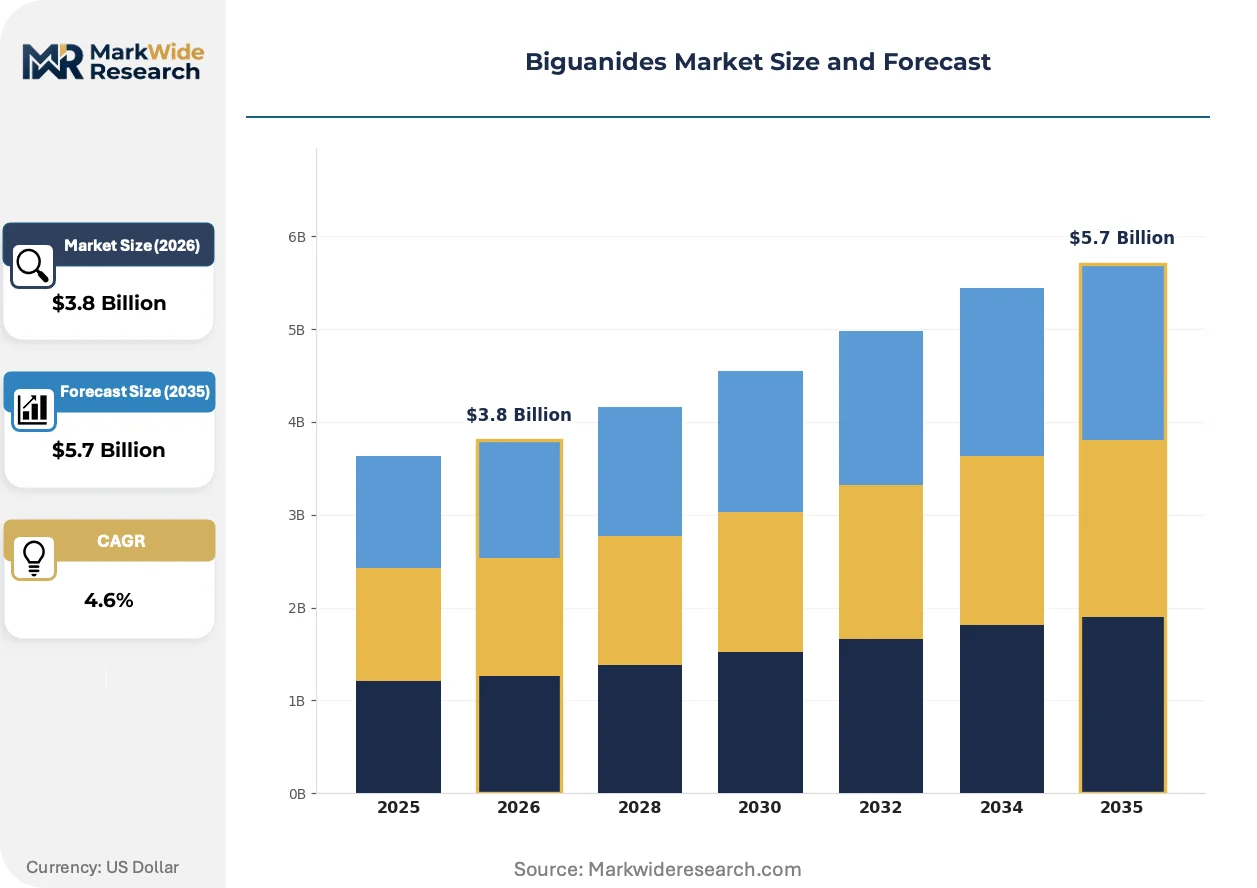
Market Dynamics
FDA bioequivalence standards and EMA pharmacovigilance requirements are compressing formulation development cycles while generic substitution policies in India, Germany, and the United States accelerate volume uptake of extended-release metformin matrices.
Growth Catalysts
- Extended-release formulation adoption:Patients and payers prioritize adherence and tolerability, driving prescriber preference toward modified-release matrices over immediate-release alternatives in diabetes management protocols.
- EMA pharmacovigilance frameworks:Accumulating safety data around metformin profiles reinforces prescriber confidence and stabilizes reimbursement thresholds across European regulated markets.
- India's CDSCO dissolution alignment:Export-oriented manufacturers accelerate approvals for European and North American supply through harmonized testing protocols, expanding API-to-tablet infrastructure scale.
Market Restraints
- API manufacturing location constraints:EU F-Gas Regulation and REACH chemical stewardship requirements indirectly restrict European supply chain configuration decisions for biguanide active pharmaceutical ingredients.
- Generic price compression:Volume substitution policies in Germany and the United States erode margin pools for originator formulations despite sustained prescription dominance of metformin hydrochloride.
- Polycystic ovary syndrome protocol formalization lag:Off-label prescriptive expansion for PCOS applications proceeds slower than diabetes management due to incomplete clinical guideline consensus across major markets.
Strategic Opportunities
- Homecare setting expansion:Chronic disease management decentralization creates channel white space for direct-to-patient distribution models and adherence-monitoring technologies in the United States and Germany.
- Bioequivalence-validated formulation premiumization:Certification differentiation enables pricing stratification between validated extended-release matrices and commodity immediate-release alternatives.
- Indian manufacturing scale leverage:Deep captive production of metformin API positions domestic champions for contract manufacturing expansion into regulated European and North American markets.
Industry Challenges
- Pharmacovigilance data management complexity:Post-market surveillance requirements under EMA and FDA frameworks demand specialized regulatory affairs talent and information technology infrastructure for signal detection.
- Formulation development timeline compression:Accelerated bioequivalence study execution requires capital-intensive clinical research organization partnerships and bioanalytical laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biguanides Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metformin, Phenformin, Buformin, Others Therapy Area: Diabetes Management, Weight Loss, Polycystic Ovary Syndrome, Cardiovascular Health Formulation: Tablets, Extended-Release Tablets, Liquid Solution, Powder End User: Hospitals, Clinics, Homecare, Research Laboratories |
| Companies Covered | Cipla Limited, Aurobindo Pharma Limited, Teva Pharmaceutical Industries Ltd, Cadila Healthcare Limited, Dr. Reddy's Laboratories Limited, Sandoz AG, Lupin Limited, Merck & Co., Sun Pharmaceutical Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biguanides Market Strategic Shifts
Formulation science and regulatory science are converging to reshape competitive positioning in biguanide supply, with extended-release matrix engineering and pharmacovigilance data infrastructure emerging as distinct capability axes.
Modified-release polymer matrix technology is decomposing the traditional immediate-release metformin market by enabling once-daily dosing protocols that improve gastrointestinal tolerability profiles. Hospital systems and integrated delivery networks in the United States are standardizing on extended-release formularies, compressing procurement volumes for conventional tablets while expanding margin capture for validated formulations.
EMA's evolving pharmacovigilance framework is mandating real-world evidence collection and periodic safety update reporting that extends post-approval compliance obligations for generic entrants. European manufacturers are investing in pharmacovigilance system master file infrastructure to satisfy these requirements, with the greatest operational impact falling on mid-scale generic houses lacking legacy regulatory affairs depth.
Prescriber preference is consolidating around bioequivalence-validated extended-release options as primary care physicians and endocrinologists prioritize patient adherence metrics in value-based reimbursement environments. This behavioral shift is most visible in German and United States markets where payer quality indicators directly tie to glycemic control outcomes, displacing undifferentiated generic substitution patterns that dominated prior procurement cycles.
Biguanides Market Segmentation
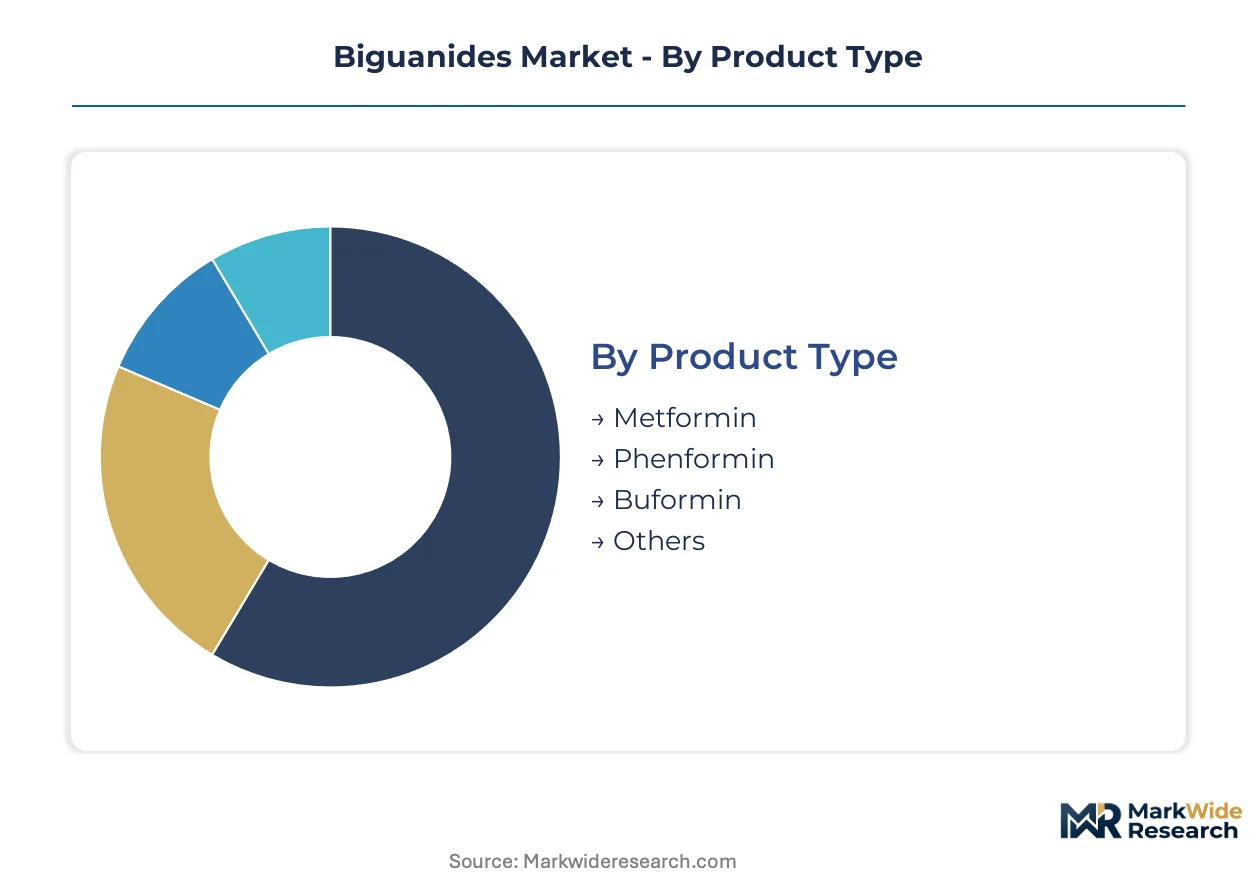
Biguanide segmentation reveals how formulation choices, prescriber settings, and therapeutic applications channel revenue toward distinct margin profiles. Channel economics and reimbursement pathways vary sharply across these dimensions, reshaping where manufacturers concentrate development resources.
Product Type:
Hospital formularies and retail pharmacy channels diverge sharply in which biguanide moieties they stock, with procurement contracts favoring specific molecular profiles based on safety databases and prescriber familiarity.
- Metformin:The guanide derivative metformin hydrochloride dominates active pharmaceutical ingredient consumption across immediate-release and extended-release matrices. United States integrated delivery networks and Indian government procurement programs concentrate volume here, driven by decades of cardiovascular outcome data and generic substitution policies that entrench first-line Type 2 diabetes protocols.
- Phenformin:Withdrawn from most regulated markets due to lactic acidosis risk profiles, this biguanide retains niche availability in select emerging markets where cost constraints override safety signal concerns. Demand concentrates in legacy hospital systems with limited formulary refresh cycles.
- Buformin:Primarily manufactured for supply to Japan and select East Asian markets where historical prescribing patterns sustain limited commercial volumes. Regulatory divergence has isolated this moiety from Western pharmacovigilance frameworks.
- Others:Includes investigational biguanides and regional heritage compounds with minimal current commercial footprint. Research laboratories represent the primary offtake channel for these moieties.
Metformin dominates installed base. Extended-release metformin matrices are where expansion concentrates.
Therapy Area:
Cost tier stratification separates acute hospital-administered protocols from chronic outpatient management, with reimbursement intensity varying across these clinical contexts.
- Diabetes Management:Glycemic control applications anchor prescriptive volume for biguanide therapy, spanning Type 2 diabetes monotherapy and combination regimens. German disease management programs and United States Medicare Part D formularies drive sustained demand, with value-based reimbursement models prioritizing HbA1c outcome metrics that favor adherent extended-release formulations.
- Polycystic Ovary Syndrome:Off-label insulin-sensitizing protocols for PCOS represent the steepest expansion trajectory as endocrinology societies formalize practice guidelines. United States reproductive endocrinology clinics and Indian gynecology practices are where this application is gaining prescriptive traction fastest.
- Weight Loss:Emerging prescriptive patterns for metabolic syndrome and pre-diabetic populations leverage metformin's modest weight-neutral to weight-reducing effects. Bariatric surgery pre-operative protocols in German and United States hospital systems constitute the primary channel.
- Cardiovascular Health:Secondary prevention applications exploit metformin's pleiotropic effects on endothelial function and inflammation markers. Cardiology practices in Japan and research-oriented United States academic medical centers concentrate exploratory prescribing here.
Diabetes management commands the revenue base. Polycystic ovary syndrome protocols are where prescriptive expansion concentrates.
Formulation:
Volume scale and margin capture diverge across delivery technologies, with manufacturing complexity creating distinct competitive moats.
- Extended-Release Tablets:Hydrophilic polymer matrix systems enable once-daily dosing that improves gastrointestinal tolerability and adherence metrics. United States pharmacy benefit managers and German sickness funds prioritize these formulations in tiered formularies, creating pricing power for bioequivalence-validated suppliers.
- Tablets:Immediate-release compressed tablets remain the volume workhorse for cost-sensitive procurement channels, particularly Indian government tenders and United States 340B discount programs. Manufacturing scale and API sourcing efficiency determine competitive position.
- Liquid Solution:Pediatric and geriatric populations with swallowing difficulties drive limited demand for oral solutions. Hospital pediatric wards and long-term care facilities in Germany constitute the primary channel.
- Powder:Compounding pharmacy and clinical trial supply applications sustain minimal commercial volumes for bulk powder formats. Research laboratories and specialized pharmacy compounders represent the offtake base.
Immediate-release tablets dominate installed base. Extended-release matrices are where margin expansion concentrates.
End User:
Customer type dictates regulatory burden and channel economics, with each setting imposing distinct compliance and logistics requirements.
- Homecare:Chronic disease management decentralization shifts biguanide consumption toward mail-order pharmacy and direct-to-patient distribution. United States Medicare Advantage plans and German integrated care contracts prioritize adherence-monitoring technologies in this channel.
- Hospitals:Inpatient glycemic control protocols and formulary standardization drive concentrated procurement volumes. United States health systems and Indian multi-specialty hospital chains leverage group purchasing organization contracts to compress acquisition costs.
- Clinics:Outpatient endocrinology and primary care practices generate recurring prescription volumes with lower logistics complexity than hospital supply. German physician networks and United States accountable care organizations concentrate purchasing here.
- Research Laboratories:Preclinical and clinical trial supply for biguanide mechanism studies and novel formulation development sustains specialized demand. Academic medical centers and contract research organizations in the United States and Germany constitute the primary offtake.
Hospitals dominate procurement volume. Homecare settings are where channel expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biguanide API manufacturing concentrates in India and China for export supply, while formulation demand clusters in the United States, Germany, and Japan where generic substitution policies and reimbursement frameworks dictate procurement economics. Trade flows reflect this bifurcation: bulk active pharmaceutical ingredients move east-to-west, while finished dosage forms circulate within regulated markets governed by FDA, EMA, and PMDA standards.
United States
Medicare Part D formularies and integrated delivery network procurement contracts drive extended-release metformin volume. FDA bioequivalence standards compress development timelines for generic entrants. New Jersey and North Carolina host major formulation packaging operations serving nationwide distribution.
Germany
Sickness fund reimbursement protocols prioritize HbA1c outcome metrics that favor adherent extended-release formulations. EMA pharmacovigilance frameworks mandate real-world evidence collection post-approval. The Rhine-Ruhr pharmaceutical corridor anchors European distribution logistics for biguanide supply.
India
CDSCO dissolution testing alignment with European and North American standards accelerates export approvals for API-to-tablet manufacturers. Government tender programs for essential medicines sustain immediate-release volume. Gujarat and Maharashtra concentrate captive metformin API production at industrial scale.
Japan
PMDA quality standards sustain demand for buformin distinct from Western metformin-dominant protocols. Aging demographics expand chronic disease management requirements. The Kansai region maintains heritage manufacturing infrastructure for domestic biguanide supply.
United Kingdom
NHS England prescribing guidelines formalize metformin first-line positioning in Type 2 diabetes protocols. MHRA post-Brexit regulatory alignment with EMA frameworks continues pharmacovigilance data sharing. The Southeast England pharmaceutical cluster manages regulatory submissions for European market access.
Biguanides Market Competitive Environment
Listed leaders compete with private specialists across formulation development and API manufacturing dimensions. The vendor base stratifies into three tiers: multinational generics houses with vertically integrated infrastructure, mid-scale regional manufacturers leveraging cost position, and originator heritage brands sustaining prescriber loyalty. Three archetypes dominate competitive positioning: FDA-validated formulation specialists, Indian-scale API producers, and European pharmacovigilance-compliant suppliers. Consolidation pressure manifests through strategic partnerships for bioanalytical capacity and geographic licensing arrangements for market access.
Among Indian-origin manufacturers, Cipla Limited and Dr. Reddy's Laboratories Limited exemplify the scale-driven archetype with deep captive API production and export-oriented regulatory dossier capabilities. Teva Pharmaceutical Industries Ltd represents the vertically integrated multinational model, spanning Israeli API sourcing through North American and European formulation distribution. Merck & Co. occupies the originator heritage position, leveraging decades of clinical outcome data and prescriber familiarity to sustain brand preference despite generic substitution policies.
| Leading Market Players |
|---|
| Cipla Limited |
| Aurobindo Pharma Limited |
| Teva Pharmaceutical Industries Ltd |
| Cadila Healthcare Limited |
| Dr. Reddy's Laboratories Limited |
| Sandoz AG |
| Lupin Limited |
| Merck & Co. |
| Sun Pharmaceutical Industries Ltd |
| Others |
Value Chain & Pricing Dynamics
API manufacturing scale in Gujarat and Maharashtra anchors competitive positioning across the biguanides market, with captive metformin production capacity determining which suppliers can sustain price floors against generic substitution policies in the United States and Germany. Volume concentration among Indian-origin manufacturers creates tiered margin structures that separate bioequivalence-validated extended-release formulations from commodity immediate-release tablets.
Pricing Analysis
Hospital procurement managers and pharmacy benefit managers anchor pricing stratification across premium, standard, and economy tiers in the biguanides market. Certification grade under FDA bioequivalence standards and EMA pharmacovigilance compliance separates validated extended-release matrices from undifferentiated generics. Cost compression in immediate-release segments is intensifying because Indian government tenders and United States 340B programs prioritize lowest-unit-cost procurement. Retail pharmacy chains exhibit highest price sensitivity, while integrated delivery networks accepting value-based reimbursement demonstrate lowest sensitivity due to adherence-metric incentives.
Supply Chain Analysis
Port congestion at Mumbai and Nhava Sheva container terminals intermittently disrupts API export schedules from Indian manufacturing clusters to European and North American formulation facilities. Active pharmaceutical ingredient production concentrates in India and China, with secondary formulation packaging capacity in the United States and Germany. Biguanide supply chains draw from guanidine chemical feedstocks, hydrochloride salt precursors, and hydrophilic polymer matrix materials. Single-source vulnerability around Indian API manufacturing creates structural exposure to CDSCO export approval delays. Distribution runs through pharmaceutical wholesalers and direct hospital system contracts in regulated markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized pharmacovigilance infrastructure and bioanalytical laboratory capacity represent scarce capabilities that separate viable generic entrants from stranded mid-scale manufacturers lacking regulatory affairs depth.
For Market Incumbents: Secure pharmacovigilance system master file infrastructure to satisfy EMA periodic safety update reporting obligations, insulating against compliance-driven market exit by undercapitalized competitors. Anchor backward integration into metformin API production to defend margin position against Indian-scale manufacturers expanding into regulated European and North American markets. For New Entrants and Emerging Players: Lead with bioequivalence-validated extended-release formulation development targeting United States Medicare Advantage and German sickness fund tiered formularies where adherence metrics command pricing premiums. Homecare direct-to-patient distribution channels represent the most penetrable white space, with adherence-monitoring technology bundling as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated API-to-tablet manufacturers with established FDA and EMA regulatory dossiers. Long-term viability across the analysis window favors acquisition targets possessing captive Indian manufacturing scale combined with European pharmacovigilance compliance infrastructure. Monitor CDSCO dissolution testing protocol harmonization announcements as the critical signal for export approval acceleration and capacity utilization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacovigilance System Master File Investment | EMA compliance infrastructure enables sustained European market access for generic biguanide entrants. |
| Extended-Release Matrix Technology Licensing | Hydrophilic polymer formulations command formulary preference in United States integrated delivery networks. |
| Backward Integration into API Manufacturing | Captive metformin production insulates margin structures from Indian export price volatility. |
| Homecare Distribution Channel Expansion | Direct-to-patient models capture chronic disease management decentralization in Medicare Advantage plans. |
| CDSCO Regulatory Dossier Harmonization | Aligned dissolution testing protocols accelerate export approvals for European and North American supply. |
Study Parameters
Desk research of FDA bioequivalence study databases, EMA pharmacovigilance assessment reports, and Indian CDSCO export approval records preceded structured interviews with regulatory affairs directors at generic pharmaceutical manufacturers, formulary managers at United States integrated delivery networks, and procurement leads at German sickness funds. Primary fieldwork combined with secondary validation against clinical trial registries, pharmaceutical customs data, and hospital procurement databases. Bottom-up prescription volume modeling and top-down API production capacity estimates were triangulated to derive market sizing.
Variance decomposition across product type, therapy area, formulation technology, and end-user setting dimensions shaped the analytical framework throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic healthcare expenditure trends. Forecast inputs incorporated EMA pharmacovigilance framework evolution, FDA bioequivalence standard updates, and Indian CDSCO regulatory alignment progress.
Forecasts assume regulatory continuity in FDA, EMA, and CDSCO regimes; material policy shifts around bioequivalence criteria or pharmacovigilance reporting obligations would require re-modeling. Specific risk factors include REACH chemical stewardship expansion restricting API manufacturing location choices and generic substitution policy reversals in Germany or the United States. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Steroid-Free Nasal Sprays Market
Pharmaceuticals
US Generic Injectables Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Renal Drugs Market
Pharmaceuticals
Intelligent Pills Market
Pharmaceuticals
Repurposed Human Immunosuppressants Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
India Opioids Market
Pharmaceuticals
Varicella Attenuated Live Vaccination Market
Pharmaceuticals
HIV Antivirals Market
Pharmaceuticals
Extended Oral Antibiotics Market
Pharmaceuticals
Metoprolol Tartrate Market
Pharmaceuticals
Teriflunomide Market
Pharmaceuticals
Saudi Arabia Diabetes Drugs Market
Pharmaceuticals
Metformin HCL Drugs Market
Pharmaceuticals
Lipid Injectable Market
Pharmaceuticals
Anticholinergic Drugs Market