
 Drug Allergy Market | 2026-2036
Drug Allergy Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Allergy Market Analysis
Biologics is rebalancing therapeutic economics in drug allergy management as monoclonal antibodies displace corticosteroids in severe hypersensitivity protocols. Novartis leverages its immunology pipeline to sustain leadership in targeted cytokine inhibition for allergic reactions. Thermo Fisher Scientific anchors the diagnostic layer through its specialized assay platforms for IgE-mediated sensitization testing. Sanofi competes across both pharmaceutical and consumer health channels with differentiated antihistamine positioning.
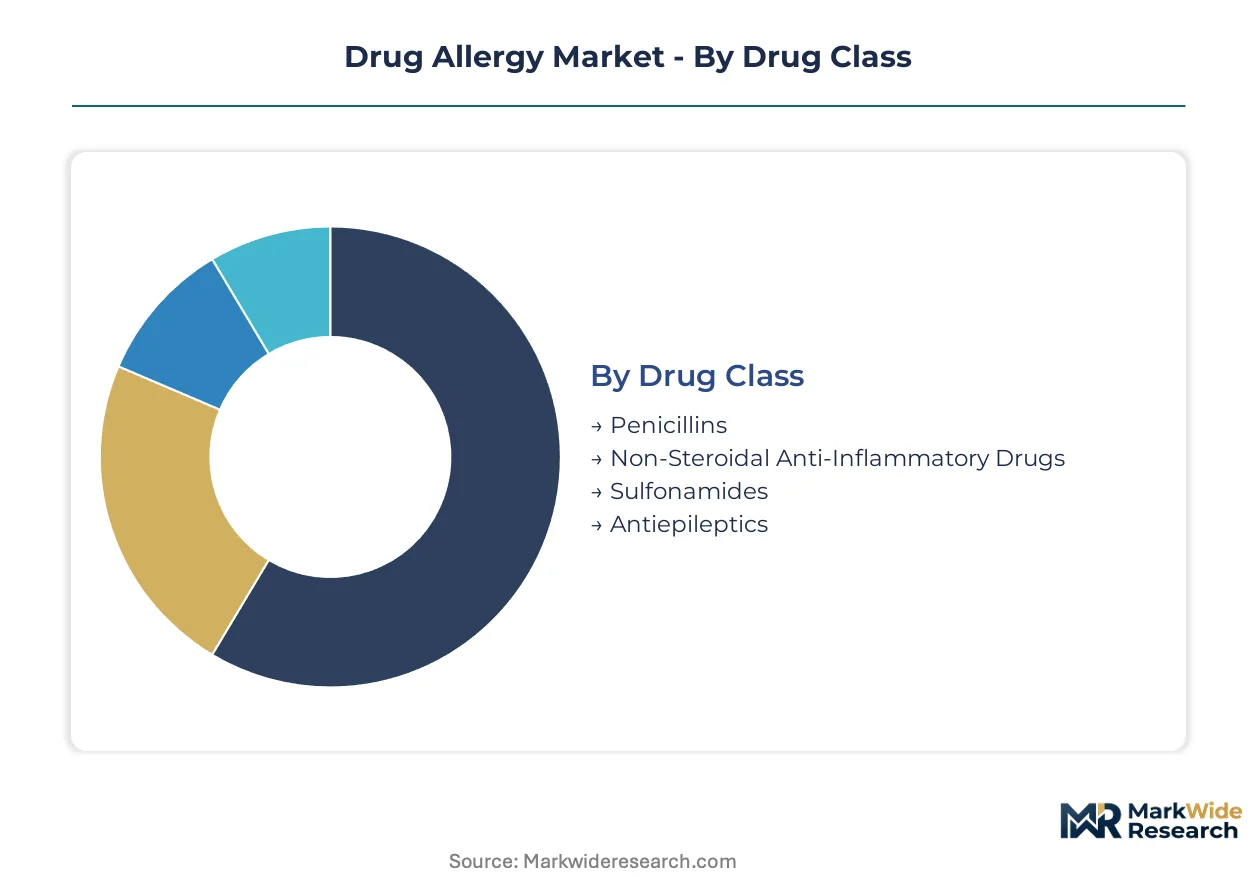
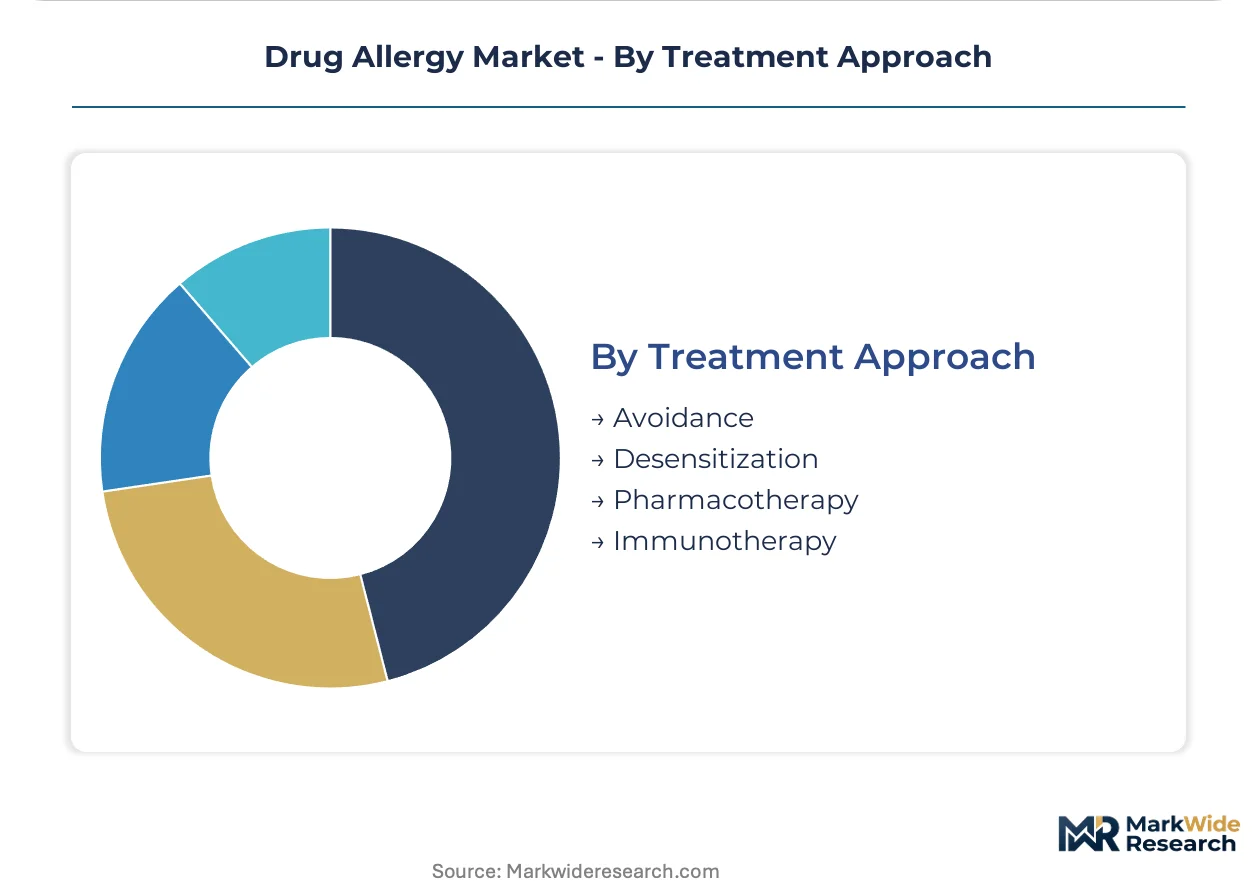
Drug allergy encompasses immunologically mediated adverse reactions to pharmacologically active compounds, classified by mechanism into IgE-dependent immediate hypersensitivity, T-cell-mediated delayed reactions, and immune complex or cytokine-driven responses, with diagnostic confirmation typically requiring skin prick testing, intradermal challenge, or serum-specific IgE quantification against drug-protein conjugates. The primary commercial purpose spans risk stratification prior to drug administration, avoidance protocol design, and guided desensitization for essential therapeutics where alternatives are clinically inferior. Penicillins generates the deepest revenue pool among drug classes due to high prescription volume and substantial over-diagnosis driving confirmatory testing demand, while immunotherapy represents the fastest-expanding treatment approach as allergen-specific protocols advance from research into clinical practice. Severity level segmentation concentrates margin in life-threatening indications where hospital-based intervention and intensive monitoring command premium reimbursement.
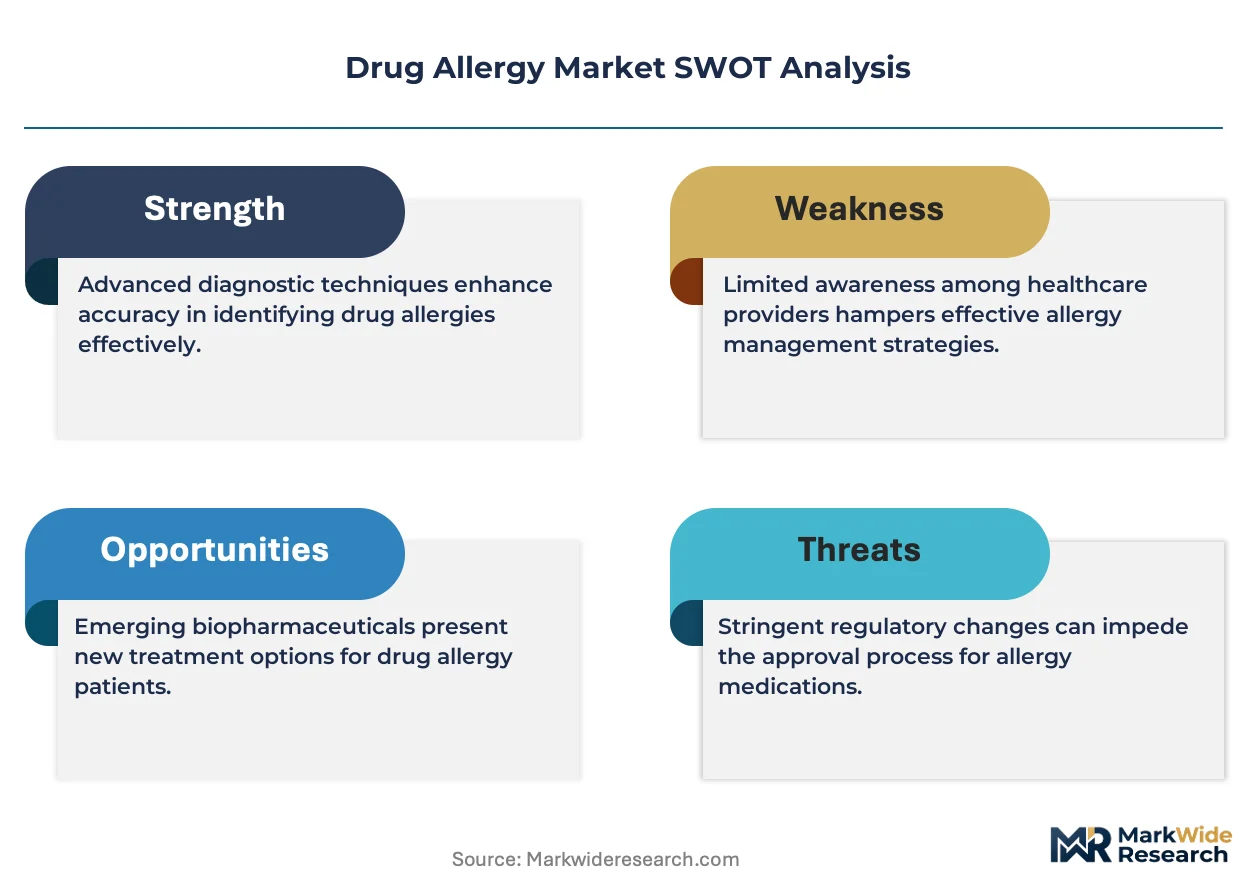
FDA oversees in vitro diagnostic and biologic product standards for the U.S. market, while EMA governs centralized marketing authorization for allergy therapeutics across European member states, and WHO pharmacovigilance frameworks coordinate adverse reaction reporting standards that shape manufacturer safety obligations. Regulatory stringency around diagnostic accuracy is elevating barriers for assay developers while simultaneously expanding validated testing access through certified laboratory networks. Stakeholders must monitor evolving desensitization protocol reimbursement decisions by national health technology assessment bodies.
Market Dynamics
Systematic delabeling initiatives across integrated health systems are dismantling decades of unverified penicillin allergy labels, creating surge demand for validated diagnostic protocols and reshaping clinical workflows toward evidence-based risk stratification.
Growth Catalysts
- Hospital-based diagnostic expansion:Academic medical centers in the United States are embedding penicillin allergy testing into preoperative pathways, converting historical contraindications into actionable clearance data.
- FDA diagnostic guidance evolution:Updated validation requirements for in vitro allergy assays are standardizing assay performance benchmarks and expanding certified laboratory network capacity.
- Biologics protocol penetration:Monoclonal antibodies targeting cytokine pathways are displacing corticosteroids in severe hypersensitivity management, creating new therapeutic categories with distinct reimbursement profiles.
Market Restraints
- Assay development cost concentration:Specialized IgE conjugate production requires dedicated cleanroom infrastructure, limiting viable suppliers to capitalized diagnostic manufacturers.
- Reimbursement fragmentation:Medicare coverage determinations for oral challenge procedures vary by contractor jurisdiction, creating geographic access disparities for confirmatory testing.
- Skin testing supply constraints:Commercial availability of standardized drug-protein reagents depends on single-source manufacturers in Western Europe.
Strategic Opportunities
- Point-of-care assay miniaturization:Lateral flow platforms for drug-specific IgE detection could shift testing from centralized laboratories to ambulatory settings.
- Desensitization protocol standardization:Professional society guidelines from the American Academy of Allergy, Asthma & Immunology are creating framework for protocol replication across health systems.
- Pharmacovigilance data monetization:Real-world hypersensitivity reaction registries offer predictive analytics value to pharmaceutical manufacturers for post-market surveillance.
Industry Challenges
- Allergy-immunology workforce density:Board-certified allergist concentration in rural and exurban United States falls below threshold for population-based testing access.
- Cross-reactivity prediction modeling:Computational platforms for structural similarity assessment require validation against clinical challenge outcomes, extending development timelines.
- Electronic health record interoperability:Allergy status documentation standards vary across Epic, Cerner, and Meditech installations, propagating label errors through care transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Allergy Market |
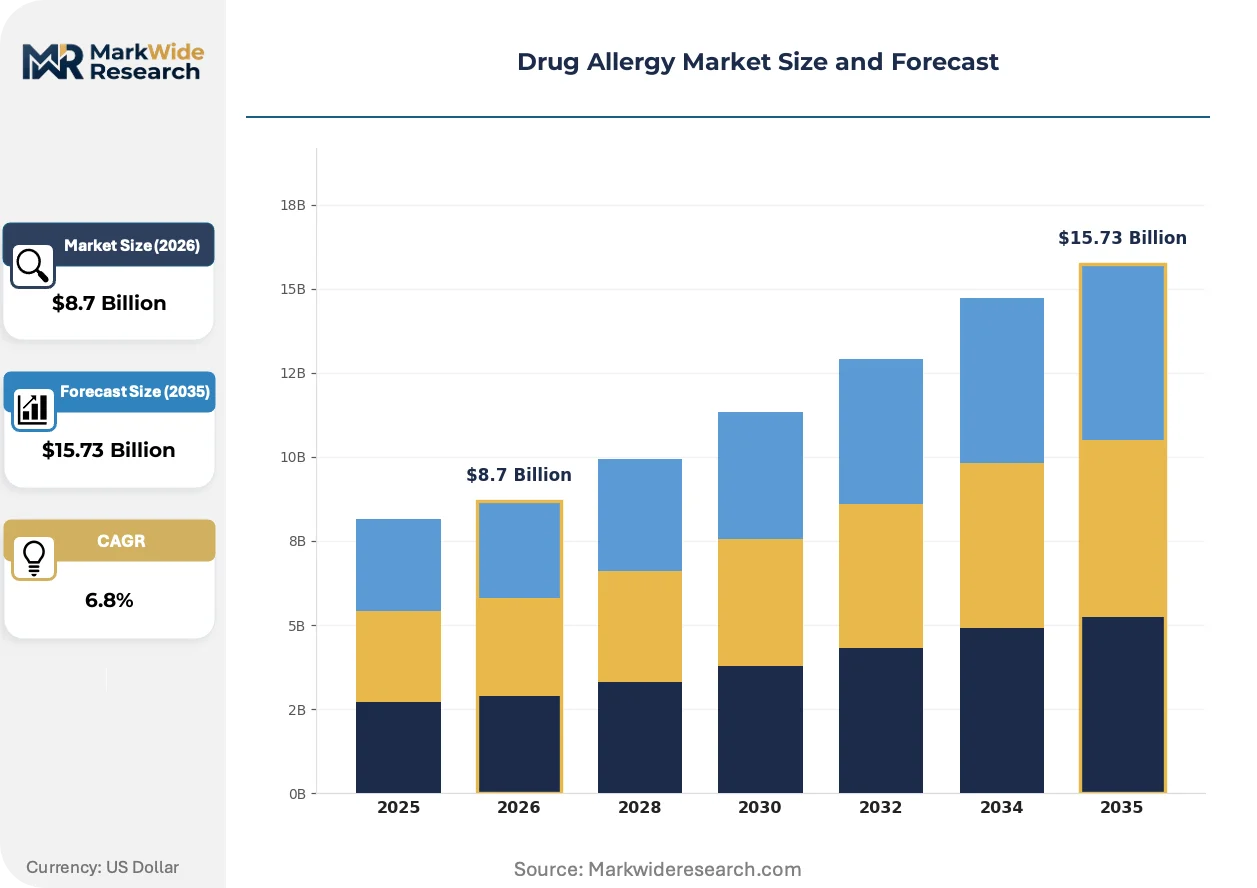
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Penicillins, Non-Steroidal Anti-Inflammatory Drugs, Sulfonamides, Antiepileptics Severity Level: Mild, Moderate, Severe, Life-Threatening Patient Demographics: Children, Adults, Elderly, Pregnant Women Treatment Approach: Avoidance, Desensitization, Pharmacotherapy, Immunotherapy |
| Companies Covered | Novartis, Roche, Johnson & Johnson, Regeneron Pharmaceuticals, AbbVie, Sanofi, Pfizer, Thermo Fisher Scientific, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Allergy Market Emerging Trajectories
Artificial intelligence applications are penetrating hypersensitivity prediction, while regulatory frameworks for companion diagnostics and biologics converge around patient stratification requirements.
Basophil activation testing is automating functional IgE assessment for drug reactions that lack reliable skin test reagents. Large referral centers in Germany and the United States are adopting flow cytometry-based platforms for perioperative evaluation. This automation is compressing turnaround times from days to hours and enabling same-day surgical clearance.
EMA's In Vitro Diagnostic Medical Devices Regulation is imposing clinical evidence requirements on allergy assay manufacturers that previously operated under self-certification. Commercial laboratories must now submit performance validation against challenge-proven patient cohorts. High-complexity molecular allergy panels face the steepest compliance burden, with several manufacturers withdrawing lower-volume tests from European markets.
Integrated health systems are unbundling allergy testing from specialist consultation, permitting direct-to-procedure scheduling for low-risk patients with isolated penicillin labels. Kaiser Permanente and Veterans Health Administration facilities have deployed nurse-protocol pathways that bypass traditional allergist triage. This channel disintermediation is most advanced in California and Texas, where capitated reimbursement incentivizes throughput optimization.
Drug Allergy Market Segmentation
Segmentation in drug allergy management reveals how clinical protocols, reimbursement structures, and patient risk profiles allocate resources across diagnostic and therapeutic pathways. Understanding these divisions exposes where health systems concentrate investment and where protocol standardization remains incomplete.
Drug Class:
Standardization dominates penicillin protocols through decades of validated testing algorithms, while newer drug classes retain customized, institution-specific approaches with uneven evidence bases.
- Penicillins:Beta-lactam antibiotics generate the deepest diagnostic demand due to high prescription volume and systematic delabeling initiatives across United States health systems. Kaiser Permanente and Veterans Health Administration facilities embed penicillin allergy testing into preoperative pathways, converting historical contraindications into clearance data.
- Non-Steroidal Anti-Inflammatory Drugs:Aspirin and ibuprofen hypersensitivity drives cross-reactive assessment protocols in respiratory-allergy clinics, where Samter's triad presentations require specialized prostaglandin pathway evaluation. German referral centers automate functional IgE assessment for NSAID reactions lacking reliable skin test reagents.
- Sulfonamides:Trimethoprim-sulfamethoxazole reactions concentrate in HIV and transplant populations where prophylactic use is unavoidable.
- Antiepileptics:Carbamazepine and phenytoin hypersensitivity triggers HLA-B*1502 pharmacogenetic screening in Asian populations prior to initiation.
Most installed capacity flows through Penicillins. Expansion is steepest in Non-Steroidal Anti-Inflammatory Drugs.
Severity Level:
Margin concentration escalates with clinical acuity, as life-threatening indications command premium reimbursement for intensive monitoring and hospital-based intervention.
- Life-Threatening:Anaphylaxis and severe cutaneous adverse reactions require emergency department infrastructure and intensive care step-down capacity. United States academic medical centers deploy monoclonal antibodies targeting cytokine pathways for corticosteroid-refractory cases.
- Severe:Serum sickness and drug-induced hepatitis necessitate hepatology and rheumatology co-management with extended monitoring protocols. EMA's strengthened clinical evidence requirements for allergy assays elevate validation burdens for manufacturers serving this tier.
- Moderate:Maculopapular eruptions and fixed drug reactions drive outpatient dermatology consultation volume.
- Mild:Isolated pruritus and minor urticaria generate the highest false-positive label burden in electronic health records.
Revenue concentrates in Life-Threatening indications. Patient volume peaks in Mild reactions.
Patient Demographics:
Age-stratified protocols reflect differential risk tolerance for drug challenge procedures and distinct reimbursement pathways across pediatric and adult populations.
- Adults:Working-age patients drive ambulatory testing demand where direct-to-procedure scheduling bypasses traditional allergist triage. California and Texas capitated reimbursement models incentivize throughput optimization for this cohort.
- Children:Pediatric protocols require weight-based dosing adjustments and modified challenge procedures with anesthesia standby. United States children's hospitals maintain specialized drug allergy units with higher staffing ratios.
- Elderly:Polypharmacy complexity and comorbidity burden complicate attribution of adverse reactions in nursing facility populations.
- Pregnant Women:Fetal safety considerations restrict challenge procedures to essential therapeutics with no acceptable alternatives.
Testing volume flows predominantly through Adults. Protocol complexity is highest in Children.
Treatment Approach:
Cost tier stratification separates avoidance-based management from resource-intensive desensitization and emerging biologic interventions.
- Pharmacotherapy:Antihistamines and corticosteroids remain the foundational revenue layer across retail pharmacy and acute care channels. Sanofi competes across pharmaceutical and consumer health segments with differentiated positioning.
- Immunotherapy:Allergen-specific protocols advance from research into clinical practice as the fastest-expanding treatment category. Novartis leverages its immunology pipeline for targeted cytokine inhibition in severe hypersensitivity.
- Desensitization:Graduated drug reintroduction protocols for essential antibiotics and chemotherapy agents require specialized infusion centers with extended observation capacity.
- Avoidance:Label-driven substitution to alternative drug classes incurs downstream resistance and therapeutic compromise costs.
Current spending concentrates in Pharmacotherapy. Investment is accelerating fastest in Immunotherapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated health systems in the United States anchor diagnostic protocol innovation, while European regulatory evolution and Asia-Pacific infrastructure buildout reshape competitive positioning across testing and therapeutic channels.
United States
Kaiser Permanente and Veterans Health Administration facilities deploy nurse-protocol pathways that bypass traditional allergist triage for penicillin delabeling. FDA guidance on in vitro diagnostic devices mandates updated validation requirements for allergy assay manufacturers. Academic medical centers in California and Texas embed testing into preoperative pathways, converting historical contraindications into clearance data.
Germany
Large referral centers automate basophil activation testing through flow cytometry-based platforms for perioperative evaluation. EMA's In Vitro Diagnostic Medical Devices Regulation imposes clinical evidence requirements on allergy assay manufacturers that previously operated under self-certification. The Rhine-Ruhr metropolitan region concentrates diagnostic laboratory capacity serving cross-border patient flows from neighboring member states.
United Kingdom
National Health Service trusts pilot direct-to-procedure scheduling models that unbundle allergy testing from specialist consultation. The country's national pharmaceutical regulator aligns with EMA centralized marketing authorization frameworks for allergy therapeutics. London-based academic hospitals maintain specialized drug allergy units with higher staffing ratios for complex desensitization protocols.
Japan
PMDA oversight of biologic product standards shapes manufacturer entry strategies for monoclonal antibody therapeutics targeting cytokine pathways. METI industrial policy supports domestic diagnostic platform development for IgE-mediated sensitization testing. The Kanto region around Tokyo hosts concentrated pharmaceutical R&D infrastructure for hypersensitivity reaction research.
India
CDSCO regulatory pathways for diagnostic devices attract multinational assay manufacturers seeking cost-optimized production bases. The country's national pharmaceutical regulator coordinates adverse reaction reporting standards with WHO pharmacovigilance frameworks. Maharashtra and Karnataka host emerging contract research organizations supporting clinical validation studies for European market access.
Drug Allergy Market Vendor Landscape
Global majors compete with regional champions across diagnostic platform and therapeutic development dimensions, producing a tiered structure where capitalized manufacturers control assay supply chains while mid-scale biotechs occupy targeted cytokine inhibition niches. Swiss and American conglomerates anchor the pharmaceutical layer through immunology pipeline depth, while specialized diagnostic houses dominate IgE conjugate production. Strategic archetypes include integrated health science conglomerates, standalone diagnostic platform developers, and biologics-focused immunology specialists. Competitive moves concentrate on regulatory certification expansion and point-of-care assay miniaturization partnerships.
Within the integrated conglomerate tier, Novartis and Roche exemplify capitalized players with cross-therapeutic reach spanning biologics and small-molecule portfolios. Thermo Fisher Scientific anchors the diagnostic layer as a standalone platform developer with specialized assay infrastructure. Sanofi occupies a hybrid position bridging pharmaceutical and consumer health channels with differentiated antihistamine positioning. These three represent distinct archetype endpoints rather than direct competitors across identical segments.
| Leading Market Players |
|---|
| Novartis |
| Roche |
| Johnson & Johnson |
| Regeneron Pharmaceuticals |
| AbbVie |
| Sanofi |
| Pfizer |
| Thermo Fisher Scientific |
| GlaxoSmithKline |
| Others |
Supply Flow & Price Mechanics
Captive production of drug-protein conjugates for IgE testing anchors supply security for capitalized diagnostic manufacturers while creating tiered pricing power based on cleanroom infrastructure ownership. This vertical integration into specialized reagent manufacturing insulates premium assay suppliers from raw material volatility and supports margin maintenance against commoditized testing alternatives.
Pricing Analysis
Input-cost pass-through from pharmaceutical-grade albumin and hapten chemistry inputs shapes assay pricing structures, with manufacturers embedding these variable costs into per-test fee schedules. Three-tier pricing structure across premium, standard, and economy levels separates high-complexity molecular panels from basic penicillin-specific IgE screens. Cost compression in economy-tier lateral flow devices is intensifying because of scale manufacturing migration to Indian production bases. Hospital laboratories exhibit lowest price sensitivity due to bundled reimbursement, while independent reference labs face acute margin pressure on Medicare-contracted test panels.
Supply Chain Analysis
Direct-to-hospital laboratory channels handle high-throughput diagnostic demand from integrated health systems, while specialty distributors serve smaller reference laboratories and ambulatory clinics. Manufacturing concentration clusters in Germany, the United States, and Switzerland for GMP-compliant conjugate production, with India emerging as a cost-optimized base for lateral flow assembly. Critical supply chain risk centers on single-source dependency for standardized penicilloyl-polylysine reagents produced by Western European manufacturers. Distribution runs through regional laboratory supply cooperatives in the United States and national tender systems in European member states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in drug allergy management rests on biologics protocol penetration displacing generic corticosteroids, with premium-tier therapeutic positioning capturing reimbursement favorable to small-molecule alternatives.
For Market Incumbents: Acquire basophil activation testing automation platforms to secure perioperative diagnostic workflow integration against emerging flow cytometry specialists. Consolidate position through backward integration into hapten chemistry manufacturing, reducing dependency on single-source European reagent suppliers. FDA diagnostic guidance evolution threatens non-compliant assay portfolios, necessitating immediate validation investment against challenge-proven patient cohorts. For New Entrants and Emerging Players: Premium-economy price-point gaps in point-of-care IgE detection create white-space entry opportunities for miniaturized lateral flow platforms. Target direct-to-procedure scheduling pathways in California and Texas capitated reimbursement markets, where throughput optimization incentives favor rapid testing alternatives. Deploy nurse-protocol partnership models that bypass traditional allergist triage for low-risk penicillin delabeling candidates. For Investors and Strategic Acquirers: Roll-up economics work for regional diagnostic laboratory networks because EMA's In Vitro Diagnostic Medical Devices Regulation is forcing consolidation among sub-scale European players unable to bear clinical evidence submission costs. Long-term viability favors platforms with both assay manufacturing and health system contract channel control. Watch basophil activation testing adoption rates in German and United States academic medical centers as inflection indicator for functional IgE assessment market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Care Assay Miniaturization | Lateral flow platforms shift testing from centralized laboratories to ambulatory settings, expanding addressable market. |
| Desensitization Protocol Standardization | American Academy of Allergy, Asthma and Immunology guidelines enable protocol replication across health systems. |
| Biologics Pipeline Expansion | Monoclonal antibodies targeting cytokine pathways displace corticosteroids in severe hypersensitivity management. |
| Regulatory Certification Expansion | EMA clinical evidence requirements elevate barriers for assay developers while expanding validated laboratory network access. |
| Pharmacovigilance Data Monetization | Real-world hypersensitivity registries offer predictive analytics value to pharmaceutical manufacturers for post-market surveillance. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with allergy-immunology department heads, diagnostic laboratory directors, pharmaceutical regulatory affairs leads, and hospital procurement managers with secondary validation from FDA filings, EMA centralized marketing authorization submissions, ClinicalTrials.gov hypersensitivity protocol registrations, and CMS Medicare coverage determination databases. Bottom-up test volume modeling and top-down therapeutic revenue triangulation anchored market sizing across segments.
Comparable-period anchoring linked historical diagnostic procedure volumes to projected biologics protocol penetration rates across the analysis window. Segmentation dimensions modeled included drug class, severity level, patient demographic cohort, and treatment approach, with regional regulatory clusters capturing FDA, EMA, PMDA, and CDSCO framework variations. CAGRs derived from weighted average of epidemiological trend extrapolation and technology adoption curve analysis, incorporating allergist workforce density and reimbursement policy trajectory as industry-specific forecast inputs.
Caveats apply where allergist workforce shortages, cross-reactivity prediction algorithm validation delays, or electronic health record interoperability failures could materially shift the outlook. Forecasts reflect documented assumptions regarding desensitization protocol reimbursement expansion and biologics formulary placement velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Cytomegalovirus Treatment Market
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
Global Exocrine Pancreatic Insufficiency (EPI) Market
Pharmaceuticals
Antiandrogens Market
Pharmaceuticals
South Korea Human Papillomavirus Vaccine Market
Pharmaceuticals
Cyclosporine Drugs Market
Pharmaceuticals
Anastrozole Tablets Market
Pharmaceuticals
Eperisone Hcl Market
Pharmaceuticals
Asia-Pacific Meglitinide Market
Pharmaceuticals
Antiglaucoma Drugs Market
Pharmaceuticals
Loxoprofen Market
Pharmaceuticals
HIV Antivirals Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Global Respiratory Drug Market
Pharmaceuticals
Brazil Diabetes Drugs Market