
 Cefazedone Sodium Market | 2026-2036
Cefazedone Sodium Market Size, Share, and Industry Trends Forecast 2026-2036
Cefazedone Sodium Market Insights
Hospital procurement departments are redrawing the Cefazedone Sodium competitive map as homecare and retail pharmacy buyers lose relative influence in bulk antibiotic purchasing. Biosynth Carbosynth leverages its catalog breadth to serve research-scale buyers across multiple geographies. KyungDong Pharm anchors its position through Korean domestic manufacturing and regional hospital supply contracts. Shandong Luoxin Pharmaceutical Group competes on cost-efficient cephalosporin fermentation capacity serving Asian markets.
Cefazedone sodium is a first-generation cephalosporin antibiotic active against gram-negative and gram-positive pathogens, typically supplied as a sterile powder for reconstitution and parenteral administration with specified potency and endotoxin limits. The injectable product type dominates hospital formularies due to the drug's poor oral bioavailability and the need for precise dosing in severe infections. Among delivery modes, IV infusion leads in surgical prophylaxis applications where rapid achievement of therapeutic plasma levels is critical, while liquid formulation development represents the fastest-growing segment as manufacturers seek ready-to-use presentations that reduce pharmacy compounding burden.
China's NMPA enforces GB standards for cephalosporin API purity and sterility that shape export eligibility for domestic producers, while India's CDSCO mandates batch release testing that filters out substandard entrants. The US FDA maintains active pharmaceutical ingredient inspection protocols that determine which overseas facilities can supply the American hospital market. Stakeholders must monitor regulatory divergence between major pharmaceutical markets as compliance investments increasingly determine which manufacturers retain supply contracts versus those forced into lower-margin regional niches.
Market Dynamics
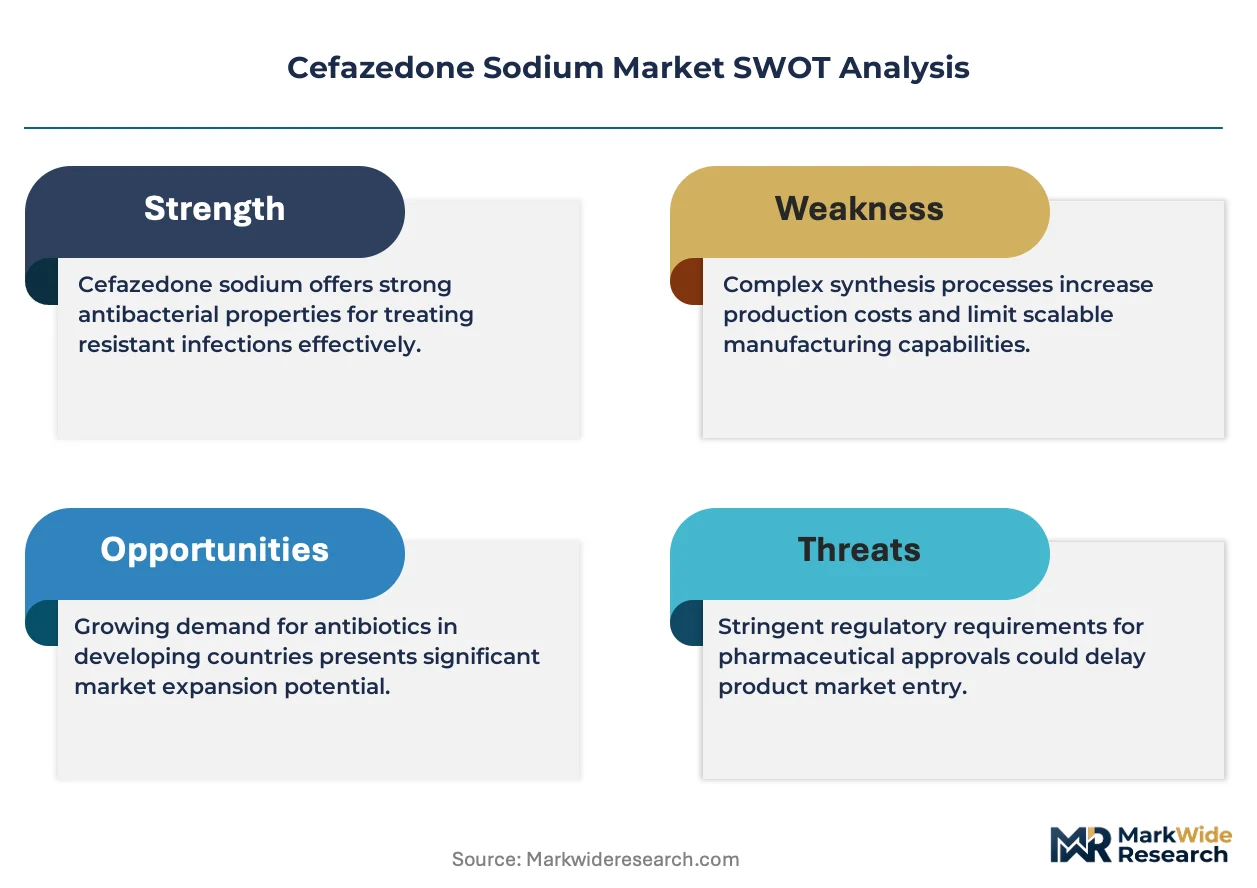
Hospital formulary consolidation is compressing supplier margins as procurement departments centralize antibiotic purchasing under single-source contracts with strict potency and endotoxin specifications.
Growth Catalysts
- Injectable capacity expansion:Domestic sterile manufacturing investments in India and China are reducing import dependency for hospital antibiotic programs.
- CDSCO batch release mandates:India's tightened testing protocols are filtering substandard API entrants and elevating quality-certified supplier premiums.
- Surgical prophylaxis protocols:Rising hospital infection control standards are embedding first-generation cephalosporins into pre-operative antibiotic regimens.
Market Restraints
- Fermentation input volatility:Penicillin G and 7-ACA precursor costs fluctuate with agricultural commodity cycles, squeezing cephalosporin API margins unpredictably.
- NMPA impurity profiling compliance:China's tightened GB standards for cephalosporin APIs are forcing facility upgrades that smaller fermentation houses cannot fund.
- Carbapenem substitution pressure:Broad-spectrum alternatives are displacing first-generation cephalosporins in ICU settings with multidrug-resistant pathogen prevalence.
Strategic Opportunities
- Ready-to-use liquid formulations:Pre-mixed IV presentations reduce pharmacy compounding burden and command hospital formulary preference.
- ASEAN hospital network expansion:Vietnam, Indonesia, and Thailand are building domestic sterile injectable capacity with unmet API supply contracts.
- Dual carbon manufacturing incentives:China's MEE carbon intensity targets reward fermentation facilities with renewable energy integration and process water recycling.
Industry Challenges
- Sterile process engineering talent scarcity:Aseptic manufacturing expertise concentrates in legacy cephalosporin hubs, constraining new facility commissioning timelines.
- Endotoxin validation bottlenecks:LAL testing capacity and reference standard access delay batch release for export markets requiring FDA or EMA documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cefazedone Sodium Market |
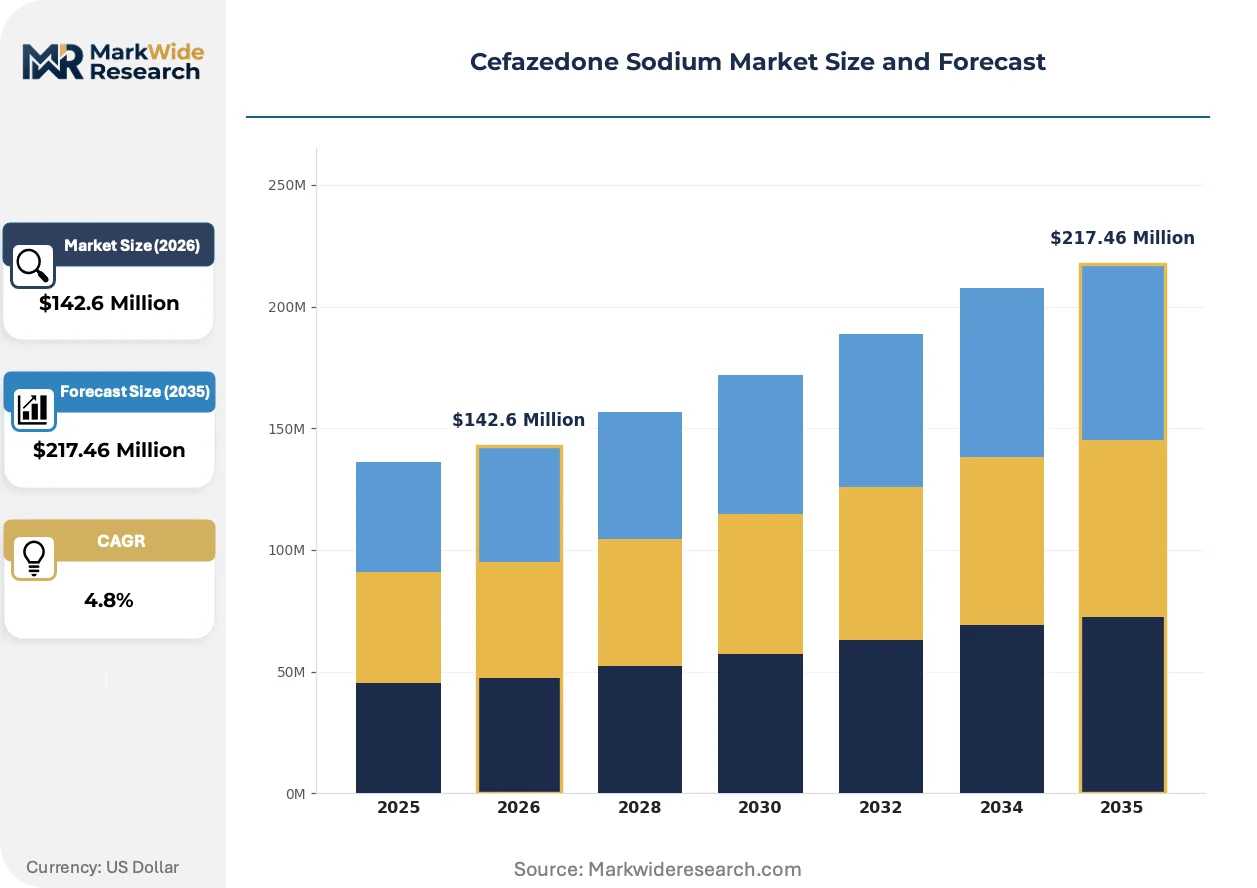
| Market Size in 2026 | $142.6 Million |
| Market Size in 2035 | $217.46 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral, Topical, Solution End User: Hospitals, Clinics, Homecare, Retail Pharmacies Delivery Mode: IV Infusion, IM Injection, Oral Tablet, Liquid Formulation Application: Antibiotic Treatment, Infection Control, Surgical Prophylaxis, Empirical Therapy |
| Companies Covered | Biosynth Carbosynth, MedKoo Biosciences, AK Scientific, KyungDong Pharm, Xingrui Industry Co., LEAPChem, BOCSCI, SynZeal Research, Shandong Luoxin Pharmaceutical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cefazedone Sodium Market Trends and Innovations
Continuous manufacturing and real-time release testing are displacing traditional batch processing in cephalosporin API production, compressing quality verification cycles from weeks to hours.
Lyophilized powder technology is miniaturizing unit-dose presentations for hospital automated dispensing cabinets. Korean and Chinese manufacturers are adopting this format to reduce pharmacy labor and dosing errors. The shift is compressing bulk powder demand while elevating value-added formulation premiums.
EMA's revised Annex 1 sterile manufacturing guidelines are mandating barrier isolation technology and single-use systems for cephalosporin API facilities. European hospital suppliers must demonstrate contamination control investments to retain GMP certificates. Contract manufacturers in India and China are retrofitting isolators to maintain EU market access.
Hospital buying committees are consolidating antibiotic procurement under therapeutic class tenders rather than molecule-specific contracts. This behavior concentrates volume with dual-source suppliers offering cephalosporin portfolios across generations. The pattern is most visible in China's tier-one municipal hospital networks and India's corporate hospital chains.
Cefazedone Sodium Market Segmentation
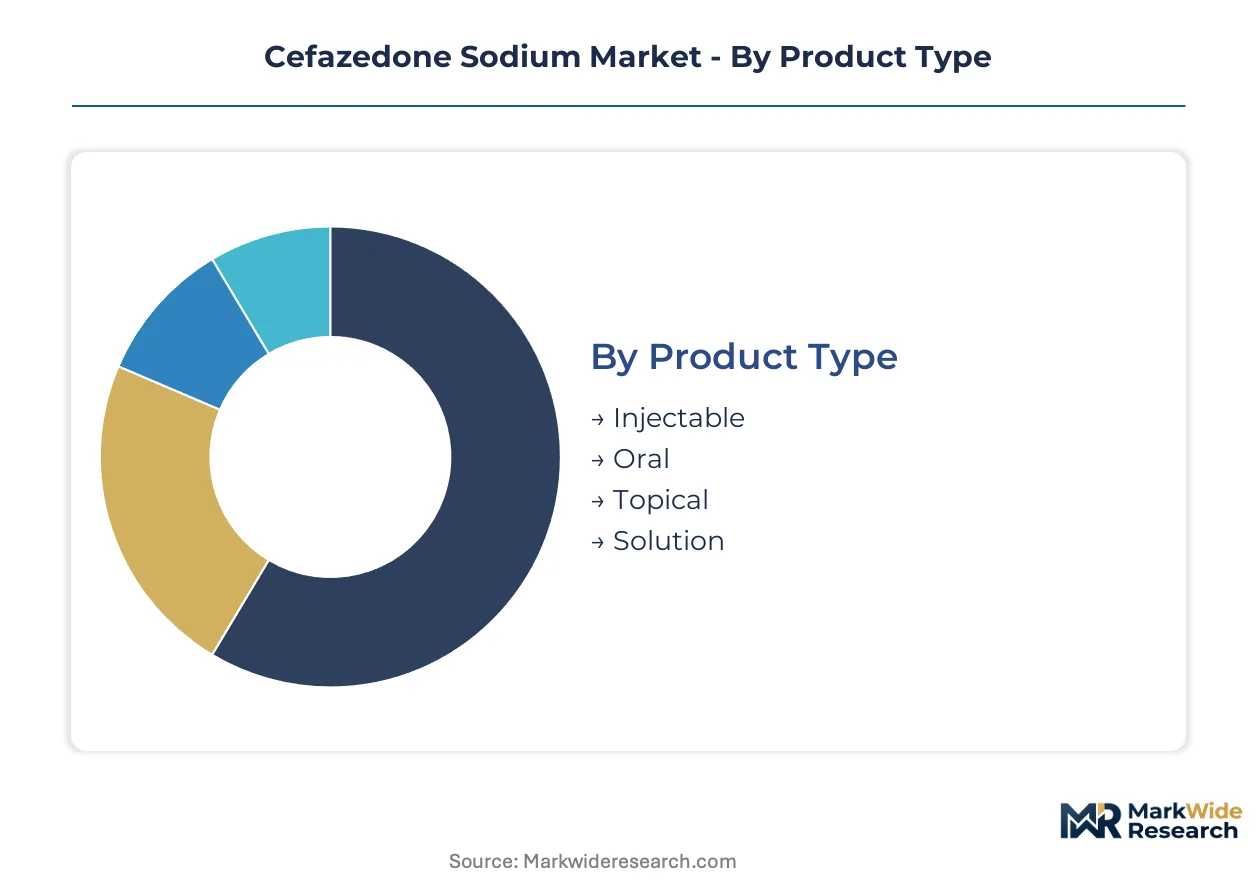
Cefazedone sodium's poor oral bioavailability and parenteral administration requirements create sharp segmentation boundaries. Hospital procurement patterns and regulatory compliance costs determine which product formats and delivery modes capture sustainable margin pools.
Product Type:
Margin concentration follows formulation complexity and sterility assurance burden.
- Injectable:Sterile powder for reconstitution dominates hospital formularies due to precise dosing requirements in severe gram-negative and gram-positive infections. China's NMPA GB standards and India's CDSCO batch release mandates filter substandard entrants, elevating quality-certified supplier premiums in tier-one municipal hospital networks.
- Solution:Ready-to-use liquid formulations reduce pharmacy compounding burden and command preferential formulary placement. Korean and Chinese manufacturers adopting this format target automated dispensing cabinets in corporate hospital chains across India and ASEAN markets.
- Oral:Limited bioavailability constrains therapeutic utility to mild outpatient infections with narrow spectrum coverage.
- Topical:Restricted to localized skin and soft tissue applications with minimal hospital procurement volume.
The dominant share belongs to Injectable, while Solution is closing the gap fastest.
End User:
Procurement centralization is redrawing influence across customer types.
- Hospitals:Antibiotic treatment programs and surgical prophylaxis protocols embed first-generation cephalosporins into pre-operative regimens. China's tier-one municipal networks and India's corporate chains consolidate purchasing under therapeutic class tenders.
- Clinics:Outpatient antibiotic administration for moderate infections with IV infusion capability captures regional volume.
- Homecare:Limited penetration due to parenteral administration requirements and infection control liability.
- Retail Pharmacies:Oral and topical formats serve residual outpatient demand with compressed margins.
Hospitals retain the volume anchor position, though Clinics are expanding share through ambulatory surgery center networks.
Delivery Mode:
Surgical protocol requirements determine route selection and reimbursement positioning.
- IV Infusion:Rapid therapeutic plasma level achievement makes this the standard for surgical prophylaxis and empirical therapy in ICU settings. EMA's revised Annex 1 guidelines mandate barrier isolation technology for sterile manufacturing, retrofitting requirements for EU market access.
- Liquid Formulation:Pre-mixed presentations eliminate reconstitution steps and reduce dosing errors. Manufacturers in Korea and China target this segment for ASEAN hospital network expansion in Vietnam, Indonesia, and Thailand.
- IM Injection:Alternative parenteral route for patients without reliable venous access in clinic settings.
- Oral Tablet:Bioavailability limitations restrict use to step-down therapy after initial IV stabilization.
IV Infusion holds the established position, with Liquid Formulation gaining share fastest through ready-to-use convenience.
Application:
Clinical setting and pathogen resistance profiles shape demand concentration.
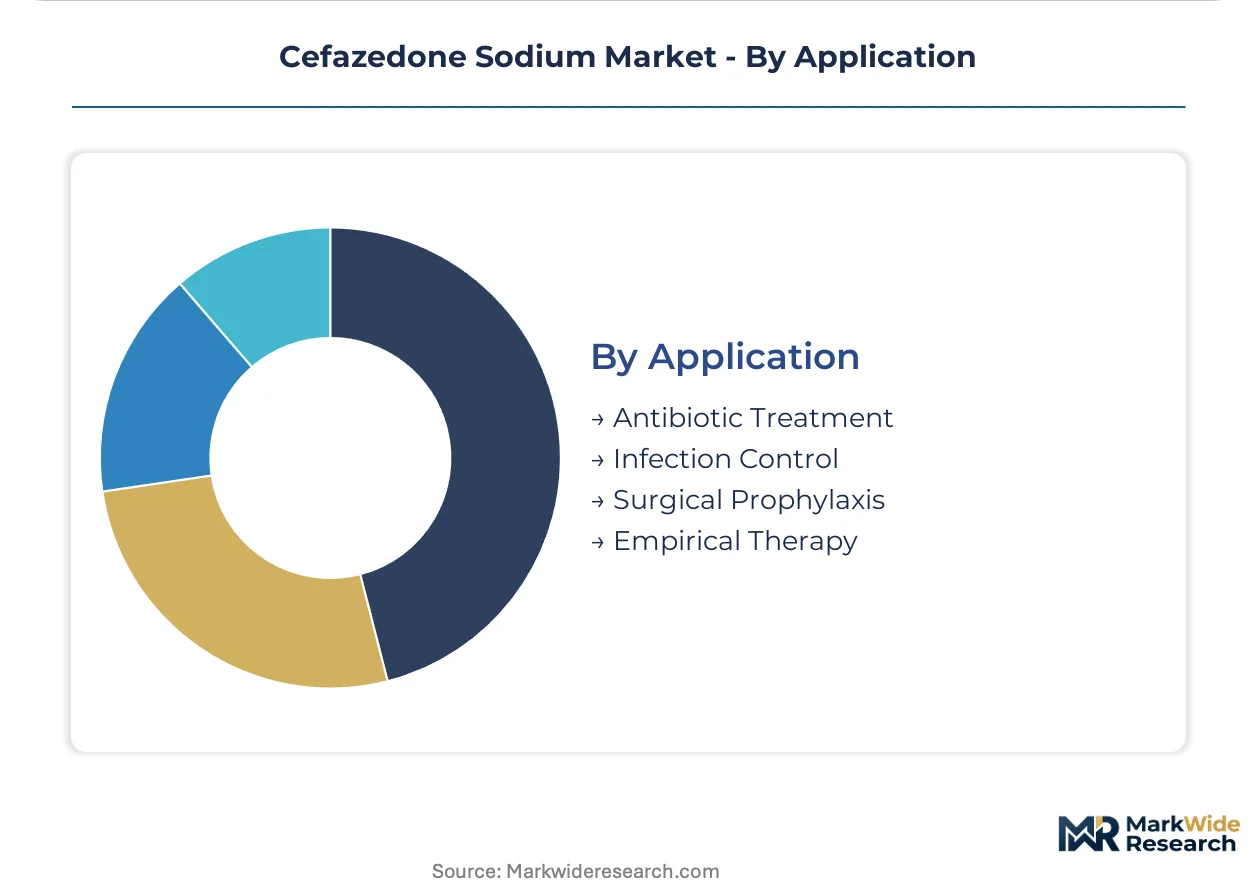
- Surgical Prophylaxis:Pre-operative antibiotic regimens in infection control protocols drive standardized dosing. Rising hospital infection control standards embed first-generation cephalosporins into procedural checklists across China's expanding sterile injectable capacity.
- Antibiotic Treatment:Definitive therapy for documented gram-negative and gram-positive infections with culture-directed selection.
- Infection Control:Hospital-acquired infection prevention bundles in high-risk departments.
- Empirical Therapy:Initial broad-spectrum coverage pending culture results, facing displacement pressure from carbapenems in multidrug-resistant ICU settings.
Surgical Prophylaxis commands the volume base, while Antibiotic Treatment is climbing the fastest through precision diagnostics integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports cefazedone sodium API to hospital networks across India and Southeast Asia, while Korean manufacturers supply finished formulations to ASEAN markets seeking ready-to-use injectable presentations.
China
Tier-one municipal hospital networks in Shanghai and Beijing are consolidating antibiotic procurement under therapeutic class tenders. The NMPA enforces GB standards for cephalosporin API purity and sterility that shape export eligibility for domestic producers. Shandong Province anchors fermentation capacity expansion as manufacturers retrofit facilities to meet tightened impurity profiling rules.
India
Corporate hospital chains in Mumbai and Delhi are deepening domestic sterile injectable capacity to reduce import dependency. The CDSCO mandates batch release testing that filters out substandard API entrants and elevates quality-certified supplier premiums. Gujarat's pharmaceutical clusters are commissioning aseptic manufacturing lines to serve ASEAN hospital network expansion.
South Korea
Regional hospital supply contracts in Seoul and Busan drive formulation exports to Vietnam and Indonesia. The MFDS maintains GMP certification requirements that determine eligibility for sterile injectable production. Kyunggi-do province concentrates lyophilized powder manufacturing for automated dispensing cabinet formats.
Vietnam
Ho Chi Minh City and Hanoi hospital networks are building domestic sterile injectable capacity with unmet API supply contracts. The national pharmaceutical regulator enforces import licensing for cephalosporin antibiotics that prioritizes quality-certified suppliers. The Red River Delta is attracting Korean and Chinese manufacturers seeking ASEAN market access.
Indonesia
Jakarta and Surabaya hospital systems are expanding surgical prophylaxis protocols that embed first-generation cephalosporins into procedural checklists. The national drug and food control agency regulates API import quality standards that favor established fermentation houses. Java island concentrates sterile manufacturing investments from regional pharmaceutical partners.
Cefazedone Sodium Market Competitive Landscape
Player mix skews toward fermentation-based API specialists and regional formulation houses. The supplier base fragments across quality tiers defined by regulatory certification breadth rather than scale concentration. Two strategic archetypes dominate: vertically integrated cephalosporin fermentation houses with captive 7-ACA supply, and formulation specialists leveraging contract manufacturing for hospital network access. Competitive moves center on sterile capacity expansion in India and China, and strategic partnerships with ASEAN hospital procurement consortiums.
Within the quality-certified API tier, Shandong Luoxin Pharmaceutical Group and KyungDong Pharm exemplify contrasting geographic anchoring strategies. Biosynth Carbosynth occupies a position serving research-scale buyers across multiple geographies through catalog breadth. These three represent the archetype spectrum from bulk fermentation supply to specialized research chemical distribution.
| Leading Market Players |
|---|
| Biosynth Carbosynth |
| MedKoo Biosciences |
| AK Scientific |
| KyungDong Pharm |
| Xingrui Industry Co. |
| LEAPChem |
| BOCSCI |
| SynZeal Research |
| Shandong Luoxin Pharmaceutical Group |
| Others |
Pricing and Supply Chain Analysis
Carbapenem displacement in ICU settings simultaneously redraws supply geography toward Asian fermentation hubs and compresses pricing economics for first-generation cephalosporin APIs. China's NMPA impurity profiling mandates and India's CDSCO batch release requirements bifurcate the supplier base into quality-certified premium tiers and margin-constrained regional players.
Pricing Analysis
The formulation-technology pricing gap separates lyophilized unit-dose presentations from bulk sterile powders, with ready-to-use liquid formulations commanding hospital formulary premiums over reconstitution-dependent formats. Three-tier pricing structure across GMP-certified, CDSCO-compliant, and non-certified suppliers reflects endotoxin validation and barrier isolation investments. Pricing pressure stems from fermentation input volatility in penicillin G and 7-ACA precursors. Corporate hospital chains in India exhibit acute price sensitivity, while tier-one municipal networks in China prioritize supply security over unit cost.
Supply Chain Analysis
China and India anchor cephalosporin API fermentation, with South Korea specializing in lyophilized finished formulations for ASEAN export. Supply chains draw from agricultural commodity cycles for penicillin G feedstocks and 7-ACA intermediate chemistry. Single-source vulnerability concentrates in Shandong Province fermentation clusters subject to NMPA environmental compliance shutdowns. Distribution runs through hospital procurement consortiums and GPO contracts rather than wholesale pharmaceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ready-to-use liquid formulation services expand faster than bulk API hardware, creating attach-revenue opportunities through pharmacy compounding reduction and automated dispensing integration.
For Market Incumbents: Secure barrier isolation retrofit completion ahead of EMA Annex 1 enforcement deadlines to defend EU market access against contract manufacturers in India and China. Lock in captive 7-ACA supply through backward integration or long-term offtake agreements with fermentation houses in Shandong Province. Carbapenem substitution in multidrug-resistant ICU settings threatens volume retention in empirical therapy segments. For New Entrants and Emerging Players: CDSCO fast-track certification for sterile injectable facilities opens procurement doors in India's corporate hospital chains. Target Vietnam and Indonesia hospital network expansion where domestic sterile capacity construction outpaces qualified API supply. Lead with ready-to-use liquid formulations to bypass established powder-reconstitution incumbents in ASEAN markets. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian contract manufacturers holding CDSCO batch release capabilities but lacking formulation R&D depth. The five-to-ten year viability window favors quality-certified API specialists over commodity fermentation houses facing NMPA compliance attrition. Monitor carbapenem resistance surveillance data as volume inflection signal for first-generation cephalosporin surgical prophylaxis protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Isolation Retrofit | EMA Annex 1 compliance preserves EU GMP certificates for export eligibility. |
| Ready-to-Use Liquid Formulation Launch | Pre-mixed IV presentations reduce pharmacy labor and command formulary preference. |
| Captive 7-ACA Supply Integration | Backward integration into fermentation intermediates insulates margin from agricultural commodity cycles. |
| CDSCO Fast-Track Certification | Expedited batch release approval unlocks India's corporate hospital chain procurement. |
| ASEAN Hospital Network Partnership | Vietnam and Indonesia capacity expansion creates unmet API supply contract opportunities. |
Research Methodology
Operator-level perspectives from hospital procurement managers, sterile manufacturing engineers, regulatory affairs leads, and GPO contract specialists anchored the qualitative base. Primary interview insights combined with secondary validation from NMPA GB standards documentation, CDSCO batch release records, EMA Annex 1 guideline revisions, and hospital formulary databases. Bottom-up facility capacity assessments and top-down antibiotic consumption models underwent triangulation.
Sensitivity analysis tested forecast outputs against regulatory enforcement intensity and fermentation input cost scenarios across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user, and regional regulatory cluster. CAGRs derived from hospital procurement volume trajectories and sterile capacity commissioning timelines incorporate surgical prophylaxis protocol adoption rates and carbapenem substitution elasticity.
Underlying assumptions cover NMPA compliance enforcement continuity and CDSCO batch release capacity expansion, with deviation risk concentrated in carbapenem resistance prevalence shifts and agricultural commodity cycle volatility. Recalibration cycles align with material shifts in regulatory enforcement intensity and hospital infection control protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Polypill Products Market
Pharmaceuticals
Esophageal Achalasia Drug Market
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
Selective Serotonin Reuptake Inhibitors Market
Pharmaceuticals
South Korea Human Papillomavirus Vaccine Market
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
Ophthalmic Drugs Market
Pharmaceuticals
Global Preventive Vaccines Market
Pharmaceuticals
Global RFID in Pharmaceuticals Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
Guanethidine Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
PD-1/PD-L1 Inhibitor Market
Pharmaceuticals
Antiretroviral (ARV) Agents Market
Pharmaceuticals
Etomidate Market
Pharmaceuticals
Glioblastoma Treatment Drugs Market