
 Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market | 2026-2036
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market Foresight
The capital-intensity divergence between large-cap multinationals and focused mid-tier specialists is bifurcating competitive strategy across the European MIGS landscape. Alcon Inc. leverages its integrated cataract-glaucoma surgical platform to sustain premium positioning in hospital purchasing committees. Glaukos Corporation anchors its presence through proprietary trabecular meshwork stent technology that dominates clinician training networks. iSTAR Medical differentiates via hydrus microstent designs that compete on anatomical fit and procedural efficiency.
Micro Invasive Glaucoma Surgery devices comprise miniature implants, stents, and microcatheters typically measuring less than one millimeter in cross-section, designed to restore aqueous humor outflow through the trabecular meshwork or suprachoroidal space without major conjunctival dissection. Stents command the largest revenue share among device types due to established reimbursement codes and repeatable implantation protocols, while microcatheters represent the fastest-expanding category as surgeons adopt ab interno canaloplasty techniques. Ophthalmology clinics absorb disproportionate volume growth relative to hospitals, driven by same-day discharge economics and lower facility fees that align with payer cost-containment objectives.
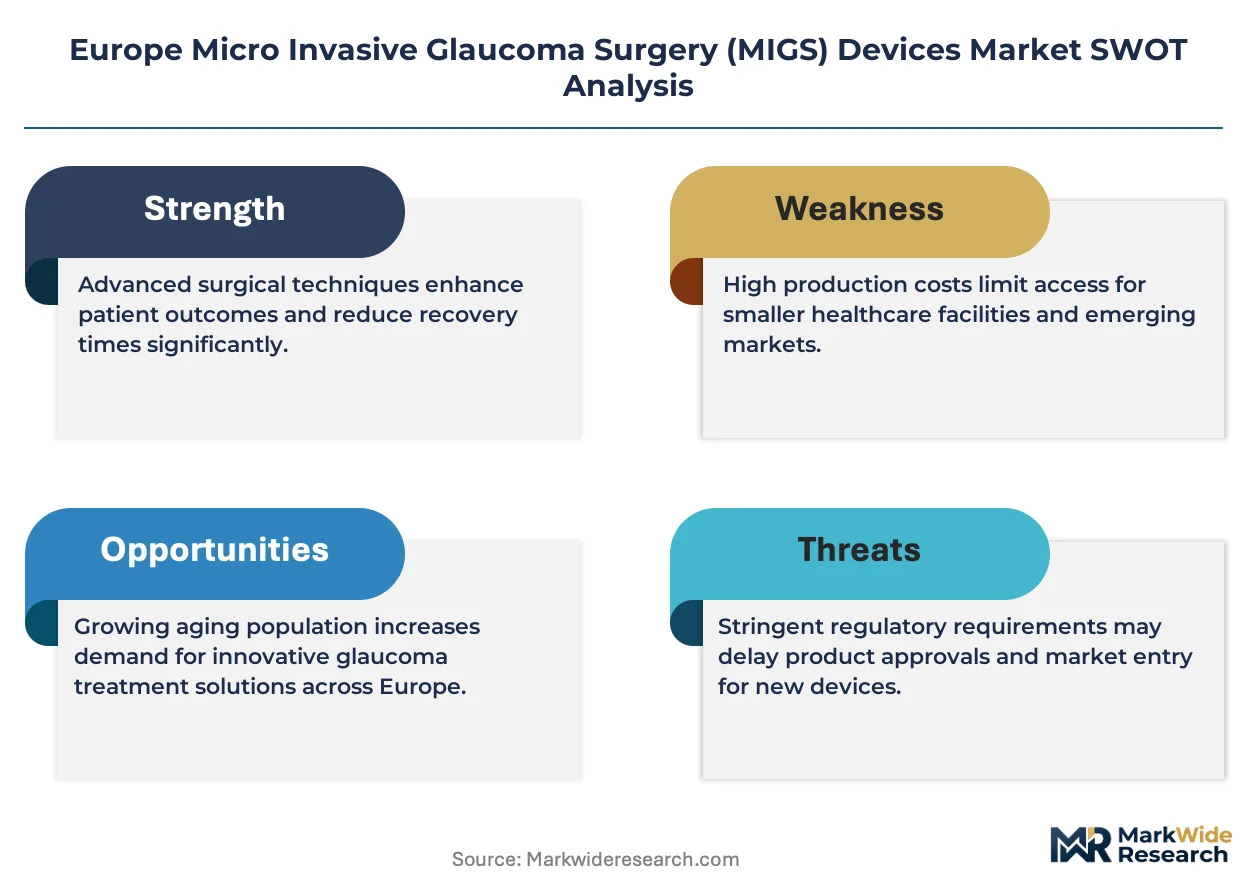
The EU Medical Device Regulation (MDR) and CE marking framework administered by notified bodies in Germany, France, and the Netherlands impose escalating clinical evidence requirements that extend time-to-market for novel implant designs. EMA coordination with national health technology assessment bodies in England, France, and Germany increasingly ties reimbursement decisions to real-world outcome registries, compressing margins for manufacturers lacking post-market surveillance infrastructure. Stakeholders must monitor evolving HTA convergence patterns and decide whether to front-load clinical trial investments across multiple European jurisdictions or sequence market entry based on favorable reimbursement rulings.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing product launch timelines while simultaneously elevating clinical evidence thresholds, forcing manufacturers to restructure post-market surveillance capabilities ahead of reimbursement negotiations with national health technology assessment bodies.
Growth Catalysts
- CE marking pathways:Streamlined conformity assessment procedures for Class III ophthalmic implants under notified bodies in Germany and the Netherlands are accelerating hospital procurement cycles.
- Day-case surgery economics:Reimbursement frameworks in France and England that favor same-day discharge protocols are pulling MIGS adoption away from traditional trabeculectomy.
- Trabecular meshwork stent technology:Refinement of ab interno implantation techniques is reducing operative time and expanding addressable patient pools beyond refractory glaucoma cases.
Market Restraints
- Silicone polymer supply concentration:Three specialized European compounders control medical-grade silicone feedstock for microstent fabrication, creating input vulnerability.
- MDR clinical evidence escalation:The EU Medical Device Regulation now demands prospective registry data for novel suprachoroidal shunt designs, extending time-to-reimbursement by 18-24 months.
- Pharmacological substitution:Fixed-dose combination eye drops with prostaglandin analogues remain first-line therapy in Southern Europe, delaying surgical intervention.
Strategic Opportunities
- Poland and Czech Republic hospital networks:Underpenetrated cataract-glaucoma combination surgery volumes in Central Europe offer expansion corridors for stent-based platforms.
- Real-world evidence mandates:France's ANSM and Germany's BfArM are increasingly accepting post-market registry outcomes for reimbursement dossiers, rewarding manufacturers with existing surveillance infrastructure.
- OCT-guided implantation:Integration of anterior segment optical coherence tomography with microstent delivery systems is opening precision-placement protocols that command premium positioning.
Industry Challenges
- Glaucoma fellowship training bottlenecks:The pipeline of surgeons proficient in gonioscopic anatomy and ab interno navigation remains constrained across Iberia and Italy.
- MDR notified body capacity:Consolidation of designated conformity assessment organizations in ophthalmic devices is stretching certification timelines for iterative product modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market |
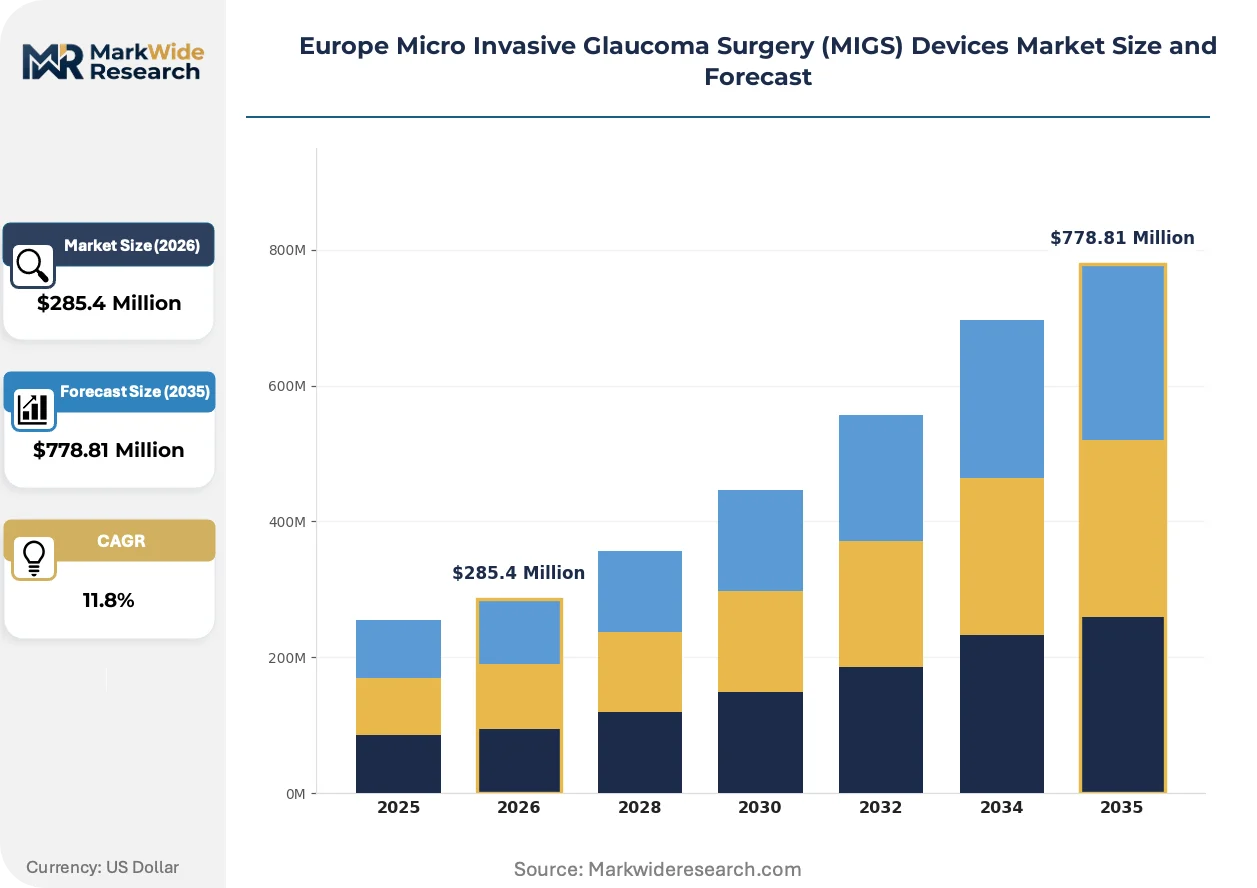
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $778.81 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Stents, Shunts, Implants, Microcatheters End User: Hospitals, Ophthalmology Clinics, Ambulatory Surgical Centers, Research Institutes Technology: Minimally Invasive Techniques, Laser Technology, Surgical Visualization, Ultrasonic Devices Application: Glaucoma Treatment, Sight Preservation, Pressure Management, Eye Surgery |
| Companies Covered | Alcon Inc., Glaukos Corporation, Allergan plc, Santen Pharmaceutical Co., Ltd., iSTAR Medical, Ivantis Inc., Nova Eye Medical Limited, Sight Sciences Inc., Carl Zeiss Meditec AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market Shifts & Advancements
Device miniaturization and imaging integration are converging to redefine surgical workflow economics, while regulatory data requirements are shifting competitive advantage toward manufacturers with captive clinical research infrastructure.
Suprachoroidal microshunt designs are displacing traditional trabecular bypass stents in premium hospital segments. German university hospitals are piloting these implants for normal-tension glaucoma populations previously excluded from MIGS candidacy. The technology is displacing conventional filtration surgery in academic centers that prioritize bleb-free outcomes and reduced postoperative management burden.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic patient follow-up through 10-year horizons. Manufacturers must now fund independent registry studies or risk non-renewal of CE certificates. France's ANSM and England's MHRA are cross-referencing these longitudinal datasets during health technology appraisal, compressing margins for firms lacking dedicated epidemiology teams.
Hospital purchasing committees are consolidating ophthalmic device contracts into multi-year framework agreements that bundle cataract platforms with glaucoma adjuncts. Independent clinics in Spain and Portugal are responding through group purchasing organizations that aggregate volume across regional networks. The shift is most pronounced in Andalusia, where public hospital outsourcing to private surgical centers has created hybrid procurement channels demanding flexible pricing structures.
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market Segmentation
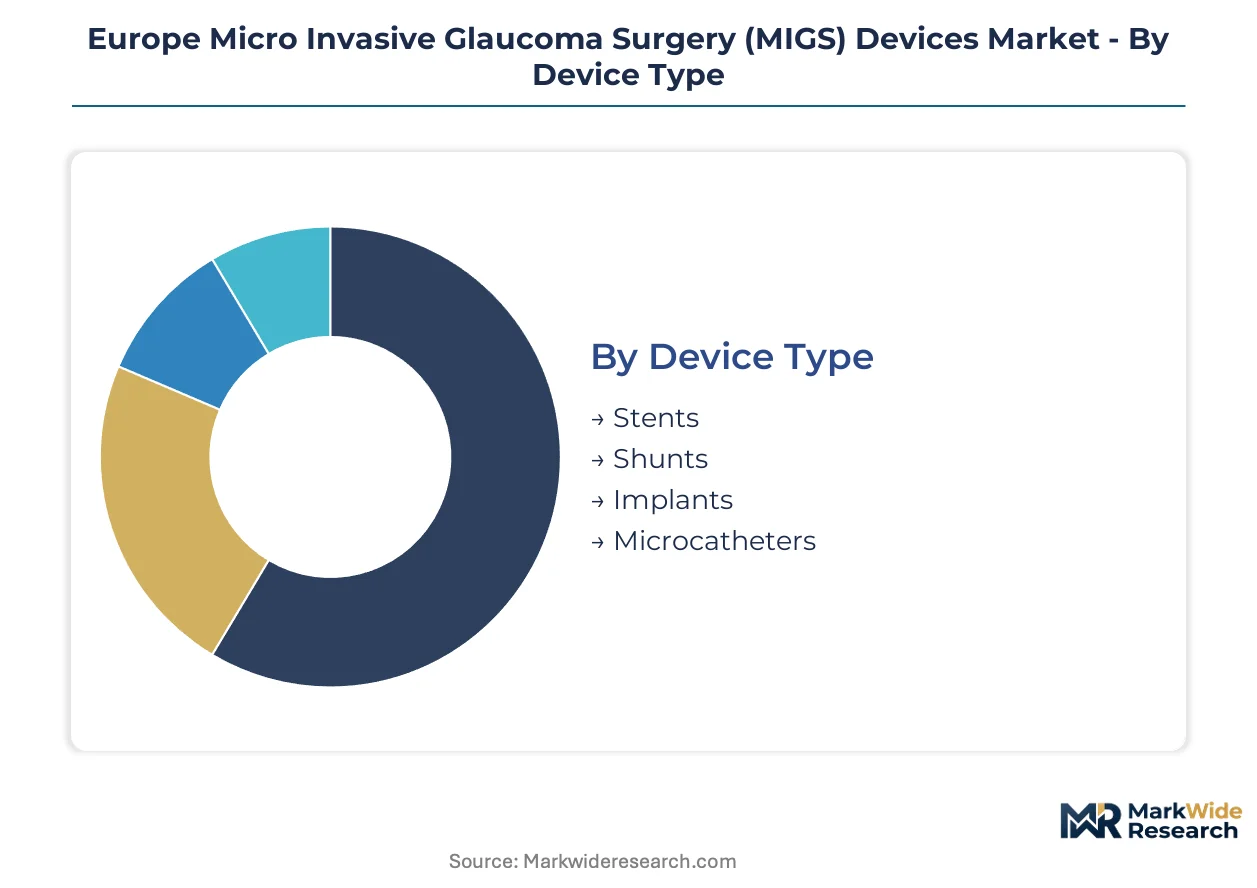
Margin pools across the European MIGS landscape concentrate in device categories with established CE marking pathways and repeatable implantation protocols. Understanding where procurement committees allocate budget and where reimbursement codes have matured reveals which segments command sustainable pricing power.
Device Type:
Premium positioning clusters around implantable hardware with proprietary delivery systems, while commoditization pressure affects catheter-based platforms lacking differentiation.
- Stents:Miniature trabecular meshwork implants fabricated from medical-grade silicone or nitinol, typically 1mm or less in cross-section, restore aqueous outflow without conjunctival dissection. German university hospitals concentrate demand here, driven by established DRG reimbursement codes that cover combination cataract-glaucoma procedures. MDR clinical evidence requirements favor incumbents with decade-long safety registries.
- Shunts:Suprachoroidal microshunts divert aqueous humor to the suprachoroidal space, eliminating bleb-related complications of traditional filtration surgery. French academic centers are piloting these devices for normal-tension glaucoma populations previously excluded from surgical intervention. The category captures the steepest expansion trajectory as surgeons prioritize reduced postoperative management burden.
- Implants:Hydrus-style intracanalicular scaffolds maintain Schlemm's canal patency through sustained mechanical support. iSTAR Medical's designs compete on anatomical fit and procedural efficiency.
- Microcatheters:Ab interno canaloplasty tools enable viscodilation of collector channels without implant placement. Ophthalmology clinics in Spain and Portugal favor these for lower facility fees and same-day discharge economics.
Stents hold installed capacity. Microcatheters are rotating up the share rankings.
End User:
Procurement authority fragments across facility types with divergent capital allocation cycles and payer contracting leverage.
- Hospitals:Tertiary centers with integrated cataract suites command purchasing volume through multi-year framework agreements bundling glaucoma adjuncts with phacoemulsification platforms. German hospital networks concentrate investment here, where Klinikum procurement committees negotiate centralized contracts.
- Ophthalmology Clinics:Independent surgical centers absorb disproportionate volume growth driven by lower facility fees and streamlined same-day discharge protocols. England's NHS outsourcing to private providers accelerates this shift.
- Ambulatory Surgical Centers:Day-case surgery specialists in France leverage streamlined ANSM registration pathways for rapid technology adoption.
- Research Institutes:Academic medical centers in the Netherlands pilot novel suprachoroidal designs under investigator-initiated study protocols.
Hospitals anchor revenue concentration. Ophthalmology clinics are climbing the fastest.
Technology:
Intellectual property moats concentrate in visualization and minimally invasive delivery systems rather than energy-based modalities.
- Minimally Invasive Techniques:Ab interno surgical approaches eliminate conjunctival dissection, reducing operative time and postoperative complications. Alcon's integrated platforms dominate training networks across Western Europe.
- Laser Technology:Selective laser trabeculoplasty competes with MIGS for early-stage glaucoma, though reimbursement gaps limit penetration in Southern Europe.
- Surgical Visualization:Anterior segment optical coherence tomography integration with microstent delivery commands premium positioning. German manufacturers lead gonioscopic imaging innovation.
- Ultrasonic Devices:High-intensity focused ultrasound for ciliary body ablation remains niche due to irreversibility concerns and limited CE marking pathways.
Minimally invasive techniques hold installed capacity. Surgical visualization is gaining share fastest.
Application:
Reimbursement codes align procedural economics with disease severity staging, concentrating margin in sight preservation rather than pressure management alone.
- Glaucoma Treatment:Definitive surgical intervention for primary open-angle and pseudoexfoliative variants drives stent and shunt volumes. German DRG codes specifically reimburse trabecular bypass procedures.
- Sight Preservation:Neuroprotection-focused protocols in French academic centers prioritize IOP reduction to prevent optic nerve damage progression.
- Pressure Management:Adjunctive MIGS during cataract surgery captures combination procedure economics across England's NHS trusts.
- Eye Surgery:General ophthalmic surgical applications include MIGS as standard-of-care integration in comprehensive glaucoma management pathways.
Glaucoma treatment holds installed capacity. Sight preservation is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net import dependence characterizes the European MIGS devices landscape, with specialized silicone polymer feedstock and precision-machined delivery systems sourced from Swiss and German compounders while finished stent assemblies flow toward hospital networks across the continent.
Germany
Klinikum procurement committees in Bavaria and North Rhine-Westphalia drive centralized purchasing of trabecular bypass platforms through multi-year framework agreements. The BfArM coordinates with national health technology assessment bodies to tie reimbursement decisions to real-world outcome registries. University hospitals in Heidelberg and Tübingen pilot suprachoroidal microshunt designs for normal-tension glaucoma populations.
France
ANSM registration pathways enable rapid adoption of ab interno canaloplasty techniques in Parisian ophthalmology clinics. Day-case surgery economics pull MIGS volumes away from traditional trabeculectomy through streamlined same-day discharge protocols. Academic medical centers in Lyon and Marseille prioritize sight preservation protocols that emphasize IOP reduction to prevent optic nerve damage progression.
United Kingdom
NHS trusts in England outsource combination cataract-glaucoma procedures to private surgical centers, creating hybrid procurement channels demanding flexible pricing structures. The MHRA cross-references longitudinal registry datasets during health technology appraisal, compressing margins for manufacturers lacking dedicated epidemiology teams. London and Manchester concentrate demand for integrated phacoemulsification platforms.
Spain
Group purchasing organizations aggregate volume across Andalusian regional networks in response to public hospital outsourcing trends. Fixed-dose combination eye drops with prostaglandin analogues remain first-line therapy in Southern Europe, delaying surgical intervention. Barcelona and Madrid host training networks addressing glaucoma fellowship bottlenecks in gonioscopic anatomy proficiency.
Netherlands
Notified bodies in the Randstad administer CE marking frameworks that impose escalating clinical evidence requirements on novel implant designs. Research institutes in Leiden and Rotterdam pilot investigator-initiated study protocols for next-generation suprachoroidal shunts. The country's central position in European logistics channels supports distribution efficiency to surrounding markets.
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market Competitive Landscape
Concentration sits with integrated ophthalmic multinationals that leverage cataract platform bundling to secure hospital purchasing committee contracts. Mid-tier specialists compete on proprietary trabecular meshwork or suprachoroidal delivery technologies. Three archetypes dominate: full-suite platform vendors with training network captivity, stent-focused innovators with hydrus-style anatomical differentiation, and microcatheter specialists serving clinic economics. Competitive moves center on M&A for registry infrastructure and strategic partnerships for silicone polymer supply security.
Within the integrated platform tier, Alcon Inc. and Glaukos Corporation occupy positions that exemplify divergent scale advantages—Alcon through its cataract-glaucoma surgical bundling capabilities and Glaukos through proprietary stent technology embedded in clinician training networks. iSTAR Medical represents the focused specialist archetype with hydrus microstent designs competing on anatomical fit. Among these, Alcon Inc. and Glaukos Corporation anchor the competitive structure, with iSTAR Medical occupying a distinct mid-tier position.
| Leading Market Players |
|---|
| Alcon Inc. |
| Glaukos Corporation |
| Allergan plc |
| Santen Pharmaceutical Co., Ltd. |
| iSTAR Medical |
| Ivantis Inc. |
| Nova Eye Medical Limited |
| Sight Sciences Inc. |
| Carl Zeiss Meditec AG |
| Others |
Supply & Pricing Matrix
Nitinol alloy substitution for medical-grade silicone in microstent fabrication is redrawing European procurement maps while compressing margin structures for manufacturers tethered to legacy polymer supply agreements. This materials transition simultaneously elevates Swiss precision-metalworking centers and erodes the pricing power of German silicone compounders that historically dominated ophthalmic implant feedstock.
Pricing Analysis
Hospital purchasing committees anchor three-tier pricing structure across premium, standard, and economy levels in the European MIGS landscape. Price differentiation rests on CE marking tier and procedural training bundling, with premium tiers commanding positioning through integrated cataract platform compatibility. Cost compression in standard-tier stents is intensifying because Polish and Czech hospital networks are consolidating procurement through multi-year framework agreements. Ophthalmology clinics in Southern Europe exhibit highest price sensitivity due to fragmented payer landscapes, while German university hospitals demonstrate lowest sensitivity given established DRG reimbursement pathways.
Supply Chain Analysis
Swissmedic-regulated precision machining in the Lake Geneva corridor underwrites critical chokepoint capacity for nitinol delivery system components. Feedstock concentration spans Switzerland for metal alloys, Germany for medical-grade silicone, and the Netherlands for polymer compounding. Raw material dependencies include nitinol shape-memory wire, platinum-iridium marker bands, and medical-grade silicone elastomers. Single-source vulnerability concentrates in specialized wire-drawing facilities certified for implantable device tolerances. Distribution runs through notified body-coordinated logistics hubs in the Randstad, with secondary staging in Bavaria for Central European hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European MIGS market functions as a service-attach opportunity where post-market surveillance registry management expands faster than hardware shipment volumes, rewarding manufacturers with captive clinical data infrastructure. Real-world evidence mandates from France's ANSM and Germany's BfArM are elevating surveillance services above device margins as the primary value capture mechanism.
For Market Incumbents: Compound defensive positioning through backward integration into silicone polymer compounding and captive registry infrastructure deployment. Alcon-scale multinationals must consolidate training network captivity against emerging microcatheter specialists threatening price erosion in clinic segments. CE marking pathway acceleration through pre-submission dialogue with German notified bodies represents the critical lever for maintaining procurement committee access. For New Entrants and Emerging Players: Post-market surveillance service gaps where incumbents under-serve create entry corridors for mid-tier specialists lacking epidemiology teams. Central European cataract-glaucoma combination surgery volumes in Poland and Czech Republic hospital networks offer the most penetrable geography given underdeveloped reimbursement pathways. A go-to-market angle anchored to ANSM-accepted registry outcomes for rapid French clinic adoption bypasses incumbent training network advantages. For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors vertically integrated specialists with captive clinical research infrastructure. Long-term viability across the projection horizon hinges on post-market surveillance capability rather than device innovation velocity alone. Acquisition target archetypes include mid-tier stent manufacturers with decade-long safety registries and established BfArM dialogue. The signal to watch is MDR notified body capacity constraints extending certification timelines for iterative modifications, compressing margins for capital-constrained players.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | Pre-submission dialogue with German notified bodies compresses time-to-reimbursement for novel suprachoroidal designs. |
| Hospital System Partnership | Multi-year framework agreements with Bavarian Klinikum networks bundle glaucoma adjuncts with phacoemulsification platforms. |
| Backward Integration into Feedstock | Captive silicone polymer compounding mitigates supply concentration risk among three specialized European compounders. |
| Software Companion Development | Anterior segment OCT integration with microstent delivery commands premium positioning in German academic centers. |
| Reimbursement Strategy | Real-world registry alignment with France's ANSM and England's MHRA health technology appraisal pathways secures payer access. |
Research Methodology
A standing panel of glaucoma surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary fieldwork phases. Secondary validation drew from EMA coordination documents, BfArM reimbursement rulings, hospital procurement databases, and CE marking frameworks administered by notified bodies in Germany, France, and the Netherlands. Bottom-up volume modeling across device categories triangulated against top-down expenditure flows from national health technology assessment bodies.
Consistency checks against external benchmarks validated analytical framework outputs across the analysis window. Segmentation dimensions modeled include device type, end-user facility category, surgical technology approach, and application severity staging. CAGRs were derived from procedure volume trajectories, reimbursement code expansion patterns, and surgeon training pipeline constraints. Industry-specific forecast inputs incorporated MDR transition timelines and HTA convergence patterns between England, France, and Germany.
Forecasts assume regulatory continuity in EU MDR implementation and national HTA coordination; material policy shifts in notified body designation or reimbursement code restructuring would require re-modeling. Specific risk factors include silicone polymer supply disruptions, MDR clinical evidence escalation for suprachoroidal designs, and pharmacological substitution persistence in Southern Europe. Practitioners should keep alternative scenarios live as HTA convergence patterns and day-case surgery economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Eye Sphere Implants Market
Medical Devices
Minimally Invasive Deformity Correction System Market
Medical Devices
Global Tumor Tracking Systems Market
Medical Devices
Asia-Pacific Medical Aesthetic Devices Market
Medical Devices
Intrauterine Insemination Devices Market
Medical Devices
Global Assistive Listening Device Market
Medical Devices
Contact Thermometer Market
Medical Devices
Europe Spinal Fusion Devices Market
Medical Devices
Wireless Handheld Ultrasound Devices Market
Medical Devices
Gastroretentive Drug Delivery Systems Market
Medical Devices
Ligament Stabilizers Market
Medical Devices
Global Wearable Healthcare Devices Market
Medical Devices
Snare Devices Market
Medical Devices
Global Reflex Hammer Market
Medical Devices
Global Medical Composite Market
Medical Devices
India Minimally Invasive Surgery Devices Market