
 Surgical Devices Market | 2026-2036
Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Devices Market Intelligence
The consolidation of Group Purchasing Organization contracts is rewriting the procurement landscape for hospitals and surgical centers. Johnson & Johnson leverages its extensive portfolio to secure bundled deals with major hospital networks. Medtronic sustains its market position through innovation in robotic-assisted surgical systems, particularly for cardiovascular and neurosurgery applications. B. Braun operates with a focus on high-volume disposables and infusion therapy products.
Surgical devices encompass instruments and apparatus used during operative procedures to modify biological tissue. These tools, often made from medical-grade stainless steel, must meet stringent sterility and biocompatibility standards. Robotic Assistance technology represents a high-growth segment, commanding premium pricing for its precision in complex applications like neurosurgery. In contrast, the market for conventional instruments like sutures and forceps is mature, with competition centered on supply chain efficiency and volume sales to hospitals.
Device approval and market access are governed by rigorous frameworks, including the FDA's 510(k) clearance process in the United States, the EU's Medical Device Regulation (MDR), and China's NMPA registration system. These regulations mandate extensive clinical data and post-market surveillance, directly influencing development timelines and R&D costs. Success depends on navigating evolving reimbursement policies for new technologies and ensuring supply chain resilience.
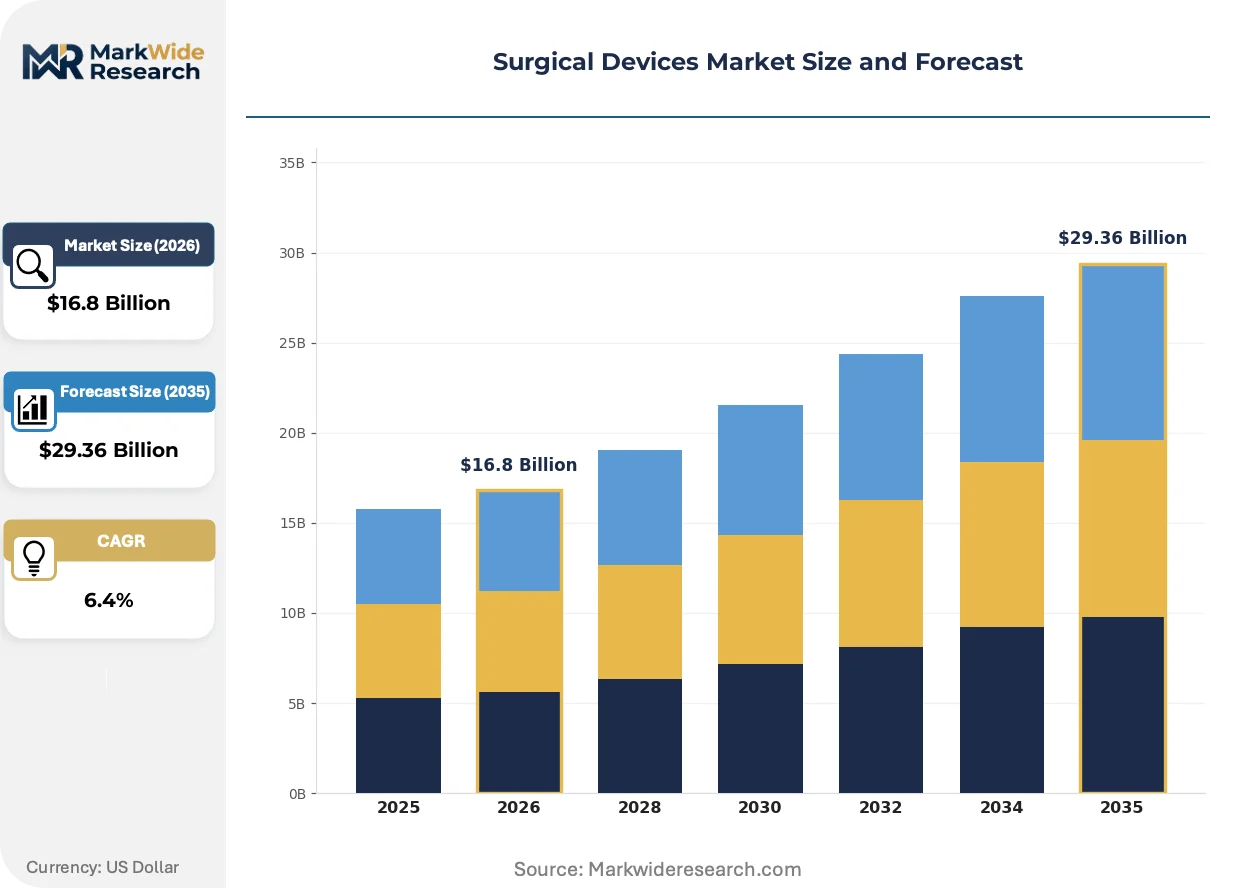
Market Dynamics
The primary force shaping the surgical devices market is the tension between rapid innovation in robotic-assisted systems and the increasingly stringent regulatory frameworks, such as the EU's MDR, which govern market access and product development cycles.
Growth Catalysts
- Robotic Assistance:The adoption of robotic systems for enhanced precision in complex procedures like neurosurgery and cardiovascular operations provides a significant growth vector.
- Aging Demographics:An expanding elderly population in Japan and Western Europe directly increases the volume of necessary surgical interventions and device consumption.
- Infrastructure in China:Government investment in China's hospital capacity creates sustained demand for a full spectrum of surgical instruments and equipment.
Market Restraints
- Regulatory Burden:The EU's Medical Device Regulation (MDR) imposes high compliance costs and long validation timelines, creating significant market entry barriers.
- High Capital Costs:The investment for robotic surgical systems limits their adoption to well-funded hospitals, constraining access for smaller, less-capitalized medical centers.
- Reimbursement Policies:Inconsistent reimbursement for novel devices across different healthcare systems creates financial risk for manufacturers and slows the adoption of new technologies.
Strategic Opportunities
- Ambulatory Surgical Centers:The procedural shift to cost-effective Ambulatory Surgical Centers (ASCs) creates a market for devices specifically designed for outpatient settings.
- AI-Powered Analytics:Integrating artificial intelligence for pre-operative planning and surgical outcome analysis offers a new frontier for value-added services and differentiation.
- Tele-mentoring Platforms:Digital platforms for remote surgical guidance can accelerate the adoption of complex technologies, like robotics, in underserved geographic regions.
Industry Challenges
- Cybersecurity Vulnerabilities:The connectivity of smart surgical devices and robotic systems introduces risks, requiring robust security protocols to protect patient data and hospital networks.
- Specialized Training Gaps:A shortage of surgeons and staff proficient in operating advanced robotic systems hinders technology diffusion and full utilization within hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Devices Market |
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $29.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrosurgical Instruments, Sutures, Surgical Scissors, Forceps End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Technology: Robotic Assistance, Minimally Invasive Surgery, Conventional Surgery, Laser Surgery Application: Orthopedic Surgery, Cardiovascular Surgery, Neuro Surgery, General Surgery |
| Companies Covered | Medtronic, Johnson & Johnson, Stryker Corporation, Intuitive Surgical, B. Braun, Zimmer Biomet Holdings, Boston Scientific, Smith & Nephew, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Devices Market Strategic Shifts & Innovations
Product development in surgical devices is shaped by the parallel pursuit of technological sophistication and adherence to tightening global regulatory standards. This dynamic forces manufacturers to balance innovation with the operational demands of compliance and clinical validation.
Smart surgical instruments incorporate embedded sensors to provide real-time haptic feedback and data on tissue interaction. Specialized surgical departments in teaching hospitals and research centers are the primary adopters of these advanced tools. The focus for high-end instrumentation is migrating from purely mechanical reliability to a new standard that includes data generation and software integration.
Europe's Medical Device Regulation (MDR) has fundamentally altered the path to market access. The regulation mandates more extensive clinical data and continuous post-market surveillance, increasing both costs and timelines for device approval. This shift particularly impacts smaller device innovators, who face greater resource constraints in meeting the EU's heightened evidentiary requirements.
Centralized purchasing decisions by hospital networks and Group Purchasing Organizations (GPOs) are supplanting choices made by individual surgeons. This shift disrupts traditional sales models, favoring vendors with broad product portfolios capable of offering comprehensive, bundled contracts. The trend is most advanced within the consolidated United States healthcare market, influencing procurement strategies nationwide.
Surgical Devices Market Segmentation
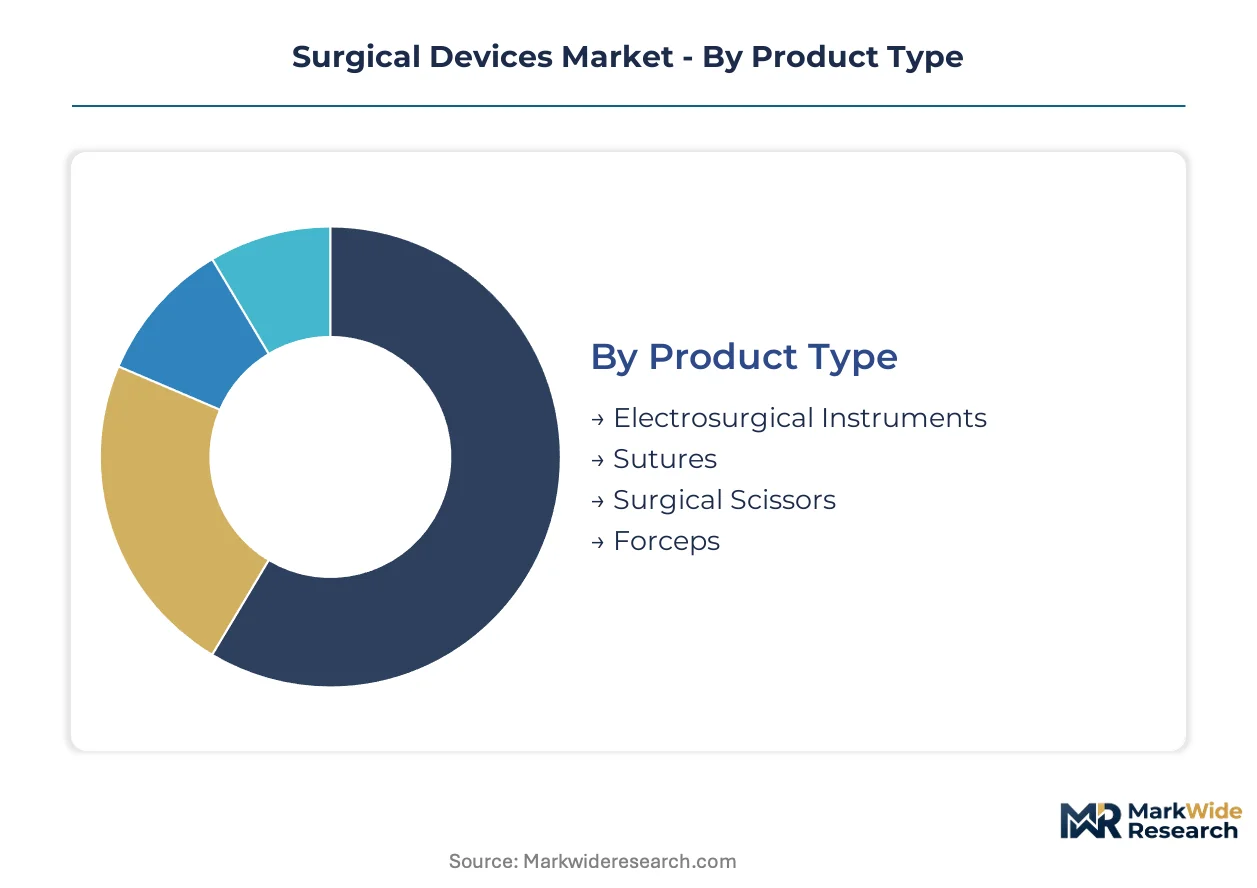
The surgical devices market, characterized by its technological diversity, is comprehensively segmented to reflect the varied product types, end-user environments, technological sophistication, and specific surgical applications. This granular breakdown enables a detailed understanding of demand drivers and competitive dynamics across the industry.
Product Type:
The product type segment for surgical devices exhibits a clear maturity spectrum, ranging from highly specialized, advanced tools to foundational, high-volume consumables.
- Electrosurgical Instruments:These devices use high-frequency electrical currents to cut, coagulate, desiccate, or fulgurate tissue during surgery. Demand concentrates in advanced surgical procedures, particularly in hospitals adopting modern surgical techniques.
- Sutures:Composed of sterile threads or wires, sutures are used to close wounds and approximate tissues during surgical interventions. Their demand is consistently high in all surgical settings, driven by the sheer volume of operative procedures performed globally.
- Surgical Scissors:These precision cutting tools, often made of stainless steel, are essential for dissecting tissue and materials in various surgical fields.
- Forceps:Forceps are hand-held, pincer-like instruments used by surgeons to grasp, manipulate, or hold tissue and other objects during operations.
Sutures handle the majority of throughput; Electrosurgical Instruments are the fastest mover on share.
End User:
The end-user landscape for surgical devices reflects distinct operational environments, each with unique procurement patterns and device requirements.
- Hospitals:These large healthcare facilities perform the broadest range of surgical procedures, from routine to highly complex, requiring a comprehensive array of surgical devices. Demand for advanced instruments and high-volume disposables is consistently strong within major hospital networks.
- Ambulatory Surgical Centers:ASCs specialize in outpatient procedures, offering cost-effective alternatives to hospital-based surgeries for less complex interventions. Demand for devices tailored for efficiency and rapid patient turnover is concentrating here, driven by healthcare cost containment.
- Clinics:Smaller medical facilities and specialized practices utilize surgical devices for minor procedures and diagnostic interventions.
- Research Institutions:These organizations employ surgical instruments for experimental surgeries, anatomical studies, and medical device development and testing.
Hospitals dominate device volume; Ambulatory Surgical Centers show the steepest expansion trajectory.
Technology:
Technological advancements in surgical devices are primarily driven by the pursuit of enhanced precision, reduced invasiveness, and improved patient outcomes.
- Robotic Assistance:These sophisticated systems integrate advanced robotics with surgical instruments, offering surgeons enhanced dexterity, 3D visualization, and precision for complex operations. Demand for these premium systems is concentrating in neurosurgery and cardiovascular applications, driven by superior clinical results.
- Minimally Invasive Surgery:MIS techniques involve small incisions and specialized instruments, reducing patient trauma, recovery times, and hospital stays. Demand for MIS instruments is widespread across surgical specialties, driven by patient preference and healthcare efficiency goals.
- Conventional Surgery:Traditional open surgical procedures still require a broad array of standard instruments for direct tissue access and manipulation.
- Laser Surgery:This technology uses focused light beams for precise tissue cutting, ablation, and coagulation, finding application in ophthalmology and dermatology.
Conventional Surgery retains foundational importance; Robotic Assistance is rapidly gaining market share.
Application:
The application segment highlights the diverse anatomical focus and procedural complexity addressed by specialized surgical devices.
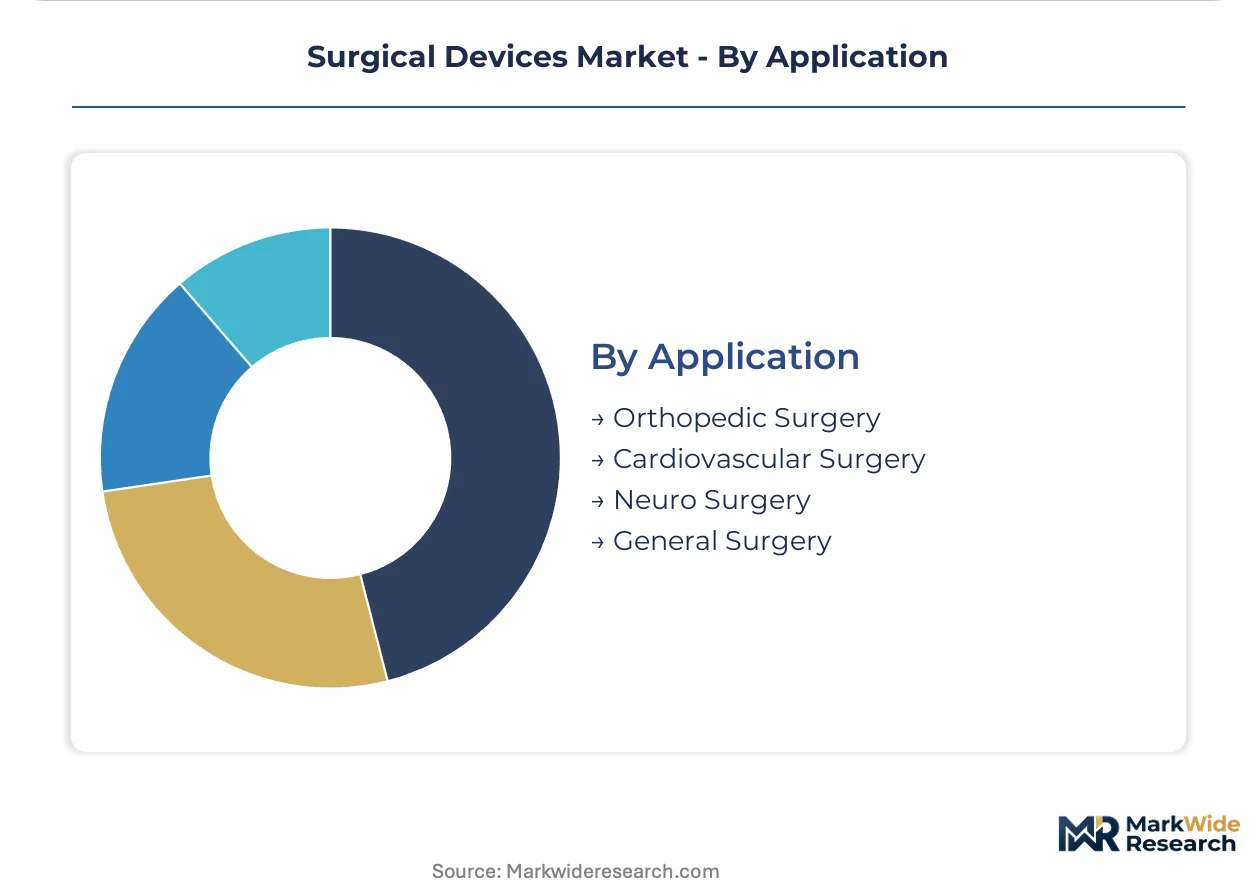
- General Surgery:This broad category encompasses procedures involving the abdominal organs, skin, soft tissue, breast, and hernias, requiring a wide array of versatile surgical instruments. Demand for foundational tools and high-volume disposables is consistently high across all healthcare settings.
- Neuro Surgery:Procedures involving the brain, spinal cord, and peripheral nerves demand extremely precise and specialized instruments, often integrated with advanced imaging and navigation systems. Demand for high-precision robotic systems and micro-instruments is concentrating here, driven by the delicate nature of the interventions.
- Orthopedic Surgery:This specialty focuses on the musculoskeletal system, utilizing devices for bone repair, joint replacement, and trauma management.
- Cardiovascular Surgery:Devices in this segment support operations on the heart and blood vessels, including bypass grafts and valve replacements.
General Surgery constitutes the largest segment; Neuro Surgery exhibits the fastest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's rigorous 510(k) clearance process significantly influences product development and market access across the global surgical devices market. This regulatory environment shapes innovation pipelines and commercial strategies for manufacturers worldwide. Demand for advanced surgical tools is driven by aging populations and increasing surgical volumes in key economies.
United States
Demand for advanced surgical devices is strong, driven by high healthcare spending and a focus on precision medicine. The FDA's 510(k) clearance process mandates extensive clinical data, impacting development timelines for new instruments. Major medical device clusters in Massachusetts and California foster innovation in robotic assistance and minimally invasive technologies.
Germany
An aging demographic in Germany sustains consistent demand for orthopedic and cardiovascular surgical interventions. The EU's Medical Device Regulation (MDR) imposes stringent compliance costs, influencing market entry for device manufacturers. The Tuttlingen region, known as the "Medical Valley," concentrates numerous specialized surgical instrument companies.
China
Government investment in expanding hospital infrastructure across China creates substantial demand for a full spectrum of surgical instruments. China's NMPA registration system requires local clinical trials, affecting market access for foreign surgical device companies. The Yangtze River Delta region is a hub for medical device manufacturing and distribution, serving a large patient base.
Japan
Japan's rapidly aging population drives a consistent need for surgical procedures, particularly in neurosurgery and orthopedics. The PMDA's approval pathways prioritize patient safety and efficacy, requiring thorough clinical evidence for new devices. Tokyo's medical technology parks host research and development centers focused on advanced robotic surgical systems.
India
India's growing middle class and expanding healthcare access are increasing demand for both conventional and advanced surgical tools. The CDSCO regulates medical devices, with evolving frameworks influencing product registration and post-market surveillance. Bengaluru and Hyderabad are emerging as medical technology hubs, attracting investment in device manufacturing and R&D.
Surgical Devices Market Key Industry Players
Global conglomerates and specialized innovators split the surgical devices market, reflecting a tiered competitive structure. Large players leverage extensive product portfolios for bundled contracts with hospital networks and Group Purchasing Organizations. Smaller, agile firms focus on niche technologies like advanced robotic assistance and AI-powered analytics. Dominant competitive moves include strategic acquisitions for technology access and continuous R&D investment for product differentiation in high-growth segments.
Within the diversified portfolio tier, Johnson & Johnson exemplifies broad market penetration across multiple surgical device categories, leveraging its extensive global footprint. Medtronic, another prominent entity, represents innovation in high-precision robotic-assisted surgical systems, particularly in complex applications like neurosurgery. B. Braun occupies a significant position as a specialist in high-volume disposables and infusion therapy products, anchoring a different segment of the market with a focus on supply chain efficiency. These companies leverage their established distribution channels and brand recognition to maintain strong market presence and influence procurement patterns.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Stryker Corporation |
| Intuitive Surgical |
| B. Braun |
| Zimmer Biomet Holdings |
| Boston Scientific |
| Smith & Nephew |
| Olympus Corporation |
| Others |
Cost & Logistics Intelligence
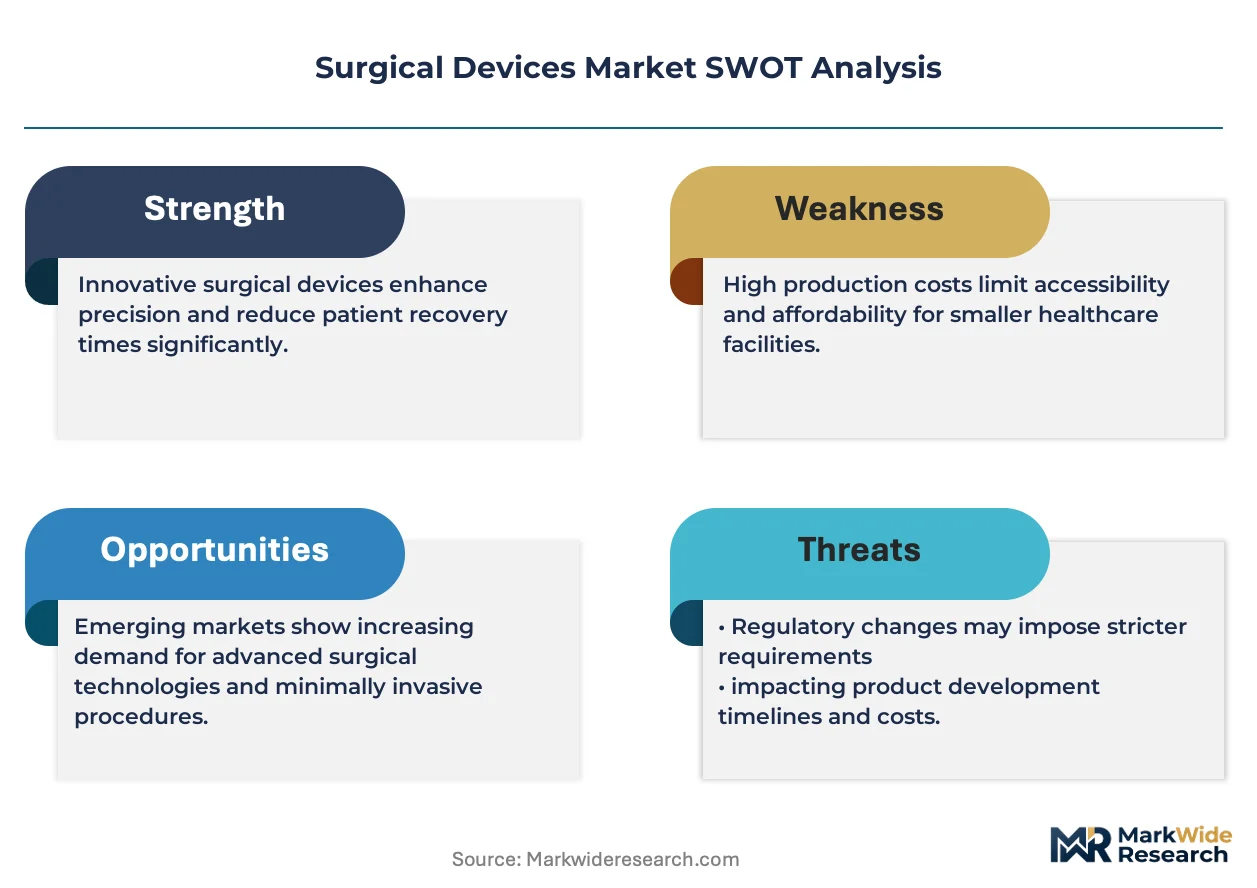
Regulatory chokepoints, specifically the EU's Medical Device Regulation (MDR), determine both pricing tier spreads for new devices and the strategic shape of manufacturer supply chains. This stringent framework necessitates significant investment, impacting market entry costs and product availability.
Pricing Analysis
Configured-to-order robotic surgical systems command a premium, contrasting with the standard pricing of high-volume disposables like sutures. The dominant pricing model for advanced devices is value-based, reflecting superior clinical outcomes and precision. Price differentiation stems from the FDA 510(k) clearance level and specialized brand premium, particularly for complex neurosurgery tools. Pricing pressure stems from Group Purchasing Organization (GPO) consolidation, especially impacting conventional instruments. Ambulatory Surgical Centers (ASCs) exhibit the highest price sensitivity for routine consumables, while teaching hospitals are less sensitive for cutting-edge robotics.
Supply Chain Analysis
Upstream feedstock, primarily medical-grade stainless steel and specialized polymers, is sourced globally from key industrial regions in Germany and China. Raw material dependencies extend to microelectronics for robotic systems and biocompatible materials for implants. Single-source vulnerability for specialized robotic components represents a significant structural risk, potentially disrupting advanced system production. Downstream distribution runs through established channels, including direct sales teams for major hospital networks and third-party distributors servicing smaller clinics and Ambulatory Surgical Centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surgical devices market sits at an early-cycle expansion phase, with a named tailwind in the increasing penetration of robotic assistance across complex surgical applications.
For Market Incumbents:
Build a regulatory barrier moat by investing heavily in clinical data generation and post-market surveillance required by frameworks like the EU MDR. Expand bundled contract offerings with major hospital networks, leveraging broad product portfolios to counter competitive threats from niche innovators. Focus R&D on integrating AI-powered analytics into existing platforms, creating a stickier ecosystem for surgeons. This strategy mitigates margin pressure from GPO consolidation and emerging lower-cost alternatives.
For New Entrants and Emerging Players:
Build out specialized device portfolios tailored for the Ambulatory Surgical Center (ASC) segment, focusing on cost-effective, efficient tools for outpatient procedures. Target underpenetrated geographic regions like India and China, where expanding healthcare infrastructure creates demand for foundational and mid-tier instruments. A strong go-to-market angle involves offering value-added services, such as tele-mentoring platforms, to accelerate adoption of complex technologies in underserved areas.
For Investors and Strategic Acquirers:
The market sits at a growth phase that favors specialized technology firms with strong intellectual property in high-precision areas. Long-term viability remains robust over a five-to-ten-year window, driven by aging demographics and continuous technological advancement. Identify acquisition targets with proprietary robotic platforms or proven AI integration capabilities that offer unique clinical differentiation. The signal to watch is evolving reimbursement policies for novel devices, which will dictate broader market access and revenue potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Robotic Assistance Portfolio | This initiative captures market share in high-growth, premium-priced surgical segments like neurosurgery. |
| Invest in EU MDR Compliance | Ensuring adherence to European regulations maintains market access and builds trust with healthcare providers. |
| Develop ASC-Specific Devices | Tailoring products for outpatient settings addresses cost-containment pressures and expands market reach. |
| Integrate AI for Pre-operative Planning | Leveraging artificial intelligence enhances surgical precision and improves patient outcomes. |
| Strengthen GPO Contract Negotiations | Securing comprehensive bundled deals with purchasing organizations ensures stable volume sales. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary validation from public sources. Primary data involved discussions with surgeons, hospital procurement managers, medical device engineers, and regulatory affairs specialists. Secondary research drew from FDA 510(k) filings, NMPA registrations, EU MDR guidance documents, and GPO contract disclosures. This dual approach ensured comprehensive coverage and triangulated findings through both bottom-up and top-down data synthesis.
Forecast inputs considered historical market performance, current adoption rates, and projected technological advancements across the modeling period. The analytical framework modeled segmentation dimensions including product type, end user, technology, application, and regional regulatory clusters. Compound Annual Growth Rates (CAGRs) were derived from a synthesis of historical growth trends and anticipated future demand drivers. Key industry-specific forecast inputs included surgical procedure volumes and government investment in healthcare infrastructure, particularly in China.
Stress conditions across regulatory policy shifts, capital expenditure cycles, and technological disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding market dynamics and macroeconomic stability. Unforeseen geopolitical events or major economic downturns represent specific risk factors that could revise these projections. Cross-checking against national health expenditure data and major medical device manufacturer earnings reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Endovenous Ablation Devices Market
Medical Devices
Tinnitus Maskers Market
Medical Devices
Asia-Pacific Digital Dentistry Market
Medical Devices
Robot Assisted PCI Market
Medical Devices
Nephrostomy Catheters Market
Medical Devices
Global Medical Device Security Market
Medical Devices
Digital Body Thermometer Market
Medical Devices
Pulmonary Function Testing System Market
Medical Devices
Ventricle Assist Device Market
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
Japan Minimally Invasive Surgery Devices Market
Medical Devices
Cardiac Implants Market
Medical Devices
Supraglottic Airway Devices Market
Medical Devices
Guide Extension Catheter Market
Medical Devices
Global Cast Saw Devices Market