
 Microcapsules Market | 2026-2036
Microcapsules Market Size, Share, and Industry Trends Forecast 2026-2036
Microcapsules Market Foresight
Specialty chemical producers in Germany is rebalancing capacity toward pharmaceutical-grade shell polymers after feedstock volatility disrupted coating material supply. BASF SE leverages its integrated polymer precursor chain to secure captive supply of methacrylate-based shell chemistries. Evonik Industries AG anchors high-barrier lipid microcapsule output through RESOMER platform specialization. Givaudan SA competes in flavor-encapsulation niches where thermal stability requirements exceed standard spray-dried offerings.
Microcapsules are engineered particles with diameters typically ranging from one to one thousand micrometers, comprising a core material surrounded by a protective shell of polymer, lipid, or inorganic composition, produced via coacervation, spray drying, or solvent evaporation processes to enable controlled release, taste masking, or environmental protection of sensitive actives. Polymeric microcapsules dominate value pools due to tunable degradation kinetics that align with extended-release pharmaceutical dosing regimens. Lipid microcapsules are gaining formulation share in cosmetics where biocompatibility and skin-permeation properties outweigh mechanical durability requirements. Hybrid architectures that combine polymer and lipid layers command premium positioning in oncology applications demanding both gastric resistance and targeted dissolution.
EPA registration requirements for encapsulated agrochemicals and FDA dissolution standards for oral dosage forms shape shell-material selection and validation protocols for entrants targeting North American supply chains. REACH substance authorization and EMA quality guidelines impose equivalent compliance burdens across European manufacturing and import channels. Stakeholders must monitor evolving FDA guidance on complex generic equivalence for multiparticulate formulations, as bioequivalence demonstration methods will determine which microcapsule platforms qualify for abbreviated approval pathways.
Market Dynamics
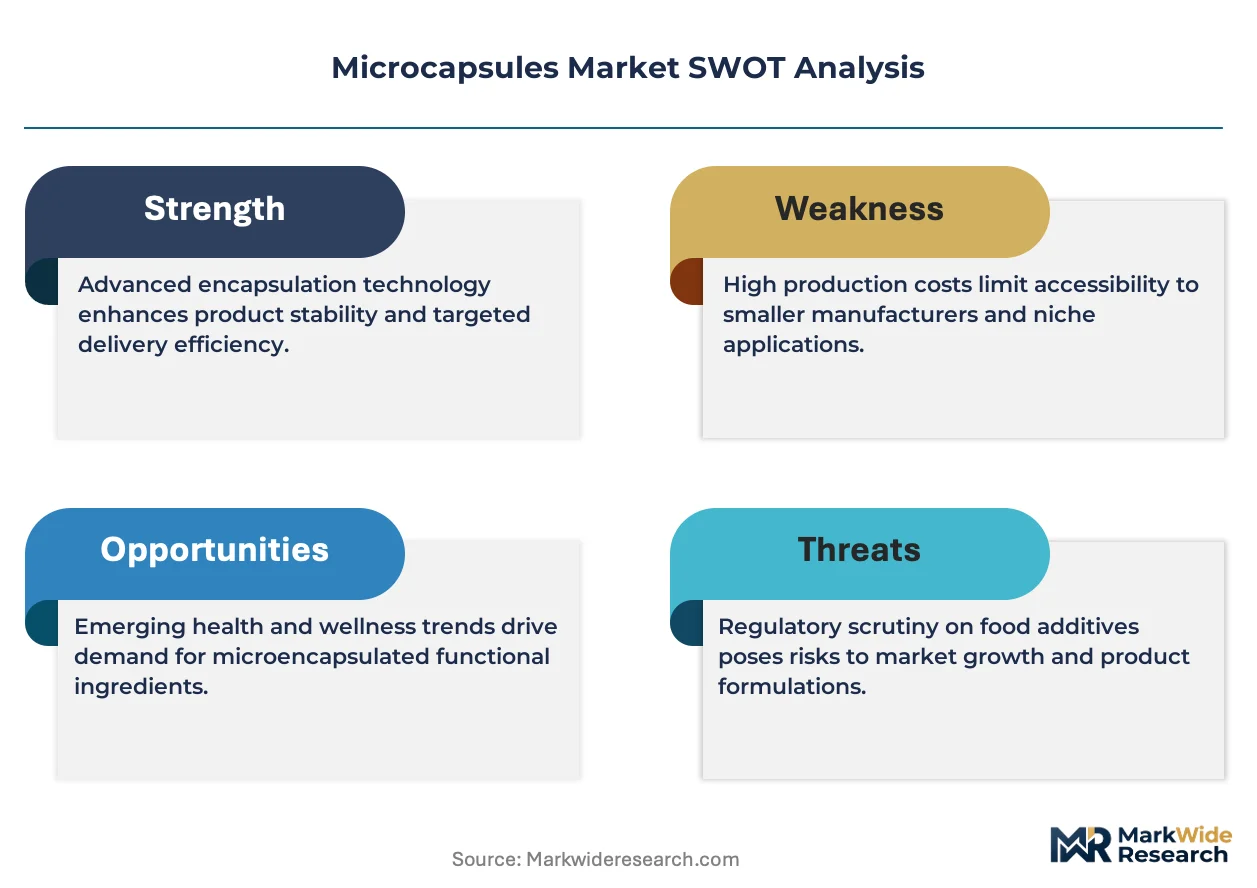
Shell material purity benchmarks are tightening across pharmaceutical and agrochemical channels, forcing formulators to revalidate polymer precursors against evolving EPA and REACH substance authorization protocols. This regulatory compression is reshaping supplier qualification timelines and captive supply strategies for methacrylate and lipid-based architectures.
Growth Catalysts
- Pharmaceutical extended-release dosing:Oral dosage form developers are expanding multiparticulate platforms to improve patient compliance through tunable degradation kinetics.
- REACH substance authorization:European shell material mandates are accelerating substitution toward pharmaceutical-grade polymer precursors with documented safety profiles.
- Oncology gastric resistance requirements:Targeted dissolution specifications for chemotherapy delivery are pulling hybrid polymer-lipid architectures into clinical formulation pipelines.
Market Restraints
- Feedstock volatility in coating materials:Methacrylate monomer price swings are compressing margin stability for specialty polymer producers.
- High-barrier lipid supply concentration:Pharmaceutical-grade lipid microcapsule output clusters among integrated German chemical producers with captive precursor chains.
- Complex generic bioequivalence demonstration:FDA dissolution standards for multiparticulate formulations are extending validation timelines for abbreviated approval pathways.
Strategic Opportunities
- Cosmetics biocompatibility positioning:Skin-permeation properties of lipid microcapsules are opening formulation share in premium dermal delivery systems.
- Flavor-encapsulation thermal stability niches:Food and beverage applications exceeding standard spray-dried performance are creating premium positioning for engineered shell architectures.
- Agrochemical EPA registration tailwinds:Encapsulated pesticide formulations are gaining preference as environmental protection mandates tighten active ingredient runoff controls.
Industry Challenges
- Multiparticle bioequivalence methodology gaps:FDA guidance evolution on complex generic equivalence is creating uncertainty for platform qualification investments.
- Cross-functional formulation expertise scarcity:Integration of polymer science, pharmacokinetics, and regulatory affairs competencies is bottlenecking development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microcapsules Market |
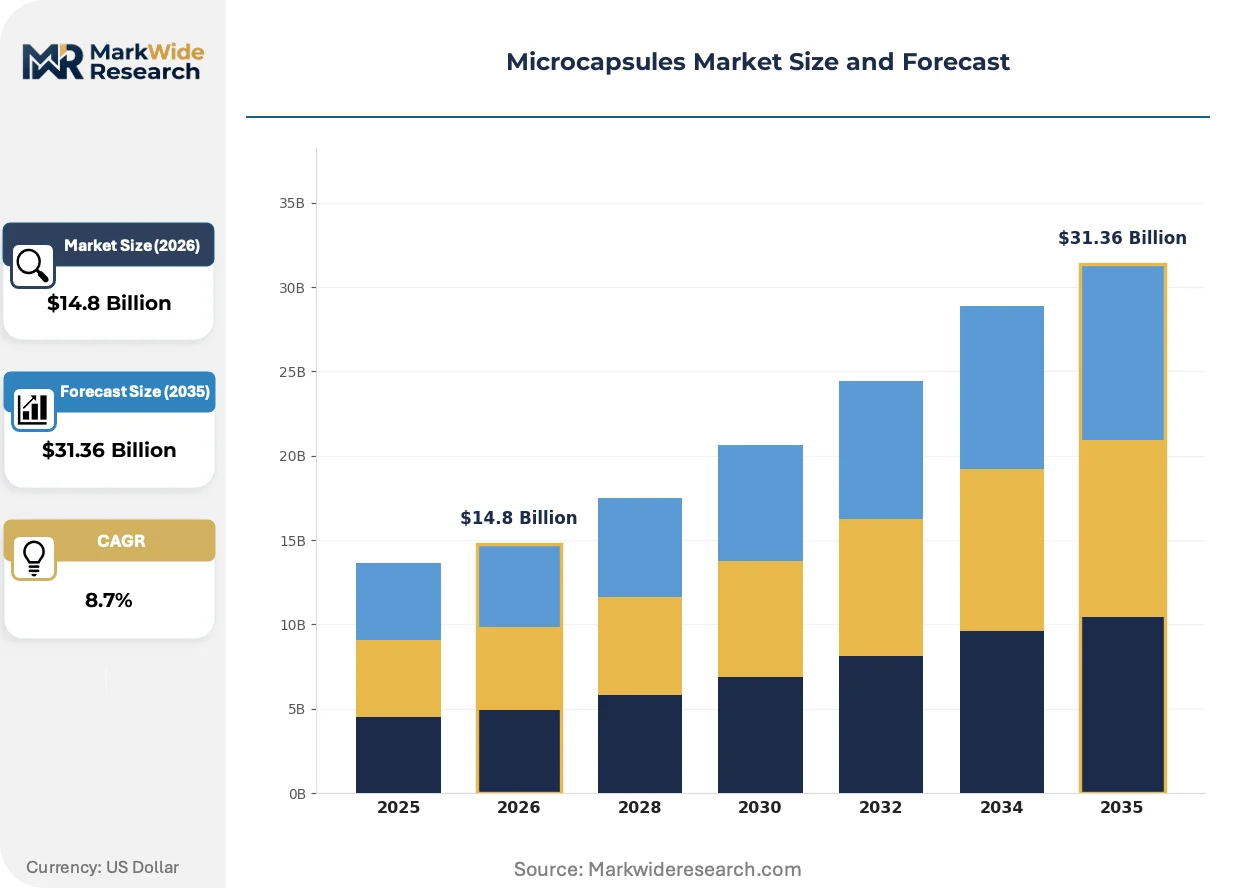
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric Microcapsules, Lipid Microcapsules, Hybrid Microcapsules, Inorganic Microcapsules Application: Pharmaceuticals, Food Processing, Cosmetics, Agriculture End User: Healthcare Providers, Food Manufacturers, Cosmetic Brands, Agricultural Suppliers Technology: Spray Drying, Coacervation, Solvent Evaporation, Emulsion Method |
| Companies Covered | BASF SE, Evonik Industries AG, Givaudan SA, International Flavors & Fragrances Inc., Balchem Corporation, LycoRed Group, Kraton Corporation, FMC Corporation, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microcapsules Market Shifts & Advancements
Continuous processing technologies are displacing batch manufacturing in shell formation, while regulatory data requirements for novel architectures are expanding validation documentation burdens. These shifts are compressing development economics and redrawing competitive capabilities.
Microfluidic shell formation is decentralizing production geography for pharmaceutical-grade microcapsules. Regional contract manufacturing clusters in Germany, China, and the United States are adopting chip-based emulsification to reduce minimum efficient scale for clinical batch production. This technology is decentralizing capacity ownership away from integrated multinational chemical producers toward specialized formulation service providers with lower capital intensity.
EPA registration requirements for encapsulated agrochemicals are tightening environmental fate study protocols for shell material degradation products. The agency's expanded data requirements for non-target organism exposure are extending registration timelines by 18-24 months for novel polymer chemistries. Agrochemical formulators are responding by reverting to established shell materials with existing ecological toxicology dossiers rather than pioneering novel architectures.
Pharmaceutical procurement teams are consolidating supplier panels for critical shell polymers to reduce qualification overhead. Large molecule developers are shifting from spot purchasing toward multi-year supply agreements with integrated polymer producers offering regulatory documentation packages. This concentration is most visible in Germany, where BASF and Evonik anchor regional supply through captive methacrylate and lipid precursor chains.
Microcapsules Market Segmentation
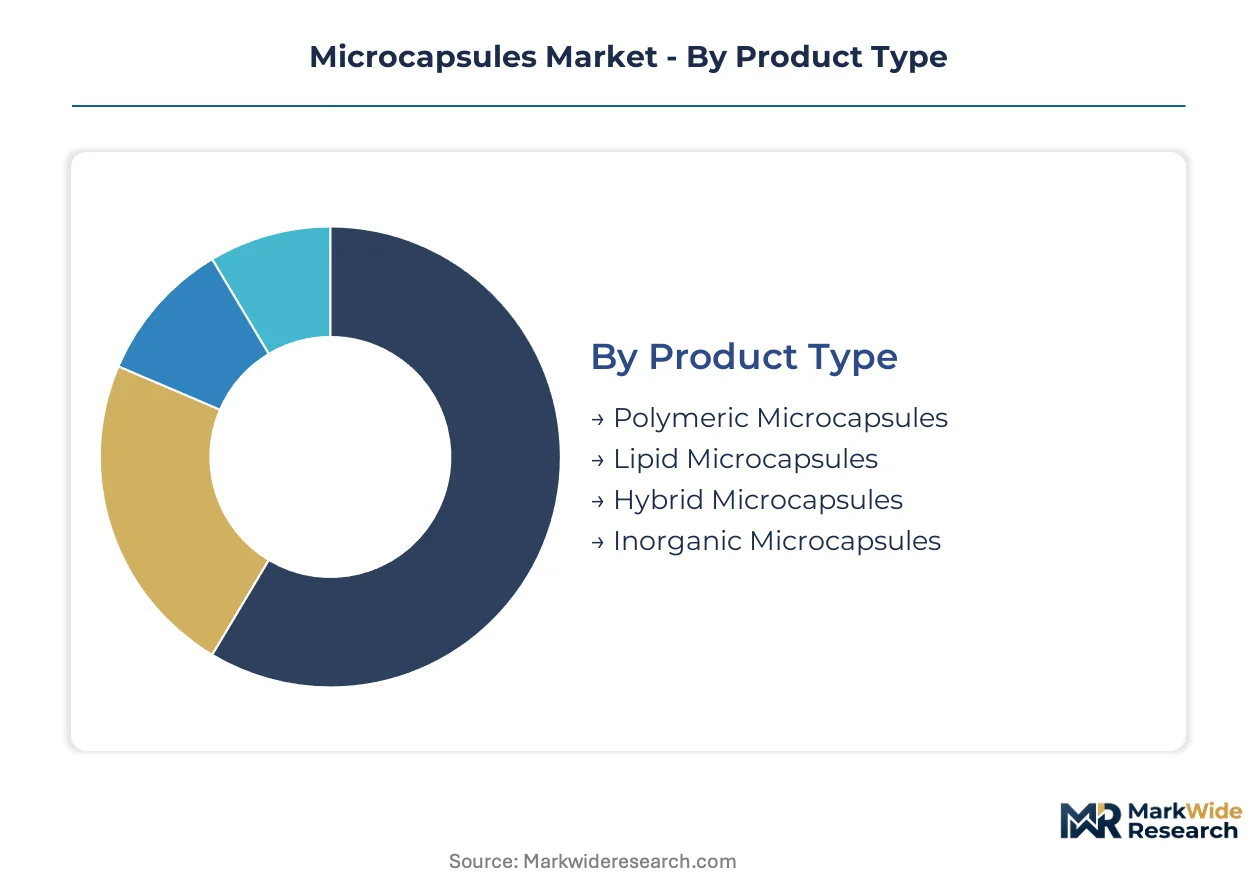
Segmentation in the microcapsules market reveals how shell material selection and processing technology determine access to high-margin therapeutic categories. Formulators align product architecture with regulatory pathways and end-use performance requirements.
Product Type:
Replacement cycles in pharmaceutical formulation are shortening as developers pursue differentiated release profiles through next-generation shell architectures.
- Polymeric Microcapsules:These engineered particles employ methacrylate, cellulose, or biodegradable polyester shells with tunable degradation kinetics calibrated to extended-release dosing regimens. Demand concentrates among oral dosage form developers in Germany and the United States seeking FDA dissolution standard compliance for multiparticulate platforms.
- Lipid Microcapsules:Comprising phospholipid or triglyceride shell matrices, these architectures prioritize biocompatibility and skin-permeation properties over mechanical durability. Cosmetics formulators in France and Switzerland are expanding procurement of pharmaceutical-grade lipid microcapsules for premium dermal delivery systems where EMA quality guidelines govern material qualification.
- Hybrid Microcapsules:Layered polymer-lipid constructions command premium positioning in oncology applications requiring simultaneous gastric resistance and targeted dissolution.
- Inorganic Microcapsules:Silica or calcium carbonate shells serve agrochemical and industrial applications where environmental stability outweighs biodegradability requirements.
Volume placements concentrate in polymeric architectures; the faster expansion belongs to hybrid configurations.
Application:
Cost tier differentiation separates commodity encapsulation from validated pharmaceutical-grade supply chains with regulatory documentation packages.
- Pharmaceuticals:Oral and parenteral dosage forms employ microcapsules for taste masking, controlled release, and targeted delivery of sensitive actives. Developers in the United States navigate FDA bioequivalence demonstration requirements for complex generic multiparticulate formulations.
- Food Processing:Thermal stability requirements for flavor encapsulation exceed standard spray-dried performance, pulling engineered shell architectures into premium positioning.
- Cosmetics:Skin-permeation properties of lipid-based systems are opening formulation share in premium dermal delivery where biocompatibility certification commands price premiums.
- Agriculture:Encapsulated pesticide formulations are gaining preference as EPA registration requirements tighten active ingredient runoff controls and environmental fate study protocols.
Revenue concentration sits with pharmaceutical applications; cosmetics represents the segment climbing fastest.
End User:
Customer type determines procurement sophistication, with integrated healthcare systems demanding captive supply agreements that spot purchasers cannot match.
- Healthcare Providers:Hospital networks and specialty pharmacies source microencapsulated oncology and extended-release formulations through consolidated supplier panels with multi-year supply agreements.
- Food Manufacturers:Beverage and confectionery producers specify engineered shell architectures where thermal stability during processing exceeds standard spray-dried offerings.
- Cosmetic Brands:Premium skincare lines in France and Switzerland qualify pharmaceutical-grade lipid microcapsule suppliers against EMA quality guidelines for dermal biocompatibility.
- Agricultural Suppliers:Formulators navigate EPA registration timelines extended by expanded environmental fate study protocols for novel polymer chemistries.
Procurement scale favors healthcare providers; cosmetic brands are expanding their share of qualified supplier capacity most aggressively.
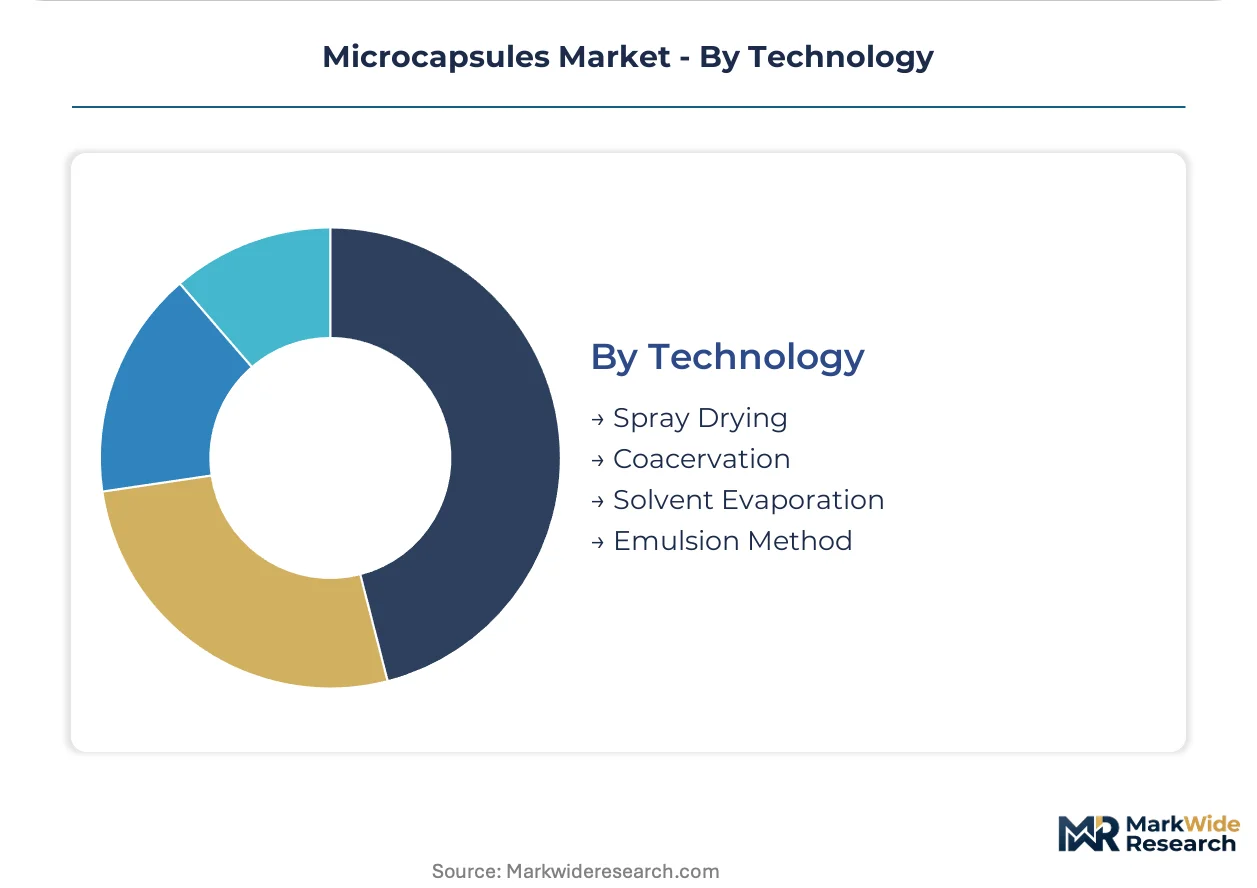
Technology:
Process maturity separates high-throughput commodity production from clinical-batch precision manufacturing with lower minimum efficient scale.
- Spray Drying:Atomization of core-shell emulsions against heated air streams delivers cost-efficient encapsulation for food and agrochemical volumes where thermal stability requirements are moderate.
- Coacervation:Phase separation of hydrocolloid polymers around core materials enables precise shell thickness control for pharmaceutical applications demanding narrow release profile specifications.
- Solvent Evaporation:Oil-in-water emulsion systems with controlled organic solvent removal serve biodegradable polyester microcapsule production for parenteral depot formulations.
- Emulsion Method:Microfluidic chip-based emulsification is decentralizing production geography for pharmaceutical-grade microcapsules with reduced capital intensity requirements.
Installed capacity concentrates in spray drying; microfluidic emulsion methods are gaining share fastest among contract manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Methacrylate monomer production clusters in Germany and the United States anchor pharmaceutical-grade shell polymer supply chains. Lipid precursor refining concentrates in Switzerland and France. Formulation demand disperses across therapeutic manufacturing hubs in China, India, and Brazil.
United States
Oral dosage form developers in New Jersey and Massachusetts drive multiparticulate platform expansion for extended-release regimens. FDA dissolution standards for complex generic bioequivalence demonstration extend validation timelines for abbreviated approval pathways. Philadelphia-area contract manufacturing clusters adopt microfluidic emulsification to reduce clinical batch production scale requirements.
Germany
Specialty chemical producers in Ludwigshafen and Marl rebalance capacity toward pharmaceutical-grade methacrylate shell polymers after feedstock volatility disrupted coating material supply. REACH substance authorization protocols accelerate substitution toward polymer precursors with documented safety profiles. Bavarian formulation service providers integrate RESOMER platform specialization for high-barrier lipid microcapsule output.
China
Domestic pharmaceutical formulators in Jiangsu and Zhejiang provinces expand encapsulated active ingredient uptake for oncology and chronic disease portfolios. NMPA quality guidelines for multiparticulate dosage forms shape shell-material selection and import validation protocols. Shanghai-based contract manufacturing clusters serve regional demand through spray drying and coacervation process capabilities.
Switzerland
Premium cosmetic brands in Geneva and Basel qualify pharmaceutical-grade lipid microcapsule suppliers against EMA quality guidelines for dermal biocompatibility certification. Swissmedic oversight of medical device-grade encapsulation materials commands price premiums in skin-permeation applications. Basel-area chemical producers leverage integrated phospholipid precursor chains for captive lipid microcapsule supply.
Brazil
Agricultural suppliers in São Paulo and Paraná navigate ANVISA-equivalent state-level environmental fate study protocols for encapsulated pesticide formulations. Encapsulated agrochemicals gain preference as runoff control mandates tighten active ingredient environmental protection requirements. Campinas formulation clusters serve South American agrochemical demand through established polymer shell materials with existing ecological toxicology dossiers.
Microcapsules Market Competitive Landscape
Global majors compete with regional champions across shell material supply and formulation service delivery. The vendor base stratifies between integrated chemical producers with captive precursor chains and specialized contract manufacturers with microfluidic processing capabilities. Three archetypes dominate: polymer science specialists with backward integration into methacrylate monomers, lipid platform developers with pharmaceutical-grade certification, and flavor-encapsulation niche players with thermal stability engineering. Competitive moves concentrate on multi-year supply agreement consolidation and microfluidic technology licensing to regional clusters.
Within the integrated chemical producer tier, BASF SE and Evonik Industries AG exemplify the polymer precursor control archetype. Givaudan SA occupies a position representing flavor-encapsulation specialization where engineered shell architectures exceed standard spray-dried performance thresholds. These three entities anchor distinct competitive vectors: methacrylate-based shell chemistries, high-barrier lipid platforms, and thermal stability niches respectively.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Givaudan SA |
| International Flavors & Fragrances Inc. |
| Balchem Corporation |
| LycoRed Group |
| Kraton Corporation |
| FMC Corporation |
| Clariant AG |
| Others |
Supply & Pricing Matrix
Integrated pharmaceutical formulators in Germany and the United States anchor procurement scale for pharmaceutical-grade shell polymers, concentrating volume leverage around multi-year supply agreements with documented REACH and FDA compliance packages. This buyer concentration feeds a contract-based pricing architecture where regulatory documentation bundling commands premium positioning over spot-market commodity grades.
Pricing Analysis
Regulatory validation services are unbundled from base polymer pricing, with EMA quality guideline documentation and EPA ecological toxicology dossiers priced as separate line items. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and industrial-grade shell materials reflects certification level and degradation kinetics precision. Pricing pressure stems from methacrylate monomer feedstock volatility compressing margin stability for specialty polymer producers. Agrochemical formulators exhibit highest price sensitivity due to extended EPA registration timelines, while oncology developers accept premium positioning for hybrid polymer-lipid architectures with gastric resistance specifications.
Supply Chain Analysis
Regional distribution centers in Ludwigshafen, Philadelphia, and Shanghai coordinate hub-and-spoke patterns for methacrylate monomers, phospholipid precursors, and biodegradable polyesters. Manufacturing concentration clusters in Germany, the United States, and China, with Swiss and French refineries anchoring pharmaceutical-grade lipid output. Raw material dependencies center on petrochemical-derived methacrylates, plant-sourced phospholipids, and specialty solvents for coacervation processes. Single-source vulnerability runs through integrated German chemical producers with captive precursor chains. Distribution runs through contract manufacturing clusters serving regional pharmaceutical and agrochemical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microfluidic emulsification is displacing batch manufacturing for clinical-scale shell formation, rendering legacy spray-drying capacity economically marginal for pharmaceutical-grade output. Formulators must revalidate technology platforms against this processing transition.
For Market Incumbents: Deploy captive precursor chain control to secure methacrylate and phospholipid supply against feedstock volatility. BASF SE and Evonik Industries AG exemplify backward integration into monomer production that buffers margin compression. Incumbents should consolidate multi-year supply agreements with large molecule developers before microfluidic decentralization erodes volume leverage. The threat of specialized formulation service providers with lower capital intensity demands defensive positioning around regulatory documentation depth. For New Entrants and Emerging Players: Launch via microfluidic contract manufacturing partnerships to bypass minimum efficient scale barriers in pharmaceutical-grade production. White-space targets include premium cosmetic dermal delivery systems in Switzerland and France, where EMA quality guideline compliance creates qualification barriers incumbents have underinvested against. Agrochemical encapsulated pesticide formulations in Brazil offer penetrable volume with established shell material dossiers reducing registration risk. Direct-to-cosmetic-brand positioning bypasses healthcare procurement consolidation. For Investors and Strategic Acquirers: The window for entry favors specialized contract manufacturers with microfluidic capabilities and regulatory documentation packages over integrated chemical producers with legacy batch assets. Long-term viability hinges on platform flexibility across polymer, lipid, and hybrid architectures. Acquisition targets should demonstrate RESOMER-equivalent lipid platform specialization or methacrylate-based shell chemistry depth. Watch FDA guidance evolution on complex generic bioequivalence demonstration as the signal for which microcapsule platforms qualify for abbreviated approval pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methacrylate Monomers | BASF SE secures captive supply against feedstock volatility disrupting coating material availability. |
| Microfluidic Emulsification Licensing | Regional clusters in Philadelphia and Shanghai reduce clinical batch production scale requirements. |
| REACH Substance Authorization Pre-Compliance | German producers accelerate substitution toward polymer precursors with documented safety profiles. |
| Hybrid Architecture R&D Partnership | Oncology applications pull polymer-lipid constructions into clinical formulation pipelines. |
| Multi-Year Supply Agreement Consolidation | Large molecule developers shift from spot purchasing toward documented regulatory packages. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with pharmaceutical formulation executives, regulatory affairs leads at shell polymer suppliers, contract manufacturing procurement managers, and agrochemical registration specialists combined with secondary validation. FDA dissolution standard documentation, EMA quality guideline submissions, EPA ecological toxicology dossiers, and REACH substance authorization records provided regulatory pathway data. Bottom-up volume modeling across shell material types and top-down market sizing triangulated demand estimates.
Granularity-level modeling captured polymeric, lipid, hybrid, and inorganic microcapsule architectures across pharmaceutical, cosmetic, food processing, and agricultural end uses. Technology dimensions including spray drying, coacervation, solvent evaporation, and microfluidic emulsification were projected across the analysis window. CAGRs derived from segment-level growth rate reconciliation against macro pharmaceutical and agrochemical output trends. Forecast inputs included NMPA quality guideline adoption timelines in China and evolving FDA guidance on complex generic bioequivalence methodology.
Feedstock volatility in methacrylate monomers, EPA registration timeline extensions for novel polymer chemistries, and FDA guidance uncertainty on multiparticulate bioequivalence demonstration are the dominant revision risks. Forecasts reflect documented assumptions on regulatory pathway evolution and technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Quinoline Yellow WS Market
Specialty Compounds
Compounds Market
Specialty Compounds
Putty Fillers Market
Specialty Compounds
GCC Specialty Chemicals Market
Specialty Compounds
Chromium Phosphate Market
Specialty Compounds
Superacids Market
Specialty Compounds
Global Sulfur Hexafluoride Market
Specialty Compounds
Potting Compound Market
Specialty Compounds
Global Specialty Polymer Market
Specialty Compounds
Additive Masterbatch Market
Specialty Compounds
Global Specialty Oilfield Chemicals Market
Specialty Compounds
Asia-Pacific Chromatography Resins Market
Specialty Compounds
Global Specialty Zeolites Market
Specialty Compounds
Global Color Masterbatch Market
Specialty Compounds
Ready Mix Joint Compound Market
Specialty Compounds
Chemical Hardener Compounds Market