
 Global Antifreeze Market | 2026-2036
Global Antifreeze Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antifreeze Market Analysis
Fleet procurement among commercial transport operators is consolidating around fewer, larger maintenance providers with national service contracts. BASF SE leverages its integrated ethylene oxide supply chain to control raw material costs across major automotive programs. ExxonMobil Corporation sustains brand loyalty through proprietary additive packages certified by OEM thermal management specifications. Valvoline Inc. competes aggressively in the aftermarket channel through direct partnerships with quick-lube networks and independent repair shops.
Antifreeze denotes a heat-transfer fluid formulated from glycol bases, corrosion inhibitors, and buffer compounds, typically mixed with water in ratios between 40:60 and 60:40 to depress freezing points below minus 37 degrees Celsius and elevate boiling points above 129 degrees Celsius. Its primary commercial purpose is protecting closed-loop cooling systems in combustion engines, industrial process equipment, and thermal storage installations from temperature extremes and metallic corrosion. Ethylene glycol formulations continue to dominate volume shipments across automotive and heavy-duty applications, though propylene glycol alternatives are gaining structural share in food-processing equipment and residential HVAC systems where toxicity exposure poses liability concerns. The OEM end-user segment commands premium pricing through factory-fill contracts and warranty-aligned specifications, while maintenance providers represent the fastest-growing channel as vehicle age profiles extend average service intervals.
The EPA regulates glycol disposal and workplace exposure limits under Clean Water Act provisions, while REACH mandates full chemical disclosure and hazard classification for products entering European Economic Area markets. China's SAMR enforces GB standards for coolant performance and labeling, creating divergent compliance burdens for multinational formulators. India's BIS certification requirements for automotive chemicals are tightening import quality gates. Stakeholders must monitor regulatory divergence between major economies when configuring regional product portfolios and manufacturing footprints.
Market Dynamics
The transition from internal combustion engines to electric vehicle thermal architectures is fundamentally restructuring glycol coolant demand, as battery thermal management systems require larger fluid volumes and specialized low-conductivity formulations.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases is redirecting industrial refrigeration users toward glycol-based secondary loop systems, expanding addressable market beyond automotive applications.
- Extended vehicle service intervals:Aging vehicle parc in Germany and the United States is stretching replacement cycles, concentrating demand at commercial fleet maintenance providers with centralized procurement.
- Ethylene oxide supply chain regionalization:Integrated petrochemical complexes in China and the Middle East are capturing upstream glycol production, lowering landed costs for regional formulators.
Market Restraints
- Ethylene glycol price volatility:Feedstock costs track naphtha and ethylene cracker margins, compressing blender margins during upstream supply disruptions.
- Propylene glycol substitution:Food-processing equipment and residential HVAC systems are migrating to less toxic alternatives, eroding glycol volume in regulated indoor environments.
- REACH compliance burden:Full chemical disclosure requirements and hazard reclassification timelines are extending product registration cycles for European Economic Area entry.
Strategic Opportunities
- India BIS certification tightening:Stricter import quality gates for automotive chemicals are creating first-mover advantages for compliant domestic manufacturing investments.
- Data center liquid cooling:Hyperscale computing facilities are adopting glycol-water loops for direct-to-chip thermal management, opening a high-purity formulation segment.
- China dual carbon goals:National emissions intensity targets are incentivizing closed-loop coolant recycling infrastructure and reclaimed glycol refinement capacity.
Industry Challenges
- Electrification skill gaps:Formulation chemists with dielectric fluid compatibility expertise remain scarce as OEM thermal specifications diverge from legacy combustion engine standards.
- Multi-jurisdiction labeling complexity:Divergent hazard communication requirements between EPA Clean Water Act provisions, REACH classification, and China's GB standards force SKU proliferation.
- Legacy system integration:Industrial process equipment with decades-old metallurgy requires backward-compatible inhibitor packages, constraining formulation innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antifreeze Market |
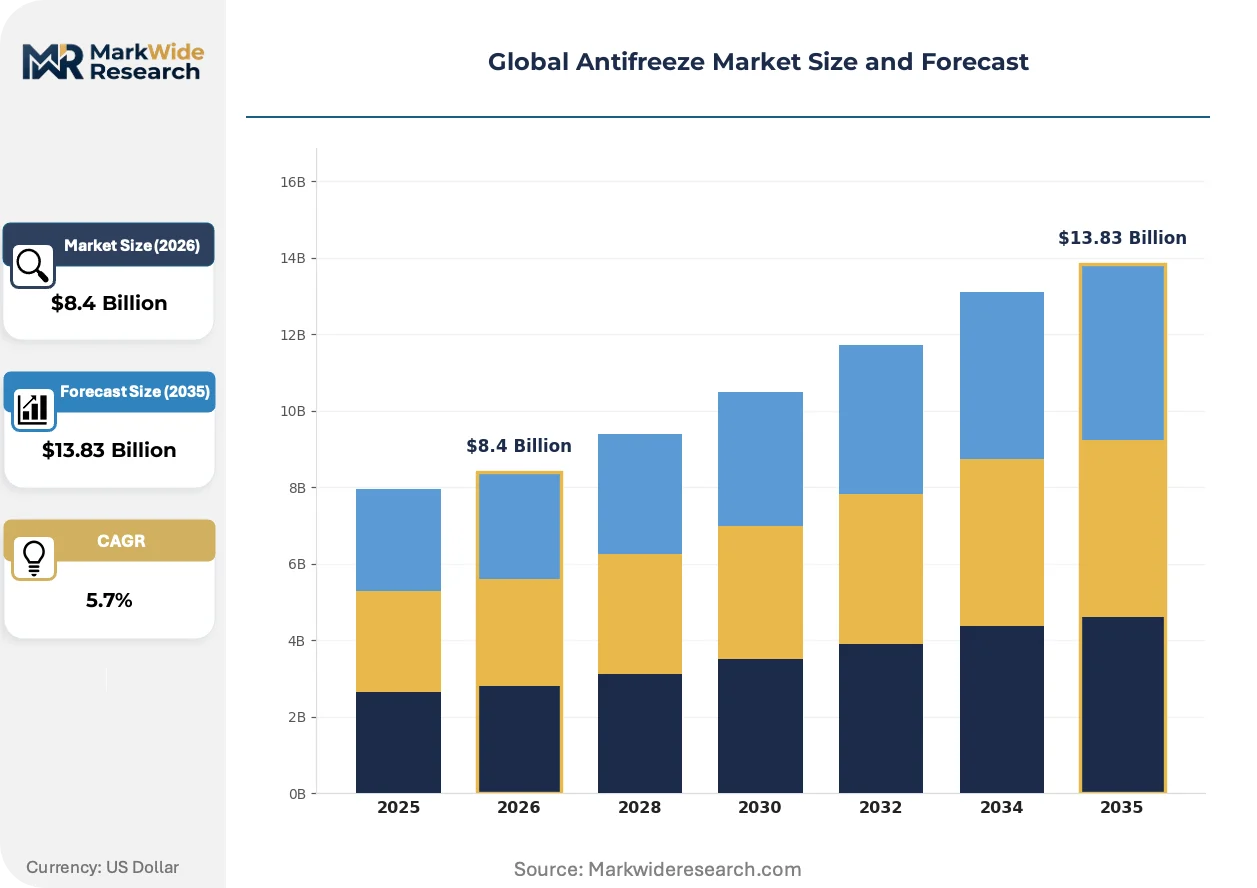
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene Glycol, Propylene Glycol, Glycerin, Others Application: Automotive, Industrial, Marine, HVAC End User: Households, Commercial, OEMs, Maintenance Providers Distribution Channel: Retail, Online, Wholesale, Direct Sales |
| Companies Covered | BASF SE, ExxonMobil Corporation, Royal Dutch Shell plc, Chevron Corporation, TotalEnergies SE, Valvoline Inc., Old World Industries, LLC, Prestone Products Corporation, Sinopec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antifreeze Market Emerging Trajectories
Electrification is fragmenting thermal management specifications, as battery electric vehicles, hybrid architectures, and residual combustion fleets each demand distinct coolant chemistries and performance envelopes.
Low-electrical-conductivity glycol formulations are absorbing the functional requirements previously served by dedicated dielectric fluids in battery pack cooling circuits. EV OEMs in China and Germany are adopting these hybrid chemistries to simplify thermal loop architecture. The technology is absorbing market share from silicone-based and fluorinated alternatives in premium electric vehicle segments.
REACH authorization procedures and the EU F-Gas Regulation are tightening chemical hazard thresholds and refrigerant containment standards simultaneously. Industrial process operators face overlapping compliance deadlines for coolant replacement and secondary loop redesign. Food-processing and pharmaceutical manufacturing facilities in Europe are responding with consolidated chemical management audits and supplier consolidation.
Fleet operators are unbundling factory-fill specifications from aftermarket service decisions, creating procurement autonomy at the maintenance provider level. National service contracts with quick-lube networks and independent repair shops are displacing dealer-captive service models in the United States commercial transport segment. This pattern is most visible in long-haul trucking and last-mile delivery fleets where vehicle age profiles exceed seven years.
Global Antifreeze Market Segmentation
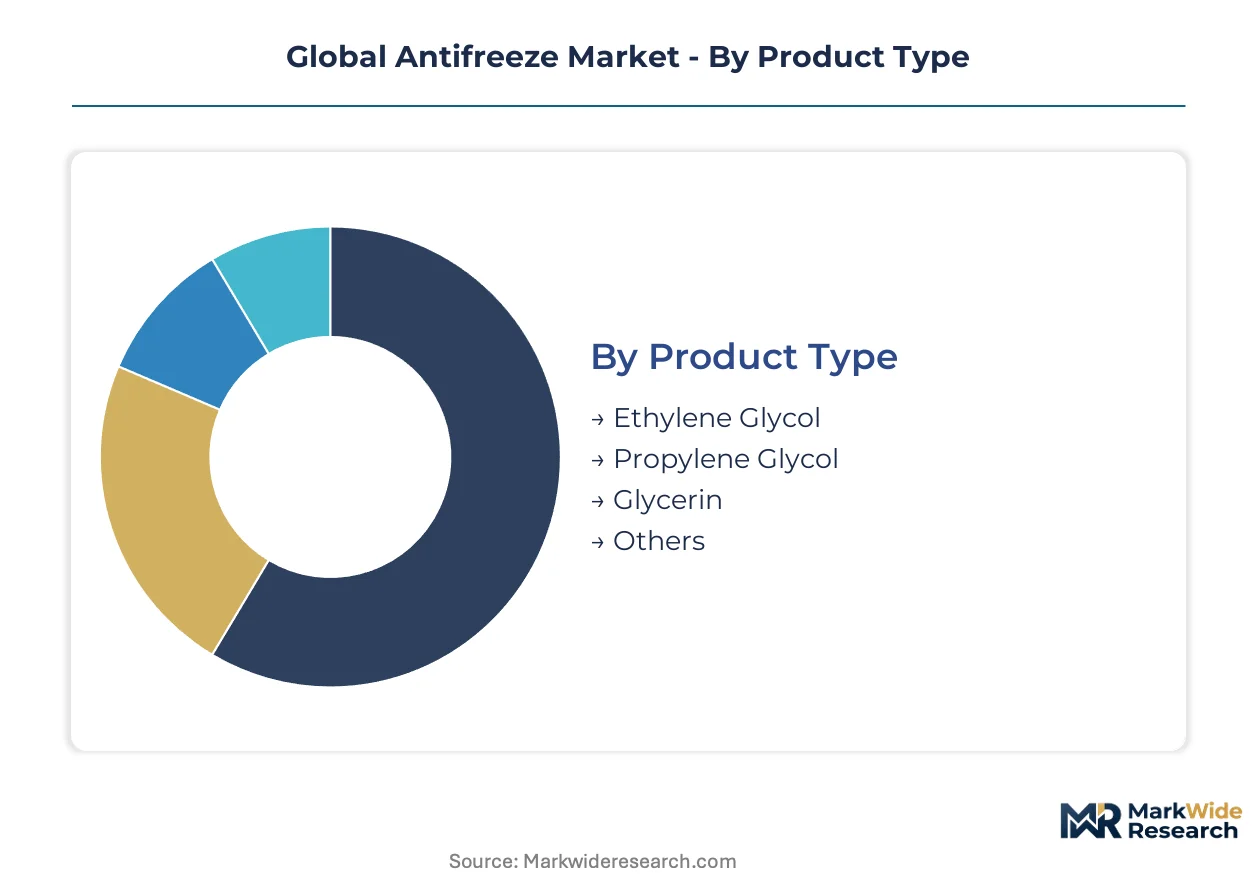
Antifreeze procurement patterns diverge sharply between factory-fill programs and aftermarket replacement cycles. Understanding segment-level demand drivers reveals where formulation investments generate returns and where price competition dominates.
Product Type:
Upgrade cycles vary by toxicity exposure risk and metallurgical compatibility requirements across end-use environments.
- Ethylene Glycol:Formulations based on ethylene oxide deliver superior heat transfer coefficients and freeze protection economics. Automotive OEMs in Germany and China specify this chemistry for combustion engine and battery thermal management systems where human exposure risk remains contained within sealed loops. REACH registration burdens and workplace exposure limits constrain formulation flexibility in European Economic Area markets.
- Propylene Glycol:Recognized as GRAS (Generally Recognized As Safe) by the FDA, this chemistry penetrates food-processing equipment and residential HVAC systems where incidental human contact probability exceeds acceptable thresholds for ethylene glycol toxicity. Food-grade certification from the country's national pharmaceutical regulator opens institutional procurement channels in North American and European markets.
- Glycerin:Biobased feedstock compatibility aligns with renewable content mandates in EU member states and certain US state-level procurement preferences.
- Others:Specialized diol chemistries serve niche aerospace and military applications with extreme temperature performance requirements.
Volume placements concentrate in Ethylene Glycol; the faster expansion belongs to Propylene Glycol.
Application:
Cost tier differentiation separates premium factory-fill specifications from commodity aftermarket replacements.
- Automotive:Combustion engine coolants, battery thermal management fluids, and hybrid system heat-transfer media. OEMs in China and Germany are redesigning cooling architectures for electric vehicle platforms, expanding glycol volume per vehicle while demanding low-electrical-conductivity formulations.
- Industrial:Process cooling, secondary refrigeration loops, and thermal storage systems. EU F-Gas Regulation phasedown is redirecting industrial refrigeration users toward glycol-based secondary loop systems, displacing fluorinated refrigerants in European manufacturing facilities.
- Marine:Closed-loop engine cooling and potable water system freeze protection for commercial shipping and recreational vessels.
- HVAC:Geothermal heat pumps, solar thermal collectors, and hydronic heating distribution networks. Residential installations in Germany and the United States favor propylene glycol formulations for toxicity risk mitigation.
Automotive commands the dominant volume position; industrial applications are climbing the fastest as F-Gas compliance deadlines approach.
End User:
Customer type determines specification authority and procurement consolidation patterns.
- OEMs:Factory-fill contracts with automakers and equipment manufacturers carry warranty-aligned performance specifications and multi-year supply agreements. BASF SE and ExxonMobil Corporation compete for thermal management program approvals through proprietary additive packages.
- Maintenance Providers:National service contracts with quick-lube networks and independent repair shops are displacing dealer-captive service models. Fleet operators in the United States commercial transport segment unbundle factory-fill specifications from aftermarket decisions, creating procurement autonomy at the maintenance provider level.
- Commercial:Industrial process operators, data center operators, and fleet maintenance departments with centralized chemical procurement.
- Households:Do-it-yourself automotive service and residential HVAC system maintenance through retail and online channels.
OEMs retain pricing power through specification control; maintenance providers are gaining share fastest as vehicle age profiles extend.
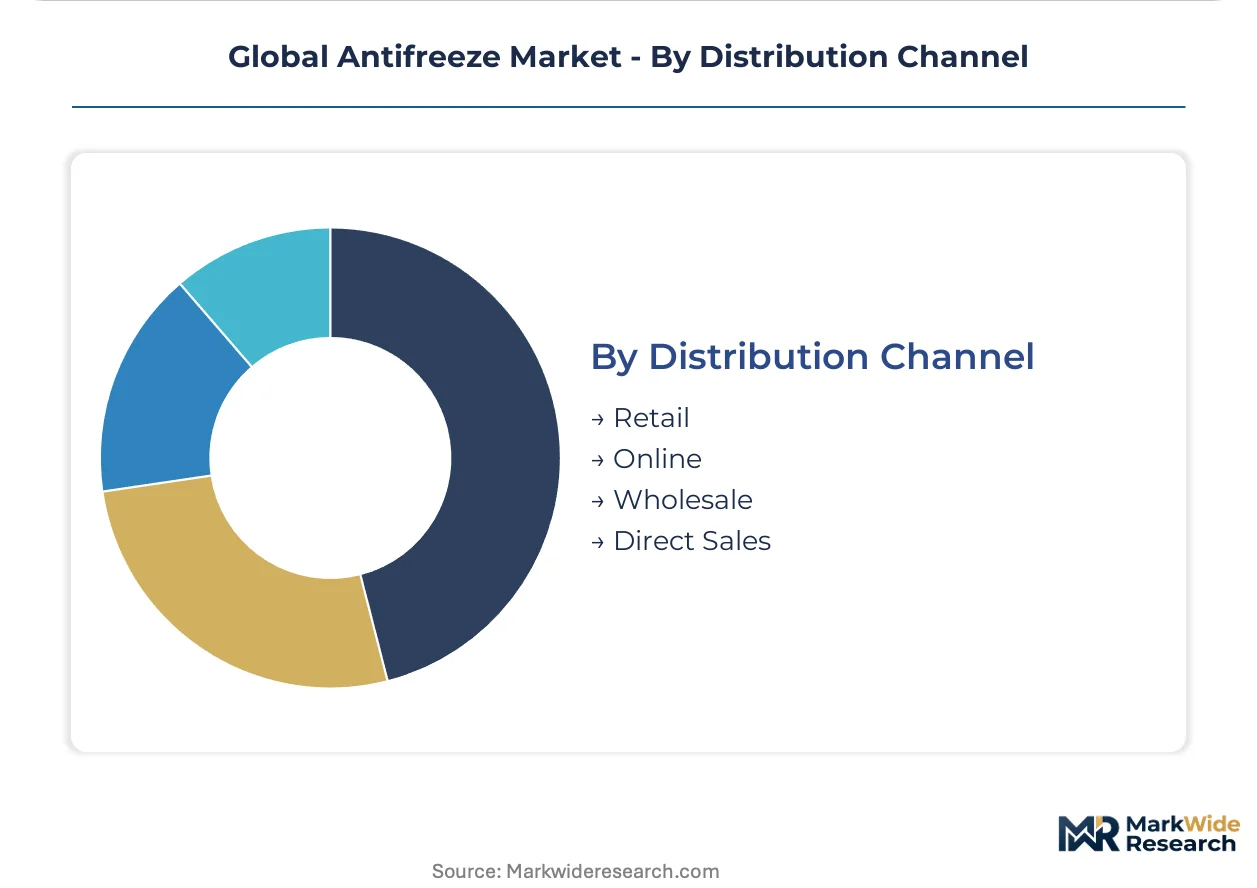
Distribution Channel:
Supply concentration varies by customer scale and urgency requirements.
- Wholesale:Bulk deliveries to industrial process operators, fleet maintenance depots, and national service contract holders. Valvoline Inc. competes aggressively through direct partnerships with quick-lube networks.
- Direct Sales:Factory-fill programs and large industrial accounts with dedicated technical service support.
- Retail:Automotive parts stores, home improvement centers, and farm supply cooperatives serving household and small commercial accounts.
- Online:E-commerce platforms capturing specification-conscious buyers with detailed technical documentation and bulk pricing transparency.
Wholesale handles the largest volume throughput; online channels are expanding most quickly among specification-savvy procurement officers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene oxide feedstock availability clusters near integrated petrochemical complexes in China, the Middle East, and the US Gulf Coast, shaping regional formulation economics and trade flows for glycol-based coolants.
China
Domestic automakers and battery manufacturers in Shanghai and Shenzhen are scaling thermal management fluid volumes per vehicle as EV platforms proliferate. SAMR enforces GB standards for coolant performance and labeling, tightening quality gates for imported formulations. Sinopec's integrated ethylene oxide complexes in Ningbo and Nanjing supply captive glycol production to regional blenders.
Germany
OEM thermal management program approvals in Stuttgart and Munich command premium pricing through warranty-aligned specifications. REACH mandates full chemical disclosure and hazard reclassification, extending product registration cycles for European Economic Area entry. The KBA certifies additive packages for factory-fill contracts across combustion and electric vehicle architectures.
United States
Commercial fleet operators in Texas and California are consolidating procurement around national service contracts with quick-lube networks. EPA regulates glycol disposal and workplace exposure limits under Clean Water Act provisions. The Gulf Coast petrochemical corridor from Houston to Baton Rouge anchors ethylene cracker capacity for domestic glycol supply.
India
Automotive chemical demand in Maharashtra and Tamil Nadu is climbing as vehicle parc ages and service intervals extend. BIS certification requirements for automotive chemicals are tightening import quality gates, creating first-mover advantages for compliant domestic manufacturing. Pune-based formulators are investing in testing infrastructure to meet new technical standards.
Saudi Arabia
Industrial process cooling demand in Jubail Industrial City is expanding as F-Gas Regulation phasedown in Europe redirects secondary loop system interest toward glycol-based alternatives. The country's national petroleum regulator oversees chemical manufacturing licensing for downstream derivatives. Integrated ethylene complexes on the Eastern Province coast supply regional glycol exports to South Asian and African markets.
Global Antifreeze Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue low-conductivity EV formulations and data center cooling specializations. The vendor base stratifies across integrated petrochemical majors, independent additive specialists, and regional blenders with captive distribution networks. Three archetypes dominate: upstream-integrated formulators controlling ethylene oxide supply, additive package licensors certifying through OEM thermal specifications, and aftermarket channel operators with quick-lube network partnerships. Competitive moves concentrate on backward integration into ethylene oxide production and geographic expansion through regional manufacturing investments.
Within the integrated petrochemical tier, BASF SE and ExxonMobil Corporation exemplify upstream control strategies, with the former anchoring European supply chains and the latter maintaining North American factory-fill relationships. Valvoline Inc. represents the aftermarket channel archetype, occupying a position within quick-lube network distribution. These three entities collectively illustrate how competitive positioning fragments across raw material access, OEM certification authority, and service channel density.
| Leading Market Players |
|---|
| BASF SE |
| ExxonMobil Corporation |
| Royal Dutch Shell plc |
| Chevron Corporation |
| TotalEnergies SE |
| Valvoline Inc. |
| Old World Industries, LLC |
| Prestone Products Corporation |
| Sinopec Corporation |
| Others |
Supply Flow & Price Mechanics
Ethylene oxide feedstock costs cascade through three distinct pricing tiers, with integrated producers in China and the Middle East capturing margin advantages that regional blenders in Europe and North America cannot match. Factory-fill contracts with German and Chinese automakers carry warranty-aligned premiums, while aftermarket volumes compete on landed cost at quick-lube networks and fleet maintenance depots.
Pricing Analysis
Warranty bundling separates OEM factory-fill specifications from unbundled aftermarket procurement decisions by fleet operators and independent repair shops. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with REACH-registered formulations commanding premiums in European Economic Area markets. Cost compression in the standard tier is intensifying because ethylene glycol spot prices track naphtha cracker margins. Fleet maintenance providers exhibit the highest price sensitivity, while OEM thermal management programs show the least.
Supply Chain Analysis
Reclaimed glycol flows from closed-loop recycling infrastructure in China are displacing virgin material in industrial process cooling applications, tightening quality gates for food-grade and automotive specifications. Upstream production concentrates in China, Saudi Arabia, and the United States, with integrated ethylene oxide complexes anchoring regional supply. Formulation draws from ethylene oxide, corrosion inhibitor packages, and deionized water inputs. Single-source vulnerability around ethylene cracker capacity in the US Gulf Coast poses structural risk. Distribution runs through bulk wholesale to industrial accounts and factory-fill programs, with retail and online channels serving fragmented household demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between REACH, EPA Clean Water Act provisions, and China's GB standards is forcing capital-constrained regional blenders toward exit or acquisition, consolidating competitive position around integrated producers and additive specialists with multi-jurisdiction compliance infrastructure.
For Market Incumbents: Hedge margin exposure by securing captive ethylene oxide supply through backward integration or long-term offtake agreements with Sinopec and Sabic affiliates. Invest in low-electrical-conductivity R&D to capture EV thermal management program approvals from Chinese and German OEMs before formulation specifications stabilize.
For New Entrants and Emerging Players: Begin with data center liquid cooling formulations for hyperscale computing facilities in Virginia and Frankfurt, where purity specifications exceed commodity automotive grades and incumbent presence remains thin. Pursue direct technical service relationships with facility engineering teams rather than distributor channels.
For Investors and Strategic Acquirers: First-mover BIS certification in India is the leading indicator that domestic manufacturing investments will capture procurement consolidation among Maharashtra and Tamil Nadu automotive clusters. Target regional blenders with testing infrastructure and compliant formulations but lacking captive feedstock. Monitor EU F-Gas Regulation phasedown deadlines as inflection signals for industrial glycol demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive feedstock supply insulates BASF and Sinopec from naphtha price volatility. |
| Low-Conductivity EV Formulation Development | Dielectric-compatible coolants unlock battery thermal management programs at Chinese OEMs. |
| BIS Certification Investment in India | Compliant domestic production captures procurement consolidation in Maharashtra automotive clusters. |
| Data Center Cooling Specialization | High-purity glycol-water loops serve hyperscale direct-to-chip thermal management demand. |
| Closed-Loop Recycling Infrastructure | Reclaimed glycol refinement aligns with China's dual carbon intensity reduction targets. |
Methodological Framework
Multi-period observation of ethylene oxide spot prices, REACH registration timelines, and EV platform launch schedules anchored the trend analysis, supplemented by interviews with formulator R&D directors, OEM thermal management engineers, fleet procurement officers, and aftermarket channel managers. Secondary validation drew from customs trade data, SEC 10-K chemical segment disclosures, SAMR GB standard filings, and IHS Markit vehicle production databases. Bottom-up volume builds across product types and applications triangulated against top-down macroeconomic drivers.
Input-output matrices mapped ethylene oxide supply through formulation tiers to end-use segments across the analysis window. Segmentation dimensions modeled include glycol base chemistry, application category, end-user type, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating EV penetration rates and F-Gas Regulation compliance deadlines. Industry-specific forecast inputs captured battery thermal management fluid volumes per vehicle and industrial refrigeration system replacement cycles.
Underlying measurement precision varies by segment; factory-fill contract volumes carry tighter precision than fragmented household retail. Forecasts reflect assumptions about EV platform ramp schedules and regulatory phasedown timelines. Practitioners should monitor ethylene cracker margin volatility, BIS certification grant rates, and hyperscale data center capex announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Carbamate Insecticides Market
Industrial Chemicals
Detergent Making Machinery Market
Industrial Chemicals
1,3-Propanediol (PDO) Market
Industrial Chemicals
Metal Treatment Chemical Market
Industrial Chemicals
Froth Flotation Chemicals Market
Industrial Chemicals
Fluidized Bed Reactors Market
Industrial Chemicals
Lime Market
Industrial Chemicals
Global Ethylene Carbonate Market
Industrial Chemicals
Enzymatically Hydrolyzed Carboxymethyl Cellulose Market
Industrial Chemicals
Global Lignosulfonate Based Concrete Admixtures Market
Industrial Chemicals
Dewatering Aids Market
Industrial Chemicals
Butadiene Extraction Market
Industrial Chemicals
Heat Treating Market
Industrial Chemicals
Blown Oils Market
Industrial Chemicals
Metalworking Treating Fluid Market
Industrial Chemicals
Acetylene Market