
 Middle East and Africa Color Masterbatch Market | 2026-2036
Middle East and Africa Color Masterbatch Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Color Masterbatch Market Outlook
Subscription-based color matching and cloud-hosted formulation libraries is consolidating how regional compounders monetize technical expertise beyond physical pellet sales. Clariant leverages its Swiss-developed pigment technology to sustain premium positioning across Gulf Cooperation Council packaging markets. SABIC anchors regional supply security through captive polyethylene and polypropylene feedstock integration at its Jubail manufacturing complex. Ampacet Corporation competes by extending its technical service footprint through localized distribution partnerships in Egypt and Morocco.
Color masterbatch denotes a concentrated mixture of pigments, carriers, and additives extruded into pellet form, typically containing 15-50% colorant by weight, designed for precise dispersion during thermoplastic processing. The composition enables uniform coloring of polymers while minimizing raw material waste and cleaning downtime on injection molding or blown film lines. Polymer masterbatches occupy the dominant volume position due to their compatibility with high-throughput polypropylene and polyethylene processing across regional packaging sectors. Specialty masterbatches command superior margin pools where conductive, flame-retardant, or UV-stabilized functionalities address automotive and electronics specifications. Black masterbatches sustain steady demand from construction materials and agricultural film producers seeking weathering resistance and opacity control.
Gulf Standards Organization certification requirements and Saudi Standards, Metrology and Quality Organization (SASO) polymer safety mandates shape product compliance costs for masterbatch importers serving Gulf markets. South Africa's National Regulator for Compulsory Specifications enforces migration limits that redirect formulation strategies for food-contact applications. Egypt's Egyptian Organization for Standardization and Quality (EOS) alignment with ISO pigment purity standards influences local compounding investments. Stakeholders must monitor regulatory divergence between Gulf and North African compliance frameworks when scaling cross-border manufacturing footprints.
Market Dynamics
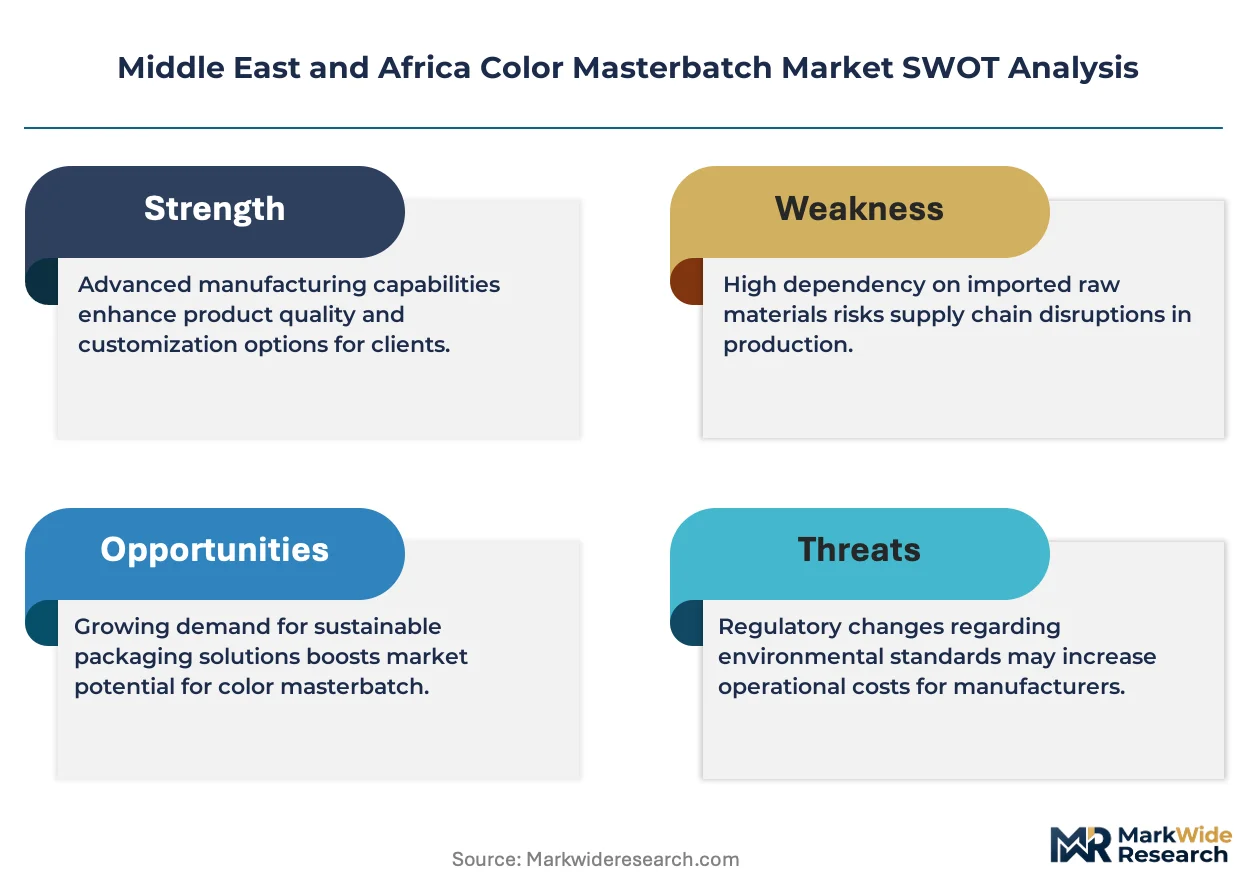
REACH-aligned chemical safety protocols and evolving Gulf Standards Organization polymer certification rules are tightening pigment migration limits for food-contact plastics across the Middle East and Africa, forcing compounders to reformulate carrier resins and accelerate compliance investments.
Growth Catalysts
- Packaging Converter Expansion:Flexible film and rigid container producers across Nigeria and South Africa are scaling color masterbatch procurement to serve domestic consumer goods markets and regional re-export channels.
- SASO Polymer Safety Mandates:Saudi Standards, Metrology and Quality Organization enforcement of food-contact migration limits is creating certified-supplier premiums for compliant masterbatch producers serving Gulf markets.
- Petrochemical Downstream Integration:Saudi Arabia's Jubail manufacturing corridor anchors captive polyethylene and polypropylene feedstock supply for regional compounding facilities serving both domestic packaging lines and re-export demand.
Market Restraints
- Pigment Raw Material Volatility:Titanium dioxide and organic pigment supply disruptions from Asian producers transmit cost instability to regional compounders lacking backward integration into colorant synthesis.
- Regulatory Divergence Costs:Misalignment between Gulf Standards Organization certification requirements and Egypt's Egyptian Organization for Standardization and Quality pigment purity standards fragments compliance investments for cross-border manufacturers.
- Technical Substitution Pressure:Liquid colorant dosing systems for high-volume polyethylene processing threaten pellet masterbatch volumes in selected blown film applications where dispersion uniformity requirements permit.
Strategic Opportunities
- Morocco Distribution Hub Development:Localized technical service partnerships and warehousing infrastructure can capture North African flexible packaging demand currently served by distant European suppliers.
- Cloud-Hosted Formulation Libraries:Subscription-based color matching platforms enable regional compounders to monetize technical expertise beyond physical pellet sales through recurring revenue streams.
- EOS-ISO Alignment Incentives:Egyptian Organization for Standardization and Quality convergence with international pigment standards reduces import certification friction and attracts foreign compounding investment into Alexandria industrial zones.
Industry Challenges
- Specialized Formulation Talent Scarcity:Regional universities produce insufficient polymer chemists trained in pigment dispersion rheology and food-contact safety compliance for masterbatch-specific applications.
- Multi-Jurisdiction Certification Timelines:Separate Gulf Standards Organization and South African National Regulator for Compulsory Specifications approval processes delay product launches by 8-14 months for cross-regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Color Masterbatch Market |
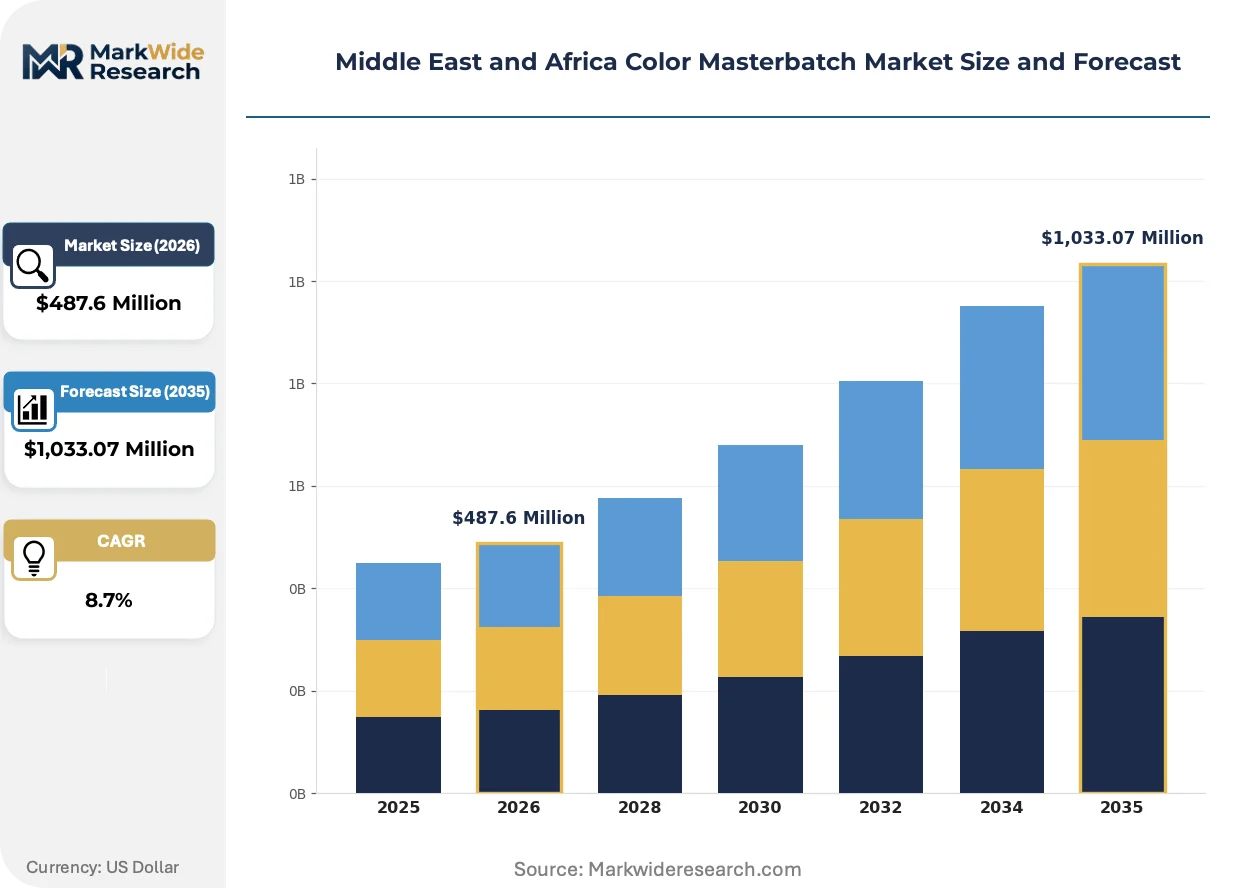
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Masterbatches, Additive Masterbatches, Specialty Masterbatches, Black Masterbatches Polymer Type: Polypropylene, Polyethylene, Polyvinyl Chloride, Polystyrene Application: Packaging, Automotive Parts, Consumer Goods, Construction Materials Industry Vertical: Plastics Manufacturing, Textiles, Agriculture, Electronics |
| Companies Covered | Cabot Corporation, Astra Polymers Compounding Co., Ltd, Clariant, BASF, PolyOne Corporation, Ampacet Corporation, SABIC, A. Schulman, EuP Egypt, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Color Masterbatch Market Strategic Shifts
Digital color matching platforms and carrier resin innovations are compressing formulation cycles while regulatory tightening across Gulf and North African jurisdictions elevates technical service capabilities as a competitive differentiator.
Specialty functional masterbatches incorporating conductive, flame-retardant, or UV-stabilized additives are expanding into automotive interior and electronics housing applications across South Africa and Gulf manufacturing zones. Tier-1 suppliers serving BMW and Nissan assembly plants in Rosslyn and Abu Dhabi are specifying these materials for dashboard components and connector housings. This expansion is compressing margins for commodity black and white masterbatches while creating premium pricing pools for compounders with polymer modification expertise.
Gulf Standards Organization migration limit updates and Saudi Standards, Metrology and Quality Organization enforcement protocols are forcing reformulation of azo pigments and heavy-metal-containing colorants across food-contact applications. Masterbatch producers serving dairy and beverage packaging lines in Jeddah and Dammam are accelerating replacement of non-compliant legacy formulations. The technical consequence is elevated R&D expenditure and extended customer qualification timelines for reformulated products.
Converters across Egypt and Morocco are consolidating supplier relationships toward technical-service-integrated partnerships that bundle color matching, inventory management, and regulatory documentation. Large flexible film producers in Cairo and Casablanca are displacing transactional spot purchasing with annual framework agreements specifying formulation exclusivity and dedicated technical support. This behavioral shift concentrates procurement volumes with compounders maintaining localized laboratory and warehousing infrastructure.
Middle East and Africa Color Masterbatch Market Segmentation
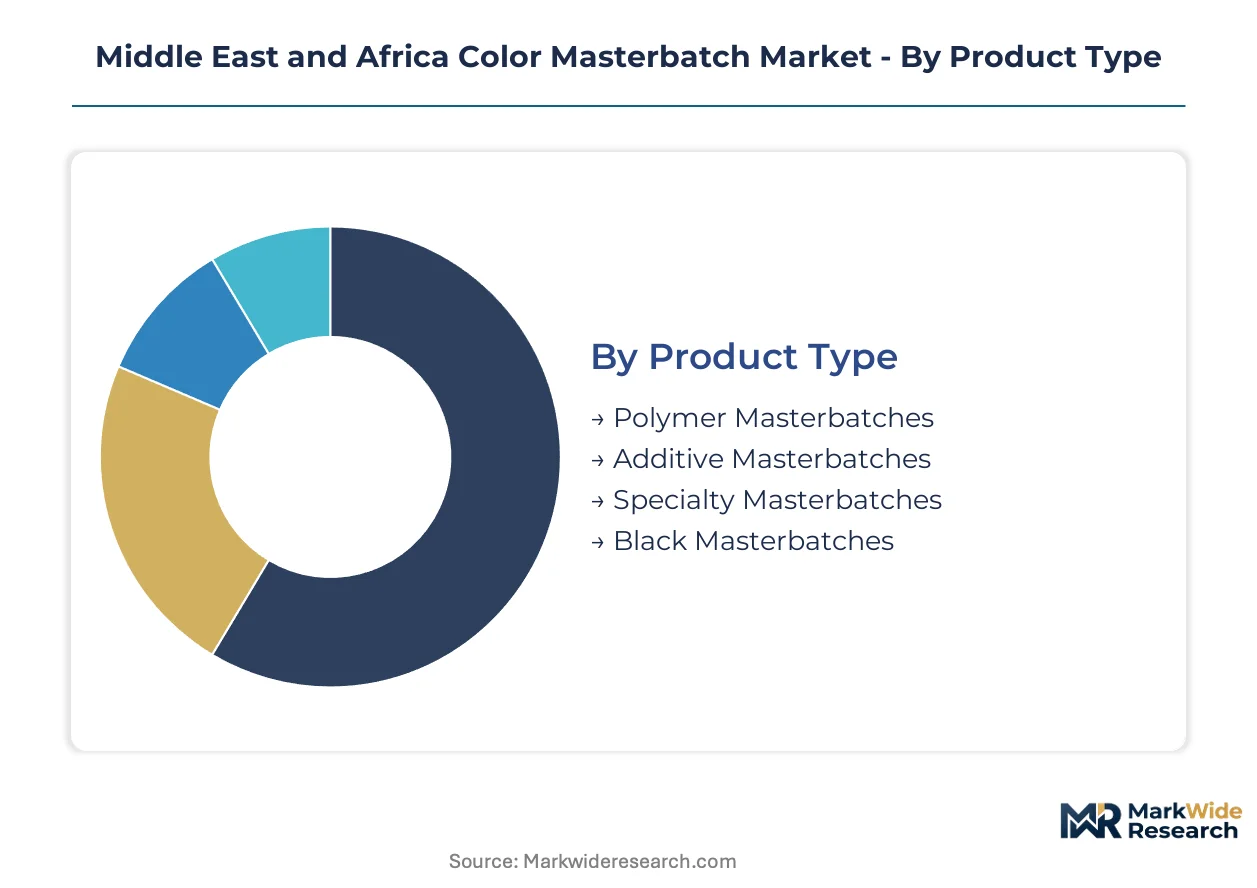
Segmentation in the Middle East and Africa color masterbatch market reveals how carrier resin compatibility, end-use performance requirements, and regulatory compliance burdens fragment procurement patterns across regional compounders and converters.
Product Type:
Buyers in this category differentiate by margin pool depth and technical service intensity rather than commodity pellet pricing alone.
- Polymer Masterbatches:Concentrated pigment-resin formulations containing 15-50% colorant by weight, engineered for uniform dispersion during high-throughput thermoplastic processing. Demand concentrates in Saudi Arabia's Jubail petrochemical corridor, where downstream packaging lines serving dairy and beverage sectors require consistent lot-to-lot color matching under Gulf Standards Organization migration limits.
- Specialty Masterbatches:Functional formulations incorporating conductive, flame-retardant, or UV-stabilized additives for performance-critical applications. South African automotive tier-1 suppliers serving BMW and Nissan assembly plants in Rosslyn specify these materials for dashboard components and electronics housings, compressing margins for commodity alternatives while creating premium pricing pools.
- Additive Masterbatches:Processing aids and property modifiers delivered through carrier resin matrices. Egyptian flexible film producers in Cairo leverage these for anti-block and slip control in food-contact packaging.
- Black Masterbatches:Carbon black-loaded formulations providing opacity control and weathering resistance. Agricultural film producers across Morocco's Souss-Massa region sustain steady procurement for greenhouse covering applications.
Volume sits with Polymer Masterbatches; growth tilts toward Specialty Masterbatches.
Polymer Type:
Carrier resin selection in this category tracks regional petrochemical feedstock availability and processing temperature requirements across converter equipment bases.
- Polypropylene:Low-density carrier resin compatible with injection molding and thermoforming lines, dominating rigid container applications. Nigerian packaging converters in Lagos and Kano are expanding procurement for consumer goods containers serving domestic retail channels.
- Polyethylene:Versatile carrier spanning LDPE, LLDPE, and HDPE grades for blown film and extrusion coating. Flexible film producers in Morocco's Casablanca-Settat region specify these masterbatches for export-oriented food packaging under EOS-ISO aligned certification requirements.
- Polyvinyl Chloride:Specialized carrier for rigid profile and pipe applications requiring heat stability. Construction material processors in South Africa's Gauteng province utilize these for window frame and conduit coloring.
- Polystyrene:Crystal and high-impact grades serving electronics packaging and disposable cutlery segments. Electronics assemblers in Dubai's Jebel Ali Free Zone source these for protective foam and tray applications.
Polyethylene captures the largest procurement volumes; Polypropylene is climbing the fastest on packaging converter expansion.
Application:
End-use concentration in this category reflects the dominance of food-contact safety mandates and the technical substitution pressure from liquid colorant systems.
- Packaging:Flexible film, rigid containers, and closure applications requiring migration-compliant formulations. REACH-aligned pigment protocols and tightening SASO enforcement are forcing reformulation of azo pigments and heavy-metal-containing colorants across dairy and beverage lines in Jeddah and Dammam.
- Automotive Parts:Interior trim, exterior cladding, and under-hood components demanding UV stability and heat resistance. Gulf-based tier-1 suppliers are consolidating procurement toward technical-service-integrated partnerships bundling color matching and regulatory documentation.
- Consumer Goods:Appliances, furniture, and household items where aesthetic differentiation drives specification. South African compounders serving this segment face technical talent scarcity in pigment dispersion rheology.
- Construction Materials:Pipes, profiles, and weather-resistant siding requiring opacity and durability. Saudi Arabia's infrastructure pipeline sustains consistent demand for black and white masterbatches in this category.
Packaging dominates current volumes; Automotive Parts shows the steepest expansion trajectory on functional masterbatch penetration.
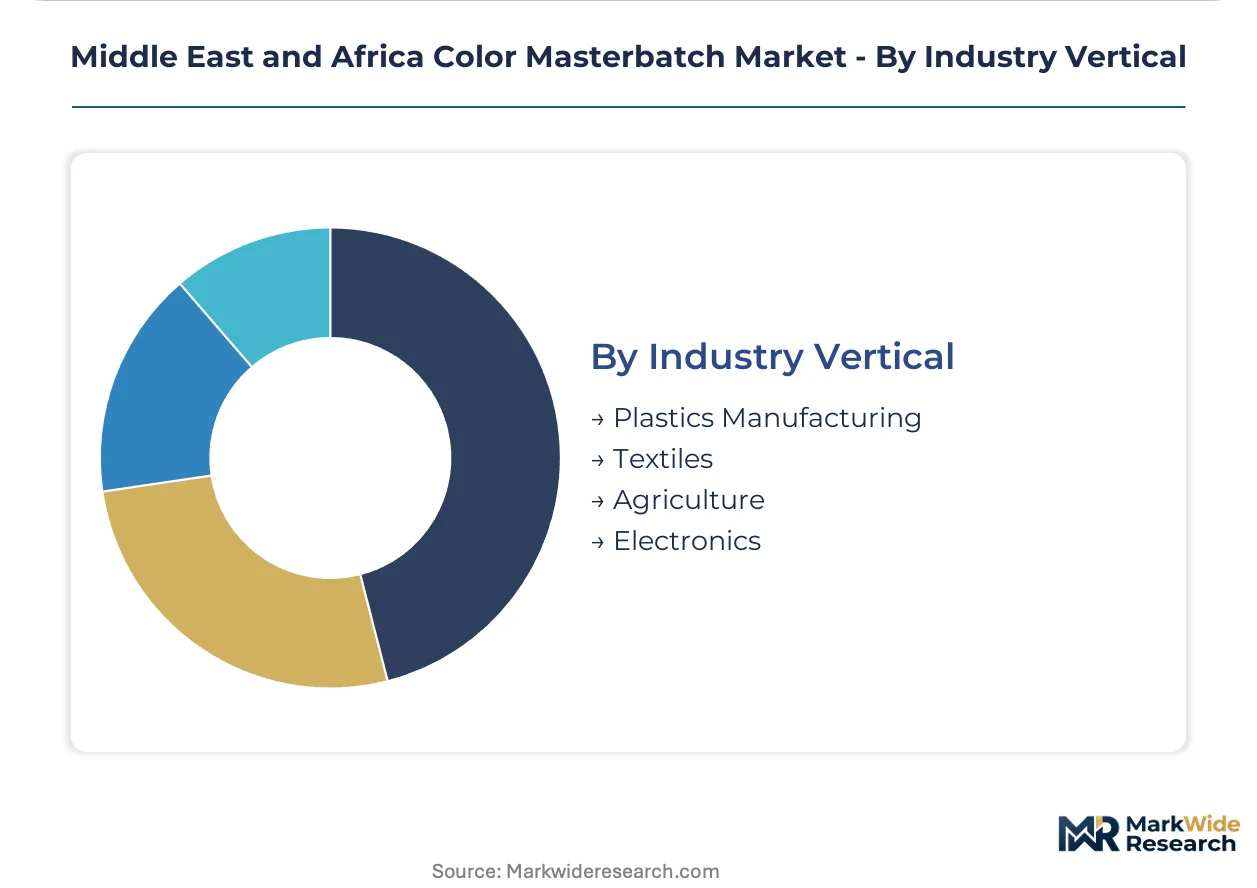
Industry Vertical:
Vertical procurement patterns in this category diverge between high-volume commodity converters and specialized compounders serving regulated end-markets.
- Plastics Manufacturing:Primary converters operating extrusion, injection molding, and blow molding equipment across flexible and rigid formats. Nigeria and South Africa are scaling masterbatch procurement to serve domestic consumer goods markets and regional re-export channels.
- Agriculture:Greenhouse films, mulching sheets, and irrigation tubing requiring UV stabilization and controlled degradation. Moroccan agricultural film producers seek weathering resistance specifications from regional compounders.
- Textiles:Synthetic fiber coloring for non-woven and woven applications. Egyptian textile processors in the Nile Delta region utilize masterbatches for PP and PET fiber pigmentation.
- Electronics:Connector housings, device enclosures, and component packaging demanding conductive and flame-retardant functionalities. Dubai and Abu Dhabi manufacturing zones specify these materials for electronics assembly export operations.
Plastics Manufacturing anchors volume concentration; Electronics is gaining share fastest on specialty functional formulation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jubail Industrial City's petrochemical corridor anchors regional masterbatch supply security through captive polyethylene and polypropylene feedstock integration serving both domestic packaging lines and re-export markets across the Gulf and East Africa.
Saudi Arabia
Packaging converters in Jeddah and Dammam are scaling color masterbatch procurement for dairy and beverage applications under tightening SASO enforcement of food-contact migration limits. The Saudi Standards, Metrology and Quality Organization mandates are forcing reformulation of azo pigments and heavy-metal-containing colorants. Downstream compounding facilities at Jubail serve re-export demand to Gulf Cooperation Council markets and East African ports.
United Arab Emirates
Dubai's Jebel Ali Free Zone electronics assemblers specify conductive and flame-retardant masterbatches for connector housings and device enclosures in export-oriented manufacturing operations. MOHAP pharmaceutical packaging regulations influence pigment purity requirements for medical-grade polymers. Abu Dhabi's Khalifa Industrial Zone hosts tier-1 automotive suppliers specifying UV-stabilized formulations for interior trim components.
South Africa
Flexible film producers in Johannesburg and rigid container manufacturers in Cape Town are expanding masterbatch procurement to serve domestic retail channels and regional re-export corridors into Sub-Saharan Africa. The National Regulator for Compulsory Specifications enforces migration limits that redirect formulation strategies for food-contact applications. Rosslyn's automotive cluster specifies specialty functional masterbatches for BMW and Nissan dashboard components.
Egypt
Cairo-based flexible film converters are consolidating supplier relationships toward technical-service-integrated partnerships bundling color matching and regulatory documentation. EOS alignment with ISO pigment purity standards reduces import certification friction and attracts foreign compounding investment into Alexandria industrial zones. Nile Delta textile processors utilize masterbatches for polypropylene and PET fiber pigmentation in woven and non-woven applications.
Morocco
Casablanca-Settat flexible film producers specify polyethylene-based masterbatches for export-oriented food packaging under EOS-ISO aligned certification requirements. Agricultural film manufacturers in the Souss-Massa region sustain steady procurement of black masterbatches for greenhouse covering applications requiring weathering resistance and UV stabilization. Localized warehousing infrastructure captures North African demand currently served by distant European suppliers.
Middle East and Africa Color Masterbatch Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the Middle East and Africa color masterbatch landscape. The market structure fragments between integrated petrochemical conglomerates with captive feedstock supply and specialized compounders monetizing technical expertise through formulation services. Three archetypes dominate: feedstock-integrated regional champions, European technology licensors with Gulf distribution partnerships, and local compounders serving single-country certification requirements. Competitive moves concentrate on geographic expansion through technical service localization and portfolio diversification into specialty functional grades.
Among petrochemical-integrated producers, SABIC anchors supply security through captive polyethylene and polypropylene production at Jubail. European technology specialists Clariant and BASF occupy premium positioning across Gulf Cooperation Council packaging markets through Swiss-developed and German-engineered pigment platforms respectively. Ampacet Corporation exemplifies the technical-service-integrated model through localized distribution partnerships in Egypt and Morocco that bundle color matching with regulatory documentation support.
| Leading Market Players |
|---|
| Cabot Corporation |
| Astra Polymers Compounding Co., Ltd |
| Clariant |
| BASF |
| PolyOne Corporation |
| Ampacet Corporation |
| SABIC |
| A. Schulman |
| EuP Egypt |
| Others |
Value Chain & Pricing Dynamics
Titanium dioxide pigment costs cascade through three distinct pricing tiers for Middle East and Africa compounders, with feedstock-integrated producers at Jubail capturing margin premiums while import-dependent Egyptian and Moroccan compounders absorb volatility from Asian colorant suppliers.
Pricing Analysis
Throughput-linked pricing dominates flexible film converter contracts, where compounders charge per-kilogram rates adjusted for dispersion quality and lot-to-lot color consistency rather than commodity pellet baselines. Certification grade under Gulf Standards Organization and SASO food-contact mandates commands substantial premiums over non-compliant alternatives, while volume-scale discounts concentrate procurement with large Nigerian and South African packaging groups. Cost compression in standard-grade polymer masterbatches is intensifying because liquid colorant systems threaten pellet volumes in high-volume polyethylene blown film lines. Small-to-mid Egyptian converters exhibit highest price sensitivity due to working capital constraints, whereas Saudi dairy packaging lines prioritize compliance assurance over unit cost.
Supply Chain Analysis
Skilled polymer chemist shortages in Egypt's Nile Delta and Morocco's Casablanca-Settat corridor constrain formulation capacity expansion despite rising North African demand. Manufacturing concentrates in Saudi Arabia's Jubail petrochemical complex, Egypt's Alexandria industrial zones, and South Africa's Gauteng province. Supply chains draw from Chinese titanium dioxide producers, German organic pigment specialists, and regional polyethylene feedstock from SABIC. Single-source vulnerability in Asian colorant imports exposes compounders to logistics disruptions through Red Sea shipping routes. Distribution runs through technical-service-integrated partnerships bundling warehousing, color matching, and regulatory documentation rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa color masterbatch sector sits at a formulation-technology inflection, with cloud-hosted color matching platforms displacing legacy laboratory-dependent services and compressing margins for compounders lacking digital infrastructure.
For Market Incumbents: Anchor defensive positioning through captive feedstock integration at Jubail and certification pre-qualification under tightening SASO migration limits. Liquid colorant substitution in polyethylene blown film applications threatens pellet volumes; counter by embedding technical service teams within major flexible film converter operations to raise switching costs. Backward integration into pigment dispersion capacity insulates margin pools from Asian supply volatility. For New Entrants and Emerging Players: Cloud-based formulation subscription models offer low-capital routes to monetize technical expertise without manufacturing assets. Morocco's Casablanca-Settat flexible film corridor presents the most penetrable white space, currently served by distant European suppliers with elongated lead times. Target annual framework agreements with mid-tier Egyptian converters seeking EOS-ISO aligned certification support bundled with inventory management. For Investors and Strategic Acquirers: SABIC's captive feedstock announcements at Jubail are the leading indicator that petrochemical-integrated masterbatch capacity will consolidate regional supply security. Long-term viability favors compounders with polymer modification expertise beyond commodity coloration, particularly those serving automotive and electronics functional masterbatch specifications. Monitor Gulf Standards Organization migration limit update timelines as signals for reformulation-driven M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Synthesis | Captive colorant production at Jubail insulates SABIC from Asian titanium dioxide volatility. |
| Cloud-Hosted Formulation Platform Launch | Subscription revenue streams enable regional compounders to monetize technical expertise beyond pellet sales. |
| Technical Service Localization in Morocco | Casablanca warehousing and laboratory infrastructure captures North African demand from European suppliers. |
| SASO Certification Pre-Qualification Program | Early compliance investment secures supplier premiums as Saudi dairy packaging mandates tighten. |
| Specialty Functional Masterbatch Capacity Addition | UV-stabilized and conductive formulations address BMW and Nissan tier-1 specifications in Rosslyn and Abu Dhabi. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving masterbatch plant managers, packaging converter procurement leads, Gulf Standards Organization certification officers, and automotive tier-1 supplier technical directors. Secondary sources included SASO enforcement bulletins, EOS-ISO alignment documentation, SABIC petrochemical output disclosures, and flexible film producer annual procurement frameworks. Bottom-up demand modeling triangulated against top-down petrochemical capacity assessments across Saudi Arabia, Egypt, and South Africa.
Reconciling shipment volume data from regional customs authorities with converter equipment utilization rates produced the installed-base consumption estimates across the projection horizon. Segmentation dimensions encompassed product type, carrier resin compatibility, end-use application, and regulatory compliance tier. CAGRs derived from elasticity-adjusted demand curves responding to pigment cost movements and certification requirement phase-ins. Industry-specific inputs included blown film line throughput specifications and automotive interior material qualification timelines.
The model holds under stable Gulf petrochemical feedstock supply and continued EOS-ISO convergence; deviation in Red Sea logistics disruption frequency or SASO enforcement acceleration would shift volume and value trajectories. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Hypalon Market
Specialty Compounds
Automated Compound Storage and Retrieval (ACSR) Market
Specialty Compounds
Film Dressing Market
Specialty Compounds
Asia-Pacific Collagen Market
Specialty Compounds
Europe Microencapsulation Market
Specialty Compounds
Global Color Masterbatch Market
Specialty Compounds
Air-Laid Product Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
United Kingdom Collagen Peptides Market
Specialty Compounds
Ready Mix Joint Compound Market
Specialty Compounds
Silk Protein Market
Specialty Compounds
Lithopone Market
Specialty Compounds
Potassium Gluconate Market
Specialty Compounds
Global Zinc Phosphate Market
Specialty Compounds
Chromatography Silica Resins Market
Specialty Compounds
Filler Masterbatch Market