
 Metasulphite Market | 2026-2036
Metasulphite Market Size, Share, and Industry Trends Forecast 2026-2036
Metasulphite Market Analytics
China is narrowing its import dependence for metasulphite grades through domestic capacity additions in Shandong and Jiangsu provinces. BASF SE leverages integrated sulphur chemistry platforms to sustain cost advantages across European supply corridors. Aditya Birla Chemicals anchors South Asian demand through captive chlor-alkali linkages and regional distribution density. Esseco Group specializes in food-grade specifications that compete on purity certification rather than volume pricing.
Metasulphite denotes a class of inorganic sulphite salts—primarily sodium, potassium, calcium, and ammonium variants—manufactured via absorption of sulphur dioxide into aqueous alkali or alkaline earth hydroxide solutions, typically yielding products with 96-99% active sulphite content and controlled heavy metal limits below 10 ppm. These compounds function as oxygen scavengers, reducing agents, and antimicrobial preservatives across industrial and food systems. Sodium metasulphite dominates volume flows due to its cost position and versatility in water treatment and textile bleaching applications, while potassium metasulphite commands margin premiums in wine stabilization where taste neutrality matters. Powder and granular forms lead physical format demand because of handling efficiency and shelf stability, though liquid formulations are displacing solids in large-scale municipal water treatment installations where dosing automation reduces labor exposure.
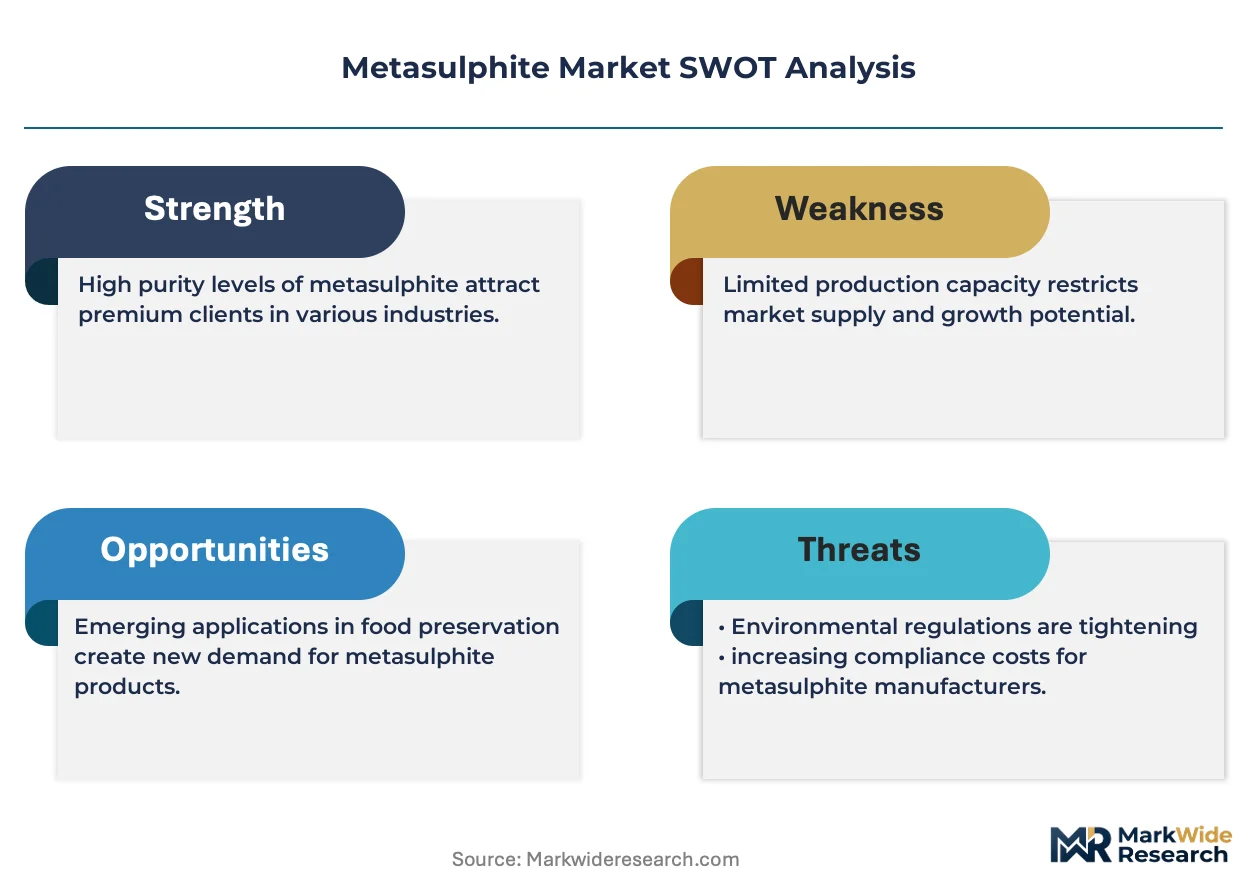
FDA food additive regulations under 21 CFR 182.3766 and REACH restrictions on sulphite labeling in the European Union constrain formulation flexibility and compel batch-level traceability investments. EPA effluent guidelines for pulp and paper mills in the United States limit sulphite discharge volumes, redirecting procurement toward higher-purity grades that minimize residual byproduct formation. India's FSSAI and China's SAMR maintain divergent maximum residue limits, fragmenting compliance architectures for multinational suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and anticipate where purity grade premiums will widen.
Market Dynamics
Regulatory divergence between FDA food additive rules and REACH purity mandates is fragmenting compliance architectures, forcing suppliers to maintain parallel production lines and batch-level traceability systems that reshape cost structures across the value chain.
Growth Catalysts
- Food-grade certification premiums:FDA 21 CFR 182.3766 compliance requirements for sulphite preservatives in wine and dried fruit processing drive specialized grade demand with margin expansion.
- China water treatment expansion:Municipal dechlorination and oxygen scavenging applications in Shandong and Jiangsu province utilities accelerate sodium metasulphite offtake.
- REACH sulphite labeling restrictions:Mandatory disclosure thresholds for consumer products in the European Union redirect formulation demand toward lower-residue potassium variants.
Market Restraints
- Sulphur dioxide feedstock volatility:Refinery byproduct supply fluctuations and energy-linked smelter economics compress margin predictability for integrated producers.
- Shandong-Jiangsu supply concentration:Domestic Chinese capacity additions narrow import arbitrage windows and strand legacy merchant suppliers without captive alkali linkages.
- Potassium metasulphite cost premium:Chlor-alkali energy intensity and potash price exposure limit substitution potential in cost-sensitive textile bleaching applications.
Strategic Opportunities
- India FSSAI alignment gaps:Divergent maximum residue limits from European and North American standards create first-mover advantage for compliance-capable suppliers in processed food exports.
- Liquid dosing automation:Municipal water treatment facilities are displacing manual powder handling with automated sulphite injection skids that reduce labor exposure and dosing variance.
- EU Green Deal industrial decarbonization:Carbon border adjustment mechanisms favor low-carbon sulphite production routes using renewable energy-integrated chlor-alkali cells.
Industry Challenges
- Analytical chemistry skill scarcity:Heavy metal testing below 10 ppm limits and batch certification documentation require specialized quality personnel that regional distributors struggle to retain.
- Legacy ERP integration:Batch-level traceability investments for REACH and FDA compliance collide with existing inventory management systems that lack lot genealogy functionality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metasulphite Market |
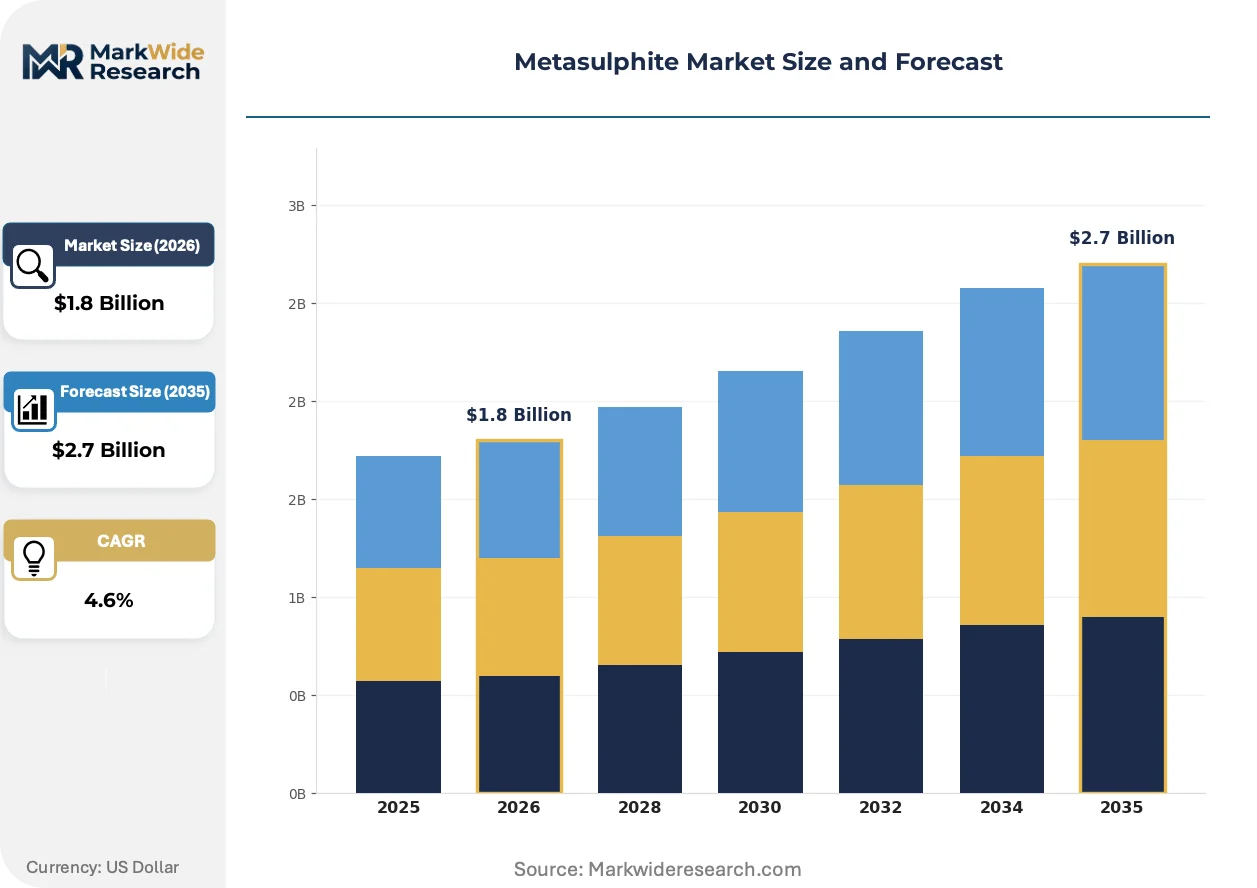
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Metasulphite, Potassium Metasulphite, Calcium Metasulphite, Ammonium Metasulphite Application: Food Preservation, Water Treatment, Wine Production, Textile Industry Form: Granular, Powder, Liquid, Tablet End User: Food & Beverage, Pharmaceuticals, Manufacturing, Agriculture |
| Companies Covered | BASF SE, INEOS Calabrian, Solvay, Aditya Birla Chemicals, Esseco Group, Grillo-Werke AG, Kailong Chemical Technology, Merck KGaA, Şişecam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metasulphite Market Evolving Landscape
Digitalization of dosing control and purity verification systems is compressing the gap between commodity sulphite supply and precision-chemical service expectations, reshaping how buyers evaluate supplier partnerships.
Automated liquid sulphite dosing skids with integrated redox monitoring and closed-loop control are virtualizing the traditional manual handling and testing workflows that dominated municipal water treatment operations. Large-scale utilities in coastal Chinese provinces adopt these systems fastest, driven by labor cost escalation and safety incident liability. The technology is virtualizing procurement evaluation criteria from unit price toward total cost of dosing accuracy and compliance documentation.
REACH restrictions on sulphite-containing product labeling and the EU's tightening heavy metal migration limits for food contact materials are compelling reformulation investments across European packaging and preservation sectors. Manufacturers must now maintain dual inventory streams for EU-compliant and export-market grades. Wine stabilization applications face the steepest compliance cost escalation due to taste-neutrality requirements that resist grade substitution.
Consolidation of wine production into large cooperative cellars and industrial-scale bottling facilities concentrates sulphite procurement authority and compresses supplier rosters. These buyers now demand certificate-of-analysis documentation, vendor-managed inventory, and technical service support that commodity traders cannot provide. The shift is most pronounced in Mediterranean basin wine regions where cooperative processing volumes exceed ten thousand hectoliters annually.
Metasulphite Market Segmentation
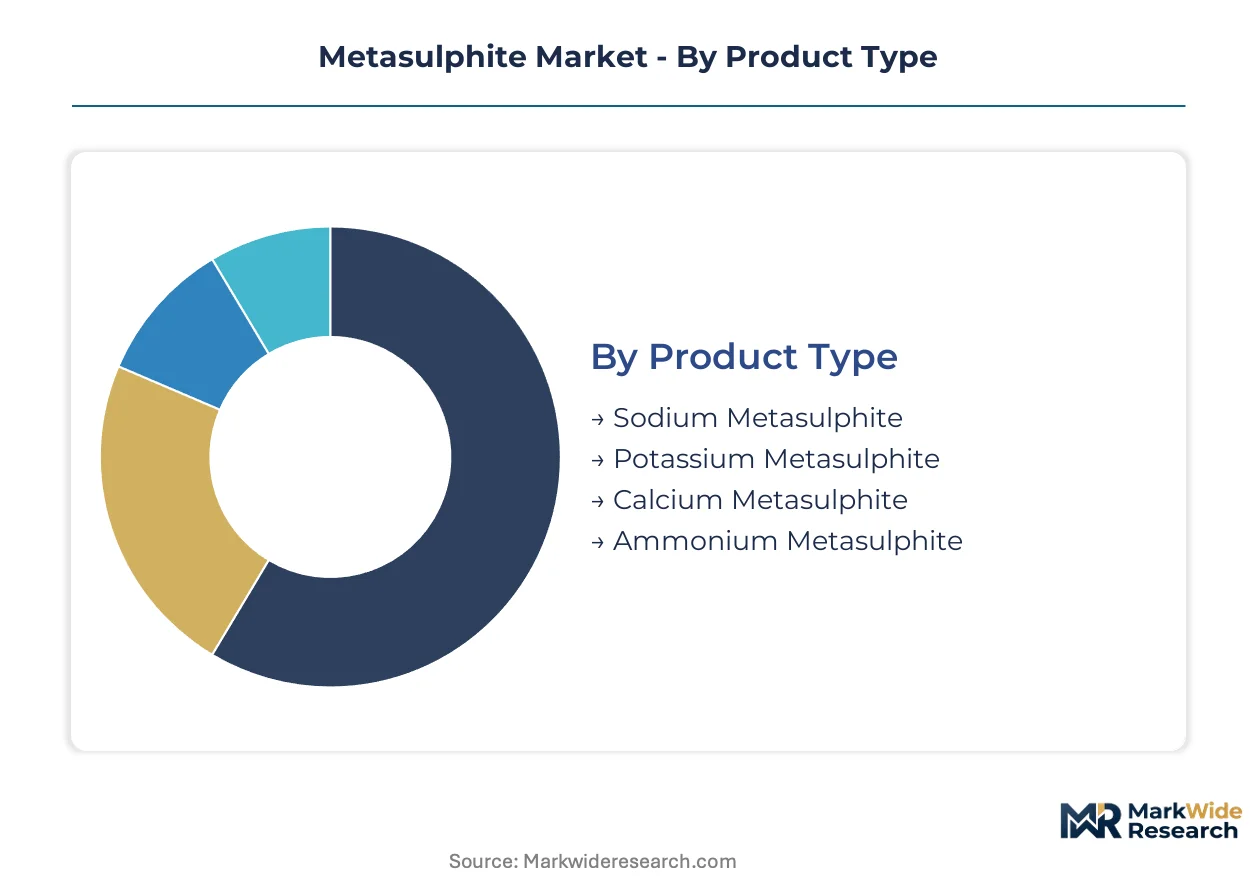
Metasulphite procurement decisions hinge on purity certification, physical handling requirements, and end-use regulatory exposure. Suppliers compete across four distinct category hierarchies that reshape margin structures and customer stickiness.
Product Type:
Mature commodity grades dominate volume flows while specialty variants capture margin premiums in taste-sensitive applications.
- Sodium Metasulphite:Manufactured via absorption of sulphur dioxide into aqueous sodium hydroxide, yielding 96-99% active sulphite content with heavy metal limits below 10 ppm. Municipal dechlorination and oxygen scavenging operations in Shandong province utilities drive concentrated offtake, though refinery byproduct sulphur dioxide volatility compresses margin predictability for merchant producers.
- Potassium Metasulphite:Produced through sulphur dioxide reaction with potassium hydroxide, commanding price premiums due to chlor-alkali energy intensity and potash feedstock exposure. Wine stabilization applications in Mediterranean cooperative cellars sustain demand where taste neutrality resists grade substitution, despite cost barriers in textile bleaching.
- Calcium Metasulphite:Alkaline earth variant with lower solubility profile suited to agricultural fumigation and select food applications. Regulatory divergence between FDA and FSSAI residue limits fragments addressable markets.
- Ammonium Metasulphite:Niche grade serving specialized reducing agent applications in photographic chemical recovery and rare earth processing. Limited merchant availability concentrates supply among integrated sulphur chemistry platforms.
Sodium metasulphite retains volume leadership; potassium metasulphite holds the steepest expansion curve.
Application:
End-use concentration varies sharply by regulatory jurisdiction and customer scale, with food-contact compliance costs reshaping supplier selection criteria.
- Food Preservation:Sulphite preservatives under FDA 21 CFR 182.3766 and REACH labeling restrictions drive specialized grade demand with certificate-of-analysis documentation. Dried fruit processors and cooperative wine cellars now require vendor-managed inventory and technical service support that commodity traders cannot deliver.
- Water Treatment:Municipal dechlorination and oxygen scavenging in coastal Chinese utilities accelerates liquid formulation adoption with automated dosing skids. Labor cost escalation and safety incident liability compress manual powder handling economics.
- Wine Production:Stabilization applications face compliance cost escalation from EU heavy metal migration limits and taste-neutrality requirements. Large cooperative cellars concentrate procurement authority and compress supplier rosters.
- Textile Industry:Bleaching and desizing operations favor sodium metasulphite cost position, though potassium variant substitution remains limited by price exposure.
Water treatment commands the largest volume footprint; food preservation generates the highest purity premiums.
Form:
Physical format selection reflects handling automation maturity and labor cost structures across end-use facilities.
- Granular:Free-flowing crystalline structure with superior shelf stability and reduced caking tendency. Large-scale food processors and textile mills favor granular for mechanical conveying compatibility.
- Powder:Fine particle distribution enabling rapid dissolution in aqueous systems. Manual handling dominance in legacy facilities faces displacement from automated alternatives.
- Liquid:Pre-dissolved sulphite solutions with integrated redox monitoring and closed-loop control. Municipal utilities in Jiangsu province adopt fastest, virtualizing procurement criteria toward dosing accuracy metrics.
- Tablet:Compressed solid form for controlled-release applications in small-scale wine production and portable water treatment. Limited addressable market constrains supplier investment.
Granular and powder formats retain installed base dominance; liquid formulations are climbing the fastest on automation tailwinds.
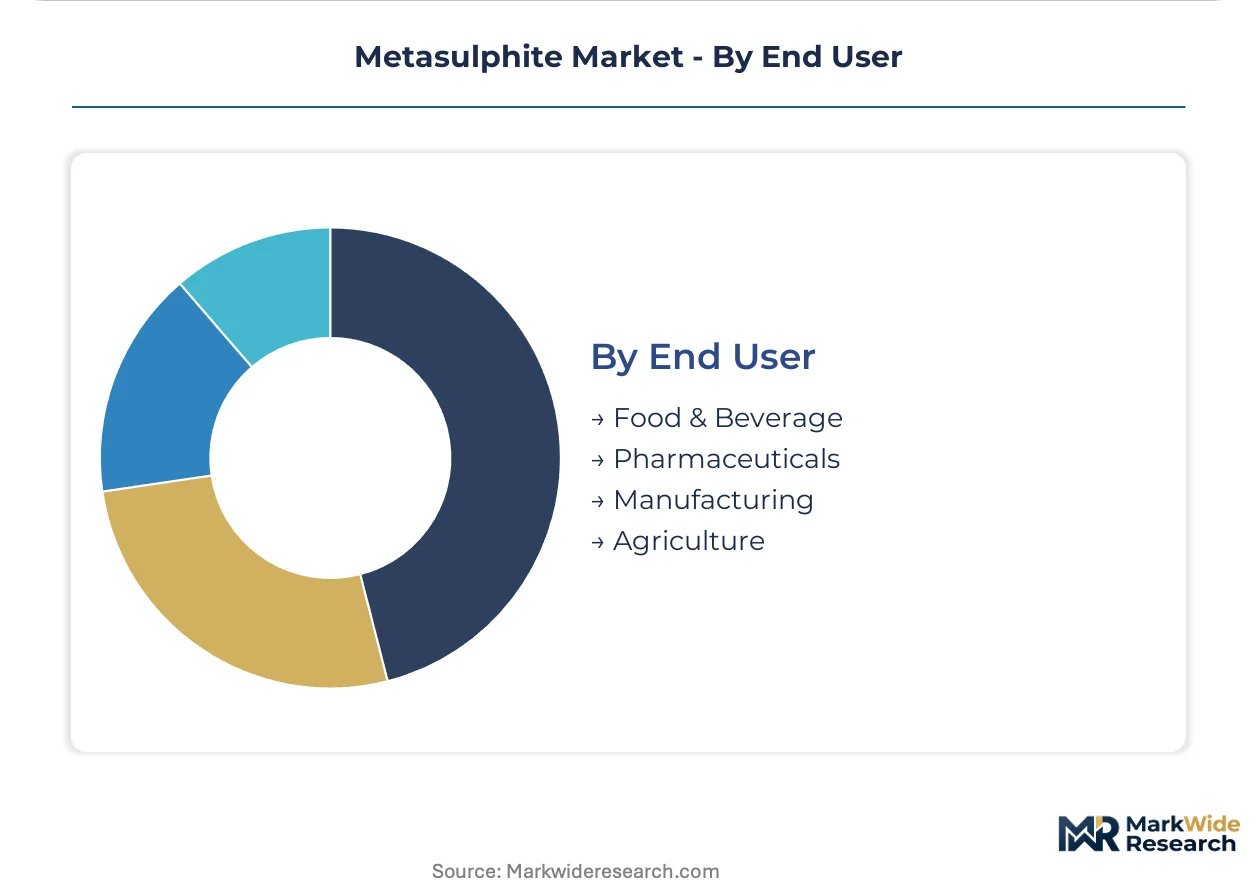
End User:
Customer concentration and compliance sophistication determine supplier partnership depth across vertical markets.
- Food & Beverage:Wine cooperatives and dried fruit processors demand batch-level traceability for REACH and FDA compliance. Certificate-of-analysis documentation and heavy metal testing below 10 ppm limits require specialized quality personnel.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient applications impose pharmacopeial grade requirements with stringent supplier qualification protocols.
- Manufacturing:Pulp and paper mills face EPA effluent guidelines limiting sulphite discharge volumes, redirecting procurement toward higher-purity grades that minimize residual byproduct formation.
- Agriculture:Fumigation and soil treatment applications operate under divergent national residue limits that fragment compliance architectures for multinational suppliers.
Food and beverage anchors revenue concentration; pharmaceuticals sustain the most demanding qualification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic capacity additions in Shandong and Jiangsu provinces are compressing import arbitrage windows and redrawing supply corridors for merchant metasulphite grades. This supply-side shift is forcing legacy traders to anchor around captive alkali linkages or retreat from Asian markets entirely.
China
Municipal dechlorination and oxygen scavenging operations in Shandong and Jiangsu province utilities drive concentrated sodium metasulphite offtake. SAMR maintains divergent maximum residue limits from Western standards, fragmenting compliance architectures for multinational suppliers. Domestic producers in the Yangtze River Delta are narrowing import dependence through integrated sulphur chemistry platforms.
United States
EPA effluent guidelines for pulp and paper mills limit sulphite discharge volumes, redirecting procurement toward higher-purity grades. FDA 21 CFR 182.3766 compliance requirements for sulphite preservatives in wine and dried fruit processing drive specialized grade demand. Manufacturing clusters in the Gulf Coast corridor face feedstock volatility from refinery byproduct sulphur dioxide supply fluctuations.
Germany
REACH restrictions on sulphite labeling in consumer products redirect formulation demand toward lower-residue potassium variants. The EU Green Deal's carbon border adjustment mechanisms favor low-carbon sulphite production routes using renewable energy-integrated chlor-alkali cells. Industrial processors in the Ruhr region and Bavaria are consolidating supplier rosters around certificate-of-analysis documentation capabilities.
India
FSSAI alignment gaps with European and North American standards create first-mover advantage for compliance-capable suppliers in processed food exports. Chlor-alkali energy intensity and potash price exposure limit potassium metasulphite substitution in cost-sensitive textile bleaching applications. Manufacturing clusters in Gujarat and Maharashtra anchor South Asian demand through regional distribution density.
Italy
Wine stabilization applications face compliance cost escalation from EU heavy metal migration limits and taste-neutrality requirements that resist grade substitution. Large cooperative cellars in Tuscany and Piedmont concentrate procurement authority and compress supplier rosters. Mediterranean basin wine regions now demand vendor-managed inventory and technical service support that commodity traders cannot deliver.
Metasulphite Market Competitive Landscape
Integrated sulphur chemistry platforms and specialized food-grade specialists split the market between cost-driven commodity supply and certification-premium segments. The vendor base concentrates around two strategic archetypes: diversified chemical conglomerates leveraging captive raw material positions, and purity-focused specialists competing on batch-level traceability rather than volume pricing. Consolidation of wine production into large cooperative cellars and municipal water treatment automation are compressing supplier rosters and favoring partners with technical service capabilities.
Among European integrated producers, BASF SE and Solvay occupy positions anchored around diversified chemical platforms with sulphur dioxide absorption capabilities. Aditya Birla Chemicals exemplifies the regional-anchored archetype with South Asian distribution density and captive chlor-alkali linkages. Esseco Group represents the specialization-focused tier, competing on food-grade purity certification and compliance documentation rather than unit economics.
| Leading Market Players |
|---|
| BASF SE |
| INEOS Calabrian |
| Solvay |
| Aditya Birla Chemicals |
| Esseco Group |
| Grillo-Werke AG |
| Kailong Chemical Technology |
| Merck KGaA |
| Şişecam |
| Others |
Value Network & Pricing Analysis
Overcapacity signals from Shandong and Jiangsu province chlor-alkali complexes are compressing spot premiums for sodium metasulphite grades and forcing merchant producers toward contract-based offtake structures that lock in volume commitments at thinner margins.
Pricing Analysis
FDA 21 CFR 182.3766 and REACH sulphite labeling restrictions dictate the pricing tier structure across food-grade, industrial-grade, and reagent-grade metasulphite variants. Three-tier pricing structure across premium, standard, and economy levels separates pharmacopeial-certified potassium metasulphite from municipal water treatment sodium grades and commodity textile bleaching powders. Cost compression in standard-grade sodium metasulphite is intensifying because domestic Chinese capacity additions have eliminated import arbitrage. Textile bleaching operations remain most price-sensitive, while wine cooperatives accept premium potassium variant pricing for taste-neutrality compliance.
Supply Chain Analysis
Extended payment terms from municipal utilities and supply-chain finance facilities from integrated chlor-alkali producers are restructuring working capital requirements for merchant distributors. Manufacturing concentrates in China, Germany, and India, with sulphur dioxide feedstock drawn from refinery byproduct streams, smelter off-gas recovery, and dedicated sulphur burning. Single-source vulnerability runs through Yangtze River Delta caustic soda supply that feeds Jiangsu metasulphite plants. Distribution runs through regional chemical distributors with technical service capabilities for automated dosing system integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat opportunity anchored in regulatory entrenchment: batch-level traceability investments for FDA and REACH compliance create switching costs that commodity traders cannot replicate.
For Market Incumbents: Pre-empt margin erosion in sodium metasulphite by securing captive sulphur dioxide supply through refinery partnership agreements or backward integration into smelter off-gas recovery. Expand food-grade certification capabilities ahead of FSSAI alignment demands in India to capture processed food export premiums. For New Entrants and Emerging Players: Establish a beachhead in automated liquid dosing system integration for municipal water treatment utilities in coastal Chinese provinces where labor cost escalation outpaces commodity chemical pricing. Target certificate-of-analysis documentation services as a service-layer wedge rather than competing on volume manufacturing. For Investors and Strategic Acquirers: Capital is best deployed toward integrated sulphur chemistry platforms with captive chlor-alkali linkages and existing REACH batch-traceability infrastructure. The long-term viability window favors producers with renewable energy-integrated cells positioned for EU carbon border adjustment mechanisms. Watch for SAMR residue limit harmonization signals as the inflection trigger for multinational supplier re-entry into Chinese food-grade segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulphur Dioxide Recovery | Secures feedstock cost position against refinery byproduct volatility for Shandong producers. |
| Food-Grade Certification Investment | Captures FDA 21 CFR 182.3766 premiums in wine stabilization applications resistant to grade substitution. |
| Automated Liquid Dosing System Partnership | Virtualizes procurement criteria toward dosing accuracy metrics for Jiangsu municipal utilities. |
| Renewable Energy Chlor-Alkali Transition | Positions European production for EU Green Deal carbon border adjustment mechanism preference. |
| Vendor-Managed Inventory Program | Locks cooperative wine cellar procurement authority away from commodity traders in Tuscany and Piedmont. |
Research Methodology
Desk research of customs trade databases, chlor-alkali industry association reports, and regulatory filing repositories preceded structured interviews with plant managers at integrated sulphur chemistry facilities, procurement leads at Mediterranean wine cooperatives, municipal water treatment utility engineers, and distribution channel partners with technical service capabilities. Primary intelligence combined with secondary validation from SEC filings of listed chemical producers and ECHA REACH registration databases. Bottom-up grade-by-grade demand modeling triangulated against top-down sector consumption estimates.
Forecast assumptions held regulatory frameworks constant across the analysis window while varying feedstock cost trajectories and automation adoption rates. Segmentation modeling spanned product type, application end-use, physical form, and customer compliance sophistication tiers. CAGRs derived from curve-fitting historical price-volume relationships against projected capacity additions and regulatory enforcement intensity. Sulphur dioxide supply volatility and chlor-alkali energy cost exposure served as key sensitivity inputs.
Sensitivities concentrate around SAMR-FDA regulatory harmonization timing, EU carbon border adjustment mechanism implementation scope, and refinery byproduct sulphur dioxide availability shifts. Forecasts reflect documented assumptions on capacity utilization rates and substitution elasticity between sodium and potassium variants. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Calcium Sulphite Market
Specialty Compounds
Global Specialty Amines Market
Specialty Compounds
Polypeptide Market
Specialty Compounds
Carbon Black for Packaging Market
Specialty Compounds
Global Engineering Plastic Compounds Market
Specialty Compounds
Expandable Microspheres Market
Specialty Compounds
Asia-Pacific Chromatography Resins Market
Specialty Compounds
Global Compound Management Market
Specialty Compounds
North America Polyphenylene Sulfide Compounds Market
Specialty Compounds
Eggshell Membrane Derivatives Market
Specialty Compounds
Global Hydrolyzed Collagen Market
Specialty Compounds
Scratch-Resistant Compound Market
Specialty Compounds
Global Heat Stabilizers Market
Specialty Compounds
Galactoarabinan Market
Specialty Compounds
Conductive Plastic Compounds Market
Specialty Compounds
Polyimide Coatings Market