
 Automated Compound Storage and Retrieval (ACSR) Market | 2026-2036
Automated Compound Storage and Retrieval (ACSR) Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Compound Storage and Retrieval (ACSR) Market Outlook
The capital-intensity divergence between players is bifurcating competitive tiers in automated compound storage. Thermo Fisher Scientific leverages its integrated life sciences platform to anchor large-scale pharmaceutical deployments across North America and Europe. Hamilton Company specializes in precision liquid handling and storage robotics, sustaining premium positioning in high-complexity biotech workflows. Liconic AG dominates climate-controlled storage modules, extending its footprint into biobanking and cell therapy supply chains.
Automated Compound Storage and Retrieval (ACSR) systems integrate robotic manipulators, vertical rack architectures, and inventory management software to maintain compounds at controlled temperatures ranging from ambient to minus 150 degrees Celsius while enabling millimeter-scale positional accuracy for sample retrieval. These systems serve pharmaceutical discovery, compound libraries, and biological specimen archives where manual handling risks contamination, temperature excursion, or chain-of-custody breaches. Robotic Systems and Management Software capture the dominant share of capital expenditure as laboratories prioritize throughput and regulatory traceability over standalone rack infrastructure. Biobanking and Research Laboratories represent the fastest-growing application segments as precision medicine initiatives and longitudinal population studies expand specimen collection volumes.
FDA 21 CFR Part 11, EMA Annex 11, and ISO 20387 biobanking standards collectively mandate electronic records integrity, temperature monitoring validation, and sample quality management that directly shape ACSR system specifications and procurement criteria. The EPA and OSHA frameworks further influence chemical storage automation through hazard communication and worker exposure limits that drive substitution of manual handling with enclosed robotic retrieval. Stakeholders must monitor evolving GxP inspection guidance on AI-enabled inventory prediction and real-time environmental monitoring as these capabilities transition from competitive differentiators to baseline compliance expectations.
Market Dynamics
The Automated Compound Storage and Retrieval market is experiencing structural pressure from regulatory digitization mandates that require validated electronic records and full sample traceability, forcing facilities to replace manual storage with robotic systems capable of millimeter-scale positional accuracy and continuous environmental monitoring.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records integrity requirements are compelling pharmaceutical manufacturers to deploy automated storage with audit trails and electronic signatures, eliminating paper-based compound tracking.
- High-throughput screening pipelines:Biotech clusters in Boston and San Francisco are expanding capital deployment in integrated robotic infrastructure to accelerate drug discovery workflows.
- ISO 20387 biobanking standards:Quality management and temperature validation protocols are driving specimen archives toward climate-controlled automated retrieval systems.
Market Restraints
- Capital intensity:Robotic manipulators and minus 150 degrees Celsius storage modules require substantial upfront investment that constrains mid-size laboratory adoption.
- Supply concentration:Precision liquid handling components and specialized rack architectures depend on a limited supplier base concentrated in German and Swiss manufacturing hubs.
- Technical limitation:Millimeter-scale positional accuracy degrades in high-humidity environments, restricting deployment in facilities without climate-controlled infrastructure.
Strategic Opportunities
- Cell therapy supply chains:Biobanking applications for CAR-T and regenerative medicine are creating demand for ultra-low temperature automated retrieval in precision medicine initiatives.
- EMA Annex 11 computerized systems guidelines:European pharmaceutical facilities face compliance deadlines that favor validated automated storage with real-time environmental monitoring.
- AI-enabled inventory prediction:Machine learning integration with management software is converging with robotic retrieval to optimize compound utilization and reduce search times.
Industry Challenges
- Validation timelines:GxP inspection requirements for computerized systems extend procurement-to-deployment cycles by 12-18 months as facilities complete protocol documentation.
- Integration complexity:Legacy laboratory information management systems require custom middleware development to interface with modern robotic storage APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Compound Storage and Retrieval (ACSR) Market |
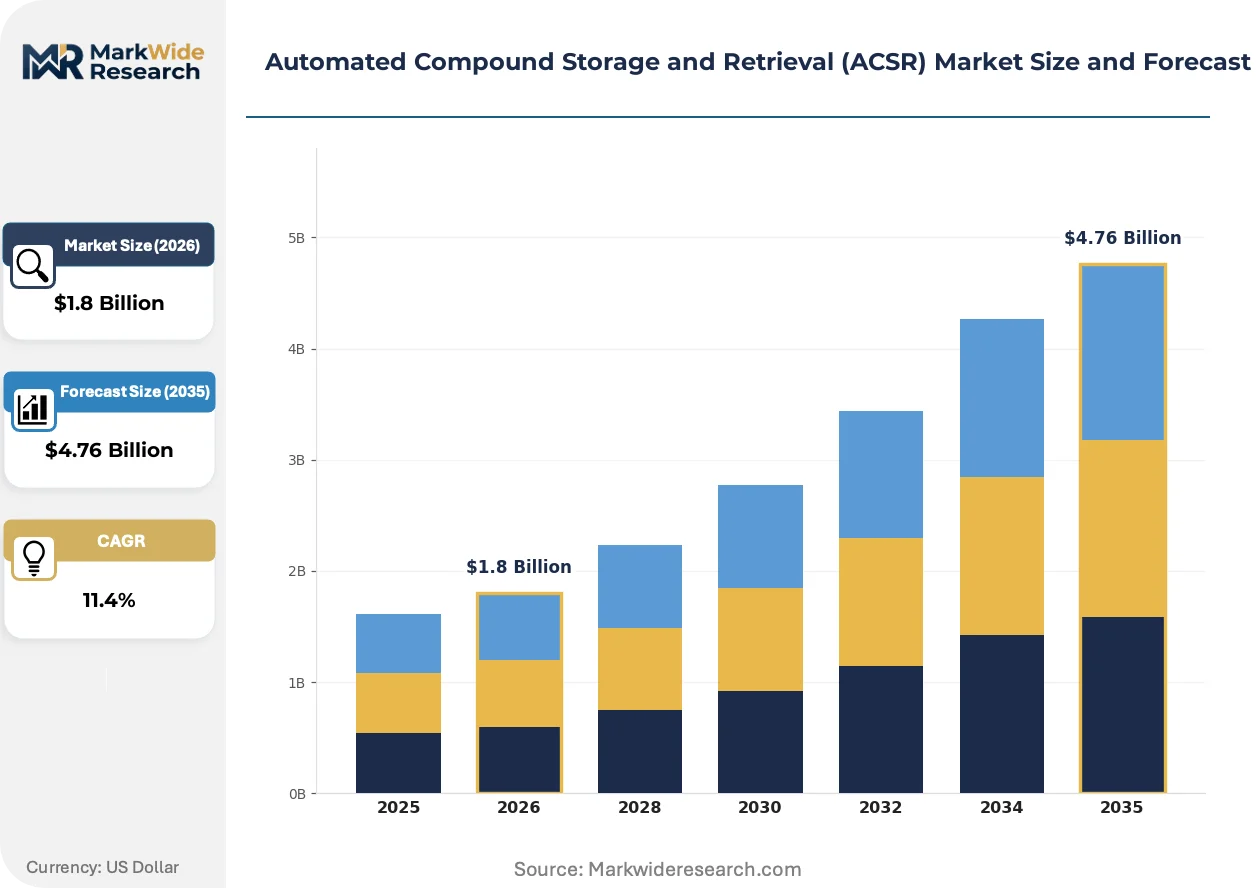
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Systems, Rack Systems, Algorithms, Management Software Application: Pharmaceuticals, Biobanking, Research Laboratories, Chemical Storage End User: Biotech Companies, Academic Institutions, Contract Research Organizations, Pharmaceutical Manufacturers Technology: Automated Guided Vehicles, Vertical Storage, Retrieval Systems, Real-time Monitoring |
| Companies Covered | Thermo Fisher Scientific, Hamilton Company, Tecan Group Ltd., Brooks Life Sciences, Azenta Life Sciences, Liconic AG, SPT Labtech, Biosero Inc., HighRes Biosolutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Compound Storage and Retrieval (ACSR) Market Strategic Shifts
Robotic architectures are displacing conventional storage paradigms through modular vertical rack designs that integrate with inventory management software, while regulatory frameworks accelerate the shift from manual to automated compound handling across pharmaceutical and biobanking facilities.
Modular climate-controlled storage units are displacing centralized cold room approaches in biobanking operations. Cell therapy manufacturers and longitudinal population study repositories are adopting distributed rack architectures that enable minus 150 degrees Celsius retrieval at multiple access points. This topology is displacing single-point-of-failure designs and enabling specimen processing workflows that previously required manual sample transport across facilities.
EMA Annex 11 and FDA 21 CFR Part 11 are converging on real-time environmental monitoring as a baseline requirement. Pharmaceutical manufacturers must now demonstrate continuous temperature logging with automated alerts for excursion events. High-throughput screening facilities in Germany and Switzerland are retrofitting existing storage with sensor networks and validated software interfaces to meet combined US-European audit standards.
Service unbundling is fragmenting traditional capital equipment sales. Biotech startups in San Francisco and Boston are procuring automated storage through usage-based contracts that separate hardware acquisition from software licensing and maintenance. This model is compressing initial capital outlays while shifting lifecycle costs to operational budgets, particularly among venture-funded discovery platforms prioritizing cash flow flexibility over asset ownership.
Automated Compound Storage and Retrieval (ACSR) Market Segmentation
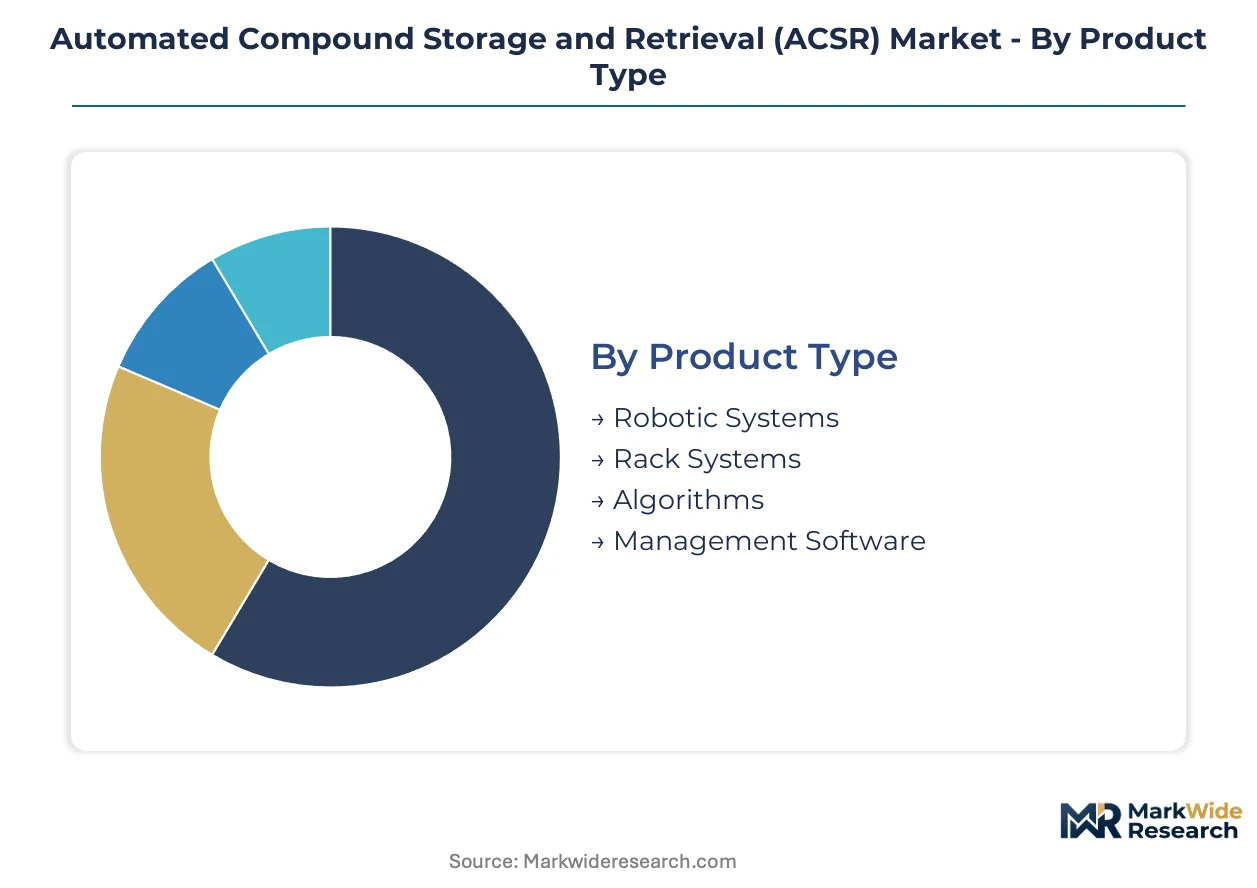
ACSR procurement decisions bifurcate sharply between high-throughput pharmaceutical manufacturers requiring validated GxP compliance and research laboratories prioritizing configurability over audit rigor. Segmentation reveals how regulatory tiering, sample volume thresholds, and integration complexity reshape vendor selection criteria across end-use categories.
Product Type:
FDA 21 CFR Part 11 and EMA Annex 11 impose divergent validation burdens on hardware versus software components, with electronic records modules facing stricter qualification protocols than mechanical subsystems.
- Robotic Systems:Multi-axis manipulators with millimeter-scale positional accuracy execute sample retrieval across temperature ranges from ambient to minus 150 degrees Celsius. Pharmaceutical manufacturers in Germany and Switzerland deploy these for high-throughput screening pipelines where manual handling risks contamination or chain-of-custody breaches.
- Management Software:Inventory tracking platforms integrate electronic signatures, audit trails, and environmental logging to satisfy FDA and EMA computerized systems guidelines. Biotech clusters in Boston and San Francisco prioritize these modules for real-time specimen traceability across distributed research operations.
- Rack Systems:Modular vertical architectures enable climate-controlled storage density in facilities with constrained floor space.
- Algorithms:AI-enabled inventory prediction tools optimize retrieval sequencing and compound utilization rates.
Robotic Systems handle the majority of throughput; Management Software is expanding most quickly on share as regulatory digitization mandates accelerate.
Application:
Cost tiering separates capital-intensive pharmaceutical deployments from mid-budget research laboratory installations, with biobanking operations occupying a middle tier driven by ISO 20387 quality management requirements.
- Biobanking:Longitudinal population studies and precision medicine initiatives demand climate-controlled automated retrieval for specimen archives spanning decades. Cell therapy manufacturers in the United States and Switzerland are expanding minus 150 degrees Celsius infrastructure for CAR-T supply chains.
- Pharmaceuticals:High-throughput screening pipelines integrate ACSR with liquid handling workstations to accelerate drug discovery workflows. Major manufacturers prioritize validated systems with continuous temperature monitoring to satisfy combined US-European audit standards.
- Research Laboratories:Academic and government facilities balance configurability against capital constraints.
- Chemical Storage:EPA and OSHA hazard communication requirements drive substitution of manual handling with enclosed robotic retrieval for hazardous compounds.
Pharmaceuticals commands the largest installed base; Biobanking is climbing the fastest as cell therapy commercialization expands specimen processing volumes.
End User:
Customer type determines procurement modality, with pharmaceutical manufacturers favoring capital purchase and validation packages while contract research organizations increasingly adopt usage-based contracting to preserve cash flow flexibility.
- Pharmaceutical Manufacturers:Large-scale deployers require integrated robotic infrastructure with full GxP qualification documentation. These facilities in the United States and Germany extend procurement-to-deployment cycles by 12-18 months to complete protocol validation.
- Biotech Companies:Venture-funded discovery platforms in Boston and San Francisco prioritize modular systems with rapid reconfiguration for evolving assay portfolios.
- Contract Research Organizations:Service providers demand flexible capacity scaling across client programs.
- Academic Institutions:University laboratories face capital constraints that favor shared core facility models over individual installations.
Pharmaceutical Manufacturers dominate capital deployment; Biotech Companies are gaining share fastest through venture-funded expansion in major research clusters.
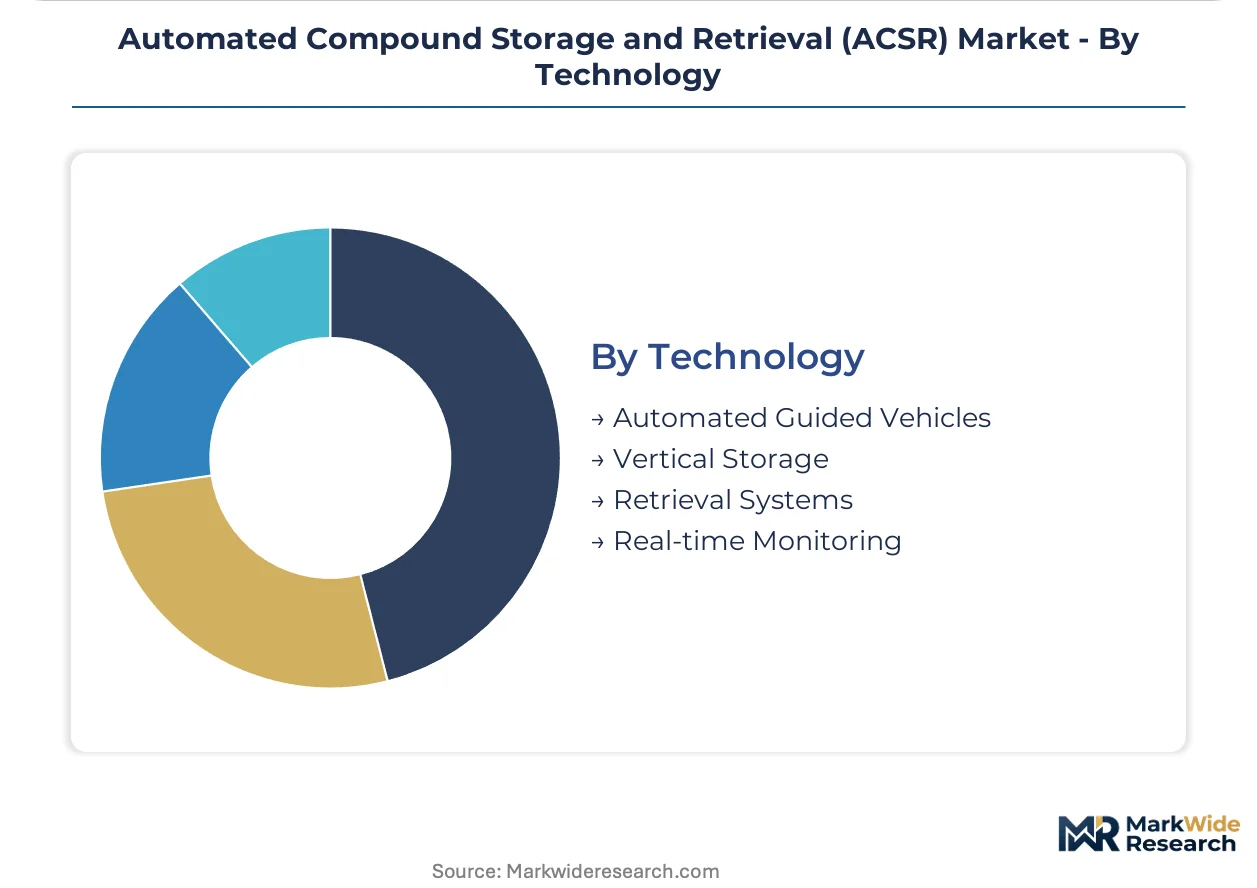
Technology:
Supply concentration in German and Swiss manufacturing hubs shapes availability of precision components, with vertical storage architectures and real-time monitoring systems commanding premium positioning.
- Vertical Storage:Rack configurations maximize cubic density in facilities with limited footprint, enabling minus 150 degrees Celsius retrieval at multiple access points. Distributed architectures are displacing single-point-of-failure designs in biobanking operations across the United States and Switzerland.
- Real-time Monitoring:Sensor networks deliver continuous temperature logging with automated excursion alerts to satisfy EMA and FDA convergence on environmental surveillance. High-throughput screening facilities in Germany retrofit existing infrastructure with validated interfaces.
- Automated Guided Vehicles:Mobile transport systems enable specimen movement across facilities without manual handling.
- Retrieval Systems:Pick-and-place mechanisms integrate with inventory software for millimeter-scale positional accuracy.
Vertical Storage anchors the majority of installed capacity; Real-time Monitoring shows the steepest expansion trajectory as regulatory frameworks mandate continuous environmental surveillance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in automated compound storage equipment tilt toward net imports in emerging biotech hubs while established manufacturing centers in Germany and Switzerland maintain trade surpluses in precision robotic components. Capital deployment concentrates where regulatory validation requirements intersect with high-throughput screening infrastructure expansion.
United States
FDA 21 CFR Part 11 compliance deadlines and cell therapy commercialization propel demand for validated automated storage with audit trails. Boston and San Francisco biotech clusters drive capital expenditure in integrated robotic infrastructure for drug discovery pipelines. Venture-funded discovery platforms in these metros prioritize modular systems with rapid reconfiguration capabilities.
Germany
EMA Annex 11 computerized systems guidelines and high-throughput screening facility retrofits accelerate procurement of sensor networks with validated software interfaces. German pharmaceutical manufacturers extend procurement-to-deployment cycles by 12-18 months to complete GxP protocol documentation. The Rhine-Main and Upper Bavaria regions concentrate precision component manufacturing for robotic manipulators.
Switzerland
Swissmedic requirements for pharmaceutical quality management and ISO 20387 biobanking standards drive specimen archives toward climate-controlled automated retrieval. Cell therapy manufacturers expand minus 150 degrees Celsius infrastructure for CAR-T supply chains. Basel and Zurich anchor precision liquid handling component production for European distribution.
China
NMPA digitization mandates for pharmaceutical records and domestic biotech expansion create demand for electronic signature-enabled inventory platforms. National pharmaceutical regulator guidelines on computerized systems push facilities toward automated environmental monitoring. Shanghai and Suzhou biotech parks deploy integrated robotic storage to accelerate discovery workflows.
United Kingdom
MHRA convergence with FDA and EMA standards on electronic records integrity compels pharmaceutical manufacturers to replace manual compound tracking. London and Cambridge biotech clusters invest in robotic infrastructure for precision medicine initiatives. Academic core facilities balance capital constraints against configurability requirements for longitudinal population studies.
Automated Compound Storage and Retrieval (ACSR) Market Competitive Environment
Concentration sits with diversified life sciences conglomerates and precision robotics specialists that anchor distinct competitive tiers. The vendor base stratifies between integrated platform providers capable of full GxP validation packages and modular specialists serving reconfigurable research workflows. Two strategic archetypes dominate: vertically integrated conglomerates leveraging cross-selling from adjacent instrumentation portfolios, and focused robotics houses commanding premium positioning in high-complexity liquid handling applications. Competitive moves center on strategic partnerships for middleware development and geographic expansion into emerging biotech clusters.
Within the diversified conglomerate tier, Thermo Fisher Scientific occupies a position exemplifying integrated life sciences platform breadth. Hamilton Company and Liconic AG represent precision-focused specialists anchoring premium market segments. These three companies collectively illustrate the competitive bifurcation between scale-driven full-service provision and targeted excellence in climate-controlled storage modules or liquid handling robotics.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Hamilton Company |
| Tecan Group Ltd. |
| Brooks Life Sciences |
| Azenta Life Sciences |
| Liconic AG |
| SPT Labtech |
| Biosero Inc. |
| HighRes Biosolutions |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at German and Swiss precision manufacturing hubs creates scale economies that compress unit costs for robotic manipulators while establishing price floors for climate-controlled storage modules. Pharmaceutical manufacturers in Boston and San Francisco absorb premium positioning for validated GxP systems, whereas mid-size research laboratories face capital barriers that segment procurement tiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Pharmaceutical manufacturers with FDA 21 CFR Part 11 validation requirements pay premiums for electronic records modules and audit trail software, while academic core facilities select economy-tier rack systems with reduced configurability. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in standard-tier robotic systems is intensifying because venture-funded biotech startups in San Francisco demand usage-based contracting with compressed initial outlays. Contract research organizations exhibit the highest price sensitivity due to cash flow constraints across client programs.
Supply Chain Analysis
Germany and Switzerland anchor precision component production for multi-axis manipulators and climate-controlled storage architectures. Robotic Systems draw from specialized suppliers of linear motion controls, cryogenic insulation materials, and validated sensor networks concentrated in Rhine-Main and Upper Bavaria manufacturing corridors. Single-source vulnerability in precision liquid handling components creates exposure to extended lead times when Swissmedic or FDA inspection backlogs delay qualification protocols. Distribution runs through direct sales forces for pharmaceutical manufacturers and channel partners serving research laboratory segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward pharmaceutical manufacturers consolidating procurement across high-throughput screening pipelines, fragmenting vendor negotiation leverage. Contract research organization consolidation in Boston and San Francisco amplifies volume concentration among price-sensitive purchasers.
For Market Incumbents: Consolidate middleware development capabilities to reduce integration complexity with legacy laboratory information management systems. Deepen captive supply of precision liquid handling components to offset tariff exposure in German and Swiss manufacturing hubs. Lock in pharmaceutical manufacturers through bundled validation packages that extend switching costs. For New Entrants and Emerging Players: Differentiate on AI-enabled inventory prediction modules that optimize retrieval sequencing for biobanking operations. Target academic core facilities in the United Kingdom and China where capital constraints favor shared infrastructure models over individual installations. Pursue strategic partnerships with established management software vendors to bypass 12-18 month GxP validation timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision robotics specialists with defensible climate-controlled storage expertise over diversified conglomerates exposed to cross-selling margin pressure. Long-term viability hinges on cell therapy commercialization sustaining demand for minus 150 degrees Celsius infrastructure. Monitor EMA Annex 11 enforcement patterns across European pharmaceutical facilities as an inflection indicator for real-time environmental monitoring adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Middleware Development Partnership | Reduces integration friction with legacy LIMS platforms at German pharmaceutical facilities. |
| AI-Enabled Inventory Module Launch | Accelerates retrieval sequencing optimization for CAR-T supply chain manufacturers. |
| Usage-Based Contracting Model | Captures venture-funded biotech demand in Boston and San Francisco clusters. |
| Validation Documentation Package | Compresses procurement-to-deployment cycles for FDA 21 CFR Part 11 compliance deadlines. |
| Cryogenic Component Supply Agreement | Secures precision liquid handling capacity from Swiss manufacturing hubs. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical manufacturing executives, biobanking operations directors, regulatory affairs specialists, and laboratory procurement managers. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA Annex 11 computerized systems guidelines, ISO 20387 biobanking standards, and SEC filings from publicly traded life sciences instrumentation providers. Bottom-up segmentation analysis triangulated against top-down market sizing from trade flow data and capital expenditure disclosures across major biotech clusters.
Across the analysis window, the forecast framework modeled product type segmentation, application tiering, end-user procurement modality, and technology architecture adoption patterns. CAGRs were derived from regression analysis against pharmaceutical R&D expenditure trends and biobanking specimen volume trajectories. Industry-specific inputs included high-throughput screening pipeline expansion rates and cell therapy commercialization timelines for CAR-T manufacturing infrastructure.
Material uncertainties — regulatory enforcement intensity for AI-enabled inventory systems, supply chain disruptions in German precision component manufacturing, and venture capital availability for biotech startup expansion — sit outside the modeled envelope. Forecasts reflect documented assumptions about GxP validation protocol durations and temperature monitoring technology adoption curves. Recalibration cycles align with material shifts in FDA inspection guidance and EMA computerized systems enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Special Effect Masterbatches Market
Specialty Compounds
Gulf Collagen Market
Specialty Compounds
Middle East and Africa Polypropylene Compounds Market
Specialty Compounds
Global Color Masterbatch Market
Specialty Compounds
Superacids Market
Specialty Compounds
Middle East and Africa Color Masterbatch Market
Specialty Compounds
EPDM Sealing Strip Market
Specialty Compounds
United States Caustic Potash Market
Specialty Compounds
Compounds Market
Specialty Compounds
Gypsum-Free Plaster Market
Specialty Compounds
Chromium Phosphate Market
Specialty Compounds
Global Sulfur Hexafluoride Market
Specialty Compounds
Spackling Paste Market
Specialty Compounds
Tosyl Chloride Market
Specialty Compounds
Global Masterbatch Market
Specialty Compounds
Low Density Sheet Moulding Compound (SMC) Market