
 Liquid Ammonium and Liquid Potassium Thiosulfate Market | 2026-2036
Liquid Ammonium and Liquid Potassium Thiosulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Ammonium and Liquid Potassium Thiosulfate Market Analysis
Fertilizer distributor networks across the North American Corn Belt is rewriting procurement patterns for sulfur-containing liquid nutrients. Nutrien Ltd. leverages its retail agronomy footprint to push bundled thiosulfate-fertigation programs directly to farm gate customers. Yara International ASA anchors European supply through its Norwegian production complex, while CF Industries Holdings, Inc. competes on ammonia integration economics at its US Gulf Coast manufacturing hubs.
Liquid ammonium thiosulfate and liquid potassium thiosulfate denote aqueous fertilizer solutions containing thiosulfate anions complexed with ammonium or potassium cations, typically formulated at 60% solution concentration with 12% nitrogen and 26% sulfur content for ammonium variants, designed primarily for fertigation and foliar feeding in sulfur-deficient soils. These products serve commercial agriculture where sulfur availability limits protein synthesis in oilseed and legume crops. Agriculture end-use dominates volume consumption, though horticulture segments command margin premiums through precision greenhouse dosing systems. Direct sales channels sustain the strongest producer-farmer relationships in row-crop regions, while agricultural cooperatives consolidate smaller operator demand in the US Midwest and Canadian prairies.
EPA nutrient management guidelines and state-level 4R nutrient stewardship programs in Iowa and Illinois shape product registration and application training requirements for thiosulfate fertilizers. REACH chemical registration in the European Union governs import specifications and labeling standards for potassium thiosulfate entering member state markets. Stakeholders must monitor evolving carbon border adjustment mechanisms and farm bill conservation title funding shifts that could restructure sulfur fertilizer cost competitiveness against alternative amendments.
Market Dynamics
The EPA's revised nutrient management guidelines for agricultural runoff are pressuring conventional fertilizer formulations toward lower-salt-index alternatives, forcing sulfur supplementation strategies toward thiosulfate-based liquid solutions that integrate with precision fertigation infrastructure.
Growth Catalysts
- 4R Nutrient Stewardship Programs:State-level implementation in Iowa and Illinois mandates optimized fertilizer placement, accelerating thiosulfate adoption for in-season sulfur delivery through irrigation systems.
- Pivot Irrigation Expansion:Brazil's Mato Grosso soybean belt demonstrates concentrated demand where liquid injection systems displace dry ammonium sulfate in premium operations.
- Specialty Crop Intensification:California's Central Valley almond and grape growers favor thiosulfate-based fertigation for precise sulfur timing during critical reproductive stages.
Market Restraints
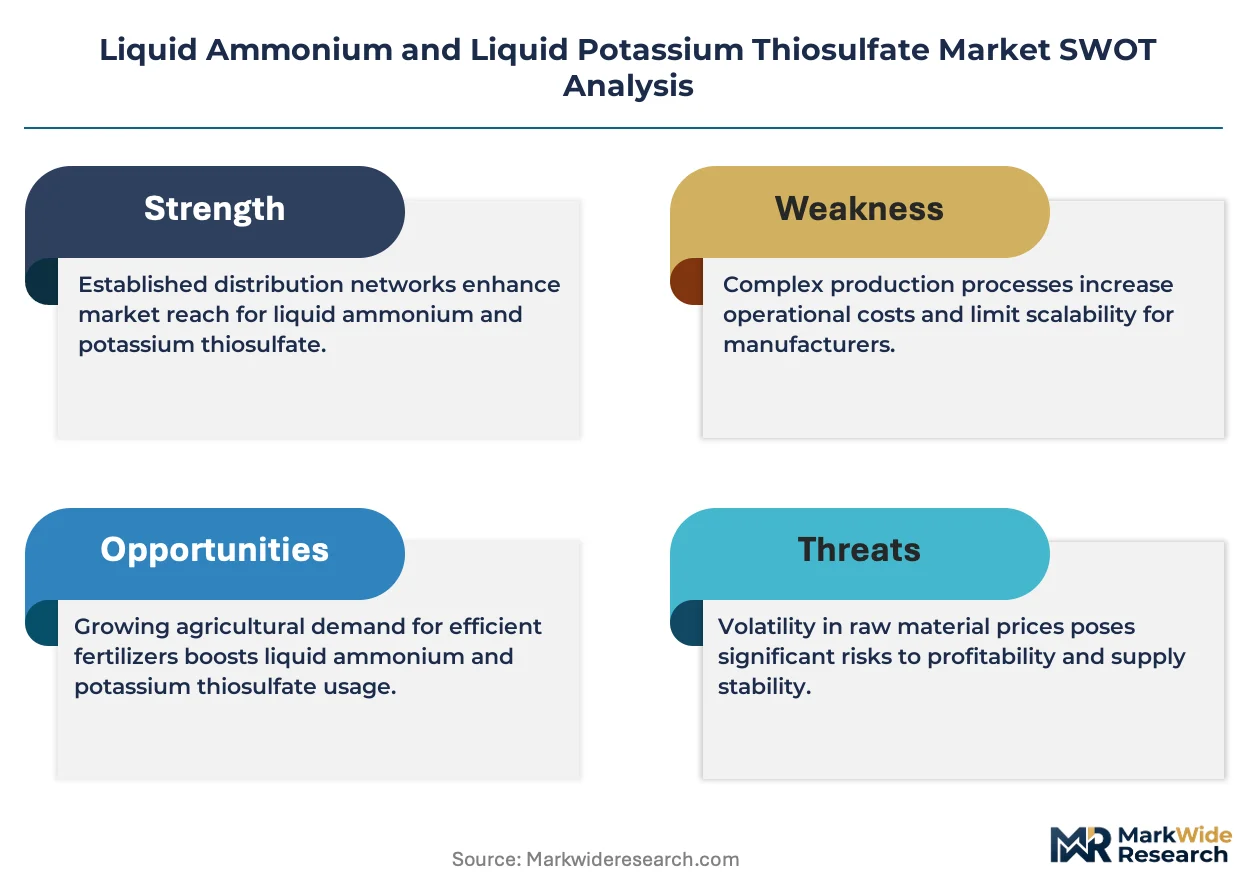
- Feedstock Ammonia Volatility:Natural gas price fluctuations directly compress manufacturing margins for ammonium thiosulfate producers operating at US Gulf Coast ammonia hubs.
- Norwegian Supply Concentration:European potassium thiosulfate availability hinges on Yara International's single Norwegian production complex, creating geographic vulnerability to shipping disruptions.
- Dry Sulfate Competition:Ammonium sulfate retains cost advantage in broadcast application scenarios where irrigation infrastructure is absent or underdeveloped.
Strategic Opportunities
- Carbon Border Adjustment Mechanisms:EU Green Deal implementation creates preferential market access for low-carbon sulfur fertilizer production, rewarding process efficiency investments.
- Greenhouse Precision Dosing:Horticulture segments command margin premiums through automated thiosulfate injection systems in controlled-environment vegetable production.
- Direct-to-Farm Channel Development:Bundled thiosulfate-fertigation programs bypass traditional cooperative distribution, capturing margin from agronomy service integration.
Industry Challenges
- Application Equipment Calibration:Thiosulfate solution compatibility requires retrofit of legacy injection pumps and flow meters designed for urea-ammonium nitrate formulations.
- REACH Registration Complexity:Potassium thiosulfate import specifications demand extensive ECHA documentation, extending market entry timelines for non-European suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Ammonium and Liquid Potassium Thiosulfate Market |
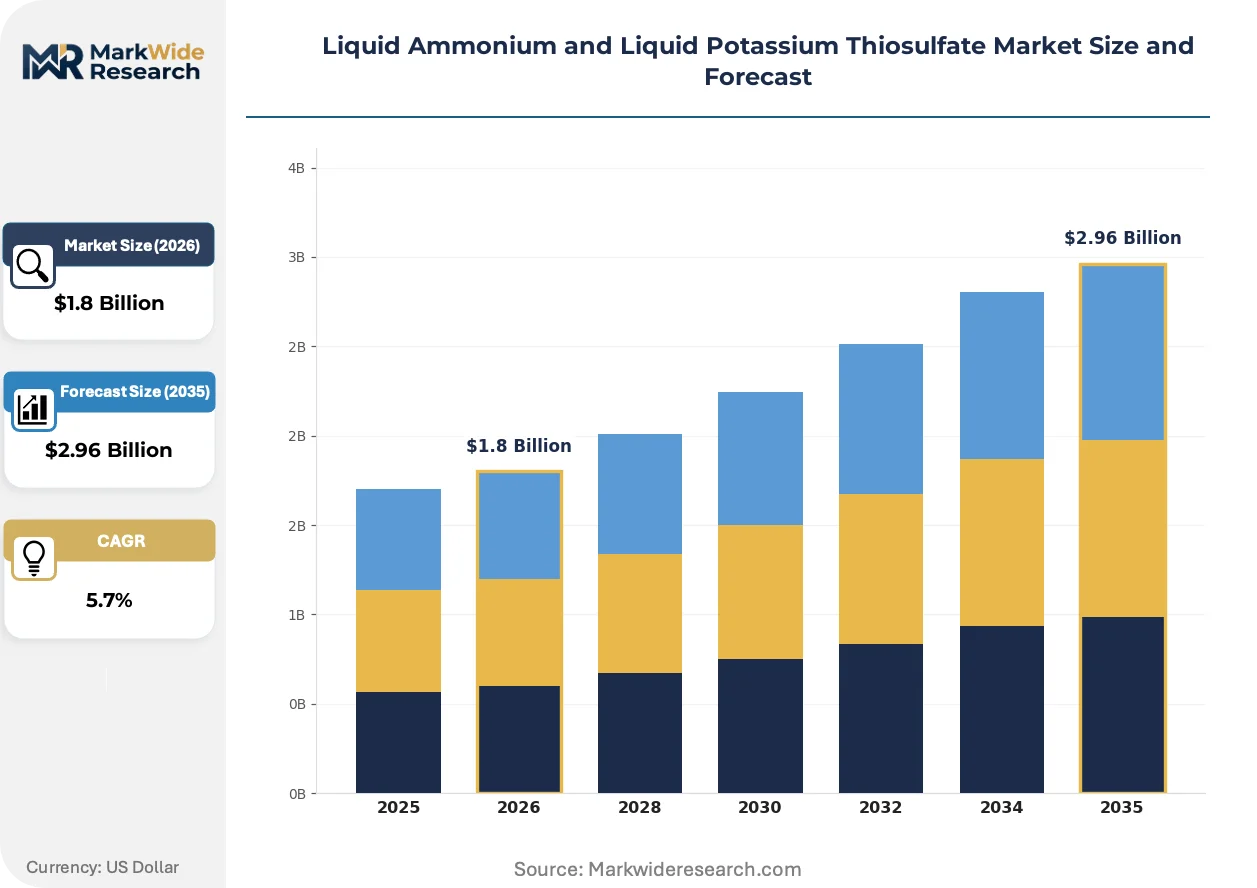
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Ammonium, Liquid Potassium Thiosulfate, Aqueous Solutions, Fertilizer Blends End Use: Agriculture, Horticulture, Industrial, Chemical Processing Molecule Type: Thiosulfate, Ammonium, Potassium, Nutrient Additives Distribution Channel: Direct Sales, Online Retail, Agricultural Cooperatives, Wholesalers |
| Companies Covered | Nutrien Ltd., Yara International ASA, CF Industries Holdings, Inc., Tessenderlo Group, Martin Midstream Partners, Mears Fertilizer, Inc., Plant Food Company, Inc., The Mosaic Company, TerraLink Horticulture Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Ammonium and Liquid Potassium Thiosulfate Market Emerging Trajectories
Active innovation centers on integration between liquid sulfur chemistry and digital agriculture platforms, with formulation science converging on sensor-enabled variable-rate application systems.
Variable-rate thiosulfate injection technology is migrating from static prescription maps to real-time soil sensor feedback loops. Specialty crop operations in California's Central Valley deploy these systems for within-field sulfur adjustments. The technology is migrating from early-adopter almond orchards toward mainstream row-crop adoption, compressing the premium window for precision application services.
REACH chemical registration governs potassium thiosulfate import specifications and labeling standards across European Union member state markets. Industrial consequence includes mandatory safety data sheet harmonization and extended substance evaluation timelines. Fertilizer distributors serving Dutch and German horticulture clusters absorb compliance costs through dedicated regulatory affairs staffing.
Cooperative consolidation among smaller operators in the US Midwest and Canadian prairies is compressing buyer fragmentation. Agricultural cooperatives now aggregate thiosulfate demand into volume contracts that bypass traditional distributor tiers. This pattern is most visible in Iowa and Illinois where 4R nutrient stewardship program participation concentrates procurement through certified agronomy providers.
Liquid Ammonium and Liquid Potassium Thiosulfate Market Segmentation
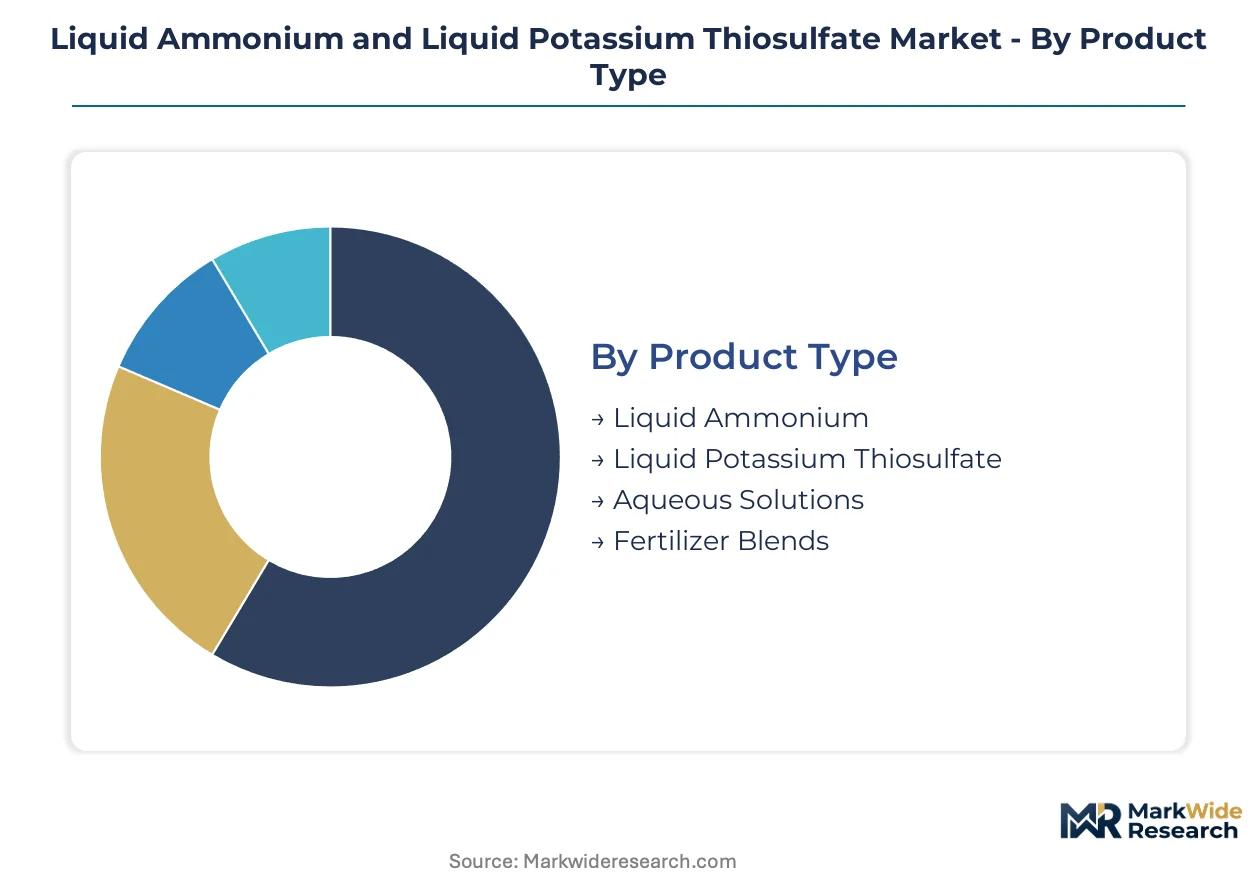
Segmentation in liquid thiosulfate markets reveals how formulation chemistry, application method, and procurement channel determine margin capture and customer loyalty. Each dimension exposes distinct competitive dynamics between bulk commodity positioning and precision agriculture services.
Product Type:
Mature commodity formulations dominate volume, while emerging solution variants capture premium positioning through compatibility advantages.
- Liquid Ammonium Thiosulfate:Standard 60% aqueous solution delivering 12% nitrogen and 26% sulfur content serves as the workhorse formulation for pivot irrigation injection. Demand concentrates in Brazil's Mato Grosso soybean belt where liquid injection systems displace dry ammonium sulfate in premium operations facing EPA nutrient runoff pressure.
- Liquid Potassium Thiosulfate:Zero-nitrogen alternative formulated for chloride-sensitive crops and sulfur-deficient soils requiring potassium supplementation. California Central Valley almond and grape growers favor this chemistry for precise sulfur timing during critical reproductive stages without nitrogen excess.
- Aqueous Solutions:Dilute formulations for foliar feeding and greenhouse fertigation systems.
- Fertilizer Blends:Thiosulfate-integrated NPK combinations for single-pass application efficiency.
Liquid ammonium thiosulfate handles the majority of throughput; liquid potassium thiosulfate is the fastest mover on share.
End Use:
Application intensity separates high-volume field crop consumption from precision dosing premiums in controlled environments.
- Agriculture:Dominant volume segment encompassing row-crop sulfur supplementation through fertigation and sidedress application. Iowa and Illinois 4R nutrient stewardship programs mandate optimized placement, accelerating in-season sulfur delivery through certified agronomy providers.
- Horticulture:Greenhouse and nursery operations command margin premiums through automated injection systems and sensor-enabled variable-rate dosing. Dutch and German horticulture clusters absorb REACH compliance costs through dedicated regulatory staffing.
- Industrial:Mining flotation and water treatment applications.
- Chemical Processing:Reducing agent and intermediate uses in specialty manufacturing.
Agriculture commands absolute volume leadership; horticulture is climbing the fastest on value per ton.
Molecule Type:
Core chemistry versus additive positioning determines manufacturing integration depth and import dependency.
- Thiosulfate:Functional anion enabling sulfur availability in reduced form for plant protein synthesis.
- Ammonium:Nitrogen carrier complex subject to natural gas feedstock volatility at US Gulf Coast manufacturing hubs.
- Potassium:Cation alternative for chloride-sensitive cropping systems with supply concentrated through Yara International's Norwegian production complex.
- Nutrient Additives:Micronutrient and stabilizer packages for enhanced uptake efficiency.
Thiosulfate chemistry anchors all formulation; potassium complexation is gaining share fastest in specialty crop regions.
Distribution Channel:
Channel structure determines producer margin retention versus cooperative buying power consolidation.
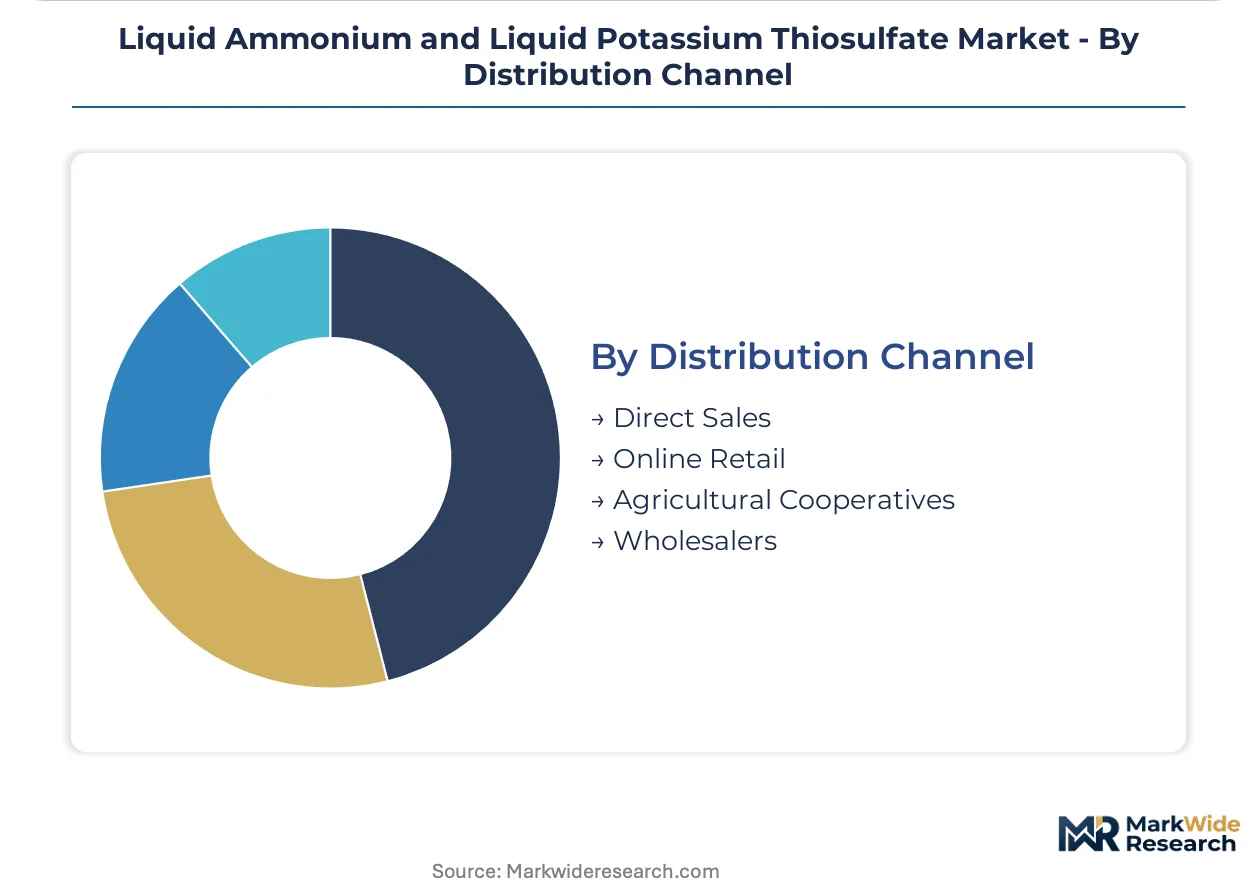
- Direct Sales:Bundled thiosulfate-fertigation programs bypass traditional tiers, capturing margin from agronomy service integration. Nutrien Ltd. leverages retail agronomy footprint to push programs directly to farm gate customers across the North American Corn Belt.
- Agricultural Cooperatives:Iowa and Illinois consolidation aggregates demand into volume contracts that bypass distributor tiers, compressing buyer fragmentation.
- Online Retail:Emerging platform for smaller operator procurement and technical documentation access.
- Wholesalers:Traditional bulk distribution for undifferentiated commodity formulations.
Direct sales channels sustain the strongest producer-farmer relationships; agricultural cooperatives are expanding fastest through 4R program concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA nutrient management guidelines and state-level 4R nutrient stewardship programs are accelerating thiosulfate adoption across major agricultural economies. Brazil's pivot irrigation expansion and California's specialty crop intensification concentrate visible demand. European REACH compliance and carbon border mechanisms reshape import competitiveness.
United States
Iowa and Illinois 4R nutrient stewardship programs mandate optimized fertilizer placement, driving certified agronomy providers toward liquid thiosulfate for in-season sulfur delivery. The EPA's revised runoff guidelines pressure conventional formulations toward lower-salt-index alternatives. Nutrien Ltd. leverages its retail footprint to push bundled fertigation programs directly to farm gate customers across the Corn Belt.
Brazil
Mato Grosso's soybean belt demonstrates the most concentrated regional demand globally, where liquid thiosulfate injection into pivot irrigation systems has displaced dry ammonium sulfate in premium operations. State-level environmental licensing for large-scale irrigation projects favors precision nutrient delivery systems. The Cerrado agricultural frontier anchors thiosulfate volume growth through mechanized row-crop expansion.
Canada
Agricultural cooperatives across the Prairie Provinces aggregate thiosulfate demand into volume contracts that bypass traditional distributor tiers. Health Canada and PMRA regulate fertilizer registration and labeling standards for potassium thiosulfate entering horticulture markets. Saskatchewan and Manitoba wheat operations increasingly adopt liquid sulfur supplementation through center-pivot and lateral-move irrigation infrastructure.
Germany
Dutch and German horticulture clusters absorb REACH compliance costs through dedicated regulatory affairs staffing for potassium thiosulfate import specifications. The EU Green Deal's carbon border adjustment mechanisms create preferential market access for low-carbon sulfur fertilizer production. The Lower Rhine region's greenhouse vegetable production commands margin premiums through automated thiosulfate injection systems.
China
Dual carbon goals and agricultural non-point source pollution controls under MEE direction are pressuring fertilizer formulations toward precision delivery systems. The Yangtze River Delta's intensified horticulture and protected vegetable production creates demand for chloride-sensitive crop formulations. Shandong Province's greenhouse clusters increasingly specify potassium thiosulfate for sulfur timing without nitrogen excess.
Liquid Ammonium and Liquid Potassium Thiosulfate Market Vendor Landscape
On the supply side, the industry is moderately consolidated around integrated ammonia producers and specialty fertilizer distributors. Three archetypes dominate: ammonia-integrated manufacturers leveraging Gulf Coast feedstock economics, Norwegian-centered European suppliers commanding REACH-registered potassium formulations, and North American retail agronomy networks bundling thiosulfate with precision application services. Competitive moves concentrate on direct-to-farm channel development and carbon-intensity positioning for EU market access.
Within the integrated manufacturing tier, Nutrien Ltd., Yara International ASA, and CF Industries Holdings, Inc. occupy positions that exemplify distinct strategic vectors. Nutrien represents the retail-integrated archetype with farm gate distribution control. Yara anchors European supply concentration through its Norwegian production complex. CF Industries exemplifies ammonia feedstock integration at US Gulf Coast manufacturing hubs. Tessenderlo Group and Martin Midstream Partners sit within specialty chemical and midstream logistics niches respectively.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| Yara International ASA |
| CF Industries Holdings, Inc. |
| Tessenderlo Group |
| Martin Midstream Partners |
| Mears Fertilizer, Inc. |
| Plant Food Company, Inc. |
| The Mosaic Company |
| TerraLink Horticulture Inc. |
| Others |
Supply Flow & Price Mechanics
The US Gulf Coast ammonia hub concentration near Houston anchors thiosulfate manufacturing economics, where natural gas feedstock volatility directly transmits to downstream pricing power for liquid ammonium thiosulfate producers serving pivot irrigation markets.
Pricing Analysis
Certification level (REACH-registered versus standard-grade formulations) creates the primary spread between European potassium thiosulfate imports and domestic ammonium variants. Contract-based long-term offtake dominates premium operations, while spot procurement serves smaller cooperatives. Price differentiation rests on ammonia integration depth and sulfur sourcing reliability. Cost compression in standard-grade ammonium thiosulfate is intensifying because dry ammonium sulfate retains broadcast application cost advantage. Agricultural cooperatives in Iowa and Illinois exhibit highest price sensitivity; greenhouse horticulture clusters in Germany and the Netherlands show lowest.
Supply Chain Analysis
Export-control regimes on ammonia synthesis technology limit capacity expansion outside established production corridors. Geographic supply concentrates in the United States, Norway, and Brazil. Raw material dependencies include natural gas for ammonia feedstock, elemental sulfur from petroleum refining, and potassium chloride for cation complexation. Single-source vulnerability characterizes European potassium thiosulfate availability through Yara International's Norwegian complex. Distribution runs through direct-to-farm agronomy networks and agricultural cooperative aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where bundled fertigation program subscriptions expand faster than commodity thiosulfate volume, as precision application training and sensor calibration services capture recurring revenue.
For Market Incumbents: Insulate margin position by deepening captive ammonia supply at US Gulf Coast hubs and accelerating REACH-registered potassium thiosulfate capacity in alternative geographies. Dry ammonium sulfate cost competition threatens standard-grade positioning; certification investment for EU carbon border adjustment compliance represents the priority defensive lever.
For New Entrants and Emerging Players: Mid-scale horticulture operations in China's Shandong Province greenhouse clusters represent the most penetrable entry point, where chloride-sensitive crop demand for potassium thiosulfate outpaces established supply relationships. Brazil's Cerrado irrigation expansion offers secondary white-space for ammonium thiosulfate injection system partnerships. Go-to-market through precision agriculture platform integration bypasses cooperative procurement consolidation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors retail-integrated agronomy networks with direct farm gate relationships over pure manufacturing assets. Long-term viability hinges on carbon intensity differentiation for EU market access and digital agriculture service attach rates. The signal to monitor is carbon border adjustment mechanism implementation timing affecting import competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Production | Natural gas feedstock control at US Gulf Coast hubs compresses manufacturing cost variability for ammonium thiosulfate. |
| REACH Registration Expansion | Regulatory compliance investment unlocks potassium thiosulfate access to Dutch and German horticulture premium segments. |
| Direct-to-Farm Channel Development | Bundled fertigation programs bypass cooperative procurement consolidation in Iowa and Illinois corn operations. |
| Sensor-Enabled Variable-Rate Systems | Real-time soil feedback integration migrates thiosulfate application from prescription maps to automated dosing. |
| Carbon Intensity Certification | EU Green Deal alignment positions low-carbon sulfur fertilizer for preferential market access under border adjustments. |
Methodological Framework
A spread of perspectives from fertilizer plant managers, agricultural cooperative procurement leads, precision irrigation system engineers, and greenhouse operations directors converged on the working assumptions underlying demand projections. Primary field engagement combined with secondary validation from customs trade data, EPA nutrient management guideline documentation, SEC 10-K filings from integrated ammonia producers, and REACH registration databases. Bottom-up volume builds across crop-specific application rates triangulated against top-down ammonia feedstock consumption patterns.
Demand-supply balance modeling anchored the analytical framework across the projection horizon. Segmentation dimensions included formulation chemistry, application method, end-use intensity, and regional regulatory cluster. CAGRs derived from slope analysis of historical price-volume relationships and forward capacity expansion announcements. Industry-specific forecast inputs incorporated pivot irrigation infrastructure deployment rates and 4R nutrient stewardship program participation thresholds.
Practitioners should monitor natural gas price volatility, EPA runoff guideline enforcement intensity, and carbon border adjustment mechanism implementation for early signals requiring forecast revision. Material shifts in ammonia feedstock economics or REACH registration timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Automated Compound Storage and Retrieval (ACSR) Market
Specialty Compounds
Ready Mix Joint Compound Market
Specialty Compounds
Potassium Monopersulfate (KMPS) Market
Specialty Compounds
Galactoarabinan Market
Specialty Compounds
Dysprosium Acetate Market
Specialty Compounds
Hypalon Market
Specialty Compounds
Latin America Hydroxypropyl Methylcellulose Market
Specialty Compounds
Polypropylene Compounds Market
Specialty Compounds
China Collagen Market
Specialty Compounds
Global Antifreeze Proteins Market
Specialty Compounds
Chemical Synthesis Methyl Salicylate Market
Specialty Compounds
Alginates and Derivatives Market
Specialty Compounds
Asia-Pacific Collagen Market
Specialty Compounds
Special Effect Masterbatches Market
Specialty Compounds
Mexico Masterbatch Market
Specialty Compounds
Global Polymer Clay Market