
 USA Spinal Surgery Devices Market | 2026-2036
USA Spinal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
USA Spinal Surgery Devices Market Analytics
The Hospital Value-Based Purchasing Program is recalibrating procurement criteria toward patient-reported outcomes and readmission metrics. Medtronic Plc leverages its integrated spine and biologics portfolio to sustain comprehensive service contracts with major hospital systems. Stryker Corporation anchors its competitive stance through Mako robotic spine applications and specialized navigation hardware. Johnson & Johnson differentiates via DePuy Synthes and its concentrated R&D allocation toward expandable interbody technologies.
USA spinal surgery devices comprise implantable hardware systems, biologic graft materials, and instrument platforms designed to stabilize vertebral segments, restore disc height, or decompress neural elements through open, minimally invasive, or robot-assisted approaches; titanium alloy and polyetheretherketone construction dominate load-bearing applications while demineralized bone matrix and synthetic ceramics address osteoinductive requirements. Spinal fusion devices occupy the largest revenue pool given procedural volume and hardware intensity, though robotic surgery and navigation systems represent the fastest-expanding technology segment as hospitals amortize capital equipment across orthopedic service lines. Minimally invasive techniques command premium pricing relative to conventional open approaches but reduce length-of-stay sufficiently to justify acquisition costs under bundled payment models.
FDA premarket notification pathways and ISO 13485 quality system requirements govern device commercialization, while CMS national coverage determinations and local contractor policies directly shape reimbursement access and adoption velocity. OSHA bloodborne pathogen standards and state-level certificate-of-need regulations further constrain facility-based expansion and capital deployment. Stakeholders must monitor FDA guidance on artificial intelligence-enabled surgical planning tools and anticipate how CMS site-of-service differential adjustments will redistribute volumes between inpatient and ambulatory settings.
Market Dynamics
CMS site-of-service differential adjustments are redistributing spinal procedure volumes from inpatient hospitals toward ambulatory surgical centers, compressing capital equipment amortization timelines and forcing manufacturers to reconfigure service contract structures.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways for robotic navigation platforms compress technology transition cycles and reduce regulatory friction for novel spinal instrumentation.
- Sun Belt Demographic Migration:Retiree population concentration in Florida, Arizona, and Texas generates localized demand spikes that attract orthopedic specialty clusters and device distribution hubs.
- Demineralized Bone Matrix Advances:Synthetic ceramic and biologic graft material innovations expand fusion success rates in osteoporotic patient populations previously excluded from surgical candidacy.
Market Restraints
- Titanium Alloy Supply Concentration:Load-bearing implant fabrication depends on a narrow supplier base concentrated in aerospace-adjacent metallurgy channels, exposing manufacturers to input volatility.
- Certificate-of-Need Regulations:State-level CON restrictions in New York, California, and Illinois block ambulatory surgical center expansion and limit addressable procedure volume growth.
- Polyetheretherketone Substitution Limits:Radiolucent interbody cage materials face technical ceilings in multilevel constructs exceeding three vertebral segments, constraining application breadth.
Strategic Opportunities
- AI-Enabled Surgical Planning:FDA guidance development for machine learning-based preoperative templating creates first-mover advantage for platforms integrating imaging with predictive outcome modeling.
- Rural Hospital Outpatient Departments:Underpenetrated markets in Montana, Wyoming, and North Dakota present volume expansion potential as CMS reimbursement parity improves procedural economics.
- Navigation-Biologics Convergence:Real-time intraoperative imaging combined with patient-specific graft delivery systems opens premium positioning in complex deformity correction cases.
Industry Challenges
- Robotic Surgery Technician Scarcity:Capital platform deployment outpaces certified operator training programs, creating utilization bottlenecks and extended equipment commissioning timelines.
- ISO 13485 Recertification Burden:Quality system audits for expanded biologics manufacturing capabilities impose documentation overhead that delays product line extensions by 12-18 months.
- Legacy EMR Integration Friction:New navigation hardware requires costly middleware development to interface with entrenched hospital information systems, inflating total cost of ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Spinal Surgery Devices Market |
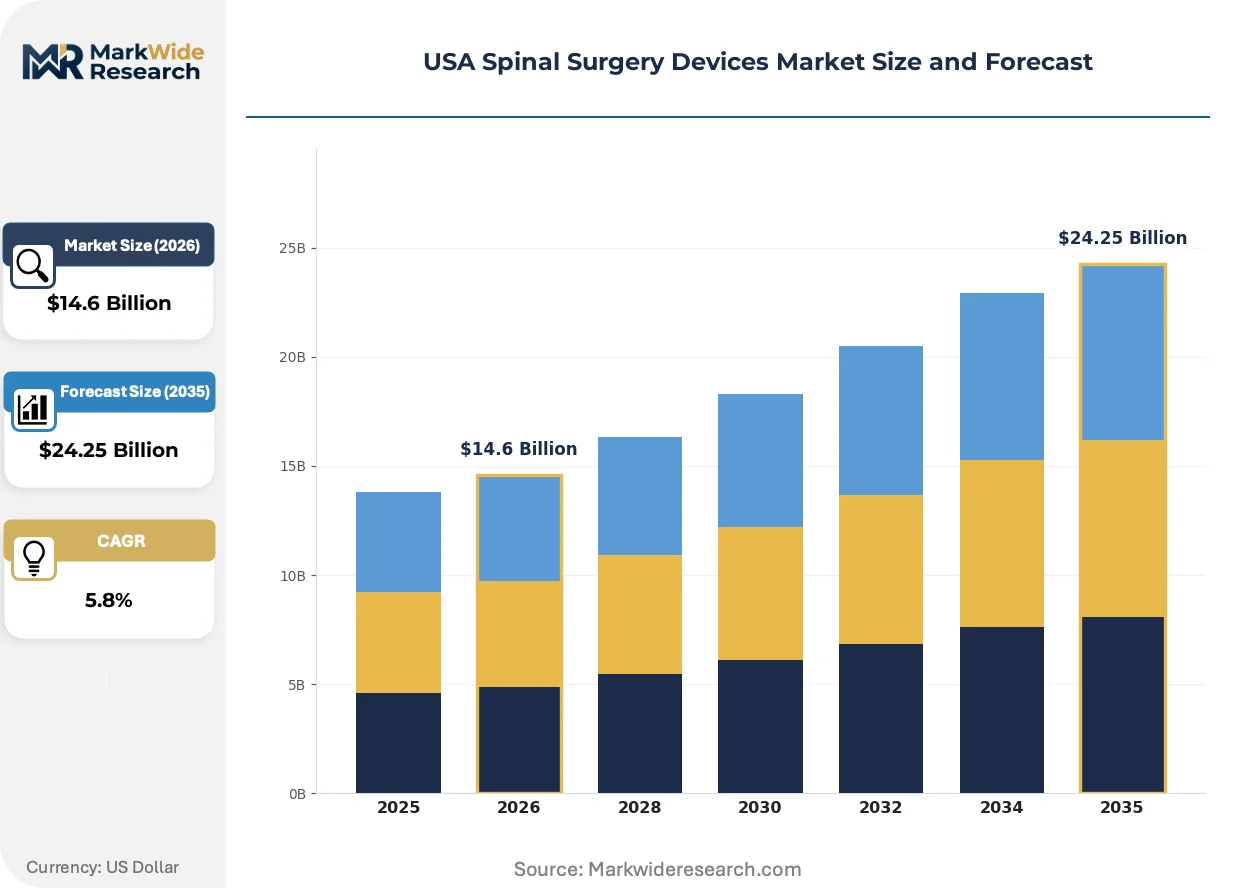
| Market Size in 2026 | $14.6 Billion |
| Market Size in 2035 | $24.25 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spinal Fusion Devices, Spinal Implants, Intervertebral Discs, Spinal Decompression Devices End User: Hospitals, Surgical Centers, Orthopedic Clinics, Rehabilitation Facilities Technology: Minimally Invasive Techniques, Robotic Surgery, Navigation Systems, Biologics Application: Degenerative Disc Disease, Spinal Stenosis, Scoliosis, Trauma |
| Companies Covered | Medtronic Plc, Stryker Corporation, Johnson & Johnson, Zimmer Biomet Holdings Inc., Globus Medical Inc., NuVasive Inc., Orthofix Medical Inc., B. Braun Melsungen AG, Alphatec Holdings Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Spinal Surgery Devices Market Evolving Landscape
Robotic-assisted platforms are compressing the technical gap between high-volume academic centers and community hospitals, while reimbursement policy and material science advances simultaneously reshape competitive positioning across the value chain.
Robot-assisted spinal navigation is decentralizing complex deformity correction capabilities from major metropolitan academic centers to regional hospital systems. Community hospitals in secondary markets are acquiring capital platforms at accelerated pace to retain locally insured patient populations. This geographic diffusion of surgical capability is compressing referral network dependencies and redistributing high-value procedure economics.
CMS national coverage determinations for outpatient lumbar fusion are eliminating prior authorization barriers that previously confined these procedures to inpatient settings. Ambulatory surgical centers in Texas and Florida are expanding operating room capacity specifically to capture this volume shift. Device manufacturers are restructuring pricing models to align with bundled payment timelines rather than fee-for-service reimbursement cycles.
Patient-reported outcome measurement has displaced length-of-stay as the primary procurement evaluation criterion under Hospital Value-Based Purchasing Program adjustments. Health system materials management departments are requiring longitudinal outcome data commitments from implant vendors before contract renewal. This behavioral shift is most visible in California and New York, where integrated delivery networks command sufficient volume to enforce data-sharing mandates.
USA Spinal Surgery Devices Market Segmentation
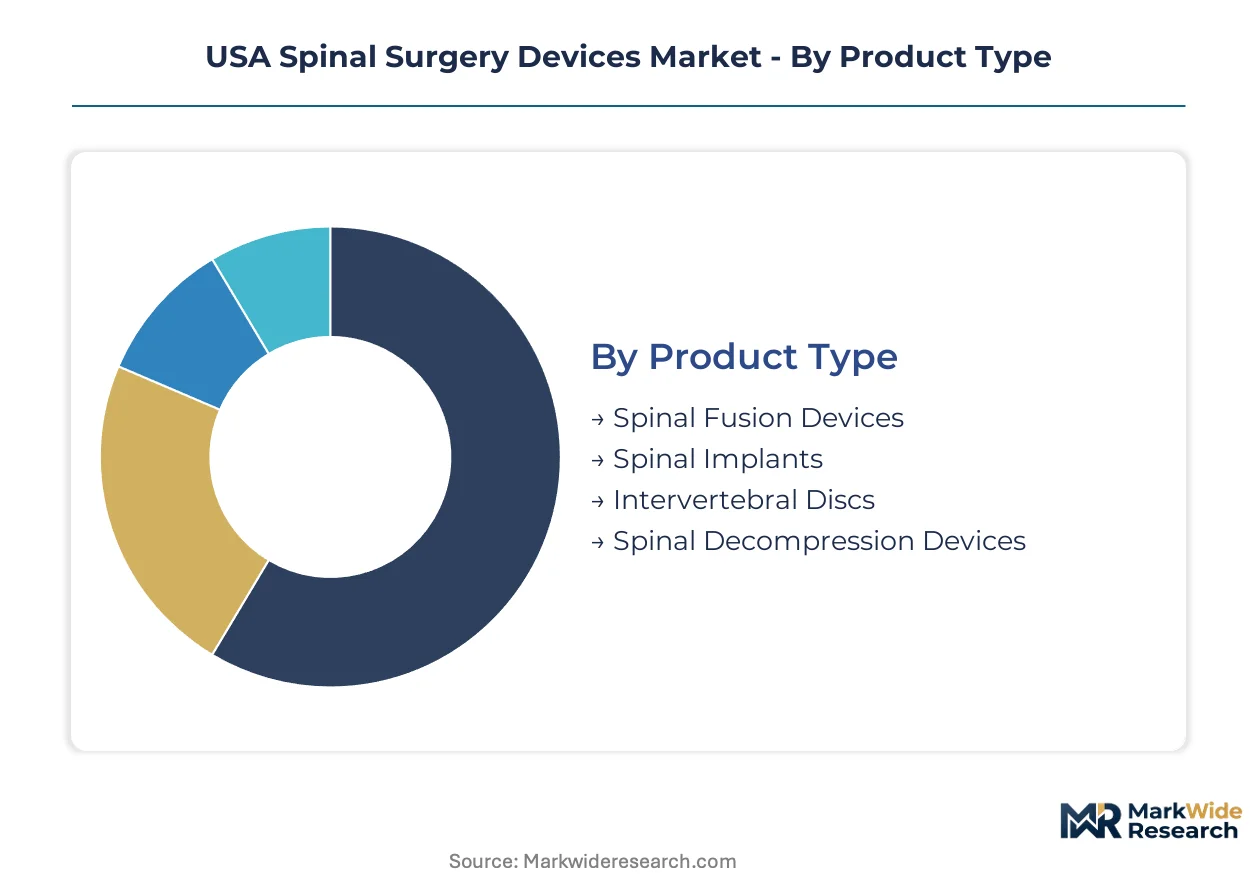
Segmentation in the USA spinal surgery devices market reveals how procurement priorities diverge across facility types and reimbursement structures. Manufacturers must configure product portfolios that balance capital intensity against procedural economics under shifting CMS payment models.
Product Type:
Standardization dominates high-volume fusion hardware while customization concentrates in patient-specific intervertebral solutions.
- Spinal Fusion Devices:Titanium alloy and polyetheretherketone constructs stabilize multilevel vertebral segments through pedicle screw-rod systems and interbody cages. Demand concentrates in Texas and Florida hospital systems where bundled payment contracts reward hardware-intensive procedures. The Hospital Value-Based Purchasing Program is pressuring vendors to demonstrate fusion success rates over 24-month follow-up periods.
- Spinal Implants:Load-bearing components including plates, hooks, and dynamic stabilization systems address motion-preservation requirements. Arizona orthopedic specialty clusters are driving adoption of expandable cage technologies that accommodate intraoperative adjustment. FDA 510(k) clearance timelines for novel implant geometries remain the primary constraint on product line refresh cycles.
- Intervertebral Discs:Artificial disc replacement systems preserve segmental motion in cervical and lumbar applications.
- Spinal Decompression Devices:Laminectomy instruments and interspinous process spacers relieve neural compression without fusion.
Most installed capacity flows through Spinal Fusion Devices. Expansion is steepest in Spinal Implants.
End User:
Capital deployment capacity separates high-volume inpatient anchors from ambulatory settings capturing CMS site-of-service differentials.
- Hospitals:Academic medical centers and community hospital systems maintain comprehensive spine service lines with dedicated operating suites and fellowship-trained surgeons. California and New York integrated delivery networks command sufficient volume to enforce outcome data-sharing mandates from implant vendors. Certificate-of-need regulations in these states constrain competitor entry and protect incumbent supplier relationships.
- Surgical Centers:Ambulatory facilities in Texas and Florida are expanding operating room capacity specifically to capture outpatient lumbar fusion volume liberated by CMS national coverage determinations. These centers prioritize disposable instrument sets and compressed sterilization cycles that align with same-day discharge protocols.
- Orthopedic Clinics:Physician-owned practices concentrate preoperative planning and postoperative monitoring functions.
- Rehabilitation Facilities:Post-acute settings manage conservative care pathways and surgical recovery protocols.
Revenue concentration remains heaviest in Hospitals. Volume is climbing fastest in Surgical Centers.
Technology:
Capital intensity stratifies this category from high-margin robotic platforms to commoditized biologic graft materials.
- Minimally Invasive Techniques:Tubular retractor systems and percutaneous screw placement reduce soft tissue disruption and accelerate recovery trajectories. Community hospitals in secondary markets are acquiring these capabilities to retain locally insured populations that previously required transfer to academic centers. Premium pricing over open approaches is justified through length-of-stay reductions under bundled payment models.
- Robotic Surgery:Navigation platforms with intraoperative imaging and predictive trajectory planning are compressing the technical gap between high-volume academic centers and regional hospital systems. FDA breakthrough device designations for these platforms are accelerating technology transition cycles and reducing regulatory friction for novel instrumentation deployment.
- Navigation Systems:Optical and electromagnetic tracking hardware enables real-time instrument localization.
- Biologics:Demineralized bone matrix and synthetic ceramic graft materials address osteoinductive requirements in osteoporotic patient populations.
Biologics command the broadest installed base. Robotic Surgery is gaining share fastest.
Application:
Procedure complexity and reimbursement adequacy determine addressable patient populations across indications.
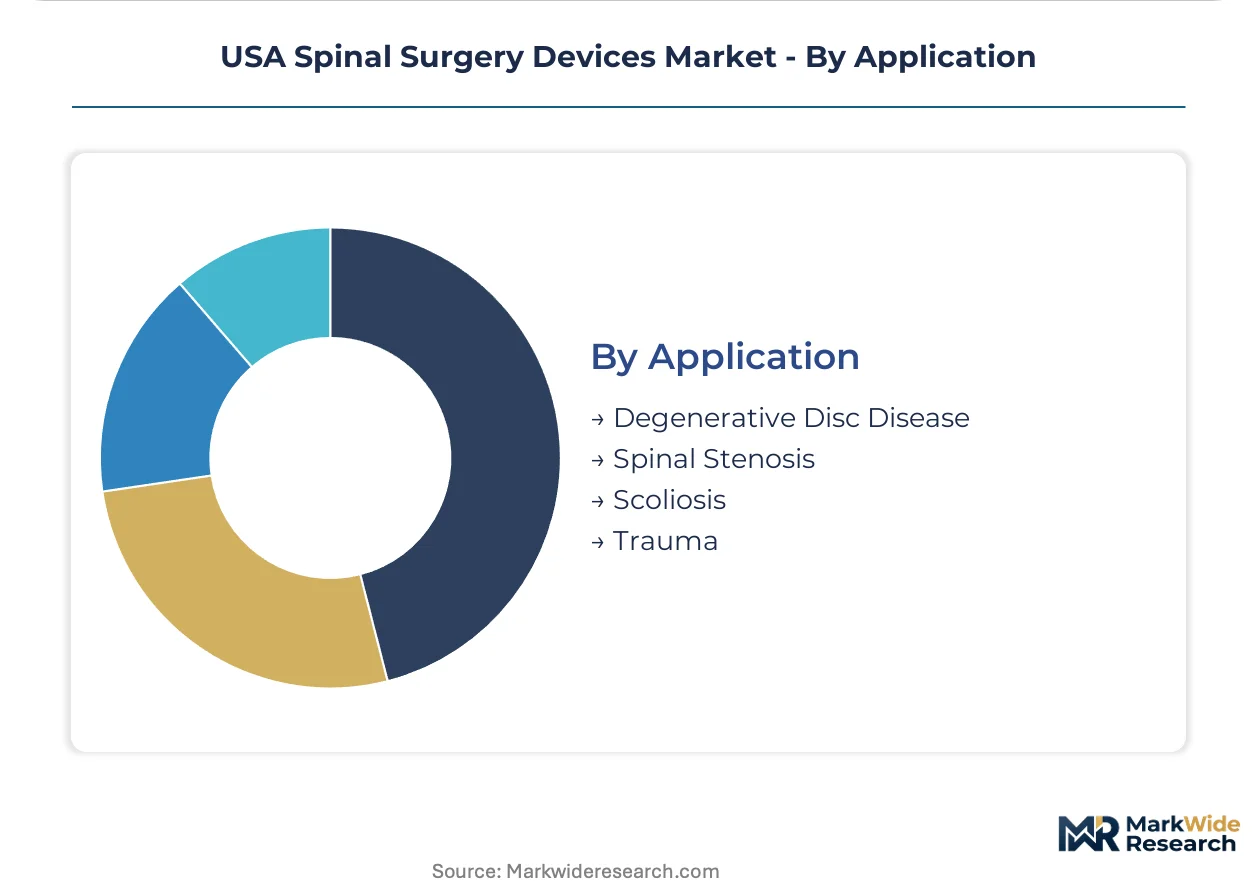
- Degenerative Disc Disease:Disc arthroplasty and fusion procedures address age-related disc collapse and mechanical back pain. The Sun Belt demographic migration is generating localized demand spikes in Florida, Arizona, and Texas where retiree concentration intersects with orthopedic specialty cluster development. CMS reimbursement parity between cervical and lumbar disc replacement remains uneven.
- Spinal Stenosis:Decompression procedures relieve neural element compression from ligamentum flavum hypertrophy and facet arthropathy. Rural hospital outpatient departments in Montana and Wyoming present volume expansion potential as procedural economics improve. Patient-reported outcome measurement has displaced length-of-stay as the primary procurement evaluation criterion for these procedures.
- Scoliosis:Deformity correction requires complex multilevel constructs and specialized instrumentation.
- Trauma:Acute fracture stabilization demands rapid implant availability and surgeon accessibility.
Procedure volume concentrates in Degenerative Disc Disease. Expansion is steepest in Spinal Stenosis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The USA spinal surgery devices industry traces its commercial scale to the 1990s titanium pedicle screw innovations pioneered in Memphis and Warsaw, Indiana, establishing the Midwest as the original manufacturing corridor before coastal technology clusters absorbed navigation and robotics development.
Texas
Retiree migration into Dallas-Fort Worth and Houston generates concentrated demand for degenerative disc procedures, with orthopedic specialty clusters expanding across the Texas Medical Center. CMS site-of-service differentials for outpatient lumbar fusion have triggered ambulatory surgical center construction in Austin and San Antonio. Device distributors are relocating inventory hubs to Dallas to serve same-day delivery requirements for ASCs.
Florida
Aging demographic concentration in Tampa, Orlando, and South Florida drives cervical and lumbar fusion volumes exceeding national per-capita averages. State certificate-of-need regulations remain less restrictive than Northeast counterparts, permitting rapid ASC capacity expansion in Jacksonville and Fort Lauderdale. Miami orthopedic groups are consolidating purchasing power to negotiate outcome-data contracts with implant vendors.
California
Integrated delivery networks in Los Angeles and the Bay Area enforce patient-reported outcome mandates that reshape procurement evaluation criteria. FDA breakthrough device designations for Silicon Valley-developed surgical planning software accelerate technology transitions. Certificate-of-need restrictions in San Diego and Sacramento protect incumbent hospital supplier relationships against ambulatory competitors.
Arizona
Phoenix and Tucson retirement communities generate localized demand spikes for motion-preservation implants and expandable cage technologies. Lower facility construction costs attract orthopedic specialty clusters migrating from higher-regulation states. Scottsdale surgical centers are piloting bundled payment models that compress device pricing negotiations into multi-year contracts.
New York
Academic medical centers in Manhattan and Long Island maintain complex deformity correction capabilities that anchor referral networks across the Northeast. State certificate-of-need regulations block ASC expansion in New York City, protecting inpatient volume for hospital systems. Buffalo and Rochester hospitals are consolidating spine service lines to retain commercially insured patients against Pennsylvania competitors.
USA Spinal Surgery Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the USA spinal surgery devices landscape, with integrated manufacturers maintaining captive forging and coating capabilities while specialized developers outsource titanium fabrication to aerospace-adjacent suppliers. The market structure concentrates around three strategic archetypes: diversified conglomerates with orthopedic divisions, pure-play spine specialists, and navigation-robotics platform developers. Consolidation through acquisition of patient-specific implant technologies and strategic partnerships for biologics distribution dominate competitive maneuvering.
Among diversified conglomerates, Medtronic Plc and Stryker Corporation exemplify integrated service contract strategies with major hospital systems. Johnson & Johnson occupies a position representing concentrated R&D allocation toward expandable interbody technologies. These three entities anchor the premium-tier competitive vector through comprehensive spine and biologics portfolios.
| Leading Market Players |
|---|
| Medtronic Plc |
| Stryker Corporation |
| Johnson & Johnson |
| Zimmer Biomet Holdings Inc. |
| Globus Medical Inc. |
| NuVasive Inc. |
| Orthofix Medical Inc. |
| B. Braun Melsungen AG |
| Alphatec Holdings Inc. |
| Others |
Value Network & Pricing Analysis
CMS site-of-service differential adjustments for outpatient lumbar fusion are compressing reimbursement timelines and forcing manufacturers to restructure service contracts toward bundled payment cycles, which in turn pressures titanium alloy sourcing economics and redistributes margin capture toward ambulatory-focused distributors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates robotic navigation platforms from conventional instrumentation and commoditized biologic graft materials. Price differentiation hinges on FDA breakthrough device designation status and hospital system contract scale, with academic medical centers commanding steepest discounts through longitudinal outcome data commitments. Cost compression in standard-tier fusion hardware is intensifying because ambulatory surgical centers prioritize disposable instrument sets with compressed sterilization cycles. Rural hospital outpatient departments exhibit highest price sensitivity; integrated delivery networks in California and New York demonstrate lowest.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume academic center demand while specialized distributors serve ambulatory surgical centers requiring same-day delivery capabilities. Titanium alloy forging capacity concentrates in USA aerospace-adjacent metallurgy corridors, with polyetheretherketone resin sourcing anchored in European chemical manufacturing hubs. Raw material dependencies span titanium sponge, medical-grade PEEK resin, and demineralized bone matrix preparations. Single-source vulnerability in titanium alloy supply exposes manufacturers to aerospace sector demand fluctuations. Distribution runs through manufacturer-direct contracts for major hospital systems and regional distributors for ambulatory facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Texas and Florida offer geographic-arbitrage advantages through lower certificate-of-need restrictions and faster ambulatory surgical center permitting timelines relative to New York and California, compressing capital deployment cycles and accelerating volume capture.
For Market Incumbents: Deploy outcome data-sharing mandates as contract renewal leverage against emerging navigation-robotics platform developers. Backward integration into captive titanium forging capabilities defends margin position against aerospace sector demand surges. Consolidate purchasing power through orthopedic specialty cluster partnerships in Sun Belt markets to neutralize price erosion from commoditized interbody cage competitors. For New Entrants and Emerging Players: Rural hospital outpatient departments in Montana, Wyoming, and North Dakota present the most penetrable volume expansion opportunity given reimbursement parity improvements and limited incumbent service coverage. AI-enabled surgical planning software offers white-space positioning ahead of FDA guidance finalization. Lead with disposable instrument set economics tailored to same-day discharge protocols rather than capital platform sales. For Investors and Strategic Acquirers: Asymmetric upside sits with patient-specific implant technology developers holding expandable cage patents and biologics distribution agreements. The five-to-ten year viability window favors platforms integrating real-time navigation with osteoinductive graft delivery. Target acquisition archetypes include mid-cap spine specialists with ISO 13485 biologics manufacturing capabilities and established surgeon training programs. Watch FDA artificial intelligence guidance development as signal for platform valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated review compresses technology transition cycles for robotic navigation platforms. |
| Hospital System Partnership | Comprehensive service contracts with Texas and Florida IDNs lock in bundled payment volume. |
| Reimbursement Strategy | CMS site-of-service differential alignment captures outpatient lumbar fusion volume shift. |
| Software Companion Development | AI-enabled surgical planning integration creates premium positioning in deformity correction. |
| CE Marking Pathway | European regulatory expansion diversifies revenue beyond USA certificate-of-need constraints. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with orthopedic surgeons, hospital purchasing committee chairs, GPO contracts managers, and ambulatory surgical center administrators with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and ISO 13485 quality system audit disclosures. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored segment-level estimates.
Segment-weighting across product type, end user, technology, and application dimensions shaped the analytical framework over the projection horizon. CAGRs derived from procedure volume trajectories, capital equipment replacement cycles, and reimbursement policy phase-in schedules. Modeling incorporated titanium alloy price indices, Sun Belt demographic migration patterns, and FDA breakthrough device designation timelines as industry-specific forecast inputs.
Underlying measurement precision varies by segment; spinal fusion devices and robotic surgery platforms carry tighter precision than biologics and navigation systems given more transparent procurement reporting. Forecasts reflect assumptions around CMS site-of-service policy stability, titanium supply continuity, and surgeon training program expansion rates. Periodic stress-testing of base assumptions is recommended against regulatory reimbursement shifts, raw material supply disruptions, and robotic technician scarcity bottlenecks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Medical Crutches Market
Orthopedic Devices
Humeral Implant Market
Orthopedic Devices
Global Total Ankle Replacement Market
Orthopedic Devices
Kyphoscoliosis Treatment Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
UAE Spinal Surgery Devices Market
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
Global Shoulder Replacement Market
Orthopedic Devices
Hip Resurfacing Implants Market
Orthopedic Devices
Personalized Orthopaedic Implant Market
Orthopedic Devices
Global Orthopedic Navigation Systems Market
Orthopedic Devices
3D Medical Implant Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Hip Reconstruction Devices Market
Orthopedic Devices
Orthopedic Braces Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market