
 Global Animal Feed Protein Ingredients Market | 2026-2036
Global Animal Feed Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Animal Feed Protein Ingredients Market Analysis
Multi-source procurement for oilseed meals is decoupling from decades of soy-dominant contracting. Cargill Inc. leverages its crushing footprint across North and South American port networks to secure origin flexibility. Evonik Industries AG differentiates through precision fermentation of amino acids that reduce crude protein requirements in compound feeds. Bunge Limited anchors its position through backward integration into Brazilian soybean origination and river logistics.
Animal feed protein ingredients comprise concentrated nitrogenous compounds derived from oilseeds, animal byproducts, marine biomass, and leguminous crops, typically specified at minimum crude protein thresholds between 40% and 85% on a dry-matter basis, formulated to balance indispensable amino acid profiles in livestock diets. Soy protein dominates volume throughput due to established crushing infrastructure and consistent lysine content, while pea protein is gaining formulation share in European compound feeds as processors seek non-genetically modified alternatives with favorable carbon labeling. Fish meal occupies premium aquaculture applications where species-specific digestibility and omega-3 retention justify elevated input costs against plant-based substitutes.
The EU Green Deal and REACH frameworks constrain marine ingredient sourcing and residual contaminant thresholds, while the FDA and USDA jointly oversee feed safety under the Food Safety Modernization Act and BSE feed ban regulations in the United States. China's SAMR enforces GB standard compliance for imported protein meals, creating divergent certification burdens for exporters serving multiple jurisdictions. Stakeholders must monitor regulatory asymmetry between jurisdictions as a primary determinant of formulation flexibility and market access cost.
Market Dynamics
Multi-origin sourcing strategies are fragmenting the soy-dominant procurement architecture that has governed compound feed formulation for three decades. Crushing capacity dispersion across Brazilian interior states, US Gulf terminals, and Black Sea export corridors is forcing feed manufacturers to rebalance origin exposure against amino acid consistency requirements.
Growth Catalysts
- EU Green Deal feed sustainability benchmarks:Mandates for deforestation-free supply chains are accelerating certification adoption among European compound feed manufacturers, creating premium market tiers for traceable oilseed meals.
- Aquaculture species diversification:Vietnam's expansion into high-value marine finfish species is intensifying demand for specialty protein meals with targeted amino acid profiles and digestibility coefficients.
- Precision fermentation platforms:Industrial biotechnology advances are enabling microbial protein production with customized nitrogen content, reducing dependence on agricultural commodity cycles.
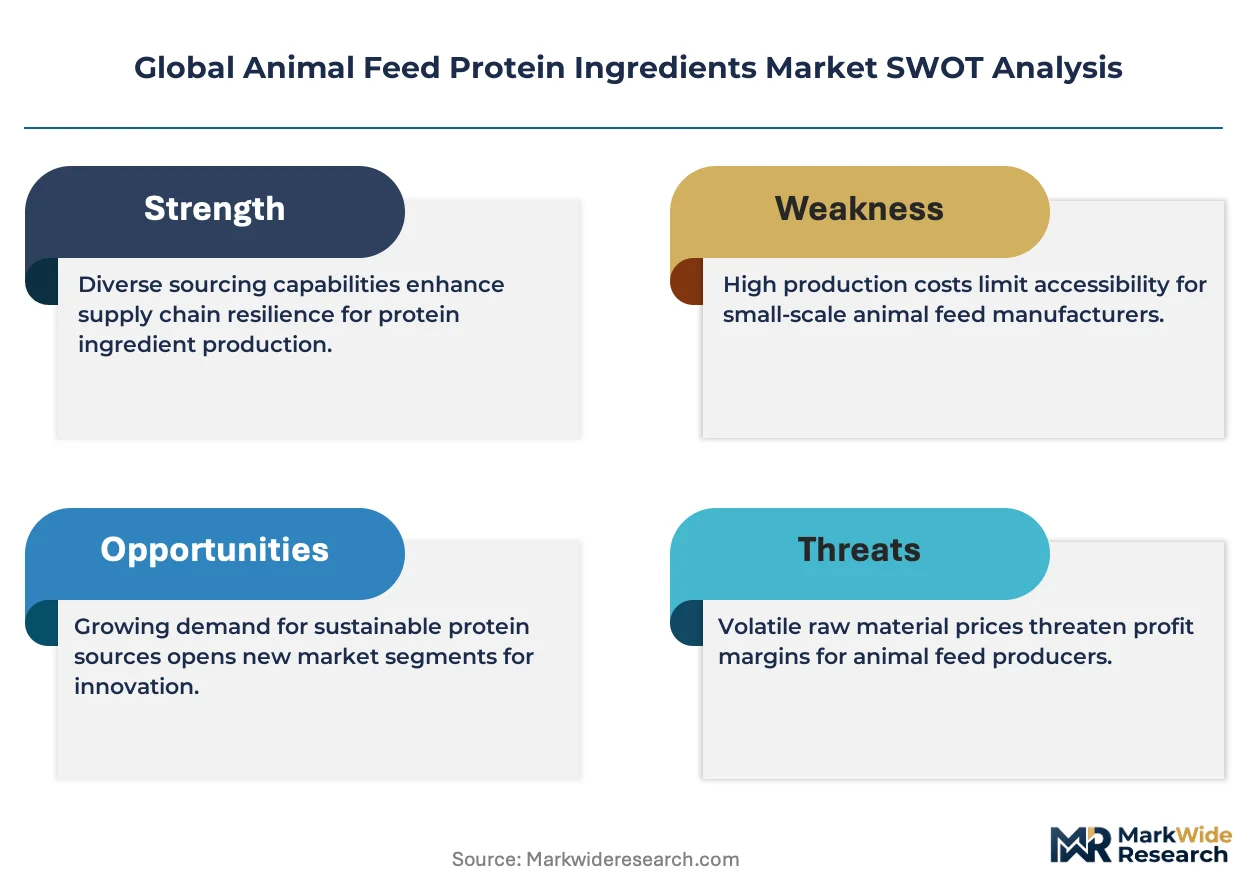
Market Restraints
- Input cost volatility in marine biomass:Peruvian anchovy catch variability and El Niño disruptions create price spikes that destabilize aquaculture feed budgeting cycles.
- Supply concentration in Brazilian soybean origination:Three states control over sixty percent of exportable surplus, exposing international buyers to localized weather and logistics disruptions.
- Regulatory friction from REACH contaminant thresholds:European residual substance limits for heavy metals and dioxins in fish meal are tightening faster than testing infrastructure can validate compliance.
Strategic Opportunities
- Underpenetrated insect protein processing:Netherlands and Belgium are emerging as regulatory sandboxes for black soldier fly larvae meal approval in poultry and aquaculture diets.
- Regulatory tailwind from China's dual carbon goals:National policy incentives for low-carbon feed ingredients are creating preferential market access for processors with verified carbon footprints.
- Technology convergence of near-infrared spectroscopy and blockchain:Real-time protein quality verification combined with immutable chain-of-custody records is enabling origin-premium capture.
Industry Challenges
- Specialized formulation talent scarcity:Shortage of nutritionists capable of balancing amino acid profiles across multi-origin meal blends is constraining product development timelines.
- Capex intensity of cold-chain marine ingredient infrastructure:Temperature-controlled storage and rapid processing requirements for fish meal demand substantial facility investment with extended payback periods.
- Certification timeline compression:Accelerating audit cycles for deforestation-free and carbon-labeled supply chains are straining third-party verification capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Animal Feed Protein Ingredients Market |
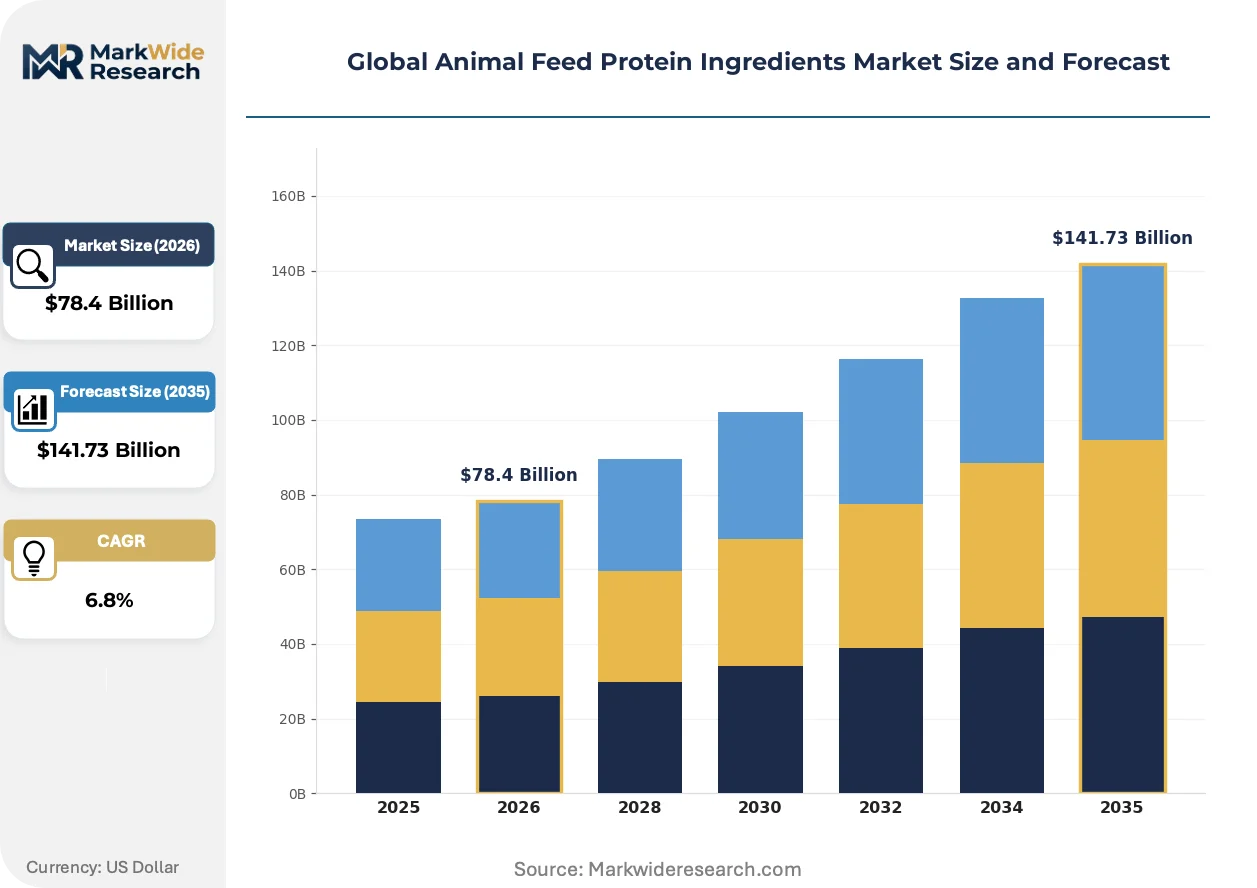
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Protein, Meat Meal, Fish Meal, Pea Protein End User: Poultry, Ruminants, Swine, Aquaculture Form: Pellets, Powder, Liquid, Granules Distribution Channel: Online, Offline, Wholesalers, Retailers |
| Companies Covered | Wilmar International Limited, Evonik Industries AG, Cargill Inc., Nutreco N.V., DSM-Firmenich, Archer Daniels Midland Company (ADM), Charoen Pokphand Foods PCL, De Heus Animal Nutrition, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Animal Feed Protein Ingredients Market Emerging Trajectories
Biotechnology-enabled protein production and digital traceability systems are converging to restructure how nitrogenous feed inputs are sourced, validated, and priced. These developments are compressing traditional commodity trading margins while opening specialized value capture opportunities.
Single-cell protein derived from methanotrophic bacteria is decentralizing the geographic distribution of high-quality feed nitrogen production. Aquafeed manufacturers in Norway and Chile are integrating these fermentation-derived ingredients at ten to fifteen percent inclusion rates. The technology is decentralizing supply risk away from agricultural harvest cycles and marine catch fluctuations toward industrial bioreactor uptime metrics.
REACH framework amendments on persistent organic pollutant thresholds in marine-derived ingredients are forcing reformulation of salmonid diets across European aquaculture operations. Maximum residue limits for polychlorinated biphenyls have tightened by fifty percent, disqualifying traditional North Atlantic fish meal sources. Norwegian feed producers are responding by accelerating algae oil and microbial protein substitution in grower diets.
Integrated poultry operations in Brazil's southern states are consolidating meal procurement through captive crushing partnerships rather than spot market purchases. Large-scale integrators are negotiating multi-year supply agreements directly with processor cooperatives, bypassing traditional trading houses. This concentration is most visible in Santa Catarina's vertically coordinated broiler complexes, where origin-locked contracts now cover eighty percent of soybean meal requirements.
Global Animal Feed Protein Ingredients Market Segmentation
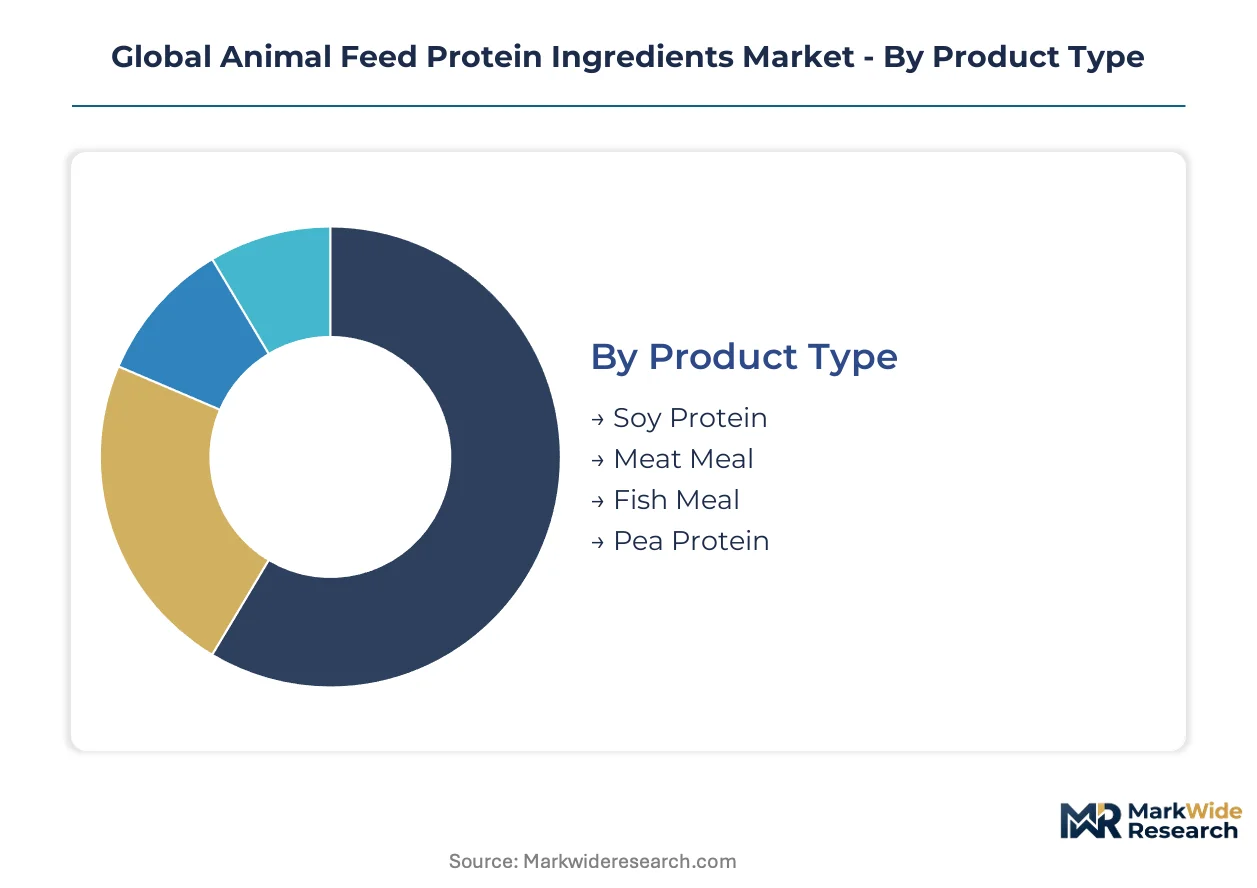
Protein ingredient procurement patterns diverge sharply across livestock species and feed processing formats. Compound feed manufacturers configure sourcing strategies around amino acid digestibility coefficients, handling characteristics, and regulatory compliance burdens specific to each segment combination.
Product Type:
Ingredient selection tracks integration depth into compound feed formulations, with some proteins serving as standalone nutritional anchors while others function as embedded specialty additives.
- Soy Protein:Derived from solvent-extracted soybean meal with standardized 44% or 48% crude protein specifications and consistent lysine-to-methionine ratios. Demand concentrates in Brazil's integrated poultry belt where crushing partnerships lock in origin-traceable supply chains under EU Green Deal deforestation-free mandates.
- Fish Meal:Marine biomass meal processed from whole fish or trimmings, retaining 60-72% crude protein with species-specific amino acid profiles and omega-3 fatty acid content. Norwegian and Chilean aquafeed manufacturers are accelerating substitution with algae oil and single-cell proteins as REACH PCB thresholds tighten residue limits.
- Meat Meal:Rendered byproduct meal from slaughterhouse residuals, typically specified at 50-55% crude protein with variable bone content affecting calcium-phosphorus balance. US rendering facilities operate under FDA BSE feed ban protocols restricting ruminant protein recycling.
- Pea Protein:Air-classified or wet-fractionated protein concentrate from yellow field peas, offering non-genetically modified positioning with favorable carbon labeling for European compound feeds. Netherlands processors are expanding extraction capacity to serve premium poultry and aquaculture formulations.
Volume placements concentrate in soy protein; the faster expansion belongs to pea protein.
End User:
Species-specific digestive physiology and production economics determine protein inclusion rates, with cost-per-unit-gain calculations varying dramatically across livestock categories.
- Poultry:Broiler and layer operations require balanced amino acid profiles with emphasis on digestible lysine and sulfur-containing amino acids for rapid muscle deposition and egg production. Santa Catarina's vertically coordinated complexes in Brazil now cover eighty percent of soybean meal requirements through captive crushing partnerships.
- Aquaculture:Marine and freshwater finfish species demand protein meals with high biological value, precise digestibility coefficients, and minimal anti-nutritional factors. Vietnam's expansion into high-value marine finfish is intensifying procurement of specialty meals with targeted amino acid formulations.
- Swine:Growing-finishing diets utilize soybean meal as the primary protein source, with phase-feeding protocols adjusting lysine levels across weight brackets. Chinese integrators are testing reduced-crude-protein formulations supplemented with precision-fermented amino acids to align with dual carbon policy incentives.
- Ruminants:Cattle and sheep operations historically relied on oilseed meals, though regulatory constraints on animal protein recycling limit formulation flexibility. EU dairy operations are evaluating insect protein meal approvals as novel feed ingredients under EFSA safety assessments.
Feed conversion efficiency drives premium pricing in aquaculture; regulatory compliance costs weigh most heavily on ruminant formulations.
Form:
Physical processing state determines handling infrastructure requirements, storage stability, and inclusion precision in automated feed manufacturing systems.
- Pellets:Extruded cylindrical forms with standardized dimensions for mechanical handling and controlled dissolution rates in aquatic environments. Norwegian salmon feed producers favor pelleted marine protein meals for sea-cage distribution systems.
- Powder:Fine-milled protein meals enabling homogeneous blending in mash feeds and precision inclusion in micro-premixes. Powdered soy protein isolates serve starter diets for young animals with immature digestive systems.
- Liquid:Hydrolyzed protein solutions and concentrated amino acid suspensions for high-moisture feed applications and automated liquid addition systems. Liquid lysine from Evonik's fermentation platforms reduces overall crude protein requirements in compound feeds.
- Granules:Intermediate particle size offering flowability advantages over powders with faster hydration than dense pellets. Granulated fish meal supports pelleting operations where thermal processing must preserve heat-sensitive nutrients.
Processing throughput favors pellet and powder formats; liquid systems claim the steepest expansion trajectory in precision nutrition applications.
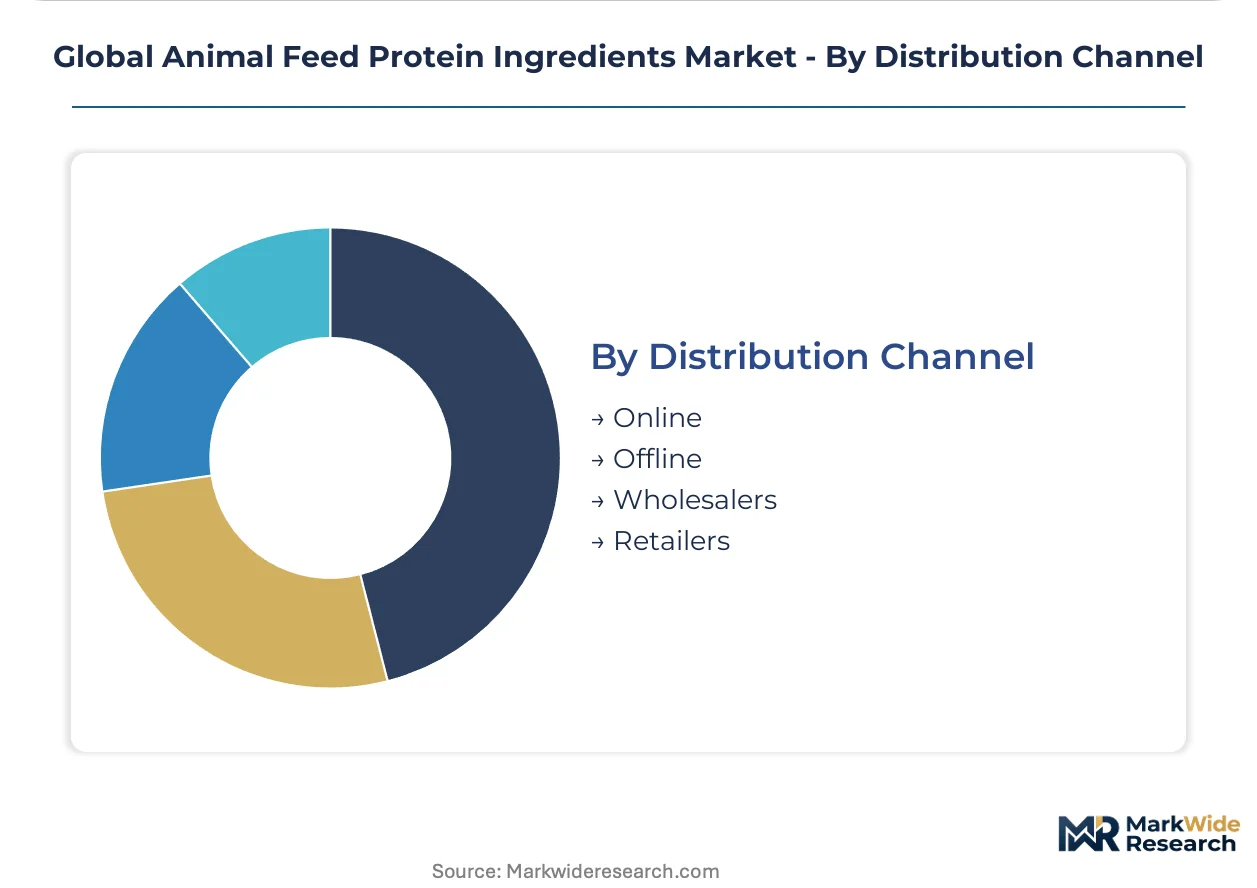
Distribution Channel:
Channel structure reflects transaction scale, technical service intensity, and traceability documentation requirements across buyer segments.
- Wholesalers:Volume aggregators managing bulk commodity flows from crushing facilities to regional feed mills, with inventory positioning at major port terminals. Cargill leverages North and South American port networks to secure origin flexibility for international wholesale customers.
- Offline:Direct procurement relationships between feed manufacturers and protein processors, often involving multi-year supply agreements with quality specifications and volume commitments. Bunge anchors its position through backward integration into Brazilian soybean origination and river logistics.
- Retailers:Packaged protein supplements and specialty ingredients for small-scale livestock operations and hobby farmers, with labeling compliance for consumer-facing channels. European farm supply cooperatives are expanding certified deforestation-free product lines under EU Green Deal procurement guidelines.
- Online:Digital platforms for spot purchases, price discovery, and specialty ingredient sourcing with blockchain-verified chain-of-custody documentation. Near-infrared spectroscopy data feeds enable real-time protein quality verification for remote buyers.
Contractual volume locks through offline channels dominate procurement value; online platforms are gaining share fastest in specialty ingredient segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's soybean origination belt anchors the global protein meal trade, with crushing capacity concentrated across interior states that supply integrated poultry operations and export corridors. Vietnam's aquaculture expansion and Norway's salmon feed innovation are reshaping marine and alternative protein sourcing patterns.
Brazil
Santa Catarina's vertically coordinated broiler complexes drive captive crushing partnerships covering eighty percent of soybean meal requirements. ANVISA enforces feed safety protocols aligned with EU deforestation-free import standards. Paraná and Mato Grosso crushing facilities channel exportable surplus through Santos port terminals.
Vietnam
Expansion into high-value marine finfish species intensifies procurement of specialty protein meals with targeted amino acid formulations. The Ministry of Agriculture and Rural Development implements aquafeed quality standards under national food safety frameworks. Mekong Delta processing clusters scale alternative protein meal purchases for shrimp and pangasius operations.
Norway
Salmon feed producers accelerate algae oil and single-cell protein substitution as REACH polychlorinated biphenyl thresholds tighten. EFSA safety assessments govern novel feed ingredient approvals including insect protein meals. Bergen and Trondheim biotech clusters commercialize methanotrophic bacterial protein for ten to fifteen percent diet inclusion rates.
United States
Integrated pork and poultry operations test reduced-crude-protein formulations supplemented with precision-fermented amino acids. FDA and USDA jointly oversee feed safety under the Food Safety Modernization Act and BSE feed ban regulations. Iowa and Illinois crushing facilities leverage Gulf Coast export terminals for origin-flexible supply chains.
China
National dual carbon policy incentives create preferential market access for processors with verified low-carbon feed ingredient footprints. SAMR enforces GB standard compliance for imported protein meals, creating divergent certification burdens. Shandong and Guangdong compound feed manufacturers integrate fermented amino acids to reduce nitrogen emissions.
Global Animal Feed Protein Ingredients Market Vendor Landscape
Backward integration into origination and crushing assets dominates the current landscape as processors seek supply security amid commodity volatility. The vendor base structures across three tiers: multinational traders with hemisphere-spanning logistics networks, regional nutrition specialists with formulation expertise, and biotechnology platforms producing fermentation-derived inputs. Strategic archetypes include origin-locked processors securing Brazilian soybean flows, precision nutrition providers reducing crude protein requirements, and alternative protein developers commercializing insect and microbial meals. M&A activity and captive crushing partnerships represent the dominant competitive moves, with integrators bypassing traditional trading houses through multi-year supply agreements.
Among agribusiness trading houses, Cargill Inc. and Bunge Limited exemplify the origin-flexible archetype through crushing footprint dispersion across North and South American port networks. Evonik Industries AG occupies a distinct position within the precision fermentation tier, representing biotechnology-enabled reduction of agricultural commodity dependence. Wilmar International Limited anchors the Asia-Pacific origination-processing nexus, while DSM-Firmenich and Nutreco N.V. exemplify nutrition-specialist positioning in species-specific formulation markets.
| Leading Market Players |
|---|
| Wilmar International Limited |
| Evonik Industries AG |
| Cargill Inc. |
| Nutreco N.V. |
| DSM-Firmenich |
| Archer Daniels Midland Company (ADM) |
| Charoen Pokphand Foods PCL |
| De Heus Animal Nutrition |
| Bunge Limited |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed Brazilian processor cooperatives and family-owned crushing facilities anchor origin-locked contracting, tightening pricing discipline as captive supply agreements displace spot market liquidity. This ownership concentration feeds directly into premium capture for deforestation-certified meals and compresses margins on generic commodity grades.
Pricing Analysis
Quality certification and carbon footprint verification are bundled into long-term offtake contracts, while unbundled spot transactions trade at discounts without traceability documentation. Three-tier pricing structure across premium, standard, and economy levels separates EU Green Deal-compliant meals from conventional grades and residual feed fractions. Cost compression in standard-tier soy protein is intensifying because Brazilian integrators are internalizing crushing capacity. Small-scale aquafeed manufacturers in Vietnam exhibit the highest price sensitivity, while Norwegian salmon feed producers accept premiums for REACH-compliant marine ingredients.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian interior states for soybean origination, where Paraná, Mato Grosso, and Rio Grande do Sul control exportable surplus flows. The supply chain draws from Peruvian anchovy fisheries for fish meal, Black Sea sunflower corridors for oilseed alternatives, and Dutch insect protein pilot facilities. Tariff exposure on deforestation-free certification compliance creates structural risk for European compound feed manufacturers. Distribution runs through Santos port terminals for Atlantic-bound shipments and Mekong Delta processing clusters for Asian aquaculture feed milling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a biotechnology-transition phase, with precision fermentation platforms displacing agricultural commodity cycles as the primary nitrogen source for high-value aquaculture formulations.
For Market Incumbents: Hedge against amino acid price volatility by securing captive crushing partnerships in Brazil's southern states and investing in precision-fermented lysine capacity. Defend formulation share against microbial protein substitutes by embedding blockchain-verified traceability into premium product tiers. For New Entrants and Emerging Players: Begin with regulatory sandbox positioning in Netherlands and Belgium for black soldier fly larvae meal approvals, targeting poultry and aquaculture diet applications. Capture white-space demand from Vietnam's marine finfish expansion by offering species-specific amino acid formulations with digestibility guarantees. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale rendering facilities with FDA BSE compliance infrastructure in the US Midwest. Long-term viability hinges on biotechnology platform acquisitions rather than commodity trading assets. Watch EFSA novel feed ingredient approval timelines as the inflection signal for insect protein commercialization scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origination | Cargill and Bunge secure Brazilian soybean flows through river logistics control and interior crushing assets. |
| Precision Fermentation Scale-Up | Evonik's microbial amino acid platforms reduce compound feed crude protein requirements and agricultural commodity exposure. |
| Regulatory Sandbox Positioning | Netherlands and Belgium pilot facilities accelerate black soldier fly larvae approval for poultry and aquaculture diets. |
| Blockchain Traceability Deployment | Near-infrared spectroscopy data feeds enable real-time protein quality verification and origin-premium capture. |
| Captive Crushing Partnerships | Santa Catarina integrators lock in eighty percent of soybean meal requirements through multi-year processor agreements. |
Methodological Framework
Document review covered trade flow databases, regulatory filings with EFSA and FDA, and customs records, complemented by interviews with compound feed formulation directors, crushing facility operations managers, aquafeed procurement leads, and biotechnology platform R&D heads. Secondary validation drew from EU Green Deal implementation reports, ANVISA feed safety protocols, and SAMR GB standard documentation. Bottom-up volume modeling and top-down value reconciliation ensured cross-method consistency.
Historical volume trajectories were cross-referenced against expert panel inputs to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include protein source type, livestock species category, physical processing form, and distribution channel structure. CAGRs were derived from iterative convergence between demand-side consumption forecasts and supply-side capacity expansion pipelines, incorporating El Niño cycle impacts on marine biomass availability and EU deforestation-free certification adoption curves.
Underlying measurement precision varies by segment; soy protein and fish meal carry tighter precision than emerging insect protein categories due to established trade reporting infrastructure. Forecasts reflect assumptions about regulatory timeline execution, biotechnology scale-up rates, and climate variability in South American origination belts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Roasted Wheat Market
Others
Diamond Mining Market
Others
Italy 3D Printing Construction Market
Others
Brazil Passenger Vehicles Lubricants Market
Others
Security Bottles Market
Others
Digital Signage Media Player Market
Others
Profilometer Market
Others
Smart Home and Office Market
Others
5G Tester Market
Others
Lightweight Compact Wheel Loader Market
Others
Electric Pallet Jack Truck Market
Others
Quadrant Scale Market
Others
North America Printed Signage Market
Others
North America Astrology Market
Others
Calendered Polyvinyl Chloride Flexible Films Market
Others
Coloring Apps Market