
 Feed Ingredients Market | 2026-2036
Feed Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Ingredients Market Analysis
Buyer concentration among livestock integrators is shifting as Brazilian and Thai poultry conglomerates internalize feed formulation, reducing spot-market dependence on independent suppliers. Cargill, Incorporated anchors North American grain origination and oilseed processing through its vertically aligned elevator network. Evonik Industries AG specializes in precision amino acids, leveraging microbial fermentation to displace commodity protein sources in least-cost ration formulations. Charoen Pokphand Foods PCL dominates Southeast Asian aquafeed through captive shrimp and fish operations integrated with its ingredient procurement.
Feed ingredients comprise the functional additives, base nutrients, and processing co-products blended into compounded diets for food-producing animals, with amino acid profiles, mineral bioavailability, and pellet durability serving as critical quality parameters governing feed conversion ratios. The ruminant segment sustains demand for bypass proteins and rumen-protected fats as dairy herd sizes expand in temperate grazing regions. Aquaculture applications lead growth in functional additives, with probiotic inclusion rates rising fastest in shrimp and salmon diets where disease pressure intensifies. Powder and liquid vitamin premixes occupy mature margin pools, while pellet form gains share in automated delivery systems for large-scale broiler and swine operations.
The EU Green Deal and REACH frameworks restrict antibiotic growth promoters and mandate feed additive safety dossiers through EFSA, reshaping product registration costs and reformulation timelines for exporters. China's MEE enforces stricter effluent standards on feed mills, accelerating enzyme adoption to improve phosphorus digestibility and reduce manure nutrient loads. India's FSSAI and BIS certification requirements for imported feed ingredients tighten traceability protocols. Stakeholders must monitor regulatory divergence between jurisdictions to avoid formulation lock-ins that foreclose market access.
Market Dynamics
Livestock integrators in Brazil and Thailand are internalizing feed formulation, reducing spot-market dependence and compressing margins for independent ingredient suppliers while reshaping procurement hierarchies.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Antibiotic restrictions accelerate functional additive adoption as producers reformulate rations to maintain performance without growth promoters.
- Intensive aquaculture expansion:Southeast Asian shrimp and salmon operations drive formulated feed demand as traditional extensive farming gives way to high-density systems requiring precise nutrition.
- Enzyme technology maturation:Phytase and carbohydrase adoption improves phosphorus digestibility and reduces manure nutrient loads, aligning with China's MEE effluent standards.
Market Restraints
- Soybean meal price volatility:Weather-driven supply swings in Argentina and Brazil compress formulation margins and destabilize least-cost ration optimization.
- REACH registration costs:EFSA safety dossier requirements for novel feed additives extend reformulation timelines and raise capital barriers for exporters targeting European markets.
- Plant protein amino acid gaps:Lysine and methionine deficiencies in pea and canola meals limit complete soybean displacement without synthetic amino acid supplementation.
Strategic Opportunities
- India's FSSAI traceability mandates:Certification requirements for imported ingredients create first-mover advantage for suppliers building integrated sourcing documentation systems.
- Single-cell protein fermentation:Microbial biomass from methanotrophs and algae converges with precision fermentation to unlock bypass protein categories beyond conventional oilseed meals.
- Vietnamese pangasius sector:Underpenetrated feed-to-farm integration offers white space for ingredient premix specialists establishing direct mill relationships.
Industry Challenges
- Formulation talent scarcity:Shortage of nutritionists capable of least-cost optimization under multi-constraint regulatory environments slows product development cycles.
- Legacy mill retrofit costs:Automated liquid additive systems require capital-intensive upgrades incompatible with aging pelleting infrastructure in independent mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Ingredients Market |
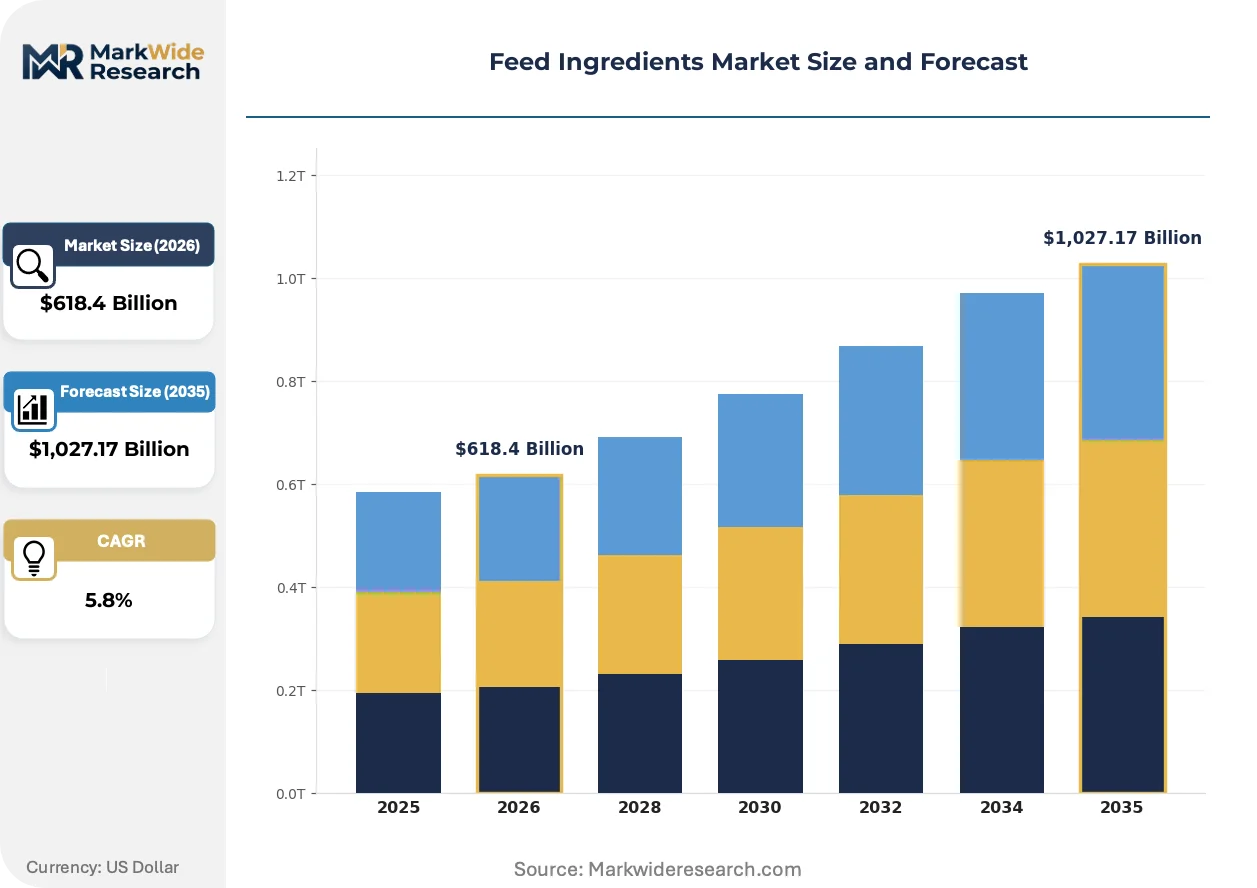
| Market Size in 2026 | $618.4 Billion |
| Market Size in 2035 | $1,027.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Amino Acids, Probiotics Application: Poultry, Ruminants, Aquaculture, Swine Form: Powder, Granules, Liquid, Pellets End User: Farmers, Feed Manufacturers, Livestock Producers, Pet Owners |
| Companies Covered | New Hope Group, Evonik Industries AG, Cargill, Incorporated, De Heus Animal Nutrition, BRF S.A., Archer Daniels Midland Company, BASF SE, Tyson Foods, Inc., Charoen Pokphand Foods PCL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Ingredients Market Emerging Trajectories
Precision nutrition platforms and alternative protein streams are compressing traditional commodity ingredient hierarchies while regulatory frameworks fragment across jurisdictions.
Single-cell protein from methanotrophic bacteria is expanding into salmon and shrimp diets as a bypass protein source with favorable amino acid profiles. Norwegian and Chilean aquafeed producers are scaling inclusion rates beyond trial volumes. This technology is expanding into premium marine feed categories previously dominated by fishmeal.
REACH and the EU Green Deal are tightening antibiotic growth promoter restrictions and mandating additive safety dossiers through EFSA. Exporters face extended registration timelines and reformulation costs. European compounders are accelerating enzyme and probiotic substitution to maintain performance metrics.
Buyer concentration among Brazilian and Thai poultry integrators is compressing spot-market volumes as captive milling capacity expands. Independent suppliers are pivoting toward specialty additive premixes and technical service contracts. This pattern is most visible in São Paulo state and Thailand's eastern seaboard feed clusters.
Feed Ingredients Market Segmentation
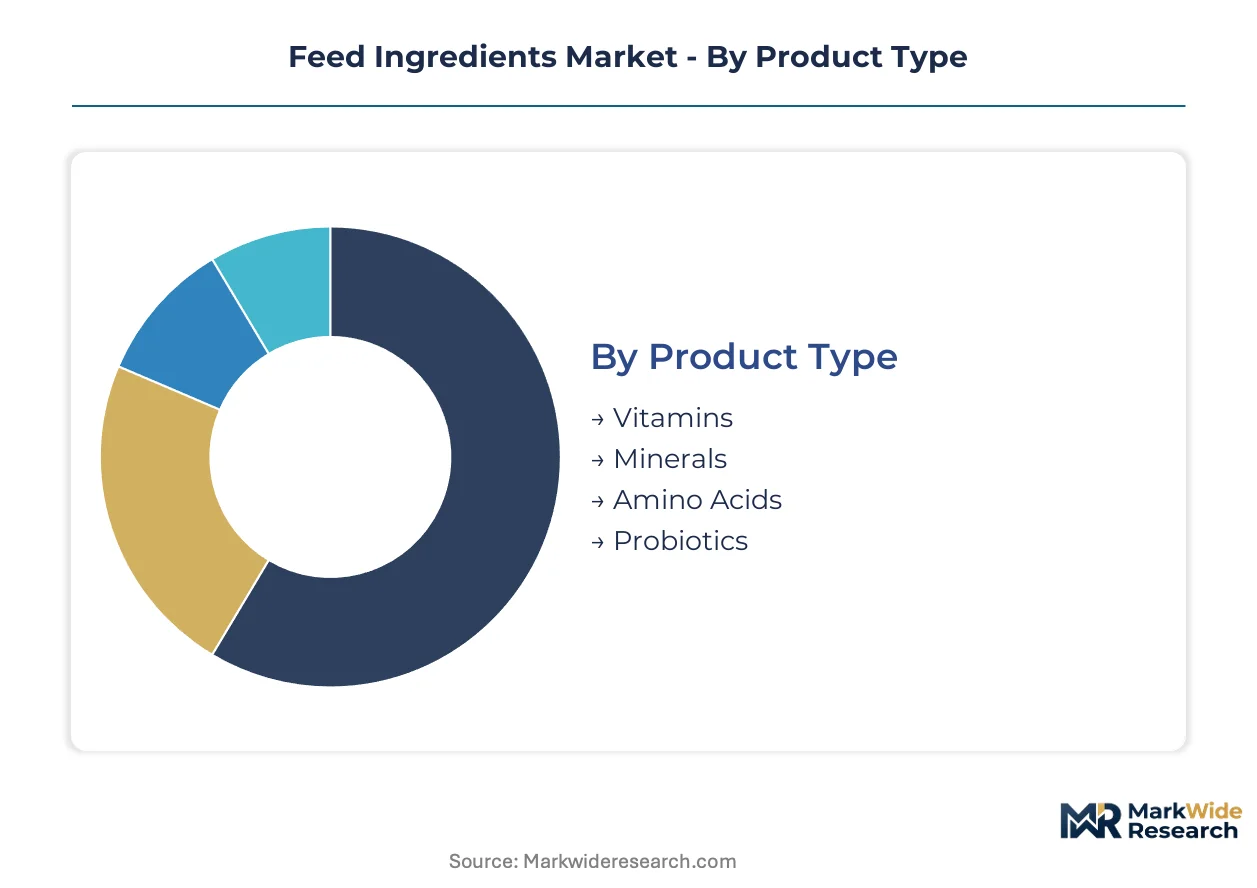
Feed ingredient suppliers configure product portfolios around species-specific digestive physiology and mill processing capabilities. Segmentation choices determine margin capture, with functional additives commanding premiums over commodity base nutrients.
Product Type:
Standalone micronutrient categories operate independently in premix operations, while embedded amino acid systems integrate directly into least-cost formulation software.
- Amino Acids:Synthetic lysine, methionine, threonine, and tryptophan produced via microbial fermentation enable precise protein optimization. Brazilian and Thai poultry integrates now specify crystalline amino acid inclusion rates directly in procurement contracts, displacing commodity soybean meal volumes.
- Probiotics:Live microbial cultures including Bacillus subtilis and Lactobacillus strains colonize gut epithelium to exclude pathogens. EU Green Deal antibiotic restrictions are accelerating substitution in German and Dutch swine operations where EFSA registration timelines favor established strain dossiers.
- Vitamins:Fat-soluble A, D, E, K and water-soluble B-complex compounds stabilize metabolic function.
- Minerals:Macro minerals calcium and phosphorus plus trace elements zinc, copper, and selenium support enzymatic cascades.
Amino acids lead volumes today; probiotics are gaining share fastest.
Application:
Species segments diverge sharply in nutrient density requirements and regulatory exposure, with aquaculture facing the steepest formulation complexity.
- Aquaculture:Shrimp and salmon diets demand precision amino acid balancing alongside probiotic pathogen suppression. Norwegian and Chilean producers are scaling single-cell protein inclusion as fishmeal displacement accelerates under marine ingredient sustainability pressures.
- Poultry:Broiler and layer operations prioritize feed conversion ratio optimization through phytase enzyme adoption. Brazilian integrators in São Paulo state are consolidating captive milling capacity, compressing spot-market volumes for independent suppliers.
- Swine:Grower-finisher phases require lysine-dense formulations to maximize lean tissue deposition.
- Ruminants:Dairy herds in temperate grazing regions utilize bypass proteins and rumen-protected fats to sustain milk yield.
Poultry dominates absolute consumption; aquaculture exhibits the steepest expansion trajectory.
Form:
Physical presentation governs handling economics, with automated delivery systems favoring flowable formats over dusty powders.
- Pellets:Compressed cylindrical forms withstand transport abrasion and enable precise metering in automated broiler and swine feeding systems. Large-scale operations in Brazil's Mato Grosso feed clusters specify pellet durability indices above 95 percent to minimize fines generation.
- Liquid:Pumpable suspensions of enzymes, acids, and oils integrate post-pelleting to preserve heat-labile activity. Thailand's eastern seaboard aquafeed mills are retrofitting liquid additive systems to accommodate probiotic and organic acid inclusion.
- Powder:Fine particulate premixes require manual handling or specialized dosing equipment.
- Granules:Intermediate particle size bridges flowability and surface area for coating applications.
Pellets anchor volume leadership; liquid form is climbing the fastest as mill automation spreads.
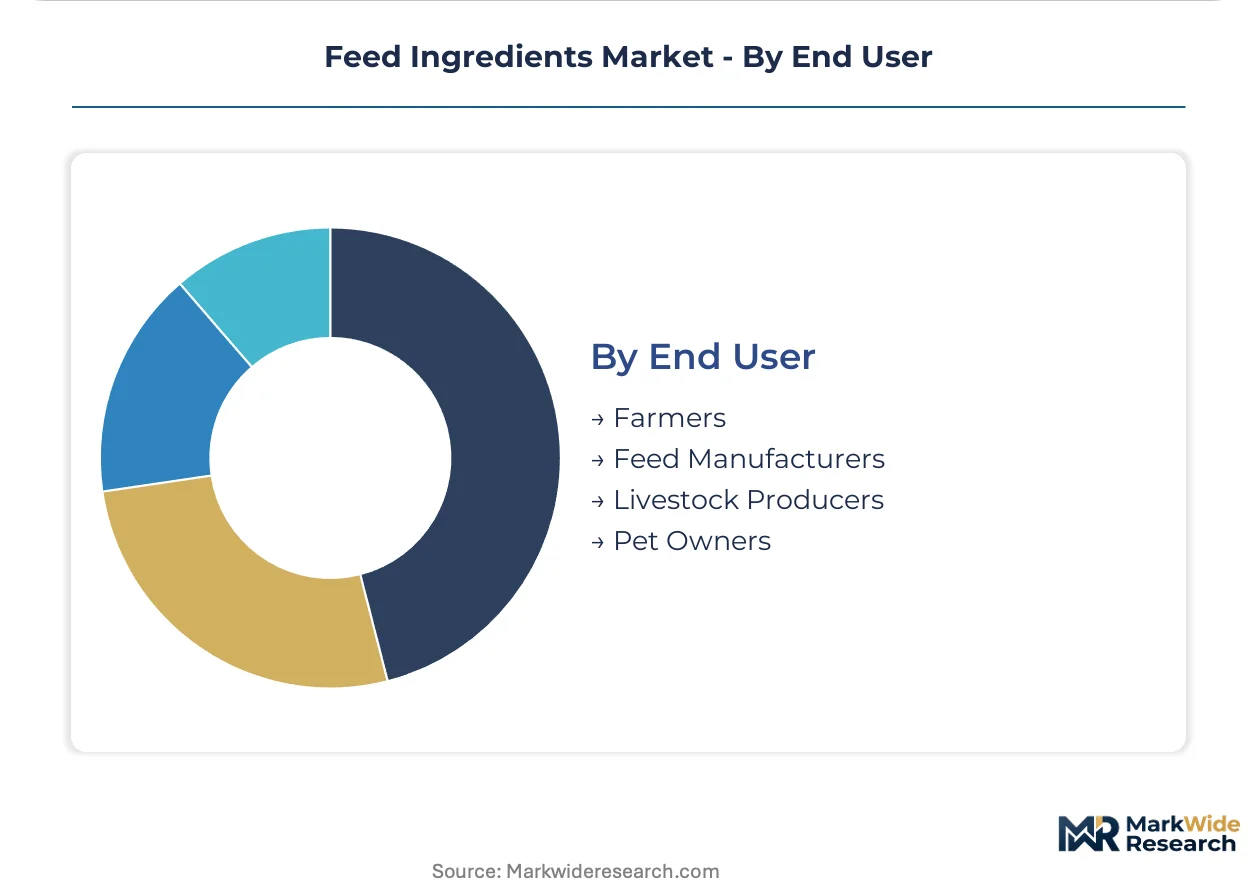
End User:
Customer type determines technical service intensity, with integrated livestock operators internalizing formulation expertise previously outsourced.
- Feed Manufacturers:Independent compounders purchase base nutrients and functional additives for custom ration blending. Vietnamese pangasius feed mills represent underpenetrated territory for premix specialists establishing direct technical relationships.
- Livestock Producers:Integrated poultry and pork processors operate captive milling facilities. Charoen Pokphand Foods PCL and Brazilian conglomerates now control ingredient specification directly, reducing supplier negotiation leverage.
- Farmers:Small-scale operators rely on branded complete feeds with embedded additives.
- Pet Owners:Companion animal nutrition represents a niche premium channel.
Feed manufacturers retain volume leadership; livestock producers are capturing share fastest through backward integration into milling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil and Thailand diverge in feed ingredient sourcing strategies, with Brazilian integrators consolidating captive milling while Thai aquafeed producers expand formulated diet imports. China and the EU impose divergent regulatory pressures on additive safety and environmental compliance. Vietnam and India represent contrasting frontier markets for premix penetration.
Brazil
Poultry and pork integrators in São Paulo and Mato Grosso are absorbing independent feed mills into captive operations, reducing spot-market volumes for amino acid suppliers. ANVISA enforces stricter residue monitoring for imported additives, extending customs clearance timelines. The southern feed clusters around Chapecó and Cascavel concentrate soybean processing and oilseed crushing capacity.
China
MEE effluent standards are accelerating enzyme adoption across Yangtze River Delta feed mills to reduce phosphorus discharge loads. The dual carbon goals framework imposes energy intensity caps on fermentation-based amino acid production. Shandong Peninsula and Guangdong Province house the densest concentrations of phytase manufacturing and microbial fermentation facilities.
Germany
EFSA registration timelines for novel probiotics are compressing reformulation windows for exporters targeting Dutch and Danish swine compounders. REACH dossier requirements for feed additive safety data raise capital barriers for non-EU suppliers. The Lower Saxony feed corridor between Hanover and Osnabrück anchors ruminant bypass protein formulation expertise.
Thailand
Shrimp and salmon aquaculture expansion along the eastern seaboard is driving formulated feed demand as extensive pond systems convert to intensive recirculation. Charoen Pokphand Foods PCL controls captive ingredient procurement across its integrated operations. Rayong and Chonburi provinces concentrate aquafeed mill capacity and probiotic inclusion system retrofits.
Vietnam
Pangasius producers in the Mekong Delta remain underpenetrated by premix specialists, creating white space for direct mill relationships and technical service contracts. The Ministry of Agriculture and Rural Development tightens antibiotic residue surveillance in export-oriented aquaculture. Can Tho and An Giang provinces host the largest concentrations of independent feed compounders serving catfish operations.
Feed Ingredients Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across amino acid fermentation and aquafeed formulation segments. The vendor base stratifies into three tiers: integrated agribusinesses with captive oilseed processing, precision additive manufacturers with microbial fermentation platforms, and regional feed compounders with localized premix operations. Dominant competitive moves include backward integration into oilseed crushing and strategic partnerships for single-cell protein scale-up.
Within the diversified agribusiness tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify North American grain origination and oilseed processing archetypes. Evonik Industries AG occupies a position among precision fermentation specialists focused on crystalline amino acids for least-cost ration optimization. Charoen Pokphand Foods PCL represents the Southeast Asian integrated model combining captive aquaculture operations with controlled ingredient procurement.
| Leading Market Players |
|---|
| New Hope Group |
| Evonik Industries AG |
| Cargill, Incorporated |
| De Heus Animal Nutrition |
| BRF S.A. |
| Archer Daniels Midland Company |
| BASF SE |
| Tyson Foods, Inc. |
| Charoen Pokphand Foods PCL |
| Others |
Supply Flow & Price Mechanics
Captive milling integration among Brazilian and Thai poultry conglomerates anchors both supply security and pricing leverage, compressing spot-market volumes while elevating contract negotiation power for crystalline amino acids and functional additives. This backward integration into in-house feed production reshapes procurement hierarchies and compresses margins for independent ingredient suppliers serving the remaining open-market compounders.
Pricing Analysis
Capacity additions in China's Shandong Peninsula are reshaping price floors for microbial fermentation-derived amino acids. Contract-based long-term offtake dominates between integrated livestock operators and precision additive manufacturers, with price differentiation hinging on EFSA registration status and volume scale commitments. Cost compression in standard-grade lysine is intensifying because Brazilian integrators now specify inclusion rates directly in procurement contracts. Spot-market buyers among Vietnamese pangasius compounders exhibit highest price sensitivity; least-sensitive buyers are Norwegian salmon producers securing marine-certified single-cell protein.
Supply Chain Analysis
EFSA safety dossier and REACH registration requirements gate European market access, extending qualification timelines for novel probiotic strains and enzyme formulations. Manufacturing concentration centers on China, Germany, and Brazil, with raw material flows drawing from Argentine soybean crushing, Southeast Asian fishmeal reduction, and North American corn wet milling. Supply chain risk rests on single-source vulnerability for methionine fermentation capacity concentrated in Tianjin and Ludwigshafen. Distribution runs through regional premix blending facilities co-located with major feed mill clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Feed Ingredients Market functions as a stable compounder anchored by irreversible dietary upgrading in intensive aquaculture and antibiotic-restricted livestock systems. Protein optimization mandates and functional additive substitution create durable demand visibility across economic cycles.
For Market Incumbents: Anchor formulation partnerships with Vietnamese pangasius mills before captive integration spreads, and secure EFSA dossier positions for probiotic strains ahead of EU Green Deal enforcement tightening. Synthetic amino acid producers face displacement pressure from single-cell protein fermentation scale-up; defensive investment in microbial biomass R&D preserves bypass protein relevance. Capacity additions in Rayong and Chonburi aquafeed clusters offer channel control leverage.
For New Entrants and Emerging Players: Regional premix blenders in Can Tho and An Giang provinces represent the most penetrable entry channel, given underdeveloped technical service relationships between existing suppliers and independent Mekong Delta compounders. Direct mill relationships with pangasius feed manufacturers bypass established distribution hierarchies. A certification-first go-to-market angle exploiting India's FSSAI traceability mandates creates first-mover documentation advantage.
For Investors and Strategic Acquirers: Consolidation pressure builds where formulation talent scarcity intersects with legacy mill retrofit requirements, favoring acquisition of precision fermentation specialists with integrated technical service capabilities. Five-to-ten-year viability favors microbial biomass platforms over commodity amino acid fermentation. Watch single-cell protein inclusion rate announcements from Norwegian and Chilean salmon producers as inflection indicators for fishmeal displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Brazilian integrators secure soybean meal supply certainty while compressing independent supplier margins. |
| EFSA Probiotic Strain Registration | EU Green Deal antibiotic restrictions elevate registered live culture premiums in Dutch swine operations. |
| Liquid Additive System Retrofit | Thailand's eastern seaboard mills automate probiotic delivery to intensive shrimp recirculation systems. |
| Single-Cell Protein Scale-Up Partnership | Methanotrophic fermentation unlocks bypass protein categories beyond conventional oilseed meals. |
| FSSAI Traceability Documentation Build | Indian certification requirements favor suppliers with integrated sourcing systems for imported ingredients. |
Methodological Framework
Bottom-up livestock integrator modeling reconciled against top-down amino acid fermentation capacity tracking forms the analytical core. Primary interviews with feed mill procurement directors, livestock nutritionists, regulatory affairs specialists at additive manufacturers, and aquafeed compounder technical managers combined with secondary validation from ANVISA import clearance records, EFSA additive safety dossier filings, Chinese MEE effluent compliance disclosures, and Brazilian agricultural census data. Triangulation across these sources calibrated volume estimates for captive versus open-market procurement splits.
Input-output matrices mapped lysine, methionine, threonine, and tryptophan inclusion rates by species segment across the projection horizon, with phytase and probiotic adoption curves modeled separately for poultry, swine, ruminant, and aquaculture applications. Segmentation dimensions spanned product type, species application, physical form, and end-user integration level. CAGRs derived from least-cost formulation software penetration rates and regulatory substitution mandates, with China's dual carbon goals framework and EU Farm to Fork antibiotic restrictions as primary forecast drivers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to single-cell protein scale-up economics and marine ingredient sustainability certification fragmentation. Model outputs reflect assumptions regarding enzyme adoption curves and integrator backward integration velocity. A model refresh is warranted upon material change in EFSA registration timelines or Brazilian captive milling consolidation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Glucosylglycerol Market
Ingredients
Coconut Oil Market
Ingredients
Native Starch Market
Ingredients
Multi-Grain Premixes Market
Ingredients
Cocoa Processing Market
Ingredients
France Soy Protein Market
Ingredients
Bertholletia Excelsa Seed Oil Market
Ingredients
Omega 9 Market
Ingredients
Europe Agar Market
Ingredients
Soy Lecithin Market
Ingredients
Global Distillers Corn Oil Market
Ingredients
Egg Yolk Lecithin Market
Ingredients
Cocoa Powder Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Modified Soya Flour Market
Ingredients
Global Vitamin Ingredients Market