
 North America Printed Signage Market | 2026-2036
North America Printed Signage Market Size, Share, and Industry Trends Forecast 2026-2036
North America Printed Signage Market Foresight
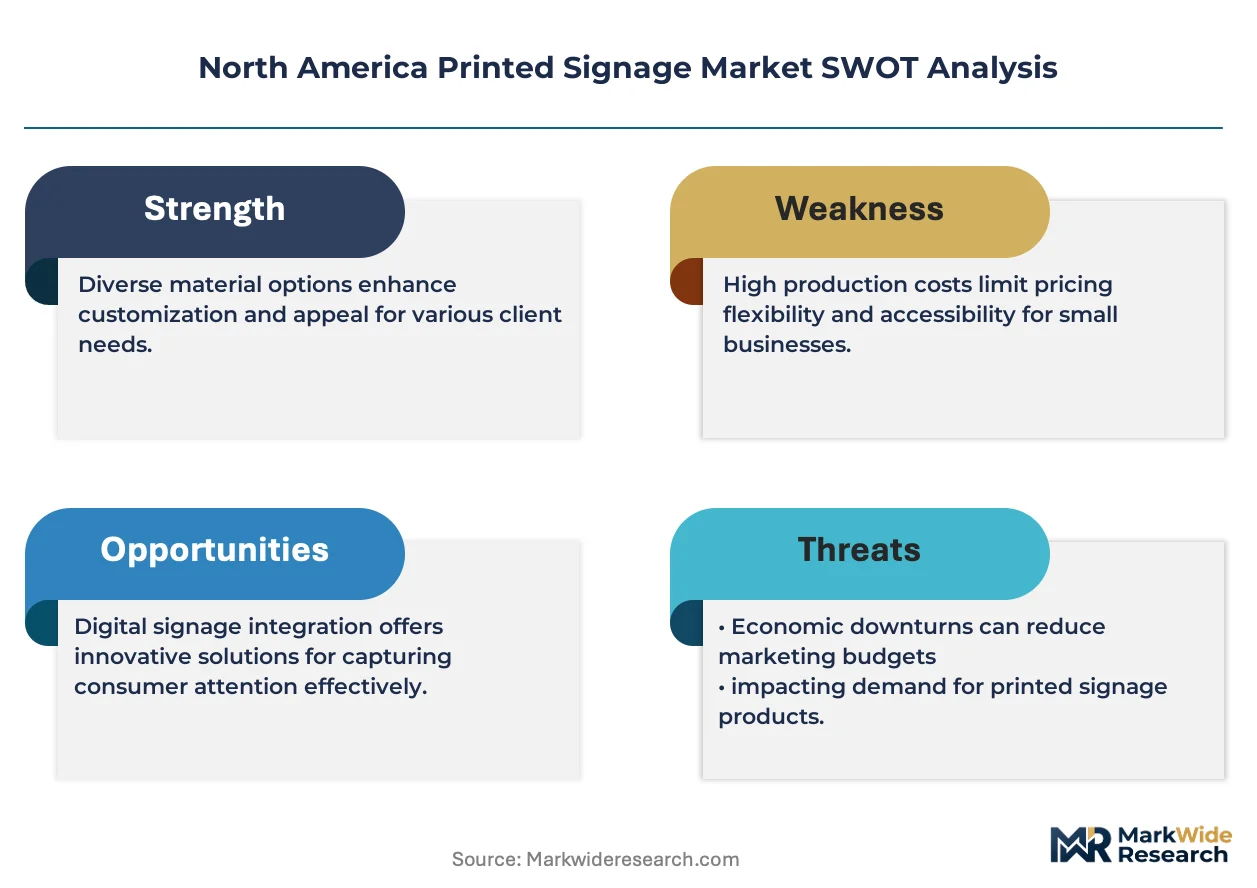
Equipment leasing and managed print service contracts are reconfiguring competitive entry barriers for mid-sized signage producers. FASTSIGNS International Inc. leverages its franchise network to sustain national coverage without heavy owned-asset exposure. Cimpress plc anchors its position through centralized digital manufacturing that competes on unit economics against local shops. Avery Dennison Corporation differentiates via captive material science capabilities spanning adhesive films and overlaminates.
Printed signage encompasses graphic displays produced through mechanical or digital deposition of pigmented inks onto rigid or flexible substrates, typically involving resolutions between 300 and 1,200 dpi for close-view applications and UV or solvent curing for outdoor durability. These products serve commercial communication needs ranging from wayfinding systems to promotional advertising in physical retail and service environments. Banners and vehicle wraps represent the fastest-expanding product categories as fleet operators and event marketers prioritize mobile and temporary branding solutions. Digital printing technology leads volume growth among production methods, while screen printing retains margin concentration in long-run specialty color matching for corporate identity programs.
The EPA regulates volatile organic compound thresholds for ink formulations used in commercial printing operations across the United States, directly affecting material selection and equipment investment cycles for signage manufacturers. Health Canada enforces parallel chemical safety standards through its Environmental Protection Act provisions, creating cross-border compliance complexity for suppliers serving both national markets. OSHA workplace exposure limits for solvent vapors further shape shop-floor technology choices, particularly in high-volume screen printing facilities. Stakeholders must monitor evolving state-level extended producer responsibility proposals that could impose end-of-life collection obligations on printed substrate flows.
Market Dynamics
Digital inkjet systems are compressing screen-printing margins across the North American signage industry, as converters absorb capital costs to capture shorter-run, faster-turnaround demand from retail and event marketing clients.
Growth Catalysts
- EPA VOC emission thresholds:Federal limits on solvent-based formulations accelerate converter investment in UV-curable and water-based ink systems, expanding addressable substrate ranges.
- Franchise retail expansion:Quick-service restaurant and fitness chains in the U.S. Sun Belt generate recurring orders for standardized point-of-purchase and exterior signage programs.
- Fleet graphics adoption:Commercial vehicle operators across Canada and the United States deploy mobile advertising wraps to maximize asset utilization during transit hours.
Market Restraints
- Petrochemical substrate volatility:PVC and polyethylene film prices fluctuate with ethylene feedstock costs, compressing converter margins on large-format banner contracts.
- Equipment supplier concentration:High-speed flatbed inkjet press manufacturing concentrates among German and Japanese OEMs, creating lead-time risk for North American print shops.
- Digital out-of-home substitution:Programmatic LED billboard networks in dense urban corridors capture advertising budgets previously allocated to static printed displays.
Strategic Opportunities
- Canadian extended producer responsibility frameworks:Provincial proposals for end-of-life substrate collection create first-mover advantage for converters offering closed-loop recycling programs.
- Textile dye-sublimation convergence:Soft signage for trade show and event applications expands as fabric substrates displace rigid boards in temporary installations.
- E-commerce packaging integration:Corrugated converters in the United States add short-run graphic capabilities to capture unboxing experience budgets from direct-to-consumer brands.
Industry Challenges
- Color management specialist scarcity:ICC profiling expertise for multi-substrate consistency remains concentrated among aging screen-printing veterans, constraining quality scaling.
- Legacy RIP software integration:Prepress workflows built on decade-old raster image processing architectures resist seamless connection to modern web-to-print order portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Printed Signage Market |
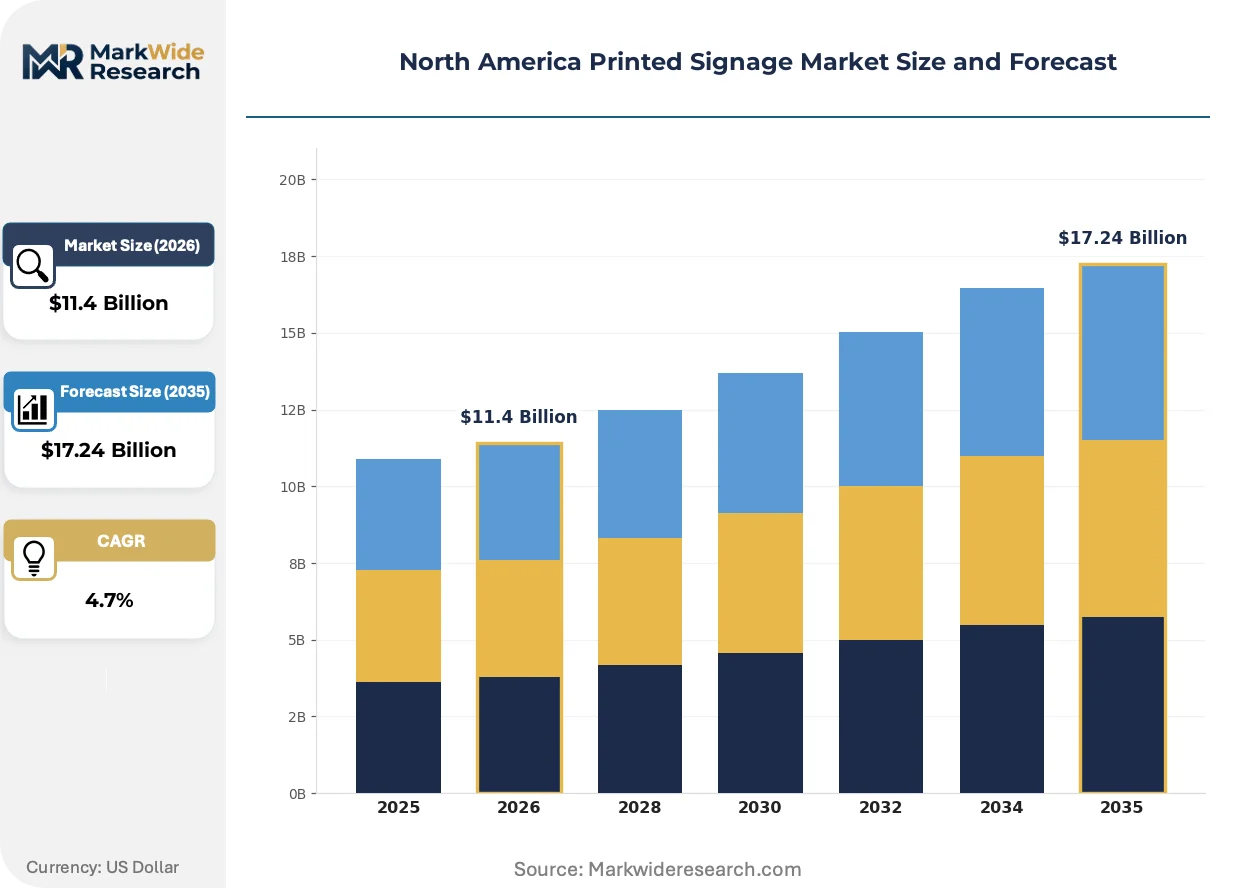
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $17.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Billboards, Banners, Posters, Vehicle Wraps Material: Vinyl, Paper, Fabric, Coroplast Technology: Digital Printing, Screen Printing, Lithography, Inkjet Printing End User: Retail, Education, Hospitality, Healthcare |
| Companies Covered | R.R. Donnelley & Sons Company, Kelly Signs Inc., FASTSIGNS International Inc., AlphaGraphics Inc., Signarama, Avery Dennison Corporation, Cimpress plc, Image360, Quad/Graphics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Printed Signage Market Shifts & Advancements
Production workflows across the North American signage sector are fragmenting into two parallel tracks: high-velocity digital output for temporary campaigns and precision screen printing for brand-critical color fidelity.
UV-LED curing technology is migrating from narrow-format label applications into wide-format rigid substrate printing, enabling direct-to-board production on acrylic, aluminum composite, and expanded PVC without lamination. Large-format print shops in California and Texas are retrofitting existing gantries with LED arrays to reduce energy consumption and eliminate mercury-vapor lamp disposal costs. This transition compresses turnaround times for outdoor permanent signage while narrowing the quality gap with traditional UV-gas-cured output.
Health Canada's Environmental Protection Act provisions on chemical safety in consumer products are tightening disclosure requirements for adhesive films and overlaminates used in retail environments. Importers serving Canadian retail chains must now document substrate composition through supply chain attestations, increasing administrative burden but creating compliance-based differentiation for domestic converters. U.S.-based suppliers with cross-border certification infrastructure capture incremental share in Toronto and Vancouver metropolitan markets.
Brand procurement teams now unbundle graphic production from installation services, issuing separate RFPs for manufacturing and field deployment. This bifurcation pressures full-service signage houses to defend margin on execution while commodity print production migrates to centralized digital manufacturing platforms. The trend is most pronounced among national retail and hospitality chains headquartered in Chicago and Dallas, where procurement functions have consolidated vendor management under dedicated facilities teams.
North America Printed Signage Market Segmentation
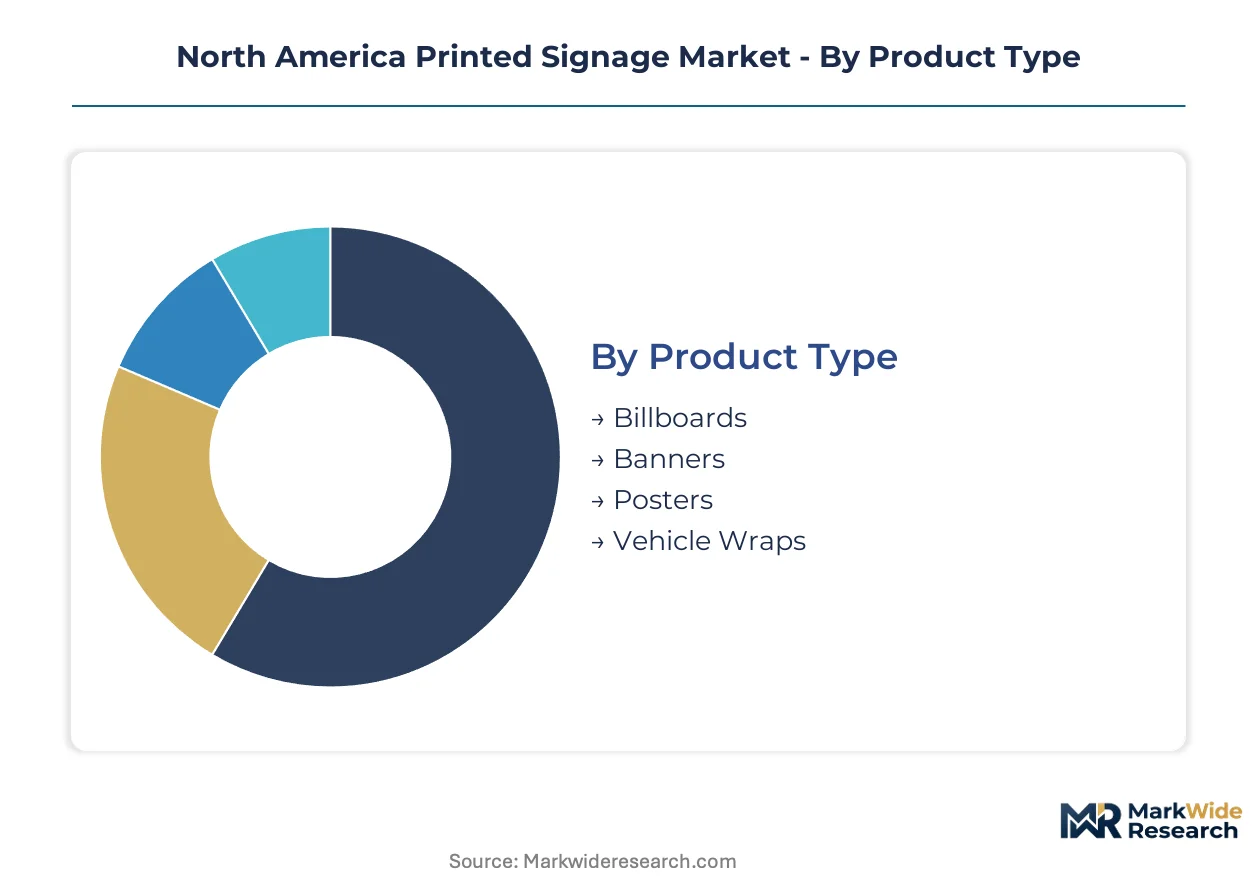
Printed signage procurement patterns diverge sharply across application environments, substrate durability requirements, and production velocity needs. Understanding these segment boundaries allows converters to align capital equipment and inventory positions with predictable demand clusters.
Product Type:
Signage formats span permanent infrastructure installations through temporary promotional deployments, each carrying distinct margin profiles and replacement cycles.
- Billboards:Large-format roadside structures engineered for extended outdoor exposure, typically printed on flexible vinyl or rigid substrates at grand format scales. Demand concentrates along interstate corridors in Texas, Florida, and California where commercial development and tourism traffic sustain recurring media buys, though digital out-of-home networks now capture premium urban inventory.
- Banners:Portable flexible displays deployed for events, construction sites, and retail promotions, produced through digital inkjet on reinforced vinyl or mesh substrates. Fleet operators and event marketers in the U.S. Sun Belt states generate recurring orders for temporary mobile branding, with quick-turn production requirements favoring local digital shops over centralized manufacturing.
- Posters:Indoor point-of-purchase displays and transit shelter advertising printed on paper or synthetic substrates at 300-600 dpi resolution. Retail chains across Canada and the United States standardize poster dimensions for seasonal campaign refreshes.
- Vehicle Wraps:Pressure-sensitive adhesive films applied to commercial fleet surfaces for mobile advertising exposure. Franchise quick-service restaurant operators prioritize wrap programs to maximize asset utilization during delivery and transit hours.
Established volume favors billboards; emerging adoption favors vehicle wraps.
Material:
Substrate selection balances durability specifications against environmental compliance constraints and installation logistics.
- Vinyl:PVC-based flexible films dominating outdoor banner and vehicle wrap applications through weather resistance and print compatibility. Petrochemical feedstock volatility compresses converter margins on large-format contracts, particularly for polyethylene-rich formulations.
- Paper:Uncoated and coated stocks for short-duration indoor posters and retail signage. Quick-service restaurant chains in Chicago and Dallas metropolitan areas drive standardized poster replenishment programs.
- Fabric:Polyester and dye-sublimation-ready textiles displacing rigid boards in trade show and event installations. Soft signage adoption climbs fastest in Toronto and Vancouver exhibition corridors where temporary display logistics favor collapsible transport.
- Coroplast:Fluted polypropylene boards for economical short-term outdoor yard signs and directional displays. Political campaign cycles and real estate marketing generate concentrated seasonal demand in U.S. swing states and Canadian provincial elections.
Margin concentration sits with vinyl; sustainability pressure favors fabric substitution.
Technology:
Production method selection determines run-length economics, color fidelity, and substrate versatility.
- Digital Printing:Electrophotographic and inkjet systems capturing shorter-run, faster-turnaround demand from retail and event marketing clients. UV-curable ink configurations expand substrate compatibility while meeting EPA VOC emission thresholds.
- Screen Printing:Stencil-based deposition retaining margin concentration in long-run specialty color matching for corporate identity programs. Aging ICC profiling expertise constrains quality scaling as veteran technicians retire.
- Lithography:Offset reproduction for high-volume poster and paper-based signage requiring precise color consistency across extended runs. Equipment investment cycles favor established commercial printers with existing press infrastructure.
- Inkjet Printing:Piezoelectric drop-on-demand systems leading volume growth through variable-data capability and reduced makeready waste. Wide-format flatbed configurations enable direct-to-rigid production on acrylic and aluminum composite without lamination.
Volume leadership belongs to inkjet; color-critical retention favors screen printing.
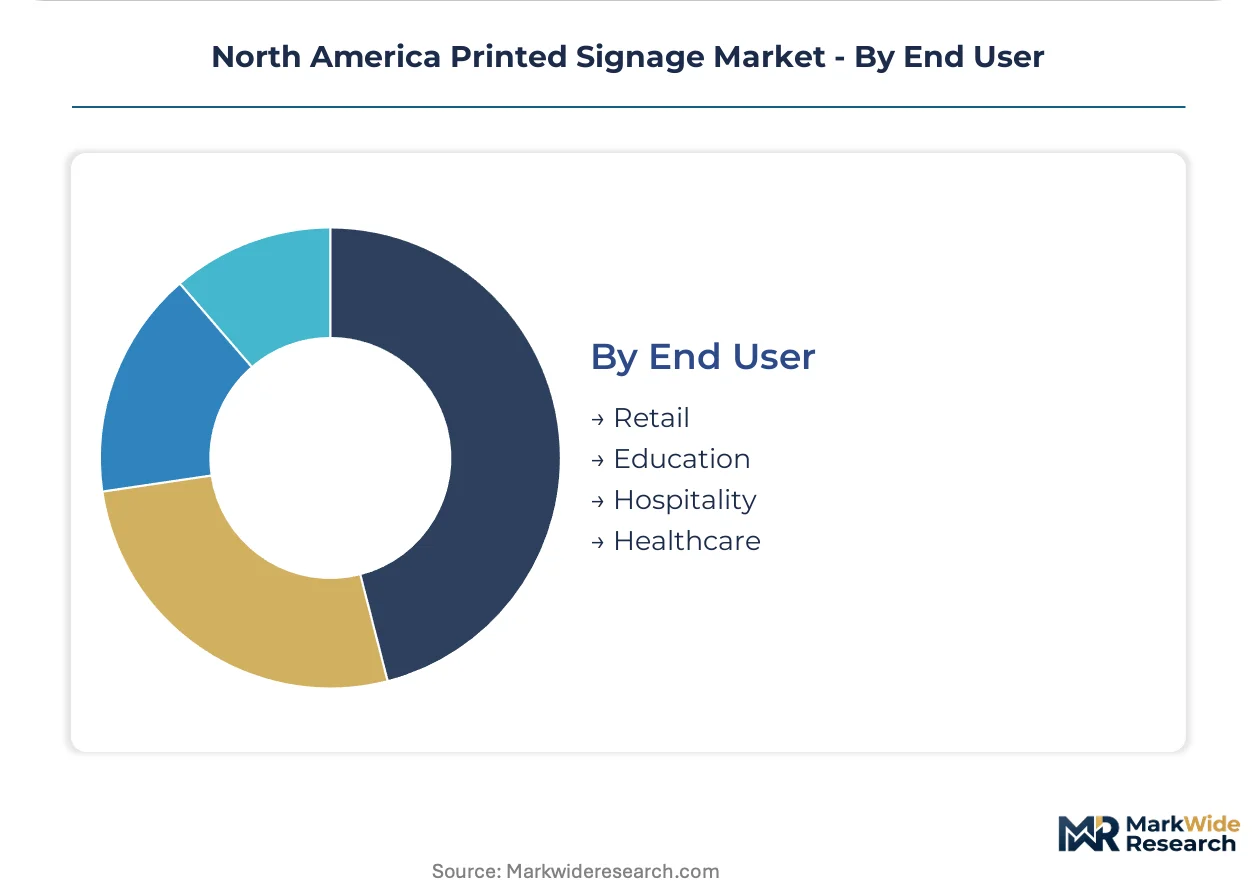
End User:
Vertical market requirements shape durability specifications, procurement cadence, and compliance documentation.
- Retail:Franchise chains and big-box operators generating standardized point-of-purchase and exterior signage programs with quarterly refresh cycles. Procurement teams now unbundle graphic production from installation services, issuing separate RFPs for manufacturing and field deployment.
- Education:K-12 districts and university campuses requiring wayfinding systems, event promotion, and athletic facility branding. Budget constraints favor economical coroplast and paper substrates over premium vinyl installations.
- Hospitality:Hotel chains and restaurant groups prioritizing interior ambiance signage and exterior identification. Brand-critical color fidelity demands screen-printed or lithographic production for permanent installations.
- Healthcare:Hospital systems and clinic networks requiring ADA-compliant wayfinding, regulatory posting, and privacy signage. Health Canada Environmental Protection Act provisions tighten disclosure requirements for adhesive films used in patient care environments.
Procurement standardization favors retail; compliance complexity favors healthcare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal VOC emission thresholds under the EPA are accelerating converter investment in UV-curable and water-based ink systems across the continent. Provincial extended producer responsibility frameworks in Canada are creating first-mover advantages for closed-loop recycling programs. These regulatory drivers are reshaping where production capacity concentrates and which substrates dominate regional supply chains.
United States
Quick-service restaurant and fitness chains in the Sun Belt generate recurring orders for standardized point-of-purchase and exterior signage programs. OSHA workplace exposure limits for solvent vapors shape shop-floor technology choices in high-volume screen printing facilities. The Dallas and Chicago metropolitan areas host consolidated procurement functions that now unbundle graphic production from installation services.
Canada
Health Canada's Environmental Protection Act provisions tighten disclosure requirements for adhesive films used in retail and patient care environments. Importers serving Toronto and Vancouver metropolitan markets must document substrate composition through supply chain attestations. Domestic converters with cross-border certification infrastructure capture incremental share in exhibition corridors where soft signage adoption climbs fastest.
California
Large-format print shops in California are retrofitting existing gantries with UV-LED arrays to reduce energy consumption and eliminate mercury-vapor lamp disposal costs. State-level air quality regulations exceed federal EPA thresholds, pushing faster adoption of zero-emission curing technologies. The state's commercial construction activity sustains demand for outdoor permanent signage with compressed turnaround requirements.
Texas
Fleet operators across Texas deploy mobile advertising wraps to maximize asset utilization during transit hours. Petrochemical substrate volatility compresses converter margins on large-format banner contracts, particularly for polyethylene-rich formulations. Houston and Austin industrial clusters concentrate digital inkjet capacity serving event marketing and construction site applications.
Florida
Tourism traffic along interstate corridors sustains recurring media buys for billboards and temporary promotional displays. Franchise retail expansion in the state generates standardized signage refresh cycles with quarterly procurement cadences. Miami and Orlando metropolitan areas anchor demand for vehicle wraps and event banners with quick-turn production requirements.
North America Printed Signage Market Competitive Landscape
On the supply side, the industry is bifurcating between centralized digital manufacturing platforms and distributed franchise networks. Equipment leasing and managed print service contracts are reconfiguring competitive entry barriers for mid-sized producers. Three strategic archetypes dominate: franchise-based national coverage without heavy owned-asset exposure, centralized manufacturing competing on unit economics, and material science specialists with captive substrate capabilities. Dominant competitive moves include geographic expansion through franchise development and portfolio diversification into installation services.
Among franchise-network operators, FASTSIGNS International Inc. exemplifies the asset-light national coverage model. Cimpress plc occupies a position representing centralized digital manufacturing at scale. Avery Dennison Corporation anchors the material science archetype with captive capabilities spanning adhesive films and overlaminates.
| Leading Market Players |
|---|
| R.R. Donnelley & Sons Company |
| Kelly Signs Inc. |
| FASTSIGNS International Inc. |
| AlphaGraphics Inc. |
| Signarama |
| Avery Dennison Corporation |
| Cimpress plc |
| Image360 |
| Quad/Graphics Inc. |
| Others |
Supply & Pricing Matrix
German and Japanese OEM concentration in high-speed flatbed inkjet press manufacturing anchors margin capture upstream, while downstream converters in Texas and California absorb equipment lead-time risk and petrochemical feedstock volatility on large-format banner contracts.
Pricing Analysis
Certification level for EPA VOC compliance and Health Canada Environmental Protection Act disclosure creates the primary spread between premium UV-curable ink systems and economy solvent-based formulations. Three-tier pricing structure across premium certified, standard compliant, and economy legacy tiers dominates contract structures. Cost compression in economy tiers is intensifying because petrochemical substrate volatility squeezes converter margins on polyethylene-rich vinyl formulations. Franchise retail procurement teams show highest price sensitivity on standardized refresh programs, while healthcare systems demonstrate lowest sensitivity due to compliance documentation requirements.
Supply Chain Analysis
Export-control scrutiny on piezoelectric printhead technology limits flows from Japanese precision component suppliers to North American equipment assemblers. Manufacturing concentrates in Germany, Japan, and China for press systems, while South Korea and Taiwan supply specialty ink chemistries. Raw material dependencies include ethylene feedstocks for PVC substrates, photoinitiators for UV-curable formulations, and aluminum composite panels for rigid signage. Single-source vulnerability concentrates in piezoelectric drop-on-demand printhead architectures. Distribution runs through franchise networks for localized quick-turn production and centralized digital manufacturing platforms for standardized national programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UV-LED curing migration and EPA emission threshold enforcement constitute a dual technological-regulatory inflection compressing turnaround times while eliminating mercury-vapor lamp disposal costs across the North American signage sector.
For Market Incumbents: Pre-empt digital out-of-home substitution by retrofitting existing gantry systems with LED arrays before California air quality regulations accelerate compliance deadlines. Consolidate ICC profiling expertise through targeted technician retention programs as veteran screen-printing specialists retire. Backward integration into captive adhesive film formulation buffers Health Canada disclosure requirement impacts on cross-border Canadian retail contracts. For New Entrants and Emerging Players: Pursue textile dye-sublimation convergence for trade show and event applications in Toronto and Vancouver exhibition corridors where soft signage adoption climbs fastest. Target fleet graphics wrap programs for quick-service restaurant operators in Texas and Florida seeking mobile advertising exposure during transit hours. Deploy web-to-print order portal integration as primary go-to-market angle to bypass legacy RIP software constraints burdening established competitors. For Investors and Strategic Acquirers: Capital is best deployed toward material science specialists with captive substrate capabilities spanning adhesive films and overlaminates, given durable margin concentration in supply-constrained input tiers. Long-term viability favors converters with cross-border certification infrastructure capturing incremental share in Canadian metropolitan markets. Watch provincial extended producer responsibility framework adoption rates as inflection indicator for closed-loop recycling program valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| UV-LED Retrofit Program | California print shops reduce energy consumption while meeting state air quality thresholds exceeding EPA limits. |
| Cross-Border Certification Infrastructure | U.S. converters capture Toronto and Vancouver share as Health Canada tightens adhesive film disclosure requirements. |
| Textile Dye-Sublimation Capacity Addition | Fabric substrate production displaces rigid boards in temporary exhibition installations across Canadian corridors. |
| Closed-Loop Recycling Program | First-mover advantage emerges as Canadian provinces propose end-of-life substrate collection obligations. |
| Web-to-Print Portal Integration | Bypasses legacy RIP software constraints resisting seamless connection to modern order workflows. |
Research Methodology
Cross-validation between primary interviews with franchise network operators, digital manufacturing platform engineers, and EPA compliance officers and secondary validation through SEC 10-K filings, EPA enforcement databases, and Health Canada regulatory notices anchors the qualitative findings. Bottom-up triangulation across converter capacity surveys and top-down reconciliation against petrochemical feedstock trade flows ensures segmentation integrity.
Calibration against historical equipment investment cycles and substrate price elasticity informs the analytical framework across the analysis window. Segmentation dimensions modeled include product type, substrate material, production technology, and end-user vertical with regional regulatory cluster overlays. CAGRs derive from installed base depreciation schedules and replacement demand curves. Forecast inputs incorporate franchise expansion pipeline data from quick-service restaurant and fitness chains and VOC compliance cost pass-through elasticity.
Macroeconomic conditions sit as an overlay; deviation in commercial construction activity across the U.S. Sun Belt and ethylene feedstock pricing volatility would shift the trajectory. Forecasts reflect documented assumptions regarding EPA enforcement consistency and Health Canada disclosure phase-in timelines. Material shifts in digital out-of-home network expansion rates or provincial extended producer responsibility implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Cosmetovigilance Market
Others
Three Proofing Rugged Tablet Market
Others
Latin America Travel Retail Market
Others
Dried Egg Market
Others
Asia-Pacific Military 4D Printing Market
Others
Disposable Non Woven Sponge Market
Others
HPHT Diamond Cubic Press Market
Others
China Packaging Primers Market
Others
Workstation Desktops Market
Others
Mobile Computer Cart Market
Others
US Tablet Market
Others
Thailand Travel Retail Market
Others
Asia-Pacific Air Separation Unit Market
Others
3D Printing Construction Market
Others
Middle East 3D Printing Construction Market
Others
China Cloud Gaming Technology Market