
 Electric Pallet Jack Truck Market | 2026-2036
Electric Pallet Jack Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Pallet Jack Truck Market Analysis
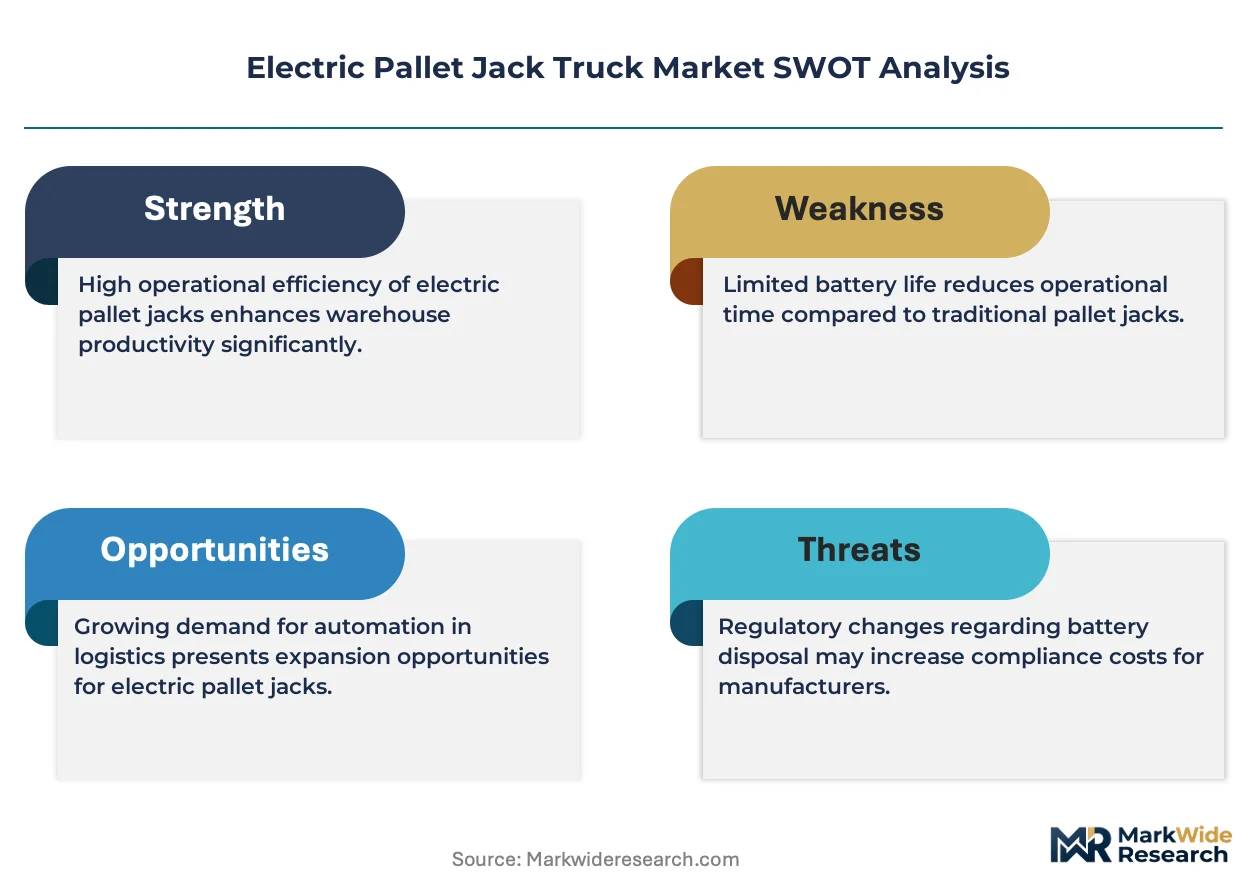
Certified forklift technician shortages across major logistics corridors is unwinding delivery timelines and service capacity for fleet operators. Toyota Material Handling Group leverages its captive parts network to sustain uptime guarantees for high-velocity distribution centers. Jungheinrich anchors European demand through dense service infrastructure in the Benelux and German industrial belts. Crown Equipment Corporation differentiates via vertical integration into drive motor and controller manufacturing, insulating its supply chain from component volatility.
An electric pallet jack truck is a battery-powered material handling device with load capacities typically spanning 1,500 to 8,000 pounds, utilizing DC or AC drive motors to transport palletized goods across warehouse and retail floors without manual hydraulic pumping. Walkie electric units dominate volume sales for short-haul dock-to-stock applications, while rider electric configurations command margin premiums in large-scale distribution facilities requiring operator transport over extended distances. Lithium-ion battery adoption is displacing lead acid across premium fleet segments due to opportunity charging compatibility and elimination of battery swap infrastructure.
OSHA powered industrial truck standards and the EU Machinery Directive 2006/42/EC collectively mandate operator training, stability testing, and electromagnetic compatibility certification that elevate compliance costs for non-compliant imports. EPA Tier 4 final rules and California Air Resources Board warehouse fleet regulations are compressing the operational window for internal combustion alternatives, redirecting procurement budgets toward electric pallet jack platforms. Stakeholders must evaluate total cost of ownership models that incorporate battery chemistry depreciation, utility rate structures, and residual value recovery before committing to fleet standardization strategies.
Market Dynamics
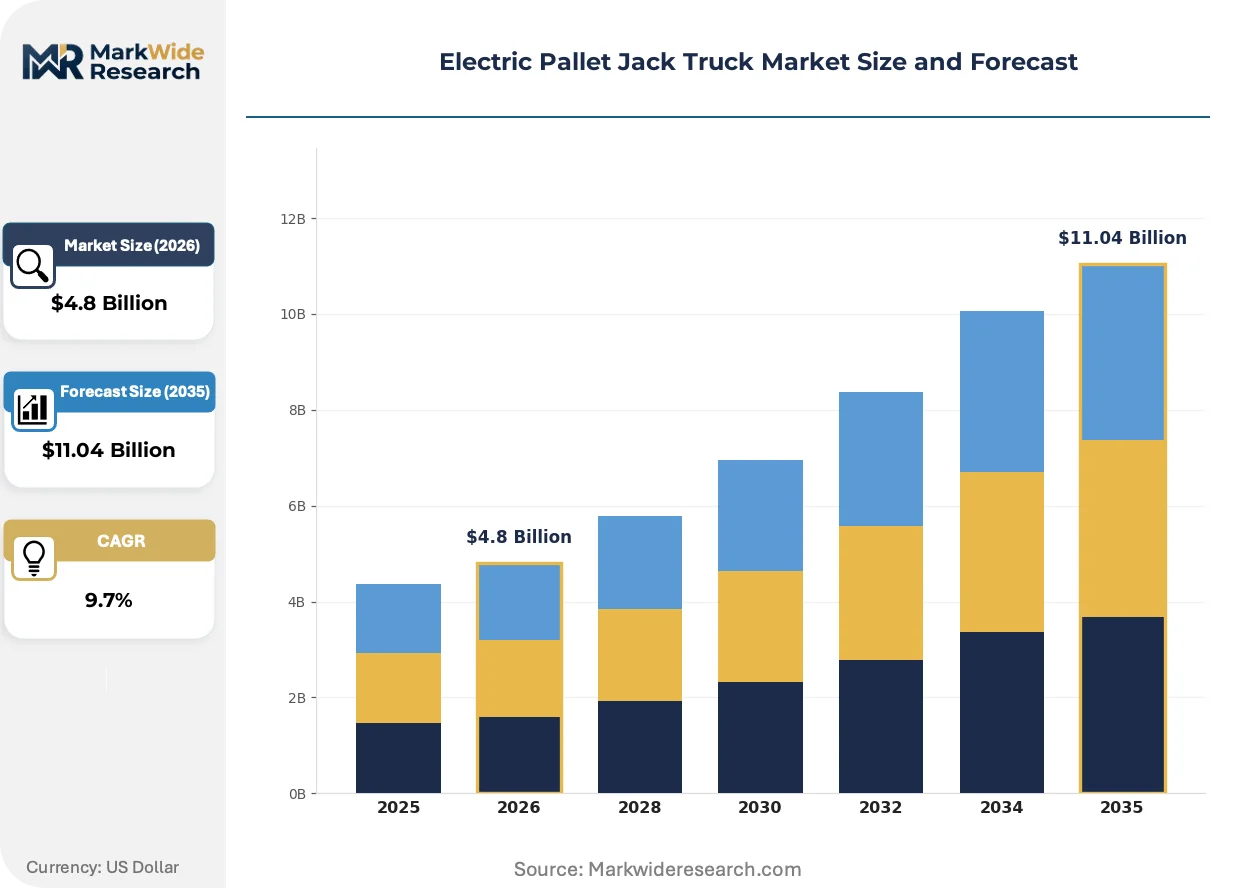
Fleet electrification mandates across logistics corridors are compressing replacement cycles for internal combustion equipment while lithium-ion battery standardization reconfigures procurement evaluation frameworks around total cost of ownership metrics.
Growth Catalysts
- OSHA powered industrial truck standards:Operator certification requirements and stability testing protocols are elevating replacement demand for compliant electric units in US distribution networks.
- Lithium-ion chemistry:Opportunity charging compatibility and elimination of battery swap infrastructure are accelerating fleet conversion timelines in high-velocity fulfillment operations.
- German industrial belt concentration:Dense warehousing clusters in Baden-Württemberg and Bavaria are generating concentrated demand for rider electric configurations with extended range specifications.
Market Restraints
- Cobalt and lithium carbonate volatility:Raw material price swings in battery supply chains are compressing margin structures for original equipment manufacturers.
- Lead-acid installed base inertia:Existing battery swap infrastructure and sunk capital in legacy fleets are extending replacement timelines for cost-sensitive operators.
- Electromagnetic compatibility certification:EU Machinery Directive testing requirements are creating friction for non-compliant import penetration into European markets.
Strategic Opportunities
- India warehousing expansion:E-commerce fulfillment center buildouts in Maharashtra and Karnataka are creating greenfield demand for walkie electric units without legacy equipment displacement costs.
- Telematics-ERP convergence:Integration of fleet management software with warehouse management systems is enabling predictive maintenance revenue streams for equipment vendors.
- California Air Resources Board fleet regulations:Warehouse emissions mandates are redirecting capital allocation toward zero-emission material handling platforms in the US West Coast corridor.
Industry Challenges
- Certified technician scarcity:Shortages of qualified forklift service technicians across major logistics corridors are extending mean time to repair and degrading uptime guarantees.
- Legacy WMS integration complexity:Retrofitting electric fleet telematics into existing warehouse software architectures is requiring custom middleware development and elongating deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Pallet Jack Truck Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walkie Electric, Rider Electric, Low Profile, Heavy Duty End User: Warehouses, Retail, Manufacturing, Logistics Power Source: Lead Acid Battery, Lithium-ion Battery, Fuel Cell, Others Control Mechanism: Manual Control, Electric Control, Remote Control, Automated |
| Companies Covered | Toyota Material Handling Group, Jungheinrich, Crown Equipment Corporation, Hyster-Yale Materials Handling, Yale Materials Handling, Raymond, EP Equipment, Hangcha Forklift, KION Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Pallet Jack Truck Market Emerging Trajectories
Battery chemistry migration and embedded sensor proliferation are redefining equipment lifecycle economics while regulatory emissions frameworks compress the operational viability of combustion alternatives.
Lithium-ion phosphate configurations are decomposing the traditional lead-acid replacement cycle in multi-shift distribution environments. Third-party logistics operators in the Netherlands and Belgium are deploying opportunity charging infrastructure to eliminate battery changeout downtime. This chemistry shift is decomposing the capital allocation logic that previously favored lower upfront equipment costs over lifetime operating expenditure.
EU Machinery Directive electromagnetic compatibility amendments are mandating revised certification protocols for drive motor controllers entering European markets. Industrial equipment importers are restructuring supplier qualification processes to pre-validate compliance documentation. German and French warehousing operators are prioritizing CE-marked platforms to avoid customs detention and deployment delays.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-market fleet operators. Third-party financiers and original equipment manufacturers are competing to bundle maintenance, telematics, and battery replacement into per-hour usage agreements. This financing transformation is most visible in US retail distribution networks where seasonal volume volatility favors operational expenditure classification.
Electric Pallet Jack Truck Market Segmentation
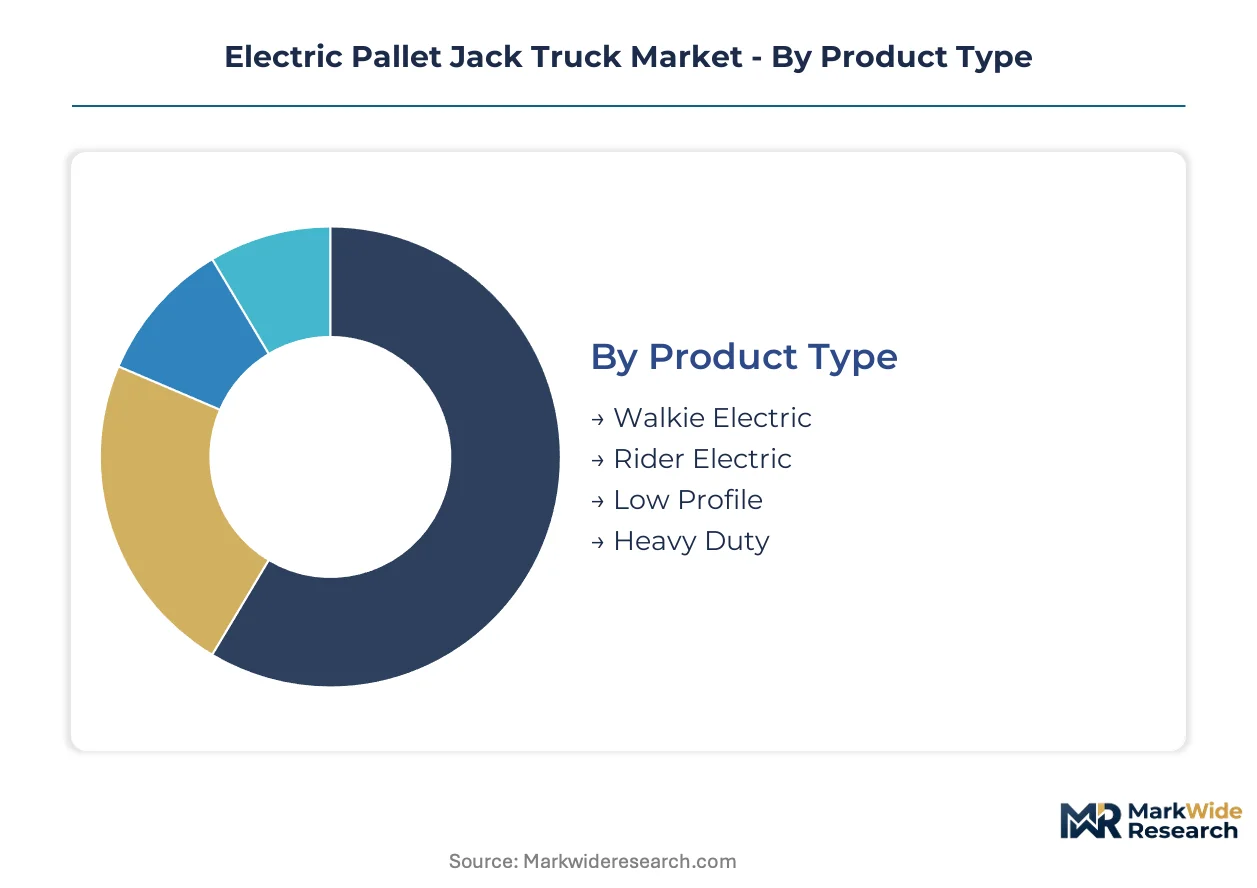
Segmentation in the electric pallet jack truck market reveals how procurement decisions fragment across operational intensity, facility scale, and power infrastructure maturity. Fleet operators prioritize different performance thresholds based on shift patterns, aisle dimensions, and existing battery management investments.
Product Type:
Substitution pressure from autonomous mobile robots and conveyor systems threatens walkie configurations most acutely, while rider units defend position through transport-distance economics that automation cannot yet match.
- Walkie Electric:Compact units with operator walking pace speeds up to 3.5 mph and load centers optimized for dock-to-stock distances under 200 feet. Demand concentrates in US retail distribution networks where seasonal volume spikes favor flexible labor deployment over fixed automation infrastructure.
- Rider Electric:Sit-down or stand-on configurations with travel speeds exceeding 6 mph and operator platforms for extended horizontal transport. German automotive parts distribution centers in Stuttgart and Wolfsburg generate concentrated procurement for multi-shift operations requiring reduced operator fatigue.
- Low Profile:Deck heights below 2.5 inches for ground-level loading and specialty pallet formats. Cold storage facilities in the Netherlands specify these for frozen food handling with minimal lift clearance.
- Heavy Duty:Reinforced frames and drive motors rated above 6,000 pounds for steel, beverage, and building materials handling. Port-adjacent warehousing in Belgium and northern France drives specification for container destuffing applications.
Walkie electric configurations anchor the volume base while rider electric units gain share at the steepest rate as distribution facility footprints expand.
End User:
Margin structures diverge sharply across customer types, with manufacturing procurement emphasizing durability specifications and retail buyers prioritizing acquisition cost minimization.
- Warehouses:Multi-shift fulfillment operations with 24-hour runtime requirements and opportunity charging infrastructure. Third-party logistics operators in California and Texas specify lithium-ion compatible units to meet CARB fleet regulations without battery swap labor.
- Retail:Backroom stocking and seasonal volume surges with intermittent usage patterns. Big-box distribution networks in the US Midwest favor walkie electric units with lead-acid batteries for capital cost containment.
- Manufacturing:Just-in-time component delivery with synchronized production line feeding. Automotive assembly plants in Bavaria demand rider electric units with precision speed control for line-side replenishment.
- Logistics:Cross-dock operations with rapid trailer turnover and multi-customer handling. Parcel sorting hubs in Belgium and the Netherlands specify heavy-duty configurations for irregular freight weights.
Warehouses represent the largest revenue pool while logistics end users are expanding most quickly as e-commerce fulfillment networks densify.
Power Source:
Customer investment in charging infrastructure creates switching costs that segment the installed base between chemistry-dependent fleet ecosystems.
- Lead Acid Battery:Flooded or sealed lead-acid configurations with established swap station infrastructure and lower upfront capital requirements. Cost-sensitive operators in India and Southeast Asia extend replacement cycles due to sunk investment in battery rooms and watering systems.
- Lithium-ion Battery:Lithium iron phosphate and nickel manganese cobalt chemistries with partial state-of-charge tolerance and elimination of battery changeout labor. German industrial belt operators in Baden-Württemberg deploy opportunity charging at dock doors to maximize equipment utilization rates.
- Fuel Cell:Hydrogen proton exchange membrane systems with three-minute refueling and zero local emissions. Pilot deployments at Walmart distribution centers in California test viability for continuous multi-shift operations.
- Others:Emerging chemistries including sodium-ion and solid-state prototypes in pre-commercial validation. Japanese material handling manufacturers evaluate these for next-generation platform standardization.
Lead-acid batteries retain the largest installed base while lithium-ion configurations are climbing the fastest as total cost of ownership models gain procurement influence.
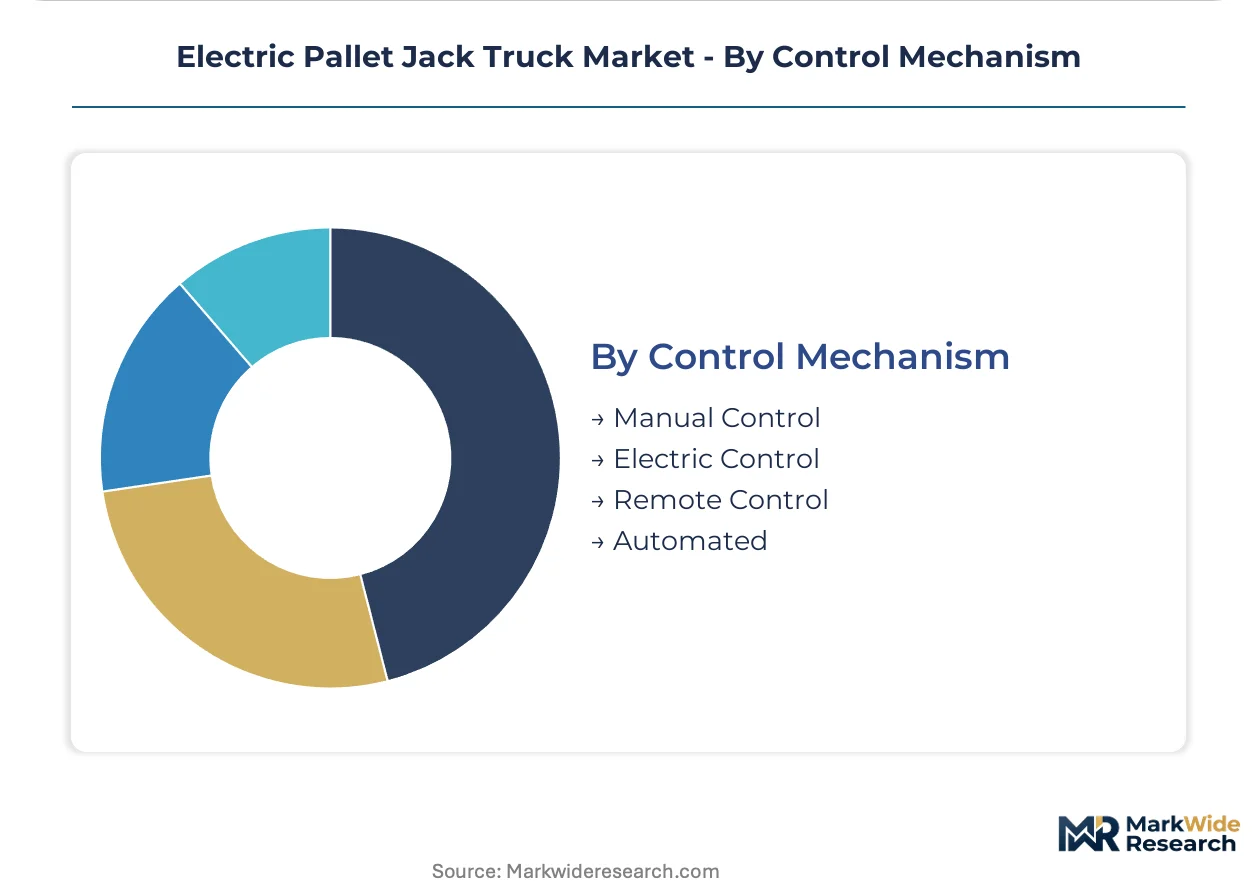
Control Mechanism:
Automation readiness separates facility investment tiers, with manual control defending position in variable task environments and automated systems penetrating greenfield high-velocity operations.
- Manual Control:Tiller arm or pendant control with operator discretion over acceleration, braking, and lift functions. Legacy warehousing in the US Southeast and Midwest maintains this specification for workforce flexibility and minimal training requirements.
- Electric Control:Solid-state drive controllers with programmable acceleration curves and regenerative braking. European operators prioritize these for OSHA and EU Machinery Directive electromagnetic compatibility compliance.
- Remote Control:Wireless pendant or wearable transmitter operation for hazardous environment access or dual-pallet handling. Chemical processing facilities in Texas and Louisiana specify these for explosive atmosphere zones.
- Automated:LiDAR or vision-guided navigation with warehouse management system integration for unmanned transport missions. Amazon fulfillment centers and Ocado automated warehouses in the UK deploy these for goods-to-person picking workflows.
Electric control mechanisms dominate current procurement volumes while automated configurations are gaining share fastest as labor cost inflation accelerates robotics deployment timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's industrial belt while cost-sensitive procurement dominates Indian warehousing expansion. This asymmetry fragments regional margin structures and redirects manufacturer investment toward high-specification European markets versus volume-scale Asian deployments.
United States
California CARB warehouse fleet regulations and Texas e-commerce fulfillment buildouts drive divergent demand profiles. OSHA powered industrial truck standards mandate operator certification and stability testing that elevate compliance costs for import equipment. Distribution centers in the Inland Empire and Dallas-Fort Worth corridor specify lithium-ion compatible units to meet emissions mandates without battery swap labor.
Germany
Automotive parts distribution in Stuttgart and Wolfsburg generates concentrated procurement for rider electric configurations with extended range. EU Machinery Directive electromagnetic compatibility amendments mandate revised certification protocols for drive motor controllers entering European markets. Baden-Württemberg and Bavaria warehousing clusters deploy opportunity charging at dock doors to maximize equipment utilization rates.
China
Domestic logistics operators in the Yangtze River Delta and Pearl River Delta prioritize acquisition cost minimization over premium specifications. GB standards and MIIT industrial equipment directives shape local certification requirements that foreign manufacturers must navigate. Shenzhen and Shanghai distribution hubs favor walkie electric units for high-volume, short-haul applications.
India
E-commerce fulfillment center buildouts in Maharashtra and Karnataka create greenfield demand without legacy equipment displacement costs. The country's national industrial safety regulator enforces operator training mandates that elevate compliance investments for fleet operators. Mumbai and Bangalore warehousing clusters specify lead-acid configurations to contain capital expenditure amid rapid capacity scaling.
Netherlands
Third-party logistics operators deploy opportunity charging infrastructure to eliminate battery changeout downtime in multi-shift environments. REACH and RoHS directives constrain battery chemistry selection for equipment entering Dutch distribution networks. Rotterdam port-adjacent warehousing and Venlo logistics parks drive specification for heavy-duty configurations in container destuffing applications.
Electric Pallet Jack Truck Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where premium specification vendors coexist with scale-focused fabricators. The vendor base concentrates among integrated industrial equipment conglomerates with captive component production and regional specialists serving price-sensitive procurement. Three archetypes dominate: integrated technology leaders with in-house drive motor manufacturing, regional scale players with cost-optimized platforms, and emerging Asian fabricators capturing volume growth in developing markets. Competitive dynamics center on backward integration into battery and controller supply chains alongside geographic expansion through distribution partnerships.
Among Japanese industrial equipment conglomerates, Toyota Material Handling Group exemplifies the integrated archetype with its captive parts network sustaining uptime guarantees. German specialists Jungheinrich and Crown Equipment Corporation occupy positions emphasizing dense service infrastructure and upstream control over drive motor production respectively. These three anchors represent divergent strategic bets on technology depth versus geographic coverage versus supply chain insulation.
| Leading Market Players |
|---|
| Toyota Material Handling Group |
| Jungheinrich |
| Crown Equipment Corporation |
| Hyster-Yale Materials Handling |
| Yale Materials Handling |
| Raymond |
| EP Equipment |
| Hangcha Forklift |
| KION Group |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for lithium-ion battery packs from South Korean cell suppliers compress pricing power for European OEMs while elevating spot-premium exposure for North American distributors without captive supply arrangements. This inventory-band tension feeds directly into configured-to-order premium spreads and standard-catalog pricing tiers across the electric pallet jack truck procurement landscape.
Pricing Analysis
The customization-premium spread between configured-to-order rider electric units and standard walkie electric configurations spans three performance tiers: premium lithium-ion rider platforms with telematics integration, standard lead-acid walkie units for seasonal retail deployment, and economy-grade imports for cost-sensitive Indian warehousing. Price differentiation hinges on battery chemistry certification grade and aftermarket service bundling intensity. Cost compression in the standard tier is intensifying because Chinese fabricators are expanding European distribution partnerships. Third-party logistics operators in California demonstrate the lowest price sensitivity due to CARB compliance mandates, while Midwest retail distribution networks exhibit acute sensitivity to upfront capital outlay.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for drive motor controllers sourced from Chinese manufacturing clusters, compressing margin buffers for European equipment assemblers. Component concentration centers on China for cast steel frames and hydraulic assemblies, Germany for precision drive motors, and South Korea for lithium-ion cells. Raw material dependencies span cobalt carbonate, rare-earth magnets, and high-grade electrical steel. Single-source vulnerability in battery management system chipsets creates structural risk exposure. Distribution runs through authorized dealer networks with captive parts warehousing for aftermarket service revenue capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among third-party logistics operators with multi-site fleet standardization mandates, fragmenting price negotiation leverage for smaller warehousing operators and elevating volume-discount thresholds across procurement contracts.
For Market Incumbents: Fortify captive battery supply arrangements through upstream partnerships with South Korean cell manufacturers to offset cobalt price volatility. Deepen service infrastructure density in the German industrial belt where Jungheinrich maintains network advantages. Autonomous mobile robot substitution in walkie electric applications represents the priority threat requiring R&D investment in human-machine collaboration interfaces. For New Entrants and Emerging Players: Differentiate on lithium-ion retrofit kits for lead-acid installed bases in India and Southeast Asia where legacy battery room infrastructure creates switching-cost friction for incumbent OEMs. Target Maharashtra e-commerce fulfillment greenfield deployments with walkie electric platforms priced below European premium tiers. Pursue equipment-as-a-service contracting to bypass capital-budget approval cycles among mid-market fleet operators. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with underoptimized material handling divisions lacking integrated battery or controller manufacturing capabilities. Long-term viability favors vendors with backward integration into power electronics and dense regional service footprints. Monitor lithium iron phosphate cell pricing inflection as the signal for fleet conversion acceleration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Chemistry Vertical Integration | In-house lithium-ion cell assembly insulates Crown Equipment from South Korean supply volatility. |
| Opportunity Charging Infrastructure Deployment | Dock-door fast-charging networks enable Jungheinrich customers to eliminate battery swap labor in Baden-Württemberg. |
| Telematics-ERP Platform Convergence | Predictive maintenance revenue streams deepen Toyota Material Handling's software-services attach rates. |
| EU Machinery Directive Pre-Certification | CE-marked drive controllers prevent customs detention for EP Equipment penetrating Rotterdam logistics hubs. |
| Equipment-as-a-Service Contracting | Per-hour usage agreements convert capital expenditure to operational expenditure for US retail distribution volatility. |
Methodological Framework
Initial hypotheses were tested against primary input from fleet maintenance directors, warehouse operations managers, OEM procurement teams, and aftermarket service heads, then refined through secondary validation against customs trade data, OSHA enforcement records, SEC equipment manufacturer filings, and EU Machinery Directive certification databases. Bottom-up unit shipment estimates triangulated against top-down fleet replacement cycle modeling.
Variance decomposition across the projection horizon isolates volume drivers by product type, power source chemistry, end-use intensity, and regional regulatory cluster. CAGRs were derived from segmented growth rate reconciliation against macroeconomic freight indices and e-commerce fulfillment square footage expansion. Forecast inputs incorporate lithium carbonate price trajectories and certified technician labor availability by logistics corridor.
Material uncertainties — battery raw material price spikes, electromagnetic compatibility regulatory amendments, and autonomous mobile robot substitution velocity — sit outside the modeled envelope. Forecasts reflect documented assumptions about fleet electrification mandate enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Nonlinear Editing System Market
Others
Global Pumpkin Candles Market
Others
Global Multi-Access Edge Computing Market
Others
Idaas Market
Others
Augmented Reality in Energy and Utilities Market
Others
Cloud-Based Streaming Services Market
Others
Aircraft Lighting Market
Others
Lepidolite Market
Others
Global Virtual Keyboard Market
Others
Thailand Travel Retail Market
Others
Cathode Battery Material Market
Others
UAE Location-Based Services Market
Others
Global Pregnancy Tracker Apps Market
Others
Smartphone Gimbal Market
Others
Fabric Based Computing Market
Others
5G Smartphone Market