
 Feed Protein Market | 2026-2036
Feed Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Protein Market Analysis
Direct procurement between soybean processors and integrated livestock operators is reconfiguring traditional distributor roles in the feed protein value chain. Cargill Inc. leverages its crushing assets across the U.S. Midwest to secure origination-to-feedlot pipelines. Archer Daniels Midland Company anchors its position through extensive oilseed processing networks and destination country port investments. Bunge Limited competes by controlling South American origination and ocean freight logistics to Asian markets.
Feed protein encompasses processed oilseed meals, rendered animal proteins, and novel plant and microbial ingredients formulated to deliver standardized amino acid profiles, typically 40-50% crude protein for soybean meal, to monogastric and ruminant diets. Soybean meal dominates volume flows due to its cost-per-unit-protein economics and established crushing infrastructure across the U.S. Corn Belt and Brazilian Cerrado. Pea protein is gaining formulation share in aquaculture and pet food applications where allergen labeling and non-GMO certification command premium positioning. Fish meal remains supply-constrained as Peruvian anchovy quotas tighten, pushing marine protein toward high-value shrimp and salmon diets.
The U.S. FDA and USDA govern feed safety through the Food Safety Modernization Act and BSE prevention rules, while the EU REACH and EFSA frameworks restrict chemical residues in imported meals. Brazil's MAPA and China's SAMR enforce parallel mycotoxin and GMO labeling standards that determine market access for major exporters. Stakeholders must monitor regulatory divergence on novel protein approvals, particularly for fermented single-cell ingredients and insect meal, as these pathways determine which suppliers capture next-generation formulation contracts.
Market Dynamics
The EU F-Gas Regulation and Green Deal are compressing supply windows for carbon-intensive feedstock imports, redirecting procurement toward certified sustainable origination corridors and novel protein fermentation infrastructure.
Growth Catalysts
- EU Green Deal sustainability mandates:Binding deforestation-free import requirements are accelerating demand for certified soybean meal and traceable pea protein across European compound feed operations.
- Indonesian aquaculture expansion:Shrimp farming and poultry integrators are scaling formulated feed capacity, pulling higher volumes of fish meal and alternative protein meals into Southeast Asian supply chains.
- Precision fermentation:Microbial protein production is achieving cost parity with conventional meals in salmon and pet food formulations, opening captive offtake contracts with integrated protein processors.
Market Restraints
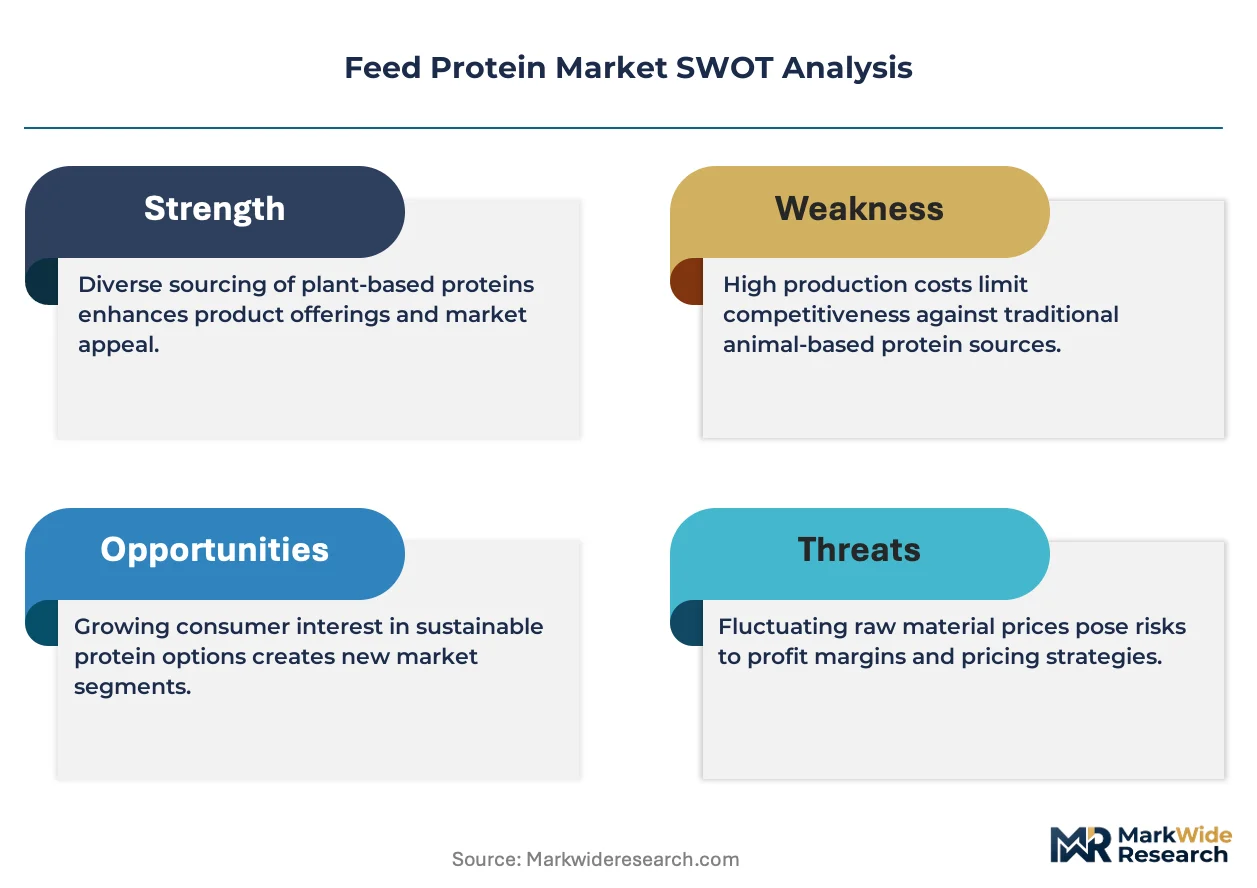
- Peruvian anchovy quota volatility:Tight marine catch limits constrain fish meal supply, forcing high-value aquaculture diets toward costlier insect meal and single-cell protein substitutes.
- Brazilian Cerrado logistics concentration:Crushing capacity clusters in Mato Grosso and Paraná create origination bottlenecks during harvest windows, amplifying freight cost exposure for Asian importers.
- Novel protein approval timelines:EFSA and FDA regulatory pathways for insect meal and fermented ingredients extend 18-36 months, freezing formulation adoption until safety dossiers clear.
Strategic Opportunities
- Underpenetrated Indian aquafeed:Shrimp farming in Andhra Pradesh and Gujarat lacks domestic protein meal crushing infrastructure, creating origination-to-farm supply chain buildout potential.
- Carbon credit monetization:EU CSRD disclosure requirements and voluntary offset markets are enabling premium pricing for verified low-carbon soybean and microbial protein certificates.
- Direct processor-livestock procurement:Crushing assets in the U.S. Midwest are bypassing traditional distributors to secure origination-to-feedlot pipelines with integrated cattle and swine operators.
Industry Challenges
- Fermentation scale-up capex:Commercial single-cell protein facilities require nine-figure capital deployment for bioreactor infrastructure, constraining mid-tier entrants.
- Multi-jurisdictional mycotoxin compliance:Brazil's MAPA, China's SAMR, and EU EFSA enforce divergent aflatoxin and vomitoxin thresholds, forcing exporters to maintain parallel testing protocols.
- Legacy formulation integration:Ruminant and monogastric nutritionists face knowledge gaps in amino acid balancing for novel proteins, slowing substitution rates in commercial diets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Protein Market |
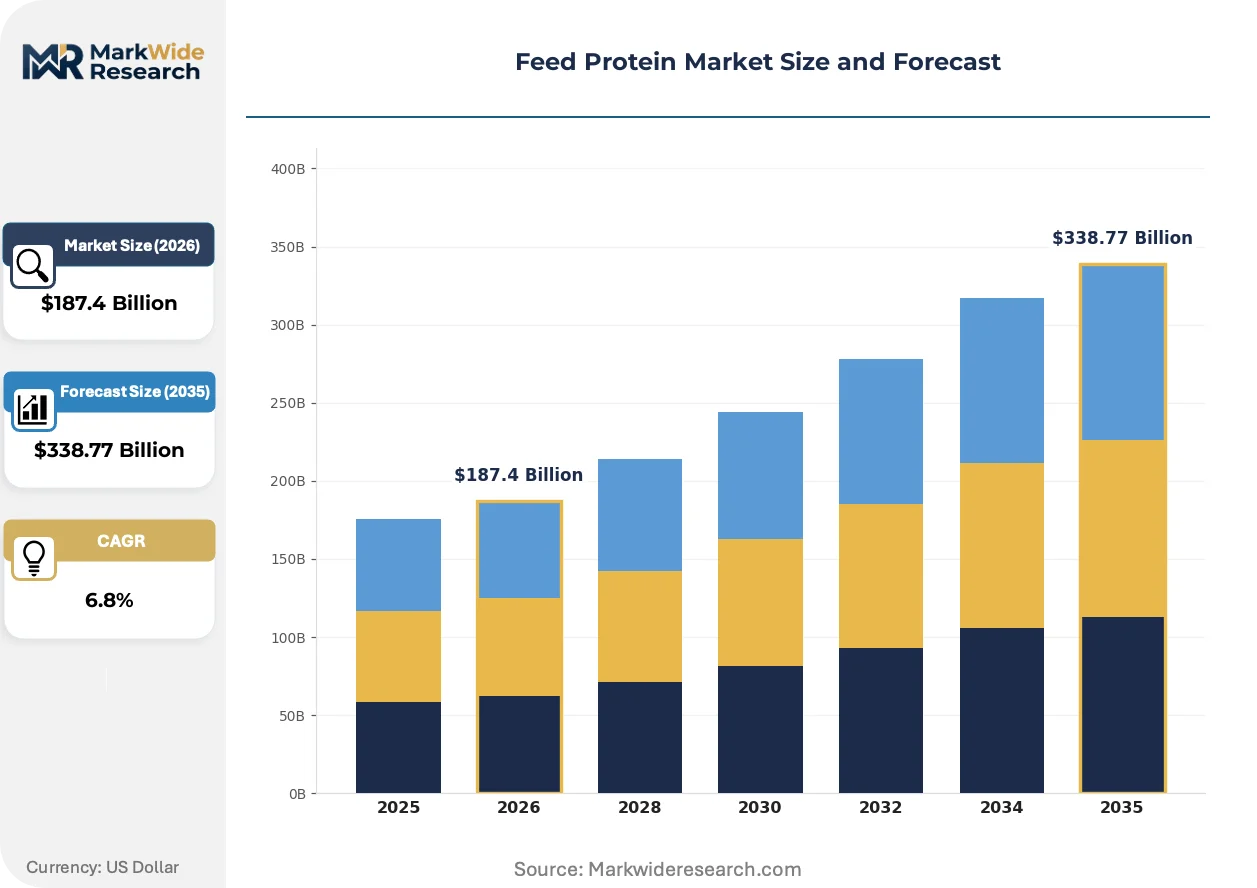
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soybean Meal, Canola Meal, Fish Meal, Pea Protein Application: Poultry, Ruminants, Swine, Aquaculture Form: Meal, Concentrate, Isolate, Hydrolysate End User: Animal Feed Producers, Feed Millers, Farmers, Livestock Operators |
| Companies Covered | Cargill Inc., Archer Daniels Midland Company, Bunge Limited, Wilmar International Limited, Charoen Pokphand Foods PCL, DuPont, Evonik Industries AG, DSM-Firmenich, Nutreco N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Protein Market Emerging Trajectories
Digital origination platforms and bioprocess automation are compressing the gap between farm-level traceability and formulation precision, enabling real-time protein quality verification.
Precision fermentation of single-cell proteins is virtualizing the traditional crushing-to-meal value chain. Salmon feed producers in Norway and Chile are integrating microbial protein concentrates at 15-30% inclusion rates. This technology is virtualizing commodity protein procurement into specification-driven, contract-manufactured ingredient streams.
REACH and EU F-Gas Regulation restrictions on chemical inputs are tightening residue limits in imported oilseed meals. Crushing operators in Argentina and Ukraine must now certify solvent extraction methods and hexane recovery rates to maintain European market access. Aquaculture feed blenders are responding by dual-sourcing from REACH-compliant EU crush facilities and certified South American origination.
Integrated livestock operators are consolidating procurement decisions at the headquarters level, displacing decentralized distributor relationships. U.S. feedlot chains and Brazilian poultry integrators now negotiate directly with soybean processors for twelve-month origination contracts. This concentration is most visible in the U.S. Corn Belt and Mato Grosso, where processor-owned logistics assets enable just-in-time meal delivery to captive feed mills.
Feed Protein Market Segmentation
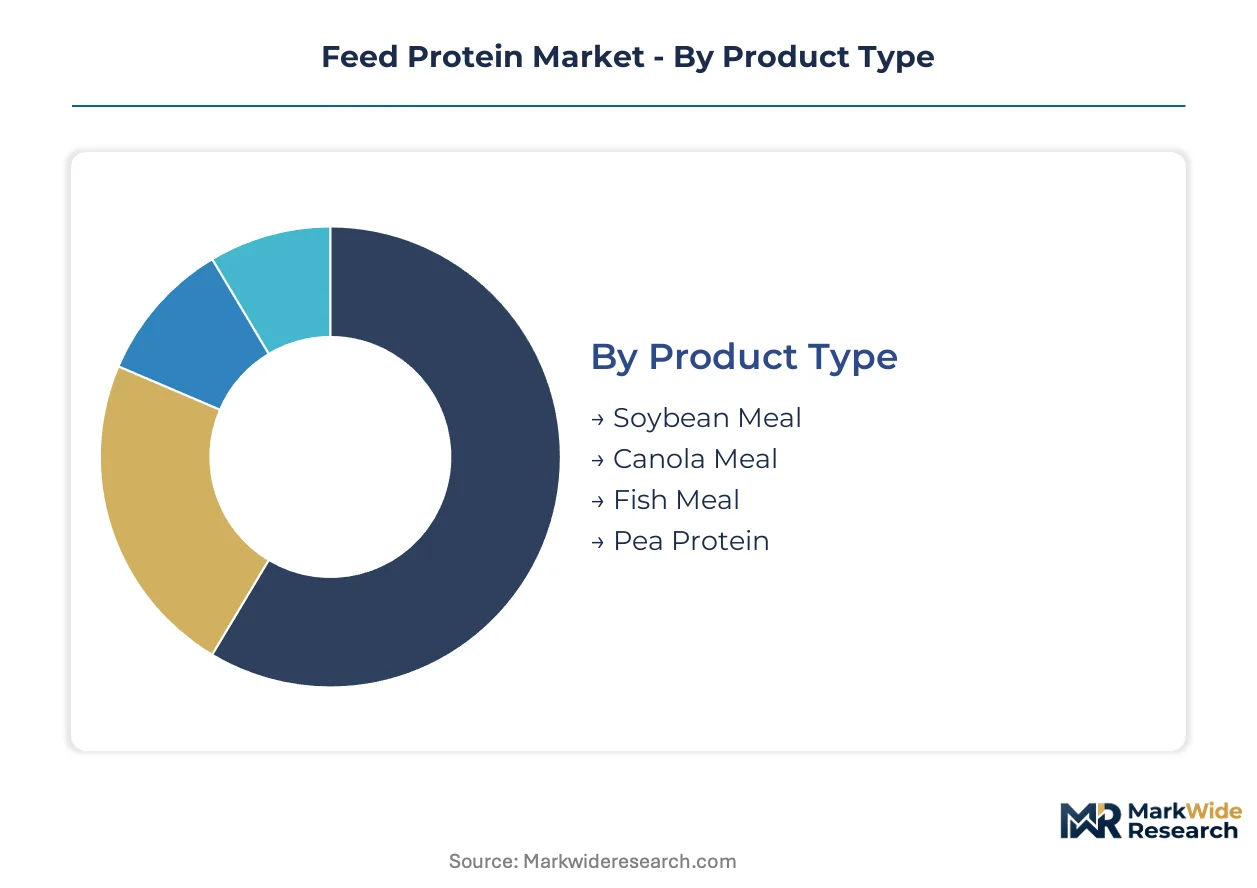
Feed protein segmentation tracks how formulation requirements diverge across species physiology, processing economics, and procurement scale. Understanding these splits reveals where margin pools concentrate and which technical specifications command premium positioning.
Product Type:
Cost tier determines procurement priority, with commodity meals anchoring volume flows and specialty proteins capturing formulation premiums.
- Soybean Meal:Standardized at 44-48% crude protein with digestible lysine profiles optimized for monogastric diets. Poultry integrators in the U.S. Southeast and swine operators in Mato Grosso negotiate twelve-month origination contracts directly with crush facilities to lock in basis spreads.
- Fish Meal:Peruvian anchovy catch constraints limit supply to 6-8 million metric tons annually, concentrating residual volumes in high-value shrimp and salmon diets. Norwegian aquafeed producers pay 3-4x soybean meal equivalents for 65-72% protein concentrates with complete essential amino acid spectra.
- Canola Meal:Lower glucosinolate varieties from Canadian Prairie crushing plants serve dairy ruminant formulations where rumen-degradable protein requirements differ from poultry needs.
- Pea Protein:Non-GMO certification and allergen-free labeling command premium positioning in European pet food and aquaculture applications.
Soybean meal commands the established base. The steepest expansion runs through pea protein.
Application:
Species-specific amino acid requirements create distinct formulation specifications and procurement scale economies.
- Poultry:Broiler operations require 20-24% dietary protein with precise methionine-to-lysine ratios, driving demand for standardized soybean meal and synthetic amino acid supplementation.
- Aquaculture:Salmon and shrimp diets demand 35-50% protein inclusion with marine-derived omega fatty acid profiles, pulling fish meal and fermented single-cell proteins into premium formulations.
- Swine:Finishing diets balance cost-per-unit-protein against feed conversion ratios, with nursery phases requiring higher-quality protein meals than grower-finisher stages.
- Ruminants:Dairy operations utilize rumen-bypass proteins and oilseed meals with controlled degradability to optimize milk yield without ammonia losses.
Poultry absorbs the largest volume share. Aquaculture exhibits the fastest value-per-tonne growth trajectory.
Form:
Processing intensity separates commodity flows from precision-formulated ingredient streams.
- Meal:Standardized 44-50% protein fractions from mechanical or solvent extraction dominate volume economics in bulk compound feed manufacturing.
- Isolate:90%+ protein concentrates with minimal fiber and anti-nutritional factors serve premium pet food and specialized aquaculture diets where digestibility premiums justify 2-3x meal pricing.
- Concentrate:Intermediate 60-70% protein grades bridge cost-performance requirements for mid-tier poultry and swine formulations.
- Hydrolysate:Enzymatically processed peptides with enhanced bioavailability target early-stage aquaculture diets and therapeutic animal nutrition applications.
Meal forms anchor procurement volumes. Isolates are climbing the fastest as pet food humanization trends accelerate.
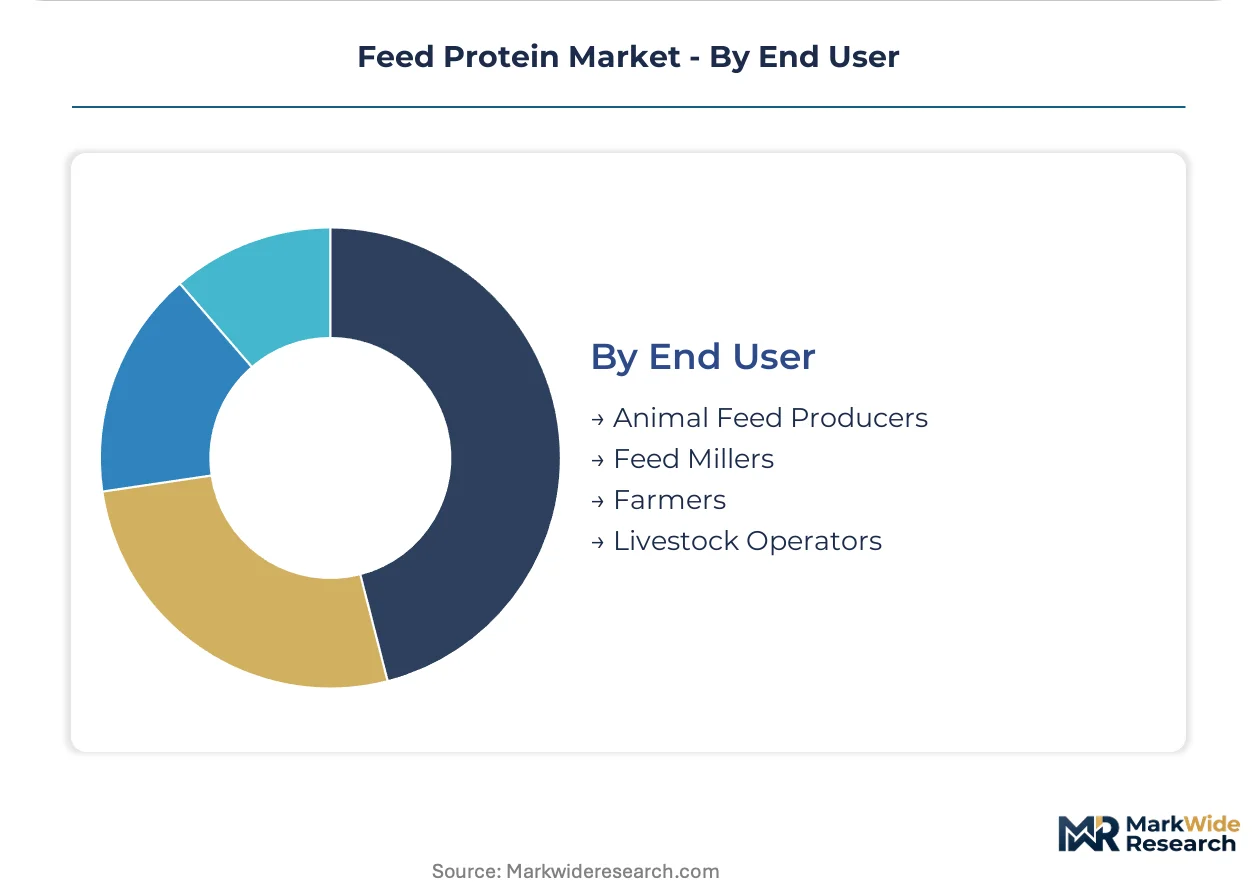
End User:
Customer scale and integration depth determine contract structures and technical service requirements.
- Animal Feed Producers:Integrated protein processors like Cargill and ADM leverage captive crushing assets to supply formulated feeds directly to livestock operators, bypassing traditional distribution.
- Livestock Operators:Large-scale feedlot chains and poultry integrators negotiate direct origination contracts with soybean processors for just-in-time meal delivery to captive mills.
- Feed Millers:Independent compounders blend multiple protein sources to customer specifications, requiring flexible procurement from multiple origination corridors.
- Farmers:Smallholder operations purchase bagged concentrates and premixes through distributor networks with higher per-unit logistics costs.
Animal feed producers control the volume base. Livestock operators are expanding their share fastest through direct procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR enforces GMO labeling and mycotoxin standards that determine which suppliers access Chinese feed protein demand. The EU Green Deal and F-Gas Regulation compress supply windows for carbon-intensive imports. Procurement patterns redirect toward certified sustainable origination corridors across multiple jurisdictions.
United States
Poultry integrators in the Southeast and cattle feedlots in the Midwest drive soybean meal consumption. The FDA and USDA govern feed safety through FSMA and BSE prevention rules. Crushing assets across the Corn Belt enable direct origination-to-feedlot pipelines that bypass traditional distribution.
Brazil
MAPA enforces parallel mycotoxin and GMO labeling standards that shape export market access. Soybean crushing clusters in Mato Grosso and Paraná create origination bottlenecks during harvest windows. Asian importers face amplified freight cost exposure from this logistics concentration.
Indonesia
Shrimp farming operations and poultry integrators scale formulated feed capacity across Java and Sumatra. The national government supports aquaculture expansion through infrastructure investment programs. Feed millers in Surabaya and Medan pull higher volumes of fish meal and alternative protein meals into domestic supply chains.
Norway
Salmon feed producers integrate microbial protein concentrates at 15-30% inclusion rates. EFSA regulatory pathways for novel proteins extend approval timelines for fermented ingredients. Processing facilities in Bergen and Trondheim anchor precision fermentation scale-up for aquaculture applications.
India
Shrimp farming in Andhra Pradesh and Gujarat lacks domestic protein meal crushing infrastructure. The country's national feed regulator enforces safety standards for imported oilseed meals. Feed millers in Visakhapatnam and Ahmedabad create origination-to-farm supply chain buildout potential for integrated processors.
Feed Protein Market Vendor Landscape
Integrated processors and independent oilseed traders split the market along origination control lines. Consolidation concentrates among firms with captive crushing assets and destination port investments. Three archetypes dominate: multinational agribusiness conglomerates with global origination networks, regional oilseed specialists with logistics integration, and precision fermentation entrants targeting premium aquaculture formulations. Competitive moves center on direct procurement consolidation and bioreactor infrastructure deployment.
Within the multinational tier, Cargill Inc. and Archer Daniels Midland Company exemplify scale-driven origination-to-feedlot pipeline control. Bunge Limited occupies a position anchored on South American supply corridors and ocean freight logistics. Among Asia-Pacific integrated operators, Wilmar International Limited and Charoen Pokphand Foods PCL represent regional procurement consolidation. Specialty nutrition players including Evonik Industries AG and DSM-Firmenich sit within the precision fermentation and amino acid supplementation segment.
| Leading Market Players |
|---|
| Cargill Inc. |
| Archer Daniels Midland Company |
| Bunge Limited |
| Wilmar International Limited |
| Charoen Pokphand Foods PCL |
| DuPont |
| Evonik Industries AG |
| DSM-Firmenich |
| Nutreco N.V. |
| Others |
Supply Flow & Price Mechanics
Crushing overcapacity in Mato Grosso during peak harvest windows compresses soybean meal basis spreads and forces processors into aggressive origination pricing to maintain utilization rates. This dynamic simultaneously erodes margins for Brazilian exporters and creates procurement leverage for Asian compound feed millers negotiating twelve-month offtake contracts.
Pricing Analysis
Geographic price spreads between Brazilian FOB Santos and CFR Shanghai quotations fluctuate with ocean freight volatility and currency basis movements. The market operates on long-term contract-based offtake structures for integrated livestock operators, with spot premiums for certified deforestation-free and non-GMO soybean meal tiers. Price differentiation hinges on sustainability certification grade and volume scale commitments, with EU Green Deal compliance commanding substantial premiums. Cost compression in standard commodity meal runs through freight rate exposure and basis risk transfer. Poultry integrators in Southeast Asia exhibit the highest price sensitivity, while Norwegian salmon feed producers absorb premium pricing for novel protein isolates with minimal volume elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic sourcing decisions for soybean processors navigating trade policy uncertainty. Supply concentrates in Brazil, the United States, and Argentina for oilseed origination, with crushing capacity clustering in Mato Grosso, the U.S. Corn Belt, and the Argentine Pampas. Raw material dependencies include glyphosate-tolerant soybean seed genetics, hexane solvent for extraction, and natural gas for drying operations. Single-source vulnerability permeates Peruvian anchovy fish meal supply, where quota volatility disrupts global aquaculture protein inclusion rates. Distribution runs through processor-owned logistics assets directly to captive feed mills, displacing traditional distributor intermediation in integrated supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feed protein markets sit in early-cycle expansion as precision fermentation achieves cost parity in premium aquaculture formulations and regulatory pathways mature for novel protein approvals. Indonesian shrimp farming and Indian aquafeed infrastructure gaps represent penetration tailwinds accelerating adoption velocity.
For Market Incumbents: Build regulatory certification moats around EFSA and FDA novel protein approval dossiers to lock out fermentation entrants during 18-36 month safety review windows. Defensive consolidation should prioritize backward integration into South American origination corridors and bioreactor infrastructure deployment in Norway and Singapore. The threat of microbial protein substitution in salmon diets demands captive supply chain control over fermentation capacity additions. For New Entrants and Emerging Players: Underdeveloped protein meal crushing infrastructure in Andhra Pradesh and Gujarat represents the most penetrable entry point for integrated origination-to-farm supply chain buildouts. Precision fermentation specialists should target premium pet food applications in Europe where allergen-free and non-GMO labeling commands immediate price premiums absent lengthy aquaculture formulation trials. A direct processor-farm procurement model bypassing traditional feed miller intermediation offers the clearest go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision fermentation operators with captive offtake contracts to integrated salmon feed producers. Long-term viability over the next decade hinges on regulatory approval velocity and fermentation scale-up economics rather than commodity crush margin cyclicality. Acquisition targets should screen for bioreactor infrastructure in REACH-compliant jurisdictions and existing EFSA safety dossiers. The signal to watch is inclusion rate expansion beyond 15-30% microbial protein thresholds in commercial Norwegian aquafeed formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Captive bioreactor deployment in Bergen and Singapore anchors microbial protein cost parity in salmon diets. |
| Deforestation-Free Certification Program | EU Green Deal compliance unlocks premium pricing corridors for Brazilian and Argentine soybean meal exports. |
| Direct Processor-Livestock Procurement | Cargill and ADM crushing assets bypass distributors to secure origination-to-feedlot pipelines with U.S. integrators. |
| Novel Protein Regulatory Approval Pathway | EFSA and FDA safety dossiers for insect meal and single-cell proteins determine formulation adoption timelines. |
| South American Origination Expansion | Capacity additions in Mato Grosso and Paraná reduce harvest window bottlenecks for Asian importers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from major processors, EFSA novel food approvals, and FAO aquaculture production statistics. Primary interviews engaged crushing plant managers, aquafeed formulation scientists, procurement leads at integrated poultry operators, and regulatory affairs specialists at fermentation startups. Secondary validation drew from MAPA export certifications, SAMR GMO labeling registrations, and EU REACH compliance databases. Bottom-up volume modeling triangulated against top-down protein meal consumption estimates across species-specific formulation requirements.
Forecast inputs span species application splits, protein form tier adoption curves, and origination corridor capacity utilization trajectories across the projection horizon. The analytical framework models segmentation across product type, application species, processing form, and end-user integration depth. CAGRs derive from fitted growth curves against historical crush margin volatility and regulatory approval velocity benchmarks. Industry-specific forecast inputs include Peruvian anchovy quota cycles, EU F-Gas Regulation implementation phases, and precision fermentation yield improvement curves.
Practitioners should monitor EFSA novel protein approval timelines, Brazilian harvest logistics disruptions, and Chinese SAMR import policy shifts for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Slippery Elm Market
Agriculture and Agri Products
Taro Market
Agriculture and Agri Products
US Greenhouse Horticulture Market
Agriculture and Agri Products
Global Medicated Feed Market
Agriculture and Agri Products
Netherlands Cashew Market
Agriculture and Agri Products
Sweet Potato Flour Market
Agriculture and Agri Products
Vietnam Shrimp Feed Market
Agriculture and Agri Products
Argentina Agriculture Market
Agriculture and Agri Products
United Kingdom Animal Protein Market
Agriculture and Agri Products
France Alfalfa Hay Market
Agriculture and Agri Products
Frozen Egg Market
Agriculture and Agri Products
Palm Kernel Expeller Market
Agriculture and Agri Products
Plant Antifreeze Market
Agriculture and Agri Products
North America Eggs Market
Agriculture and Agri Products
Post-Harvest Treatment Market
Agriculture and Agri Products
Cattle Feed Concentrate Market