
 Calendered Polyvinyl Chloride Flexible Films Market | 2026-2036
Calendered Polyvinyl Chloride Flexible Films Market Size, Share, and Industry Trends Forecast 2026-2036
Calendered Polyvinyl Chloride Flexible Films Market Intelligence
Aftermarket service revenue for film conversion and die-cutting is reshaping margin distribution across the value chain. RENOLIT SE leverages its European manufacturing footprint to dominate medical-grade film supply. Teknor Apex Company anchors North American demand through specialized compounding capabilities. Caprihans India Limited competes on cost-optimized production for consumer goods packaging across South Asia.
Calendered polyvinyl chloride flexible films are thermoplastic sheets produced by passing PVC compound through heated rollers to achieve precise gauge control, typically ranging from ultra-thin membranes below 0.1 mm to thick gauges exceeding 1.5 mm for industrial barrier applications. These films deliver chemical resistance, weldability, and conformability for packaging sterile medical devices, waterproofing building membranes, and surfacing automotive interiors. Laminated films command premium positioning in medical packaging where multi-layer barrier properties satisfy sterility requirements, while stretch films occupy high-volume, lower-margin tiers in palletized logistics and food service wrapping. Construction-grade medium and thick gauges represent mature demand in geomembranes and temporary enclosure systems across temperate climate zones.
REACH restrictions on phthalate plasticizers and the EU MDR's heightened scrutiny of patient-contact materials are redirecting formulation investments toward bio-based and non-phthalate alternatives in European medical film production. The FDA's ongoing evaluation of PVC in neonatal and pediatric devices creates compliance uncertainty for US suppliers serving regulated healthcare channels. Stakeholders must monitor regulatory divergence between European ECHA hazard classifications and FDA's substance-by-substance review timelines to avoid stranded inventory in cross-border medical supply chains.
Market Dynamics
REACH phthalate restrictions and FDA pediatric device scrutiny are forcing simultaneous reformulation across European and North American medical film supply chains, compressing development timelines while expanding R&D overhead.
Growth Catalysts
- EU MDR sterility mandates:Heightened barrier requirements for single-use medical devices are pulling multi-layer laminated films into hospital procurement specifications across German and French healthcare networks.
- Automotive interior surfacing:Lightweighting imperatives in electric vehicle cabins are displacing heavier thermoset alternatives with calendered PVC skins for dashboard and door panel applications.
- Waterproofing membrane demand:Germany's building energy retrofit programs are accelerating geomembrane installations for basement and foundation sealing in temperate climate zones.
Market Restraints
- Plasticizer input volatility:Epoxidized soybean oil and bio-based alternatives trade at premiums to legacy phthalates, squeezing margin on medical-grade formulations.
- Supply concentration risk:European medical film production clusters heavily in Germany's industrial corridor, exposing buyers to single-point logistics disruptions.
- Substitution threat:Thermoplastic polyurethane films are capturing share in high-flex cycling applications where PVC fatigue resistance underperforms.
Strategic Opportunities
- Indian medical packaging expansion:CDSCO's streamlined device registration pathways are opening import substitution opportunities for domestic calendered film production.
- Recyclate integration:ECHA's evolving end-of-life frameworks are creating first-mover advantage for producers with validated post-industrial PVC feedstock streams.
- Digital print compatibility:UV-curable ink adhesion on calendered surfaces is enabling short-run customization for pharmaceutical blister branding.
Industry Challenges
- Cross-border compliance synchronization:Divergent ECHA hazard classifications and FDA substance-by-substance review timelines strand inventory in transatlantic medical supply chains.
- Specialized compounding talent scarcity:Formulation chemists with simultaneous REACH and FDA submission experience command premiums that mid-tier converters cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calendered Polyvinyl Chloride Flexible Films Market |
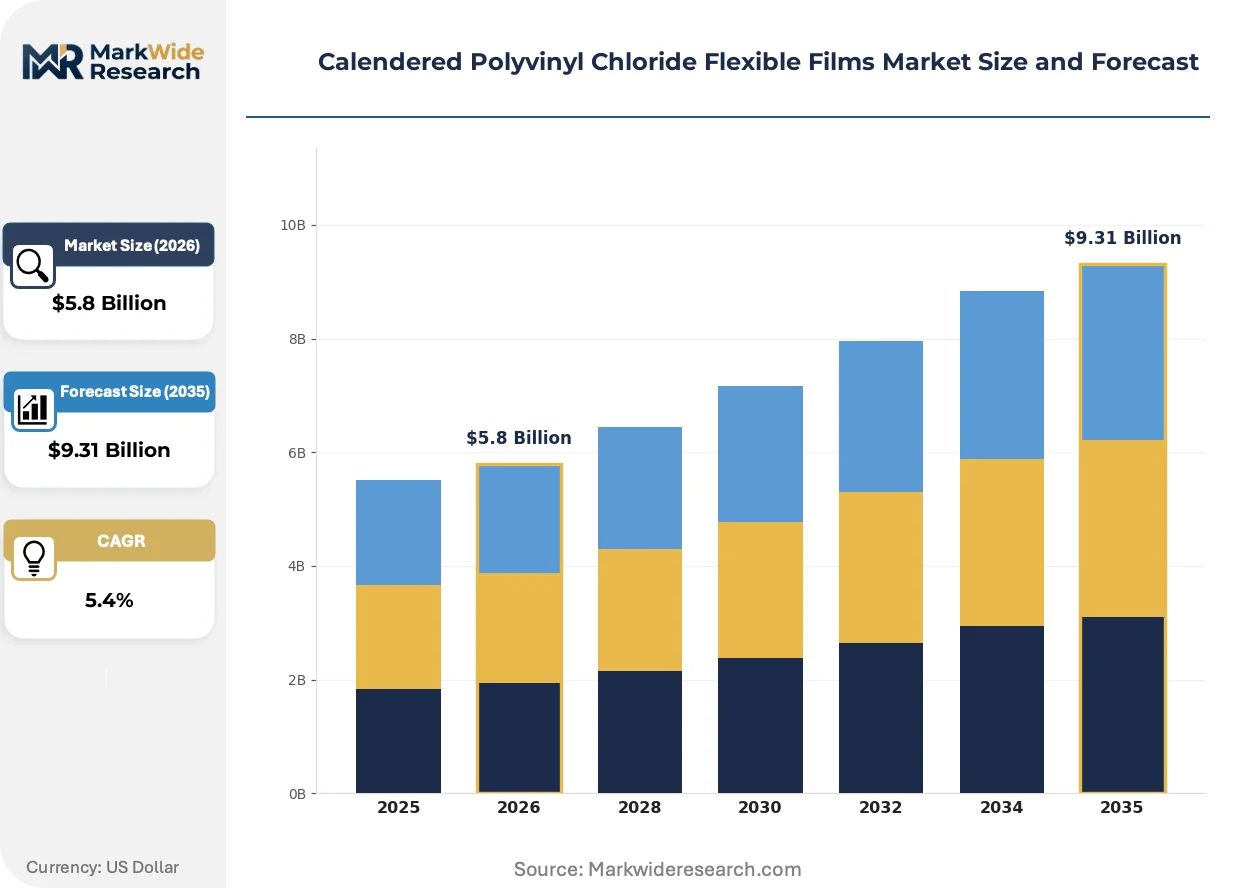
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.31 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
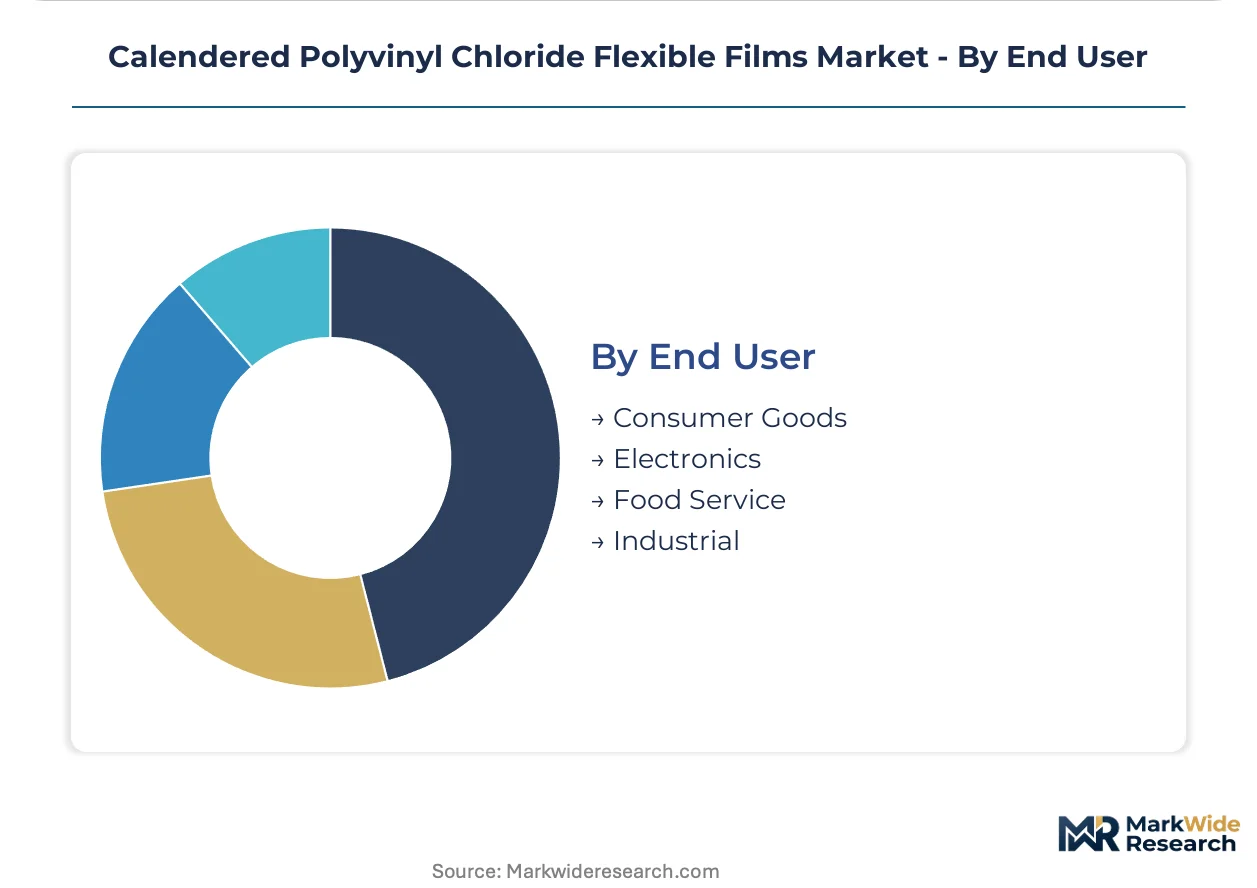
| Segmentation | Product Type: Rigid Films, Stretch Films, Laminated Films, Coated Films Application: Packaging, Construction, Automotive, Medical Thickness: Thin, Medium, Thick, Ultra-Thin End User: Consumer Goods, Electronics, Food Service, Industrial |
| Companies Covered | Mississippi Polymers, Teknor Apex Company, Canadian Speciality Vinyls, South Asia Plastics Group, ACG, Caprihans India Limited, RENOLIT SE, ALFATHERM SpA, Mondorevive S.p.a., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calendered Polyvinyl Chloride Flexible Films Market Strategic Shifts & Innovations
Formulation chemistry and manufacturing process control are converging to address regulatory pressure while opening new performance tiers previously occupied by alternative polymers.
Non-phthalate plasticizer systems, particularly citrate-based and bio-derived alternatives, are migrating from niche medical applications toward mainstream food-contact and consumer goods films as ECHA restrictions harden. German compounders are accelerating validation batches for DINP and DEHP replacements. This technology shift is compressing the premium pricing window for legacy formulations while expanding addressable market for compliant producers.
ECHA's 2025 update to REACH Annex XVII restrictions on medium-chain chlorinated paraffins is forcing flame-retardant film producers toward phosphorus-based and mineral filler alternatives. The industrial consequence extends beyond substitution to require recalibration of extrusion temperature profiles. Construction-grade geomembrane manufacturers in Belgium and the Netherlands are absorbing the steepest compliance costs due to existing inventory of affected formulations.
Hospital network consolidation is compressing supplier qualification cycles and bundling film procurement with device OEM contracts. Large US health systems are displacing spot-market purchasing with multi-year sole-source agreements that privilege converters with validated sterile barrier capabilities. This concentration is most visible in the Midwest hospital supply chain, where three purchasing cooperatives control the majority of medical packaging volume.
Calendered Polyvinyl Chloride Flexible Films Market Segmentation
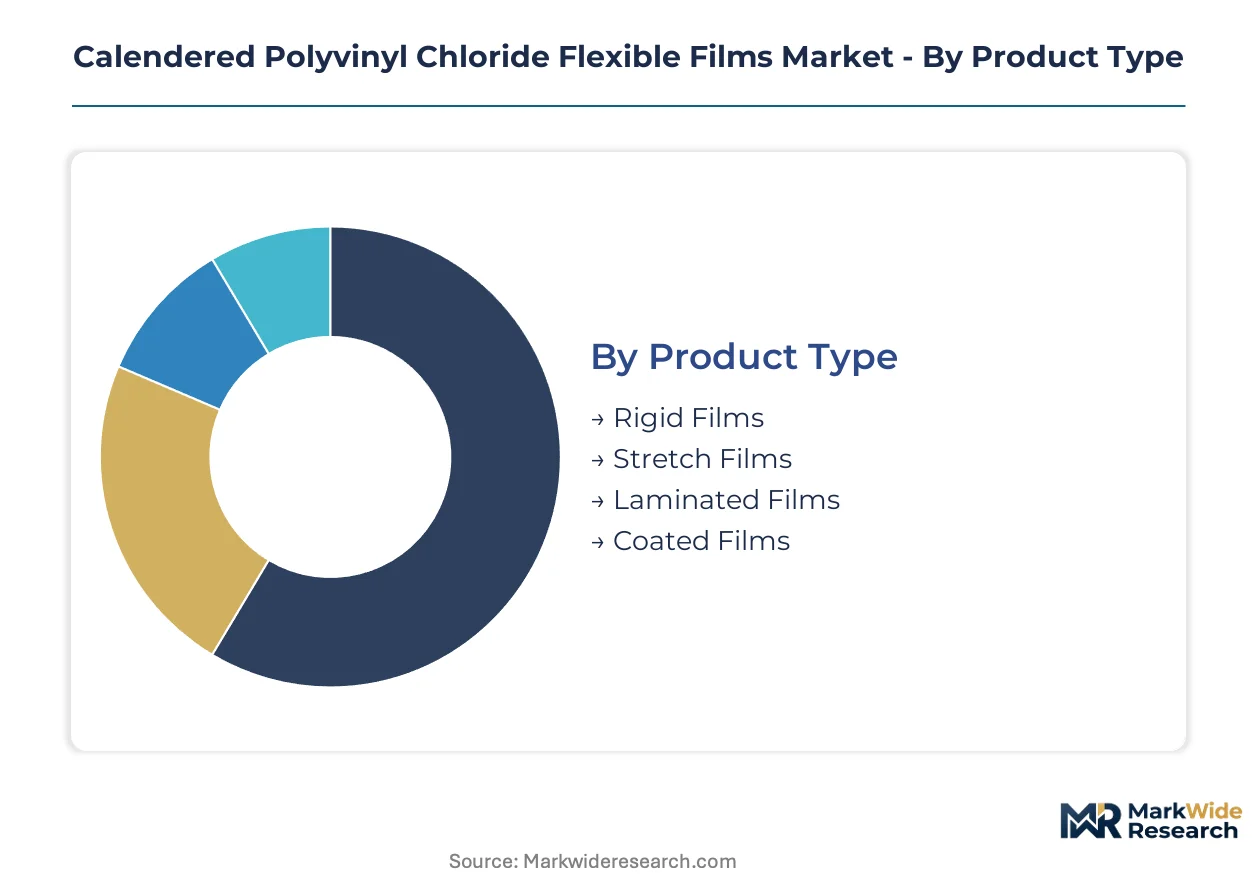
Segmentation in calendered PVC flexible films reveals how formulation chemistry and gauge precision map to distinct value pools. Product architecture, application requirements, and end-user specifications create tiered margin structures that separate commodity converters from specialized medical-grade suppliers.
Product Type:
Films span a use-case spectrum from commodity stretch wrapping to precision-engineered multi-layer barriers for sterile environments.
- Laminated Films:Multi-layer constructions bond PVC with polyethylene or ethylene vinyl acetate to achieve moisture and oxygen barriers exceeding single-layer performance. Hospital networks in Germany and France specify these for Class II and III medical device packaging under EU MDR sterility mandates.
- Stretch Films:Linear low-density formulations with PVC blends deliver cling force and puncture resistance for palletized logistics. Food service distributors in North America consume high volumes with thin-gauge specifications dominating procurement.
- Rigid Films:Higher modulus calendered sheets serve thermoformed blister packs and clamshell packaging where dimensional stability trumps conformability.
- Coated Films:Surface-treated layers enable UV-curable ink adhesion for pharmaceutical branding and short-run customization.
Established volume favors stretch films; emerging adoption favors laminated films.
Application:
Demand concentrates where regulatory compliance intersects with material performance requirements.
- Medical:Sterile barrier applications command premium positioning through validated manufacturing processes and extractables testing. REACH phthalate restrictions and FDA pediatric device scrutiny are forcing simultaneous reformulation across European and North American supply chains.
- Automotive:Dashboard skins and door panel surfacing in electric vehicle cabins prioritize lightweighting over thermoset alternatives. German OEMs specify low-VOC formulations meeting KBA interior air quality protocols.
- Construction:Geomembranes and temporary enclosure systems represent mature demand in basement waterproofing and building energy retrofits across temperate climate zones.
- Packaging:General-purpose films serve consumer goods with cost-optimized specifications and shorter qualification cycles than regulated channels.
Medical applications expand most quickly; construction maintains the largest installed base.
Thickness:
Gauge selection directly determines calendering line configuration and end-use performance envelope.
- Ultra-Thin:Sub-0.1 mm membranes serve pharmaceutical blister packs where precise dose visibility and push-through force matter. European converters dominate this specification tier through specialized roller technology.
- Thick:Gauges exceeding 1.5 mm deliver puncture resistance for industrial barrier applications and geomembrane installations. German building energy retrofit programs are accelerating specification of these grades for foundation sealing.
- Thin:0.1-0.3 mm range balances conformability with handling strength for food service wrapping and consumer goods overwrap.
- Medium:0.3-1.0 mm thickness occupies general industrial applications with moderate barrier and mechanical requirements.
Ultra-thin gauges gain share fastest in medical packaging; thick gauges anchor construction volume.
End User:
Procurement sophistication separates regulated industries from spot-market purchasing patterns.
- Food Service:High-volume, price-sensitive buyers prioritize film clarity and seal integrity for fresh and prepared food presentation. Stretch and cling specifications dominate with rapid inventory turns.
- Electronics:Anti-static and cleanroom-compatible films protect sensitive components during manufacture and shipment. ESD control specifications add formulation complexity.
- Consumer Goods:Brand owners specify printed films for retail shelf appeal with shorter runs and faster design cycles than industrial applications.
- Industrial:Pallet wrapping and protective masking films emphasize throughput and cost per unit over specialized performance.
Food service generates the highest unit volume; electronics commands the steepest premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in German automotive and medical channels accept premium pricing for REACH-compliant formulations, while South Asian packaging converters drive hard bargains on commodity stretch films. This elasticity divide splits procurement patterns between regulated healthcare networks and price-sensitive logistics operators.
Germany
Automotive interior surfacing and medical device packaging dominate demand, with electric vehicle OEMs specifying low-VOC calendered skins for cabin lightweighting. KBA interior air quality protocols enforce strict emissions testing on dashboard materials. Production clusters heavily in North Rhine-Westphalia's industrial corridor, where compounders operate integrated calendering lines serving both automotive Tier 1s and hospital supply chains.
United States
Midwest hospital purchasing cooperatives bundle medical film procurement with device OEM contracts, displacing spot-market buying. FDA's ongoing pediatric device scrutiny creates compliance uncertainty for suppliers serving neonatal care channels. Teknor Apex anchors North American supply from specialized compounding facilities in the Northeast, feeding converter networks across the Great Lakes manufacturing belt.
India
CDSCO's streamlined device registration pathways are opening import substitution opportunities for domestic medical packaging production. Cost-optimized consumer goods films serve South Asian food service and retail wrapping markets with thin-gauge specifications. Caprihans India Limited operates from Maharashtra's industrial zones, competing on volume scale for regional logistics and consumer packaging applications.
China
Building energy retrofit programs and electric vehicle manufacturing are pulling medium and thick-gauge films into geomembrane and automotive applications. MIIT's evolving standards on interior air quality in passenger vehicles mirror European VOC protocols. Yangtze River Delta converters supply both domestic EV brands and export medical packaging channels with differentiated gauge capabilities.
Italy
Pharmaceutical blister packaging and luxury goods surfacing sustain demand for ultra-thin and coated film specifications. EU MDR sterility mandates pull Italian converters toward validated medical-grade production for export to German and French hospital networks. Lombardy-based specialists leverage proximity to Milan's design-intensive consumer goods sector for short-run printed film applications.
Calendered Polyvinyl Chloride Flexible Films Market Key Industry Players
Capability concentration sits with European compounders holding REACH and FDA dual submission experience; scale advantage sits with Asian converters feeding high-volume packaging markets. The vendor base separates into three tiers: integrated resin-to-film producers commanding medical-grade premiums, regional converters competing on logistics proximity, and commodity specialists absorbing thin-margin stretch film volumes. Dominant competitive moves include backward integration into captive plasticizer compounding and geographic expansion through distributor partnerships in underpenetrated medical packaging markets.
Within the European integrated tier, RENOLIT SE and ALFATHERM SpA exemplify compounders with validated sterile barrier capabilities serving hospital procurement networks. Teknor Apex occupies a position among North American specialists with dual-hemisphere regulatory submission experience. Caprihans India Limited represents the cost-optimized volume play, anchoring South Asian supply for consumer goods and logistics applications where specification tolerance permits thinner gauges and shorter qualification cycles.
| Leading Market Players |
|---|
| Mississippi Polymers |
| Teknor Apex Company |
| Canadian Speciality Vinyls |
| South Asia Plastics Group |
| ACG |
| Caprihans India Limited |
| RENOLIT SE |
| ALFATHERM SpA |
| Mondorevive S.p.a. |
| Others |
Cost & Logistics Intelligence
Germany's industrial corridor concentration of medical-grade compounders funnels margin capture toward REACH-validated formulation tiers, while spot-market buyers in South Asian packaging channels extract cost concessions from thin-gauge stretch film suppliers. This upstream clustering downstream of plasticizer feedstock nodes creates divergent pricing power between regulated healthcare networks and commodity logistics operators.
Pricing Analysis
Aftermarket service revenue for film conversion and die-cutting anchors lifetime value realization across the value chain. Three-tier pricing structure across premium, standard, and economy levels separates EU MDR-validated medical grades from industrial geomembrane specifications and food-service stretch films. Cost compression in commodity tiers intensifies because South Asian converters absorb thinner margins on high-volume consumer packaging contracts. Food service distributors exhibit highest price sensitivity; German hospital purchasing cooperatives accept premiums for sterile barrier validation.
Supply Chain Analysis
Upstream PVC resin and specialized plasticizer feedstock draw from petrochemical complexes in Germany, China, and the United States. Epoxidized soybean oil and citrate-based alternatives feed from agricultural processing streams in North America and Southeast Asia. Single-source vulnerability concentrates in Germany's North Rhine-Westphalia corridor where integrated compounders serve both automotive Tier 1s and medical device OEMs. Distribution runs through converter networks that laminate, die-cut, and sterilize films before hospital network delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists possessing simultaneous REACH and FDA submission experience command compensation premiums that fragment competitive capability between integrated European compounders and scale-focused Asian converters. This talent scarcity concentrates strategic optionality with incumbents holding validated regulatory dossiers.
For Market Incumbents: Build regulatory dossier depth by securing dual-hemisphere submission experience for non-phthalate plasticizer systems before ECHA's 2025 Annex XVII enforcement tightens. Anchor capacity addition in India's Maharashtra industrial zones to capture CDSCO pathway acceleration for import substitution. Thermoplastic polyurethane substitution in high-flex cycling applications threatens PVC's patient-contact positioning; preemptive TPU partnership or acquisition defends medical-grade share. For New Entrants and Emerging Players: Establish a beachhead in Indian medical packaging by targeting CDSCO-registered device OEMs seeking domestic film supply for blister and pouch applications. White-space concentrates in medium-gauge geomembranes for China's building energy retrofit programs where MIIT standards mirror European VOC protocols. Go-to-market leverage rests on validated post-industrial recyclate streams that satisfy ECHA's evolving end-of-life frameworks for first-mover positioning. For Investors and Strategic Acquirers: Capital is best deployed toward integrated compounders with captive plasticizer production and dual regulatory submission capabilities across the 5-10 year viability window. Acquisition target archetype: mid-tier European converters with sterile barrier validation but underutilized calendering capacity. Signal to watch: FDA's substance-by-substance pediatric device review timeline divergence from ECHA hazard classifications, which would strand cross-border inventory and trigger distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plasticizer Compounding | Captive supply of citrate-based alternatives insulates margin from epoxidized soybean oil price volatility. |
| Recyclate Integration Program | Validated post-industrial PVC feedstock streams unlock first-mover advantage under ECHA's evolving end-of-life frameworks. |
| Digital Print Surface Engineering | UV-curable ink adhesion enables short-run pharmaceutical blister customization for brand differentiation. |
| Hospital System Partnership | Multi-year sole-source agreements with Midwest purchasing cooperatives displace spot-market procurement cycles. |
| Geographic Expansion through Distributor Partnerships | CDSCO pathway acceleration in India opens import substitution for domestic medical packaging production. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with plant managers at calendering facilities, procurement leads at automotive Tier 1 suppliers, hospital GPO contracts managers, and formulation R&D directors; and secondary validation through customs and trade data, SEC filings of listed compounders, ECHA REACH registration dossiers, and FDA 510(k) submission databases. Bottom-up volume modeling across gauge specifications and application tiers triangulated against top-down value estimates from production capacity disclosures.
Forecast inputs considered segment-level growth trajectories across laminated, stretch, rigid, and coated film architectures, with thickness stratification from ultra-thin pharmaceutical grades to thick geomembrane specifications. End-use demand drivers modeled included EU MDR sterility mandates, KBA interior air quality protocols, and MIIT passenger vehicle standards. CAGRs derived from elasticity-adjusted volume projections and price evolution assumptions across the analysis window.
Sensitivities concentrate around FDA pediatric device review timeline divergence from ECHA classifications, plasticizer feedstock price volatility in agricultural-derived alternatives, and thermoplastic polyurethane substitution rates in high-flex applications. Cross-checking against ECHA registration database updates and FDA guidance document releases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Corn Fiber Market
Others
Eye Balm Market
Others
Deep Sea Mining Market
Others
Nanomedicine for Drug Delivery Market
Others
South Asia Geosynthetics Market
Others
Performance Testing Tools Market
Others
Storm Surge Barriers Market
Others
North America Cashew Market
Others
Global Extruded Plastics Market
Others
Egg Market
Others
Foldable Smartphone Market
Others
Europe Smart Homes Market
Others
Global Multi Domain Controller Market
Others
Global Flexible PVC Films Market
Others
Africa Lime Market
Others
Folding Mobile Phone Market